
 Diagnostic Vials Market | 2026-2036
Diagnostic Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Diagnostic Vials Market Outlook
Hospital central laboratories is realigning procurement toward higher-capacity blood collection vials as outpatient testing volumes rise. Thermo Fisher Scientific leverages its distribution breadth across North American health systems. Greiner Bio-One anchors European supply through automated production lines. Eppendorf AG specializes in premium plastic vials for molecular diagnostics workflows.
Diagnostic vials are cylindrical primary containers manufactured from borosilicate glass or medical-grade polymers, designed to preserve sample integrity during collection, transport, and automated analysis. Blood collection vials lead volume due to routine hematology demand, while plastic variants in polypropylene represent the fastest-expanding material class as labs seek breakage reduction. Closure innovation concentrates in screw-on caps with integrated sealing liners, where margin pools deepen for suppliers certifying to pharmacopeial extractables standards.
The FDA enforces biocompatibility and extractables testing under ISO 10993 for plastic diagnostic vials entering clinical use, while the EU MDR reclassifies certain specimen containers as Class I medical devices with intensified post-market surveillance. Japan's PMDA maintains distinct JIS standards for vacuum blood collection tubes that foreign manufacturers must navigate for market access. Stakeholders must monitor evolving polymer regulations and automate compliance documentation before product registration timelines compress further.
Market Dynamics
Central laboratory automation is compressing turnaround time expectations while tightening material certification requirements. Blood collection vial specifications now integrate directly with robotic handling systems, forcing suppliers to synchronize dimensional tolerances with equipment OEMs.
Growth Catalysts
- EU MDR reclassification:Specimen containers now face Class I medical device standards with intensified post-market surveillance, creating replacement demand for certified inventory.
- Polypropylene breakage reduction:Hospital central laboratories are converting glass-dominant workflows to medical-grade polymers to minimize sample loss during high-speed centrifugation.
- Japan vacuum tube standards:PMDA's distinct JIS certification requirements for blood collection tubes create dedicated supply contracts for compliant foreign manufacturers.
Market Restraints
- Borosilicate glass energy costs:European natural gas price volatility directly impacts furnace-operating margins for traditional glass vial producers.
- Extractables testing burden:ISO 10993 biocompatibility protocols for plastic variants extend product development timelines by eight to fourteen months.
- Single-source polymer grades:Medical-certified polypropylene resin concentrates among three global petrochemical suppliers, creating input concentration risk.
Strategic Opportunities
- Point-of-care molecular diagnostics:Miniaturized plastic vial formats for PCR workflows remain undersupplied relative to decentralized testing expansion.
- Integrated closure-liner systems:Screw-cap designs with pre-assembled sealing elements command premium positioning in automated handling environments.
- India diagnostic infrastructure:The country's PLI scheme for medical devices incentivizes local vial manufacturing for domestic lab network expansion.
Industry Challenges
- Pharmacopeial extractables documentation:USP and EP compliance for plastic vial leachables requires specialized analytical chemistry capabilities that constrain supplier entry.
- Legacy equipment dimensional mismatch:Automated analyzer compatibility specifications vary across installed bases, fragmenting production runs and tooling amortization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diagnostic Vials Market |
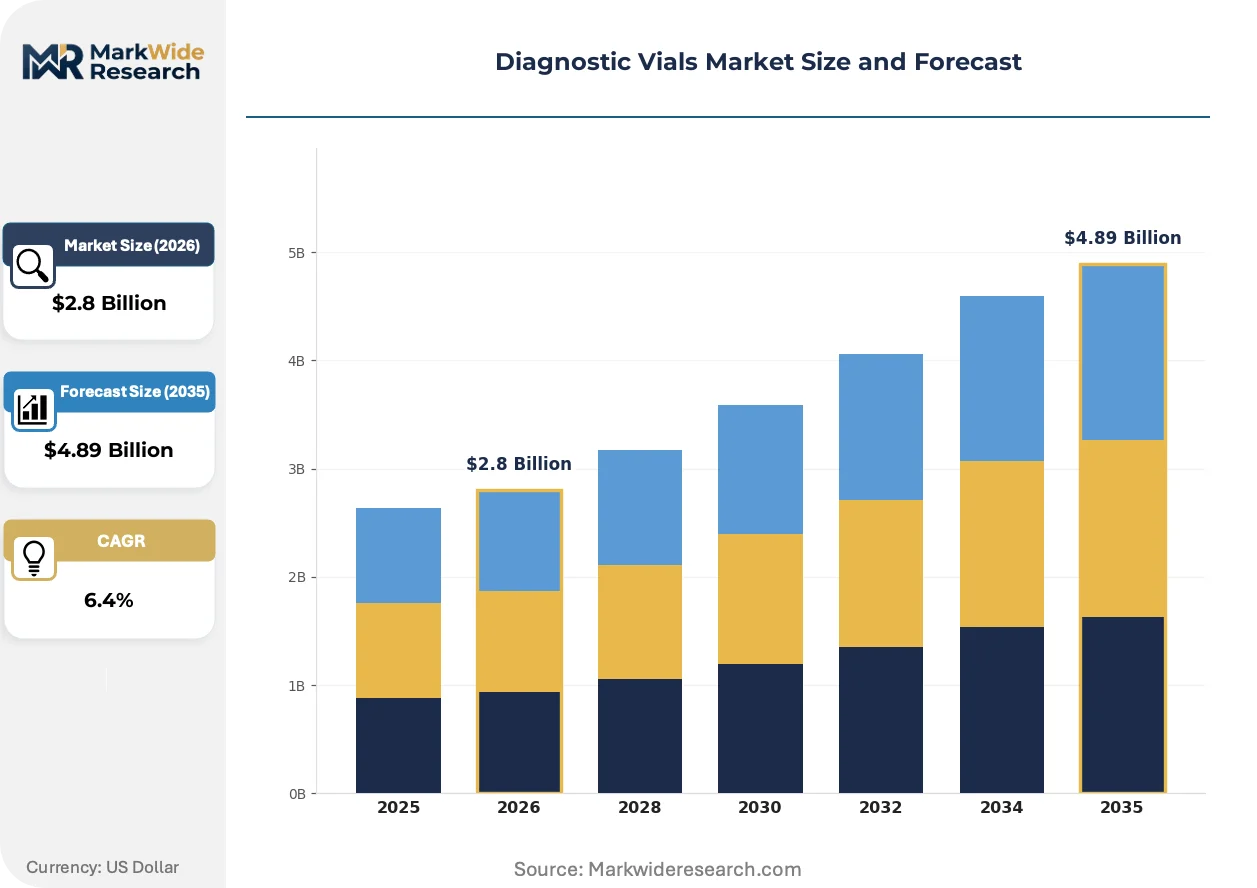
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serum Vials, Sample Vials, Blood Collection Vials, Preservation Vials Material: Glass, Plastic, Polypropylene, Polyethylene Closure Type: Pierceable Caps, Snap-On Caps, Screw-On Caps, Sealing Liners End User: Hospitals, Diagnostics Labs, Research Institutes, Pharmaceutical Companies |
| Companies Covered | Greiner Bio-One, Eppendorf AG, Thermo Fisher Scientific, Heathrow Scientific, Globe Scientific, Corning Incorporated, Cole-Parmer, BrandTech Scientific, DWK Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diagnostic Vials Market Strategic Shifts
Material science convergence with regulatory science is redefining competitive differentiation in primary diagnostic packaging. Suppliers now compete on extractables data depth rather than unit economics alone.
Co-extruded barrier polymers are rewriting sample stability guarantees for extended transport chains. Multi-layer polypropylene-ethylene vinyl alcohol constructions now preserve nucleic acid integrity across seventy-two-hour ambient shipping windows. Reference laboratories in Germany and the United States are qualifying these formats for decentralized collection networks.
REACH substance restrictions on candidate plasticizers are forcing reformulation of closure elastomers ahead of sunset dates. The ECHA authorization list now covers phthalate alternatives previously adopted as drop-in replacements. European vial manufacturers are accelerating halogenated butyl rubber validation to maintain CE marking continuity.
Consolidated buying by multi-site health systems is compressing vendor qualification cycles. Integrated delivery networks now mandate single-source contracts with automated replenishment integration. This concentration is most visible in United States hospital central laboratories, where three-year sole-source agreements displace spot purchasing.
Diagnostic Vials Market Segmentation
Diagnostic vial suppliers configure production assets around material processing requirements and closure complexity. Segment boundaries determine tooling investment, certification timelines, and margin structures across the value chain.
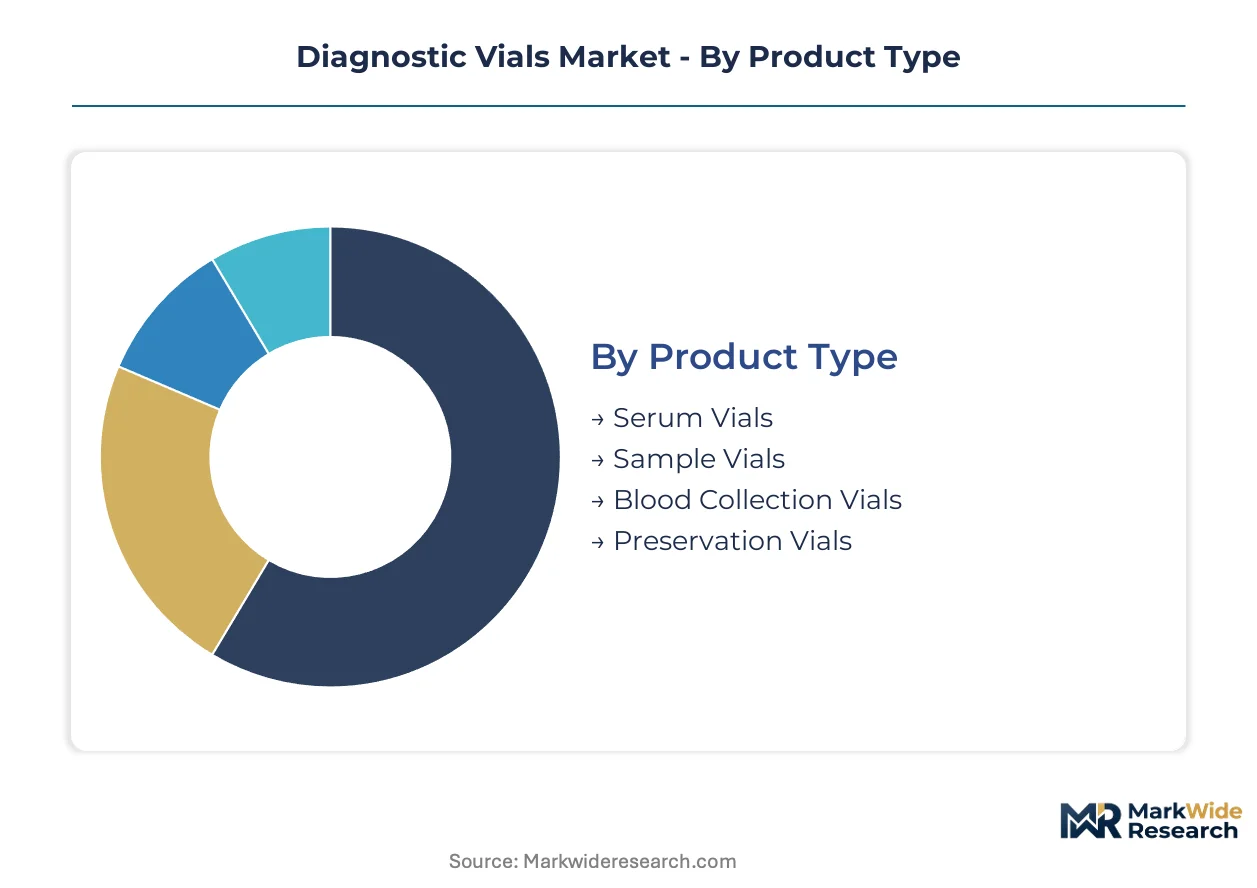
Product Type:
Capital intensity peaks in segments requiring vacuum integrity and additive integration during manufacture.
- Blood Collection Vials:Vacuum-evacuated tubes with pre-measured anticoagulant coatings dominate hospital procurement volumes. German and United States central laboratories specify these for automated analyzer compatibility, driving dimensional standardization investments.
- Serum Vials:Borosilicate glass containers with inert interior surfaces separate clot-activated specimens for chemistry panels. Research institutes in Japan specify these for reference method validation, sustaining premium positioning despite polymer displacement elsewhere.
- Sample Vials:General-purpose containers for non-anticoagulated specimens serve decentralized collection networks.
- Preservation Vials:Stabilization chemistry-integrated formats protect nucleic acids during ambient transport chains.
Most installed capacity flows through Blood Collection Vials. Expansion is steepest in Preservation Vials.
Material:
Polymer certification costs now rival glass furnace capital in total investment requirements.
- Polypropylene:Medical-grade resin with centrifugation stress resistance is displacing glass in high-throughput hematology workflows. Hospital central laboratories in the United States convert to this material to reduce breakage loss during automated handling.
- Glass:Borosilicate formulations maintain dominance in reference laboratories requiring thermal stability for heat-inactivated assays. European energy costs compress furnace economics, forcing regional producers toward specialty coated variants.
- Plastic:Broad polymer category capturing intermediate performance specifications for non-clinical applications.
- Polyethylene:Lower-density alternative for cryogenic storage vials in biobanking infrastructure.
Glass retains the largest installed base. Polypropylene is climbing the fastest.
Closure Type:
Automation compatibility now dictates closure design more than material cost.
- Screw-On Caps:Threaded closures with integrated sealing liners command premium positioning in robotic handling environments. Diagnostics labs specify these for leak-free transport through pneumatic tube systems.
- Pierceable Caps:Elastomeric septum designs enable direct needle access for automated liquid handling. Pharmaceutical companies in Germany require these for compound library storage under inert atmosphere.
- Snap-On Caps:Press-fit designs serve cost-sensitive high-volume applications with minimal handling automation.
- Sealing Liners:Independent gasket components for custom closure assembly in specialized workflows.
Screw-On Caps absorb the majority of current capacity investment. Pierceable Caps show the steepest expansion trajectory.
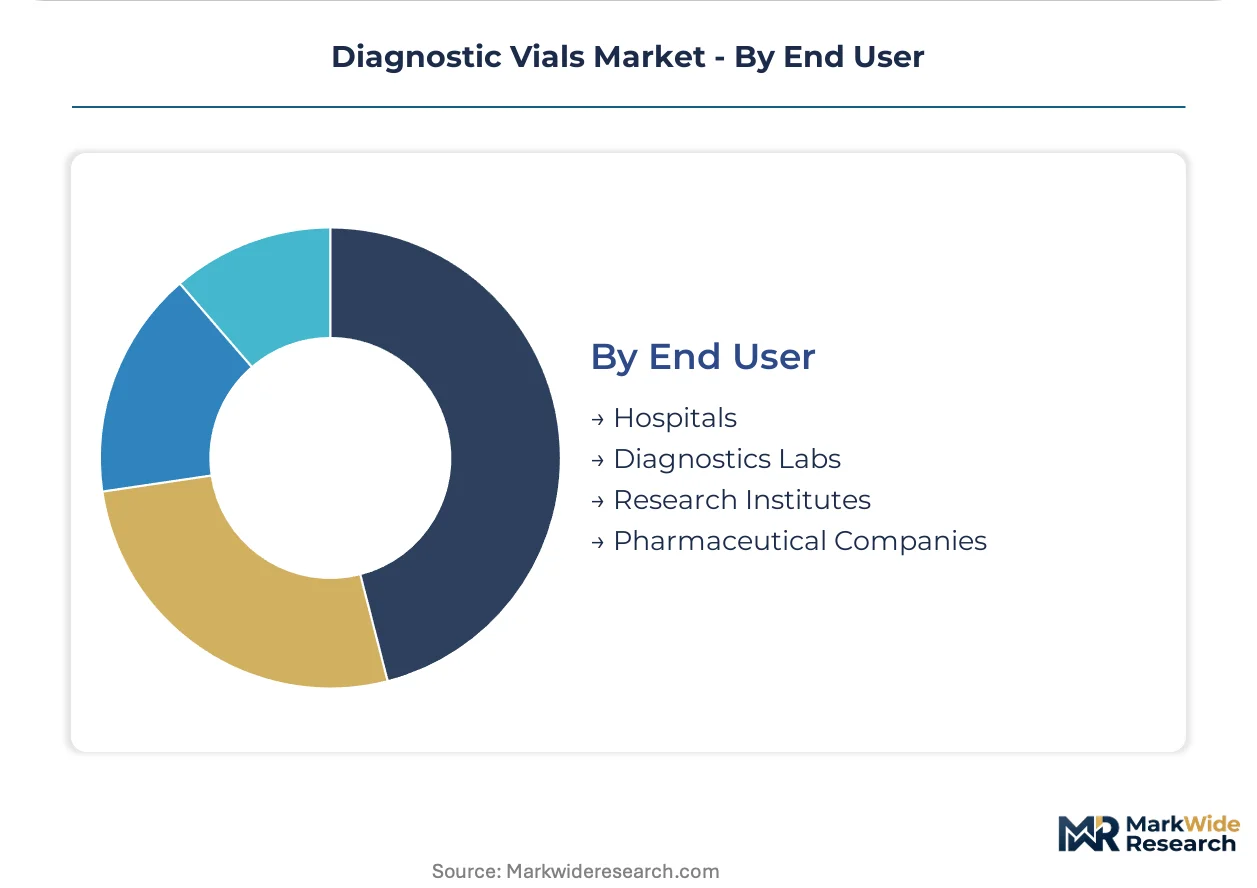
End User:
Procurement consolidation is reshaping supplier relationships across customer categories.
- Diagnostics Labs:Centralized reference facilities drive volume concentration through multi-year sole-source contracts. United States integrated delivery networks now mandate automated replenishment integration for primary packaging.
- Hospitals:Outpatient testing expansion is realigning central laboratory procurement toward higher-capacity formats. Japan's hospital networks upgrade collection infrastructure under PMDA quality system requirements.
- Research Institutes:Academic and government laboratories sustain demand for certified reference materials.
- Pharmaceutical Companies:Clinical trial supply chains require lot-traceable vial documentation under FDA IND protocols.
Diagnostics Labs command the largest share of dedicated production lines. Hospital procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined medical device certification pathways. Producers migrate capacity to exploit cost-of-compliance gaps between established and emerging regulatory frameworks.
United States
FDA biocompatibility requirements under ISO 10993 drive domestic qualification timelines for plastic diagnostic vials. Hospital central laboratories in the United States consolidate procurement through integrated delivery networks with automated replenishment mandates. The Boston-Cambridge biotech corridor sustains demand for high-integrity sample containers in clinical trial workflows.
Germany
EU MDR reclassification of specimen containers as Class I medical devices accelerates inventory replacement across German reference laboratories. ECHA REACH restrictions on phthalate plasticizers force reformulation of closure elastomers ahead of sunset dates. The Rhine-Main industrial cluster hosts automated production lines serving centralized European lab networks.
Japan
PMDA's distinct JIS standards for vacuum blood collection tubes create dedicated supply contracts for compliant foreign manufacturers. Hospital networks upgrade collection infrastructure under intensified quality system surveillance. The Kanto region around Tokyo concentrates diagnostic infrastructure investment from both domestic and multinational suppliers.
India
PLI scheme incentives for medical devices attract domestic vial manufacturing capacity for expanding lab network coverage. CDSCO registration pathways for Class A/B medical devices compress market entry timelines relative to European benchmarks. Gujarat and Maharashtra industrial corridors host emerging fabrication capacity targeting hospital central laboratory procurement.
China
NMPA medical device registration reforms streamline approval timelines for polymer-based diagnostic containers. Domestic lab automation expansion drives specification alignment with international dimensional standards. The Yangtze River Delta manufacturing belt concentrates injection-molding capacity for medical-grade polypropylene conversion.
Diagnostic Vials Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments. The market structures around three tiers: multinational life science conglomerates with distribution breadth, mid-cap specialists with material science depth, and regional fabricators serving price-sensitive procurement. Competitive moves concentrate on automated production line expansion and pharmacopeial certification acquisition to defend positioning in consolidated buying environments.
Within the premium-tier vector, Thermo Fisher Scientific and Greiner Bio-One exemplify scale-driven archetypes with health system integration capabilities. Eppendorf AG occupies a position among specialists targeting molecular diagnostics workflows with polymer expertise. These three entities represent contrasting strategic postures: distribution breadth, automated manufacturing scale, and application-specific material science depth respectively.
| Leading Market Players |
|---|
| Greiner Bio-One |
| Eppendorf AG |
| Thermo Fisher Scientific |
| Heathrow Scientific |
| Globe Scientific |
| Corning Incorporated |
| Cole-Parmer |
| BrandTech Scientific |
| DWK Life Sciences |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery networks in the United States now mandate automated replenishment integration for primary packaging, forcing suppliers to absorb inventory carrying costs and compressing distributor margins across three-tier pricing structures. This procurement consolidation redirects margin pressure upstream toward resin suppliers and certification laboratories, fragmenting profitability across the value chain.
Pricing Analysis
Distributor margins in diagnostic vial channels absorb the heaviest compression as hospital central laboratories consolidate procurement through sole-source contracts. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-certified vials with full extractables documentation from basic clinical-grade alternatives. Pricing pressure stems from European energy costs elevating borosilicate glass furnace economics, while polymer variants face margin tightening due to ISO 10993 testing burdens. Research institutes in Japan exhibit the lowest price sensitivity, prioritizing JIS-certified vacuum integrity over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States integrated delivery networks, while regional distributors serve fragmented hospital procurement in India and China. Manufacturing concentrates in Germany, the United States, and China, with medical-grade polypropylene resin drawing from three global petrochemical suppliers. Borosilicate glass production rests on European furnace capacity exposed to natural gas price volatility. Single-source vulnerability in medical-certified polymer grades creates input concentration risk. Distribution runs through health system GPOs in North America and direct reference laboratory contracts in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diagnostic vials market functions as a stable compounder, with clinical laboratory automation driving replacement demand and specification upgrades across the installed base.
For Market Incumbents: Anchor defensive positioning through backward integration into medical-grade polypropylene resin sourcing to mitigate single-supplier concentration risk. Expand automated production line capacity in the Rhine-Main cluster to serve EU MDR-driven inventory replacement. Prioritize pharmacopeial certification acquisition for closure-liner systems to defend margin position against emerging polymer specialists. For New Entrants and Emerging Players: Begin with point-of-care molecular diagnostics vials for PCR workflows, where miniaturized plastic formats remain undersupplied relative to decentralized testing expansion. Target India's hospital central laboratory procurement under PLI scheme incentives, where CDSCO registration pathways compress market entry timelines. Pursue co-development partnerships with domestic lab automation OEMs to secure dimensional specification alignment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing material science depth and existing pharmacopeial extractables documentation. Long-term viability favors suppliers with captive polymer formulation capabilities and automated handling compatibility certification. Monitor EU MDR enforcement intensity and REACH substance restriction timelines as inflection indicators for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Certification Investment | USP and EP extractables documentation secures sole-source contracts with United States integrated delivery networks. |
| Automated Production Line Expansion | German reference laboratories demand dimensional tolerances synchronized with robotic handling system OEMs. |
| Backward Integration into Polymer Resin | Medical-certified polypropylene sourcing mitigates concentration risk among three global petrochemical suppliers. |
| Point-of-Care Format Development | Miniaturized vial designs for PCR workflows address undersupply in decentralized molecular diagnostics. |
| India Manufacturing Localization | PLI scheme incentives attract capacity targeting domestic hospital laboratory infrastructure expansion. |
Study Parameters
Multiple input streams — procurement manager interviews, biomedical engineer panels, regulatory affairs consultations, and GPO contract database analysis — were reconciled against secondary validation from FDA 510(k) filings, EU MDR technical documentation, and hospital supply chain disclosures. Bottom-up demand modeling from individual laboratory automation projects combined with top-down triangulation against medical device trade flows and resin consumption data.
Historical volume trajectories were cross-referenced against expert panel assessments of EU MDR implementation pacing and polymer substitution rates. Segmentation modeling incorporated material type, closure complexity, and end-user procurement consolidation stage across the projection horizon. CAGRs were derived from installed base expansion rates and replacement cycle compression in automated handling environments. Forecast inputs included PMDA JIS certification timelines and ECHA REACH substance restriction sunset dates.
Several conditions sit outside the modeled scope, including abrupt polymer supply disruptions, unscheduled regulatory enforcement intensity shifts, and laboratory automation OEM consolidation events. Forecasts reflect assumptions about EU MDR compliance pacing and polymer breakage reduction adoption curves. Periodic stress-testing of base assumptions is recommended against CDSCO registration pathway efficiency and NMPA reform implementation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Respiratory Masks Market
Medical Supplies
Global Needles Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Global Lancet and Pen Needles Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Global Dried Blood Spot Collection Cards Market
Medical Supplies
Cryoboxes Market