
 Epithelial Ovarian Cancer Market | 2026-2036
Epithelial Ovarian Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Epithelial Ovarian Cancer Market Analysis
Market Context
Oncology procurement at academic medical centers is bifurcating from community practice as complex biomarker testing and combination protocols concentrate in tertiary settings. AstraZeneca leverages its first-mover position in PARP inhibition through sustained investment in BRCA and HRD companion diagnostic infrastructure. Roche anchors the diagnostic backbone with its tissue-agnostic and tumor-specific assay platforms, while Merck & Co. competes through checkpoint inhibitor combinations in platinum-resistant populations.
Technical Definition and Segment Structure
Epithelial ovarian cancer comprises malignant neoplasms arising from the surface epithelium or fallopian tube epithelium of the ovary, characterized by serous, endometrioid, clear cell, or mucinous histopathological subtypes with distinct molecular driver profiles and chemotherapy responsiveness patterns. The disease's primary commercial purpose centers on extending progression-free survival through cytoreductive surgery followed by platinum-taxane chemotherapy and maintenance biologic therapy. PARP inhibitors within the drug class dimension command the dominant margin pool as maintenance therapy expands from BRCA-mutant to homologous recombination deficiency-positive populations, while immunotherapy represents the fastest-growing treatment type despite limited single-agent efficacy, with hospitals capturing the highest procedure volume among end user segments due to centralized surgical complexity.
Regulatory Framework and Outlook
FDA oncology drug approvals and EMA centralized marketing authorizations shape demand through accelerated pathways for breakthrough therapies, while NCCN guideline incorporations directly influence payer coverage determinations and prescribing behavior in the United States. The country's national pharmaceutical regulator maintains stringent pharmacovigilance requirements for novel biologics, creating compliance barriers that favor established manufacturers with integrated safety databases. Stakeholders must monitor emerging biomarker definitions and companion diagnostic co-development requirements to anticipate shifts in addressable patient populations and reimbursement thresholds.
Market Dynamics
Academic medical centers are consolidating complex ovarian cancer care into tertiary hubs, concentrating surgical volume and biomarker-directed therapy decisions away from community oncology practices. This structural concentration reshapes competitive positioning across drug manufacturers and diagnostic platform vendors.
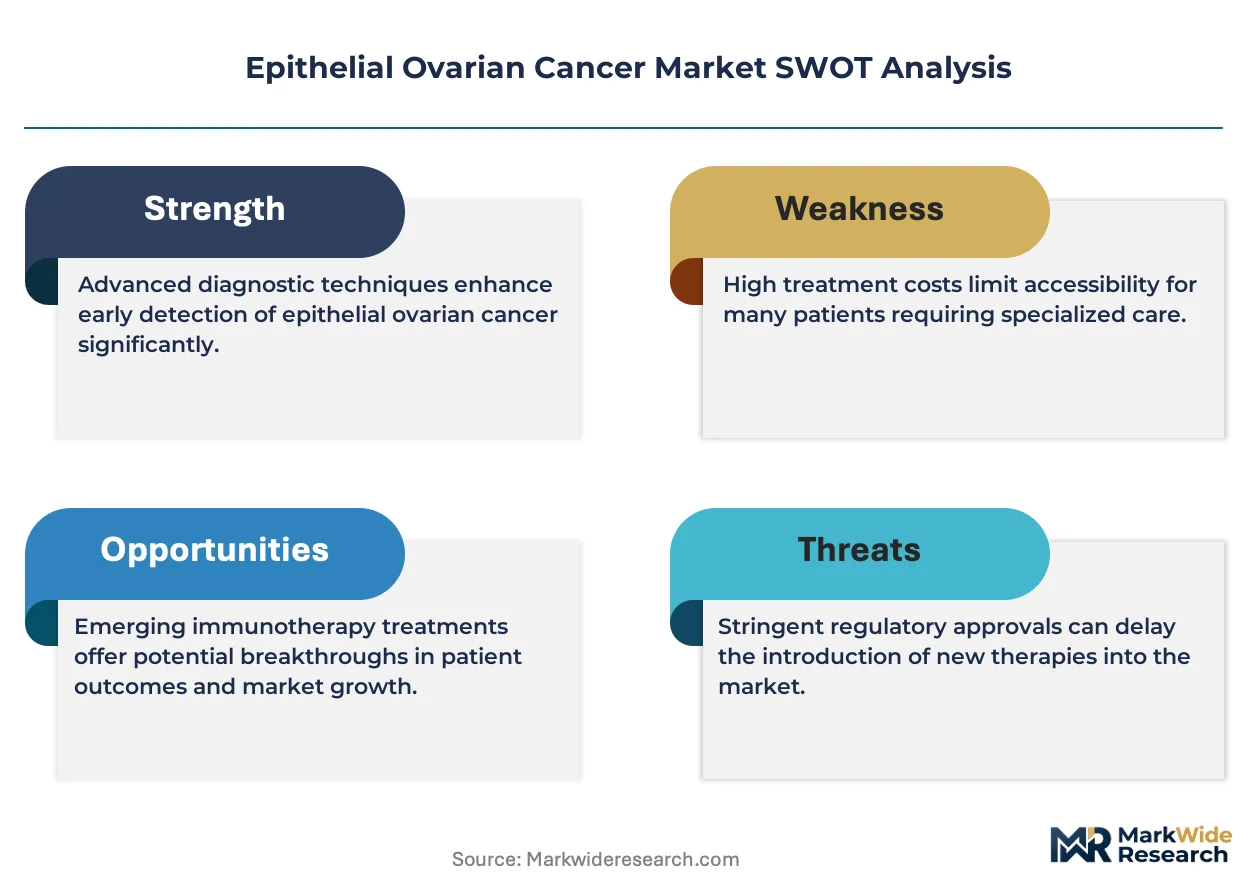
Growth Catalysts
- Frontline PARP maintenance expansion:FDA and EMA approvals for homologous recombination deficiency-positive populations extend addressable patient pools beyond BRCA-mutant subsets. Academic centers now standardize maintenance sequencing protocols.
- HRD companion diagnostic infrastructure:Tertiary hospitals invest in integrated tissue and liquid biopsy platforms to stratify patients for PARP inhibitor eligibility. Testing consolidation drives protocol adherence.
- Medicare reimbursement alignment:NCCN guideline updates for biomarker-directed therapy directly influence Medicare coverage determinations, accelerating access to maintenance regimens in United States hospital systems.
Market Restraints
- Platinum resistance biology:Recurrent disease mechanisms limit durable responses to PARP monotherapy in homologous recombination-proficient tumors, constraining label expansion potential.
- Diagnostic access fragmentation:Community oncology settings lack standardized HRD testing infrastructure, creating a two-tier treatment access pattern between academic and non-academic sites.
- Immunotherapy efficacy ceiling:Checkpoint inhibitors demonstrate limited single-agent activity in epithelial ovarian cancer, dampening investment in monotherapy development programs.
Strategic Opportunities
- Platinum-resistant combination protocols:Anti-angiogenic and checkpoint inhibitor combinations in recurrent disease represent underserved populations with unmet medical need.
- FALLOPIAN tube origin reclassification:Shifting surgical paradigms toward risk-reducing salpingectomy creates preventive intervention markets in BRCA-mutation carriers.
- Real-world evidence generation:Flatiron and similar oncology data networks enable post-approval efficacy tracking to support label expansion and payer negotiations.
Industry Challenges
- Gynecologic oncology surgical workforce constraints:Complex cytoreductive procedures require specialized training pipelines that academic centers struggle to scale.
- Companion diagnostic co-development timelines:Synchronized FDA approval of drug and test creates regulatory complexity that delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epithelial Ovarian Cancer Market |
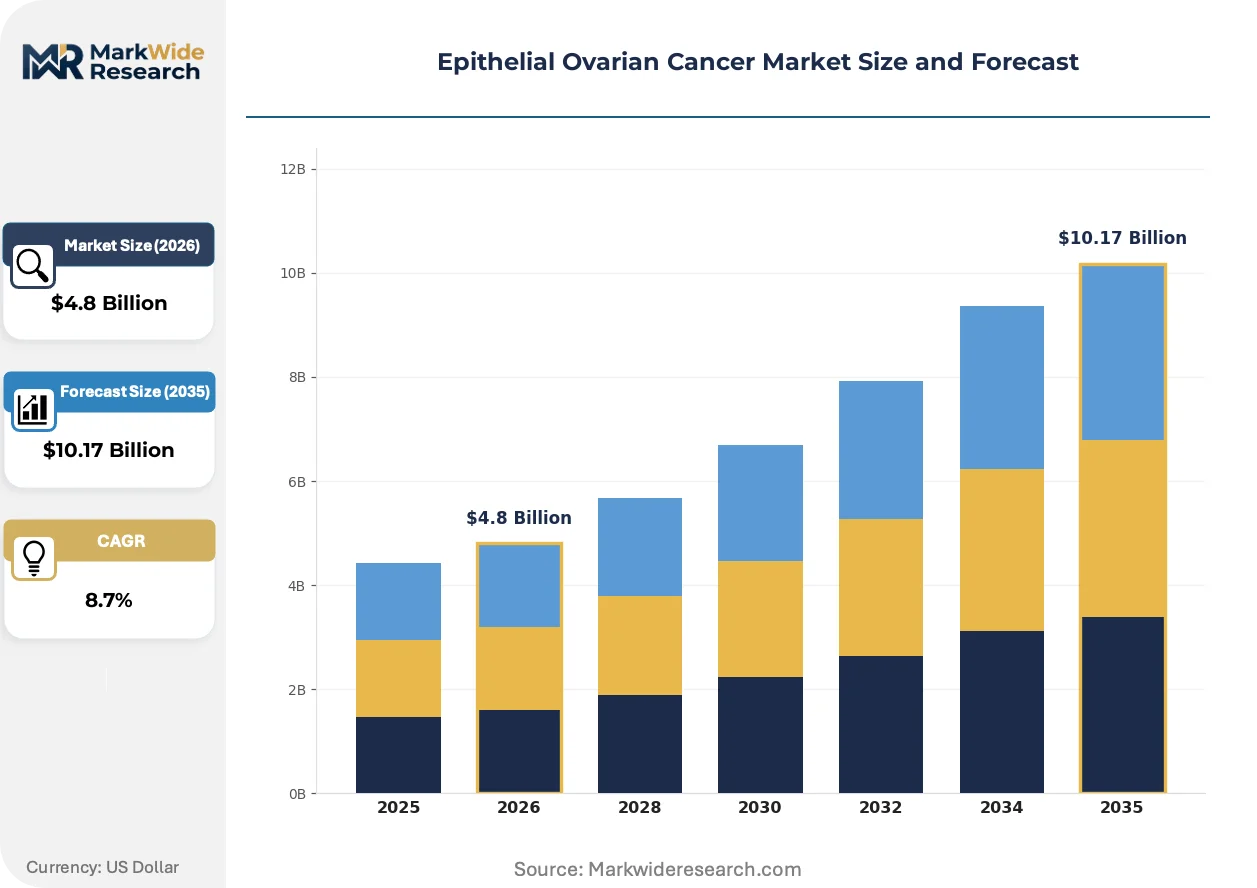
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Chemotherapy, Targeted Therapy, Immunotherapy Stage of Disease: Stage I, Stage II, Stage III, Stage IV End User: Hospitals, Clinics, Research Institutes, Homecare Settings Drug Class: PARP Inhibitors, Chemotherapeutics, Monoclonal Antibodies, Cytotoxic Agents |
| Companies Covered | AstraZeneca, Roche, GSK, AbbVie, Merck & Co., Novartis, Pfizer, Bristol Myers Squibb, Eli Lilly, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epithelial Ovarian Cancer Market Emerging Trajectories
Liquid biopsy platforms are displacing tissue-based testing as the primary modality for treatment monitoring and resistance detection. This technological pivot compresses turnaround times and enables serial sampling in ways that reshape clinical trial design and real-world care delivery.
Next-generation sequencing panels for minimal residual disease detection are miniaturizing into point-of-care formats. Community oncology networks in the United States pilot cartridge-based platforms to decentralize HRD testing. This capability compression erodes the diagnostic monopoly of centralized academic laboratories and forces platform vendors to defend installed bases through service contracts.
EMA's revised oncology guideline on maintenance therapy endpoints now requires overall survival data for full approval, not merely progression-free survival surrogates. This regulatory elevation lengthens development timelines but raises the evidence bar for reimbursement in European markets. Manufacturers with mature phase III programs capture first-mover advantage while late entrants face higher evidentiary hurdles.
Hospital pharmacy committees now unbundle drug procurement from diagnostic service agreements, reversing prior bundled contracting models. United States health systems separately negotiate PARP inhibitor formulary placement and companion diagnostic reference lab contracts. This purchasing fragmentation creates pricing transparency that erodes manufacturer rebate structures and shifts negotiation leverage toward institutional buyers.
Epithelial Ovarian Cancer Market Segmentation
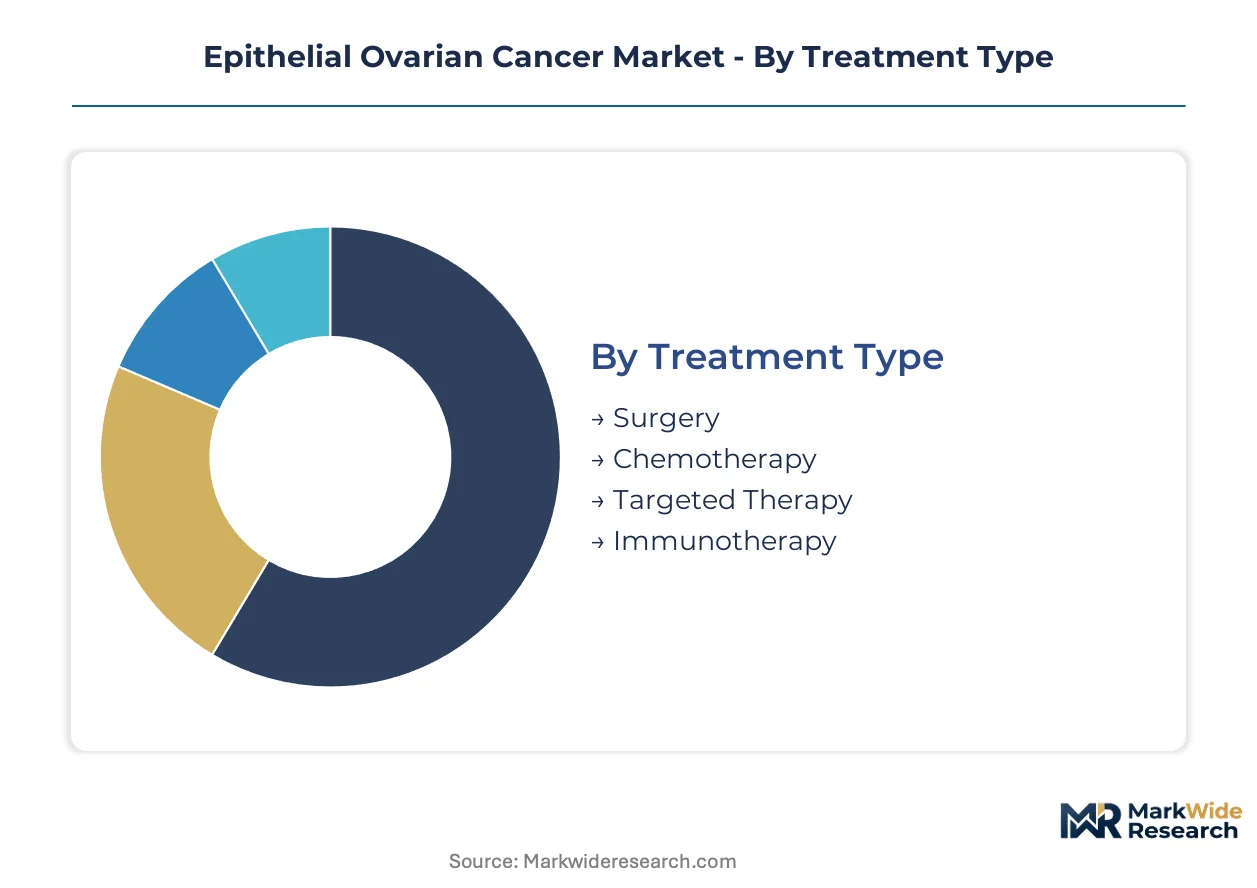
Epithelial ovarian cancer treatment protocols fragment across multiple decision axes, with biomarker status and surgical candidacy determining eligibility for specific therapeutic modalities. Manufacturers and providers must align portfolio investments with the concentration of complex care in tertiary hospital systems and the evolving regulatory requirements for companion diagnostic pairing.
Treatment Type:
FDA and EMA approval pathways diverge sharply across these modalities, with accelerated designations concentrating in targeted therapy while surgery maintains device-centric regulatory oversight through separate quality system requirements.
- Surgery:Cytoreductive procedures involving total abdominal hysterectomy, bilateral salpingo-oophorectomy, and omentectomy constitute the foundational intervention for all stages. Academic medical centers in the United States concentrate complex debulking volume, with Medicare reimbursement rates directly influencing institutional capacity expansion for minimally invasive approaches.
- Chemotherapy:Platinum-taxane combination regimens remain the cytotoxic backbone for adjuvant and neoadjuvant protocols. Community oncology practices in the United States administer the majority of cycles, though dose-dense scheduling requires hospital-based infusion center capacity.
- Targeted Therapy:PARP inhibitors and anti-angiogenic agents require HRD companion diagnostic confirmation prior to initiation.
- Immunotherapy:Checkpoint inhibitors demonstrate limited single-agent efficacy but feature in combination trials for platinum-resistant populations.
Chemotherapy handles the majority of throughput; targeted therapy is the fastest mover on share.
Stage of Disease:
Cost tiers stratify sharply across stages, with advanced disease consuming disproportionate resource intensity per patient due to repeated surgical interventions and sequential lines of systemic therapy.
- Stage I:Confined to ovaries or fallopian tubes with intact capsule and no surface involvement. Early detection programs in the United States target BRCA-mutation carriers for risk-reducing surgery, creating preventive intervention revenue streams distinct from therapeutic oncology.
- Stage II:Pelvic extension with uterine or fallopian tube involvement but no extrapelvic spread. Intermediate complexity drives community hospital surgical volume where gynecologic oncology fellowship training varies.
- Stage III:Peritoneal implants outside pelvis or retroperitoneal lymph node involvement. Tertiary centers capture the majority of cytoreductive procedures, with NCCN guidelines mandating specialist surgeon involvement for optimal debulking outcomes.
- Stage IV:Distant metastases to liver parenchyma or extra-abdominal organs. Palliative care integration and clinical trial enrollment concentrate at National Cancer Institute-designated comprehensive cancer centers.
Stage III commands the dominant procedure volume; Stage I shows the steepest expansion trajectory from preventive screening protocols.
End User:
Customer type determines purchasing authority structure, with hospital pharmacy committees controlling formulary placement while research institutes operate under separate grant-funded procurement mechanisms.
- Hospitals:Integrated delivery networks negotiate bundled contracts for PARP inhibitors and companion diagnostic services. United States health systems with gynecologic oncology fellowship programs capture complex surgical referrals from surrounding community practices.
- Clinics:Community oncology practices face diagnostic access fragmentation for HRD testing, creating referral patterns to academic center laboratories.
- Research Institutes:Early-phase clinical trial units require specialized pharmacy infrastructure for investigational agent handling.
- Homecare Settings:Oral PARP inhibitor maintenance enables administration outside infusion centers, though monitoring requirements limit full decentralization.
Hospitals absorb the majority of acute intervention volume; homecare settings are climbing the fastest as oral maintenance protocols expand.
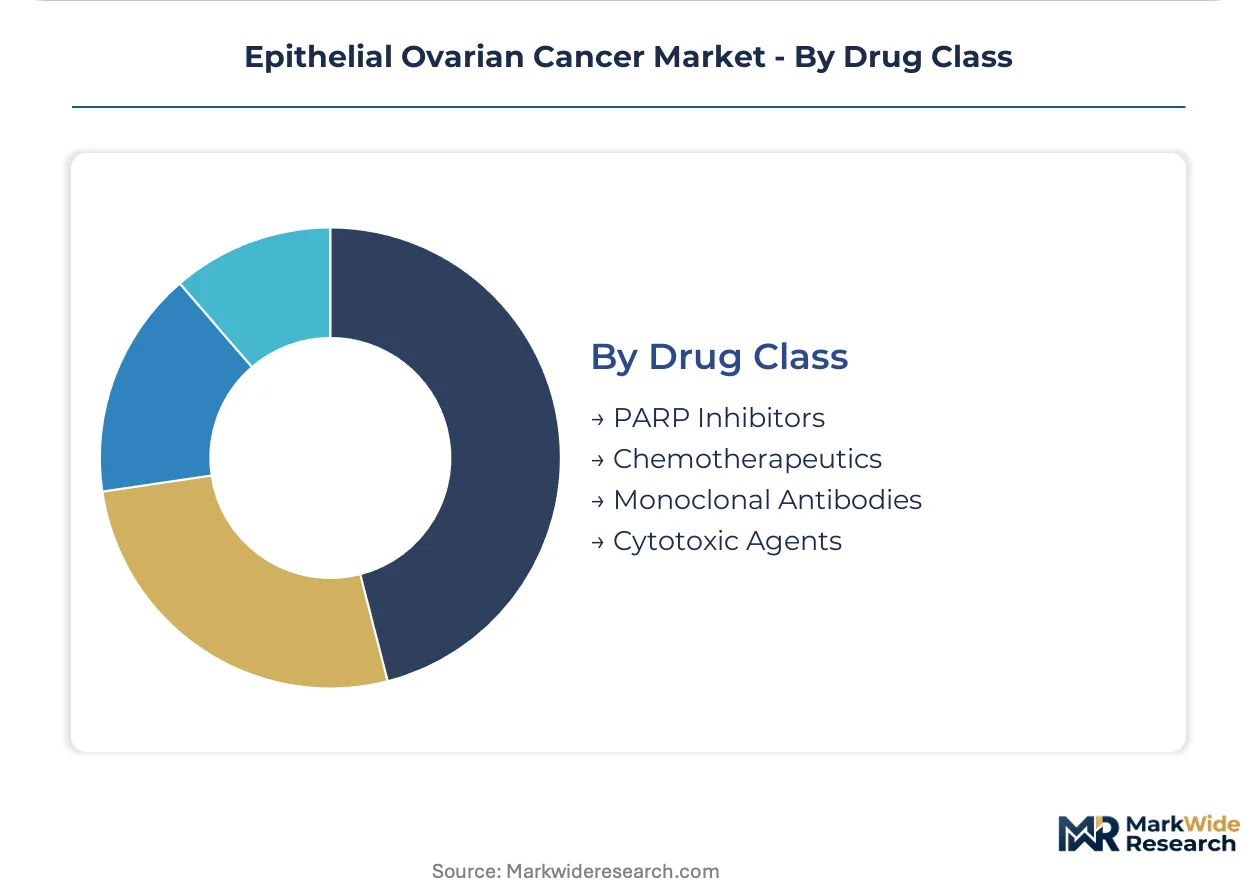
Drug Class:
Margin concentration varies dramatically, with PARP inhibitors commanding premium pricing supported by companion diagnostic exclusivity while cytotoxic agents face generic erosion.
- PARP Inhibitors:Small-molecule inhibitors of poly ADP-ribose polymerase exploit synthetic lethality in HRD-positive tumors. FDA maintenance approvals for frontline therapy in the United States have shifted treatment sequencing, with olaparib, niraparib, and rucaparib competing for formulary placement.
- Chemotherapeutics:Carboplatin and paclitaxel constitute the platinum-taxane standard, with biosimilar competition emerging for supportive care agents.
- Monoclonal Antibodies:Bevacizumab maintains indication in frontline and recurrent settings despite biosimilar entry.
- Cytotoxic Agents:Liposomal doxorubicin and topotecan serve platinum-resistant salvage protocols with established reimbursement codes.
PARP inhibitors capture the dominant margin pool; monoclonal antibodies face the steepest pricing pressure from biosimilar substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate the highest surgical volume and biomarker-directed therapy adoption, while tertiary hospitals in Germany and Japan build comparable HRD testing infrastructure. Payer reimbursement policies and regulatory approval timelines create sharp access gradients across national markets.
United States
Medicare reimbursement alignment with NCCN guidelines accelerates PARP inhibitor maintenance access in hospital systems. FDA accelerated approval pathways for frontline therapy indications compress commercialization timelines for manufacturers. The MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center anchor clinical trial enrollment and protocol standardization for biomarker-directed sequencing.
Germany
EMA centralized marketing authorizations for ovarian cancer therapies establish reference pricing across EU member states. The country's statutory health insurance system mandates companion diagnostic confirmation prior to targeted therapy reimbursement. Heidelberg University Hospital and Charité Berlin concentrate gynecologic oncology surgical fellowships and HRD testing capacity.
Japan
PMDA oncology drug reviews incorporate overall survival endpoints earlier than other regulators, shaping development program design for Asia-Pacific submissions. The national health insurance price listing process creates predictable reimbursement timelines for approved therapies. National Cancer Center Hospital in Tokyo anchors Phase I/II trial infrastructure for platinum-resistant combination protocols.
United Kingdom
NICE technology appraisals for ovarian cancer therapies apply cost-effectiveness thresholds that filter market access for premium-priced biologics. NHS England's specialized commissioning framework concentrates complex surgery in Cancer Alliance-designated centers. The Royal Marsden NHS Foundation Trust and University College London Hospitals anchor translational research partnerships for liquid biopsy validation.
China
NMPA priority review pathways for innovative oncology drugs accelerate market entry for multinational manufacturers with local clinical data. The national reimbursement drug list update cycle creates biennial access windows for price-negotiated inclusion. Fudan University Shanghai Cancer Center and Peking Union Medical College Hospital concentrate gynecologic oncology volume and biomarker testing adoption.
Epithelial Ovarian Cancer Market Vendor Landscape
Player mix skews toward integrated pharmaceutical conglomerates with oncology franchises spanning small-molecule, biologic, and diagnostic assets. Market structure concentrates around three to five manufacturers with approved PARP inhibitors and established companion diagnostic partnerships. Two strategic archetypes dominate: vertically integrated oncology specialists with diagnostic co-development capabilities, and diversified pharma majors leveraging immunology and immuno-oncology platforms. Competitive moves center on label expansion through Phase III maintenance trials and real-world evidence generation to support payer negotiations.
Within the integrated oncology tier, AstraZeneca and Roche occupy positions as archetype anchors for PARP inhibitor and diagnostic platform development respectively. GSK represents the mid-scale pharmaceutical archetype with oncology portfolio diversification through acquisition. These three companies exemplify the competitive positioning required to synchronize drug and companion diagnostic regulatory submissions across FDA and EMA jurisdictions.
| Leading Market Players |
|---|
| AstraZeneca |
| Roche |
| GSK |
| AbbVie |
| Merck & Co. |
| Novartis |
| Pfizer |
| Bristol Myers Squibb |
| Eli Lilly |
| Others |
Supply Flow & Price Mechanics
Liquid biopsy cartridge platforms are displacing centralized tissue-based HRD testing, simultaneously shifting supply geography from academic medical center laboratories toward distributed point-of-care networks and compressing pricing economics for companion diagnostic vendors defending installed bases through service contracts.
Pricing Analysis
Cost-plus contracts with Medicare reimbursement indexation anchor PARP inhibitor pricing in United States hospital systems. Three-tier pricing structure across premium branded, authorized generic, and economy biosimilar levels differentiates olaparib, niraparib, and rucaparib formulary placement. Pricing pressure stems from unbundled procurement negotiations separating drug from diagnostic contracts. Community oncology clinics exhibit highest price sensitivity; NCI-designated comprehensive cancer centers demonstrate lowest.
Supply Chain Analysis
FDA-registered companion diagnostic kit manufacturing concentrates in the United States, Germany, and Japan, with reagent production anchored in Singapore and Ireland. Active pharmaceutical ingredients for PARP inhibitors draw from specialized chemical synthesis facilities in Switzerland and India, while monoclonal antibody biologics hinge on mammalian cell culture capacity in South Korea and the Netherlands. Single-source vulnerability runs through CRISPR guide RNA suppliers for HRD test development. Distribution runs through integrated delivery network pharmacy committees controlling formulary access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation in the United States, with integrated delivery networks now controlling PARP inhibitor procurement for populations exceeding five million covered lives.
For Market Incumbents: Shield maintenance therapy market share through backward integration into liquid biopsy platform development, countering diagnostic commoditization threats from point-of-care entrants. Deepen vertical control over HRD testing data pipelines to preserve companion diagnostic exclusivity. Prioritize real-world evidence generation partnerships with Flatiron and similar oncology networks to defend pricing in Medicare coverage determinations. For New Entrants and Emerging Players: Community oncology HRD testing access fragmentation offers white-space entry for cartridge-based platforms bypassing academic laboratory referral requirements. Platinum-resistant combination protocols represent the most penetrable therapeutic segment, with checkpoint inhibitor-anti-angiogenic pairings underserved by current PARP-focused portfolios. Pursue risk-sharing agreements with United States gynecologic oncology group purchasing organizations as primary go-to-market channel. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated diagnostics developers with synchronized FDA drug-test submission capabilities and established Medicare coverage codes. Long-term viability across the projection horizon rests on capturing biomarker-defined patient stratification infrastructure rather than single-agent therapeutic assets. Watch EMA maintenance therapy endpoint guidance evolution as inflection signal for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Synchronized FDA submissions with olaparib or niraparib shorten time-to-reimbursement in Medicare hospital systems. |
| Real-World Evidence Partnership | Flatiron Health data access supports label expansion negotiations with NCCN guideline committees. |
| Liquid Biopsy Platform Miniaturization | Cartridge-based HRD testing erodes academic laboratory diagnostic monopolies in community oncology settings. |
| Platinum-Resistant Combination Trial | Checkpoint inhibitor-anti-angiogenic protocols address unmet need in recurrent disease populations beyond PARP efficacy. |
| Integrated Delivery Network Contracting | Bundled PARP inhibitor and testing agreements secure formulary placement against biosimilar substitution pressure. |
Methodological Framework
Initial hypotheses were tested against primary input from gynecologic oncology fellowship directors, hospital pharmacy committee chairs, payer access specialists, and companion diagnostic platform engineers and refined through secondary validation against FDA approval documents, EMA centralized marketing authorization databases, ClinicalTrials.gov enrollment records, and Medicare Part B reimbursement fee schedules. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation across the analysis window.
Variance decomposition across treatment line, disease stage, biomarker status, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level growth rate blending weighted by addressable patient population. Forecast inputs incorporated NCCN guideline revision cycles, Medicare coverage determination timelines, and EMA maintenance therapy endpoint requirement evolution throughout the modeling period.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA centralized marketing authorization procedures; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as PMDA overall survival endpoint requirements and NICE cost-effectiveness threshold revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
America Cancer Immunotherapy Market
Oncology
Colorectal Cancer Market
Oncology
Bone Metastasis Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
North America Proton Therapy Market
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Esophageal Cancer Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Bone Cancer Treatment Market
Oncology
France Radiation Oncology Market
Oncology
Global Proton Therapy Market
Oncology
Sterile Oncology Injectable Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Esophageal Cancer Drugs Market