
 Cryopreservation & Fertilization Media Market | 2026-2036
Cryopreservation & Fertilization Media Market Size, Share, and Industry Trends Forecast 2026-2036
Cryopreservation & Fertilization Media Market Analytics
Pharmaceutical-grade specification tiers is unwinding older research-grade formulations across fertility media portfolios. Thermo Fisher Scientific leverages its GMP-certified manufacturing footprint to supply validated cryopreservation kits directly into hospital pharmacy chains. Merck KGaA anchors European distribution through its life-science division, competing on DMSO purity grades that exceed USP monograph thresholds. Vitrolife AB specializes in sequential media systems for blastocyst-stage embryo culture, differentiating through ISO 13485-certified production lines that fertility clinics favor for regulatory audit readiness.
Cryopreservation and fertilization media comprise sterile, buffered solutions formulated with defined electrolyte balances, energy substrates, and protein supplements designed to maintain cellular viability through temperature reduction and subsequent warming cycles. These media typically incorporate permeating cryoprotectants at concentrations between 1.0 and 1.5 Molar to control ice crystal formation during controlled-rate freezing protocols. Embryo freezing applications command the largest revenue share within the application dimension, though oocyte preservation exhibits the steepest trajectory as vitrification protocols replace slow-freeze methods. Among solution types, dimethyl sulfoxide retains dominant position for sperm banking protocols, while ethylene glycol formulations are displacing DMSO in oocyte vitrification due to reduced cytotoxicity profiles and improved post-thaw fertilization rates.
FDA oversight through 21 CFR Part 1271 human cells, tissues, and cellular and tissue-based products regulations shapes formulation disclosure and donor screening documentation requirements for commercial media suppliers. The EMA's Good Manufacturing Practice guidelines for ancillary medicinal substances in advanced therapy medicinal products create parallel compliance obligations for manufacturers serving European fertility networks. Stakeholders must monitor evolving pharmacovigilance expectations around novel cryoprotectant chemistries, as regulators on both sides of the Atlantic assess whether certain formulations warrant reclassification as drug-device combination products subject to premarket authorization pathways.
Market Dynamics
Vitrification protocols are compressing slow-freeze methodologies across fertility networks, while FDA's 21 CFR Part 1271 traceability mandates are forcing wholesale reformulation of donor-derived media portfolios.
Growth Catalysts
- Elective oocyte banking:Delayed parenthood decisions among professionals are expanding fertility preservation services beyond traditional infertility treatment.
- EMA Good Manufacturing Practice guidelines:European ancillary medicinal substance standards are accelerating GMP-validated media adoption across fertility clinic networks.
- Vitrification chemistry advances:Ethylene glycol formulations with reduced cytotoxicity profiles are opening new protocol options for oocyte preservation specialists.
Market Restraints
- Pharmaceutical-grade DMSO supply concentration:USP monograph-compliant cryoprotectant sourcing clusters among limited specialty chemical manufacturers, creating input vulnerability.
- ISO 13485 certification timelines:Eighteen-month quality management system validation cycles delay new entrant commercialization of blastocyst-stage media systems.
- Research-grade formulation obsolescence:Non-GMP validated legacy portfolios face accelerated write-downs as fertility clinic procurement committees mandate certified-grade documentation.
Strategic Opportunities
- Hospital pharmacy direct distribution:Bypassing traditional laboratory supply intermediaries through validated cold-chain logistics partnerships.
- Same-sex couple and single-parent demand:Evolving family formation patterns in metropolitan fertility hubs are expanding donor gamete banking service lines.
- Artificial intelligence-assisted embryo selection:Integration of computer vision grading systems with sequential media protocols creates bundled service differentiation.
Industry Challenges
- Embryologist training pipeline gaps:Specialized vitrification technique certification programs face capacity constraints relative to clinic expansion rates.
- Legacy slow-freeze infrastructure stranding:Controlled-rate freezing equipment depreciation schedules conflict with vitrification protocol transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryopreservation & Fertilization Media Market |
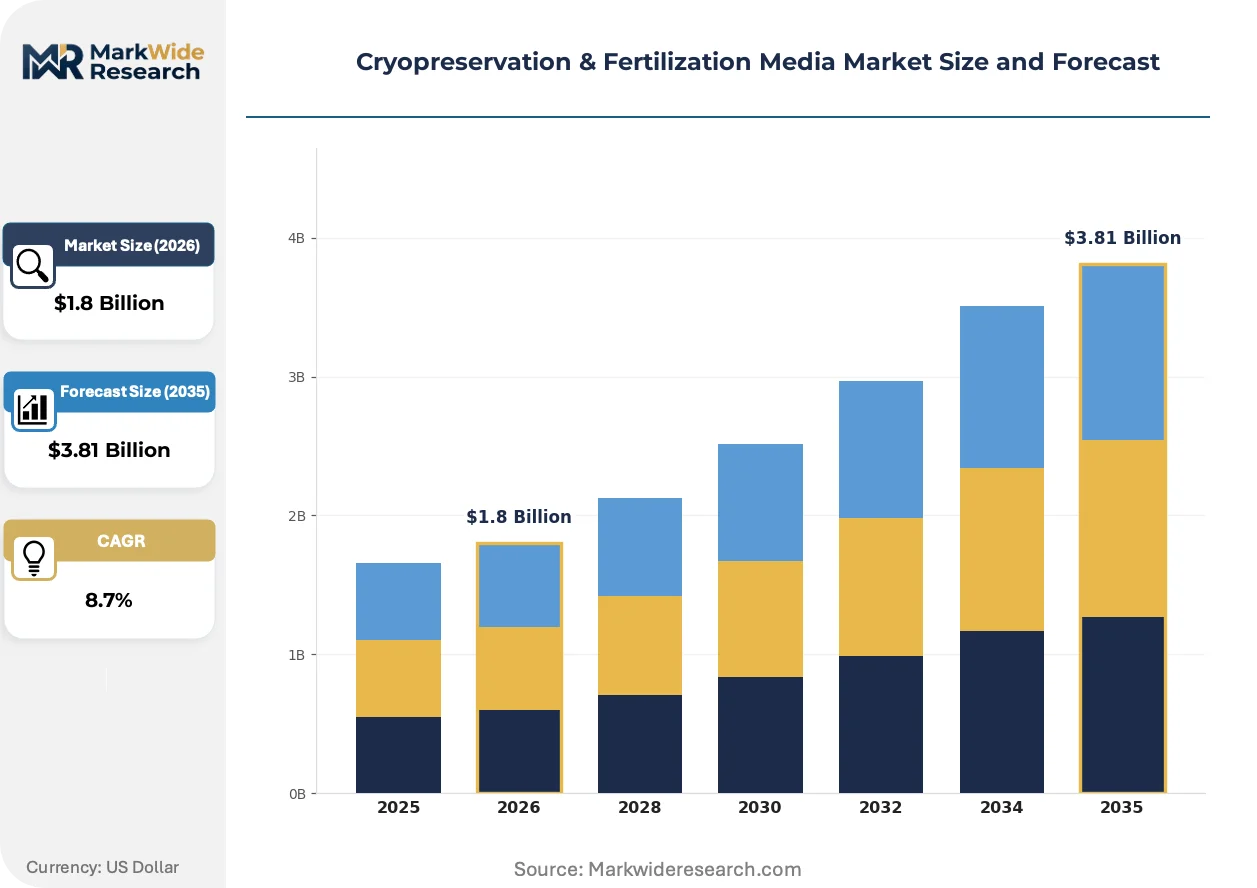
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryoprotectants, Media Supplements, Storage Containers, Thawing Solutions Application: Embryo Freezing, Oocyte Preservation, Sperm Banking, IVF Procedures End User: Fertility Clinics, Research Institutions, Hospitals, Biotechnology Firms Solution Type: Liquid Nitrogen, Dimethyl Sulfoxide, Ethylene Glycol, Hydroxyethyl Starch |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Cooper Surgical, Vitrolife AB, FUJIFILM Irvine Scientific, Sartorius AG, Cook Medical, Bio-Life Solutions, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryopreservation & Fertilization Media Market Evolving Landscape
Sequential media systems are redefining embryo culture workflows, while regulatory documentation requirements are hardening formulation transparency standards across supplier-customer relationships.
Vitrification is supplanting slow-freeze methodologies as the dominant oocyte preservation protocol. Fertility clinics in metropolitan medical centers are adopting ethylene glycol-based systems within eighteen-month equipment refresh cycles. This transition is compressing demand for controlled-rate freezing media while elevating requirements for ultra-rapid warming apparatus compatibility.
EMA's ancillary medicinal substance framework is extending Good Manufacturing Practice obligations to cryopreservation media suppliers serving advanced therapy networks. Manufacturers must now maintain drug master file documentation for protein supplement sourcing and endotoxin testing protocols. European fertility networks are responding by consolidating procurement around ISO 13485-certified suppliers with established pharmacovigilance systems.
Consolidated buying committees at networked fertility center groups are displacing individual clinic purchasing autonomy. Large multi-site operators in the United States are mandating unified GMP-validated media portfolios across their laboratory networks. This concentration is visible most acutely in states with favorable assisted reproduction insurance mandates, where volume scale supports direct manufacturer contracting.
Cryopreservation & Fertilization Media Market Segmentation
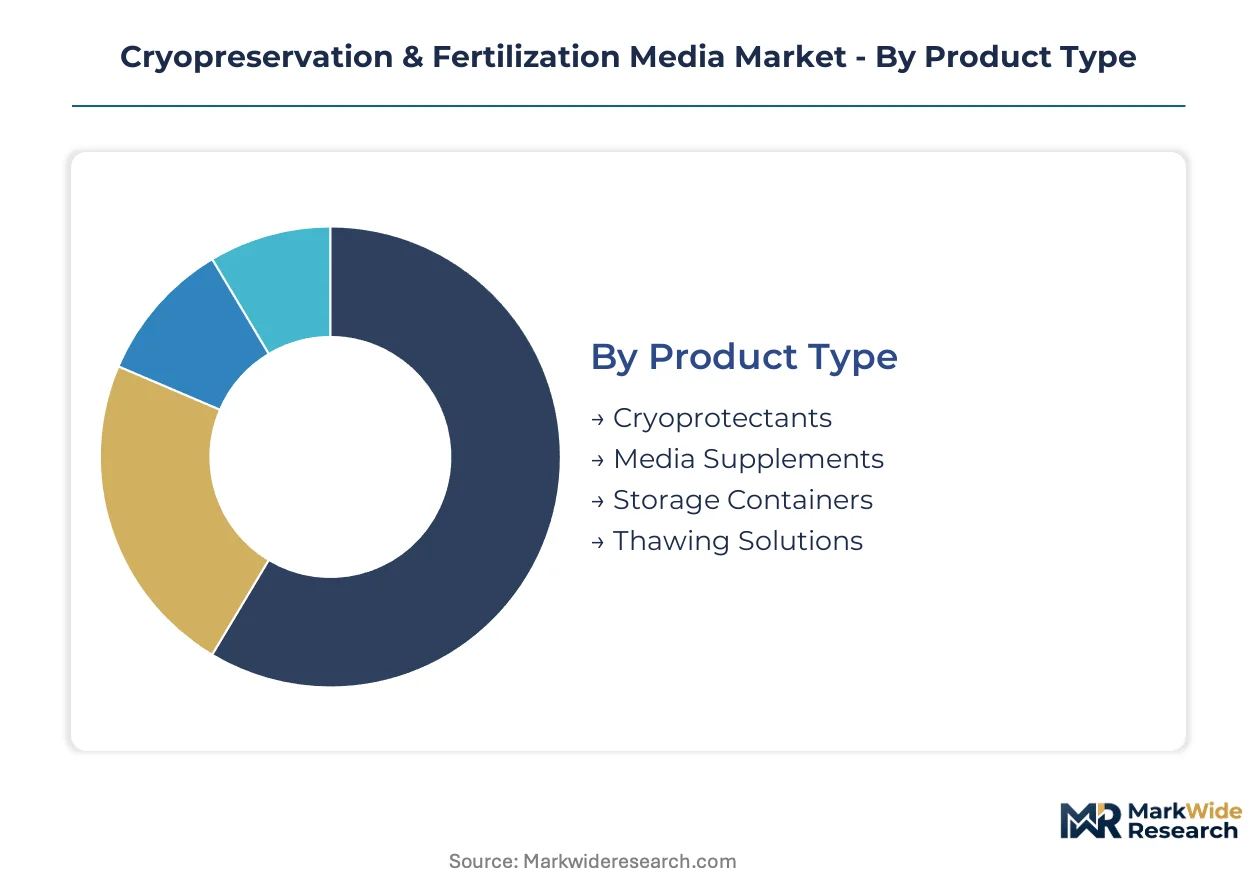
Segmentation in cryopreservation and fertilization media reflects divergent regulatory burdens across product categories. Manufacturers must architect separate compliance pathways for GMP-validated clinical formulations versus research-grade alternatives.
Product Type:
FDA's 21 CFR Part 1271 traceability mandates are forcing tiered certification requirements across product portfolios.
- Cryoprotectants:Permeating agents formulated at 1.0-1.5 Molar concentrations control ice crystal formation during controlled-rate freezing. Demand concentrates in US fertility networks consolidating procurement around USP monograph-compliant DMSO grades as donor-derived media documentation requirements tighten.
- Media Supplements:Protein-enriched additives maintain cellular viability through temperature reduction cycles. European fertility clinics favor ISO 13485-certified production lines for regulatory audit readiness under EMA ancillary medicinal substance frameworks.
- Storage Containers:Sterile vessels engineered for vapor-phase liquid nitrogen compatibility.
- Thawing Solutions:Buffered formulations engineered for rapid warming protocol compatibility.
Established volume favors Cryoprotectants; emerging adoption favors Media Supplements.
Application:
Protocol transitions are redistributing demand across clinical service lines.
- Embryo Freezing:Blastocyst-stage preservation commands the largest revenue share within clinical applications. US networked fertility centers drive volume toward sequential media systems as consolidated buying committees mandate unified GMP-validated portfolios across laboratory networks.
- Oocyte Preservation:Vitrification protocols are displacing slow-freeze methodologies for elective fertility banking. Metropolitan medical centers adopt ethylene glycol-based systems within accelerated equipment refresh cycles as delayed parenthood decisions expand service lines.
- Sperm Banking:DMSO-based formulations retain protocol dominance for donor gamete repositories.
- IVF Procedures:Integrated media workflows spanning retrieval through transfer.
Embryo Freezing anchors current procurement volumes; Oocyte Preservation is climbing the fastest.
End User:
Procurement autonomy is concentrating at the network level versus individual facility discretion.
- Fertility Clinics:Specialized reproductive medicine centers represent the fastest-expanding channel. Large multi-site operators in US states with favorable assisted reproduction insurance mandates are consolidating procurement and driving direct manufacturer contracting.
- Hospitals:Academic medical centers with integrated fertility divisions. Hospital pharmacy chains in the United States are receiving validated cryopreservation kits through direct distribution partnerships bypassing traditional laboratory supply intermediaries.
- Research Institutions:University-affiliated laboratories utilizing non-GMP validated formulations.
- Biotechnology Firms:Cell therapy developers requiring ancillary medicinal substance documentation.
Fertility Clinics capture the steepest expansion trajectory; Hospitals offer the deepest contract value.
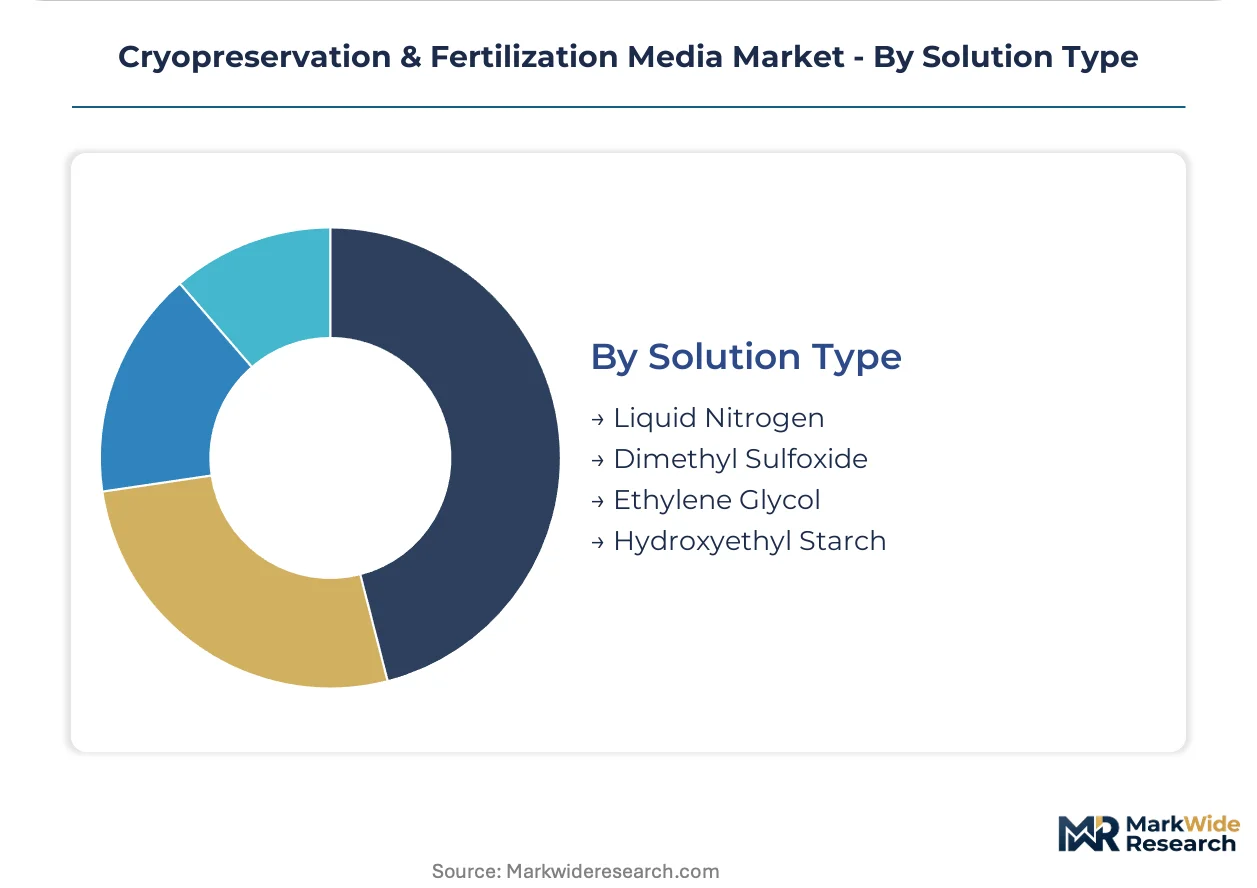
Solution Type:
Cryoprotectant chemistry selection dictates equipment compatibility and post-thaw viability outcomes.
- Dimethyl Sulfoxide:Permeating cryoprotectant retaining dominant position for sperm banking protocols. Supply concentrates among limited specialty chemical manufacturers creating input vulnerability for media formulators requiring USP monograph compliance.
- Ethylene Glycol:Reduced cytotoxicity profile is displacing DMSO in oocyte vitrification applications. Improved post-thaw fertilization rates are driving adoption across metropolitan fertility hubs transitioning from slow-freeze infrastructure.
- Liquid Nitrogen:Cryogenic storage medium maintaining vapor-phase repository temperatures.
- Hydroxyethyl Starch:Non-permeating cryoprotectant for specific cellular preservation protocols.
Dimethyl Sulfoxide maintains incumbent volume; Ethylene Glycol is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in cryopreservation media tilt toward net imports across most jurisdictions, with specialized cryoprotectant chemistry concentrating manufacturing in select chemical production clusters. Regulatory divergence between FDA and EMA frameworks shapes regional formulation requirements.
United States
Large networked fertility centers in states with favorable assisted reproduction insurance mandates drive procurement concentration toward GMP-validated portfolios. FDA's 21 CFR Part 1271 traceability requirements compel reformulation of donor-derived media with certified-grade cryoprotectants. Metropolitan medical centers in California, New York, and Massachusetts anchor demand for ethylene glycol-based vitrification systems.
Germany
Academic medical centers with integrated fertility divisions sustain demand for pharmaceutical-grade media specifications. EMA Good Manufacturing Practice guidelines for ancillary medicinal substances extend compliance obligations to cryopreservation media serving advanced therapy networks. The Rhine-Ruhr and Bavarian clusters host distributors competing on DMSO purity grades exceeding USP thresholds.
United Kingdom
London fertility hubs experience elevated demand from same-sex couples and single-parent family formation patterns expanding donor gamete banking services. The Human Fertilisation and Embryology Authority maintains stringent documentation requirements for protein supplement sourcing. Southeast England and Greater Manchester concentrate clinic networks consolidating procurement around ISO 13485-certified suppliers.
Japan
Delayed parenthood trends among professionals expand elective oocyte banking beyond traditional infertility treatment. PMDA oversight aligns with ICH guidelines for ancillary substances in cellular therapy applications. The Tokyo-Osaka corridor hosts fertility clinic networks transitioning from slow-freeze to vitrification protocols within accelerated equipment refresh cycles.
Australia
Research institutions and biotechnology firms developing cell therapies generate demand for non-GMP validated formulations alongside clinical-grade portfolios. TGA regulations for human cellular therapy products shape traceability documentation requirements. Sydney and Melbourne anchor fertility service networks adopting sequential media systems for blastocyst-stage embryo culture.
Cryopreservation & Fertilization Media Market Competitive Landscape
Listed leaders compete with private specialists across certification-grade tiers, with market structure consolidating around GMP-validated portfolios as fertility clinic procurement committees mandate unified documentation standards. Three archetypes dominate: diversified life-science conglomerates with GMP-certified manufacturing footprints, specialized reproductive medicine media suppliers with ISO 13485 production lines, and hospital pharmacy direct distributors leveraging validated cold-chain logistics. Competitive moves center on M&A to secure cryoprotectant supply positions and strategic partnerships with networked fertility center groups.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA represent archetypes of scale-driven suppliers leveraging GMP-certified manufacturing footprints to serve hospital pharmacy chains and European distribution networks respectively. Vitrolife AB occupies a specialist position exemplifying ISO 13485-certified production differentiation for regulatory audit readiness in fertility clinic networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Cooper Surgical |
| Vitrolife AB |
| FUJIFILM Irvine Scientific |
| Sartorius AG |
| Cook Medical |
| Bio-Life Solutions |
| Lonza |
| Others |
Value Network & Pricing Analysis
Ethylene glycol displacement of DMSO in oocyte vitrification protocols simultaneously redraws procurement geography toward European specialty chemical manufacturers and compresses pricing premiums for USP-grade dimethyl sulfoxide as fertility clinic demand bifurcates across cryoprotectant chemistries.
Pricing Analysis
Large networked fertility centers anchor contract pricing for GMP-validated media portfolios. Three-tier pricing structure across pharmaceutical-grade, clinical-grade, and research-grade certification levels reflects ISO 13485 audit readiness and drug master file documentation depth. Cost compression in research-grade tiers intensifies as procurement committees mandate certified-grade documentation for donor-derived media. Hospital pharmacy chains exhibit lowest price sensitivity due to bundled cold-chain logistics partnerships, while independent clinics face steepest margin pressure from reformulation compliance costs.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain European distribution economics for temperature-sensitive media formulations. Cryoprotectant manufacturing concentrates in Germany, Switzerland, and the United States, with DMSO purification anchored in Rhine-Ruhr chemical clusters and ethylene glycol formulation advancing through Swiss pharmaceutical corridors. Media production rests on USP monograph-compliant DMSO, recombinant protein supplements, and endotoxin-tested water systems. Single-source vulnerability permeates pharmaceutical-grade DMSO supply, where three specialty chemical manufacturers control monograph-compliant output. Distribution runs through validated cold-chain partnerships serving hospital pharmacy chains and direct manufacturer contracts with fertility network consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as elective fertility preservation penetrates professional demographics beyond traditional infertility treatment populations.
For Market Incumbents: Consolidate cryoprotectant supply positions through backward integration into USP monograph-compliant DMSO manufacturing or exclusive offtake agreements with Rhine-Ruhr chemical clusters. Lock in multi-year direct distribution contracts with networked fertility center groups before ISO 13485 certification mandates harden procurement committee requirements. For New Entrants and Emerging Players: Anchor in oocyte vitrification media segments where ethylene glycol formulation expertise creates differentiation against DMSO-legacy portfolios. Metropolitan fertility hubs in US states with favorable assisted reproduction insurance mandates present the most penetrable geography. Pursue hospital pharmacy direct distribution partnerships bypassing laboratory supply intermediaries as the primary go-to-market pathway. For Investors and Strategic Acquirers: FDA's anticipated 21 CFR Part 1271 enforcement escalation reshapes the acquisition landscape toward ISO 13485-certified manufacturers with established pharmacovigilance systems. Five-to-ten year viability favors specialists with sequential media system portfolios and blastocyst-stage culture expertise over diversified chemical conglomerates. Watch for EMA ancillary medicinal substance framework expansion into cryopreservation media as the definitive inflection signal for reclassification risk and premarket authorization pathway triggers.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | FDA's 21 CFR Part 1271 traceability mandates compel drug master file documentation for donor-derived media portfolios. |
| Cryoprotectant Supply Agreement | Exclusive DMSO offtake contracts with Rhine-Ruhr manufacturers secure USP monograph-compliant input for formulation pipelines. |
| Hospital Pharmacy Partnership | Direct distribution through validated cold-chain logistics bypasses laboratory supply intermediaries and captures contract value. |
| ISO 13485 Production Line Expansion | Eighteen-month quality management system validation cycles create defensive moats against new entrant commercialization timelines. |
| Vitrification Protocol Training Program | Embryologist certification capacity constraints present bundled service differentiation opportunities for media-integrated education offerings. |
Research Methodology
A standing panel of embryology laboratory directors, fertility clinic procurement managers, GMP manufacturing quality officers, and hospital pharmacy supply chain executives provided ongoing calibration against secondary validation through FDA 510(k) filings, EMA drug master file submissions, ISO 13485 audit registries, and fertility network annual procurement disclosures. Bottom-up volume estimates from individual clinic media consumption profiles triangulated against top-down manufacturer shipment data.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled encompassed product type, application, end-user channel, solution chemistry, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to vitrification protocol transition rates and fertility preservation service line expansion trajectories. Forecast inputs incorporated GMP validation timeline distributions and cryoprotectant supply concentration metrics.
Material uncertainties — regulatory reclassification of cryopreservation media as drug-device combination products, pharmaceutical-grade DMSO supply disruption, and fertility clinic network consolidation pace — sit outside the modeled envelope. Forecasts reflect assumptions around current FDA and EMA framework stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Microcarrier Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Hemodialysis Consumables Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
Medical Bags Market
Medical Supplies
Earwax Removal Aid Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Drainage Bottles Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Nucleic Acid Isolation and Purification Kits Market