
 Europe Insulin Syringe Market | 2026-2036
Europe Insulin Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Insulin Syringe Market Foresight
A capital-intensity divergence between automated assembly lines and manual packaging operations is rotating competitive advantage toward manufacturers with in-house molding capabilities. Becton Dickinson leverages its European sterilization infrastructure to sustain bulk supply contracts across national health systems. Terumo Corporation anchors its position through precision needle grinding technology that competes on unit consistency. B. Braun Medical Inc. differentiates via integrated distribution control over hospital supply channels in Central Europe.
Europe insulin syringes are single-use hypodermic devices typically constructed from medical-grade polypropylene barrels, stainless-steel needles with lubricant coatings, and elastomer plunger seals, designed to deliver measured insulin doses subcutaneously with minimal dead space. Safety syringes now lead volume growth as sharps-protection mechanisms become mandatory under evolving workplace safety directives. Home care dominates end-user expansion, while prefilled syringes capture margin pools through convenience premiums and reduced dosing-error liability. Plastic materials sustain cost leadership across high-volume tenders, though glass prefilled formats occupy premium reimbursement tiers in Nordic systems.
The EU MDR and EMA device oversight frameworks are elevating clinical evidence requirements for syringe biocompatibility and needlestick-prevention validation, compressing market access timelines for non-compliant suppliers. France's ANSM and Germany's BfArM enforce national vigilance reporting that shapes post-market surveillance obligations across the value chain. REACH chemical restrictions further constrain lubricant and adhesive selections in needle manufacturing. Stakeholders must monitor harmonized standards development for connected injection devices and decide whether to build digital dose-tracking capabilities or partner with diabetes platform developers.
Market Dynamics
EU Medical Device Regulation (MDR) sterility mandates are compressing market access timelines and forcing manufacturers to consolidate safety-engineered syringe portfolios ahead of 2027 certificate renewal waves.
Growth Catalysts
- Outpatient diabetes networks:Germany's reimbursement pathways for self-injection devices have matured, shifting insulin delivery from clinical settings to patient homes.
- EU MDR Article 10:Sharps-protection mechanism requirements are accelerating safety syringe standardization across member states.
- Polypropylene barrel molding:In-house polymer processing capabilities are reducing per-unit costs for high-volume tenders in Central European health systems.
Market Restraints
- Stainless-steel needle supply:Specialty steel sourcing concentrates in Austrian and Swedish mills, exposing manufacturers to alloy price volatility.
- REACH lubricant restrictions:Silicone oil formulations face ECHA scrutiny, forcing reformulation cycles that extend validation timelines.
- Prefilled glass alternatives:Nordic premium reimbursement tiers for glass formats are fragmenting demand away from conventional plastic syringes.
Strategic Opportunities
- French home care expansion:ANSM vigilance reporting standardization is creating pathways for connected injection device pilots in regional diabetes networks.
- Connected dose-tracking:Bluetooth-enabled syringes are converging with mobile health platforms, opening subscription revenue models.
- Central European hospital supply channels:Integrated distribution control over Czech and Polish procurement consortia remains underpenetrated by safety-engineered specialists.
Industry Challenges
- Biocompatibility validation:ISO 10993 testing timelines for elastomer plunger seals are extending MDR technical documentation preparation by 8-14 months.
- Precision needle grinding:Unit consistency tolerances below 0.05mm require specialized Swiss and Japanese equipment that faces 12-month delivery backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Insulin Syringe Market |
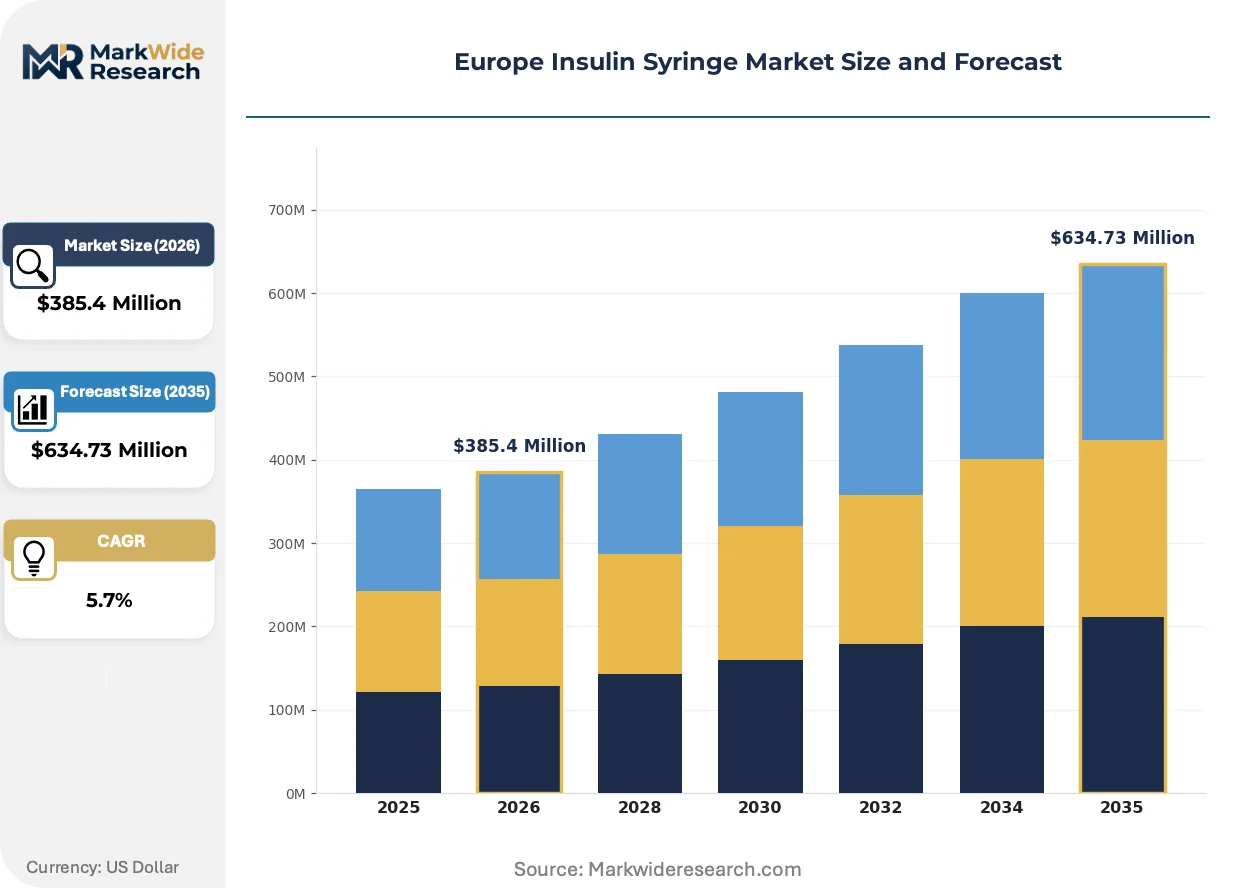
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringe, Safety Syringe, Insulin Pen, Prefilled Syringe End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Distribution Channel: Pharmacies, Online Retail, Hospital Supply, Wholesalers Material: Plastic, Glass, Rubber, Metal |
| Companies Covered | Becton Dickinson, Terumo Corporation, B. Braun Medical Inc., Nipro Corporation, HMD Healthcare Ltd., Cardinal Health, Smiths Medical, Medtronic plc, Gerresheimer AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Insulin Syringe Market Shifts & Advancements
Safety-engineered syringe architectures are fragmenting into modular component ecosystems as manufacturers decouple needle-stick prevention from barrel construction to accelerate regulatory recertification.
Passive retractable needle systems are decomposing the traditional fixed-needle syringe value chain. German outpatient diabetes networks are piloting these devices in 60-unit packs for high-frequency injectors. The technology is decomposing procurement bundling by separating sharps-protection certification from barrel sterilization validation, allowing mix-and-match supplier configurations.
EMA device oversight frameworks are tightening clinical evidence requirements for needlestick-prevention validation. Manufacturers must now submit prospective injury-rate data rather than simulated laboratory testing. Prefilled safety syringe categories face the steepest compliance burden as combination product rules overlap with MDR Article 117.
Hospital purchasing consortia are consolidating tender specifications around dead-space minimization metrics. Central European group procurement organizations are replacing single-attribute awards with multi-criteria frameworks weighting sterility assurance, unit consistency, and take-back program integration. France's regional health agencies are driving this shift through ANSM-mandated environmental compliance scoring.
Europe Insulin Syringe Market Segmentation
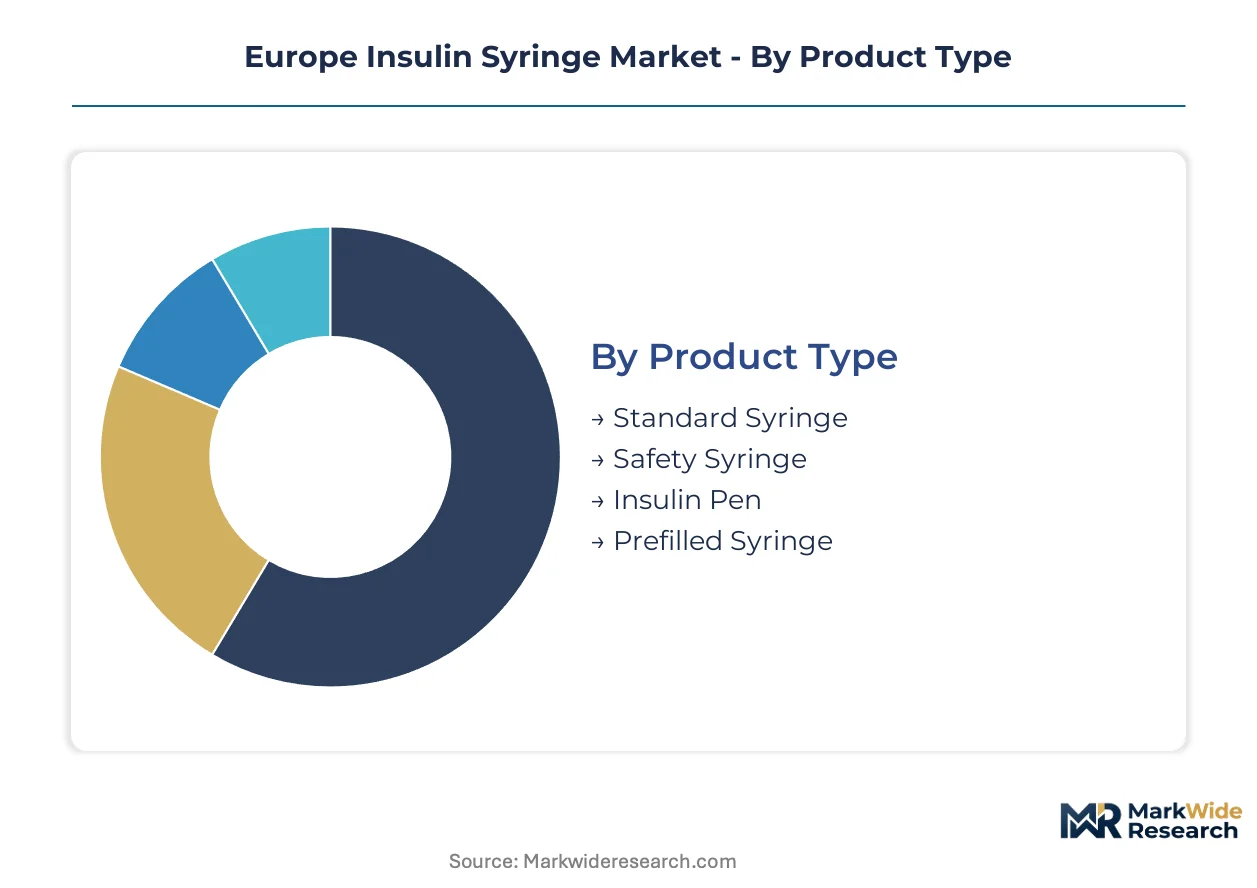
Segmentation in the Europe Insulin Syringe Market reveals how procurement power, reimbursement tiers, and regulatory compliance requirements reshape competitive positioning across distinct product configurations and delivery channels. Manufacturers must align portfolio depth with the specific evidence burdens and margin structures that govern each segment.
Product Type:
Margins concentrate in prefilled formats where combination product rules and convenience premiums protect pricing, while safety-engineered devices capture volume through mandatory sharps-protection procurement.
- Standard Syringe:Conventional fixed-needle devices constructed from polypropylene barrels and bonded stainless-steel cannulae. Demand concentrates in Central European hospital tenders where cost-per-unit dominates award criteria and bulk sterilization contracts sustain supply relationships.
- Safety Syringe:Passive retractable or shielded needle systems engineered for automatic sharps protection upon dose completion. Germany's outpatient diabetes networks are standardizing these devices through reimbursement pathway maturation that prioritizes needlestick-prevention liability reduction.
- Insulin Pen:Reusable cartridge-based injection systems with dose-dialing mechanisms and disposable needle attachments.
- Prefilled Syringe:Manufacturer-loaded single-use devices combining drug product with delivery system under EMA combination product oversight.
The dominant share belongs to Standard Syringe, while Safety Syringe is closing the gap fastest.
End User:
Volume scale tilts toward settings where self-injection training infrastructure and reimbursement for disposable supplies have achieved regulatory clarity.
- Hospitals:Acute care institutions managing inpatient glycemic control and perioperative insulin administration. Procurement runs through centralized supply consortia in France and Poland that weight sterility assurance and dead-space minimization in multi-criteria tenders.
- Home Care:Patient-directed injection environments supported by diabetes educator networks and remote monitoring platforms. France's regional health agencies are expanding pilot programs for connected device integration through ANSM-standardized vigilance reporting pathways.
- Clinics:Outpatient facilities providing injection training and acute complication management.
- Long-term Care Facilities:Residential settings managing polypharmacy populations with variable injection competency.
Home Care commands the largest volume position, with Hospitals retaining the densest procurement concentration.
Distribution Channel:
Channel economics fragment based on tender aggregation scale, cold-chain requirements, and the regulatory burden of traceability documentation.
- Hospital Supply:Direct contracting between manufacturers and health system procurement organizations. Central European consortia in the Czech Republic and Poland are consolidating specifications around integrated take-back programs and environmental compliance scoring.
- Pharmacies:Community-based dispensing points for prescription insulin and associated delivery devices. Germany's reimbursement pathways for self-injection devices have matured pharmacy-level stocking of safety-engineered formats.
- Online Retail:Direct-to-patient platforms bypassing traditional wholesale intermediaries.
- Wholesalers:Regional distributors consolidating fragmented demand across independent clinics and smaller facilities.
Hospital Supply anchors the highest volume throughput, though Pharmacies are gaining share through reimbursement pathway expansion.
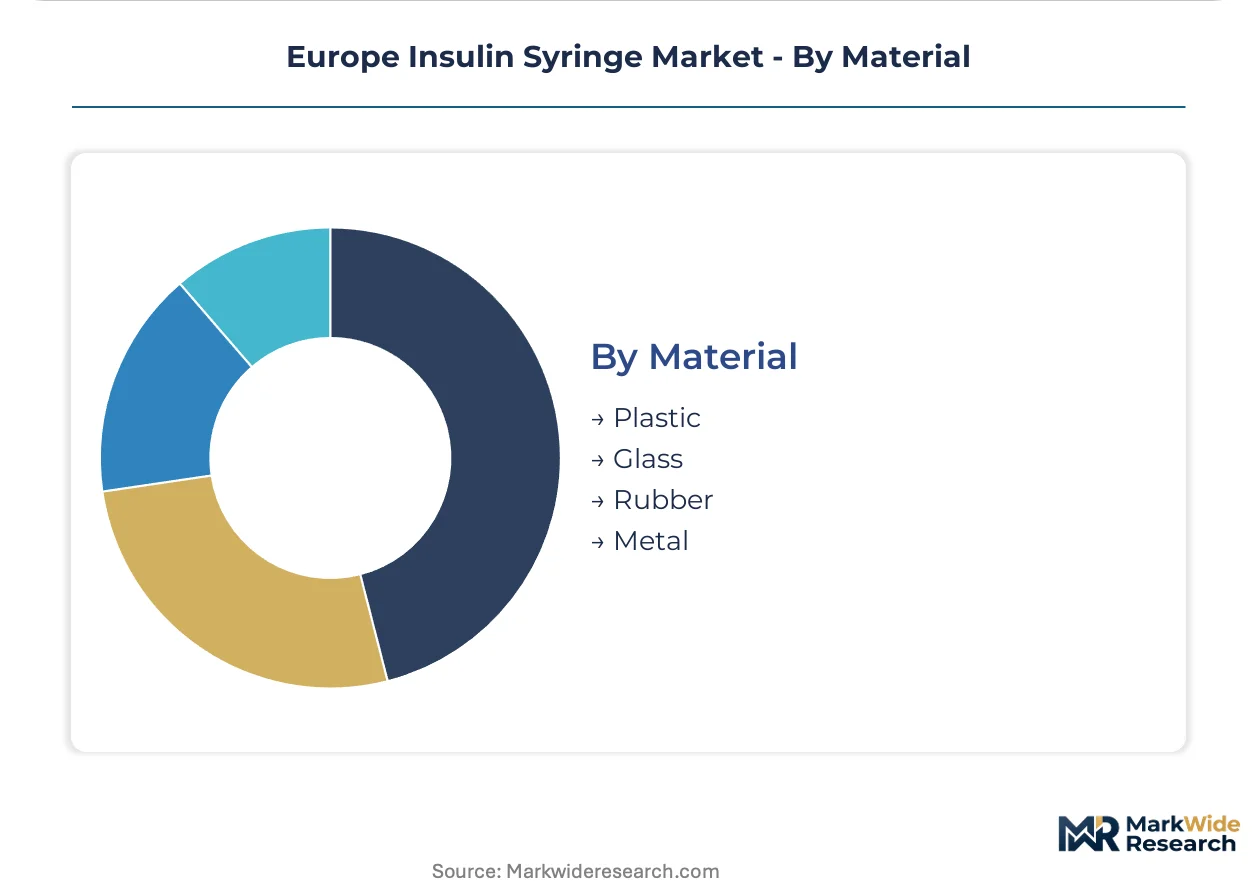
Material:
Cost structure and biocompatibility validation timelines diverge sharply between polymer-based disposables and glass formats serving premium reimbursement tiers.
- Plastic:Medical-grade polypropylene barrels and polyethylene packaging dominating high-volume production. In-house molding capabilities at major manufacturers are compressing per-unit costs for tenders across German and French national health systems.
- Glass:Borosilicate barrels for prefilled formats requiring drug-product compatibility and extended shelf stability. Nordic systems maintain distinct premium reimbursement tiers that sustain glass penetration despite higher unit economics.
- Rubber:Elastomer plunger seals and needle shields requiring ISO 10993 biocompatibility validation.
- Metal:Stainless-steel cannulae with silicone lubricant coatings.
Plastic holds the dominant cost-positioned share, while Glass maintains premium tier insulation through reimbursement differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Europe diverge sharply between Nordic systems favoring glass prefilled formats and Central European markets prioritizing cost-optimized plastic disposables for high-volume tenders.
Germany
Outpatient diabetes networks in Bavaria and North Rhine-Westphalia are expanding self-injection device reimbursement pathways that favor safety-engineered syringes. BfArM vigilance reporting requirements are compressing supplier qualification timelines for connected device pilots. The Rhine-Ruhr industrial corridor hosts sterilization infrastructure serving bulk supply contracts.
France
Regional health agencies in Île-de-France are driving environmental compliance scoring in multi-criteria tenders that weight take-back program integration. ANSM standardization of vigilance reporting is creating pathways for Bluetooth-enabled injection device pilots. The Lyon-Grenoble medical technology cluster concentrates precision molding capabilities for polypropylene barrel production.
United Kingdom
NHS procurement consortia are consolidating specifications around dead-space minimization metrics in England and Scotland. MHRA post-Brexit device oversight maintains alignment with EU MDR sterility mandates while streamlining UKCA marking pathways. The Cambridge-Oxford life sciences corridor attracts connected device development partnerships.
Italy
Lombardy and Emilia-Romagna hospital purchasing groups are fragmenting award criteria toward integrated distribution control over pharmacy supply channels. National pharmaceutical regulator AIFA is tightening biocompatibility documentation requirements for elastomer plunger seals. The Milan-Turin industrial zone sustains manual packaging operations for mid-volume specialty formats.
Poland
Central European procurement consortia in Warsaw and Kraków are consolidating tenders around integrated take-back programs and environmental compliance scoring. The national health fund is expanding reimbursement for self-injection devices in regional diabetes networks. Silesian manufacturing zones host contract sterilization services serving cross-border distribution.
Europe Insulin Syringe Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages rotating toward manufacturers with captive polymer processing and European sterilization infrastructure. The vendor base fragments across three strategic archetypes: diversified medical device conglomerates with full vertical control, precision needle specialists competing on unit consistency, and regional packaging contractors serving mid-volume tenders. Dominant competitive moves include backward integration into medical-grade polypropylene molding and strategic partnerships with diabetes platform developers for connected dose-tracking capabilities.
Among diversified medical technology conglomerates, Becton Dickinson and Terumo Corporation exemplify the integrated-leader archetype through European sterilization infrastructure and precision manufacturing capabilities. B. Braun Medical Inc. occupies a position within the distribution-control specialist tier, with its GmbH structure suggesting German operational roots. These three anchors represent contrasting pathways to competitive position: bulk supply chain scale, unit consistency technology, and channel integration depth.
| Leading Market Players |
|---|
| Becton Dickinson |
| Terumo Corporation |
| B. Braun Medical Inc. |
| Nipro Corporation |
| HMD Healthcare Ltd. |
| Cardinal Health |
| Smiths Medical |
| Medtronic plc |
| Gerresheimer AG |
| Others |
Supply & Pricing Matrix
Long-term sterilization service contracts lock in both polypropylene resin access and unit cost visibility for manufacturers serving German and French national health tenders. These arrangements tether pricing power to captive molding infrastructure while insulating against stainless-steel needle alloy volatility from Austrian and Swedish mills.
Pricing Analysis
Contract-based long-term offtake dominates procurement relationships between manufacturers and Central European hospital consortia, with volume scale and CE-MDR certification tier as the primary differentiation drivers. Three-tier pricing structure across premium glass prefilled, standard safety-engineered plastic, and economy conventional syringes segments buyer sensitivity, with Nordic systems least price-sensitive due to distinct reimbursement tiers. Cost compression in the standard plastic segment is intensifying because REACH lubricant reformulation cycles extend validation timelines and compress margin pools.
Supply Chain Analysis
Specialty stainless-steel sourcing from Austrian and Swedish mills concentrates needle manufacturing feedstock, exposing the value chain to alloy price volatility and single-source vulnerability. Polypropylene resin draws from German petrochemical complexes, while silicone lubricant formulations face ECHA scrutiny under REACH restrictions. Distribution runs through hospital supply consortia in the Czech Republic and Poland that consolidate demand across regional procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home care expansion across outpatient diabetes networks signals early-cycle penetration growth as self-injection reimbursement pathways mature beyond hospital walls.
For Market Incumbents: Compound sterilization infrastructure advantages by securing multi-year service contracts with German BfArM-qualified facilities before 2027 MDR certificate renewal waves compress supplier qualification timelines. Extend backward integration into medical-grade polypropylene molding to defend against emerging regional packaging contractors bidding on mid-volume tenders. For New Entrants and Emerging Players: ANSM-standardized vigilance reporting fast-tracks market access for Bluetooth-enabled connected syringes in French regional diabetes pilot programs. White-space concentrates in Central European hospital supply channels where integrated distribution control remains underpenetrated by safety-engineered specialists. Lead with subscription revenue models pairing dose-tracking software with disposable hardware. For Investors and Strategic Acquirers: The market sits at an early expansion phase that favors precision needle grinding specialists with Swiss or Japanese equipment access. Long-term viability hinges on manufacturers with validated ISO 10993 biocompatibility documentation for elastomer plunger seals. Watch EMA combination product rule enforcement as the inflection signal for prefilled syringe category consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance accelerates safety syringe standardization across member state procurement. |
| Backward Integration into Polypropylene Molding | In-house polymer processing compresses per-unit costs for high-volume German and French health tenders. |
| Hospital System Partnership | Direct contracting with Central European consortia secures multi-year sterilization service arrangements. |
| Software Companion Development | Bluetooth-enabled dose-tracking converges with mobile health platforms in French ANSM pilot networks. |
| Reimbursement Strategy | Germany's BfArM pathway maturation shifts procurement toward needlestick-prevention liability reduction. |
Research Methodology
A standing panel of hospital procurement managers, GPO contracts specialists, biomedical engineers, and diabetes educator network coordinators provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation from EMA device oversight filings, BfArM vigilance databases, ANSM regulatory notices, and hospital tender documentation. Bottom-up unit demand modeling triangulated against top-down health expenditure flows.
Consistency checks validated volume and value outputs against external benchmarks including national health fund reimbursement data and cross-border trade statistics. Segmentation dimensions spanned product type, end-user setting, distribution channel, and material composition across the projection horizon. CAGRs derived from logistic diffusion curves fitted to self-injection device adoption patterns, with inputs including outpatient diabetes network expansion rates and MDR compliance timeline assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EU MDR enforcement and stable REACH lubricant regulatory frameworks; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EMA combination product rule interpretation and Nordic glass prefilled reimbursement tier stability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Medical Gloves Market
Medical Supplies
Centrifuge Bottles Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
Ostomy Care and Accessories Market
Medical Supplies
Global Medical Protective Equipment Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Skin Tac Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Asia-Pacific N95 Mask Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
US N95 Mask Market