
 Ostomy Drainage Bags Market | 2026-2036
Ostomy Drainage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Ostomy Drainage Bags Market Intelligence
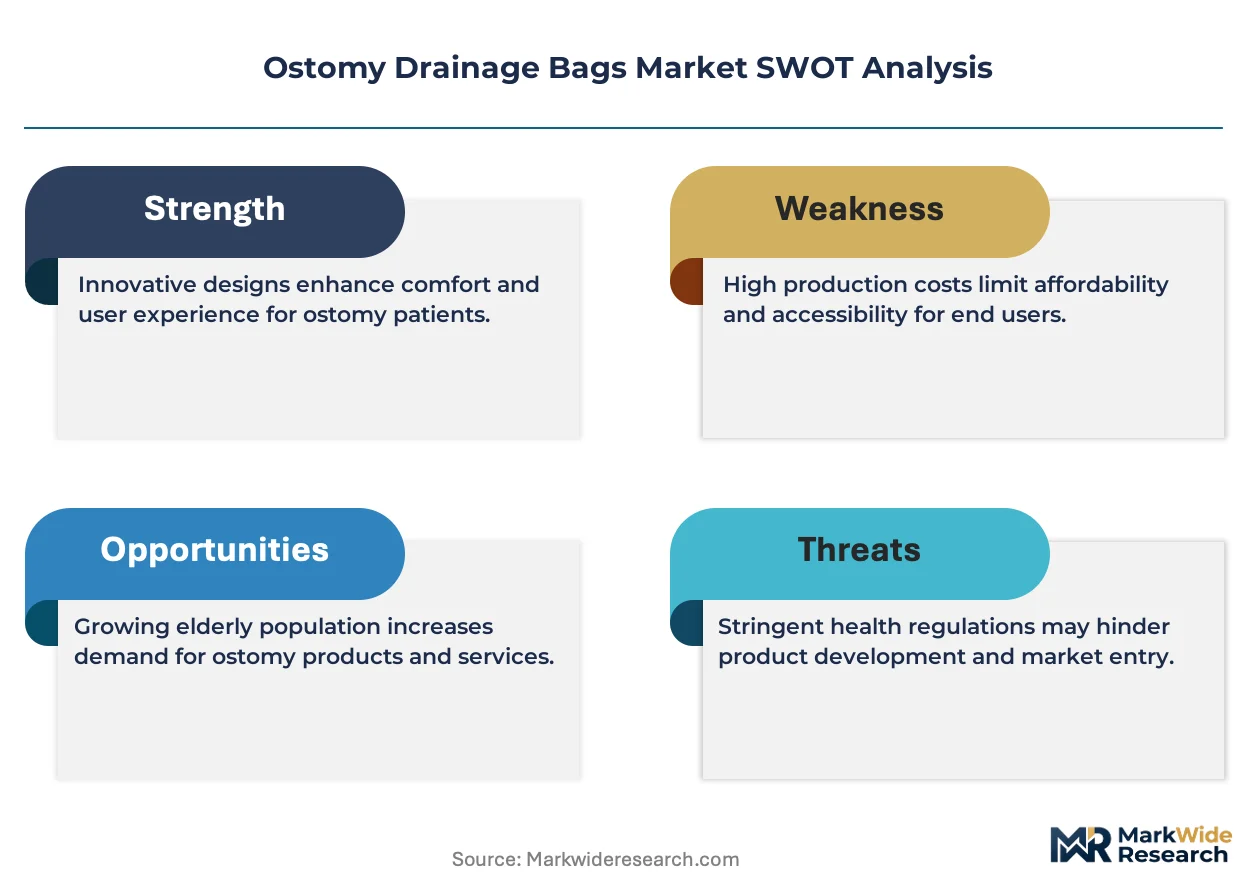
The distinction between basic, single-use systems and advanced, multi-day wear bags with integrated filters is collapsing as patient expectations for comfort and discretion rise. Coloplast leverages its strong brand and direct-to-consumer channels to promote these premium products. ConvaTec differentiates through its focus on advanced hydrocolloid adhesive technologies. Hollister sustains a significant market presence through its extensive educational resources for both patients and healthcare professionals, building long-term user loyalty.
Ostomy drainage bags are medical devices designed to securely collect bodily waste from a surgically created stoma. These systems typically consist of a multi-layer, odor-proof plastic pouch and a skin barrier wafer made from hydrocolloid adhesives that protect peristomal skin. Two-piece systems offer greater flexibility and are gaining share over traditional one-piece bags, especially for long-term users. The home care end-user segment is expanding rapidly, driven by a global shift away from prolonged hospital stays toward patient self-management.
Regulatory frameworks, such as the U.S. FDA's 510(k) clearance pathway and Europe's Medical Device Regulation (MDR), mandate stringent requirements for material safety and device performance. These regulations directly influence product design, manufacturing processes, and market access for ostomy bag producers. Future competitive advantage will hinge on developing products that demonstrably improve patient quality of life through enhanced discretion, comfort, and ease of use.
Market Dynamics
The market's evolution is fundamentally shaped by the global healthcare trend of shifting patient care from hospitals to home settings. This transition elevates patient expectations for discretion and comfort, forcing manufacturers to innovate beyond basic waste collection toward user-centric designs.
Growth Catalysts
- Aging Demographics:An increasing prevalence of colorectal cancer and inflammatory bowel disease in aging populations, particularly in Germany and Japan, is leading to a higher volume of ostomy-creating surgical procedures.
- Material Science Advances:Innovations in hydrocolloid formulations are extending wear times and improving skin health. This technological improvement directly addresses patient comfort and reduces the frequency of pouch changes, encouraging adoption.
- Home Care Expansion:A systemic shift towards patient self-management outside of institutional settings creates sustained demand for ostomy products that are intuitive, reliable, and easy for non-clinicians to use.
Market Restraints
- Reimbursement Variability:Inconsistent and often restrictive reimbursement policies for ostomy supplies across national health systems can limit patient access to more advanced, higher-cost products, favoring basic systems.
- Stringent Regulatory Pathways:The U.S. FDA's 510(k) and Europe's MDR processes impose significant costs and timelines for product approval, slowing the market entry of innovative designs and materials.
- Patient Education Gaps:Insufficient training and support for new ostomy patients can lead to improper device use, skin complications, and product dissatisfaction, potentially hindering long-term adherence and market growth.
Strategic Opportunities
- Emerging Market Penetration:Expanding healthcare access and rising disposable incomes in countries like Brazil and Mexico present significant growth opportunities for ostomy bag manufacturers to establish a market presence.
- Smart Technology Integration:The convergence of ostomy bags with sensor technology offers a pathway to develop next-generation products that can monitor for leaks, track output, and alert users via connected apps.
- Subscription-Based Models:Developing direct-to-consumer subscription services for ostomy supplies can create recurring revenue streams, improve customer loyalty, and bypass traditional distribution complexities.
Industry Challenges
- Specialized Polymer Sourcing:The supply chain for advanced hydrocolloids and multi-layer odor-barrier films is concentrated, creating dependencies and vulnerability to price fluctuations or material shortages for manufacturers.
- End-of-Life Product Management:Growing environmental concerns regarding the disposal of single-use plastic medical devices present a challenge, requiring investment in research for more sustainable materials and disposal solutions.
- Clinical Data Generation:Demonstrating the clinical and quality-of-life benefits of premium products to justify higher costs to payers requires significant investment in post-market clinical follow-up studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ostomy Drainage Bags Market |
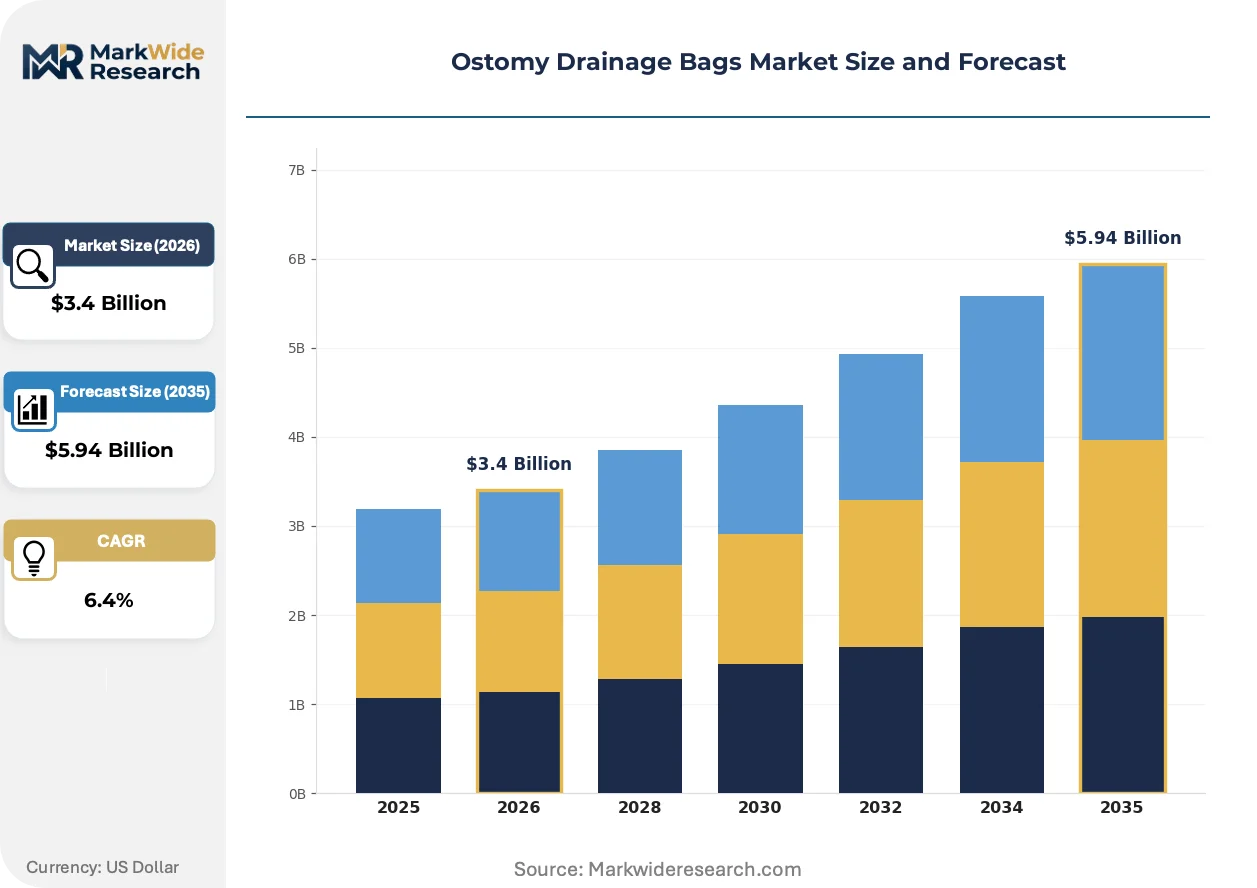
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.94 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: One-Piece, Two-Piece, Drainable, Closed-End Material: Plastic, Silicone, Rubber, Hydrocolloid Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Stores, Medical Supply Stores End User: Hospitals, Home Care, Clinics, Long-Term Care Facilities |
| Companies Covered | Coloplast, ConvaTec, Hollister, B. Braun, Salts Healthcare, Welland Medical, ALCARE, Dansac, Torbot Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ostomy Drainage Bags Market Strategic Shifts & Innovations
Product development is increasingly driven by the convergence of medical device engineering with consumer expectations for discretion, comfort, and digital integration. This forces a re-evaluation of the ostomy bag not just as a medical necessity, but as a wearable technology impacting daily life.
Advanced hydrocolloid formulations with infused materials like ceramide are becoming standard in premium product lines. These materials are actively adopted by long-term users who prioritize peristomal skin health and extended wear time. The introduction of these therapeutic skin barriers is fragmenting the market, creating a distinct premium tier differentiated by clinical skin-care benefits rather than just basic adhesion.
Europe's Medical Device Regulation (MDR) imposes more rigorous requirements for clinical evidence and post-market surveillance. This regulation forces manufacturers to generate more robust data on product safety and performance throughout the device lifecycle. The ostomy bag segment is most affected through the need for enhanced material traceability and documented evidence of biocompatibility, impacting product development timelines.
A notable behavioral change is the rise of peer-to-peer product evaluation through online patient communities and social media. This user-generated feedback loop is disrupting the traditional reliance on a clinician or stoma nurse for product selection, empowering direct-to-consumer channels. The trend is most prominent in North America and Western Europe, where patients actively seek out specific brands and features discussed in online forums.
Ostomy Drainage Bags Market Segmentation
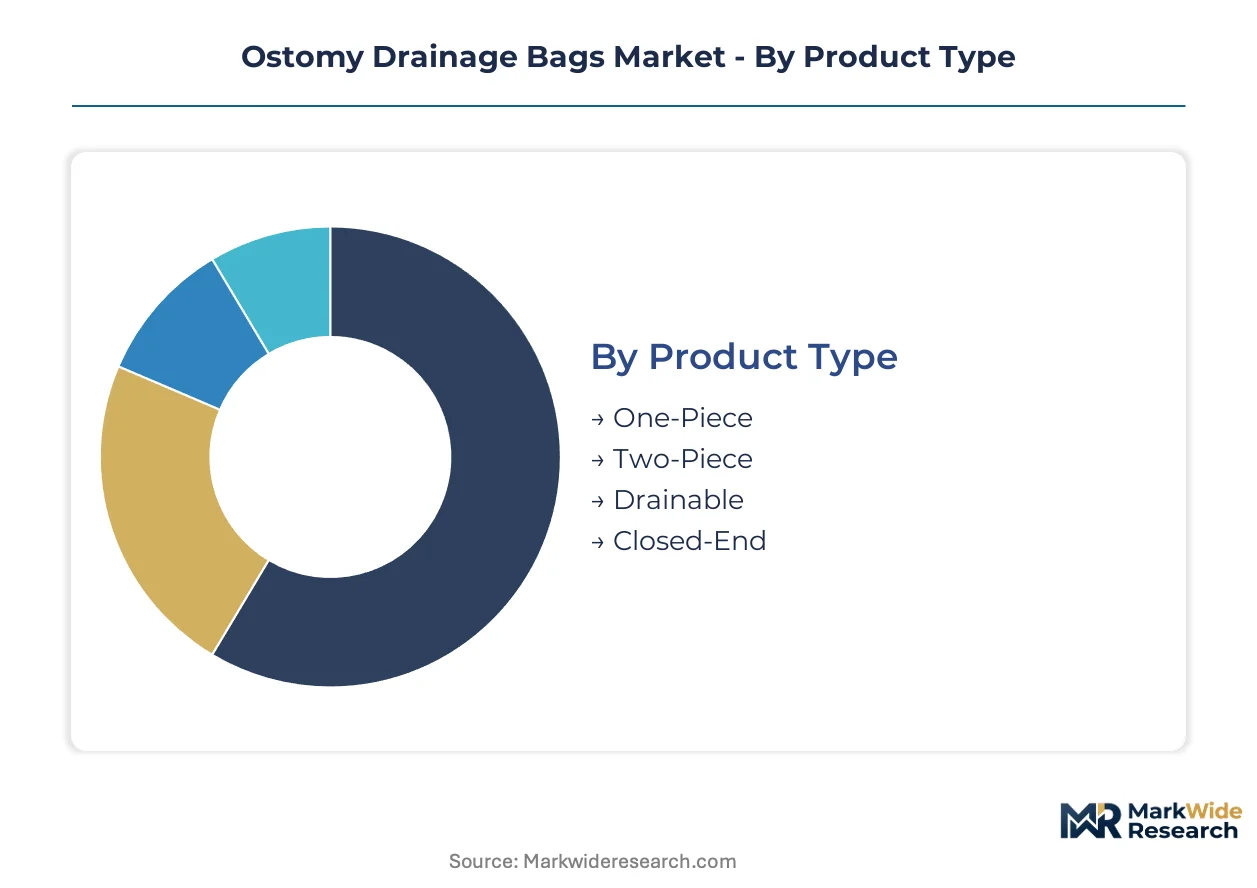
Market segmentation for ostomy drainage bags reveals critical distinctions in product design and end-user needs. Understanding these categories allows manufacturers to tailor innovations for specific patient populations. This analysis highlights how material science and distribution channels influence product development strategies, ensuring products meet diverse clinical and lifestyle demands.
Product Type:
Margin pools within product types are increasingly concentrated in advanced two-piece systems and specialized drainable bags.
- Two-Piece:Two-piece systems comprise a separate skin barrier and pouch, allowing for pouch changes without removing the entire adhesive wafer. Demand for these systems is concentrating among long-term ostomy patients in developed nations like Germany and Japan, driven by enhanced comfort and reduced peristomal skin irritation.
- Drainable:Drainable pouches feature an opening at the bottom, secured by a clamp or integrated closure, enabling repeated emptying without full removal. This design finds significant demand in home care settings, particularly for ileostomy patients, where frequent emptying and discreet management are crucial for daily living.
- One-Piece:One-piece systems integrate the pouch and skin barrier into a single unit, offering simplicity for new users and short-term applications.
- Closed-End:Closed-end pouches are designed for single use and disposal, primarily favored by colostomy patients with predictable, solid stool output.
One-piece systems hold installed capacity. Two-piece systems are rotating up the share rankings.
Material:
Material selection directly impacts product performance and patient outcomes across various applications.
- Hydrocolloid:Hydrocolloid materials form the adhesive skin barrier, comprising absorbent particles suspended in a polymer matrix, crucial for peristomal skin protection. Their application is concentrating in premium ostomy bags within Western European markets due to superior skin-friendliness and extended wear times, addressing patient comfort expectations.
- Plastic:Multi-layer plastic films, typically EVA or polyethylene, form the pouch body, providing odor-proof and leak-resistant containment for bodily waste. This material dominates basic and mid-range product lines globally, driven by cost-effectiveness and established manufacturing processes, especially in high-volume production.
- Silicone:Silicone components are sometimes integrated into skin barriers for enhanced flexibility and gentle adhesion, particularly for sensitive skin types.
- Rubber:Rubber materials, historically used for some seals and components, are largely being phased out due to superior performance and biocompatibility of newer synthetics.
Hydrocolloid material integration represents the fastest-growing trajectory, reflecting a shift towards advanced skin protection.
Distribution Channel:
Distribution channels reflect diverse patient purchasing preferences and healthcare system structures.
- Online Stores:Online stores include manufacturer direct-to-consumer platforms and third-party e-commerce sites, offering convenience and discreet purchasing. This channel is experiencing rapid expansion in North America and Western Europe, driven by patient self-management and subscription-based models, enhancing accessibility.
- Medical Supply Stores:Medical supply stores specialize in durable medical equipment and consumables, providing a focused retail environment for ostomy products. They remain a primary channel for patients seeking in-person product consultation and immediate access to specialized supplies, particularly in regions with established healthcare infrastructure.
- Hospital Pharmacies:Hospital pharmacies primarily serve immediate post-operative needs, ensuring patients receive initial supplies before discharge.
- Retail Pharmacies:Retail pharmacies offer accessible points for routine replenishment of basic ostomy supplies, often integrated with broader health services.
The shift towards home care is propelling online stores, while medical supply stores maintain a stable market presence.
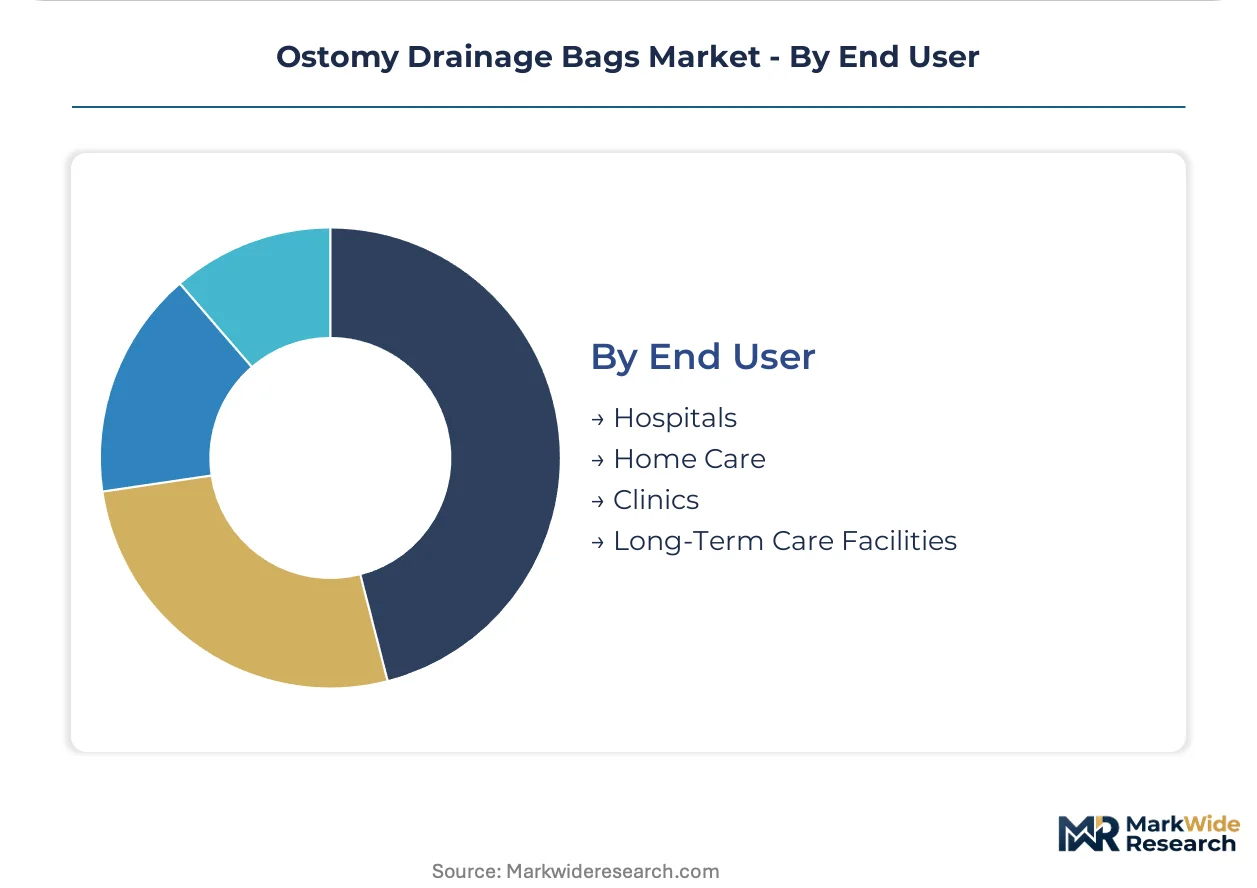
End User:
End-user segments dictate product volume requirements and specific design priorities.
- Home Care:Home care encompasses patients managing their ostomy independently or with family support outside institutional settings. This segment is expanding most quickly globally, driven by a systemic shift from prolonged hospital stays and increased patient self-management, demanding user-friendly designs.
- Hospitals:Hospitals serve acute post-surgical patients, providing initial ostomy care and product education during recovery. Demand in this segment focuses on basic, reliable, and cost-effective systems for initial patient stabilization and training, particularly in high-volume surgical centers.
- Clinics:Clinics, including specialized stoma care clinics, provide ongoing patient education, product fitting, and complication management.
- Long-Term Care Facilities:Long-term care facilities cater to elderly or chronically ill patients requiring assistance with ostomy management over extended periods.
Home care is gaining share fastest, while hospitals remain foundational for initial product provision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global ostomy drainage bags market shows a nuanced regional distribution, with manufacturing capabilities and advanced material science often concentrated in specific developed economies. This concentration dictates product availability and innovation trajectories across diverse patient populations. Demand patterns are significantly shaped by healthcare infrastructure and demographic shifts.
Germany
Germany exhibits strong demand for advanced ostomy drainage bags, driven by its aging population and high prevalence of colorectal cancer. The European Medical Device Regulation (MDR) mandates stringent quality and safety standards for all products sold. Medical technology hubs like Tuttlingen continue to innovate in material science for improved patient comfort.
Japan
Japan's demand for ostomy products is significant due to its rapidly aging demographics and sophisticated healthcare system. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees strict regulatory approval processes for medical devices. The Tokyo and Osaka regions are key centers for medical device innovation and distribution.
United States
The United States market is characterized by a rapid expansion of home care settings and a strong emphasis on patient self-management. The U.S. FDA's 510(k) clearance pathway governs market entry for ostomy devices, ensuring product safety and efficacy. Major medical device industry clusters in Massachusetts and California drive product development.
Brazil
Brazil presents a significant growth opportunity, fueled by expanding healthcare access and rising disposable incomes across its population. ANVISA, the national health surveillance agency, regulates medical devices to ensure public health standards. The metropolitan areas of São Paulo and Rio de Janeiro serve as primary distribution hubs for medical supplies.
United Kingdom
The United Kingdom market is undergoing a systemic shift towards home care, elevating patient expectations for discretion and comfort in ostomy products. The Medicines and Healthcare products Regulatory Agency (MHRA) sets standards for medical device performance and post-market surveillance. Medical technology clusters around Cambridge and Oxford contribute to product innovation.
Ostomy Drainage Bags Market Key Industry Players
Concentration sits with established medical device manufacturers offering comprehensive portfolios in ostomy care. The market exhibits a tiered structure, ranging from global leaders to specialized regional players. These manufacturers differentiate through material science innovation and direct-to-consumer channels. Strategic moves often involve vertical integration to control specialized polymer sourcing and geographic expansion into emerging markets.
Within the advanced medical device segment, Coloplast, ConvaTec, and Hollister exemplify companies leveraging deep industry experience. These entities anchor positions through extensive product development, focusing on patient comfort and discretion. Coloplast, for instance, utilizes its brand strength, while ConvaTec differentiates with hydrocolloid adhesive technologies. Hollister sustains its market presence by building long-term user loyalty through educational resources. These major players represent the strategic archetypes dominating the global ostomy drainage bags market.
| Leading Market Players |
|---|
| Coloplast |
| ConvaTec |
| Hollister |
| B. Braun |
| Salts Healthcare |
| Welland Medical |
| ALCARE |
| Dansac |
| Torbot Group |
| Others |
Cost & Logistics Intelligence
Hydrocolloid material substitution for traditional adhesives simultaneously reshapes the supply geography for advanced components and elevates product pricing economics for premium ostomy bags. This dynamic influences both manufacturing location and market access for specialized products.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure across the ostomy drainage bags market, emphasizing documented performance. Pricing stratifies across premium, standard, and economy tiers, driven by material science innovation and the depth of clinical evidence. Brand premium and after-sales service bundles also differentiate prices significantly. Pricing pressure stems from inconsistent reimbursement policies in national health systems. Home care patients often exhibit higher price sensitivity for basic supplies, while long-term users prioritize premium skin-friendly options.
Supply Chain Analysis
Port congestion and container availability for specialized chemical shipments impact the inbound logistics costs for ostomy bag manufacturers globally. Geographic supply concentration for advanced materials centers on developed economies like Germany and Japan for specialized hydrocolloids. The industry relies heavily on multi-layer plastic films and advanced hydrocolloid polymers as critical inputs. Single-source vulnerability for these specialized materials poses a structural risk. Downstream distribution runs predominantly through online stores and medical supply stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ostomy drainage bags market presents a strong defensive-moat story, primarily due to high patient switching costs associated with comfort, fit, and peristomal skin health. This creates a durable competitive advantage for established players.
For Market Incumbents:Fortify R&D investment in next-generation hydrocolloid materials to enhance wear time and skin health, counteracting pressure from emerging low-cost alternatives. Deepen direct-to-consumer channel control, leveraging subscription models to build recurring revenue streams and customer loyalty. Focus on generating robust clinical data to justify premium pricing and navigate stringent regulatory shifts like Europe's MDR. Expand educational resources for patients and healthcare professionals to reinforce brand trust.
For New Entrants and Emerging Players:Anchor in niche segments by developing smart technology integrated products that offer unique monitoring capabilities, targeting tech-savvy patient populations. The home care segment in emerging markets like Brazil and Mexico represents a penetrable white space for user-friendly, cost-effective solutions. A go-to-market angle focusing on digital health platforms and direct patient engagement can bypass traditional distribution barriers. Partner with local healthcare providers to establish initial market presence.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with mid-sized, specialized medical device manufacturers possessing proprietary material science expertise or strong regional distribution networks. The market exhibits long-term viability, driven by aging global demographics and a systemic shift towards home care. Acquire companies with robust regulatory compliance records and strong intellectual property in hydrocolloid formulations. A signal to watch is the increasing integration of sensor technology into ostomy appliances, indicating future growth vectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Hydrocolloid R&D | Improves patient comfort and extends wear time, differentiating premium product lines. |
| Expand Direct-to-Consumer Channels | Enhances patient accessibility and fosters brand loyalty through subscription services. |
| Integrate Smart Sensor Technology | Offers next-generation product capabilities like leak detection and output monitoring for users. |
| Target Emerging Market Penetration | Captures growth from expanding healthcare access and rising incomes in regions like Brazil. |
| Strengthen Regulatory Compliance Teams | Ensures smooth market access and product longevity under stringent frameworks like Europe's MDR. |
Research Approach
A spread of perspectives from clinicians, hospital purchasing committees, R&D directors, and long-term ostomy patients converged on the working assumptions for this analysis. This involved combining primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included U.S. FDA filings, Europe's MDR reports, medical device trade data, and company annual reports. The analysis utilized both bottom-up and top-down triangulation to ensure data accuracy.
Product type, material, distribution channel, end user, and regional regulatory frameworks defined the segmentation dimensions modeled. The analytical framework assessed market dynamics across the analysis window, with compound annual growth rates derived from historical trends and projected demographic shifts. Key industry-specific forecast inputs included surgical procedure rates for ostomy creation and the growth of aging populations in developed nations.
Decision-makers should treat outputs as directional under current macroeconomic stability and regulatory continuity; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological advancements and healthcare policy consistency. Supply chain disruptions or significant shifts in reimbursement policies represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global IV Tubing Sets and Accessories Market
Medical Supplies
Flexible Packaging for Healthcare Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Compression Socks Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Antibacterial Haemostatic Gels Market
Medical Supplies
Europe Ostomy Drainage Bags Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Mortuary Bags Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Tongue Depressors Market
Medical Supplies
Forensic Swabs Market