
 Intraosseous Infusion Kits Market | 2026-2036
Intraosseous Infusion Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Intraosseous Infusion Kits Market Foresight
North American manufacturing capacity for intraosseous devices is reshaping competitive dynamics as domestic producers respond to defense and civilian health system procurement preferences. Teleflex Incorporated leverages its critical care portfolio breadth to sustain hospital system relationships across integrated delivery networks. Becton, Dickinson and Company anchors its position through vascular access technology leadership and global distribution infrastructure. Smiths Medical differentiates through specialized emergency medicine product lines designed for pre-hospital and battlefield environments.
Intraosseous infusion kits comprise needle sets, access devices, infusion pumps, and supporting accessories engineered to deliver fluids and medications directly into the medullary cavity of long bones when peripheral venous access fails. These systems typically incorporate 15-gauge to 18-gauge needles with trocar-style tips capable of penetrating cortical bone within seconds, designed for sternal, proximal humerus, or proximal tibia insertion sites depending on patient age and clinical indication. Needle kits and access devices command the largest current revenue share due to disposable consumption patterns and protocol-driven replacement cycles. Military units and ambulance services represent the fastest-growing end-user category as tactical combat casualty care guidelines and civilian paramedic scope-of-practice expansions broaden deployment authorization.
The FDA's Class II special controls framework and the EU Medical Device Regulation's risk-classification requirements shape design validation, clinical evidence standards, and market access timelines for intraosseous device manufacturers. Health Canada's device licensing requirements and the TGA's conformity assessment procedures create additional compliance layers for companies targeting multi-jurisdictional procurement contracts. Stakeholders must monitor evolving battlefield medicine doctrine and civilian trauma system funding allocations to anticipate volume shifts between military and commercial channels.
Market Dynamics
Battlefield medicine doctrine revision and civilian trauma network consolidation are compressing purchasing cycles while elevating device performance specifications across military and hospital procurement channels.
Growth Catalysts
- Tactical Combat Casualty Care (TCCC) protocol expansion:Military medical services across NATO member states mandate intraosseous access as first-line vascular alternative for hemorrhagic shock, driving standardization of training curricula and equipment inventories.
- Paramedic scope-of-practice legislation:US state-level EMS regulatory boards authorize advanced airway and vascular access procedures for pre-hospital providers, extending device deployment into ambulance and aeromedical services.
- Long bone vascular access training:Emergency medicine residency programs incorporate procedural competency requirements for sternal and humeral insertion techniques, embedding consumption patterns into hospital credentialing systems.
Market Restraints
- Surgical-grade stainless steel price volatility:Needle cannula manufacturing depends on specialty alloy supply chains concentrated in German and Japanese metallurgical facilities, exposing producers to raw material cost swings.
- FDA Class II special controls compliance burden:Premarket notification pathways require clinical performance testing and human factors validation, extending development timelines and capital requirements for novel device entrants.
- Peripheral intravenous catheter substitution:Ultrasound-guided venous access technology improvements in emergency departments reduce intraosseous device utilization rates for non-critical patients.
Strategic Opportunities
- Rural hospital network penetration:Critical access facilities in the US Mountain West and Great Plains regions lack interventional radiology support, creating demand for rapid vascular access alternatives in sepsis and trauma protocols.
- Pediatric emergency medicine specialization:Distinct needle sizing and insertion site protocols for infants and children enable product line extensions with premium positioning in children's hospital procurement.
- EU Medical Device Regulation (MDR) harmonization:Conformity assessment procedure standardization across EU member states reduces multi-national registration friction for manufacturers achieving notified body certification.
Industry Challenges
- Procedural skill retention:Emergency physicians and paramedics infrequently perform intraosseous insertions outside military or major trauma center settings, requiring simulation-based recertification programs to maintain competency.
- Legacy electronic health record integration:Device utilization documentation and adverse event tracking require custom interface development with hospital information systems, complicating enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intraosseous Infusion Kits Market |
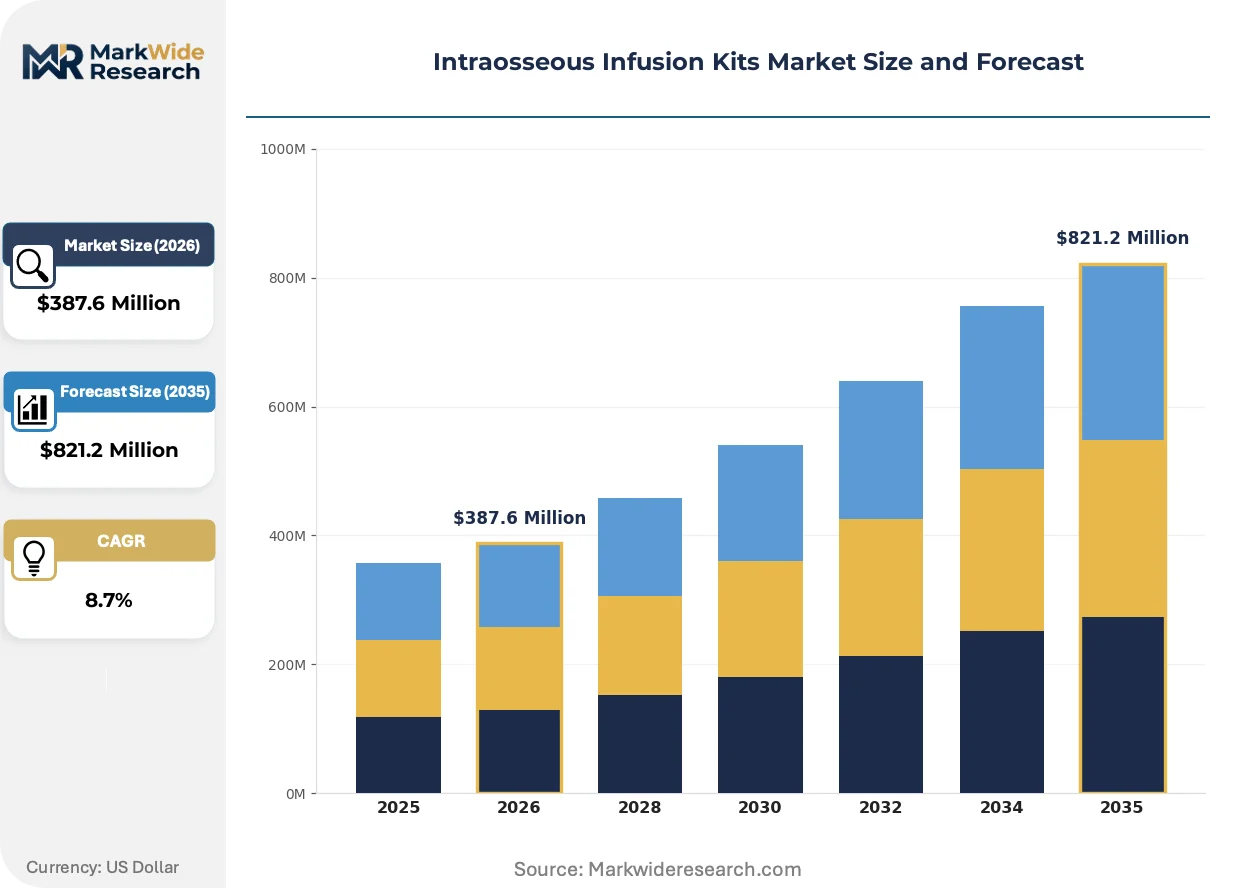
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Needle Kits, Access Devices, Infusion Pumps, Accessories Application: Emergency Medicine, Trauma Care, Pediatric Care, Anesthesia End User: Hospitals, Clinics, Ambulance Services, Military Units Distribution Channel: Direct Sales, Medical Distributors, Online Retailers, Other Channels |
| Companies Covered | Teleflex Incorporated, Becton, Dickinson and Company, Cook Medical, PAVmed Inc., Aero Healthcare, BPB Medica - Biopsybell, Smiths Medical, Ambu A/S, Argon Medical Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intraosseous Infusion Kits Market Shifts & Advancements
Device miniaturization and sensor integration are converging to produce next-generation systems capable of real-time insertion confirmation and infusion pressure monitoring.
Spring-loaded mechanical insertion devices is hybridizing with battery-powered drill-assisted systems, creating hybrid platforms that combine tactile feedback with powered penetration. Emergency departments in Level I trauma centers adopt these dual-mode instruments for rapid sequence induction scenarios. The technology is hybridizing capital equipment and disposable revenue models, compressing traditional price-per-procedure structures into bundled system contracts.
EU MDR Article 10 post-market surveillance requirements mandate systematic collection and analysis of device performance data across the product lifecycle. Manufacturers must establish quality management systems with notified body oversight for clinical follow-up studies. Class IIa intraosseous devices face heightened scrutiny of biological safety and mechanical testing documentation, accelerating consolidation among firms with established regulatory affairs capabilities.
Hospital system value analysis committees now dominate capital equipment purchasing decisions, displacing individual physician preference contracting. Integrated delivery networks in the US Southeast and Midwest consolidate vendor negotiations across multiple facilities, extracting volume-based pricing concessions. This concentration is most visible in multi-state Catholic health systems where standardization protocols override individual hospital autonomy in emergency medicine supply selection.
Intraosseous Infusion Kits Market Segmentation
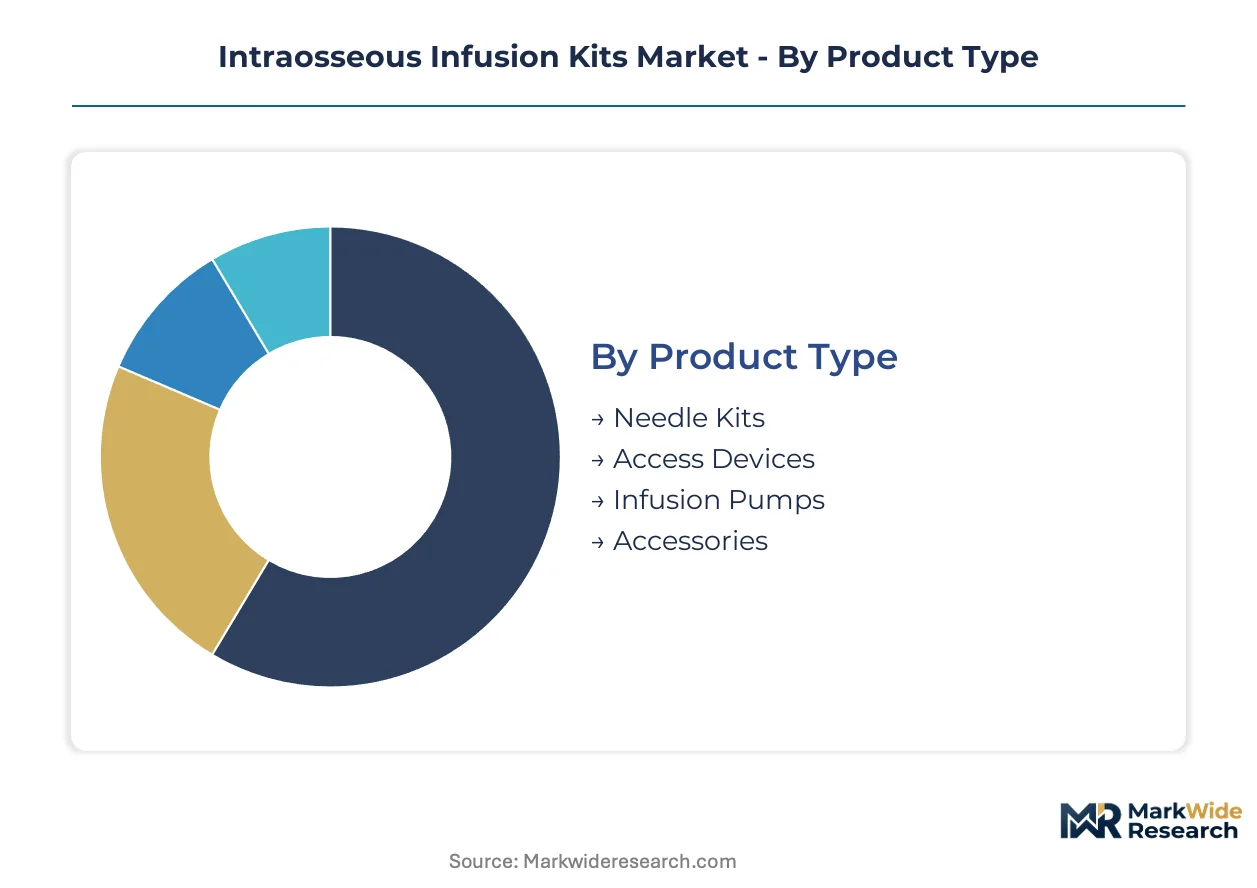
Intraosseous infusion kit manufacturers align product portfolios across four distinct segmentation axes. Each dimension shapes pricing architecture, regulatory pathways, and customer engagement models differently.
Product Type:
Cost tier stratification separates disposable consumables from capital equipment with recurring attachment sales.
- Needle Kits:15-gauge to 18-gauge trocar-tipped cannulas with depth-stop collars for sternal, humeral, or tibial insertion. Civilian emergency departments in the United States consume the highest volumes under protocol-driven replacement cycles for sterility compliance.
- Access Devices:Mechanical and battery-powered insertion drivers with tactile feedback systems. Military procurement contracts across NATO member states specify ruggedized variants for field deployability under environmental stress conditions.
- Infusion Pumps:Pressure-controlled delivery systems for high-resistance medullary infusion.
- Accessories:Stabilization dressings, extension tubing, and sharps containment components.
Needle kits command the established base. The steepest expansion runs through access devices.
Application:
Clinical indication determines device specification requirements and training intensity for credentialing.
- Emergency Medicine:Rapid vascular access during cardiac arrest and shock states. Level I trauma centers in Texas and California embed intraosseous protocols into advanced life support algorithms, driving standardized training investments.
- Trauma Care:Hemorrhagic shock management when peripheral veins collapse. Tactical Combat Casualty Care guidelines across US military branches mandate intraosseous access as first-line alternative, institutionalizing battlefield consumption patterns.
- Pediatric Care:Specialized needle sizing and insertion depth protocols for infants and children.
- Anesthesia:Backup vascular access during difficult airway procedures.
Emergency medicine commands the established base. Trauma care climbs the fastest as military doctrine revisions cascade into civilian protocol adoption.
End User:
Customer type differentiation separates institutional buyers with value analysis committees from mission-driven military procurement.
- Hospitals:Integrated delivery networks with enterprise-wide standardization mandates. Multi-state Catholic health systems in the US Southeast consolidate vendor negotiations, extracting volume-based pricing concessions across emergency departments.
- Military Units:Defense medical services with doctrine-specified equipment inventories. US Army and Marine Corps combat medic training programs drive standardization across allied NATO forces through equipment interoperability requirements.
- Ambulance Services:Pre-hospital providers with expanding scope-of-practice authorizations.
- Clinics:Urgent care facilities with limited interventional radiology backup.
Hospitals command the established base. Military units gain share fastest as tactical medicine doctrine expands across allied defense forces.
Distribution Channel:
Supply chain configuration determines margin capture and customer relationship depth across procurement modalities.
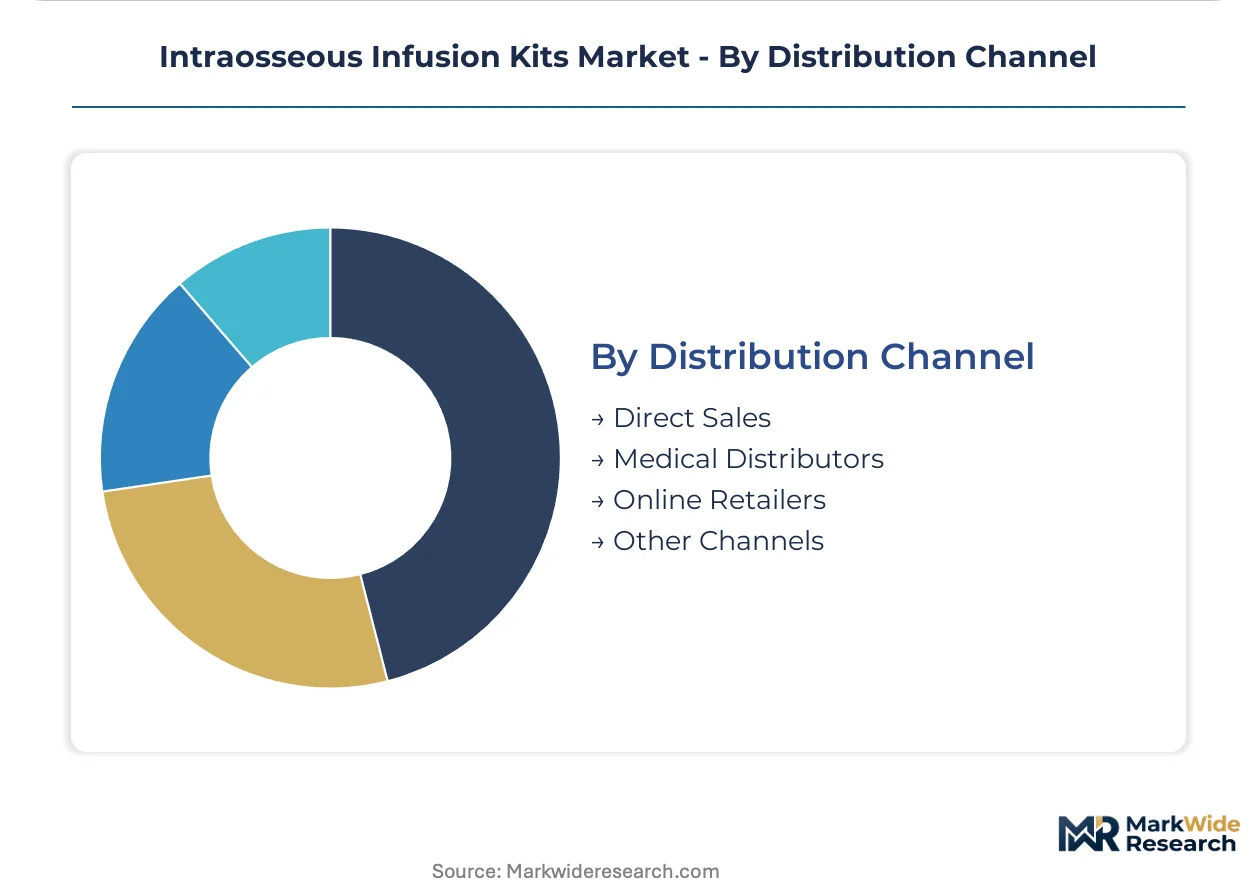
- Direct Sales:Manufacturer field representatives negotiating with hospital value analysis committees. Teleflex Incorporated and Becton, Dickinson and Company deploy dedicated critical care specialists to sustain integrated delivery network relationships.
- Medical Distributors:Broadline and specialty distributors with local inventory positioning. Cardinal Health and McKesson Corporation maintain emergency medicine product availability for same-day fulfillment in metropolitan hospital clusters.
- Online Retailers:E-commerce platforms serving smaller clinics and international buyers.
- Other Channels:Group purchasing organizations and defense procurement intermediaries.
Direct sales commands the established base. Medical distributors expand most quickly as rural hospital networks seek localized inventory support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Class II special controls establish the regulatory baseline that shapes product development trajectories across allied health systems. Trauma care protocols in civilian hospitals and military procurement standards concentrate demand in specific national markets.
United States
Level I trauma centers in Texas and California embed intraosseous protocols into advanced life support algorithms. State-level EMS regulatory boards authorize advanced vascular access for paramedics, extending deployment into ambulance services. The US Army and Marine Corps combat medic training programs drive standardization across NATO forces.
Germany
Specialty alloy supply chains for needle cannula manufacturing concentrate in German metallurgical facilities. The EU Medical Device Regulation's risk-classification requirements shape design validation timelines for manufacturers targeting European procurement. Bavarian medical device clusters support notified body certification infrastructure.
United Kingdom
Integrated delivery networks in the National Health Service consolidate vendor negotiations across emergency departments. Military medical services align with NATO TCCC protocol expansion for hemorrhagic shock management. London trauma centers serve as reference sites for civilian protocol adoption.
Canada
Health Canada's device licensing requirements create compliance layers for multi-jurisdictional procurement contracts. Critical access facilities in rural provinces lack interventional radiology support, driving demand for rapid vascular access alternatives. Ontario and Quebec hospital networks anchor domestic consumption.
Australia
The TGA's conformity assessment procedures govern market access for intraosseous device manufacturers. Pre-hospital provider scope-of-practice expansions extend deployment into aeromedical and ambulance services. Major trauma centers in New South Wales and Victoria standardize training curricula.
Intraosseous Infusion Kits Market Competitive Landscape
Critical care portfolio breadth and vascular access technology leadership split the market between diversified medical device conglomerates and emergency medicine specialists. The vendor base concentrates around manufacturers with established regulatory affairs capabilities and global distribution infrastructure. Two archetypes dominate: integrated critical care platforms and specialized emergency medicine product lines. Competitive moves center on hospital system relationship sustainment through dedicated field representatives and volume-based pricing concessions across integrated delivery networks.
Within the diversified medical technology tier, Teleflex Incorporated and Becton, Dickinson and Company exemplify archetypes built on critical care portfolio breadth and vascular access infrastructure respectively. Smiths Medical occupies a position representing specialized emergency medicine orientation designed for pre-hospital and battlefield environments.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Becton, Dickinson and Company |
| Cook Medical |
| PAVmed Inc. |
| Aero Healthcare |
| BPB Medica - Biopsybell |
| Smiths Medical |
| Ambu A/S |
| Argon Medical Devices |
| Others |
Supply & Pricing Matrix
Trans-Pacific freight corridors from German metallurgical clusters to North American device manufacturers impose cost dynamics that concentrate supply-side power among alloy suppliers while forcing downstream price differentiation between military-grade and civilian emergency medicine procurement tiers.
Pricing Analysis
Price spreads between US hospital systems and European defense procurement channels exceed 40 percent due to FDA Class II special controls compliance costs and NATO equipment interoperability mandates. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with integrated delivery networks extracting steepest discounts. Cost compression in standard-tier needle kits is intensifying because ultrasound-guided peripheral access technology reduces non-critical utilization. Ambulance services and rural critical access hospitals demonstrate highest price sensitivity; military medical services show lowest sensitivity due to doctrine-mandated standardization.
Supply Chain Analysis
US Commerce Department export controls on specialty steel production technology limit German and Japanese metallurgical equipment flows to emerging manufacturers, preserving incumbent supply dominance. Needle cannula manufacturing draws from German, Japanese, and South Korean alloy supply chains, with trocar-tip grinding equipment concentrated in Swiss and German precision machining clusters. Single-source vulnerability runs through Japanese specialty stainless steel producers exposed to seismic disruption. Distribution runs through Cardinal Health and McKesson broadline networks for civilian hospitals; defense procurement flows through dedicated military medical logistics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-era training disruption as emergency medicine residency programs restore procedural competency requirements and military combat medic pipelines expand.
For Market Incumbents: Harden regulatory affairs capabilities against EU MDR Article 10 post-market surveillance requirements through notified body relationship investment. Deepen backward integration into surgical-grade stainless steel sourcing via long-term offtake agreements with German metallurgical facilities to offset raw material volatility. Acquire simulation-based training platform providers to lock in credentialing system relationships. For New Entrants and Emerging Players: Rural critical access hospital networks in the US Mountain West present the most penetrable white space, lacking interventional radiology support and dependent on rapid vascular access alternatives. Pediatric emergency medicine specialization offers premium positioning with distinct needle sizing protocols and lower competitive density. Pursue group purchasing organization bypass strategies through direct field representative deployment to extract volume commitments from multi-facility Catholic health systems. For Investors and Strategic Acquirers: FDA's evolving Class II special controls guidance reshapes the acquisition landscape toward targets with established 510(k) clearance pathways and human factors validation documentation. Long-term viability centers on regulatory affairs scalability rather than manufacturing scale alone. Watch for EU MDR notified body certification delays as an inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Class II special controls clearance unlocks hospital system procurement eligibility across integrated delivery networks. |
| EU MDR Notified Body Certification | CE marking pathway enables defense and civilian procurement across NATO member state medical services. |
| Hospital System Partnership | Value analysis committee relationships secure enterprise-wide standardization mandates across multi-state Catholic health networks. |
| Simulation Training Platform Development | Procedural competency software embeds device consumption patterns into emergency medicine residency credentialing systems. |
| Reimbursement Strategy | CPT code alignment with trauma care protocols drives ambulance service and aeromedical deployment authorization expansion. |
Research Methodology
Initial hypotheses were tested against primary input from emergency medicine physicians, hospital purchasing committee directors, military medical logistics officers, and biomedical engineering specialists and refined through secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body certification records, GPO contract disclosure filings, and trauma center protocol documentation. Bottom-up demand modeling triangulated against top-down market sizing across needle kit, access device, and infusion pump product categories.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across product type, clinical application, end-user category, and distribution channel dimensions. CAGRs derived from procedure volume elasticity to trauma protocol adoption rates and military procurement cycle timing. Forecast inputs incorporated TCCC guideline revision schedules and state-level EMS scope-of-practice legislative tracking.
Macroeconomic conditions sit as an overlay; deviation in stainless steel alloy pricing and defense budget appropriation trajectories would shift the trajectory. Forecasts reflect underlying assumptions about regulatory pathway stability and training curriculum standardization. Cross-checking against NATO defense procurement disclosure databases and CMS emergency department utilization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryotubes Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Europe Hospital Supplies Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
India Hospital Supplies Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Pharmacy Accessory Bagging System (PABS) Market