
 Scintillation Vials Market | 2026-2036
Scintillation Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Scintillation Vials Market Analytics
Polyethylene is repositioning glass in routine environmental and pharmaceutical workflows where cost-per-sample and breakage risk govern purchasing decisions. Thermo Fisher Scientific leverages its laboratory distribution network to sustain volume leadership across North American research channels. DWK Life Sciences anchors European supply through specialized borosilicate manufacturing capabilities. Saint-Gobain competes on material science expertise, extending its glass portfolio into low-background formulations for nuclear medicine.
Scintillation vials are sealed containers engineered to contain radioactive samples in liquid scintillation counting systems, typically manufactured from borosilicate glass or radiation-resistant polymers with wall thicknesses calibrated to minimize photon absorption and chemiluminescence interference. Their primary purpose is to ensure accurate detection of beta and alpha particle emissions in quantitative radioanalysis across clinical diagnostics, environmental surveillance, and drug metabolism studies. Low background vials command premium positioning in nuclear medicine and radiochemistry where picocurie-level sensitivity thresholds define protocol validity, while micro vials represent the fastest-growing format as miniaturization trends reduce reagent consumption in high-throughput pharmaceutical screening. Standard glass vials remain the mature revenue base across university and hospital end users with less stringent background requirements.
The FDA regulates liquid scintillation counting materials used in clinical diagnostic and new drug application submissions, while the EPA governs environmental radioanalysis protocols that dictate vial specifications for compliance monitoring. ISO 9001 and ISO 13485 quality management frameworks shape manufacturing standards for pharmaceutical and medical device supply chains, directly influencing vendor qualification and procurement eligibility. Stakeholders must monitor evolving radiopharmaceutical pipeline approvals and tightening environmental radionuclide thresholds to anticipate shifts in vial material specifications and volume demand across end-user segments.
Market Dynamics
Material substitution is the dominant structural force reshaping the Scintillation Vials Market, with radiation-resistant polyethylene formulations displacing borosilicate glass in cost-sensitive environmental monitoring workflows while specialized low-background glass retains premium positioning in nuclear medicine applications.
Growth Catalysts
- Radiopharmaceutical pipeline expansion:FDA and EMA approvals for novel diagnostic isotopes are expanding liquid scintillation counting volumes in clinical and preclinical research facilities.
- EPA protocol tightening:Updated radiological emission testing standards are mandating higher-purity vial specifications for environmental compliance monitoring across watershed and air quality surveillance programs.
- German nuclear medicine concentration:Radiochemistry laboratories in Germany are anchoring European demand for high-performance borosilicate formats with picocurie-level sensitivity thresholds.
Market Restraints
- High-purity raw material scarcity:Ultra-low background borosilicate glass feedstock concentrates among a limited supplier base in Central Europe, creating input cost volatility and allocation risk.
- Polyethylene optical limitations:Chemiluminescence interference and photon absorption rates in polymer vials restrict their deployment in high-sensitivity alpha and low-energy beta detection protocols.
- ISO 13485 certification barriers:Extended qualification timelines for medical device supply chain entry deter new polymer vial manufacturers from competing in diagnostic-grade segments.
Strategic Opportunities
- Micro vial format penetration:Miniaturized 4-7 mL vials are capturing volume in high-throughput pharmaceutical screening where reagent cost reduction drives purchasing decisions.
- India radiopharmaceutical manufacturing:CDSCO regulatory harmonization and production-linked incentive schemes are attracting contract manufacturing investment for diagnostic isotopes requiring specialized counting consumables.
- Closed-loop recycling systems:Polyethylene vial recovery programs aligned with EU Green Deal circular economy mandates are creating service-based differentiation for environmental laboratory suppliers.
Industry Challenges
- Low-background metrology expertise gap:Qualified technicians capable of validating picocurie-level detection protocols remain scarce across contract research organizations and environmental testing laboratories.
- Legacy LSC system integration:Miniaturized vial formats require adapter modifications and software recalibration for compatibility with installed base liquid scintillation counters in university settings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scintillation Vials Market |
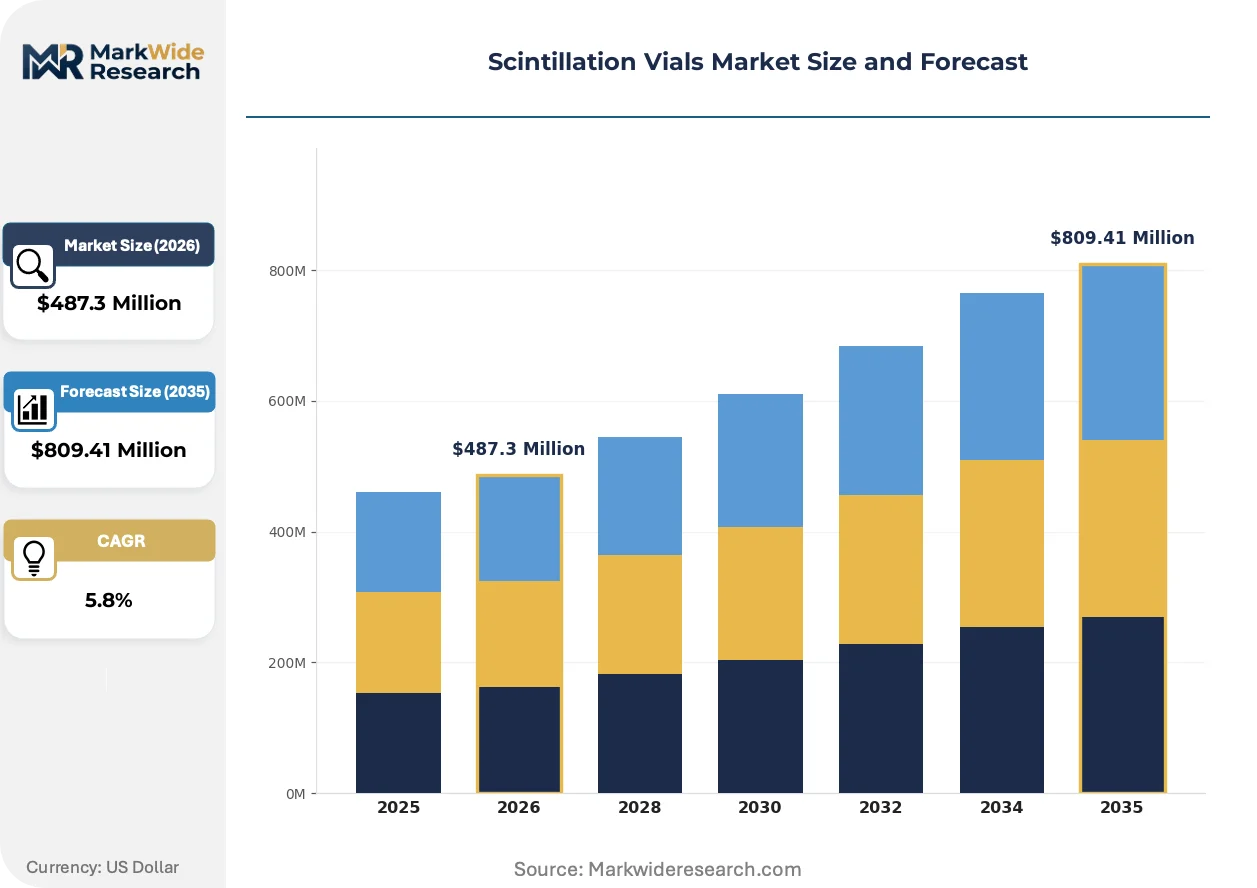
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Vials, Micro Vials, Low Background Vials, High Performance Vials Material: Glass, Polyethylene, Polystyrene, Borosilicate Application: Nuclear Medicine, Environmental Monitoring, Pharmaceutical Research, Radiochemistry End User: Hospitals, Research Institutes, Pharmaceutical Companies, Universities |
| Companies Covered | DWK Life Sciences, Wheaton Industries, Thermo Fisher Scientific, Kimble Chase, Qorpak, Saint-Gobain, VWR International, PerkinElmer, Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scintillation Vials Market Evolving Landscape
Manufacturing precision and material science convergence are redefining competitive positioning in scintillation vial supply, with automation, regulatory harmonization, and procurement centralization operating as interconnected forces rather than isolated developments.
Advanced polyethylene copolymer formulations with optimized optical clarity and radiation resistance are consolidating market share in routine environmental and pharmaceutical quality control applications. Contract testing laboratories in the United States are standardizing on these polymer formats for high-volume beta screening where breakage risk and per-sample economics govern equipment selection. This consolidation is compressing margin structures for commodity glass vial producers while opening volume opportunities for polymer specialists with ISO 9001-certified cleanroom manufacturing capabilities.
REACH substance restriction proposals and EU MDR technical documentation requirements are elevating material traceability standards for laboratory consumables used in diagnostic and environmental compliance workflows. Manufacturers must now demonstrate full supply chain transparency for borosilicate glass additives and polymer stabilizers to maintain market access. German and French radiopharmaceutical facilities are responding by consolidating supplier relationships toward vendors with established ECHA registration dossiers and dedicated regulatory affairs functions.
Consolidated procurement frameworks through group purchasing organizations and national laboratory consortia are displacing decentralized purchasing in academic and government research settings. Thermo Fisher Scientific's distribution network and DWK Life Sciences' direct European sales operations are capturing this channel shift. The United Kingdom's National Health Service and United States Department of Energy national laboratories exemplify this concentration, with multi-year framework agreements replacing transactional spot buying for liquid scintillation consumables.
Scintillation Vials Market Segmentation
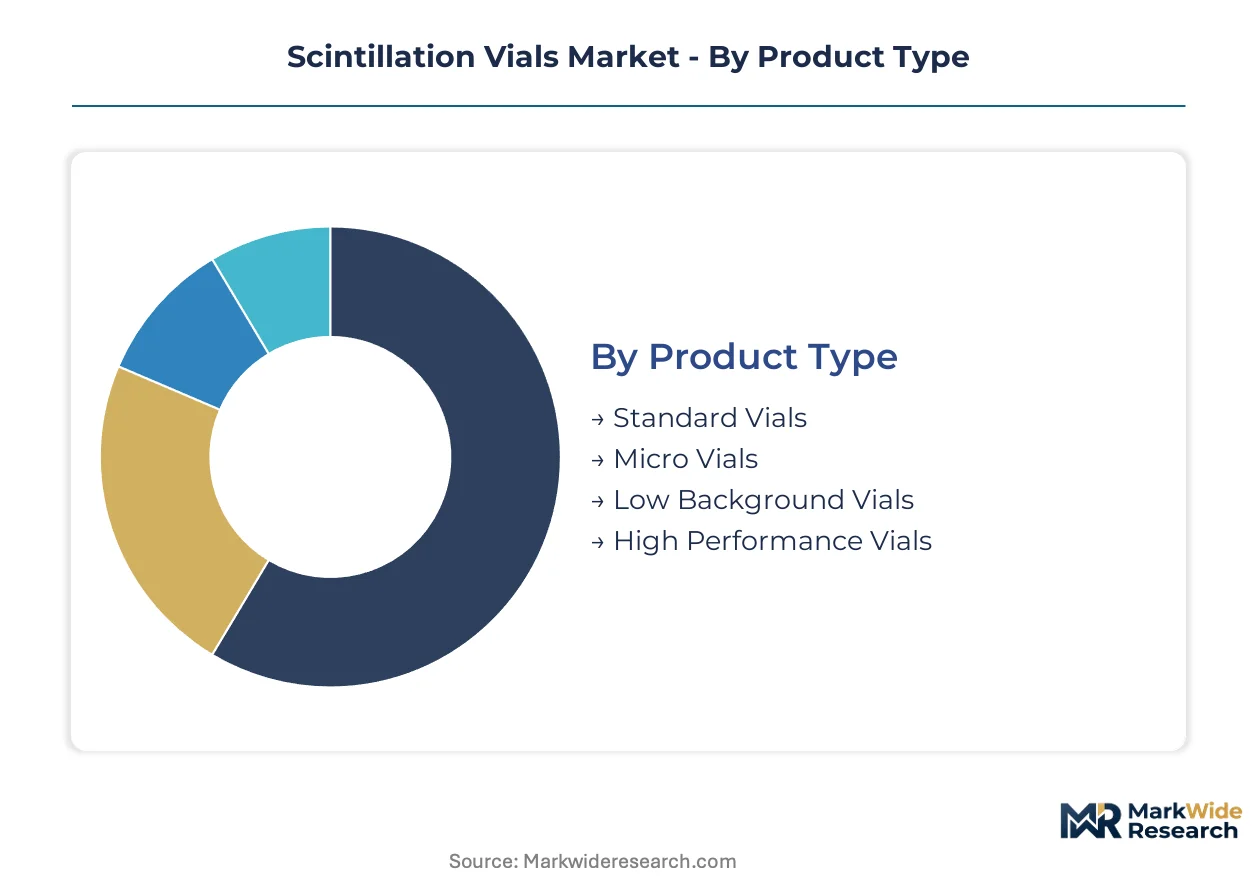
Scintillation vial procurement varies sharply by sensitivity threshold, sample volume, and regulatory compliance tier. Understanding these segment boundaries enables vendors to align manufacturing investments with validated demand pockets across nuclear medicine, environmental surveillance, and pharmaceutical workflows.
Product Type:
Customization intensity spans from commodity formats with minimal specification variance to precision-engineered variants requiring batch-level certification.
- Standard Vials:Borosilicate glass construction with 20 mL nominal capacity serves routine beta counting in university teaching labs and hospital radioimmunoassay departments. Procurement concentrates in the United States through group purchasing organizations serving academic medical centers, driven by cost-per-sample economics and compatibility with legacy liquid scintillation counters.
- Micro Vials:Miniaturized 4-7 mL polyethylene formats reduce reagent consumption in high-throughput pharmaceutical screening workflows. Demand is climbing fastest in German contract research organizations where 384-well plate integration and automated liquid handling systems require reduced sample volumes without sensitivity degradation.
- Low Background Vials:Ultra-purity borosilicate or specialized polymer formulations with potassium-40 depleted glass achieve picocurie-level detection thresholds for nuclear medicine applications.
- High Performance Vials:Engineered wall thickness and optical clarity specifications optimize photon transmission for alpha particle detection and dual-label counting protocols.
Most installed capacity flows through Standard Vials. Expansion is steepest in Micro Vials.
Material:
Material selection traces a cost-sensitivity versus optical performance frontier that separates environmental monitoring from clinical diagnostic applications.
- Glass:Soda-lime formulations dominate price-sensitive educational markets where breakage tolerance and thermal shock resistance requirements remain modest.
- Polyethylene:Radiation-resistant copolymer grades with optimized optical clarity are displacing glass in high-volume environmental testing workflows across EPA-regulated watershed monitoring programs, governed by per-sample economics and elimination of breakage risk in field collection settings.
- Polystyrene:Crystal-clear amorphous polymer serves disposable single-use applications in pharmaceutical quality control where cost minimization outweighs radiation resistance requirements.
- Borosilicate:Low thermal expansion coefficient and chemical inertness anchor premium positioning in radiochemistry laboratories requiring autoclave sterilization and aggressive solvent compatibility.
Polyethylene captures the highest shipment volumes in environmental applications. Borosilicate commands the steepest price premiums in nuclear medicine.
Application:
Regulatory stringency and detection sensitivity requirements create four distinct procurement specifications with minimal overlap in vendor qualification.
- Nuclear Medicine:PET radiopharmaceutical manufacturing and diagnostic isotope quality control demand low-background vials with documented potassium-40 content below 0.1 percent. German radiochemistry facilities anchor European consumption, with FDA and EMA batch release testing protocols mandating validated vial specifications for clinical diagnostic applications.
- Environmental Monitoring:EPA radiological emission testing protocols govern vial purity requirements for tritium and carbon-14 detection in air and water compliance surveillance. United States contract testing laboratories standardize on polyethylene formats for high-throughput beta screening where sample volume economics dominate equipment selection.
- Pharmaceutical Research:ADME studies and drug metabolism profiling require scintillation vials compatible with organic solvent cocktails and automated liquid handling systems.
- Radiochemistry:Specialized alpha and beta separation protocols demand vials with minimal chemiluminescence interference and precise geometry for coincidence counting.
Environmental Monitoring generates the highest unit volumes. Nuclear Medicine sustains the most stringent specification premiums.
End User:
Procurement centralization and technical specification authority vary sharply across institutional categories with divergent budget cycles and compliance mandates.
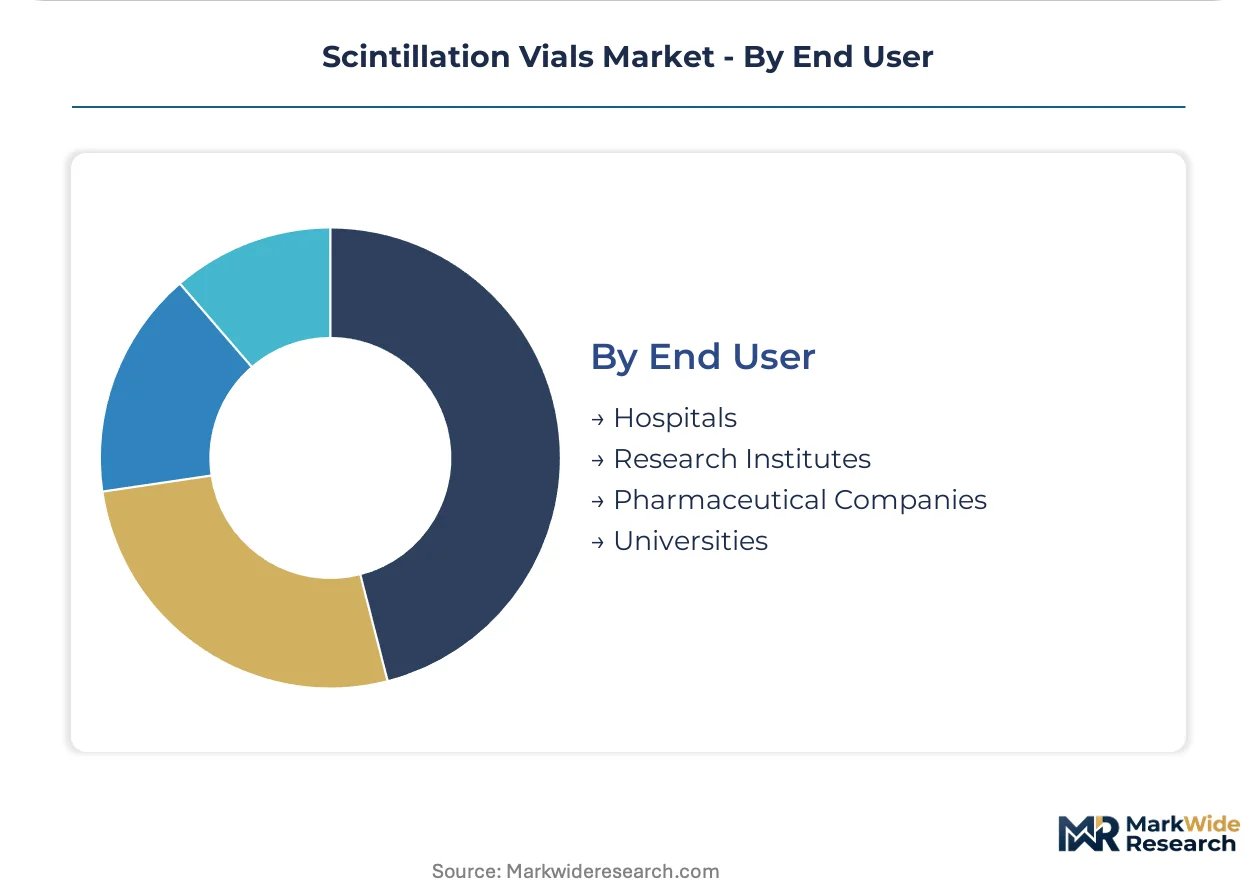
- Hospitals:Clinical diagnostic laboratories with radioimmunoassay and nuclear medicine departments purchase through consolidated supply agreements. United States health systems leverage group purchasing organization contracts for standardized vial formats, with FDA diagnostic device regulations shaping vendor qualification requirements.
- Research Institutes:National laboratories and government research facilities operate under multi-year framework agreements with stringent material traceability documentation. The United States Department of Energy national laboratory system exemplifies this procurement concentration, with ISO 9001 and ISO 13485 certification mandatory for liquid scintillation consumable suppliers.
- Pharmaceutical Companies:High-throughput screening and regulatory submission studies drive demand for micro vial formats and validated low-background specifications in drug development workflows.
- Universities:Teaching and basic research applications with less stringent background requirements sustain demand for standard glass vials through decentralized departmental purchasing.
Research Institutes concentrate the largest contract values. Pharmaceutical Companies are expanding procurement most aggressively in micro vial formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German radiochemistry laboratories anchor European consumption of high-performance borosilicate formats, while procurement centralization across United States national laboratories and health systems concentrates contract value in North America.
United States
Pharmaceutical research institutes are expanding procurement of low-background polyethylene vials for high-sensitivity liquid scintillation counting workflows. The EPA's updated radiological emission testing protocols are tightening material purity requirements for environmental monitoring applications. Department of Energy national laboratories operate under multi-year framework agreements that mandate ISO 9001 and ISO 13485 certification for liquid scintillation consumable suppliers.
Germany
Nuclear medicine facilities and radiochemistry laboratories anchor European consumption of borosilicate and specialized high-performance vial formats with picocurie-level sensitivity thresholds. The EU MDR technical documentation requirements are elevating material traceability standards for laboratory consumables used in diagnostic workflows. REACH substance restriction proposals are driving radiopharmaceutical facilities toward vendors with established ECHA registration dossiers and dedicated regulatory affairs functions.
United Kingdom
The National Health Service is consolidating procurement through multi-year framework agreements that replace transactional spot buying for liquid scintillation consumables. EU Green Deal circular economy mandates are creating service-based differentiation for environmental laboratory suppliers through closed-loop recycling systems. Academic medical centers in London and the Southeast are standardizing on group purchasing organization contracts for routine beta counting applications.
India
CDSCO regulatory harmonization and production-linked incentive schemes are attracting contract manufacturing investment for diagnostic isotopes requiring specialized counting consumables. The country's national pharmaceutical regulator is aligning with international standards to facilitate radiopharmaceutical pipeline expansion. Manufacturing clusters in Maharashtra and Gujarat are emerging as production hubs for radiation-resistant polymer formulations serving domestic and export markets.
France
Radiopharmaceutical facilities are responding to REACH substance restrictions by consolidating supplier relationships toward vendors with full supply chain transparency. ANSM oversight of clinical diagnostic materials shapes vendor qualification requirements for nuclear medicine applications. The Île-de-France region concentrates demand from research institutes and hospital networks with radioimmunoassay departments.
Scintillation Vials Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend material science expertise across glass and polymer formulations. The vendor base separates into three tiers: diversified laboratory conglomerates with distribution scale, specialized borosilicate fabricators with European manufacturing heritage, and polymer specialists with cleanroom certification capabilities. Strategic archetypes include premium-format specialists competing on low-background metrology, volume-driven polymer producers capturing environmental testing workflows, and integrated laboratory suppliers leveraging procurement centralization. M&A activity and capacity expansion in radiation-resistant polymer grades represent the dominant competitive moves.
Among diversified laboratory conglomerates, Thermo Fisher Scientific and DWK Life Sciences occupy positions that exemplify contrasting geographic anchoring strategies. Thermo Fisher Scientific represents the distribution-scale archetype across North American research channels. DWK Life Sciences sits within the specialized European manufacturing tier through its borosilicate capabilities. Saint-Gobain exemplifies the material science extension strategy, with its glass portfolio reaching into low-background formulations for nuclear medicine applications.
| Leading Market Players |
|---|
| DWK Life Sciences |
| Wheaton Industries |
| Thermo Fisher Scientific |
| Kimble Chase |
| Qorpak |
| Saint-Gobain |
| VWR International |
| PerkinElmer |
| Corning |
| Others |
Value Network & Pricing Analysis
Department of Energy national laboratories and NHS procurement frameworks concentrate buying power among qualified suppliers, compressing margins for commodity formats while sustaining premium pricing for ISO 13485-certified low-background specifications. This buyer consolidation rewards vendors with regulatory dossiers and cleanroom manufacturing capabilities.
Pricing Analysis
Ultra-low background borosilicate glass feedstock costs in Central Europe pass through directly to nuclear medicine vial pricing, with potassium-40 depleted formulations commanding substantial premiums over standard grades. Three-tier pricing structure across premium, standard, and economy levels separates validated low-background vials from routine environmental polyethylene formats and commodity soda-lime teaching lab supplies. Cost compression in standard glass intensifies as polyethylene displaces borosilicate in EPA-regulated environmental workflows. Pharmaceutical companies exhibit the sharpest price sensitivity due to high-throughput screening volumes, while German radiochemistry facilities prioritize detection thresholds over per-unit economics.
Supply Chain Analysis
Dual-sourcing requirements from United States national laboratories and European radiopharmaceutical facilities mandate multi-supplier qualification for critical low-background formats, preventing single-source dependency despite concentrated glass feedstock origins. Manufacturing draws from Germany, the United States, and India for borosilicate fabrication, radiation-resistant polymer compounding, and emerging polymer vial assembly respectively. Feedstock dependence on potassium-40 depleted glass and specialized polyethylene copolymers creates allocation risk during demand surges. Tariff exposure on Chinese-origin polymer additives threatens cost structures for environmental testing suppliers. Distribution runs through Thermo Fisher Scientific's North American laboratory network and DWK Life Sciences' direct European sales operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Scintillation Vials Market functions as a stable compounder anchored by radiopharmaceutical pipeline expansion and tightening environmental compliance mandates that sustain replacement demand across institutional end users.
For Market Incumbents: Anticipate polyethylene formulation advances eroding glass share in environmental applications by investing in radiation-resistant polymer cleanroom capacity alongside borosilicate preservation. Deepen backward integration into potassium-40 depleted glass feedstock to secure allocation against Central European supply concentration. Prioritize ISO 13485 certification maintenance as FDA diagnostic device regulations tighten vendor qualification barriers. For New Entrants and Emerging Players: CDSCO harmonization in India opens a window for contract manufacturing of diagnostic isotope counting consumables serving domestic radiopharmaceutical production. Target micro vial formats for pharmaceutical high-throughput screening where automated liquid handling integration requirements deter incumbent glass specialists. Pursue group purchasing organization channel access through technical service bundling rather than price-only positioning. For Investors and Strategic Acquirers: Laboratory conglomerates with distribution scale are the most active acquirer in this space, seeking polymer formulation capabilities to complement glass portfolios. The market supports long-term viability through regulatory ratchet effects that embed specification requirements into recurring procurement cycles. Monitor EPA protocol revision announcements as inflection indicators for low-background vial demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Polymer Capacity Expansion | Captures EPA environmental testing standardization away from glass breakage risk. |
| Potassium-40 Depleted Glass Backward Integration | Secures feedstock allocation for German radiochemistry laboratory contracts. |
| Micro Vial Format Development | Aligns with pharmaceutical 384-well plate automation and reagent cost reduction priorities. |
| ISO 13485 Certification Investment | Maintains FDA diagnostic device supply chain eligibility against tightening qualification. |
| Closed-Loop Recycling Program Launch | Addresses EU Green Deal circular economy mandates for environmental laboratory differentiation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with radiochemistry laboratory directors, pharmaceutical procurement managers, EPA compliance officers, and GPO contracts specialists with secondary validation from FDA 510(k) filings, ECHA registration dossiers, Department of Energy procurement databases, and ISO certification registries. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from trade flow analysis.
Historical reference periods anchored the projection horizon through validated installation base data for liquid scintillation counters and radiopharmaceutical production capacity expansion plans. The analytical framework modeled demand across product type, material grade, application sensitivity tier, and end-user procurement centralization level. CAGRs derived from segment-level volume trajectories weighted by price realization differentials, with radiopharmaceutical pipeline approvals and EPA protocol revision schedules serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt radiopharmaceutical regulatory rejection or polyethylene optical clarity breakthroughs. Deviation in German nuclear medicine funding allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
Global Contact Lens Solution Market
Medical Supplies
Swab Cups Market
Medical Supplies
Evidence Collection Tubes Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Nasal Splints Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Plastic Bandages Market
Medical Supplies
Blood Collection Tubes for Liquid Biopsy Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Woven Medical Tape Market