
 Europe Amniotic Membrane Market | 2026-2036
Europe Amniotic Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Amniotic Membrane Market Foresight
Cryopreserved specification-tier dominance is collapsing as decellularized formats gain traction among European surgical centers. Integra LifeSciences leverages its established tissue processing infrastructure across continental Europe. MiMedx Group Inc anchors its position through specialized placental tissue platforms. Smith & Nephew plc competes via integrated wound care portfolios that incorporate amniotic grafts.
Amniotic membrane comprises the innermost placental layer rich in collagen types IV and V, hyaluronic acid, and growth factors that modulate inflammation and scaffold epithelial migration; manufacturers preserve this matrix through cryopreservation or decellularization to retain bioactivity for clinical grafting. Cryopreserved amniotic membrane grafts lead current revenue pools due to established reimbursement pathways, while decellularized variants represent the fastest-growing product category as hospitals prioritize reduced immunogenicity profiles. Application demand concentrates in wound healing and ophthalmology, with surgical reconstruction representing a mature but stable segment where margin pools have compressed.
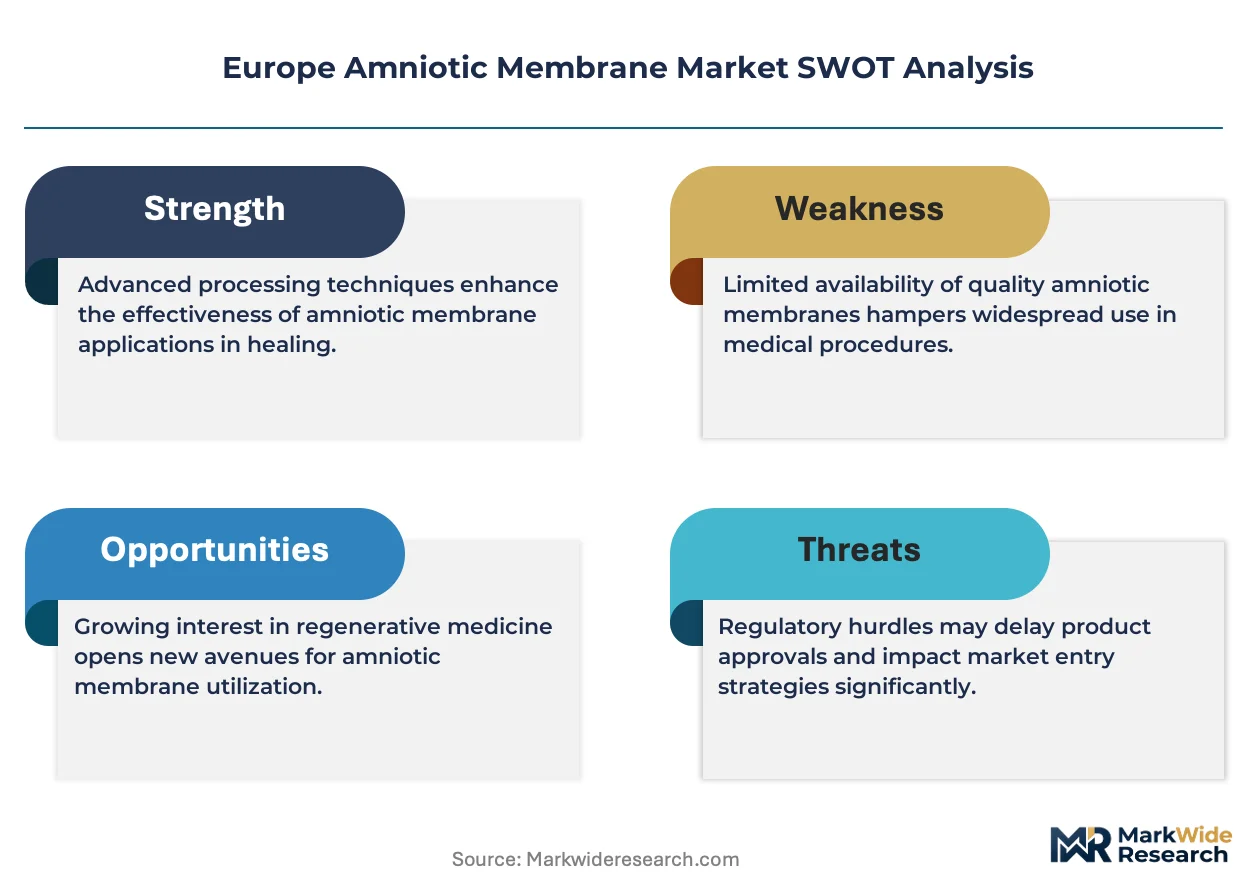
EMA oversight through the EU Tissue and Cells Directive harmonizes quality standards, while CE marking under the EU Medical Device Regulation governs commercial access and post-market surveillance obligations. National regulators in Germany, France, and Italy enforce additional tissue establishment licensing that shapes distribution feasibility. Stakeholders must monitor evolving EMA guidance on advanced therapy medicinal product classifications that could reframe regulatory pathways for bioengineered membrane derivatives.
Market Dynamics
The transition from cryopreserved to decellularized amniotic membrane formats is restructuring competitive advantage across European surgical centers, as hospitals prioritize reduced immunogenicity profiles and streamlined graft handling protocols.
Growth Catalysts
- EU Medical Device Regulation:CE marking harmonization under MDR is consolidating quality benchmarks, accelerating hospital adoption of standardized graft products across Germany, France, and Italy.
- Ophthalmology clinic demand:Corneal repair procedures are expanding membrane graft utilization as surgeons recognize superior epithelial migration scaffolding compared to synthetic alternatives.
- Decellularization technology:Advanced processing methods are removing cellular components while preserving collagen matrices, enabling broader allogeneic tissue compatibility.
Market Restraints
- Human tissue supply concentration:Placental tissue sourcing depends on a limited network of EU-registered tissue establishments, creating procurement bottlenecks during donor availability fluctuations.
- MDR compliance costs:Enhanced technical documentation and clinical evidence requirements under EU Medical Device Regulation are elevating barriers for smaller membrane processors.
- Synthetic scaffold substitution:Collagen-based synthetic matrices are capturing price-sensitive wound care segments where reimbursement rates compress graft margins.
Strategic Opportunities
- Poland and Eastern Europe:Underdeveloped amniotic membrane penetration in ophthalmology and reconstructive surgery presents first-mover expansion potential for established processors.
- Advanced therapy medicinal products:EMA guidance evolution on bioengineered membrane derivatives could unlock novel regulatory pathways for combination products.
- Direct hospital contracting:Bypassing traditional distributor networks through specialized tissue bank partnerships is reducing procurement friction for high-volume surgical centers.
Industry Challenges
- Bioprocessing technician scarcity:Specialized expertise in aseptic tissue processing and cryopreservation protocol management remains concentrated among veteran practitioners.
- EU Tissue and Cells Directive traceability:Donor-to-recipient tracking systems require substantial IT infrastructure investment for compliance with EMA-mandated documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Amniotic Membrane Market |
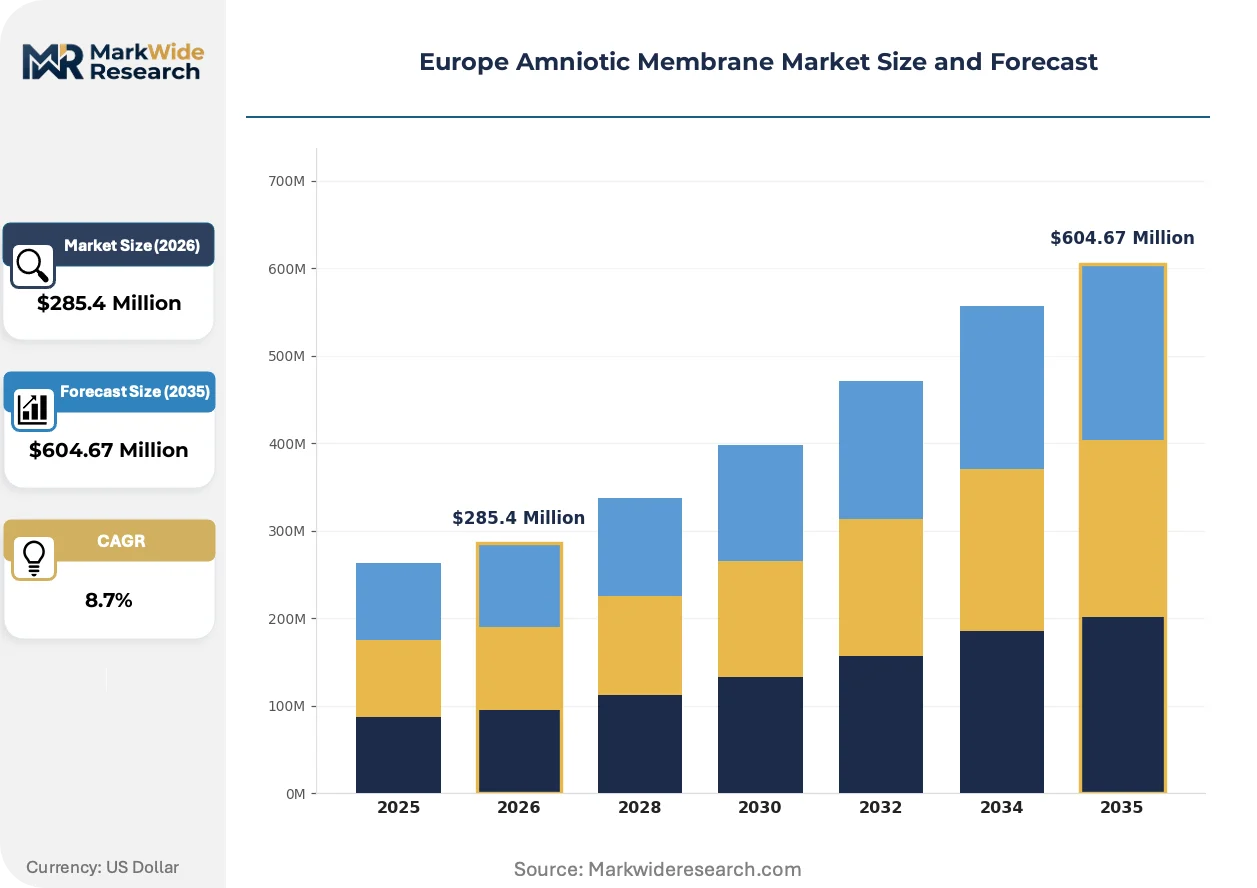
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amniotic Membrane Graft, Decellularized Amniotic Membrane, Cryopreserved Amniotic Membrane, Fresh Amniotic Membrane Application: Wound Healing, Ophthalmology, Surgical Reconstruction, Tissue Regeneration End User: Hospitals, Surgical Centers, Specialty Clinics, Research Institutions Delivery Mode: Direct Delivery, Mail Order, In-Clinic Dispensing, Telehealth Services |
| Companies Covered | Integra LifeSciences, MiMedx Group Inc, Organogenesis Holdings Inc, Smith & Nephew plc, Stryker, Skye Biologics, Amnio Technology, Applied Biologics, Human Regenerative Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Amniotic Membrane Market Shifts & Advancements
Processing technology divergence and procurement model evolution are fragmenting traditional market boundaries, creating distinct competitive arenas for premium bioactive grafts versus commoditized membrane products.
Decellularization technology is fragmenting the historical dominance of cryopreserved formats. The process removes cellular antigens while retaining hyaluronic acid and growth factor reservoirs. German and French ophthalmology clinics are adopting decellularized grafts at accelerated rates for corneal surface reconstruction. This shift is compressing margins for processors dependent on legacy cryopreservation infrastructure while rewarding facilities with advanced enzymatic processing capabilities.
EMA oversight through the EU Tissue and Cells Directive is tightening donor screening and processing documentation requirements. The directive mandates comprehensive traceability from tissue establishment to clinical implantation. Cryopreserved membrane manufacturers face the steepest compliance adaptation costs due to temperature-controlled logistics complexity. German tissue banks are investing in automated documentation systems to satisfy intensified EMA inspection protocols.
Hospital procurement departments are consolidating supplier relationships around integrated wound care portfolios. Single-source contracting for amniotic grafts bundled with advanced dressings is displacing fragmented multi-vendor purchasing. United Kingdom NHS trusts are pioneering this consolidation through framework agreements that specify membrane performance benchmarks. This behavioral shift favors processors with diversified regenerative medicine product lines over specialized amniotic membrane-only suppliers.
Europe Amniotic Membrane Market Segmentation
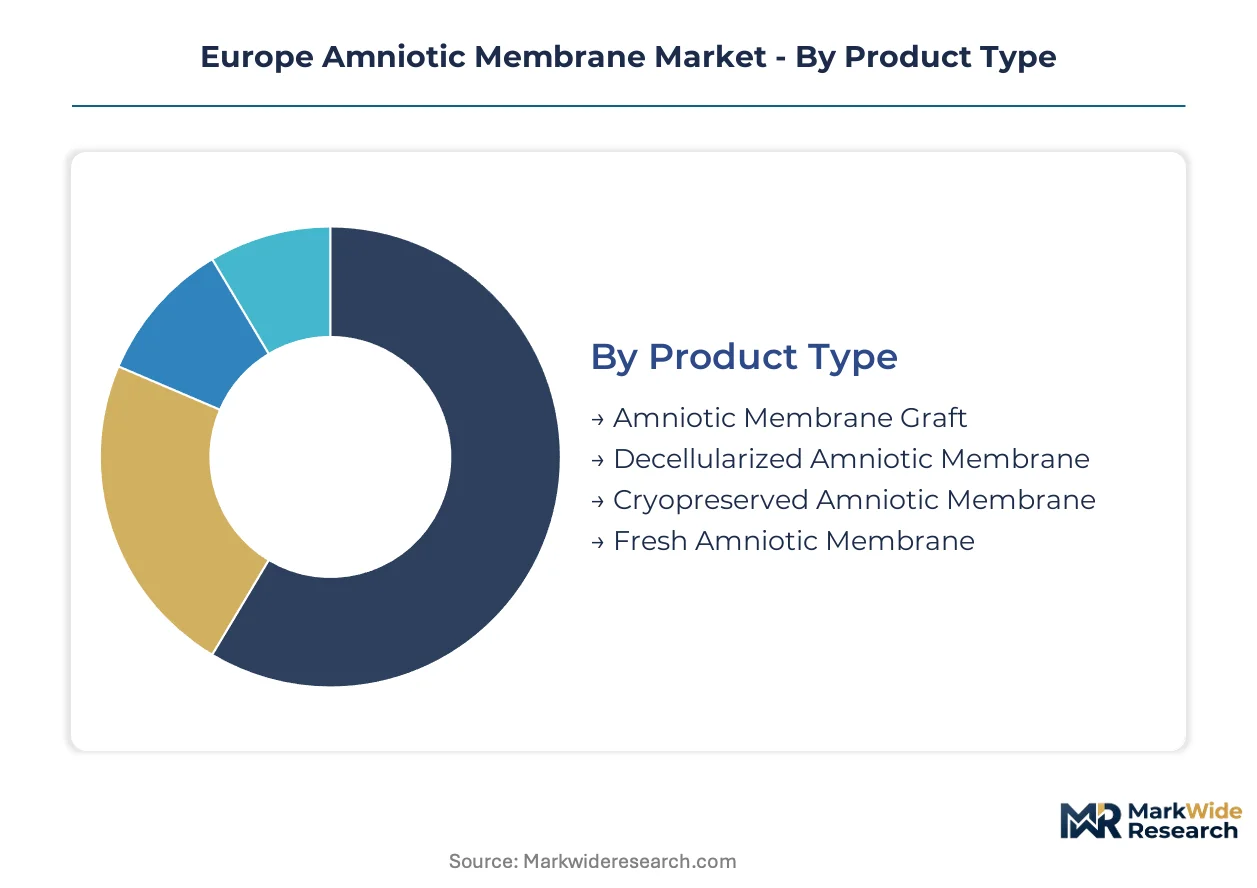
Segmentation in the Europe Amniotic Membrane Market reveals how processing methods, clinical settings, and procurement channels reshape competitive boundaries. Manufacturers align product portfolios against specific reimbursement pathways and surgical workflow requirements.
Product Type:
Cryopreserved formats dominate procurement volumes across German and French hospital networks, while decellularized variants attract export demand from specialized ophthalmology centers in Switzerland and the Nordic region.
- Amniotic Membrane Graft:Standardized grafts combine epithelial and stromal layers for immediate surgical application. United Kingdom NHS procurement frameworks prioritize these grafts for burn unit protocols due to established handling familiarity among theatre nurses.
- Decellularized Amniotic Membrane:Enzymatic processing strips cellular antigens while preserving hyaluronic acid reservoirs. Italian ophthalmology clinics in Milan and Rome are adopting these grafts for corneal surface reconstruction where immunogenicity concerns limit allogeneic tissue tolerance.
- Cryopreserved Amniotic Membrane:Temperature-controlled logistics sustain bioactive growth factor content for wound healing applications.
- Fresh Amniotic Membrane:Limited shelf-life restricts deployment to academic medical centers with on-site tissue processing capabilities.
Cryopreserved amniotic membrane commands the established base. The steepest expansion runs through decellularized formats.
Application:
Margin structures diverge sharply between reimbursed hospital procedures and cash-pay aesthetic applications, with wound healing carrying the heaviest documentation burden under MDR technical file requirements.
- Wound Healing:Chronic diabetic foot ulcers and venous leg ulcers drive recurring graft consumption. German statutory health insurance reimbursement codes support weekly application protocols in specialized wound care centers.
- Ophthalmology:Pterygium excision and corneal defect repair utilize membrane grafts as biological bandages. French university hospitals in Paris and Lyon are expanding surgical volumes for limbal stem cell deficiency cases.
- Surgical Reconstruction:Plastic surgeons deploy grafts for intraoral lining and dural repair where autologous tissue harvest carries donor site morbidity.
- Tissue Regeneration:Investigational protocols in Dutch and Belgian research hospitals explore scaffold applications for cartilage and tendon engineering.
Wound healing commands the established base. The steepest expansion runs through ophthalmology.
End User:
Procurement authority concentration varies by country, with French hospital pharmacists controlling tissue product selection while German surgeon preference cards drive purchasing decisions.
- Hospitals:Centralized tissue committees govern amniotic membrane formulary inclusion. United Kingdom teaching hospitals maintain dual-source contracts to mitigate supply disruption risk.
- Surgical Centers:Ambulatory settings in Spain and Portugal prioritize graft formats with simplified thawing protocols to minimize nursing labor costs.
- Specialty Clinics:Ophthalmology and wound care clinics in private practice purchase smaller lot sizes with premium per-unit pricing.
- Research Institutions:Academic tissue banks in Sweden and Denmark source membranes for bioengineering protocol development under EMA advanced therapy guidance.
Hospitals command the established base. The steepest expansion runs through surgical centers.
Delivery Mode:
Logistics infrastructure investment separates national distributors from pan-European players, with temperature excursion liability shaping contractual risk allocation.
- Direct Delivery:Processor-to-hospital shipments bypass wholesale layers for high-volume accounts. German tissue establishments operate dedicated cold-chain fleets serving Bavarian and North Rhine-Westphalian hospital networks.
- Mail Order:Specialized couriers handle cryopreserved shipments to remote Scottish and Irish clinics outside major urban centers.
- In-Clinic Dispensing:Point-of-care inventory holding requires refrigerator validation protocols that smaller Italian practices struggle to maintain.
- Telehealth Services:Remote consultation platforms in the Netherlands facilitate patient screening for amniotic membrane eligibility prior to surgical scheduling.
Direct delivery commands the established base. The steepest expansion runs through telehealth-integrated channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's amniotic membrane trade flows reveal a net importer position, with German and French processors sourcing placental tissue from specialized EU tissue establishments while exporting finished grafts to Swiss and Nordic clinics seeking premium decellularized formats.
Germany
Bavarian university hospitals in Munich and Erlangen drive demand for cryopreserved grafts in burn reconstruction protocols. The German Transplantation Act enforces strict tissue establishment licensing through the Paul-Ehrlich-Institut. North Rhine-Westphalia hosts concentrated processing infrastructure serving hospital networks across the Rhine-Ruhr metropolitan region.
France
Paris and Lyon ophthalmology centers expand corneal surface reconstruction volumes using decellularized membranes. ANSM oversight harmonizes with EMA's EU Tissue and Cells Directive for donor traceability compliance. The Île-de-France region concentrates procurement authority among hospital pharmacists who control formulary inclusion decisions.
United Kingdom
NHS trusts in London and Manchester pioneer framework agreements bundling amniotic grafts with advanced wound dressings. The Human Tissue Authority regulates tissue establishment licensing separately from EU frameworks post-Brexit. Scotland's remote clinics rely on specialized courier networks for cryopreserved shipments outside urban centers.
Italy
Milan and Rome ophthalmology clinics adopt decellularized formats where immunogenicity concerns limit allogeneic tolerance. The Italian National Transplant Centre enforces additional documentation beyond EMA baseline requirements. Northern Italian tissue banks invest in automated tracking systems for intensified inspection protocols.
Poland
Warsaw and Krakow surgical centers present first-mover expansion potential as ophthalmology and reconstructive surgery penetration remains underdeveloped. Polish medical device regulations align with MDR harmonization timelines. Regional hospital networks seek simplified thawing protocols to minimize nursing labor costs in ambulatory settings.
Europe Amniotic Membrane Market Competitive Landscape
Listed leaders compete with private specialists across capital access and regulatory compliance capabilities, creating a tiered structure where scale-driven processors absorb MDR documentation costs while smaller tissue banks retreat to niche regional contracts. Three archetypes dominate: diversified medtech conglomerates with integrated wound care portfolios, specialized placental tissue processors with dedicated bioprocessing infrastructure, and regional tissue banks serving single-country hospital networks. Competitive moves concentrate on M&A for tissue establishment licenses and backward integration into placental sourcing networks.
Within the diversified medtech tier, Integra LifeSciences and Smith & Nephew plc exemplify processors leveraging established European distribution infrastructure across continental markets. MiMedx Group Inc occupies a position among specialized placental tissue platforms focused on proprietary processing methods. These three entities represent contrasting strategic postures on regulatory compliance investment and geographic coverage breadth.
| Leading Market Players |
|---|
| Integra LifeSciences |
| MiMedx Group Inc |
| Organogenesis Holdings Inc |
| Smith & Nephew plc |
| Stryker |
| Skye Biologics |
| Amnio Technology |
| Applied Biologics |
| Human Regenerative Technologies |
| Others |
Supply & Pricing Matrix
Scale economies in cryopreservation infrastructure anchor price floors across German and French tissue processing networks, concentrating supply leverage among established EU-registered tissue establishments while compressing margins for smaller membrane processors lacking dedicated cold-chain logistics.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium decellularized, standard cryopreserved, and economy fresh membrane formats. Price differentiation rests on EMA certification tier and volume commitment scale, with NHS trusts commanding lowest per-unit rates through framework agreements. Cost compression in cryopreserved tiers is intensifying as MDR compliance documentation elevates fixed cost burdens. Ambulatory surgical centers in Southern Europe exhibit highest price sensitivity due to limited reimbursement bandwidth.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for temperature-controlled placental tissue shipments originating from Spanish and Portuguese donor networks. Supply concentrates in Germany, France, and Italy through licensed tissue establishments feeding downstream processors. Raw material dependencies center on donor recruitment networks, cryoprotectant solutions, and enzymatic processing reagents. Single-source vulnerability runs through limited EU-registered placenta procurement sites. Distribution runs through processor-direct cold-chain fleets serving high-volume hospital accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through EMA tissue establishment licensing creates formidable defensive moats, as MDR compliance costs and traceability infrastructure requirements deter unqualified entrants from scaling meaningful market presence.
For Market Incumbents: Secure backward integration into placental sourcing networks to eliminate donor availability bottlenecks threatening production continuity. Fortify cryopreservation capacity in Bavaria and North Rhine-Westphalia against decellularization technology substitution eroding legacy format margins. Deepen hospital system partnerships through bundled wound care portfolio contracts displacing fragmented multi-vendor purchasing.
For New Entrants and Emerging Players: Differentiate on simplified thawing protocols targeting Polish and Eastern European ambulatory surgical centers where nursing labor cost sensitivity exceeds bioactive performance requirements. Penetrate ophthalmology clinic segments in Warsaw and Krakow through specialized decellularized graft offerings. Pursue direct-to-clinic telehealth-integrated channels bypassing established distributor relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized placental tissue processors with proprietary enzymatic decellularization capabilities over diversified wound care conglomerates. Long-term viability hinges on EMA advanced therapy medicinal product pathway navigation for bioengineered membrane derivatives. Acquisition targets should demonstrate automated donor-to-recipient traceability systems satisfying intensified inspection protocols. Watch EMA guidance evolution on combination product classifications as inflection signal for regulatory pathway reframing.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investment accelerates hospital formulary inclusion across German networks. |
| Tissue Establishment Licensing | Paul-Ehrlich-Institut and ANSM registrations create procurement eligibility for NHS and French hospital systems. |
| Hospital System Partnership | Framework agreements with United Kingdom NHS trusts bundle amniotic grafts with advanced dressing portfolios. |
| Decellularization Scale-Up | Enzymatic processing capacity expansion captures ophthalmology demand shifting from cryopreserved formats. |
| Reimbursement Strategy | German statutory health insurance code alignment secures recurring weekly application protocols in wound care centers. |
Research Methodology
Desk research of EMA regulatory filings, EU Tissue and Cells Directive guidance documents, and hospital procurement databases preceded structured interviews with tissue bank operations directors, ophthalmology surgeons, wound care clinic managers, and biomedical procurement officers. Secondary validation drew from CE marking registries, Paul-Ehrlich-Institut licensing records, and NHS supply chain frameworks. Bottom-up graft volume modeling triangulated against top-down market sizing from processor capacity declarations.
Variance decomposition across product type, application, end user, and delivery mode dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate assumptions weighted by procurement volume concentration in Germany, France, and the United Kingdom. Industry-specific forecast inputs incorporated MDR implementation timelines and EMA advanced therapy guidance evolution.
The analysis sits within stated boundaries; outcomes outside sustained EMA regulatory stability and donor recruitment network expansion would require recalibration. Forecasts reflect assumptions regarding reimbursement code maintenance and cryopreserved-to-decellularized format transition velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Demulcent Eye Drops Market
Medical Supplies
Global Hot and Cold Therapy Packs Market
Medical Supplies
Foley Trays Market
Medical Supplies
Acid Citrate Dextrose Tubes Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Europe Medical Clothing Market
Medical Supplies
Endoscope Cleaning Products Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Emesis Bag Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Urine Meter Trays Market
Medical Supplies
Port Access Needles Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Tracheostomy Securement Tapes Market