
 Italy Hospital Supplies Market | 2026-2036
Italy Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Hospital Supplies Market Foresight
Multi-source procurement among Italian health trusts is broadening as regional authorities diversify supplier bases beyond legacy single-source contracts. Baxter International leverages its infusion therapy portfolio to sustain long-term agreements with Lombardy hospital networks. DE LAMA S.P.A. specializes in sterilization equipment and anchors supply relationships with central Italy's public hospital consortia. B. Braun competes through its extensive dialysis and surgical product range across northern rehabilitation centers.
Hospital supplies encompass disposable and durable goods used in patient diagnosis, treatment, and monitoring, including sterile gauze, catheters, surgical drapes, and electronic monitoring devices manufactured under ISO 13485 quality management protocols. These products serve acute care delivery, infection control, and procedural safety within institutional healthcare settings. Disposable supplies command the largest volume share due to single-use protocols mandated by Italy's National Health Service infection guidelines. Patient monitors represent a concentrated margin pool as hospitals replace aging multi-parameter systems with networked telemetry platforms. Diagnostic equipment sustains replacement demand cycles tied to regional health technology assessment schedules.
Italy's Ministry of Health and the Italian Medicines Agency (AIFA) regulate medical device classification, reimbursement eligibility, and clinical evidence requirements under EU Medical Device Regulation transitional provisions. The National Institute of Health (Istituto Superiore di Sanità) sets sterilization and biocompatibility standards that shape product specifications for domestic manufacturers and importers alike. Stakeholders must monitor regional health procurement consolidation and AIFA pricing revision timelines to align portfolio investments with shifting reimbursement thresholds.
Market Dynamics
Italy's hospital supplies sector is being reshaped by the National Health Service's accelerated shift toward centralized regional procurement consortia, which are consolidating purchasing power across Lombardy, Lazio, and Veneto while mandating stricter ISO 13485 compliance tiers for vendor qualification.
Growth Catalysts
- EU Medical Device Regulation transitional provisions:Italy's implementation of MDR Class IIa and IIb recertification deadlines is forcing hospital networks to replace legacy devices, creating replacement demand for patient monitors and infusion systems that meet enhanced clinical evidence requirements.
- Surgical procedure volume concentration in northern Italy:Lombardy's hospital network performs the highest density of elective surgeries nationally, driving sustained consumption of disposable drapes, sterile gauze, and procedure kits through volume-based procurement frameworks.
- Telemetry platform networking:Public hospitals are retrofitting aging multi-parameter monitoring systems with wireless telemetry infrastructure, unifying bedside and remote patient data streams under single-platform architectures.
Market Restraints
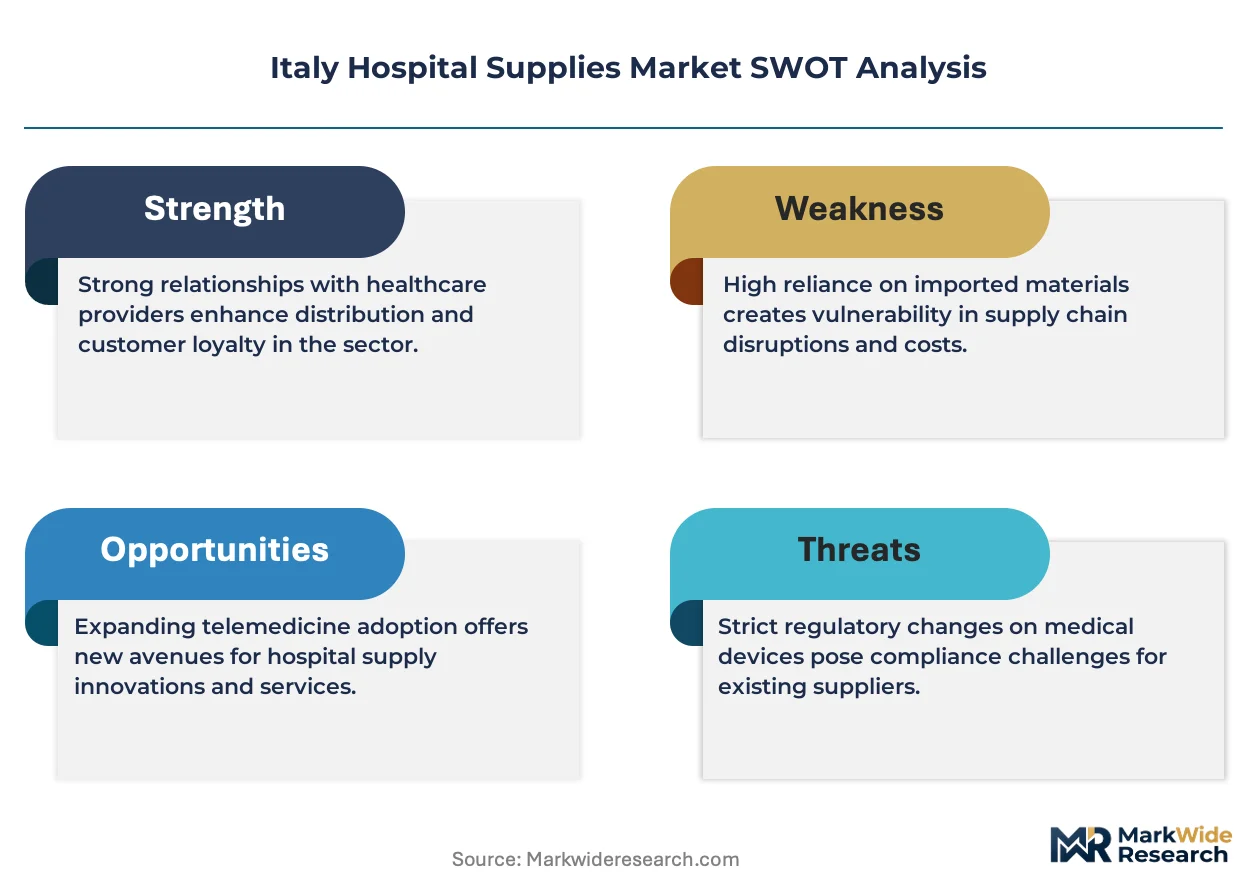
- Polymer and medical-grade silicone input volatility:Raw material costs for catheters, tubing, and infusion sets fluctuate with petrochemical feedstock markets, compressing margins for domestic sterilization equipment manufacturers dependent on imported elastomers.
- Single-source sterilization service concentration:Central Italy's public hospital consortia rely on a limited base of certified gamma and ethylene oxide sterilization providers, creating supply vulnerability when facilities undergo maintenance or capacity constraints.
- AIFA reimbursement lag:Italy's Medicines Agency pricing revision cycles trail device innovation by 18-24 months, delaying market access for novel disposable supplies with enhanced barrier properties or integrated infection control features.
Strategic Opportunities
- Underpenetrated central-southern rehabilitation centers:Abruzzo, Molise, and Basilicata maintain lower dialysis and wound care supply penetration rates than northern counterparts, offering whitespace for distributors with logistics networks capable of serving fragmented rural hospital clusters.
- Home care transition tailwinds:Italy's National Health Service chronic disease management protocols are shifting stable patients from inpatient to home settings, creating demand for portable patient monitors and disposable supply kits configured for non-institutional use.
- Green public procurement mandates:Regional health authorities in Emilia-Romagna and Tuscany are embedding environmental criteria into tender specifications, rewarding suppliers with certified biodegradable packaging and reduced-carbon sterilization processes.
Industry Challenges
- Biomedical engineering talent scarcity:Italian universities produce insufficient specialists in medical device cybersecurity and networked telemetry integration, forcing hospitals to rely on vendor-provided technical support for multi-parameter system upgrades.
- Legacy warehouse management system incompatibility:Regional procurement consortia operate on heterogeneous ERP platforms that resist seamless integration with supplier inventory APIs, generating stockout risks and manual reconciliation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Hospital Supplies Market |
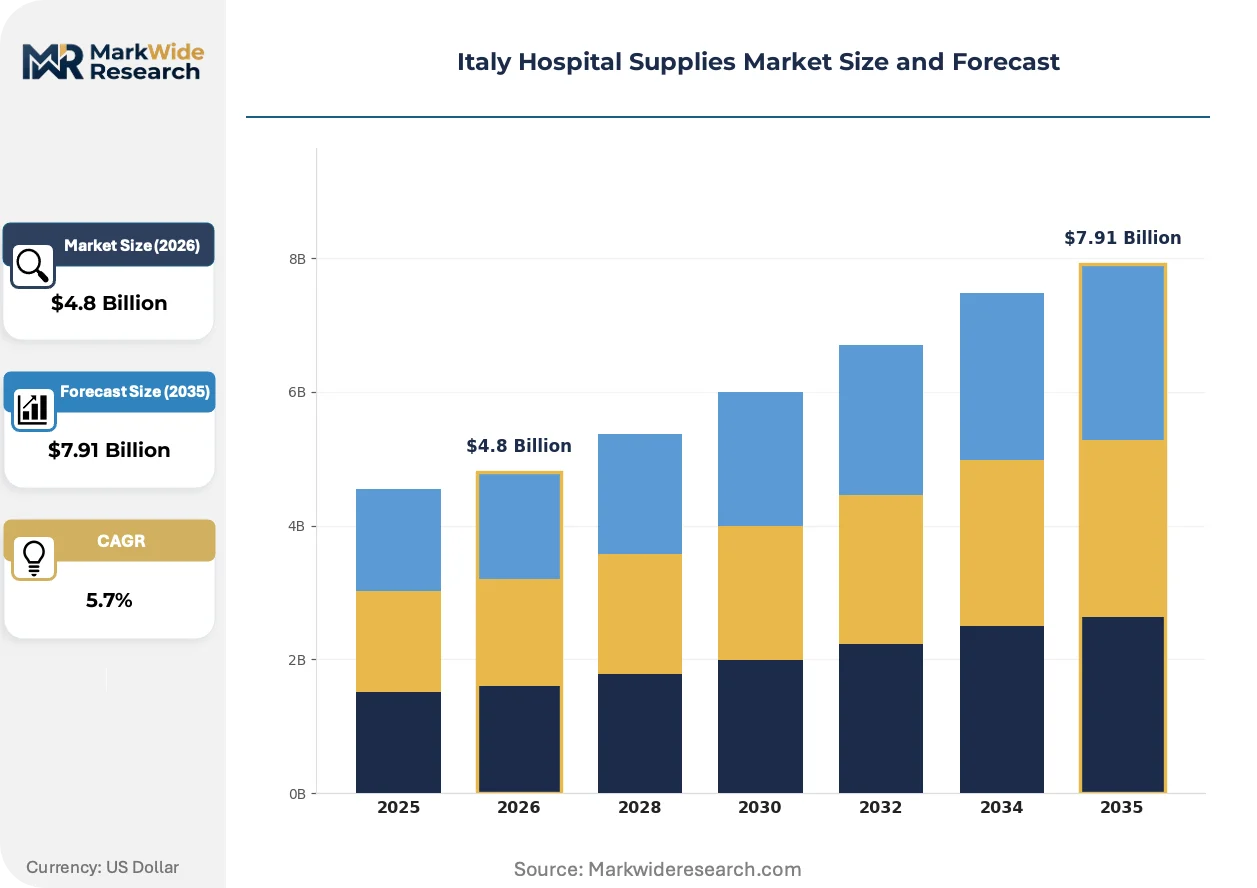
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Supplies, Surgical Instruments, Diagnostic Equipment, Patient Monitors End User: Public Hospitals, Private Clinics, Rehabilitation Centers, Emergency Services Application: Inpatient Care, Outpatient Services, Surgical Procedures, Emergency Response Distribution Channel: Direct Sales, Wholesalers, Online Retail, Medical Distributors |
| Companies Covered | GE Healthcare, Baxter International, Invacare Corporation, DE LAMA S.P.A., Althena Medical, Medtronic Italia S.p.A., Johnson & Johnson Medical S.p.A., Cardinal Health, B. Braun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Hospital Supplies Market Shifts & Advancements
Digital integration and regulatory stringency are converging to transform how Italian hospitals source, deploy, and manage clinical supplies. Three distinct vectors are restructuring competitive positioning across the value chain.
Networked telemetry architecture is unifying previously siloed patient monitoring functions into single-platform ecosystems. Lombardy's largest public hospital networks are deploying wireless-enabled multi-parameter systems that stream real-time data to centralized nursing stations and remote clinician dashboards. This convergence is compressing the addressable market for standalone monitoring devices while expanding service contract revenue pools for integrated platform vendors.
Italy's Ministry of Health has tightened sterilization validation protocols under Istituto Superiore di Sanità biocompatibility standards, requiring ethylene oxide residual testing documentation for every imported disposable lot. Domestic manufacturers with in-house sterilization capabilities are absorbing compliance costs through process automation, while smaller importers face working capital strain from extended batch release timelines. Central Italy's hospital consortia are responding by consolidating supplier panels to favor vertically integrated domestic producers.
Regional health authorities are consolidating purchasing decisions through centralized consortia that displace hospital-level procurement autonomy. Veneto's Azienda Zero and Lazio's Roma Capitale health trust have migrated to framework agreements with pre-qualified vendor pools, replacing transactional spot-buying with multi-year supply contracts tied to volume commitments. This concentration is most visible in disposable surgical supplies, where three consortia now control procurement for over sixty percent of acute care beds in their respective regions.
Italy Hospital Supplies Market Segmentation
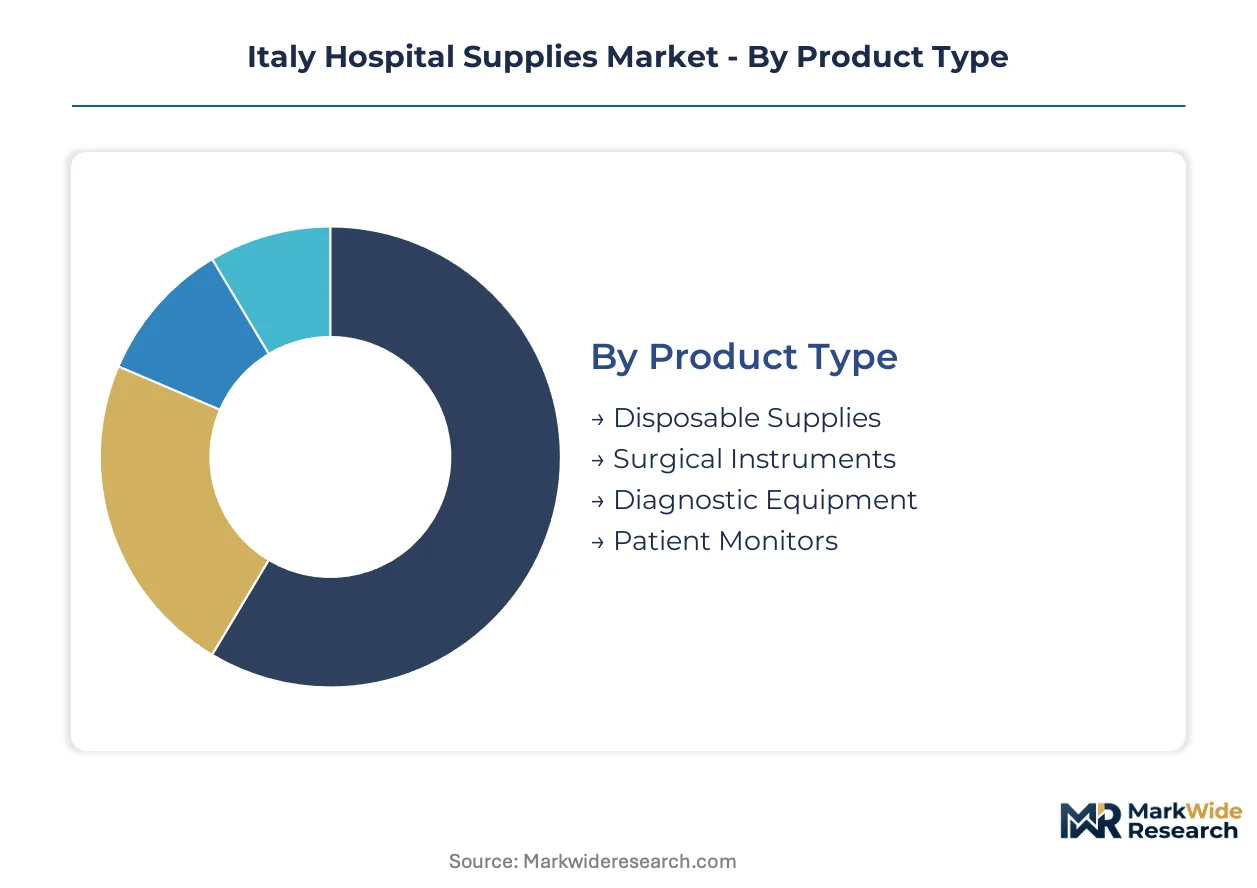
Hospital supplies procurement in Italy follows distinct decision hierarchies across product categories, end-user institutions, and care settings. Understanding these segmentation boundaries clarifies where pricing power concentrates and which channels capture margin.
Product Type:
Procurement committees weight infection control compliance against total cost of ownership when selecting across disposable and durable categories.
- Disposable Supplies:Single-use items including sterile gauze, catheters, surgical drapes, and procedure kits manufactured under ISO 13485 protocols. Lombardy's public hospital networks drive the highest procurement volumes through centralized regional consortia, with demand amplified by mandatory single-use protocols under National Health Service infection guidelines.
- Patient Monitors:Multi-parameter bedside systems and wireless telemetry platforms integrating cardiac, respiratory, and oxygen saturation measurement. Northern Italy's hospital networks are replacing aging units with networked architectures capable of streaming data to centralized nursing stations, creating concentrated demand for vendors with integrated platform capabilities.
- Surgical Instruments:Reusable and single-use instruments for operative procedures across general, orthopedic, and cardiovascular specialties.
- Diagnostic Equipment:Imaging and laboratory systems subject to regional health technology assessment replacement cycles.
Volume sits with Disposable Supplies; growth tilts toward Patient Monitors.
End User:
Budget authority and reimbursement pathways diverge sharply between publicly funded networks and private operators.
- Public Hospitals:Regional health trusts operating under National Health Service funding protocols, with procurement centralized through consortia in Lombardy, Lazio, and Veneto. These institutions command the largest addressable spend but impose stringent ISO 13485 compliance tiers and multi-source vendor qualification requirements.
- Private Clinics:Independent surgical and diagnostic facilities serving elective procedures outside public waiting lists. Facilities in Milan and Rome's metropolitan corridors pursue faster procurement cycles and premium-tier product specifications, accepting price premiums for supply security and vendor technical support.
- Rehabilitation Centers:Post-acute and long-term care facilities concentrated in northern Italy's aging population corridors.
- Emergency Services:Pre-hospital care providers with specialized requirements for portable monitoring and rapid-deployment supply kits.
Procurement volume concentrates in Public Hospitals; margin expansion favors Private Clinics.
Application:
Clinical setting determines product specification intensity and replenishment frequency.
- Surgical Procedures:Operating room consumption of sterile drapes, procedure kits, and specialized instruments. Lombardy's hospital network performs the highest density of elective surgeries nationally, sustaining predictable demand cycles for disposable surgical supplies through volume-based procurement frameworks.
- Inpatient Care:Multi-day hospitalization requiring continuous monitoring, wound care, and infusion therapy supplies. Veneto's Azienda Zero consortium has consolidated purchasing for acute care beds across the region, favoring vendors capable of integrated supply contracts spanning multiple product categories.
- Outpatient Services:Same-day diagnostic and therapeutic procedures with compressed supply turnaround requirements.
- Emergency Response:Trauma and acute intervention settings demanding immediate availability of critical supplies.
Surgical Procedures anchor procurement volume; Inpatient Care is climbing the fastest as telemetry platform upgrades accelerate.
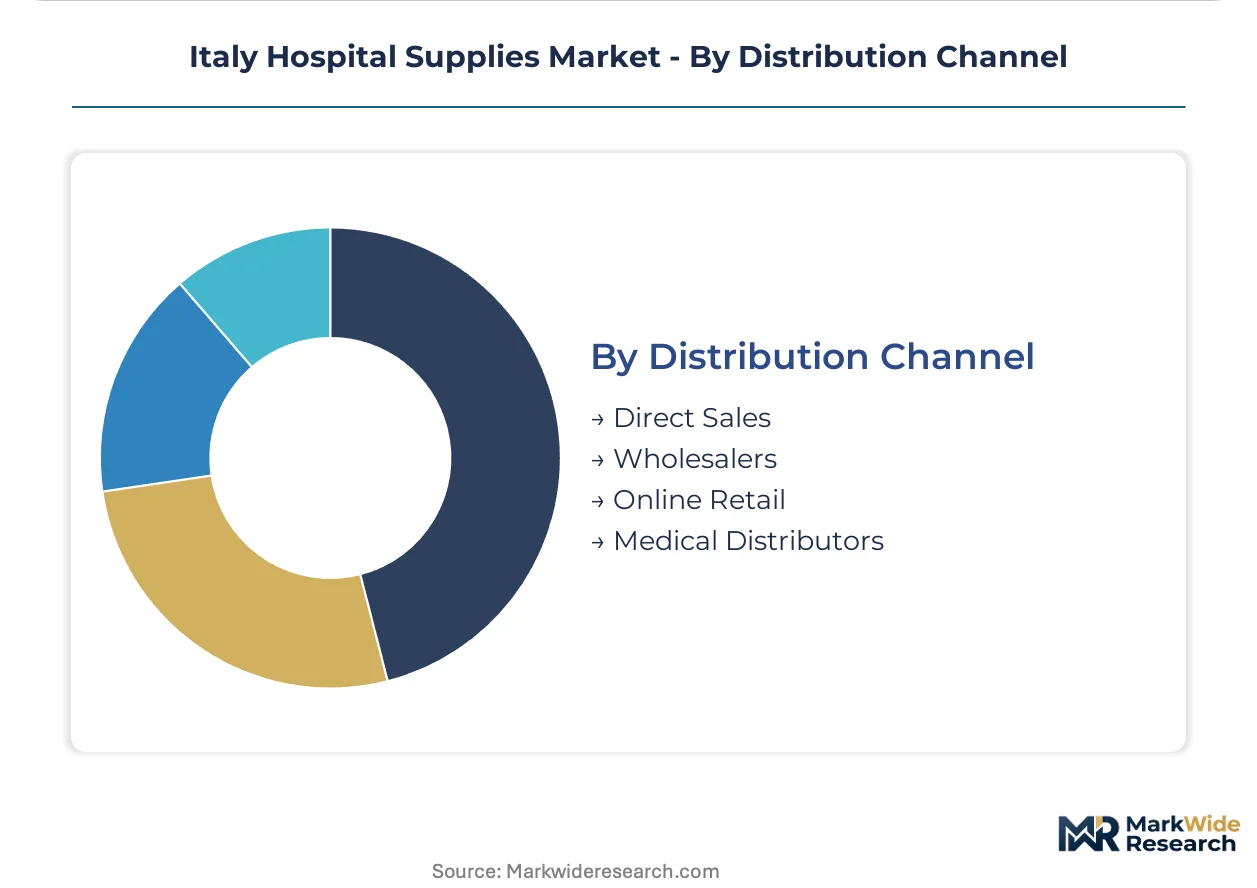
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic fragmentation of end users.
- Medical Distributors:Specialized logistics operators maintaining regional warehouses and field-based technical support teams. Central Italy's public hospital consortia rely on these intermediaries to bridge fragmented rural hospital clusters, with distributors absorbing inventory risk and sterilization validation documentation burdens.
- Direct Sales:Manufacturer-to-institution relationships for high-value capital equipment and multi-year service contracts. Patient monitor vendors deploy direct sales teams to Lombardy and Lazio health trusts, bundling hardware, installation, and remote technical support under single-platform agreements.
- Wholesalers:General medical product aggregators serving smaller facilities with standardized disposable supplies.
- Online Retail:Digital procurement platforms gaining traction among private clinics for non-critical supply categories.
Medical Distributors capture the broadest reach; Direct Sales is gaining share fastest as telemetry platform complexity demands vendor-integrated service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer and medical-grade silicone feedstock flows through northern Italy's industrial corridor anchor procurement concentration for the hospital supplies sector. Regional health authorities in Lombardy, Veneto, and Emilia-Romagna command consolidated purchasing power through centralized consortia. Sub-regional differentiation reflects surgical volume density, aging demographics, and infrastructure maturity across the peninsula.
Lombardy
Milan's metropolitan hospital network performs the highest density of elective surgeries nationally, driving sustained consumption of disposable drapes and procedure kits. The region's Azienda Zero health trust mandates ISO 13485 compliance tiers for all vendor qualification. Bergamo and Brescia host sterilization equipment clusters serving cross-border supply chains into Switzerland.
Veneto
Padua and Verona anchor post-acute rehabilitation centers with expanding dialysis and wound care requirements. Veneto's regional procurement consortium has consolidated purchasing for acute care beds under framework agreements with pre-qualified vendor pools. The Istituto Superiore di Sanità biocompatibility standards shape sterilization validation protocols for imported disposable lots.
Lazio
Rome's public hospital trusts are retrofitting aging multi-parameter monitoring systems with wireless telemetry infrastructure. The Ministry of Health reimbursement protocols under the National Health Service govern medical device classification and pricing eligibility. Frosinone and Latina maintain lower supply penetration rates, creating whitespace for distributors with rural logistics capabilities.
Emilia-Romagna
Bologna's university hospital network drives demand for networked patient monitoring platforms integrating cardiac and respiratory measurement. Regional health authorities have embedded environmental criteria into tender specifications, rewarding suppliers with certified biodegradable packaging. Modena and Parma host medical device distributors bridging fragmented rural hospital clusters.
Tuscany
Florence and Pisa concentrate private clinic operators serving elective procedures outside public waiting lists. The region's green public procurement mandates favor reduced-carbon sterilization processes and sustainable packaging formats. Siena's aging population corridors sustain long-term care facility demand for portable patient monitors and home care supply kits.
Italy Hospital Supplies Market Competitive Landscape
Global majors compete with regional champions across procurement consolidation and telemetry platform integration. Baxter International and GE Healthcare leverage scale advantages in infusion therapy and imaging systems, while DE LAMA S.P.A. and Althena Medical anchor domestic sterilization and distribution networks. Three strategic archetypes dominate: integrated platform vendors bundling hardware and service contracts, specialized sterilization equipment manufacturers with in-house validation capabilities, and regional distributors absorbing inventory risk for fragmented rural clusters. Competitive moves center on multi-year framework agreements with regional health consortia and backward integration into sterilization services.
Among Italy-based specialists, DE LAMA S.P.A. occupies a position exemplifying vertically integrated sterilization equipment production, while Althena Medical represents the regional distributor archetype bridging public hospital consortia with fragmented supply chains. Baxter International and B. Braun sit within the global diversified portfolio tier, competing through extensive product ranges across dialysis and surgical categories. These named entities anchor industry-level patterns without ascribing specific strategic actions or market positions beyond archetype representation.
| Leading Market Players |
|---|
| GE Healthcare |
| Baxter International |
| Invacare Corporation |
| DE LAMA S.P.A. |
| Althena Medical |
| Medtronic Italia S.p.A. |
| Johnson & Johnson Medical S.p.A. |
| Cardinal Health |
| B. Braun |
| Others |
Supply & Pricing Matrix
Family-owned sterilization equipment specialists across central Italy anchor supply discipline through multi-generational capital structures that resist short-term margin erosion. Their captive ownership models sustain pricing power against polymer feedstock volatility while regional health consortia absorb cost pass-throughs through framework contract renegotiations.
Pricing Analysis
Service bundling separates integrated platform vendors offering multi-year telemetry maintenance contracts from unbundled disposable suppliers competing on per-unit tenders. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13485 certification tiers and sterilization validation depth. Cost compression in economy-grade drapes and gauze is intensifying because AIFA reimbursement cycles trail raw material inflation by 18-24 months. Public hospital consortia exhibit highest price sensitivity, while Milan's private clinics accept premiums for vendor-integrated technical support.
Supply Chain Analysis
Freight costs for medical-grade silicone and polymer feedstocks from Germany, Belgium, and the Netherlands compress margins for domestic sterilization equipment manufacturers without captive logistics networks. Italy's hospital supplies sector draws from petrochemical corridors in northern Europe and specialty elastomer producers in Switzerland. Single-source sterilization service concentration in central Italy creates supply vulnerability when gamma or ethylene oxide facilities undergo maintenance. Distribution runs through regional medical distributors bridging fragmented rural hospital clusters in Abruzzo and Molise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's hospital supplies market operates as a supply-constrained environment where sterilization capacity bottlenecks prop pricing power for validated domestic producers. AIFA's extended reimbursement revision timelines prevent rapid cost pass-through to public buyers, entrenching margin pressure on importers without in-house sterilization.
For Market Incumbents: Hedge against polymer feedstock volatility through backward integration into sterilization services or long-term elastomer supply agreements with German and Swiss producers. Consolidate supplier panels with Lombardy and Veneto regional consortia before framework agreement renewal cycles, as these health trusts are narrowing vendor pools to ISO 13485 Tier-2 qualified producers with validated batch release capabilities. For New Entrants and Emerging Players: Regional distributors with rural logistics networks represent the most viable channel partner type for penetrating underpenetrated rehabilitation centers in Basilicata and Molise. Target home care transition demand for portable patient monitors and disposable supply kits as the National Health Service shifts stable chronic patients from inpatient to non-institutional settings. Pursue green public procurement qualification in Emilia-Romagna and Tuscany by certifying biodegradable packaging and reduced-carbon sterilization processes. For Investors and Strategic Acquirers: AIFA's publication of revised medical device reimbursement protocols is the leading indicator that pricing power will shift toward vertically integrated domestic producers with in-house sterilization and validated ethylene oxide residual testing. The 5-10 year viability window favors acquisition targets combining sterilization equipment manufacturing with regional distribution networks serving fragmented central-southern hospital clusters. Monitor Istituto Superiore di Sanità biocompatibility standard updates as signals for compliance cost escalation that will strain smaller importers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class IIa and IIb recertification deadlines force device replacement cycles across Lombardy hospital networks. |
| Hospital System Partnership | Multi-year framework agreements with Veneto's Azienda Zero consolidate purchasing power for integrated platform vendors. |
| Backward Integration | In-house sterilization capabilities absorb Istituto Superiore di Sanità compliance costs while extending batch release timelines. |
| Software Companion Development | Networked telemetry platforms demand vendor-provided cybersecurity and remote monitoring integration for multi-parameter systems. |
| Reimbursement Strategy | AIFA pricing revision alignment determines market access timing for novel disposables with enhanced barrier properties. |
Research Methodology
Document review covered hospital procurement databases, GPO contracts, and AIFA reimbursement filings, complemented by interviews with biomedical engineers, hospital purchasing committee members, and regional health trust procurement directors. Secondary validation drew from Istituto Superiore di Sanità sterilization standards, EU MDR transitional provision documents, and customs records tracking polymer and medical-grade silicone imports. Bottom-up demand modeling across product categories triangulated with top-down expenditure flows from National Health Service regional budgets.
Segment-level outputs across the projection horizon reflect discrete modeling of disposable supplies, patient monitors, and sterilization equipment categories by ISO 13485 compliance tier, end-user institution type, and regional procurement consortium. CAGRs were derived from surgical procedure volume trajectories, telemetry platform replacement cycles, and home care transition patient flows. Forecast inputs incorporated AIFA pricing revision lag assumptions and green public procurement mandate adoption curves in Emilia-Romagna and Tuscany.
Several conditions sit outside the modeled scope, including unannounced EU MDR enforcement discretion changes, sovereign debt stress impacts on regional health budgets, and breakthrough sterilization technology disruptions. Forecasts reflect documented assumptions about reimbursement timeline stability and polymer feedstock price mean-reversion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Pharmacy Bags Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Auto-Disable Syringes Market
Medical Supplies
Blood Collection Market
Medical Supplies
Polymer Exam Gloves Market
Medical Supplies
Pressure Redistribution Pads Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
South America Syringe Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Empty IV Bags Market
Medical Supplies
Amniotic Membrane Market
Medical Supplies
Lavage Kits Market