
 Blood Collection Tubes for Liquid Biopsy Market | 2026-2036
Blood Collection Tubes for Liquid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Collection Tubes for Liquid Biopsy Market Analysis
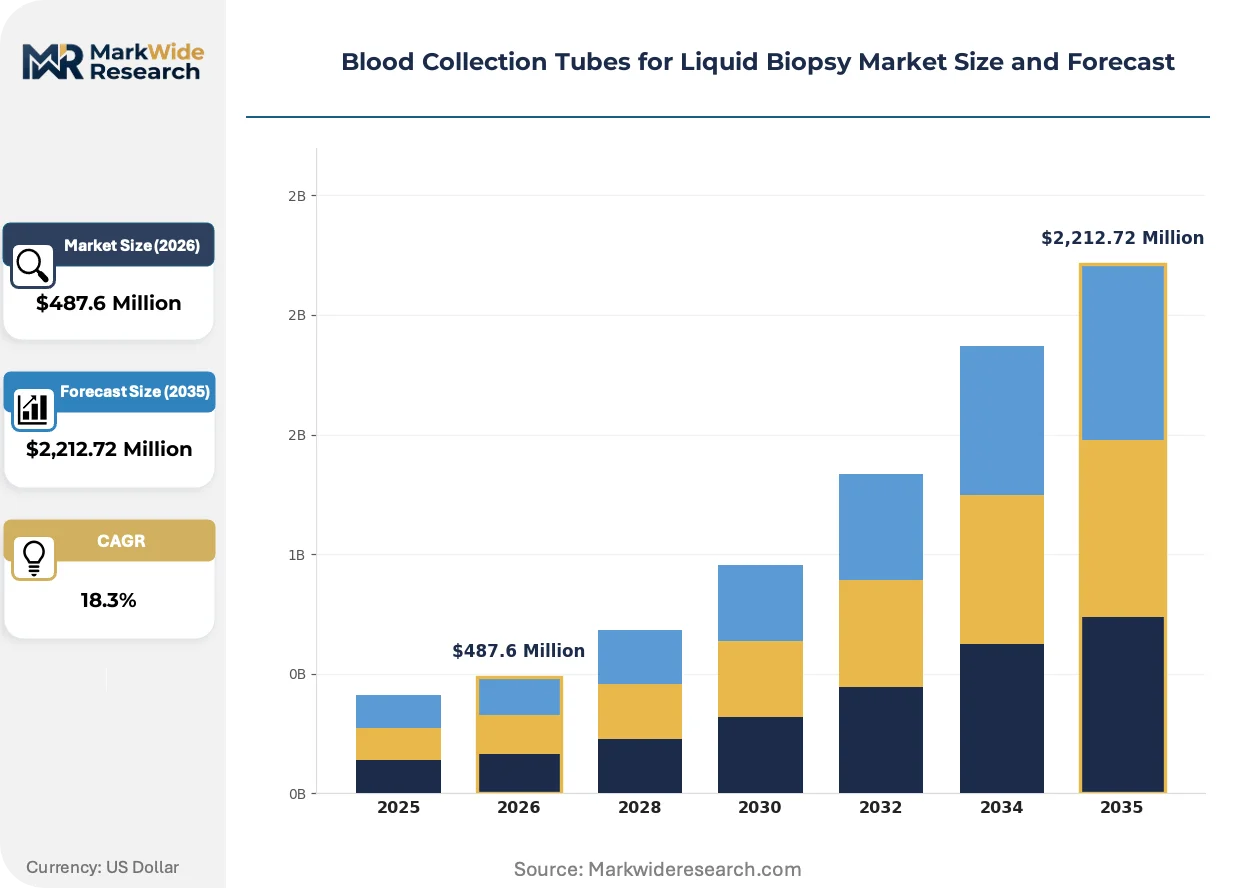
Oncology diagnostics is recalibrating the demand profile for blood collection tubes as hospitals shift from tissue-based biopsies toward serial liquid biopsy monitoring. Streck Inc. anchors the stabilizer tube segment with proprietary cell-free DNA preservation chemistry that extends sample integrity during transport. QIAGEN NV leverages its molecular diagnostics ecosystem to bundle collection tubes with downstream extraction workflows. Greiner Bio-One International GmbH competes through manufacturing scale across European and North American distribution networks.
Blood collection tubes for liquid biopsy are specialized vacuum or non-vacuum vessels engineered with stabilizing additives that prevent cellular lysis and preserve nucleic acid integrity at ambient temperatures for multi-day shipping intervals. Their primary commercial purpose is to enable reliable isolation of circulating tumor DNA, circulating tumor cells, or exosomes from peripheral blood draws for subsequent genomic analysis. EDTA tubes retain dominance in routine clinical workflows due to established compatibility with automated hematology platforms, while stabilizer-additive tubes represent the fastest-expanding margin pool as laboratories seek to eliminate cold-chain dependencies. The additive-used dimension stratifies sharply: gel separator formulations serve high-throughput reference labs, whereas preservation agent tubes command premium positioning in decentralized collection settings.
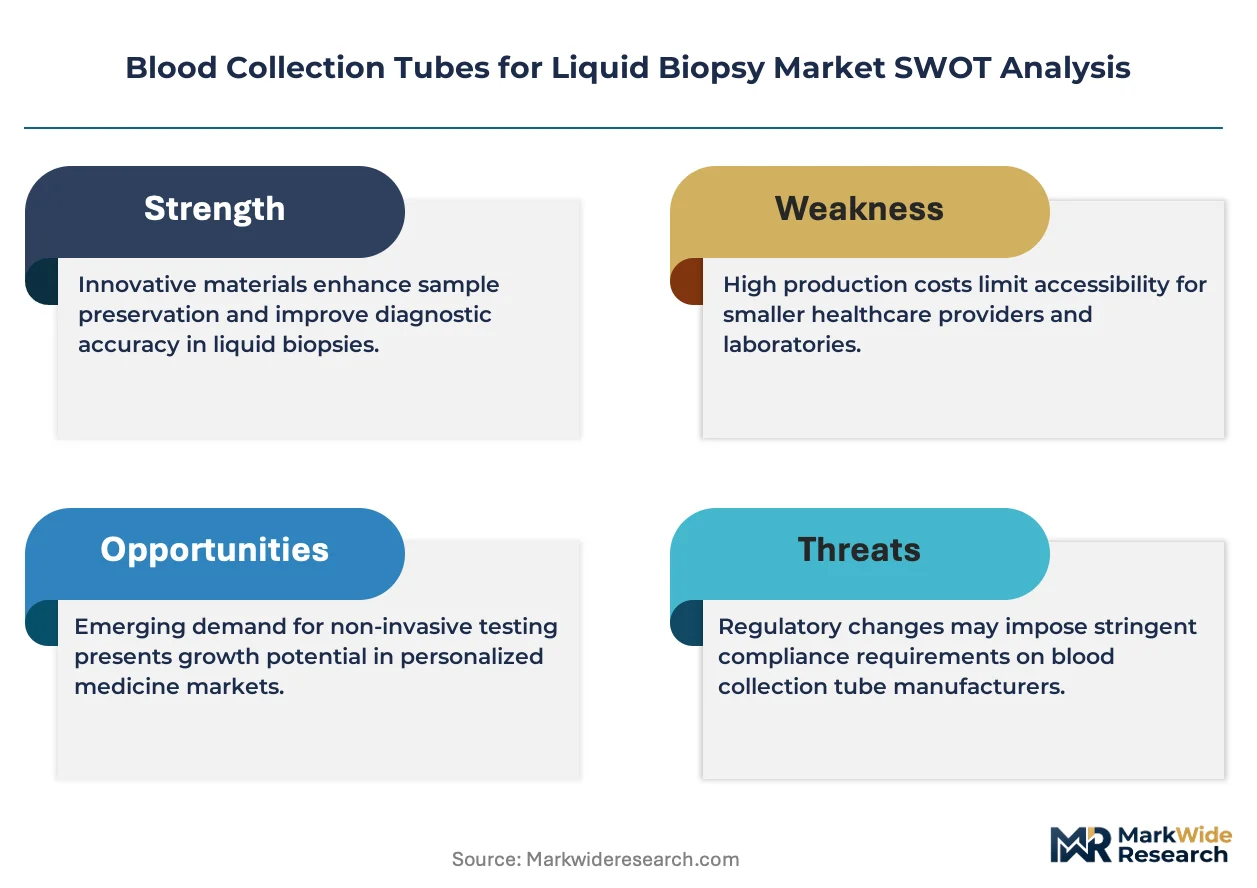
The FDA regulates these devices as Class I or Class II medical devices depending on claimed indications, while the EMA's In Vitro Diagnostic Medical Devices Regulation imposes stricter performance documentation requirements for CE-marked products entering European laboratories. ISO 10993 biocompatibility standards and CLSI guidelines for specimen handling collectively shape product development roadmaps and procurement qualification criteria. Stakeholders must monitor how evolving reimbursement pathways for companion diagnostics influence tube specification requirements across health system purchasing contracts.
Market Dynamics
The transition from tissue-based to serial liquid biopsy monitoring is restructuring procurement patterns across hospital systems, as pathology departments consolidate vendor relationships around integrated collection-to-analysis workflows rather than standalone tube purchases.
Growth Catalysts
- Companion diagnostic reimbursement expansion:Medicare coverage determinations for circulating tumor DNA tests are pulling stabilizer tube specifications into health system purchasing contracts. United States reference laboratories are scaling liquid biopsy programs in response.
- EMA MDR implementation:The European Union's stricter performance documentation requirements for CE-marked devices are filtering out low-quality suppliers and concentrating procurement among validated manufacturers.
- Cold-chain elimination:Ambient-temperature nucleic acid preservation chemistry is enabling decentralized sample collection at community oncology clinics and retail phlebotomy sites.
Market Restraints
- Specialized polymer input concentration:High-purity polypropylene and proprietary stabilizer formulations depend on a limited supplier base concentrated in Germany and Switzerland, exposing tube manufacturers to resin allocation volatility.
- Technical limitation in CTC preservation:Current additive chemistries maintain cell-free DNA integrity more reliably than circulating tumor cell viability, constraining applications requiring intact cellular material for single-cell analysis.
- FDA Class II device pathway friction:The agency's evolving guidance on in vitro diagnostic collection devices creates validation timeline uncertainty for manufacturers seeking liquid biopsy-specific indications.
Strategic Opportunities
- Decentralized collection network buildout:Community oncology practices in the United States represent underpenetrated endpoints for direct-to-laboratory shipping models that bypass hospital-based phlebotomy.
- Exosome isolation workflow convergence:The integration of size-exclusion chromatography with collection tube stabilizers is opening specimen types beyond circulating tumor DNA for multi-analyte liquid biopsy panels.
- ISO 10993 biocompatibility certification:Laboratories are prioritizing suppliers with complete extractables and leachables documentation, creating differentiation for manufacturers with pre-validated regulatory packages.
Industry Challenges
- Multi-site protocol harmonization:Health systems acquiring community oncology practices face integration complexity when consolidating disparate tube specifications, transport protocols, and vendor contracts into unified laboratory information management systems.
- Specialized field application scientist staffing:The technical selling process requires personnel who understand both pre-analytical variables in specimen handling and downstream nucleic acid extraction chemistry, a skill combination that remains scarce in diagnostic sales organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Collection Tubes for Liquid Biopsy Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,212.72 Million |
| CAGR (2026 – 2036) | 18.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tube Type: EDTA, Serum, Plasma, Heparin Additive Used: Gel Separator, Anticoagulant, Stabilizer, Preservation Agent Application Area: Oncology, Infectious Diseases, Cardiovascular, Genetic Testing End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks |
| Companies Covered | Streck Inc., QIAGEN NV, F. Hoffmann-La Roche Ltd, Biocept Inc., PreAnalytiX GmbH, Norgen Biotek Corp, Greiner Bio-One International GmbH, Becton Dickinson and Company, Exact Sciences Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Collection Tubes for Liquid Biopsy Market Emerging Trajectories
Automation is penetrating pre-analytical workflows that previously relied on manual specimen handling, while regulatory frameworks on both sides of the Atlantic are hardening documentation requirements for devices claiming nucleic acid preservation capabilities.
Integrated tube-to-extraction platforms are automating the transfer of stabilized blood specimens directly into automated nucleic acid purification instruments without manual decapping or aliquoting steps. High-throughput reference laboratories in the United States are deploying these closed systems to reduce pre-analytical variables and compress turnaround times for time-sensitive oncology decisions. This automation is compressing the competitive advantage of standalone tube manufacturers who lack downstream workflow integration.
REACH compliance deadlines for chemical substances used in stabilizer formulations are forcing European manufacturers to reformulate proprietary preservatives or secure alternative supply chains for regulated compounds. The European Chemicals Agency's substance evaluation process is extending product development timelines by twelve to eighteen months for tubes containing novel preservative chemistries. Small and mid-sized manufacturers without dedicated regulatory affairs teams are outsourcing CE-marking documentation to specialized consultants.
Consolidated purchasing by multi-hospital health systems is displacing the traditional distributor-centric model for blood collection tubes. Large United States laboratory networks are negotiating direct manufacturer contracts that bundle stabilizer tubes with molecular diagnostics reagents and service agreements. This concentration is most visible in the precision medicine initiatives of major academic medical centers, where procurement committees now mandate single-source vendor qualification across the entire specimen-to-report workflow.
Blood Collection Tubes for Liquid Biopsy Market Segmentation
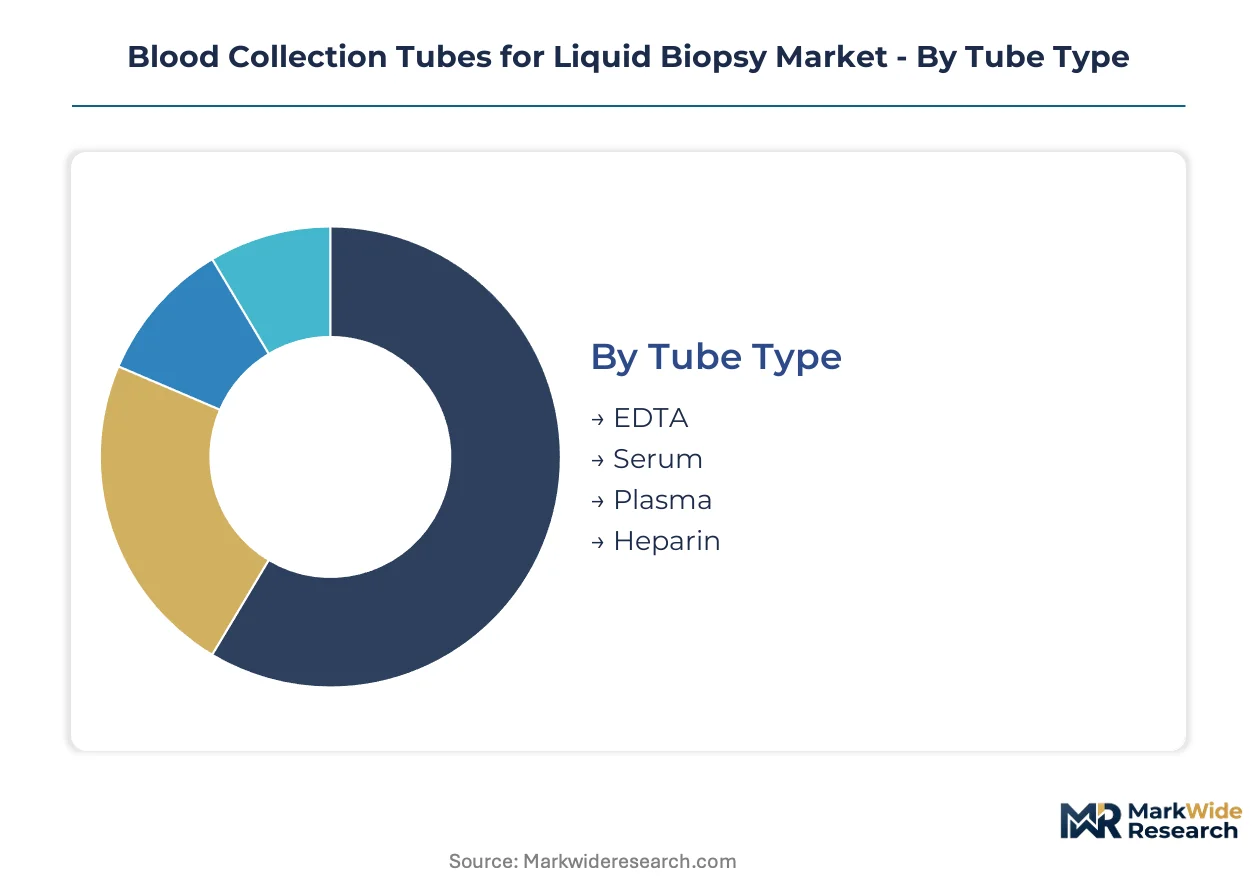
Liquid biopsy workflows demand precise tube specifications that vary sharply by analyte target and pre-analytical stability requirements. Procurement committees now evaluate segments through the lens of downstream assay compatibility rather than standalone vessel economics.
Tube Type:
Upgrade cycles in liquid biopsy programs are displacing legacy hematology tubes as laboratories validate purpose-built vessels for nucleic acid preservation.
- EDTA:Potassium ethylenediaminetetraacetic acid formulations prevent coagulation by chelating calcium ions, preserving cell morphology for circulating tumor cell workflows. United States reference laboratories specify these tubes for high-throughput automated platforms where compatibility with existing infrastructure outweighs cold-chain requirements.
- Plasma:Citrate and EDTA plasma tubes enable cell-free DNA isolation through differential centrifugation protocols. Community oncology clinics in decentralized collection networks favor plasma tubes for ambient-temperature shipping models that eliminate dry-ice logistics.
- Serum:Clot-activator tubes yield serum for protein biomarker detection in companion diagnostic panels.
- Heparin:Lithium heparin formulations suit research workflows where polymerase chain reaction inhibition is manageable.
Volume placements concentrate in EDTA; the faster expansion belongs to Plasma.
Additive Used:
Cost tiers separate commodity anticoagulants from premium stabilizer chemistries that command per-tube price multiples.
- Stabilizer:Proprietary cell-free DNA preservation agents maintain nucleic acid integrity at ambient temperatures for 14-day shipping intervals. Precision medicine initiatives at United States academic medical centers specify stabilizer tubes for serial monitoring protocols where sample degradation risks invalidate clinical decisions.
- Preservation Agent:Formaldehyde-releasing and non-crosslinking chemistries protect circulating tumor cell viability for single-cell genomic analysis. European laboratories under EMA MDR compliance prioritize preservation agents with documented extractables and leachables profiles.
- Gel Separator:Thixotropic gel formulations enable rapid plasma separation in high-throughput reference labs.
- Anticoagulant:EDTA, citrate, and heparin formulations serve routine clinical chemistry workflows.
Anticoagulant claims the highest shipment volumes; Stabilizer generates the steepest margin expansion.
Application Area:
Customer maturity varies sharply across therapeutic areas, with oncology leading protocol standardization.
- Oncology:Circulating tumor DNA and circulating tumor cell isolation drive specification requirements for stabilizer chemistry and fill volume precision. Medicare coverage determinations for liquid biopsy tests in non-small cell lung cancer and colorectal malignancies are pulling tube procurement into United States health system purchasing contracts.
- Genetic Testing:Non-invasive prenatal testing and carrier screening applications demand stringent cell-free DNA yield consistency. Direct-to-consumer genetic testing laboratories specify tubes with validated performance across extended ambient-temperature holds.
- Infectious Diseases:Pathogen cell-free DNA detection for sepsis and transplant monitoring represents emerging volume.
- Cardiovascular:Circulating nucleic acid biomarkers for heart failure stratification remain investigational.
Oncology commands the dominant procurement volume; Genetic Testing exhibits the most rapid indication expansion.
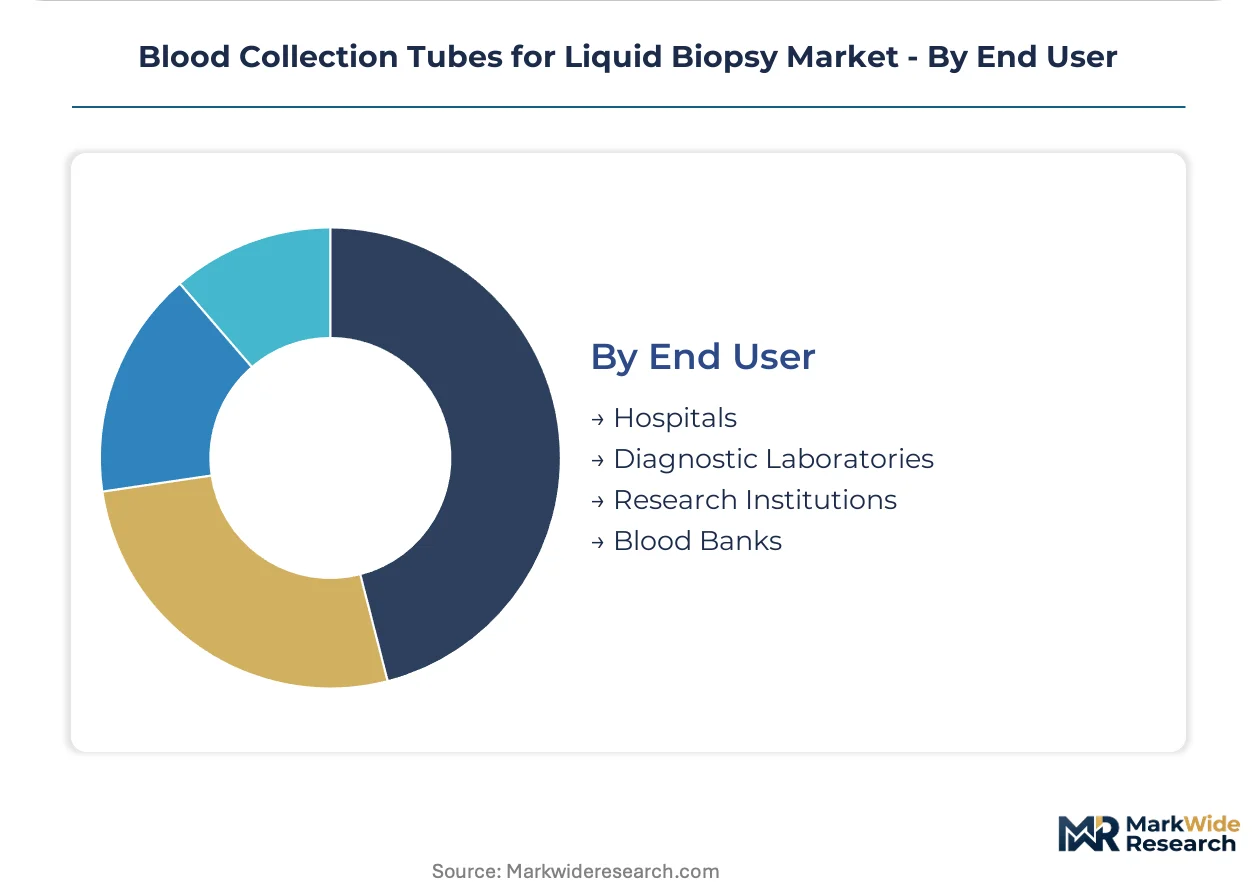
End User:
Consolidation patterns reshape purchasing power across customer categories.
- Diagnostic Laboratories:National reference networks negotiate direct manufacturer contracts bundling tubes with nucleic acid extraction reagents. Quest Diagnostics and LabCorp-scale operators in the United States mandate single-source qualification across pre-analytical and analytical workflows.
- Hospitals:Pathology departments at academic medical centers validate tube specifications for in-house liquid biopsy programs. Health system consolidation is centralizing procurement decisions for acquired community oncology practices.
- Research Institutions:Academic laboratories prioritize lot-to-lot consistency for reproducible biomarker discovery.
- Blood Banks:Transfusion medicine applications for pathogen reduction monitoring represent niche volume.
Diagnostic Laboratories anchor procurement scale; Hospitals show the fastest program buildout velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and Boston's Route 128 corridor concentrate liquid biopsy innovation through state-level tax credits for precision medicine infrastructure. These zones attract tube manufacturers seeking proximity to reference laboratory customers and FDA pre-submission pathways.
United States
Medicare coverage determinations for circulating tumor DNA tests in non-small cell lung cancer drive stabilizer tube procurement into health system contracts. The FDA's evolving Class II device guidance creates validation timeline uncertainty for manufacturers seeking liquid biopsy-specific indications. Boston's biotech cluster anchors precision medicine initiatives where academic medical centers mandate single-source vendor qualification across specimen-to-report workflows.
Germany
High-purity polypropylene resin suppliers concentrated in Baden-Württemberg expose tube manufacturers to allocation volatility during polymer supply shocks. REACH compliance deadlines for stabilizer chemistries force reformulation of proprietary preservatives or alternative supply chain sourcing. The EMA's MDR implementation filters low-quality suppliers and concentrates procurement among validated manufacturers with documented extractables profiles.
Switzerland
Proprietary stabilizer formulation expertise clusters around Basel's pharmaceutical corridor where chemical suppliers serve diagnostics manufacturers. Swissmedic maintains alignment with EMA MDR requirements while offering streamlined pathways for CE-marked devices entering European laboratories. Zurich's precision medicine networks specify tubes with validated ambient-temperature performance for decentralized oncology monitoring.
China
NMPA regulatory harmonization with international standards accelerates local manufacturer qualification for export markets. The country's dual carbon goals pressure resin suppliers to decarbonize polypropylene production for medical-grade applications. Shanghai's diagnostics industrial park hosts integrated collection-to-extraction platform developers targeting high-throughput reference laboratory automation.
United Kingdom
NHS England's consolidation of pathology services into regional hubs centralizes tube specification decisions for acquired community oncology practices. MHRA post-Brexit regulatory divergence from EMA creates parallel validation requirements for devices claiming nucleic acid preservation capabilities. London's cancer research institutes prioritize suppliers with ISO 10993 biocompatibility certification for multi-site protocol harmonization.
Blood Collection Tubes for Liquid Biopsy Market Vendor Landscape
Top-tier vendors anchor the stabilizer chemistry segment, while mid-scale manufacturers compete on manufacturing scale and regional distribution networks. The market structure reflects concentration around proprietary preservation formulations versus commodity anticoagulant tubes. Three archetypes dominate: integrated molecular diagnostics ecosystems, specialized pre-analytical device developers, and diversified laboratory consumables manufacturers. Strategic moves center on bundling collection tubes with downstream extraction workflows and securing direct contracts with consolidated health system purchasing committees.
Among specialized pre-analytical developers, Streck Inc., QIAGEN NV, and Greiner Bio-One International GmbH occupy distinct competitive positions. Streck represents the proprietary chemistry archetype with cell-free DNA preservation specialization. QIAGEN exemplifies the integrated ecosystem model leveraging molecular diagnostics breadth. Greiner Bio-One anchors the manufacturing scale archetype across European and North American distribution networks. These three entities collectively illustrate the segmentation between chemistry innovation, workflow integration, and production capacity that defines competitive positioning in liquid biopsy specimen handling.
| Leading Market Players |
|---|
| Streck Inc. |
| QIAGEN NV |
| F. Hoffmann-La Roche Ltd |
| Biocept Inc. |
| PreAnalytiX GmbH |
| Norgen Biotek Corp |
| Greiner Bio-One International GmbH |
| Becton Dickinson and Company |
| Exact Sciences Corporation |
| Others |
Supply Flow & Price Mechanics
Consolidated reference laboratory networks in the United States anchor procurement scale and compress pricing power toward contract-based bundling with nucleic acid extraction reagents. This buyer concentration forces standalone tube manufacturers to absorb resin volatility or cede position to integrated molecular diagnostics ecosystems.
Pricing Analysis
Short lead-time premiums for stabilizer tubes with validated ambient-temperature performance command price multiples over standard EDTA formulations. Three-tier pricing structure across premium stabilizer, standard plasma, and economy EDTA levels reflects certification grade and downstream workflow integration depth. Cost compression in the anticoagulant tier intensifies because commodity polypropylene feedstock faces allocation pressure from German and Swiss resin suppliers. Community oncology clinics show highest price sensitivity due to thin reimbursement margins, while academic medical centers prioritize performance consistency over per-unit economics.
Supply Chain Analysis
Dual-sourcing requirements for high-purity polypropylene resin mandate multi-supplier qualification across German Baden-Württemberg and Swiss Basel chemical corridors. Proprietary stabilizer formulations draw from specialty chemical suppliers concentrated in Switzerland, while tube manufacturing capacity clusters in Germany and the United States. Single-source vulnerability for medical-grade resin exposes manufacturers to polymer allocation shocks during supply disruptions. Distribution runs through direct manufacturer contracts with consolidated health system purchasing committees, displacing traditional distributor-centric models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood collection tube market sits in a technology-transition phase as ambient-temperature nucleic acid preservation chemistry displaces cold-chain-dependent legacy workflows. Stabilizer-additive tubes are replacing standard EDTA vessels in precision medicine protocols.
For Market Incumbents: Anticipate margin compression from integrated molecular diagnostics ecosystems bundling collection tubes with automated extraction platforms. Defensive consolidation around proprietary preservative chemistries and ISO 10993 biocompatibility certification investment will differentiate against commodity competitors. Backward integration into high-purity polypropylene resin sourcing reduces exposure to German and Swiss supplier allocation volatility.
For New Entrants and Emerging Players: Exosome isolation workflow convergence represents a technology-first wedge into underpenetrated multi-analyte liquid biopsy panels. White-space targets include decentralized community oncology collection networks in the United States and direct-to-laboratory shipping models bypassing hospital phlebotomy. A go-to-market angle anchored in REACH-compliant stabilizer reformulation addresses European EMA MDR documentation gaps left by incumbent suppliers.
For Investors and Strategic Acquirers: The window for entry favors specialized pre-analytical device developers with validated regulatory packages over diversified laboratory consumables manufacturers. Long-term viability hinges on single-source vendor qualification across specimen-to-report workflows at academic medical centers. The signal to watch is Medicare coverage determination expansion for circulating tumor DNA tests in additional oncology indications.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance filters low-quality suppliers and validates European market entry. |
| Hospital System Partnership | Direct contracts with Quest Diagnostics-scale networks bundle tubes with extraction reagents. |
| Backward Integration | In-house polypropylene resin sourcing reduces dependency on German and Swiss suppliers. |
| Reimbursement Strategy | Medicare coverage alignment for liquid biopsy tests pulls tube specifications into purchasing contracts. |
| Software Companion Development | Integrated tube-to-extraction platforms automate specimen transfer without manual decapping steps. |
Methodological Framework
Multi-period observation of FDA Class II device submission timelines and EMA MDR implementation progress anchored the trend analysis, supplemented by interviews with laboratory directors, hospital procurement managers, molecular diagnostics executives, and regulatory affairs specialists at stabilizer chemistry manufacturers. Secondary validation drew from FDA 510(k) filings, EMA CE-marking documentation, CMS Medicare coverage determination records, and ISO 10993 biocompatibility certification databases. Bottom-up shipment estimates by tube type and additive chemistry triangulated against top-down health system purchasing contract values.
Input-output matrices modeled demand drivers across oncology, genetic testing, infectious disease, and cardiovascular application areas, with segmentation by tube type, additive used, and end-user category. CAGRs were derived from regression analysis of procurement volume trends and reimbursement pathway expansion timelines. Industry-specific forecast inputs included circulating tumor DNA test adoption curves and cold-chain elimination penetration rates in decentralized collection networks.
Several conditions sit outside the modeled scope, including novel preservative chemistry breakthroughs extending cell-free DNA integrity beyond current 14-day intervals and circulating tumor cell viability preservation advances enabling single-cell genomic analysis. Forecasts reflect assumptions about Medicare coverage determination velocity and EMA MDR enforcement consistency. Deviation in FDA Class II device pathway guidance or REACH compliance deadline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Esophageal Obturator Airway Kits Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Compression Socks Market
Medical Supplies
Medical Liners Market
Medical Supplies
Elbow Splints Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Anaesthesia Conduction Kits Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
Australia Hospital Supplies Market
Medical Supplies
Filter Needles Market
Medical Supplies
Crutch Pads Market
Medical Supplies
Sterile IV Containers Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Medical Swabs Market
Medical Supplies
Petri Dishes Market
Medical Supplies
GCC Intravenous Solutions Market