
 Amniotic Membrane Market | 2026-2036
Amniotic Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Amniotic Membrane Market Intelligence
Hospital procurement channels for amniotic membrane allografts is fragmenting as specialty distributors lose ground to direct-to-site tissue bank relationships. MiMedx Group Inc. leverages its vertically integrated tissue processing network to control supply continuity. Organogenesis Holdings Inc. competes through sustained R&D investment in dehydrated membrane formulations. Smith & Nephew anchors its position via established orthobiologic sales infrastructure across major metropolitan health systems.
Amniotic membrane consists of a single epithelial layer, a thick basement membrane, and an avascular stroma rich in collagen types IV, V, and VII; manufacturers preserve this extracellular matrix through cryopreservation or lyophilization to retain bioactive cytokines and growth factors for wound healing and ocular surface reconstruction. Cryopreserved amniotic membrane dominates current revenue pools due to superior biologic activity retention, while dehydrated variants represent the fastest-growing product category as shelf-stable logistics expand access to ambulatory settings. Wound care applications command mature volume flows, though ophthalmology segments attract premium positioning because of reimbursement advantages for corneal procedures.
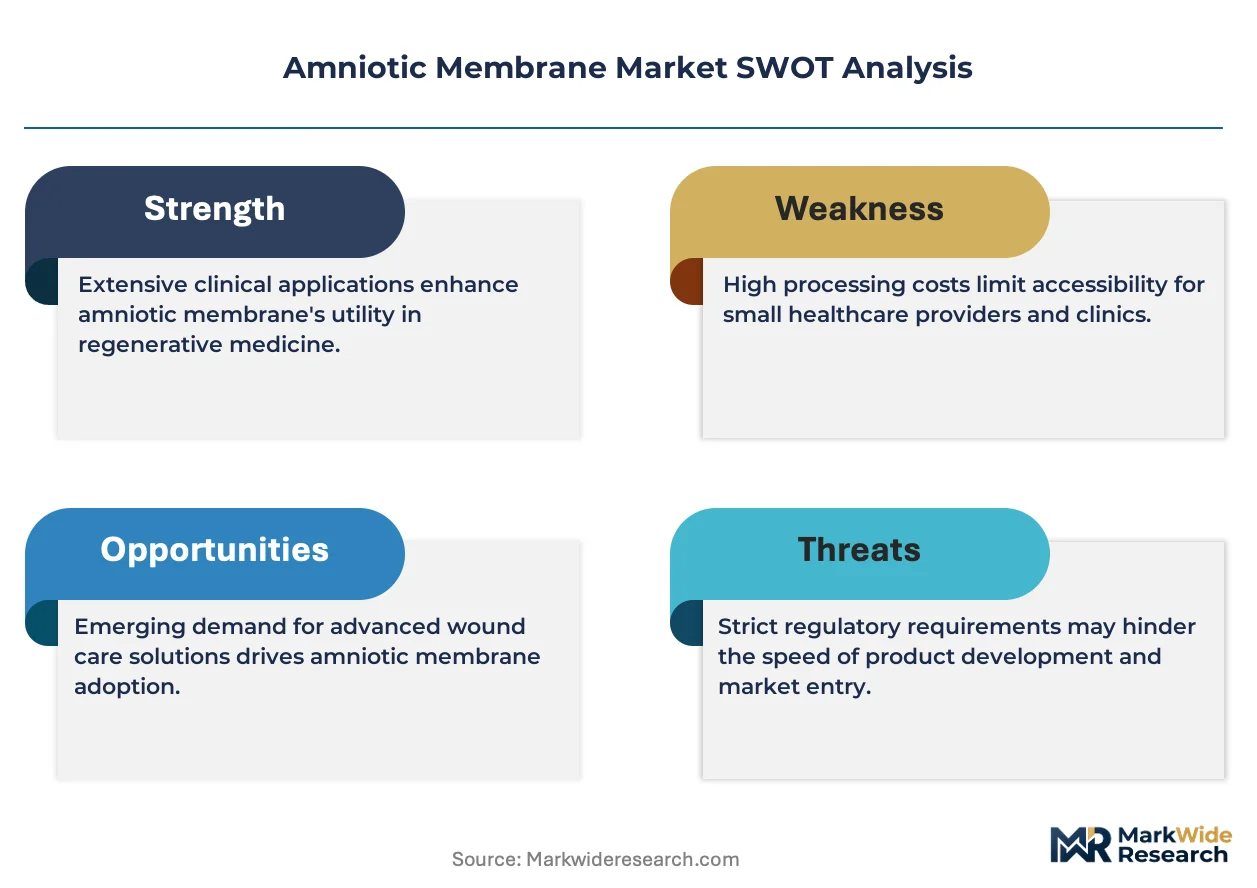
The FDA enforces 21 CFR Part 1271 human cell and tissue regulations alongside AATB accreditation standards, while the EU Medical Device Regulation reclassifies certain amniotic products into higher-risk categories requiring notified body oversight. These frameworks elevate compliance costs for smaller tissue banks and reshape competitive access across regulated markets. Stakeholders must monitor evolving classification decisions that could redirect investment toward engineered membrane platforms or downstream processing automation.
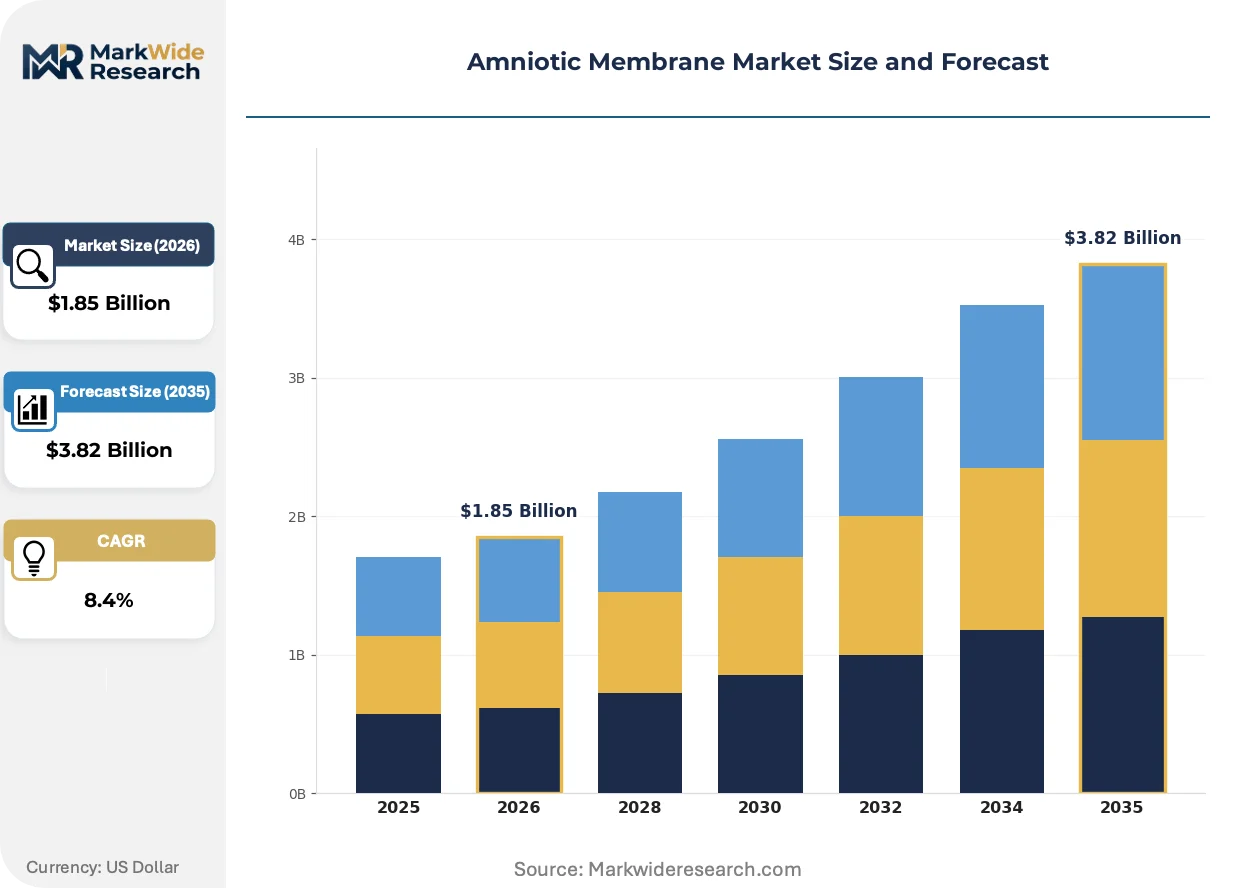
Market Dynamics
Tissue bank consolidation is concentrating supply control among vertically integrated processors, while ophthalmology's shift toward office-based surgical suites reroutes procurement through specialty distributors serving ambulatory settings.
Growth Catalysts
- EU Medical Device Regulation reclassification:Higher-risk categorization for certain amniotic products is accelerating investment in quality management systems and notified body relationships among established processors.
- Cryopreserved graft adoption:Superior retention of bioactive cytokines and growth factors is pulling corneal repair procedures toward hospital outpatient departments and specialized eye clinics.
- Chronic wound prevalence:Diabetic foot ulcer and venous leg ulcer patient volumes in Medicare-aged populations are sustaining demand for extracellular matrix wound dressings across skilled nursing facilities.
Market Restraints
- Donor tissue supply volatility:Placental donation rates fluctuate with birth volumes at contracted hospital sites, creating batch-to-batch availability constraints for smaller tissue banks.
- FDA 21 CFR Part 1271 compliance burden:Current good tissue practice requirements elevate fixed costs for quality systems, screening protocols, and adverse event reporting beyond the reach of regional processors.
- Synthetic skin substitute convergence:Engineered collagen matrices and bilayer silicone-cultured epidermal autografts are capturing select wound care indications with standardized manufacturing economics.
Strategic Opportunities
- Lyophilized product shelf stability:Dehydrated membrane formats with ambient storage requirements are opening access to physician offices and rural surgical centers lacking cryogenic infrastructure.
- India's tissue banking infrastructure:Emerging regulatory frameworks from CDSCO and expanding private hospital networks are creating first-mover positioning for accredited international suppliers.
- Orthopedic sports medicine extension:Tendon wrap and adhesion barrier applications in arthroscopic procedures represent adjacent utilization beyond established ocular and dermal indications.
Industry Challenges
- AATB accreditation timelines:New tissue bank applicants face 18-24 month evaluation cycles for full accreditation, delaying market entry and tying up capital in pre-revenue facilities.
- Cold chain integrity maintenance:Cryopreserved graft logistics require validated shipping containers and temperature monitoring across last-mile delivery to surgical sites, with excursion events triggering product quarantine.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amniotic Membrane Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Amniotic Membrane, Cryopreserved Amniotic Membrane, Dehydrated Amniotic Membrane, Engineered Amniotic Membrane Application: Ophthalmology, Wound Care, Orthopedic Surgery, Dental Surgery, Burn Treatment End User: Specialty Clinics, Research Institutions, Ambulatory Surgical Centers, Tissue Banks Processing Method: Gamma Irradiation, Electron Beam Sterilization, Ethylene Oxide Sterilization, Sterile Packaging |
| Companies Covered | MiMedx Group Inc., Organogenesis Holdings Inc., Smith & Nephew, Integra LifeSciences, Applied Biologics LLC, Alliqua BioMedical Inc., Amnio Technology LLC, Skye Biologics Inc., Human Regenerative Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amniotic Membrane Market Strategic Shifts & Innovations
Processing automation and bioactive preservation science are converging to expand the addressable site-of-care footprint for amniotic-derived therapeutics beyond traditional hospital settings.
Lyophilization technology paired with barrier packaging is virtualizing the distribution economics of amniotic membrane grafts. Ambulatory surgical centers and ophthalmology clinics lacking liquid nitrogen storage are adopting these shelf-stable formats for same-day procedure scheduling. The technology is virtualizing the historical trade-off between biologic potency retention and logistical flexibility that constrained cryopreserved product reach.
FDA's 21 CFR Part 1271 human cell and tissue regulations continue tightening donor screening and traceability mandates for amniotic allografts. Manufacturers must now maintain chain-of-custody documentation from placental recovery through final packaging, with inspection frequency intensifying for high-volume processors. Dehydrated product categories face particular scrutiny as the agency evaluates whether lyophilization alters fundamental tissue characteristics requiring premarket notification.
Direct-to-site procurement relationships are displacing traditional distributor intermediaries in metropolitan health systems with sufficient procurement scale. Hospital outpatient departments and integrated delivery networks are negotiating master service agreements with tissue banks for guaranteed supply allocation and transparent cost-plus pricing. This channel restructuring is most visible in the United States, where group purchasing organizations are losing leverage over biologic categories with limited supplier alternatives.
Amniotic Membrane Market Segmentation
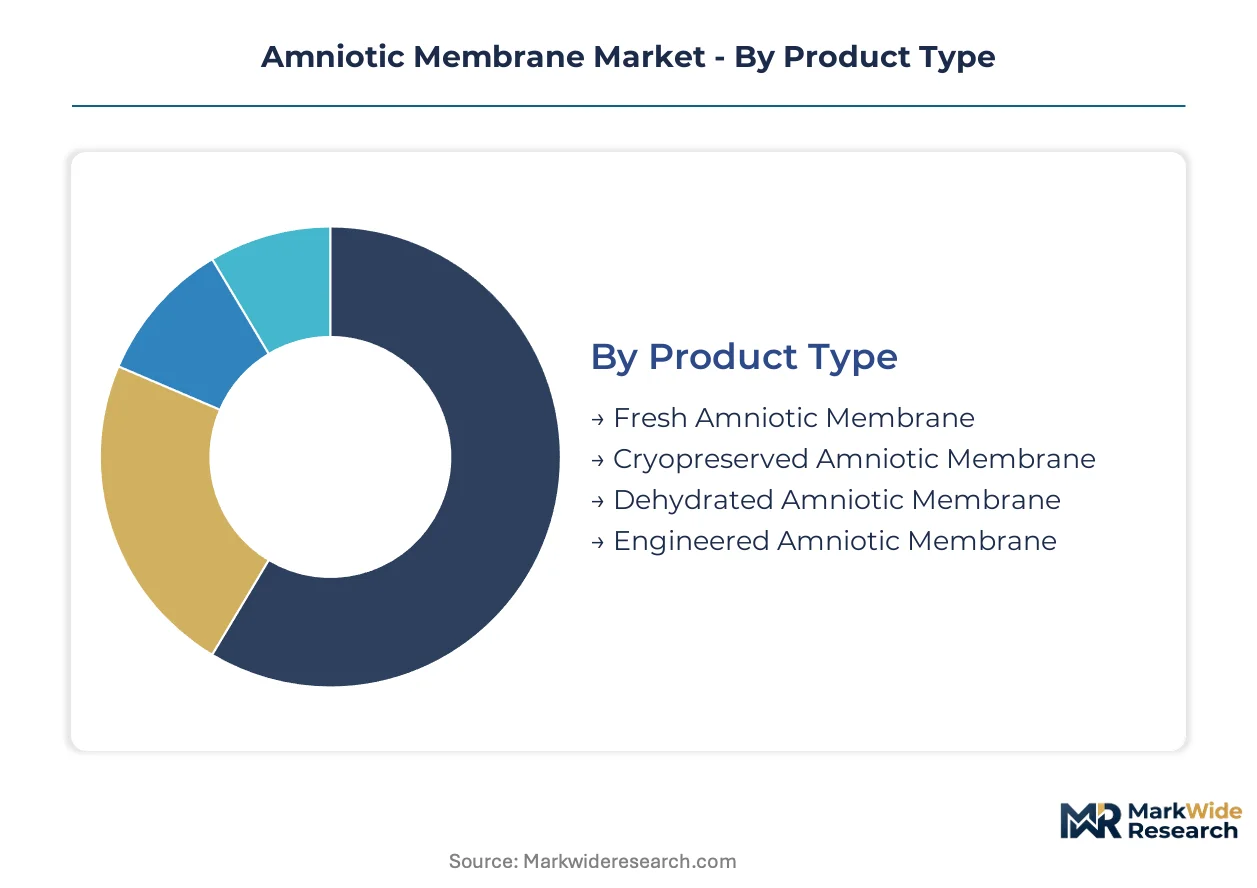
Segmentation in the amniotic membrane market reveals how processing technology and clinical setting dictate procurement patterns. Product format determines cold chain requirements, while application specialization governs reimbursement pathways and margin structures.
Product Type:
After-sales service intensity varies sharply across preservation formats, with cryopreserved products demanding continuous temperature monitoring and emergency replacement protocols that dehydrated variants simply do not require.
- Cryopreserved Amniotic Membrane:Liquid nitrogen storage preserves native extracellular matrix architecture and bioactive cytokine profiles. Hospital outpatient departments and ophthalmology clinics in the United States concentrate procurement here, drawn by superior healing outcomes in corneal procedures despite complex logistics.
- Dehydrated Amniotic Membrane:Lyophilization renders stromal collagen stable at ambient temperatures for 24-36 months. Ambulatory surgical centers lacking cryogenic infrastructure are adopting this format fastest, particularly in rural markets where cold chain reliability remains problematic.
- Fresh Amniotic Membrane:Viable cellular content requires immediate use within 48 hours of processing. Limited to emergency burn centers and specialized eye hospitals with direct tissue bank relationships.
- Engineered Amniotic Membrane:Decellularized scaffolds with recombinant growth factor loading. Early-stage utilization in orthopedic research protocols and regenerative medicine trials.
Cryopreserved amniotic membrane holds the largest share; momentum sits with dehydrated amniotic membrane.
Application:
Margin profiles diverge across clinical domains, with ophthalmology commanding premium positioning through procedure-specific reimbursement codes that wound care applications rarely access.
- Ophthalmology:Corneal surface reconstruction and pterygium excision utilize amniotic membrane as a biological bandage. Premium pricing reflects Medicare reimbursement advantages for anterior segment procedures performed in hospital outpatient settings.
- Wound Care:Diabetic foot ulcers and venous leg ulcers represent mature volume flows. Skilled nursing facilities drive procurement through Medicare Part B coverage for extracellular matrix dressings.
- Orthopedic Surgery:Tendon wrap and adhesion barrier applications in arthroscopic rotator cuff repair. Sports medicine practices in metropolitan health systems pilot utilization.
- Dental Surgery:Ridge preservation and gingival recession coverage. Limited adoption constrained by periodontal reimbursement variability.
- Burn Treatment:Temporary biological dressing for partial-thickness thermal injuries. Regional burn centers maintain emergency stockpiles.
Ophthalmology commands the highest margins; wound care delivers the steepest volume trajectory.
End User:
Procurement scale determines contracting leverage, with integrated delivery networks extracting cost-plus transparency that smaller specialty clinics cannot match.
- Ambulatory Surgical Centers:Office-based ophthalmology suites and outpatient wound clinics favor shelf-stable dehydrated formats. Direct-to-site tissue bank relationships are displacing traditional distributor channels.
- Specialty Clinics:Cornea specialists and advanced wound care centers require guaranteed supply allocation for scheduled procedures. Master service agreements with accredited tissue banks ensure continuity.
- Tissue Banks:Vertically integrated processors control upstream supply through placental recovery contracts at birthing hospitals. Quality systems and AATB accreditation create barriers to entry.
- Research Institutions:Engineered membrane platforms and novel bioactive preservation protocols. Preclinical and early-phase clinical trial supply.
Ambulatory surgical centers are gaining share fastest; tissue banks retain supply control.
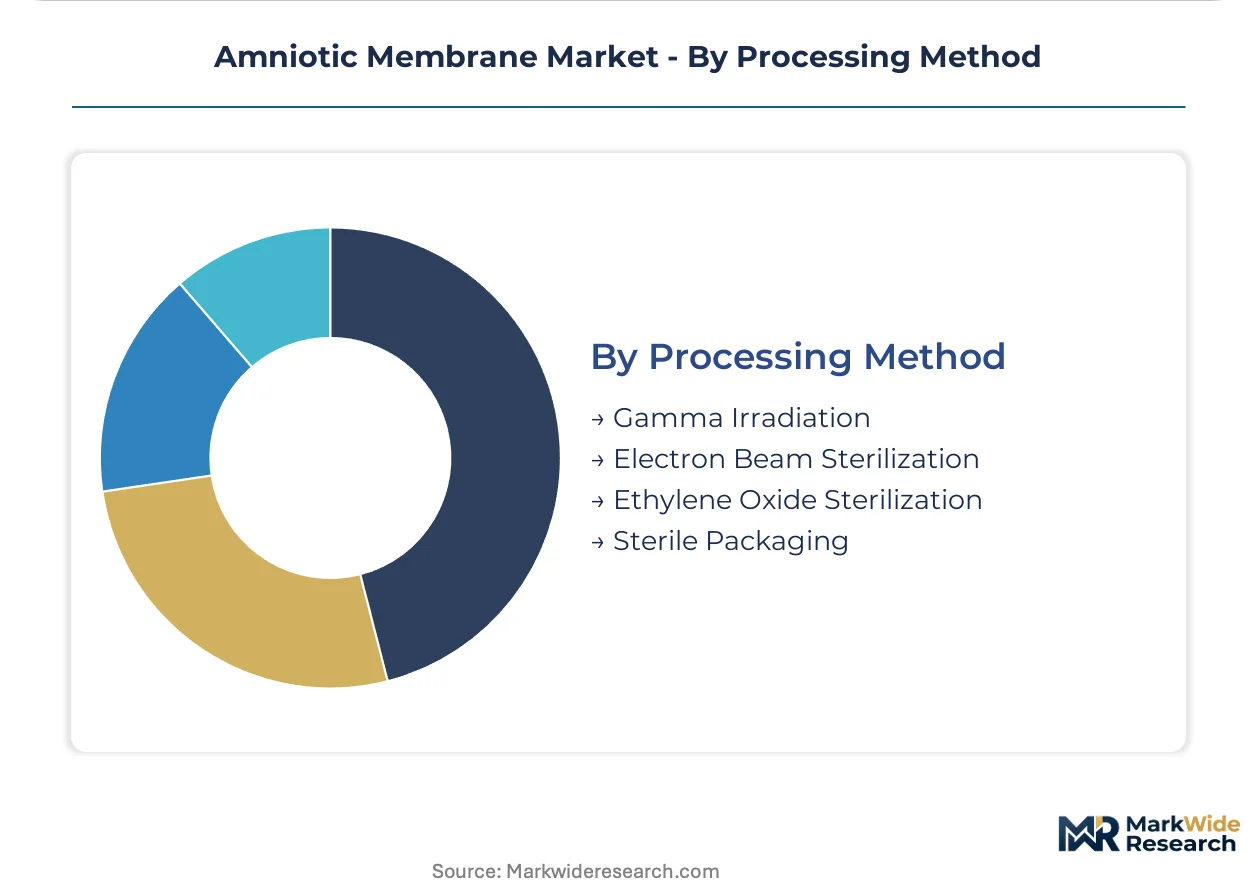
Processing Method:
Regulatory classification hinges on sterilization modality, with terminal sterilization processes triggering heightened FDA scrutiny over fundamental tissue characteristics.
- Sterile Packaging:Aseptic processing in ISO Class 5 cleanrooms preserves native tissue architecture without terminal sterilization. Premium positioning for ophthalmic applications requiring intact basement membrane integrity.
- Gamma Irradiation:Cobalt-60 or cesium-137 sources achieve sterility assurance levels with documented collagen cross-linking effects. Wound care applications tolerate structural modification better than ocular uses.
- Electron Beam Sterilization:Accelerated electrons reduce irradiation time and temperature exposure compared to gamma methods. Emerging adoption for temperature-sensitive bioactive preservation.
- Ethylene Oxide Sterilization:Gas penetration for complex geometries with residual testing requirements. Limited utilization due to aeration cycle duration and occupational safety constraints.
Sterile packaging dominates ophthalmic supply; electron beam sterilization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain logistics infrastructure underwrites Europe's position as a distribution hub for cryopreserved tissue products, while direct-to-site procurement relationships reshape procurement economics across major metropolitan health systems.
United States
Hospital outpatient departments and ambulatory surgical centers drive procurement volume through Medicare Part B reimbursement pathways. FDA 21 CFR Part 1271 regulations enforce donor screening and traceability mandates that elevate compliance costs for tissue banks. The Dallas-Fort Worth metroplex anchors processing capacity through vertically integrated tissue bank networks serving the Southwest corridor.
Germany
Specialized eye clinics in Bavaria and Baden-Württemberg adopt cryopreserved grafts for corneal surface reconstruction at accelerating rates. EU Medical Device Regulation reclassification into higher-risk categories requires notified body oversight for certain amniotic products. The Rhine-Main cluster around Frankfurt concentrates distribution logistics for dehydrated membrane formats entering Central European markets.
India
Expanding private hospital networks in Maharashtra and Karnataka generate demand for shelf-stable wound care applications. CDSCO emerging regulatory frameworks for tissue banking create first-mover positioning opportunities for accredited international suppliers. The Delhi-NCR corridor attracts investment in processing infrastructure as domestic birth volumes sustain placental donation potential.
Japan
Academic medical centers in Tokyo and Osaka prefectures utilize amniotic membrane in ophthalmology research protocols and regenerative medicine trials. PMDA oversight of human cell and tissue products maintains stringent quality system requirements for imported allografts. The Kansai region's aging demographic profile sustains chronic wound care demand through skilled nursing facility networks.
United Kingdom
NHS hospital outpatient departments procure cryopreserved formats for anterior segment procedures under specialized commissioning frameworks. MHRA alignment with EU MDR standards elevates documentation requirements for tissue establishment authorization. The Greater Manchester health system pilots direct-to-site tissue bank relationships that bypass traditional distributor intermediaries.
Amniotic Membrane Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated tissue processors with captive placental recovery networks at contracted hospital sites. The competitive structure fragments between large-scale processors controlling upstream supply and specialty distributors serving ambulatory settings. Three archetypes dominate: vertically integrated tissue banks with recovery-to-distribution control; specialty distributors pivoting toward logistics and value-added services; and orthopedic-focused orthobiologic players leveraging existing sales infrastructure. M&A activity concentrates placental recovery contracts and processing capacity under fewer entities, while strategic partnerships between tissue banks and metropolitan health systems displace traditional distribution channels.
Within the vertically integrated tier, MiMedx Group Inc. and Organogenesis Holdings Inc. exemplify archetypes of supply chain control and R&D-focused product differentiation respectively. Smith & Nephew anchors the orthobiologic infrastructure vector through established relationships across major metropolitan health systems. These three entities occupy positions that reflect distinct strategic bets on processing technology, preservation science, and channel access rather than interchangeable competitive positioning.
| Leading Market Players |
|---|
| MiMedx Group Inc. |
| Organogenesis Holdings Inc. |
| Smith & Nephew |
| Integra LifeSciences |
| Applied Biologics LLC |
| Alliqua BioMedical Inc. |
| Amnio Technology LLC |
| Skye Biologics Inc. |
| Human Regenerative Technologies LLC |
| Others |
Cost & Logistics Intelligence
Undercapacity in cryogenic processing infrastructure across the United States is forcing tissue banks toward premium pricing postures while constraining volume commitments to ambulatory surgical centers. This utilization squeeze simultaneously elevates procurement costs for hospital outpatient departments and accelerates adoption of shelf-stable dehydrated alternatives that bypass cold chain bottlenecks.
Pricing Analysis
Three-tier pricing structure across premium cryopreserved, standard dehydrated, and economy fresh formats governs contract negotiations between tissue banks and metropolitan health systems. Price differentiation rests on AATB accreditation tier and guaranteed supply allocation volumes, with cryopreserved grafts commanding substantial premiums due to bioactive cytokine retention. Cost compression in the dehydrated tier is intensifying because lyophilization technology diffusion erodes manufacturing scale advantages. Ambulatory surgical centers exhibit highest price sensitivity, while specialized ophthalmology clinics prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Vertically integrated processors in the United States, Germany, and India hold dominant placental recovery and processing capacity through contracted hospital site networks. Raw material flows draw from birthing center donation programs, sterile packaging components, and liquid nitrogen logistics infrastructure. Single-source vulnerability concentrates in cryogenic shipping container manufacturing, where validated temperature monitoring systems face extended lead times. Distribution runs through direct-to-site tissue bank relationships displacing traditional specialty distributor channels in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amniotic membrane market constitutes a high-growth disruption propelled by EU Medical Device Regulation reclassification that elevates compliance barriers and consolidates competitive access around accredited processors.
For Market Incumbents: Pre-empt synthetic skin substitute convergence by deepening bioactive preservation science investments and securing exclusive placental recovery contracts at high-birth-volume hospital systems. Lock in AATB accreditation moats before regulatory timelines extend further, while piloting orthopedic sports medicine applications to diversify beyond ophthalmology and wound care revenue concentration. For New Entrants and Emerging Players: Build out shelf-stable dehydrated membrane manufacturing capacity targeting India's emerging private hospital networks and rural United States ambulatory surgical centers lacking cryogenic infrastructure. India's CDSCO regulatory framework development creates first-mover positioning for accredited international suppliers before domestic processing capacity matures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryopreserved processing infrastructure due to FDA 21 CFR Part 1271 compliance system investments and cold chain validation requirements. Acquisition targets should display captive placental supply contracts and established notified body relationships in Europe. Monitor AATB accreditation queue lengths as inflection indicator for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Technology Scale-Up | Enables ambient-temperature distribution to physician offices lacking liquid nitrogen storage infrastructure. |
| Placental Recovery Contract Expansion | Secures upstream supply continuity through exclusive agreements at high-birth-volume birthing hospitals. |
| EU MDR Notified Body Relationship | Accelerates market access for higher-risk product classifications requiring third-party conformity assessment. |
| Orthopedic Sports Medicine Partnership | Opens adjacent utilization in arthroscopic tendon wrap applications beyond established ocular indications. |
| Direct-to-Site Procurement Agreement | Bypasses distributor intermediaries through master service agreements with integrated delivery networks. |
Research Approach
Cross-validation between tissue bank procurement managers and ophthalmology clinic administrators anchors the qualitative findings on shifting channel dynamics. Primary interviews with AATB accreditation specialists, hospital purchasing committee directors, and GPO contracts managers were combined with secondary validation from FDA 21 CFR Part 1271 guidance documents, EU MDR implementation timelines, and CMS Medicare reimbursement databases. Bottom-up demand modeling across preservation formats and top-down supply capacity assessments were triangulated to constrain forecast variance.
Calibration against historical cryopreserved versus dehydrated adoption curves informed the analytical framework across the projection horizon. Segmentation dimensions modeled include preservation technology, clinical application specialty, end-user facility type, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating chronic wound prevalence trajectories and ophthalmology procedure migration patterns toward office-based surgical suites.
Stress conditions across placental donation rate volatility, cryogenic logistics cost inflation, and synthetic substitute technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement stability and regulatory classification continuity. Quarterly review of AATB accreditation approval timelines and EU notified body capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Casting and Splinting Market
Medical Supplies
Slip Tip Syringe Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Respiratory Masks Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Blood Bags Market
Medical Supplies
Oral Syringes Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Alcohol Prep Pads Market
Medical Supplies
Global Chromatography Syringes Market
Medical Supplies
Lavage Kits Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Europe Custom Procedure Kits Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Swabs Collection Kit Market