
 US Healthcare Personal Protective Equipment Market | 2026-2036
US Healthcare Personal Protective Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Personal Protective Equipment Market Intelligence
Homecare service expansion is recalibrating demand patterns across distributor networks. 3M leverages its filtration science portfolio to anchor premium respirator positioning in acute care channels. Kimberly-Clark Corporation sustains broad category coverage through extensive private-label and branded manufacturing infrastructure. Medline Industries controls hospital supply logistics with direct-to-dock distribution capabilities that reduce procurement friction for large integrated delivery networks.
US Healthcare Personal Protective Equipment comprises engineered barrier garments and accessories manufactured from synthetic polymers, woven textiles, and melt-blown nonwovens, tested to fluid resistance, bacterial filtration efficiency, and particulate penetration thresholds to protect healthcare workers from infectious agents, chemical hazards, and biological contaminants during patient care and clinical procedures. Gloves and masks occupy the largest volume positions within the product mix, though gowns command higher unit margins as hospitals upgrade to AAMI Level 3 and Level 4 protection for surgical and isolation applications. Nitrile continues displacing latex in glove procurement due to allergy prevalence reduction and superior chemical resistance profiles, while polypropylene dominates disposable apparel substrates for cost-efficient single-use protocols.
FDA 510(k) clearance pathways and OSHA bloodborne pathogen standards govern market entry and workplace mandate compliance, with CDC infection control guidelines further shaping hospital purchasing specifications for outbreak preparedness. ASTM International maintains voluntary consensus standards for surgical mask bacterial filtration and surgical gown liquid barrier performance that manufacturers must meet for institutional contract eligibility. Stakeholders should monitor NIOSH certification backlogs and domestic production incentive programs as supply chain resilience policies reshape sourcing geography and inventory minimums.
Market Dynamics
Hospital inventory modernization is compressing procurement cycles as acute care facilities rebuild stockpiles around ASTM F2407 surgical gown standards and NIOSH-certified respirator minimums, forcing distributors to reconfigure fulfillment networks around direct-to-dock logistics.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Workplace safety mandates require employers to provide appropriate PPE for exposure-prone procedures, institutionalizing recurring purchase commitments across outpatient surgery centers and long-term care facilities.
- Nitrile glove chemistry:Superior puncture resistance and elimination of latex protein allergens is displacing natural rubber in operating rooms and emergency departments, expanding addressable volume for synthetic polymer processors.
- Texas-California-Florida hospital consolidation:Integrated delivery networks in these states are centralizing supply contracts under single-source agreements that favor distributors with national warehousing footprints.
Market Restraints
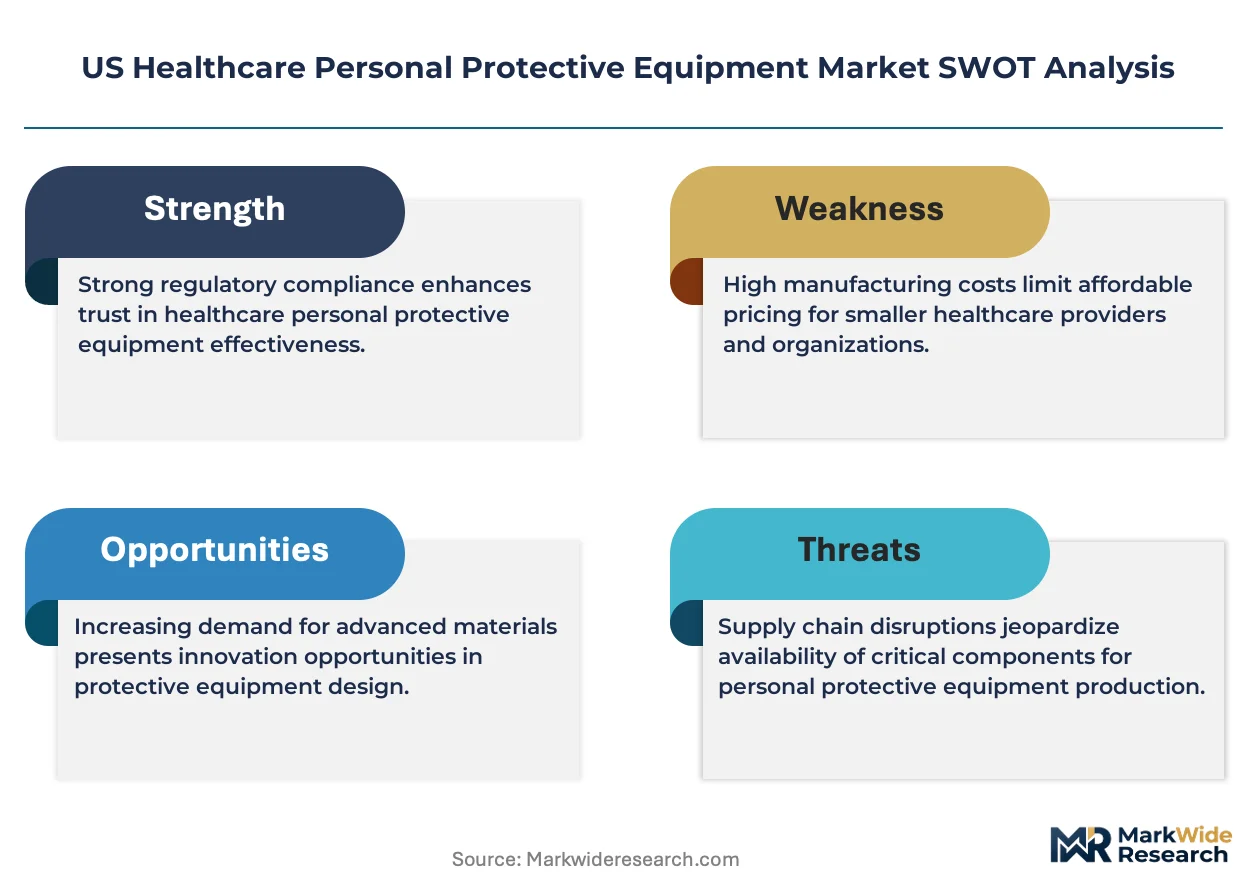
- Petrochemical input volatility:Polypropylene and nitrile butadiene rubber prices fluctuate with crude oil derivatives, compressing margin predictability for disposable apparel manufacturers.
- NIOSH certification backlog:Respirator approval delays at the National Institute for Occupational Safety and Health extend time-to-market for new N95 designs, constraining supply responsiveness during demand surges.
- Reusable gown substitution:Launderable surgical textiles with AAMI Level 4 barrier ratings are capturing preference in environmentally conscious health systems, threatening single-use polypropylene volume.
Strategic Opportunities
- Home health expansion:Medicare-reimbursed skilled nursing visits are rising in Florida and Arizona retirement corridors, creating demand for portable PPE kits sized for individual caregivers rather than institutional pallets.
- Domestic production incentives:Department of Health and Human Services supply chain resilience grants subsidize US-based melt-blown nonwoven manufacturing, reducing import dependency for critical filtration media.
- Smart packaging integration:RFID-tagged sterile barrier systems enable real-time inventory tracking through hospital ERP platforms, differentiating distributors that embed IoT infrastructure into logistics contracts.
Industry Challenges
- Biocompatibility testing timelines:FDA 510(k) submissions for novel skin-contact polymers require 12-18 month validation cycles, delaying product line extensions.
- Sterile processing technician shortage:Central supply department staffing gaps in Midwestern community hospitals slow gown and kit turnaround, forcing overtime premiums that erode operational budgets.
- Legacy distributor integration:Acute care systems merging with ambulatory networks face incompatible ERP systems that fragment PPE spend visibility and prevent volume-based pricing optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Personal Protective Equipment Market |
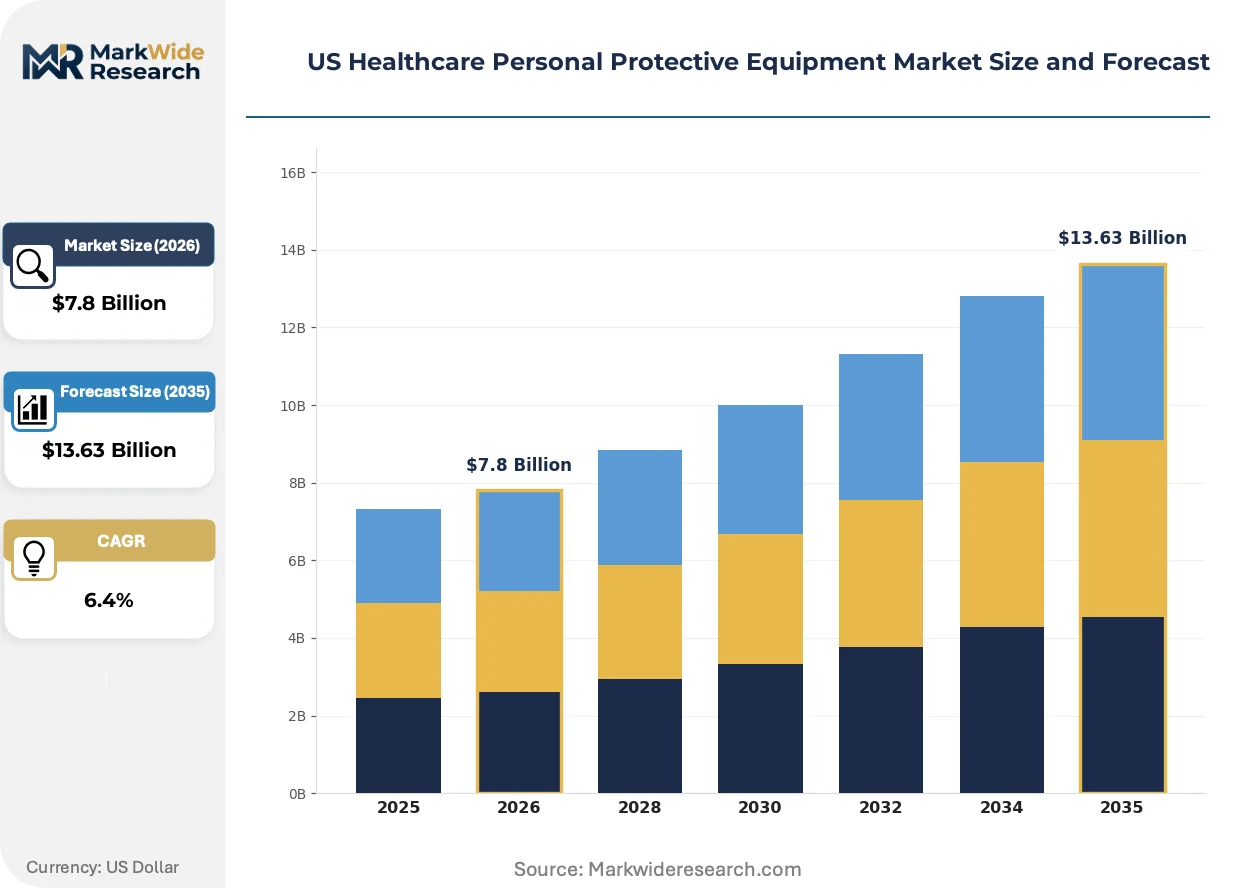
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Masks, Face Shields, Gowns End User: Hospitals, Clinics, Homecare, Laboratories Material: Nitrile, Latex, Polypropylene, Cotton Application: Infection Control, Hazardous Material, Surgery, Patient Care |
| Companies Covered | 3M, Honeywell International Inc., DuPont, Ansell Ltd., Alpha Pro Tech, Kimberly-Clark Corporation, Cardinal Health, Medline Industries, Lakeland Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Personal Protective Equipment Market Strategic Shifts & Innovations
Barrier material science and regulatory recalibration are converging to redefine acceptable protection thresholds, while procurement centralization is compressing vendor relationships into fewer, deeper partnerships.
Antimicrobial copper-infused nonwovens are absorbing bacterial load in high-touch clinical environments. Intensive care units in tertiary hospitals are piloting copper-oxide embedded isolation gowns for immunocompromised patient protocols. This technology is absorbing premium positioning from standard polypropylene as infection control committees document reduced surface contamination in peer-reviewed surveillance studies.
FDA updated its Enforcement Policy for Face Masks to incorporate ASTM F3502 barrier face covering standards, creating a formal pathway for non-NIOSH respirators in healthcare-adjacent settings. Surgical mask manufacturers are retesting legacy products against the new bacterial filtration efficiency benchmarks. Outpatient dental and veterinary clinics—previously sourcing industrial-grade alternatives—now face explicit regulatory pressure to upgrade to medical-designated inventory.
Consolidated service center purchasing is displacing departmental autonomy in multi-hospital systems. Materials management directors in California-based IDNs are mandating standardized gown specifications across all affiliated facilities, eliminating site-specific exceptions that previously fragmented contract value. This concentration is most visible in Pacific Northwest academic medical centers where procurement officers negotiate enterprise-wide AAMI Level 3 and Level 4 commitments with sole-source distributors.
US Healthcare Personal Protective Equipment Market Segmentation
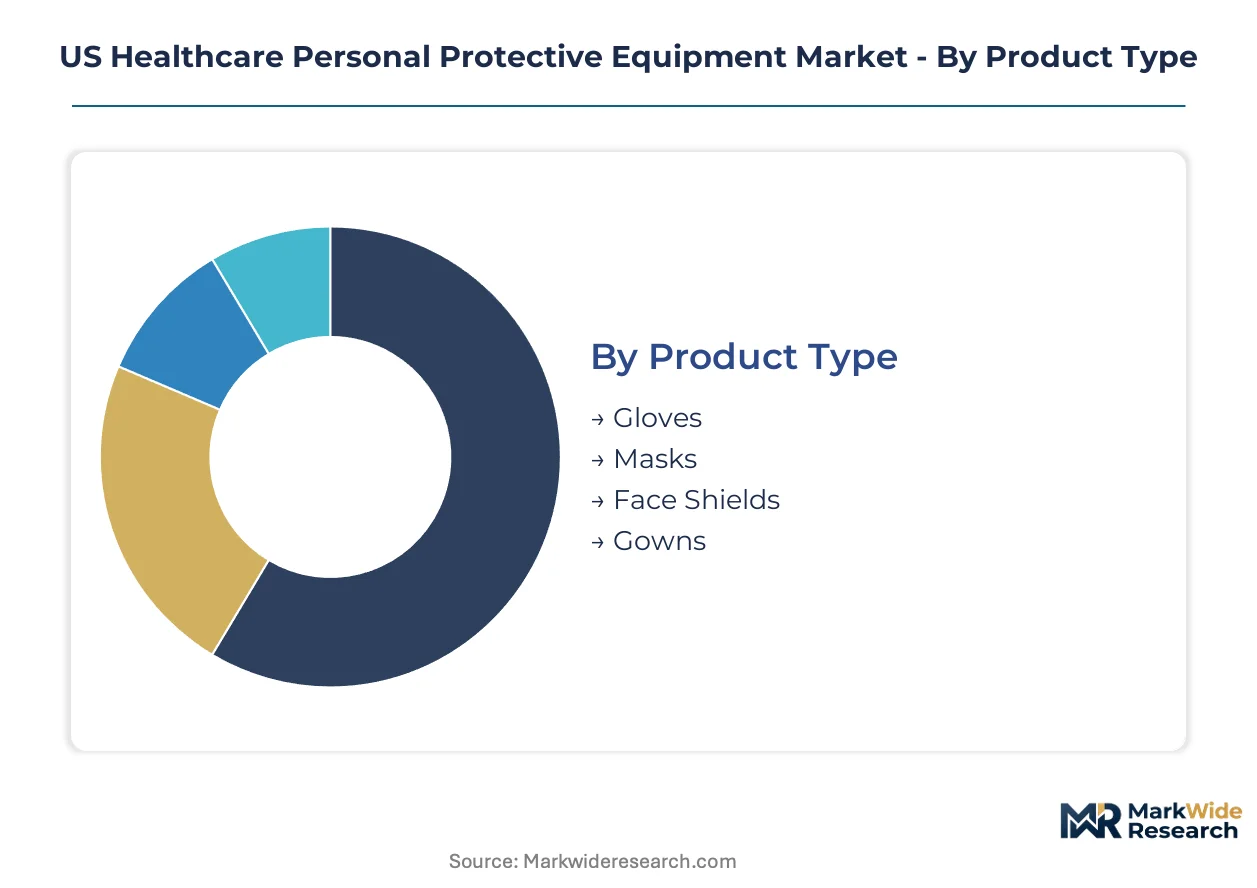
PPE procurement stratifies across multiple dimensions that determine regulatory burden, margin structure, and distributor relationships. Understanding these segment boundaries clarifies where ASTM certification requirements concentrate and which material specifications command premium positioning.
Product Type:
FDA device classification and ASTM testing protocols impose distinct compliance costs across each product category, with surgical gowns requiring the most extensive barrier validation.
- Gloves:Nitrile formulations dominate hospital procurement due to latex allergy elimination and superior puncture resistance. Texas and Florida health systems are consolidating nitrile contracts under single-source agreements with distributors holding domestic warehousing capacity.
- Gowns:AAMI Level 3 and Level 4 liquid barrier ratings differentiate surgical from isolation applications. California academic medical centers are mandating standardized Level 4 specifications across all affiliated facilities, compressing vendor relationships.
- Masks:NIOSH certification for N95 respirators and ASTM F2100 surgical mask standards create dual approval pathways. FDA updated enforcement policies now require outpatient dental clinics to upgrade from industrial-grade alternatives.
- Face Shields:Polycarbonate and PETG visors with anti-fog coatings serve splash protection protocols in emergency departments and procedural suites.
Leading the category by volume: Gloves. Growing fastest: Gowns.
End User:
Procurement scale and specification complexity vary sharply across care settings, with integrated delivery networks imposing enterprise-wide standardization.
- Hospitals:Acute care facilities drive ASTM F2407 surgical gown demand and NIOSH-certified respirator minimums. Direct-to-dock logistics from national distributors reduce procurement friction for large systems.
- Homecare:Medicare-reimbursed skilled nursing visits in Florida and Arizona retirement corridors are creating demand for portable PPE kits sized for individual caregivers.
- Clinics:Outpatient surgery centers face OSHA bloodborne pathogen mandates requiring recurring PPE purchase commitments for exposure-prone procedures.
- Laboratories:Biosafety level protocols dictate specialized barrier combinations for chemical and biological hazard containment.
Hospitals absorb the majority of premium-tier volume. Homecare channels are expanding most quickly as Medicare shifts reimbursement toward community-based care.
Material:
Petrochemical input costs and biocompatibility testing timelines shape material selection trade-offs between performance and margin predictability.
- Nitrile:Synthetic polymer displacing natural rubber in operating rooms due to chemical resistance profiles and elimination of protein allergens.
- Polypropylene:Melt-blown nonwoven substrate dominates disposable apparel for cost-efficient single-use protocols. HHS supply chain resilience grants are subsidizing domestic production capacity.
- Latex:Natural rubber retains niche positioning in specific surgical applications where tactile sensitivity requirements persist despite allergy prevalence reduction efforts.
- Cotton:Reusable launderable textiles with AAMI Level 4 barrier ratings are capturing preference in environmentally conscious health systems.
Nitrile and polypropylene together account for the largest procurement volumes. Cotton alternatives are gaining share fastest amid sustainability pressures.
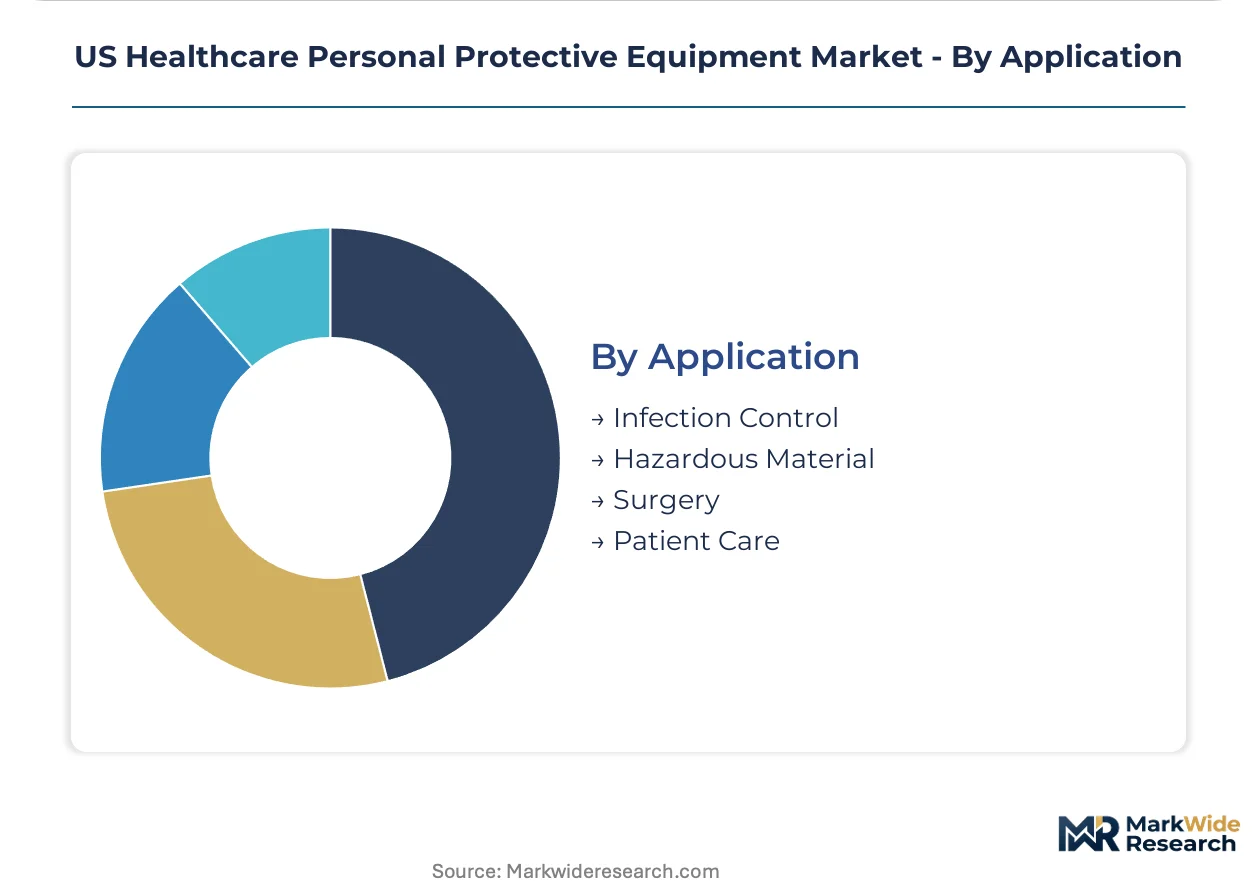
Application:
Clinical use case determines the specific ASTM or FDA performance threshold that products must satisfy for contract eligibility.
- Infection Control:Isolation protocols in immunocompromised patient units are piloting copper-oxide embedded nonwovens to reduce surface contamination.
- Surgery:Operating room demand centers on AAMI Level 3 and Level 4 gowns with fluid resistance validated to ASTM F2407 standards.
- Hazardous Material:Chemical exposure scenarios require specialized barrier combinations beyond standard medical PPE specifications.
- Patient Care:General bedside protocols utilize lower-tier protection with reduced testing burdens and corresponding price points.
Infection control applications command the steepest expansion trajectory as surveillance studies document copper-infused nonwoven efficacy. Surgery maintains the highest unit margin profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Enterprise Zones and California Opportunity Areas concentrate health system procurement through tax-advantaged distribution hubs serving consolidated integrated delivery networks.
Texas
Major health system consolidation in Dallas-Fort Worth and Houston drives centralized PPE contracting through single-source agreements. OSHA bloodborne pathogen compliance mandates institutionalize recurring purchase commitments across outpatient surgery centers. San Antonio medical device clusters anchor regional warehousing infrastructure for nitrile glove and surgical gown inventory.
California
Academic medical centers in Los Angeles and San Francisco mandate standardized AAMI Level 4 gown specifications across all affiliated facilities. FDA 510(k) clearance requirements shape manufacturer compliance obligations for barrier protection devices. Pacific Northwest procurement officers negotiate enterprise-wide commitments with sole-source distributors serving consolidated IDNs.
Florida
Medicare-reimbursed skilled nursing visits in retirement corridors create demand for portable PPE kits sized for individual caregivers. HHS supply chain resilience grants subsidize domestic melt-blown nonwoven manufacturing capacity. Tampa and Miami health systems centralize procurement under standardized inventory protocols.
New York Metro
Greater New York hospital networks rebuild stockpiles around NIOSH-certified respirator minimums and ASTM F2407 surgical gown standards. CDC infection control guidelines shape purchasing specifications for outbreak preparedness. Long Island and Westchester distribution hubs serve consolidated acute care facilities with direct-to-dock logistics.
Illinois-Michigan-Ohio
Midwestern community hospitals face sterile processing technician shortages that slow gown and kit turnaround. OSHA workplace safety mandates require appropriate PPE for exposure-prone procedures across outpatient networks. Chicago and Detroit medical supply clusters anchor regional distributor relationships for integrated delivery networks.
US Healthcare Personal Protective Equipment Market Key Industry Players
Top-tier vendors anchor premium barrier protection, while mid-scale fabricators compete on volume throughput and regional logistics. The vendor base stratifies across filtration science specialists, broad-category manufacturers, and supply chain integrators. Three archetypes dominate: diversified industrial conglomerates with healthcare divisions, dedicated medical apparel specialists, and distributor-logistics hybrids controlling hospital dock access. Competitive moves center on domestic production capacity expansion and RFID-enabled inventory tracking integration.
Within the diversified conglomerate tier, 3M and Honeywell International Inc. represent filtration science anchoring in acute care respirator channels. Among dedicated medical apparel specialists, Kimberly-Clark Corporation and Ansell Ltd. occupy positions spanning glove chemistry and barrier garment portfolios. Medline Industries exemplifies the distributor-logistics hybrid archetype with direct-to-dock capabilities reducing procurement friction for large integrated delivery networks.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| DuPont |
| Ansell Ltd. |
| Alpha Pro Tech |
| Kimberly-Clark Corporation |
| Cardinal Health |
| Medline Industries |
| Lakeland Industries |
| Others |
Cost & Logistics Intelligence
OSHA bloodborne pathogen compliance mandates gate qualified supply access and premium-tier pricing power by institutionalizing recurring purchase commitments that only certified manufacturers can fulfill. Hospital systems with enterprise-wide standardization protocols further compress vendor pools, concentrating pricing leverage with distributors holding domestic warehousing and NIOSH-certified respirator inventory.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as acute care facilities rebuild stockpiles around ASTM F2407 surgical gown standards and NIOSH-certified respirator minimums. Pricing stratifies across AAMI certification tiers, with Level 4 barrier garments commanding substantial markups over isolation-grade alternatives due to fluid resistance validation costs. Cost compression in nitrile glove procurement is intensifying because petrochemical input volatility erodes margin predictability for synthetic polymer processors. Outpatient surgery centers exhibit the highest price sensitivity, while integrated delivery networks in Texas and California absorb premium positioning for guaranteed supply continuity.
Supply Chain Analysis
Polypropylene melt-blown nonwoven supply rests on domestic manufacturing capacity expansion subsidized by Department of Health and Human Services supply chain resilience grants, though Asian producers retain significant filtration media market share. Nitrile butadiene rubber feedstocks draw from petrochemical complexes in the US Gulf Coast and Southeast Asian processing hubs, with glove finishing concentrated in Malaysia and Thailand. Single-source vulnerability permeates NIOSH certification pathways, where approval backlogs at the National Institute for Occupational Safety and Health constrain respirator supply responsiveness during demand surges. Distribution runs through national distributor-logistics hybrids with direct-to-dock capabilities serving consolidated integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NIOSH certification capacity constraints prop pricing power throughout the forecast period by limiting qualified respirator supply to hospital systems with outbreak preparedness mandates.
For Market Incumbents: Deploy backward integration into domestic melt-blown nonwoven manufacturing to secure filtration media supply against import dependency risks. Incumbent manufacturers must anchor hospital system partnerships through RFID-enabled inventory tracking integration that reduces procurement friction for materials management directors. Reusable gown substitution with AAMI Level 4 launderable textiles threatens single-use polypropylene volume, requiring incumbents to diversify into copper-oxide embedded barrier materials for immunocompromised patient protocols. For New Entrants and Emerging Players: Enter via portable PPE kit formats sized for individual caregivers in Florida and Arizona home health corridors, where Medicare-reimbursed skilled nursing visits are expanding fastest. New entrants should target the outpatient dental and veterinary clinic segment, where FDA updated enforcement policy now mandates medical-designated inventory upgrades from industrial-grade alternatives. A go-to-market angle anchored on ASTM F3502 barrier face covering compliance for healthcare-adjacent settings offers lower regulatory burden than NIOSH respirator pathways. For Investors and Strategic Acquirers: NIOSH certification backlog reduction is the leading indicator that domestic production incentives are translating into actionable supply expansion. The five-to-ten year viability window favors acquisition targets with established hospital dock access and GPO contract relationships rather than pure manufacturing assets. Investors should monitor Department of Health and Human Services grant disbursement velocity as the inflection signal for domestic melt-blown nonwoven capacity scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Melt-Blown Capacity Expansion | HHS supply chain resilience grants reduce import dependency for critical N95 filtration media. |
| NIOSH Certification Fast-Track Investment | Expedited respirator approval compresses time-to-market for new N95 designs during demand surges. |
| Hospital System Partnership Consolidation | Enterprise-wide AAMI Level 4 gown commitments with sole-source distributors lock in volume. |
| RFID-Enabled Inventory Tracking Integration | Real-time sterile barrier system visibility through hospital ERP platforms differentiates logistics contracts. |
| Copper-Oxide Embedded Nonwoven Development | Antimicrobial barrier materials capture premium positioning in immunocompromised patient protocols. |
Research Approach
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare reimbursement data underwrites the qualitative findings in this analysis. Primary interviews with materials management directors, biomedical engineers, sterile processing technicians, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, NIOSH certification records, and ASTM International standards documentation. Bottom-up demand modeling across product categories triangulated against top-down health system expenditure analysis ensures methodological rigor.
Comparable-period anchoring to historical inventory modernization cycles and outbreak-driven demand spikes structured the projection horizon for the US market. Segmentation dimensions modeled include product type, end user setting, material chemistry, and application protocol, with geographic procurement concentration in Texas, California, and Florida integrated as a regional weighting factor. CAGRs derived from volume-demand elasticity analysis calibrated to hospital bed expansion and Medicare reimbursement policy shifts, incorporating petrochemical input cost trajectories and domestic production incentive program disbursement timelines as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIOSH certification backlog persistence or acute petrochemical price volatility. Forecasts reflect assumptions regarding health system consolidation velocity, OSHA enforcement intensity, and supply chain resilience grant continuation that could revise trajectory. A small set of named triggers—NIOSH approval velocity, HHS grant disbursement rates, and reusable textile adoption curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Medical Transport Box Market
Medical Supplies
Global Dialysis Concentrate Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Dental Emergency Kit Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
United States Face Mask Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Compression Garments and Stockings Market