
 Surgical Gloves Market | 2026-2036
Surgical Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
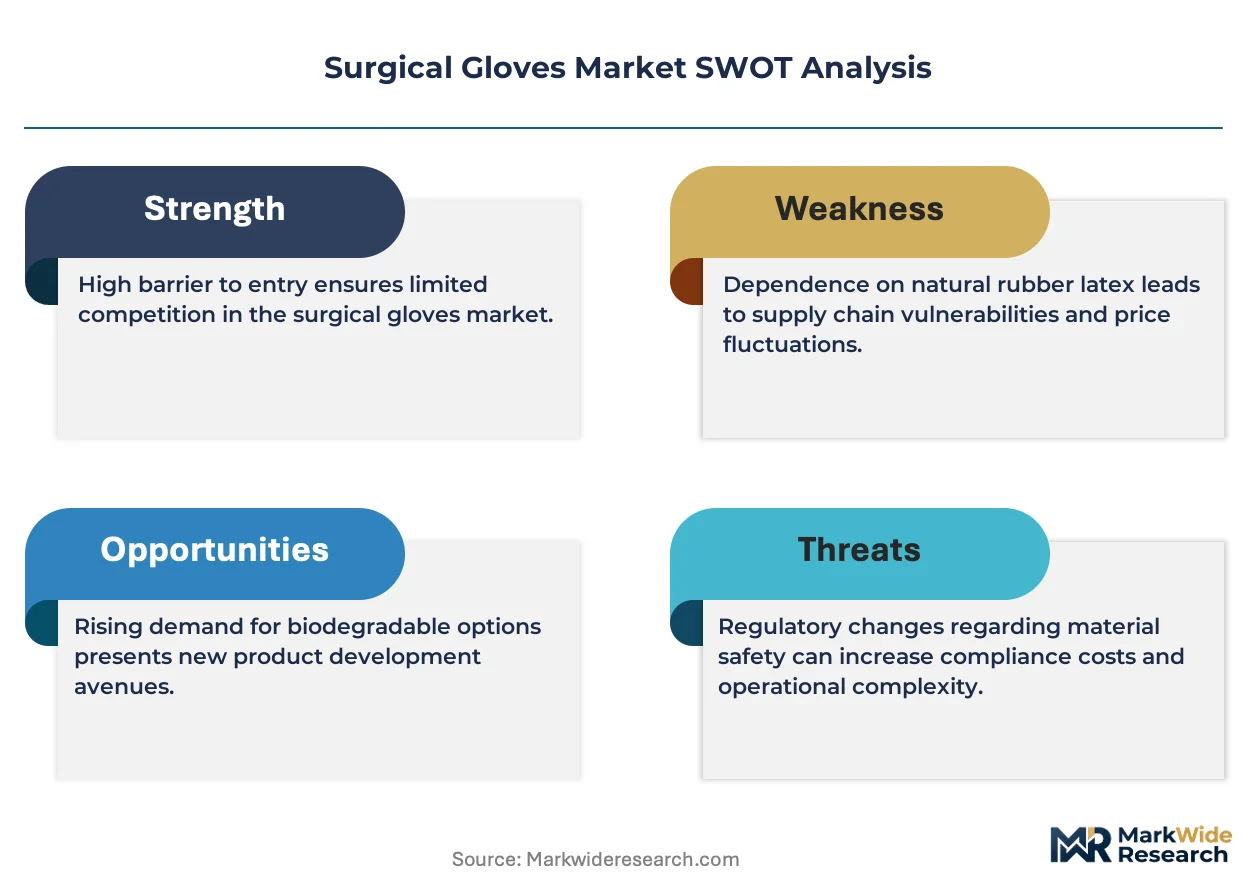
Surgical Gloves Market Analysis
Modular packaging of sterile surgical glove pairs with procedure-specific instrument kits is restructuring hospital procurement workflows. Top Glove Corporation leverages integrated manufacturing from raw latex to finished sterile packs across Southeast Asian facilities. Hartalega Holdings differentiates through ultra-thin nitrile formulations that sustain premium positioning in cardiac and neurosurgical suites. Ansell Ltd. competes on occupational skin-health compliance, anchoring its portfolio in accelerator-free chemistries for allergy-sensitive operating rooms.
Surgical gloves are personal protective barriers manufactured from natural rubber latex, synthetic nitrile, polyisoprene, or vinyl compounds, typically measuring 0.06 to 0.20 millimeters in thickness, sterilized by gamma irradiation or ethylene oxide, and designed to maintain tactile sensitivity while preventing bidirectional pathogen transmission during invasive procedures. Nitrile formulations now lead material type selection due to latex protein allergy prevalence and superior puncture resistance, though polyisoprene captures premium reconstructive surgery demand for elasticity matching natural latex. Application segmentation shows surgery generating the deepest margin pools while examination gloves face commoditization pressure from private-label entrants.
FDA quality system regulation and ISO 13485 medical device standards govern sterilization validation and biocompatibility testing requirements that determine market access for US-bound manufacturers. The EU MDR and REACH chemical restrictions are forcing reformulation of accelerators and plasticizers in gloves sold across European member states. Stakeholders must monitor evolving powder-free mandates and single-use plastic directives that will determine which material platforms retain regulatory viability across major healthcare procurement jurisdictions.
Market Dynamics
Powder-free mandates and accelerator-free chemistries are compressing legacy latex manufacturing capacity while redirecting capital toward nitrile and polyisoprene platforms. The FDA's updated quality system regulation and India's PLI scheme together are polarizing supply between regulated premium tiers and cost-optimized domestic production.
Growth Catalysts
- India PLI scheme:Production-linked incentives are scaling domestic nitrile manufacturing capacity, reducing import dependence for surgical gloves across South Asian hospital networks.
- Accelerator-free formulations:Type I hypersensitivity prevalence in operating rooms is pulling demand toward chemistries eliminating thiurams and carbamates from glove contact surfaces.
- Ambulatory surgical centers:Outpatient procedure volume expansion is fragmenting procurement into smaller, higher-frequency orders requiring flexible supply chain configurations.
Market Restraints
- Butadiene price volatility:Nitrile acrylonitrile-butadiene rubber feedstock costs swing with petrochemical cycles, compressing margin predictability for synthetic glove producers.
- Malaysian supply concentration:Over sixty percent of global nitrile glove capacity clusters in Southeast Asian integrated complexes, creating geographic single-point vulnerability.
- EU MDR transition friction:Medical Device Regulation recertification timelines are extending market access delays for non-EU manufacturers seeking European distribution.
Strategic Opportunities
- Brazil ANVISA pathway:Latin American surgical glove penetration remains below North American benchmarks, creating whitespace for nitrile substitution in public health procurement.
- Procedure-specific sterile kits:Modular packaging integrating gloves with instrument sets is capturing premium positioning in cardiac and orthopedic surgical suites.
- Gamma irradiation validation:Sterilization technology convergence with real-time dosimetry monitoring is enabling extended shelf-life claims for remote distribution channels.
Industry Challenges
- ISO 13485 audit backlog:Certification body capacity constraints are extending quality management system approval timelines for new market entrants.
- Legacy ERP integration:Track-and-trace serialization requirements are forcing mid-tier manufacturers into costly supply chain software overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Gloves Market |
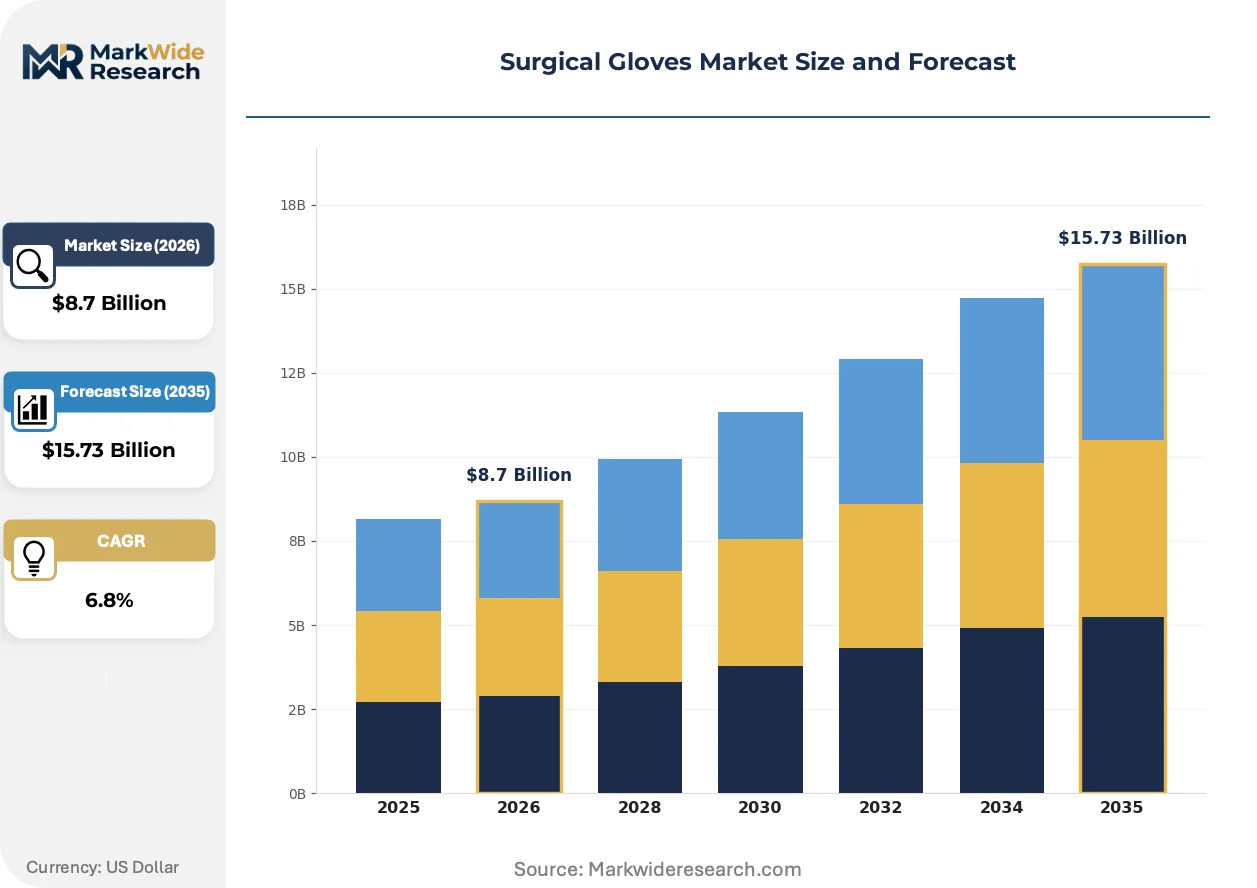
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Latex, Nitrile, Vinyl, Polyisoprene Application: Surgery, Examination, Dental, Veterinary Size: Small, Medium, Large, Extra Large End User: Hospitals, Clinics, Laboratories, Pharmacies |
| Companies Covered | Top Glove Corporation, Hartalega Holdings, Ansell Ltd., Cardinal Health Inc., Kossan Rubber Industries, Medline Industries, Inc., Sempermed, Globus Group, Kanam Latex Industries Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Gloves Market Emerging Trajectories
Material science convergence with sterilization validation protocols is redefining performance benchmarks. Regulatory chemical restrictions and procurement model fragmentation are simultaneously compressing legacy platforms and opening premium niches.
Ultra-thin nitrile formulations are absorbing tactile sensitivity requirements previously met only by natural rubber latex. Cardiac and neurosurgical suites in tertiary hospitals are adopting 0.06-0.08 millimeter gauges at accelerated replacement cycles. This absorption is compressing polyisoprene's addressable premium segment while elevating nitrile's price ceiling.
REACH chemical restrictions on accelerators and plasticizers are forcing reformulation across European-bound production lines. ECHA substance of very high concern listings are targeting thiuram disulfides and specific phthalate plasticizers used in glove manufacturing. German and French hospital procurement consortia are now requiring full material disclosure certificates, shifting supplier qualification criteria.
Hospital buying cooperatives are consolidating surgical glove procurement into multi-year framework agreements with performance guarantees. Group purchasing organizations are displacing independent distributor relationships in North American acute care settings. This concentration is most visible in United States integrated delivery networks, where standardization committees now mandate single-source contracts across facility systems.
Surgical Gloves Market Segmentation
Material chemistry and sterility requirements create distinct procurement tiers across surgical glove categories. End-user scale and procedure risk profiles determine volume allocation and margin capture differently across each segmentation dimension.
Material Type:
Price-performance tradeoffs and allergy prevalence dictate material selection in hospital procurement committees.
- Nitrile:Acrylonitrile-butadiene rubber formulations deliver puncture resistance 3-5 times superior to latex. Cardiac and neurosurgical suites in tertiary hospitals specify ultra-thin 0.06-0.08 millimeter gauges, absorbing tactile sensitivity demand that previously required natural rubber. FDA powder-free mandates and REACH accelerator restrictions are compressing legacy latex capacity toward this synthetic platform.
- Latex:Natural rubber latex retains cost advantage in price-sensitive emerging markets despite Type I hypersensitivity concerns. Protein content reduction technologies and chlorination surface treatments extend viability in veterinary and non-sterile examination applications where allergy protocols are less stringent.
- Polyisoprene:Synthetic elastomer matching natural latex elasticity without allergenic proteins. Premium reconstructive surgery demand concentrates in German and French hospital consortia requiring full material disclosure certificates under ECHA substance restrictions.
- Vinyl:Polyvinyl chloride compounds serve lowest-risk examination and dental procedures where tactile precision requirements are minimal. EU single-use plastic directives threaten long-term regulatory viability for this material platform.
Volume sits with nitrile; growth tilts toward polyisoprene.
Application:
Procedure invasiveness determines sterility grade, thickness specification, and replacement frequency.
- Surgery:Sterile gamma-irradiated or ethylene-oxide-treated gloves command premium positioning through 0.06-0.20 millimeter thickness range. Modular packaging with procedure-specific instrument kits is restructuring procurement workflows in United States integrated delivery networks.
- Examination:Non-sterile applications face commoditization pressure from private-label entrants and distributor consolidation. Group purchasing organizations are displacing independent distributor relationships across North American acute care settings.
- Dental:Nitrile substitution accelerates in oral surgery suites where latex allergy protocols intersect with puncture risk from sharps. Smaller pack sizes and color-coded sizing support practice-level inventory management.
- Veterinary:Cost-optimized latex and vinyl formulations dominate livestock and companion animal procedures. Regulatory oversight remains less stringent than human medical applications, preserving material flexibility.
Margin concentrates in surgery; volume expansion runs through examination.
Size:
Hand geometry distribution across clinical workforces shapes SKU proliferation and inventory carrying costs.
- Medium:Standard fit for majority of clinical personnel across hospital and clinic settings. Procurement standardization committees favor bulk allocation to this specification to minimize SKU complexity.
- Large:Secondary volume concentration in male-dominated surgical specialties and veterinary applications. Ambulatory surgical center fragmentation is pulling toward flexible pack quantities rather than institutional bulk.
- Small:Pediatric nursing and specific Asian market workforces drive demand. Regional manufacturing scaling under India's PLI scheme is improving domestic availability.
- Extra Large:Niche specification serving orthopedic surgery and select veterinary procedures. Higher per-unit pricing reflects lower production run volumes and specialized mold requirements.
Procurement standardization favors medium; SKU proliferation pressures inventory systems across all sizes.
End User:
Scale and regulatory sophistication create tiered qualification barriers for supplier access.
- Hospitals:Acute care facilities generate deepest margin pools through multi-year framework agreements with performance guarantees. ISO 13485 certification and FDA quality system compliance are non-negotiable entry requirements.
- Clinics:Outpatient settings fragment procurement into smaller, higher-frequency orders. Flexible supply chain configurations and distributor relationships predominate over direct manufacturer contracts.
- Laboratories:Research and diagnostic applications prioritize chemical resistance and extended cuff designs. Accelerator-free chemistries are penetrating this segment through occupational skin-health compliance mandates.
- Pharmacies:Retail health settings serve consumer-directed examination glove demand with minimal sterility requirements. Price sensitivity and private-label substitution are most acute in this channel.
Revenue concentrates in hospitals; order frequency climbs fastest in clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Southeast Asian integrated manufacturing complexes while consumption gravitates toward hospital networks in North America and Europe. India's PLI scheme is redrawing this map by scaling domestic nitrile capacity to serve South Asian demand growth.
United States
Ambulatory surgical center expansion is fragmenting procurement into higher-frequency orders requiring flexible supply chain configurations. FDA powder-free mandates and updated quality system regulations are disqualifying legacy latex suppliers from federal hospital contracts. Integrated delivery networks in Texas and Florida are consolidating glove procurement into multi-year framework agreements with performance guarantees.
Germany
Tertiary hospital consortia in Bavaria and North Rhine-Westphalia are mandating full material disclosure certificates under ECHA substance of very high concern listings. REACH restrictions on thiuram accelerators are forcing reformulation of gloves bound for European distribution. The Emden medical device cluster hosts sterilization validation facilities serving German and Dutch hospital networks.
India
Domestic manufacturing capacity is scaling rapidly under production-linked incentive frameworks to reduce import dependence for surgical gloves. CDSCO medical device rules and BIS quality standards are tightening market access for foreign suppliers. Tamil Nadu and Gujarat industrial corridors are attracting nitrile production investments to serve South Asian hospital procurement.
Malaysia
Integrated manufacturing from raw latex to finished sterile packs sustains cost positioning for global export markets. Malaysian supply concentration creates geographic single-point vulnerability given over sixty percent of global nitrile glove capacity clusters in Southeast Asian facilities. The Klang Valley manufacturing belt maintains backward integration into acrylonitrile-butadiene rubber feedstock supply chains.
Brazil
Surgical glove penetration remains below North American benchmarks, creating whitespace for nitrile substitution in public health procurement. ANVISA regulatory pathways are extending market access timelines for non-Latin American manufacturers. São Paulo state hospital networks are consolidating purchases through regional buying cooperatives.
Surgical Gloves Market Vendor Landscape
The competitive structure tilts toward integrated Southeast Asian manufacturers with captive raw material supply. Tiered qualification barriers separate FDA-compliant premium suppliers from cost-optimized regional producers. Three archetypes dominate: vertically integrated nitrile specialists, accelerator-free chemistry innovators, and modular sterile kit packagers. Capacity expansion and strategic partnerships with group purchasing organizations represent the dominant competitive moves.
Within the integrated manufacturing tier, Top Glove Corporation and Hartalega Holdings exemplify Southeast Asian production scale. Ansell Ltd. occupies a position emphasizing occupational skin-health compliance and accelerator-free formulations for allergy-sensitive operating rooms. These three companies anchor distinct strategic vectors: raw material integration, ultra-thin nitrile performance, and regulatory-compliant chemistry platforms.
| Leading Market Players |
|---|
| Top Glove Corporation |
| Hartalega Holdings |
| Ansell Ltd. |
| Cardinal Health Inc. |
| Kossan Rubber Industries |
| Medline Industries, Inc. |
| Sempermed |
| Globus Group |
| Kanam Latex Industries Pvt. Ltd. |
| Others |
Supply Flow & Price Mechanics
United States integrated delivery networks and European hospital consortia concentrate procurement power into multi-year framework agreements, compressing supplier margins while rewarding ISO 13485-certified manufacturers with volume guarantees. This buyer concentration polarizes pricing between FDA-compliant premium tiers and cost-optimized regional production.
Pricing Analysis
Margin tightening in sterile surgical gloves reflects butadiene feedstock volatility and powder-free mandate compliance costs. Three-tier pricing structure across premium accelerator-free, standard nitrile, and economy latex levels separates cardiac surgery specifications from examination applications. Cost-down pressure accelerates as Indian PLI-subsidized domestic capacity undercuts Southeast Asian import pricing. Group purchasing organizations exhibit highest price sensitivity; tertiary hospital cardiac suites maintain lowest.
Supply Chain Analysis
FDA quality system regulation and EU MDR certification requirements gate market access for manufacturers seeking United States and European distribution. Geographic supply concentrates in Malaysia, Thailand, and India, with acrylonitrile-butadiene rubber, natural rubber latex, and gamma irradiation equipment as critical inputs. Single-source vulnerability persists given Malaysian nitrile capacity dominance. Distribution runs through group purchasing organizations and regional buying cooperatives rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical gloves market sits in a material-transition phase as ultra-thin nitrile formulations displace natural rubber latex in cardiac and neurosurgical suites previously reserved for polyisoprene.
For Market Incumbents: Cement accelerator-free chemistry leadership through thiuram-free formulation patents and ECHA compliance certification ahead of REACH substance restriction expansion. Deepen backward integration into butadiene feedstock supply to buffer petrochemical cycle margin compression. Lock multi-year sterile kit partnerships with United States integrated delivery networks to displace distributor intermediaries. For New Entrants and Emerging Players: The premium-economy price gap in Indian domestic procurement creates entry opportunity for CDSCO-compliant nitrile manufacturers under PLI subsidy frameworks. Target Tamil Nadu and Gujarat industrial corridor hospital networks with procedure-specific sterile packs bundling gloves and instrument sets. Pursue ANVISA regulatory qualification for Brazilian public health procurement whitespace. For Investors and Strategic Acquirers: The window for entry favors accelerator-free chemistry specialists with existing ECHA substance disclosure infrastructure and gamma irradiation validation capabilities. Long-term viability hinges on regulatory compliance moats rather than commodity scale. Watch FDA quality system regulation enforcement intensity as inflection signal for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Chemistry Patent Portfolio | ECHA REACH substance restrictions are disqualifying thiuram-containing formulations from European hospital contracts. |
| Backward Integration into Nitrile Feedstock | Butadiene price volatility compresses margin predictability for synthetic glove producers without captive supply. |
| Procedure-Specific Sterile Kit Packaging | Modular bundling with instrument sets captures premium positioning in United States cardiac surgical suites. |
| CDSCO Regulatory Qualification | India's PLI scheme favors domestic manufacturers meeting BIS quality standards for South Asian hospital networks. |
| Gamma Irradiation Validation Investment | Real-time dosimetry monitoring enables extended shelf-life claims for remote distribution channels. |
Methodological Framework
Trade databases, hospital procurement records, and regulatory filing repositories formed the secondary backbone for volume and pricing calibration. Primary interviews with GPO contracts managers, biomedical engineers, sterile processing directors, and nitrile manufacturing plant operators validated demand assumptions. Bottom-up facility-level procurement analysis triangulated against top-down trade flow estimates across the analysis window.
Historical trendline analysis of nitrile import volumes and sterile glove sterilization capacity utilization informed projection baselines. Segmentation modeling incorporated material chemistry, sterility grade, end-user scale, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for PLI scheme capacity addition timelines and EU MDR transition friction.
Underlying measurement precision varies by segment; sterile surgical applications carry tighter precision than examination glove commoditized tiers. Forecasts reflect assumptions about butadiene price stability and regulatory enforcement intensity that could shift with petrochemical cycles or FDA quality system updates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Micro Vials Market
Medical Supplies
Nipple Shield Market
Medical Supplies
Thermal Printable Wristband Market
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Elastic Orthopedic Tape Market
Medical Supplies
Disposable Sanitary Pad Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
North America Healthcare Packaging Market