
 Human Papilloma Virus Testing Market | 2026-2036
Human Papilloma Virus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Human Papilloma Virus Testing Market Foresight
A capital-intensity divergence between automated high-throughput platforms and manual point-of-care systems is rotating competitive advantage toward scaled molecular diagnostics manufacturers. QIAGEN N.V. leverages its sample-to-answer automation installed base to sustain recurring consumable revenue across European and Asian reference laboratories. F. Hoffmann-La Roche AG anchors its position through cobas platform integration with national screening programs in Germany and Brazil. Hologic, Inc. differentiates via its ThinPrep cytology-to-molecular workflow dominance in United States hospital networks.
Human Papilloma Virus Testing encompasses nucleic acid amplification and cytological methods that detect high-risk HPV genotypes in cervical specimens, typically targeting 14-18 oncogenic types through DNA or mRNA signal detection with clinical sensitivity thresholds exceeding 90 percent for CIN2+ lesions. The technology serves primary screening, triage of abnormal cytology, and post-treatment surveillance in gynecological oncology protocols. Real-Time PCR occupies the largest revenue share due to its regulatory validation depth and throughput economics in centralized laboratories. Next-Generation Sequencing is expanding fastest among research and surveillance applications where genotype-level resolution supports epidemiological tracking and vaccine efficacy studies. HPV mRNA Tests command premium positioning in triage applications where E6/E7 oncogene expression reduces false-positive burden relative to DNA-based methods.
The FDA governs HPV test approval through premarket notification and premarket authorization pathways requiring analytical and clinical validation data, while the EMA's In Vitro Diagnostic Regulation imposes post-market performance surveillance obligations that elevate compliance costs for European market access. WHO prequalification standards shape procurement eligibility for low- and middle-income country screening programs, directly influencing manufacturer prioritization of affordable assay formats. Stakeholders must monitor evolving primary screening interval recommendations from United States Preventive Services Task Force and European guidelines, as extended intervals between tests could compress volume growth even as test complexity and reimbursement per procedure rise.
Market Dynamics
Extended-interval primary screening protocols approved by the FDA are compressing test volumes while elevating reimbursement per procedure, forcing manufacturers to optimize high-throughput automation economics against point-of-care simplicity.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation:Post-market surveillance obligations elevate compliance costs for smaller competitors, consolidating share among scaled manufacturers with dedicated regulatory infrastructure.
- Diagnostic laboratories:Reference labs in Germany and Brazil are integrating HPV molecular testing into national cervical cancer screening programs, anchoring recurring consumable demand.
- WHO prequalification standards:Procurement eligibility requirements for low- and middle-income country programs are incentivizing affordable assay format development by leading manufacturers.
Market Restraints
- Reimbursement compression in United States hospital networks:CMS payment adjustments for molecular diagnostics are constraining margin expansion despite rising test complexity.
- Supply concentration in automated platform consumables:Locked-in reagent contracts with QIAGEN and Roche limit price competition and switching flexibility for mid-sized laboratories.
- Technical limitation of DNA-based false positives:High-risk HPV DNA detection without oncogene expression confirmation generates unnecessary colposcopy referrals, burdening healthcare systems.
Strategic Opportunities
- HPV mRNA E6/E7 oncogene expression assays:Triage applications in United States integrated health networks command premium positioning by reducing false-positive burden versus DNA methods.
- Next-Generation Sequencing convergence with epidemiological surveillance:Genotype-level resolution supports vaccine efficacy studies and variant tracking in research institutions across European reference laboratories.
- Point-of-care channel innovation:Manual testing systems are penetrating rural clinic networks in Brazil where centralized laboratory infrastructure remains underdeveloped.
Industry Challenges
- Molecular diagnostics skill gap:Certified laboratory technologists capable of operating sample-to-answer automation are scarce in mid-sized United States hospital networks.
- Legacy cytology workflow integration:ThinPrep specimen handling systems require reconfiguration to accommodate parallel molecular testing, complicating capital planning.
- Extended-interval screening compliance:Patient adherence to 5-year primary HPV testing cycles remains inconsistent, threatening program effectiveness metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Papilloma Virus Testing Market |
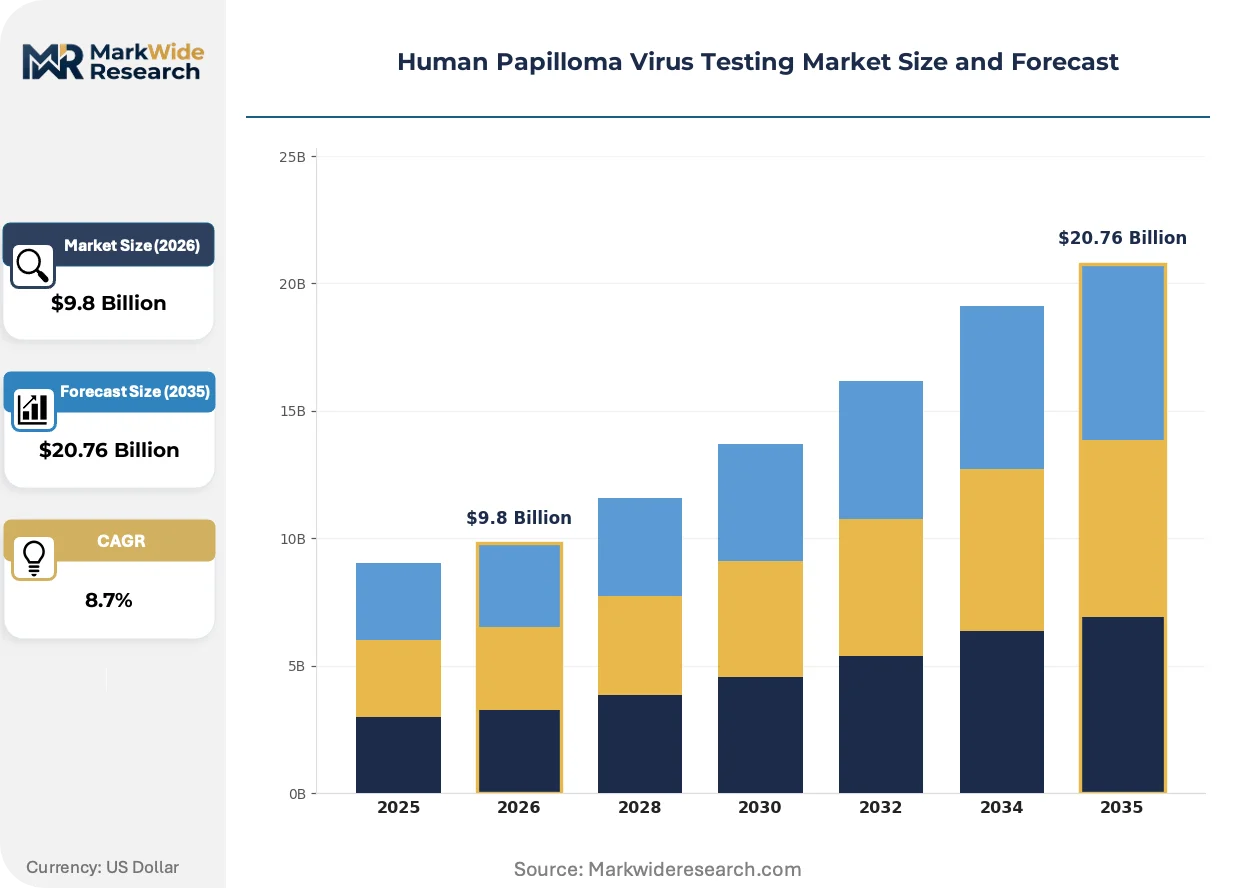
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleic Acid Test, Pap Test, HPV DNA Test, HPV mRNA Test End User: Hospitals, Diagnostic Laboratories, Ambulatory Surgical Centers, Clinics Technology: Real-Time PCR, Next-Generation Sequencing, Hybrid Capture, Lateral Flow Assay Application: Screening, Diagnosing, Surveillance, Research |
| Companies Covered | QIAGEN N.V., F. Hoffmann-La Roche AG, Hologic, Inc., Abbott Laboratories, Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Danaher Corporation, bioMérieux S.A., Seegene Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Papilloma Virus Testing Market Shifts & Advancements
HPV testing technology is fragmenting along throughput and site-of-care dimensions, with centralized automation diverging from distributed molecular platforms. This split is reshaping competitive positioning and R&D allocation across the value chain.
Real-Time PCR technology is bifurcating the market into high-volume reference laboratory installations and lower-throughput clinic-based systems. Large diagnostic laboratories in Germany and the United States are consolidating on cobas and QIAsymphony platforms for screening program economics. This technology split is compressing mid-tier manual assay margins while enabling premium positioning for integrated sample-to-answer workflows.
The FDA's extended-interval primary HPV screening approval is restructuring clinical workflows and reimbursement frameworks in United States integrated delivery networks. Laboratories must now optimize for episodic high-value testing rather than annual volume accumulation. Hospital networks with captive pathology services are responding by consolidating send-out molecular testing in-house.
Specimen procurement patterns are rotating toward self-collection kits in European screening programs, bypassing traditional gynecological clinic channels. National health systems in the Netherlands and Sweden are piloting mailed sampling to address screening access disparities. This channel shift is most visible in Nordic countries where digital health infrastructure supports remote result delivery and automated follow-up scheduling.
Human Papilloma Virus Testing Market Segmentation
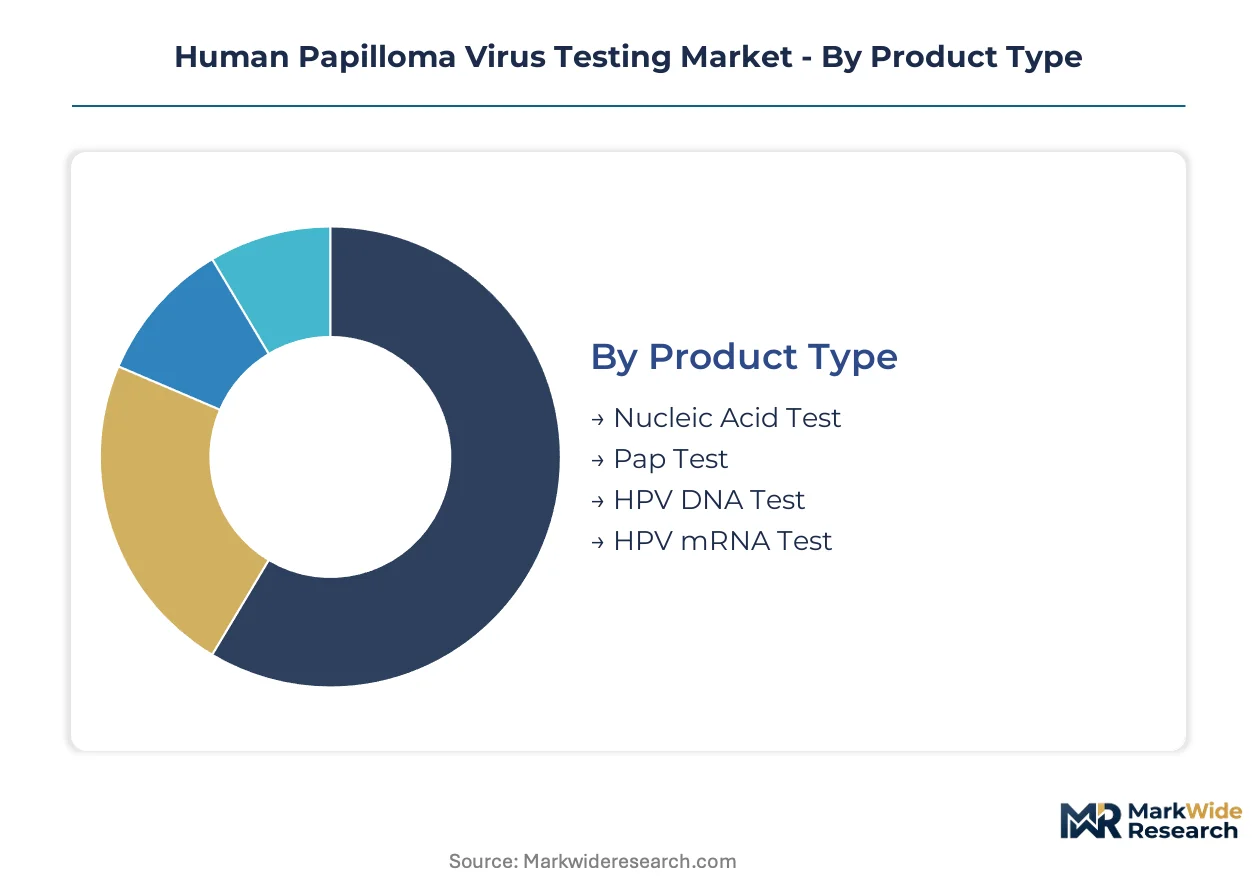
HPV testing segments diverge sharply by channel economics and site-of-care requirements. Centralized laboratories favor high-throughput automated platforms, while point-of-care networks prioritize manual simplicity and rapid turnaround.
Product Type:
Nucleic acid amplification products flow predominantly through diagnostic laboratories with captive molecular infrastructure, whereas cytology-based formats retain hospital pathology channel dominance.
- Nucleic Acid Test:Polymerase chain reaction and transcription-mediated amplification methods detect viral genetic material with analytical sensitivity exceeding 90 percent for high-risk genotypes. United States reference laboratories anchor demand as extended-interval screening protocols elevate test complexity and reimbursement per procedure.
- HPV mRNA Test:E6/E7 oncogene expression assays reduce false-positive burden versus DNA detection by confirming active viral carcinogenesis. Integrated health networks in the United States command premium positioning for triage applications where unnecessary colposcopy referrals burden healthcare systems.
- Pap Test:Conventional cytology remains embedded in legacy screening workflows requiring skilled morphological interpretation.
- HPV DNA Test:Direct high-risk genotype detection without oncogene expression confirmation generates volume in cost-sensitive public health programs.
By volume, HPV DNA Test leads. By growth pace, HPV mRNA Test is ahead.
End User:
Customer concentration varies by capital intensity, with automated platform economics favoring scaled institutions over distributed care sites.
- Diagnostic Laboratories:High-throughput cobas and QIAsymphony installations in Germany and Brazil anchor recurring consumable revenue through national screening program integration. Reference lab consolidation in the United States compresses mid-tier manual assay margins while enabling premium positioning for sample-to-answer workflows.
- Hospitals:Captive pathology services are consolidating send-out molecular testing in-house as episodic high-value testing replaces annual volume accumulation. ThinPrep cytology-to-molecular workflow dominance complicates capital planning for parallel testing infrastructure.
- Ambulatory Surgical Centers:Limited on-site molecular capability drives specimen referral to centralized laboratories.
- Clinics:Rural networks in Brazil adopt manual point-of-care systems where laboratory infrastructure remains underdeveloped.
Diagnostic Laboratories capture the largest revenue share. Clinics are expanding most quickly.
Technology:
Regulatory validation depth and throughput economics determine competitive positioning across the technology spectrum.
- Real-Time PCR:Fluorescence-based amplification monitoring occupies the largest revenue share due to FDA and EMA regulatory validation depth. Large diagnostic laboratories in Germany and the United States consolidate on validated platforms for screening program economics.
- Next-Generation Sequencing:Genotype-level resolution supports vaccine efficacy studies and variant tracking in research institutions. European reference laboratories pilot epidemiological surveillance applications where comprehensive genomic data justifies higher per-test cost.
- Hybrid Capture:Signal amplification without nucleic acid target amplification retains position in resource-limited settings.
- Lateral Flow Assay:Visual readout simplicity enables point-of-care deployment without instrumentation.
Real-Time PCR dominates current revenue. Next-Generation Sequencing shows the steepest expansion trajectory.
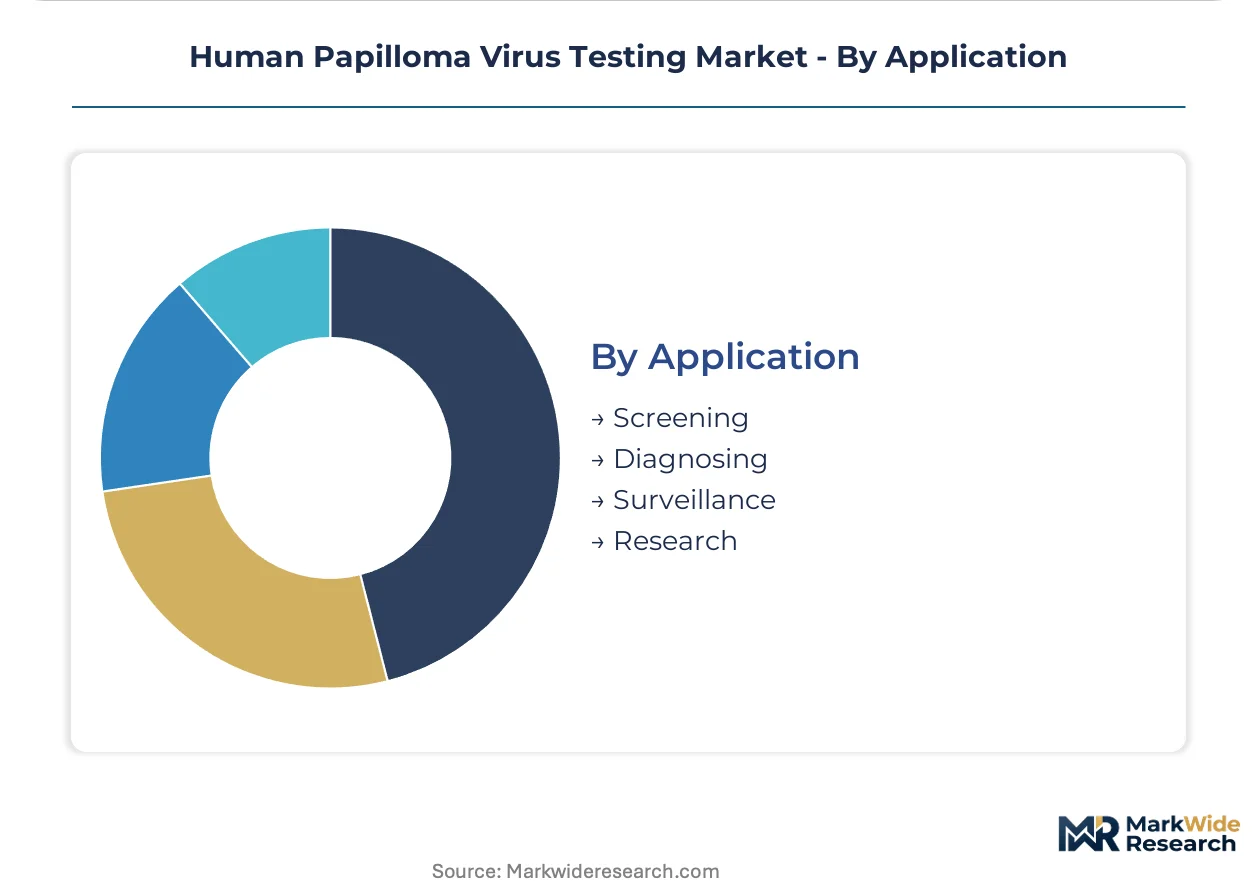
Application:
Clinical utility and reimbursement frameworks segment demand by intended use case and patient population.
- Screening:Primary cervical cancer prevention programs in the United States, Germany, and Brazil drive volume through population-scale testing mandates. FDA approval of extended-interval protocols restructures workflows toward episodic high-value testing.
- Diagnosing:Triage of abnormal cytology results commands premium positioning where HPV mRNA assays reduce false-positive burden. United States integrated health networks prioritize oncogene expression confirmation to optimize colposcopy resource allocation.
- Surveillance:Post-treatment monitoring protocols require high analytical sensitivity for residual disease detection.
- Research:Academic institutions leverage comprehensive genotype data for vaccine development and epidemiological modeling.
Screening generates the highest absolute volume. Research applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in molecular diagnostics favor net-importing markets with consolidated laboratory infrastructure. The United States absorbs premium HPV testing platforms while Germany and Brazil anchor European and Latin American demand through national screening mandates. Manufacturing concentration in Switzerland, Germany, and the Netherlands supplies automated systems to diagnostic laboratories worldwide.
United States
Integrated health networks and large reference laboratories drive volume consolidation for HPV molecular testing. FDA approval of extended-interval primary screening protocols restructures clinical workflows toward episodic high-value procedures. The Boston-Cambridge biotech corridor hosts assay development operations serving hospital network procurement.
Germany
National cervical cancer screening program integration anchors recurring consumable demand for automated platforms. EMA In Vitro Diagnostic Regulation imposes post-market surveillance obligations that elevate compliance costs for market access. The Rhine-Main metropolitan area concentrates reference laboratory infrastructure for high-throughput molecular diagnostics.
Brazil
Public health program expansion generates demand for affordable HPV assay formats in resource-limited settings. ANVISA regulatory pathways shape procurement eligibility for national screening initiatives. São Paulo state anchors diagnostic laboratory concentration serving Southeast Brazil's population centers.
China
Domestic screening program scale-up drives localization requirements for HPV testing manufacturing. NMPA premarket authorization pathways require analytical and clinical validation data for platform approval. The Yangtze River Delta clusters IVD production capacity serving hospital network procurement.
India
WHO prequalification standards incentivize affordable assay development for low- and middle-income country programs. CDSCO regulatory frameworks govern import and domestic manufacturing of molecular diagnostics. Maharashtra state concentrates diagnostic laboratory networks serving urban screening access.
Human Papilloma Virus Testing Market Competitive Landscape
Concentration sits with scaled molecular diagnostics manufacturers possessing dedicated regulatory infrastructure and automated platform installed bases. The market structure tilts toward oligopoly, with three to four companies commanding reference laboratory channel dominance through locked-in consumable contracts. Strategic archetypes include sample-to-answer automation specialists, cytology-to-molecular workflow integrators, and national screening program anchor partners. Competitive moves center on platform ecosystem expansion and geographic screening program anchoring rather than price-based rivalry.
Among European-headquartered molecular diagnostics specialists, QIAGEN N.V., F. Hoffmann-La Roche AG, and bioMérieux S.A. occupy positions representing distinct automation philosophies. QIAGEN exemplifies the sample-to-answer archetype with consumable-recurring revenue models. Roche anchors the integrated platform-screening program nexus through national contract structures. bioMérieux sits within the infectious disease molecular testing tradition extending into HPV applications. United States-based Hologic, Inc. represents the cytology-to-molecular workflow integration archetype with hospital pathology channel dominance.
| Leading Market Players |
|---|
| QIAGEN N.V. |
| F. Hoffmann-La Roche AG |
| Hologic, Inc. |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| bioMérieux S.A. |
| Seegene Inc. |
| Others |
Supply & Pricing Matrix
Manual point-of-care assay substitution for automated high-throughput platforms is redrawing supply geography toward Brazil and India while compressing premium pricing power in United States hospital networks. This input substitution simultaneously fragments procurement channels and elevates cost competition in resource-limited screening programs.
Pricing Analysis
Diagnostic laboratory buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with E6/E7 mRNA assays commanding premium positioning against DNA-based alternatives. Price differentiation rests on FDA validation depth and sample-to-answer automation integration, while reimbursement compression from CMS payment adjustments intensifies margin pressure in mid-tier manual formats. United States integrated health networks exhibit lowest price sensitivity due to captive pathology economics, whereas Brazilian public health programs drive aggressive cost negotiation.
Supply Chain Analysis
Strategic stockpiling of PCR reagents and consumables dominates inventory strategy among German and United States reference laboratories, contrasting with just-in-time procurement in smaller clinic networks. Manufacturing concentration in Switzerland, Germany, and the Netherlands feeds automated platform production, with critical dependencies on fluorophore chemistries, polymerase enzymes, and microfluidic cartridges. Single-source vulnerability in locked-in reagent contracts with scaled manufacturers elevates supply risk. Distribution runs through direct sales forces to national screening program anchor sites, bypassing traditional distributor channels for high-throughput installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against liquid biopsy-based cervical cancer screening substitutes that threaten to displace HPV molecular testing in premium triage applications. Substitution defense requires platform ecosystem deepening and workflow integration lock-in.
For Market Incumbents: Shield installed base revenue through consumable contract extension and sample-to-answer automation upgrades that embed switching costs. Deepen backward integration into reagent manufacturing to offset supply concentration risk from single-source fluorophore suppliers. Prioritize FDA validation investment for extended-interval screening protocols to maintain reimbursement tier positioning against emerging mRNA assay competitors. For New Entrants and Emerging Players: Differentiate on point-of-care simplicity and rapid turnaround for rural clinic networks in Brazil and India where laboratory infrastructure remains underdeveloped. Target ambulatory surgical centers with manual lateral flow formats that bypass capital-intensive automation requirements. Pursue WHO prequalification pathway as primary go-to-market mechanism for low- and middle-income country procurement eligibility. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scaled manufacturers with dedicated regulatory infrastructure and national screening program contracts. Long-term viability hinges on platform ecosystem breadth rather than single-assay dominance. Monitor FDA extended-interval screening compliance rates as inflection indicator for volume trajectory revision.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance unlocks European reference laboratory access and recurring consumable revenue streams. |
| Hospital System Partnership | Captive pathology service integration secures in-house molecular testing consolidation and ThinPrep workflow interoperability. |
| Reimbursement Strategy | CMS coverage determination alignment optimizes episodic high-value testing economics under extended-interval protocols. |
| Software Companion Development | Digital result delivery infrastructure enables self-collection kit pilot programs in Nordic national health systems. |
| Long-term Supply Agreement | Locked-in reagent contracts with German and Brazilian national screening programs anchor predictable consumable demand. |
Research Methodology
Desk research of FDA premarket authorization filings, EMA In Vitro Diagnostic Regulation guidance documents, and WHO prequalification standards preceded structured interviews with reference laboratory directors, hospital pathology chiefs, and national screening program procurement officers. Primary fieldwork with diagnostic platform engineers and regulatory affairs specialists at scaled manufacturers was cross-validated against secondary sources including CMS reimbursement databases, ANVISA registration records, and GPO contract repositories. Bottom-up test volume modeling and top-down market sizing were triangulated to establish segmentation boundaries.
Variance decomposition across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and reimbursement per procedure trends, with specific inputs including extended-interval screening compliance assumptions and national program expansion timelines. Modeled outputs reflect automation adoption curves and point-of-care penetration rates by geography.
Forecasts assume regulatory continuity in FDA premarket authorization pathways and EMA post-market surveillance obligations; material policy shifts would require re-modeling. Specific risks include WHO prequalification standard revisions affecting low- and middle-income country procurement eligibility, and CMS payment adjustment unpredictability constraining molecular diagnostics margin expansion. Revision becomes warranted when extended-interval screening compliance crosses thresholds that alter volume trajectory assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
North America and Europe Preclinical Medical Device Testing Services Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Syphilis Testing Market
Testing Services
Cholesterol Test Market
Testing Services
Medical Device Testing Services Market
Testing Services
Nicotine Testing Market
Testing Services
Ovulation Test Kit Market
Testing Services
Europe Esoteric Testing Market
Testing Services
INR Test Meter Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market