
 Dehydrated Culture Media Market | 2026-2036
Dehydrated Culture Media Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Culture Media Market Analysis
European dehydrated media producers is realigning capacity toward pharmaceutical-grade certification to serve stricter quality demands. Thermo Fisher Scientific leverages its distribution network to sustain dominance in North American clinical laboratory supply chains. Merck KGaA anchors its position through backward integration into raw material purification, while HiMedia Laboratories competes aggressively on price in emerging Asian markets.
Dehydrated culture media are shelf-stable, powdered formulations of nutrients, salts, and growth factors that reconstitute with water to support microbial cultivation under controlled conditions. These products typically require precise pH buffering between 6.8 and 7.4 and sterility assurance through gamma irradiation or dry heat treatment to eliminate false positives in diagnostic applications. Bacterial culture media occupies the largest revenue share due to entrenched use in pharmaceutical sterility testing, while ready-to-dissolve packets represent the fastest-expanding packaging format as laboratories prioritize workflow efficiency and reduced preparation error. Research laboratories command substantial volume through academic and government funding cycles, though food testing facilities are gaining share from intensified supply chain safety mandates.
FDA oversight of diagnostic device manufacturing and EPA guidelines for environmental microbiology testing shape formulation standards and validation requirements in the United States. The European Medicines Agency enforces Good Manufacturing Practice compliance for culture media used in pharmaceutical release testing, creating barrier conditions for uncertified suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to anticipate reformulation investments and regional approval timelines.
Market Dynamics
Pharmaceutical batch testing volumes are expanding faster than laboratory headcount, forcing quality control departments to standardize on pre-formulated dehydrated media that slash preparation time and error rates. This labor-capacity mismatch is the dominant structural force compressing workflows toward ready-to-use formats.
Growth Catalysts
- FDA Rapid Microbial Methods Guidance:The updated framework validates dehydrated formulations for automated enumeration systems, accelerating replacement of in-house prepared media in United States pharmaceutical facilities.
- Contract Testing Laboratories:Third-party microbiology service providers in the United States are consolidating purchasing power and mandating supplier certification to ISO 11133, pulling volume toward standardized dehydrated products.
- Gamma Irradiation Sterilization:This terminal sterilization method eliminates false-positive risks from heat-labile contaminants, making irradiated dehydrated media indispensable for sterility testing workflows.
Market Restraints
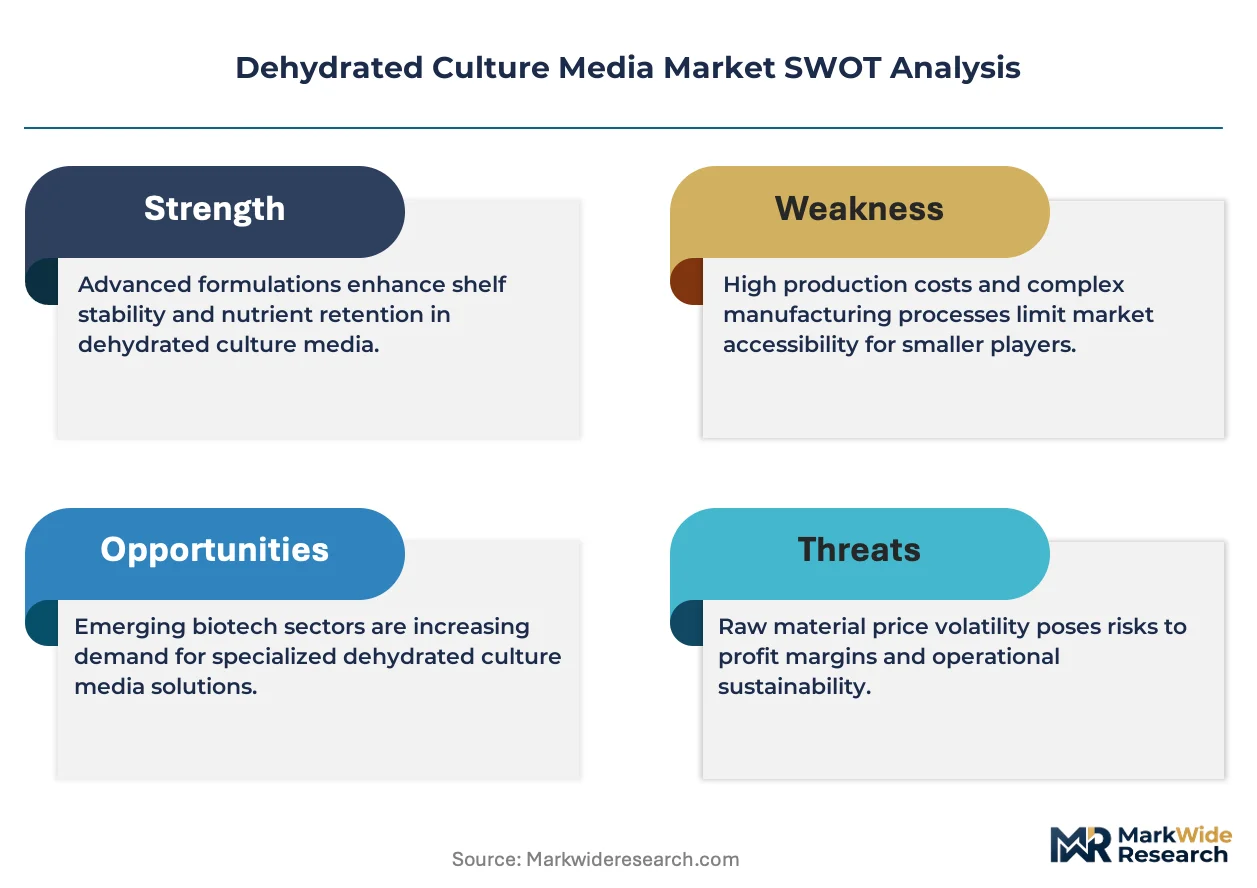
- Peptone Supply Concentration:Hydrolyzed protein sources for bacterial media derive predominantly from European animal by-product processors, exposing formulators to input cost volatility and BSE-related trade restrictions.
- EMA GMP Certification Barriers:The European Medicines Agency mandates pharmaceutical-grade culture media certification that smaller Asian manufacturers cannot readily obtain, freezing out uncertified suppliers from release testing applications.
- Ready-to-Use Liquid Media Substitution:Pre-poured plates and bottled broths eliminate reconstitution steps entirely, capturing workflow-critical applications where preparation time exceeds dissolution economics.
Strategic Opportunities
- India Biopharmaceutical Expansion:CDSCO-mandated quality upgrades at domestic vaccine and biosimilar facilities are creating first-time demand for pharmacopeia-compliant dehydrated media as manufacturers exit in-house preparation.
- Environmental Microbiology Automation:Convergence of laser-induced fluorescence detection with dehydrated membrane filtration media enables same-day coliform enumeration, opening municipal water utility contracts.
- Single-Use Packet Formats:Pre-weighed aliquots in tear-open sachets reduce weighing errors and traceability documentation, aligning with lean laboratory methodologies spreading through academic research clusters.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent pH buffering specifications between USP, EP, and JP standards force manufacturers to maintain parallel inventory SKUs, complicating production scheduling and regional compliance.
- Skilled Media Preparation Technician Shortage:Consolidation of clinical microbiology training programs has shrunk the pipeline of technicians capable of validating in-house media performance against reference strains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Culture Media Market |
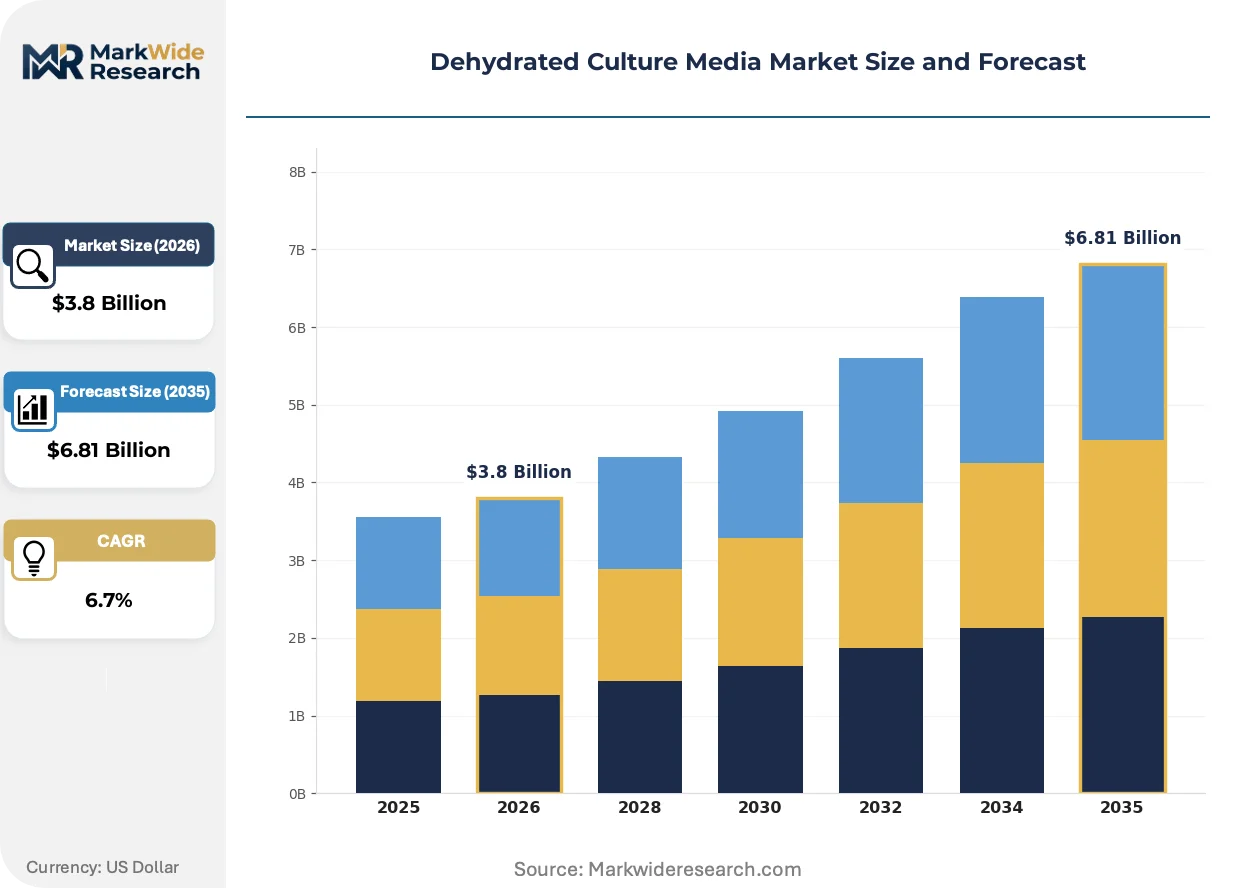
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial Culture Media, Fungal Culture Media, Nutrient Agar, Selective Media End User: Research Laboratories, Pharmaceutical Companies, Clinical Laboratories, Food Testing Facilities Packaging Type: Dried Powder, Ready-to-Dissolve Packets, Pre-Mixed Solutions, Bottled Media Application: Microbial Analysis, Quality Control, Research & Development, Environmental Testing |
| Companies Covered | HiMedia Laboratories, bioMérieux, Thermo Fisher Scientific, Hardy Diagnostics, Neogen Corporation, Merck KGaA, Bio-Rad Laboratories, Sigma-Aldrich, BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Culture Media Market Emerging Trajectories
Synthetic biology workflows and point-of-care diagnostics are rewriting material specifications for culture media, pushing formulators toward animal-component-free and rapid-resuscitation chemistries that depart from century-old recipes.
Chromogenic enzyme substrates are rewriting detection protocols in clinical laboratories. These synthetic molecules release colored or fluorescent products upon specific enzymatic cleavage by target organisms. Large hospital systems in the United States are adopting chromogenic agars for direct specimen plating, bypassing enrichment steps. This substrate technology is rewriting the economics of diagnostic microbiology by compressing turnaround times from days to hours.
REACH authorization requirements for boric acid and other traditional buffer components are forcing European manufacturers to reformulate classic media recipes. The European Chemicals Agency's restriction roadmap now covers multiple salts historically used in pH stabilization. Formulators serving pharmaceutical release testing are accelerating substitution trials with Good's buffers and other REACH-exempt alternatives to maintain uninterrupted supply.
Laboratory purchasing consortia are consolidating procurement decisions for dehydrated media across multi-site health systems. These centralized buying entities negotiate multi-year sole-source agreements that bundle media with validation support and inventory management services. The United Kingdom's National Health Service Supply Chain exemplifies this aggregation, where framework contracts now cover dehydrated culture media alongside diagnostic reagents and consumables.
Dehydrated Culture Media Market Segmentation
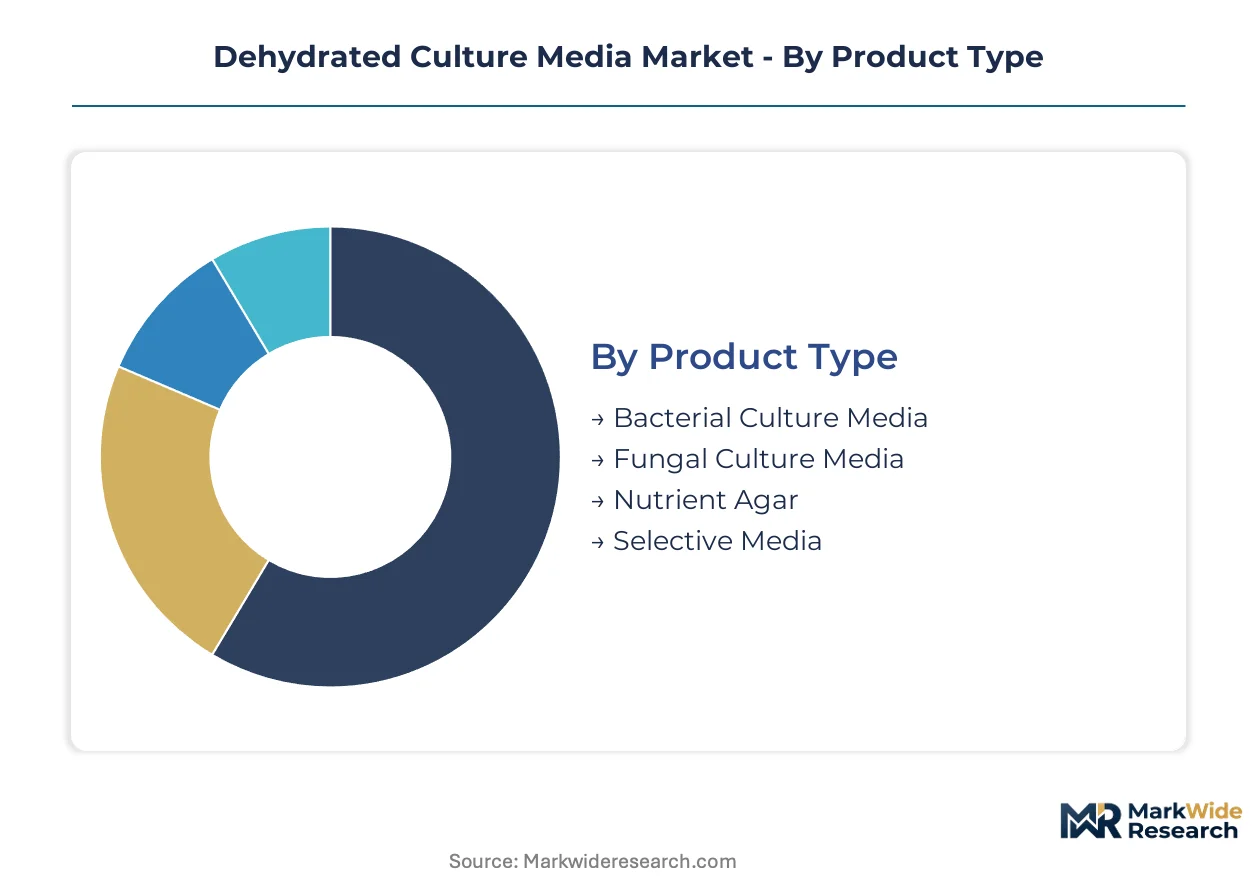
Dehydrated culture media segmentation reveals how formulation chemistry, packaging logistics, and end-user workflows intersect to determine purchasing decisions. Manufacturers must align product architectures with the divergent validation requirements of pharmaceutical release testing versus academic research environments.
Product Type:
Supply concentration among European peptone processors tilts competitive advantage toward formulators with captive raw material access or long-term supply agreements.
- Bacterial Culture Media:Powdered nutrient formulations support aerobic and anaerobic bacterial cultivation across diagnostic and industrial applications. Pharmaceutical sterility testing departments in the United States consume the largest volumes, driven by FDA-mandated batch release protocols that require documented media performance against reference strains.
- Fungal Culture Media:Specialized formulations incorporate lower pH buffers and selective antimicrobials to suppress bacterial competition during mold and yeast isolation. Clinical mycology laboratories in Germany and France are expanding usage as hospital-acquired fungal infections rise in immunocompromised patient populations.
- Nutrient Agar:General-purpose growth medium combining peptone, beef extract, and agar for non-fastidious organism cultivation.
- Selective Media:Differential formulations containing inhibitory agents that suppress non-target flora while permitting pathogen detection.
Today's leader: Bacterial Culture Media. Tomorrow's challenger: Selective Media.
End User:
Cost tier stratification separates pharmacopeia-certified purchasers from price-sensitive academic buyers who prioritize volume discounts over validation documentation.
- Research Laboratories:University and government-funded facilities drive bulk powder purchases for protocol development and strain characterization. Funding cycles at the National Institutes of Health and European Research Council create demand spikes that strain manufacturer inventory planning.
- Pharmaceutical Companies:Quality control departments require gamma-irradiated, certified media with full traceability documentation for regulatory submissions. United States biopharmaceutical manufacturers are consolidating suppliers to reduce audit burden and secure multi-year framework agreements.
- Clinical Laboratories:Hospital-based microbiology services process patient specimens for diagnostic confirmation and antimicrobial susceptibility testing.
- Food Testing Facilities:Commercial laboratories and in-house quality departments verify supply chain safety against Salmonella, Listeria, and coliform specifications.
Pharmaceutical Companies command premium pricing power. Food Testing Facilities are climbing the fastest as supply chain safety mandates intensify.
Packaging Type:
Volume economics favor large-format containers for high-throughput facilities, while single-use formats capture lean laboratory methodologies prioritizing error reduction over unit cost.
- Dried Powder:Bulk containers of 500g to 25kg support high-volume reconstitution at centralized preparation facilities. Contract testing laboratories in India and Brazil prefer this format for cost efficiency in high-throughput environmental monitoring.
- Ready-to-Dissolve Packets:Pre-weighed aliquots in moisture-barrier sachets eliminate weighing errors and accelerate workflow throughput. Academic consortia in the United Kingdom are adopting this format to reduce technician training requirements and standardize preparation across multi-site studies.
- Pre-Mixed Solutions:Concentrated liquid concentrates requiring dilution rather than full reconstitution from powder.
- Bottled Media:Glass or plastic containers of dehydrated powder with wide-mouth access for scoop dispensing.
Dried Powder dominates procurement value. Ready-to-Dissolve Packets are expanding most quickly as labor costs outpace material savings.
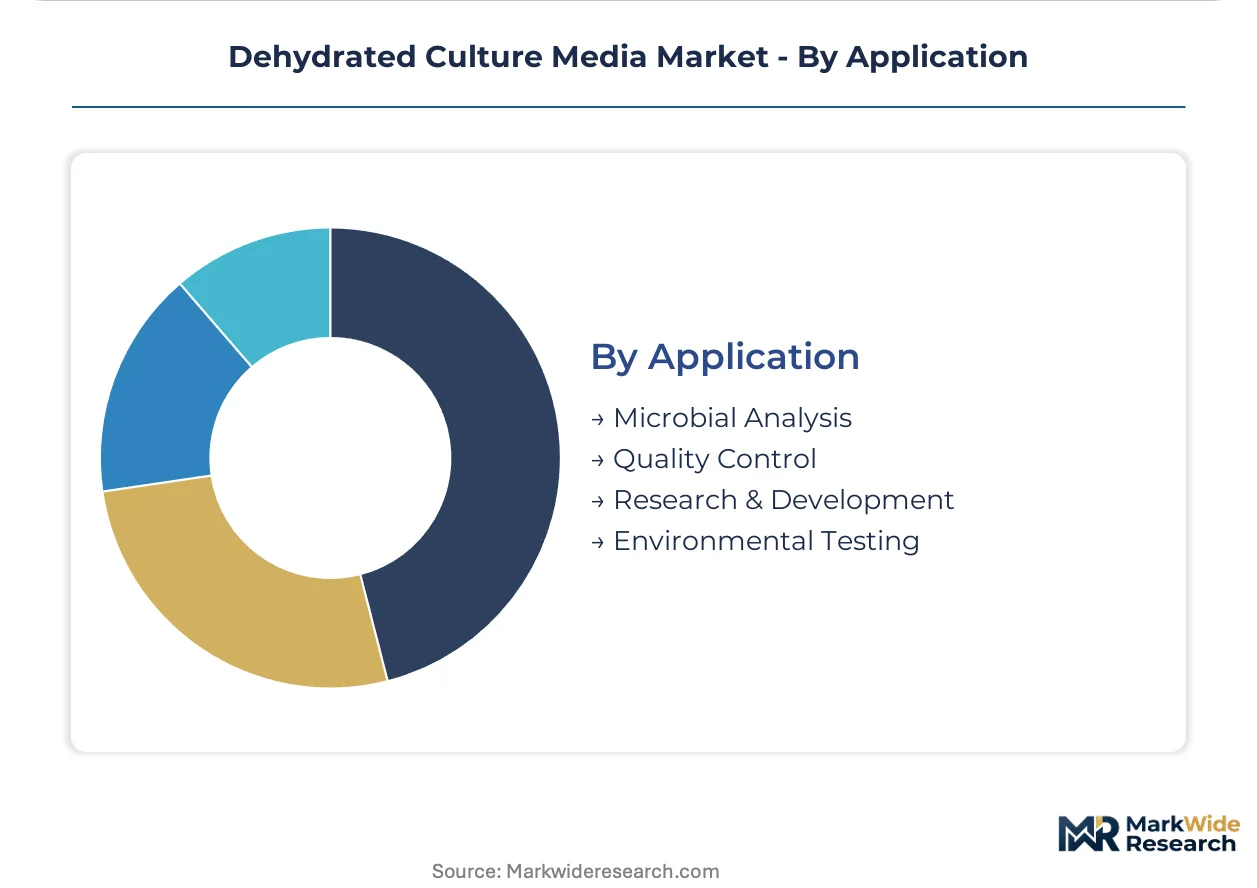
Application:
Customer maturity varies sharply: environmental testing represents an emerging automation frontier, while quality control demands century-old validation rigor.
- Microbial Analysis:Enumeration and identification workflows in clinical, food, and environmental specimens. Municipal water utilities in Japan are deploying membrane filtration with dehydrated media for coliform monitoring under METI-enforced safety standards.
- Quality Control:Pharmaceutical batch release testing, raw material verification, and in-process monitoring. EMA GMP certification requirements exclude uncertified suppliers from European pharmaceutical applications, creating protected market segments for established manufacturers.
- Research & Development:Strain engineering, synthetic biology, and novel antimicrobial discovery in academic and biotechnology settings.
- Environmental Testing:Soil, water, and air microbiology for regulatory compliance and ecological assessment.
Quality Control anchors revenue stability. Environmental Testing shows the steepest expansion trajectory as automation enables same-day enumeration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States pharmaceutical manufacturers consume dehydrated media volumes that dwarf German demand, yet Indian biopharmaceutical expansion is compressing the gap through CDSCO-mandated quality upgrades.
United States
FDA rapid microbial methods guidance and biopharmaceutical production expansion drive procurement. The agency's updated framework validates dehydrated formulations for automated enumeration systems. Greater Boston's contract testing laboratory cluster consolidates purchasing power toward ISO 11133-certified suppliers.
Germany
EMA GMP certification requirements and REACH buffer component restrictions reshape formulation standards. The European Chemicals Agency's boric acid authorization roadmap forces substitution trials with Good's buffers. Baden-Württemberg's pharmaceutical manufacturing belt demands certified media with full traceability documentation.
India
CDSCO-mandated quality upgrades at vaccine and biosimilar facilities create first-time pharmacopeia-compliant demand. Domestic manufacturers exit in-house preparation as regulatory scrutiny intensifies. Maharashtra's biopharmaceutical corridor anchors capacity expansion for export-oriented sterile media production.
Japan
METI-enforced municipal water safety standards accelerate membrane filtration media adoption for coliform monitoring. Laser-induced fluorescence detection convergence enables same-day enumeration contracts. Kanto region utilities deploy automated systems requiring validated dehydrated formulations.
United Kingdom
NHS Supply Chain framework contracts aggregate dehydrated media procurement across multi-site health systems. Centralized buying entities negotiate sole-source agreements bundling validation support services. Academic consortia in the Midlands adopt ready-to-dissolve packets to standardize preparation across distributed research networks.
Dehydrated Culture Media Market Vendor Landscape
United States producers anchor one tier; European specialists hold certification-advantaged positions in pharmaceutical-grade segments. Market structure tilts toward consolidated supply relationships where multi-year framework agreements lock in volume commitments. Three archetypes dominate: diversified life science conglomerates with distribution scale, mid-cap formulators with backward integration into raw material purification, and price-competitive regional suppliers serving emerging markets. Capacity realignment and pharmacopeial harmonization investments represent the dominant competitive moves.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning through captive distribution networks and upstream control over peptone supply chains. HiMedia Laboratories occupies a distinct archetype as a price-competitive specialist targeting emerging Asian markets where certification barriers remain lower. These three anchors illustrate how geographic origin and structural configuration determine competitive access rather than product differentiation alone.
| Leading Market Players |
|---|
| HiMedia Laboratories |
| bioMérieux |
| Thermo Fisher Scientific |
| Hardy Diagnostics |
| Neogen Corporation |
| Merck KGaA |
| Bio-Rad Laboratories |
| Sigma-Aldrich |
| BD |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical quality control departments in the United States and contract testing laboratory clusters in Greater Boston anchor procurement volumes toward long-term framework agreements that bundle validation support with volume commitments. This buyer concentration tilts pricing power toward suppliers holding EMA GMP certification and ISO 11133 compliance, creating tiered access based on regulatory credentialing rather than commodity cost alone.
Pricing Analysis
Capacity additions in India and Germany are reshaping price floors for pharmacopeia-grade dehydrated media. Three-tier pricing structure across premium, standard, and economy levels separates gamma-irradiated pharmaceutical-grade formulations from research-grade powders and private-label alternatives. Price differentiation rests on certification tier and traceability documentation depth. Cost compression in the research-grade tier is intensifying because academic consortia are consolidating purchasing power. Food testing facilities exhibit the highest price sensitivity due to margin pressure in commercial laboratory services, while pharmaceutical quality control departments prioritize supply security over unit cost.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle high-volume sterility testing demand, while distribution through laboratory supply consortia serves fragmented academic buyers. Geographic supply concentrates in Germany, India, and the United States for finished formulations, with peptone raw material processing anchored in European animal by-product facilities. Raw material dependencies include hydrolyzed protein sources, agar from seaweed harvesters, and REACH-compliant buffer salts. Single-source vulnerability in European peptone supply exposes formulators to BSE-related trade restrictions and input cost volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA rapid microbial methods guidance and EMA GMP certification requirements continuously elevate compliance barriers that favor incumbent suppliers with validation infrastructure.
For Market Incumbents: Cement market position by deepening backward integration into peptone purification and securing multi-year sole-source agreements with United States contract testing laboratory clusters. The threat of ready-to-use liquid media substitution in workflow-critical applications demands accelerated packet-format innovation. Certification investment in CDSCO-compliant production for India's biopharmaceutical corridor represents the priority defensive lever. For New Entrants and Emerging Players: CDSCO-mandated quality upgrades in India open a window for first-time suppliers of pharmacopeia-compliant dehydrated media as domestic vaccine manufacturers exit in-house preparation. White-space targets include single-use packet formats for academic consortia and environmental microbiology automation for Japanese municipal water utilities. A certification-first go-to-market angle bypasses direct price competition with established European suppliers. For Investors and Strategic Acquirers: Life science conglomerates with captive distribution networks are the most active acquirer in this space, seeking mid-cap formulators with backward integration into raw material supply. Long-term viability hinges on pharmacopeial harmonization investments that reduce parallel SKU maintenance. The signal to watch is consolidation velocity among United States contract testing laboratories, which determines purchasing power concentration and supplier margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| EMA GMP Certification Investment | Unlocks pharmaceutical release testing revenue in Baden-Württemberg's manufacturing belt. |
| Backward Integration into Peptone Supply | Insulates margin from European animal by-product processor concentration and BSE trade restrictions. |
| Single-Use Packet Format Launch | Aligns with NHS Supply Chain lean laboratory methodologies and reduces technician training burdens. |
| CDSCO-Compliant Capacity Expansion | Captures first-time demand from Maharashtra's vaccine and biosimilar facilities exiting in-house preparation. |
| Environmental Microbiology Automation Partnership | Enables same-day coliform enumeration contracts with Kanto region municipal water utilities under METI standards. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with quality control directors at pharmaceutical manufacturers, procurement managers at contract testing laboratories, regulatory affairs specialists, and laboratory supply distributors. Secondary validation draws from FDA guidance documents, EMA GMP certification registries, CDSCO quality upgrade notifications, and pharmacopeial standard harmonization records. Bottom-up demand modeling from end-user consumption patterns triangulates against top-down supply-side capacity assessments.
Granularity-level modeling disaggregates volume and value across bacterial versus fungal culture media, pharmaceutical versus research end-use segments, and packet versus bulk powder packaging formats throughout the projection horizon. CAGRs derive from segment-specific growth trajectories weighted by regional biopharmaceutical production capacity expansion and regulatory compliance mandate intensity. Forecast inputs include laser-induced fluorescence detection adoption curves in environmental testing and REACH authorization timelines for boric acid buffer substitutions.
Revisions become necessary when pharmacopeial harmonization agreements between USP, EP, and JP materially advance or when peptone supply disruptions from European animal by-product processors exceed historical volatility bands. Forecasts reflect assumptions regarding regulatory certification timeline stability and raw material trade flow continuity. Periodic stress-testing of base assumptions against CDSCO enforcement intensity and FDA rapid microbial methods validation throughput is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Disposable Face Mask Market
Medical Supplies
Hospital Consumables Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
Safety Needles Market
Medical Supplies
Global Synthetic Absorbable Sutures Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Europe Ostomy Care and Accessories Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Casting and Splints Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Medical Liners Market