
 Aluminum Fluoride Market | 2026-2036
Aluminum Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Fluoride Market Intelligence
A transition from long-term single-sourcing to diversified multi-sourcing is pivoting procurement strategies for major aluminum smelters seeking supply chain resilience. Rio Tinto Plc leverages its vast integrated mining and smelting operations to maintain a degree of captive supply for its facilities. In contrast, specialized chemical producers like Hunan Nonferrous Fluoride Chemical Group and Fluorsid S.p.A. compete on factors such as product purity, consistent granulation, and logistical reliability for the merchant market.
Aluminum fluoride is an inorganic compound, chemical formula AlF3, that serves as a crucial additive in electrometallurgy. Its primary industrial purpose is to act as a flux in the Hall-Héroult process, lowering the melting point of alumina and increasing the electrolyte's conductivity. The aluminum smelting application overwhelmingly drives market volume, requiring specific powder and granular forms for optimal performance. Demand from the glass industry, while smaller, specifies high-purity grades of aluminum fluoride to act as an opacifier and fluxing agent in specialty glass formulations.
Manufacturers navigate a complex regulatory environment defined by frameworks such as the European Union's REACH for chemical registration and China's MEE standards for industrial pollutants. These regulations impose strict limits on fluoride emissions during production and handling, directly impacting operational costs and technology choices. The central strategic decision for producers involves managing the price volatility of fluorspar, the primary raw material, while investing in process efficiencies to meet tightening environmental mandates.
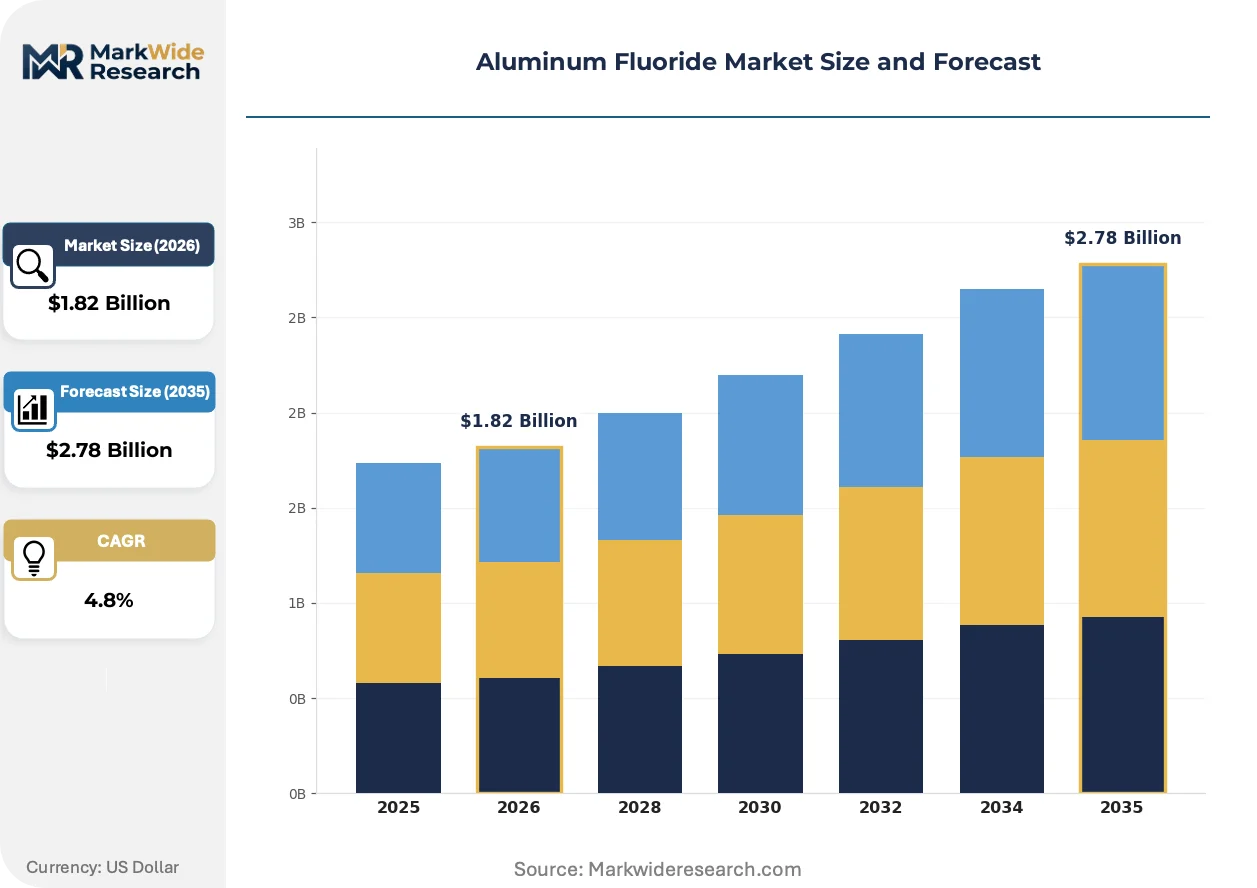
Market Dynamics
The market's central dynamic is the tension between the aluminum industry's immense, geographically concentrated demand and a global regulatory push for stricter environmental controls on fluoride production, directly influencing technology choices and raw material sourcing strategies.
Growth Catalysts
- Primary Aluminum Expansion:Continued investment in new primary aluminum smelting capacity, particularly in the Middle East and India, directly creates new, large-volume demand points for aluminum fluoride as an essential electrolyte additive.
- Efficiency Mandates:China's dual carbon goals incentivize smelters to improve energy efficiency, a target supported by using higher-purity aluminum fluoride grades that enhance electrolyte conductivity and reduce overall energy consumption per ton of aluminum.
- Advanced Glass Formulations:Demand from the specialty glass sector for high-purity aluminum fluoride acts as a catalyst for product innovation, as it is used as an opacifier and fluxing agent in manufacturing high-performance glass.
Market Restraints
- Raw Material Volatility:The price and availability of acid-grade fluorspar, the primary feedstock for aluminum fluoride production, are subject to significant volatility, directly impacting producer cost structures and margin stability.
- Regulatory Compliance Costs:Adherence to stringent environmental frameworks, such as the EU's REACH and China's MEE standards on industrial pollutants, requires substantial capital investment in emission abatement technologies, increasing operational expenses.
- Logistical Complexity:The handling and transportation of both fluorspar and aluminum fluoride, which is a fine powder, involve complex logistics and safety protocols, adding cost and risk to the supply chain.
Strategic Opportunities
- Fluorine Recovery Technologies:Developing and scaling technologies to recover fluorine from industrial waste streams, such as from phosphate fertilizer production, offers a path to create fluorspar-free production routes and mitigate raw material risks.
- High-Purity Niche Applications:Investment in production capabilities for ultra-high purity aluminum fluoride can open new revenue streams in non-metallurgical applications like advanced catalysts, specialty ceramics, and optical materials.
- Regional Production Hubs:Establishing localized aluminum fluoride production facilities near major aluminum smelting clusters outside of China, such as in North America or the Persian Gulf, can capture demand from buyers prioritizing supply chain security.
Industry Challenges
- Capital Expenditure Intensity:The construction of new aluminum fluoride plants or the retrofitting of existing ones to meet modern environmental standards for hydrogen fluoride containment represents a significant capital hurdle for producers.
- Specialized Talent Scarcity:A shortage of chemical engineers and technicians with deep expertise in hydrofluoric acid chemistry and high-temperature furnace operations poses an operational challenge for plant management and expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Fluoride Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.78 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Paste Application: Aluminum Smelting, Glass Industry, Ceramics, Welding Flux End User: Manufacturers, OEMs, Distributors, Research Institutions Packaging Type: Bags, Drums, Bulk Containers, Totes |
| Companies Covered | Industries Chimiques du Fluor, Rio Tinto Plc, Fluorsid S.p.A., Gulf Fluor, Hunan Nonferrous Fluoride Chemical Group, Do-Fluoride Chemicals Co., Ltd., PhosAgro Group, MilliporeSigma, Alufluoride Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Fluoride Market Strategic Shifts & Innovations
Producers are navigating a landscape defined by a dual push for process sustainability and supply chain resilience. Innovations focus on reducing environmental footprints and decoupling production from volatile raw material inputs, altering the competitive basis from pure cost to technological efficiency.
Dry-process granulation technology, which produces a denser and more uniform aluminum fluoride product, is gaining favor over traditional wet-process methods. Aluminum smelters are adopting these granular forms at a steady rate due to their superior handling properties, reduced dust emissions, and better performance in smelting pots. This technology is expanding into a standard for premium product offerings, allowing producers to differentiate on physical characteristics and environmental health and safety benefits.
The European Union's Green Deal and its related industrial emissions directives are setting rigorous new benchmarks for fluorinated compound releases. These regulations compel both aluminum fluoride producers and their primary customers, aluminum smelters, to invest in best-available-technologies for emission capture and abatement. The aluminum smelting segment is most affected, with compliance pressures driving a preference for higher-quality flux agents that optimize consumption and minimize waste.
A clear behavioral change is occurring as major buyers move away from single-source dependencies toward a diversified portfolio of suppliers. This strategic shift replaces long-term exclusive contracts with a multi-sourcing model to mitigate geopolitical risks and enhance negotiation leverage. The trend is most pronounced among smelters in Europe and North America, who are actively qualifying second and third suppliers to build a more resilient supply chain.
Aluminum Fluoride Market Segmentation
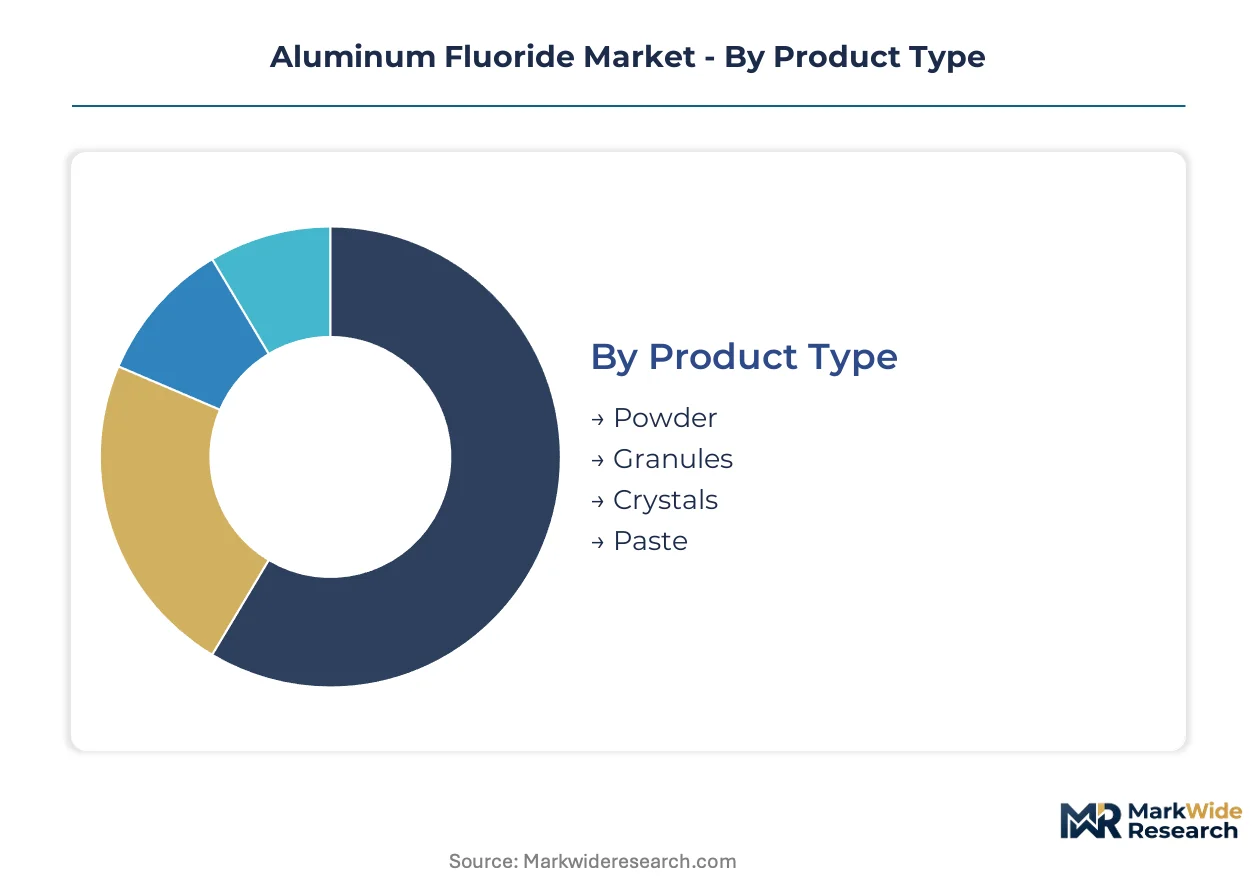
Segmentation analysis provides a granular view of the aluminum fluoride market, dissecting its various components to reveal underlying demand patterns and supply dynamics. Understanding these distinct segments helps producers tailor product offerings, optimize distribution channels, and navigate specific regulatory requirements across different end-use sectors. This detailed breakdown informs strategic decision-making for market participants.
Product Type:
Product type segmentation highlights the diverse physical forms of aluminum fluoride, each engineered for specific industrial requirements and processing methods.
- Powder:Powdered aluminum fluoride is a fine, high-surface-area material, commonly used as a flux agent due to its rapid dissolution properties. China's extensive primary aluminum production relies heavily on powder forms for cost-effective electrolyte management and widespread availability.
- Granules:Granular aluminum fluoride consists of uniform, dense particles, offering superior handling characteristics and reduced dust generation compared to powder. Aluminum smelters in Europe favor granular forms for their improved performance in Hall-Héroult cells and compliance with environmental health and safety standards.
- Crystals:Crystalline aluminum fluoride, often produced for specific chemical reactions or smaller-scale applications, offers high purity and controlled morphology.
- Paste:Aluminum fluoride paste, a less common form, finds niche applications where a viscous consistency is required for specialized chemical processes.
Powder leads on scale; Granules leads on momentum.
Application:
The application segment details the primary industrial uses for aluminum fluoride, reflecting its functional versatility across various manufacturing processes.
- Aluminum Smelting:Aluminum fluoride serves as a critical electrolyte additive in the Hall-Héroult process, lowering alumina's melting point and increasing conductivity. This application overwhelmingly drives market volume, particularly in the Middle East and India, where new capacity is expanding.
- Glass Industry:The glass industry utilizes high-purity aluminum fluoride as an opacifier and fluxing agent in specialty glass formulations, including optical and technical glass. Demand from this sector mandates stringent purity specifications and consistent product quality for advanced formulations.
- Ceramics:Aluminum fluoride acts as a flux in ceramic manufacturing, facilitating lower firing temperatures and enhancing material properties for specific technical ceramics.
- Welding Flux:In welding, aluminum fluoride is incorporated into flux formulations to improve arc stability and shield molten metal from atmospheric contamination.
Aluminum smelting applications command the largest volume, while the glass industry exhibits a steady demand for specialized grades.
End User:
End-user segmentation delineates the primary customer types procuring aluminum fluoride, illustrating distinct purchasing patterns and supply chain roles.
- Manufacturers:Manufacturers, primarily large-scale aluminum smelters and specialty glass producers, directly consume aluminum fluoride as a raw material in their industrial processes. These entities often engage in long-term contracts to secure stable supply for continuous operations.
- Distributors:Distributors act as intermediaries, purchasing aluminum fluoride in bulk and supplying smaller quantities or specialized grades to a diverse customer base. Their role is critical in reaching fragmented markets and managing regional logistics for various industrial buyers.
- OEMs:Original Equipment Manufacturers (OEMs) integrate aluminum fluoride into their products, such as specialized welding electrodes or advanced catalysts, for resale.
- Research Institutions:Research institutions acquire aluminum fluoride for experimental purposes, including material science studies and process optimization in laboratory settings.
Manufacturers represent the largest direct consumers of aluminum fluoride, with distributors playing a critical role in market reach.
Packaging Type:
Packaging type segmentation reflects the logistical requirements and volume considerations for transporting and storing aluminum fluoride across the supply chain.
- Bags:Bags, typically ranging from 25kg to 1000kg, provide flexible and manageable packaging for aluminum fluoride powder or granules, suitable for smaller-scale operations or specific batch processes. This packaging type is prevalent for merchant market sales and diverse customer needs.
- Bulk Containers:Bulk containers, including large sacks or specialized railcars, are employed for high-volume shipments of aluminum fluoride, primarily serving major aluminum smelters. This method optimizes transportation efficiency and reduces handling costs for large industrial consumers.
- Drums:Drums offer robust containment for aluminum fluoride, often preferred for international shipping or when enhanced protection against moisture is required.
- Totes:Intermediate bulk containers (IBCs), or totes, provide a reusable and efficient option for transporting moderate volumes of aluminum fluoride to various industrial sites.
Bulk containers facilitate high-volume shipments for large smelters, while bags offer flexibility for diverse buyer needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aluminum fluoride market exhibits a distinct regional dynamic, where production often migrates due to varying environmental compliance costs and raw material access. This regulatory arbitrage influences investment decisions and supply chain configurations, particularly between regions with stringent emission standards and those prioritizing industrial expansion. Major demand centers for primary aluminum production drive localized consumption patterns.
China
China's immense primary aluminum production capacity generates the largest volume demand for aluminum fluoride as a flux agent. The nation's dual carbon goals and MEE standards compel producers to adopt cleaner technologies and higher-purity grades. Smelters in the Xinjiang and Inner Mongolia regions are expanding capacity, requiring substantial and consistent aluminum fluoride supply.
United Arab Emirates
The United Arab Emirates sees sustained demand from its expanding aluminum smelting sector, driven by government initiatives to diversify the economy. Environmental regulations, including local industrial emissions standards, influence the adoption of advanced flux agents. Major smelters in Abu Dhabi and Dubai prioritize reliable, high-volume supply for continuous operations.
India
India's growing aluminum industry fuels a rising demand for aluminum fluoride, supported by infrastructure development and manufacturing growth. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial chemicals, impacting product specifications. New smelting projects in Odisha and Gujarat represent significant future consumption points.
Germany
Germany's aluminum fluoride consumption is characterized by a preference for granular forms, driven by the European Union's Green Deal and REACH regulations. These frameworks mandate reduced emissions and enhanced worker safety in industrial processes. Chemical production hubs in Bavaria and North Rhine-Westphalia focus on high-purity materials for specialized applications.
United States
The United States market emphasizes supply chain security and product quality for its established aluminum smelting and specialty glass industries. EPA regulations on fluoride emissions influence production and handling practices for both domestic and imported materials. Aluminum producers in the Pacific Northwest and Ohio Valley seek consistent, high-performance flux agents.
Aluminum Fluoride Market Key Industry Players
Established producers occupy the standard tier, serving the high-volume aluminum smelting sector, while emerging entrants pursue niche applications and sustainable production methods. The market structure exhibits a tiered consolidation, with a few large integrated players and numerous specialized chemical manufacturers. Strategic archetypes include vertically integrated raw material suppliers and pure-play chemical processors. Capacity expansion and strategic partnerships represent dominant competitive moves.
On the premium-tier vector, Fluorsid S.p.A. exemplifies a specialized chemical producer focusing on product purity and consistent granulation for the merchant market. Rio Tinto Plc represents a vertically integrated mining and smelting giant, maintaining a degree of captive supply for its extensive operations. Hunan Nonferrous Fluoride Chemical Group, a China-based entity, occupies a position among large-scale producers serving the immense domestic aluminum industry.
| Leading Market Players |
|---|
| Industries Chimiques du Fluor |
| Rio Tinto Plc |
| Fluorsid S.p.A. |
| Gulf Fluor |
| Hunan Nonferrous Fluoride Chemical Group |
| Do-Fluoride Chemicals Co., Ltd. |
| PhosAgro Group |
| MilliporeSigma |
| Alufluoride Ltd. |
| Others |
Cost & Logistics Intelligence
Acid-grade fluorspar price volatility significantly influences aluminum fluoride pricing across the supply chain, cascading into differentiated contract terms for major smelters and merchant market buyers.
Pricing Analysis
Input cost pass-through remains a primary determinant of aluminum fluoride pricing, especially for producers reliant on open market fluorspar. The market largely operates on a contract-based long-term offtake model for large smelters, complemented by spot sales for smaller or intermittent demand. Price differentiation stems from product purity, with high-purity grades commanding premiums, and geographic delivery costs impacting regional competitiveness. Pricing softness in standard grades stems from oversupply in certain regions. Large aluminum smelters exhibit lower price sensitivity for high-quality, consistent supply, while smaller glass industry buyers are more sensitive to fluctuations.
Supply Chain Analysis
Direct-to-manufacturer channels handle the bulk of aluminum fluoride distribution, particularly for large-scale aluminum smelters. Geographic supply concentration centers heavily on China, which also dominates fluorspar extraction, along with emerging production in the Middle East and India. The supply chain relies heavily on acid-grade fluorspar as its primary raw material, with hydrogen fluoride as an intermediate. A key structural risk is the single-source vulnerability to fluorspar supply, exacerbated by geopolitical tensions and environmental regulations. Distributors play a crucial role in reaching fragmented glass and ceramics industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum fluoride market offers geographic-arbitrage opportunities, as environmental compliance costs in the EU significantly exceed those in certain Asian production hubs, influencing operational siting decisions.
For Market Incumbents:
Deploy process efficiency investments to counter rising raw material costs and tightening environmental regulations. Vertically integrated players should deepen captive supply of fluorspar to insulate against price volatility and secure consistent feedstock. Consolidate production capacity in regions with favorable regulatory landscapes to maintain cost competitiveness against smaller, agile players. Invest in advanced granulation technologies to meet the evolving quality demands from European and North American smelters.
For New Entrants and Emerging Players:
Fluorine recovery technologies represent a technology-first wedge for new entrants, enabling fluorspar-free production routes and mitigating raw material risks. Target niche, high-purity applications like specialty ceramics or optical materials where performance outweighs volume considerations. A direct-to-customer technical sales approach, emphasizing product innovation and environmental benefits, can penetrate markets seeking advanced formulations. Focus on establishing localized production hubs near major aluminum smelting clusters outside of China to capture demand for supply chain security.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized chemical producers possessing advanced environmental abatement technologies and diversified raw material sourcing. Long-term viability hinges on companies that can navigate stringent global environmental mandates while ensuring consistent product quality. Acquisition targets should be mid-sized firms with established relationships in high-growth regions like India or the Middle East. The signal to watch is the successful commercialization of alternative fluorine sources, reducing dependence on fluorspar.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Middle East | Gulf Fluor expands production capabilities to serve growing aluminum smelting demand in the UAE. |
| Fluorspar-Free Production R&D | Do-Fluoride Chemicals invests in fluorine recovery to reduce reliance on volatile raw material inputs. |
| High-Purity Product Line Development | Fluorsid S.p.A. introduces ultra-high purity grades for specialty glass and catalyst applications. |
| Multi-Sourcing Supply Chain Agreements | Rio Tinto Plc secures diverse fluorspar suppliers to enhance resilience against geopolitical risks. |
| Advanced Granulation Technology Adoption | Hunan Nonferrous implements dry-process granulation for superior product handling and environmental benefits. |
Research Approach
Direct dialogue with chemical plant managers, procurement leads at aluminum smelters, distribution channel partners, and R&D directors informed the qualitative grounding. This primary research was rigorously validated against secondary sources including customs data, chemical industry association reports, and company 10-K filings. The approach integrated both bottom-up market sizing and top-down validation, ensuring comprehensive data triangulation. Stakeholder insights provided critical context for market dynamics and competitive landscape.
A bottom-up analytical lens was applied to build market size estimates, aggregating demand from key end-use industries like aluminum smelting and specialty glass. Segmentation dimensions modeled include product type, application, end-user, packaging type, and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected future demand, considering new capacity additions. Industry-specific forecast inputs included primary aluminum production forecasts and fluorspar supply-demand balances across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to raw material price volatility and evolving environmental regulations. Projections reflect a set of base assumptions regarding technological advancements and geopolitical stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Rolled Steel Motor Market
Metals
Reconditioned Steel Drums Market
Metals
Japan Aluminium Powder Market
Metals
Base Metals Market
Metals
Russia Metal Fabrication Market
Metals
316 Stainless Steel Container Market
Metals
North America Electrical Steel Market
Metals
Titanium Market
Metals
Nickel Oxide Target Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Silver Enamel Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Global Aluminium Wire Rod Market
Metals
High-End Copper Foil Market
Metals
Stainless Steel Sheet Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market