
 Stainless Steel Sheet Market | 2026-2036
Stainless Steel Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Sheet Market Analysis
Multi-source procurement is shifting toward consolidated mill-direct contracts across the stainless steel sheet supply base. POSCO leverages captive chromium sourcing to sustain cost discipline in austenitic grades. Acerinox S.A. anchors European distribution through specialized service centers in Spain and Belgium. Jindal Stainless Group dominates Indian flat-rolled supply for kitchenware and railway coach applications.
Stainless steel sheet denotes flat-rolled corrosion-resistant alloy strip, typically containing 10.5% minimum chromium by mass, produced via continuous hot rolling above recrystallization temperature or cold rolling for tighter dimensional tolerance and brighter surface finish. The material serves primarily in environments requiring oxidation resistance, hygiene compliance, or structural longevity under chemical exposure. Grade 304 occupies the largest volume share due to its versatility across food processing and architectural cladding, while 316 commands premium positioning in marine and pharmaceutical applications where molybdenum-enhanced pitting resistance justifies higher unit economics. Cold-rolled sheet carries superior margin pools versus hot-rolled commodity tonnage, though hot-rolled output sustains greater absolute throughput in heavy-gauge construction and tank fabrication.
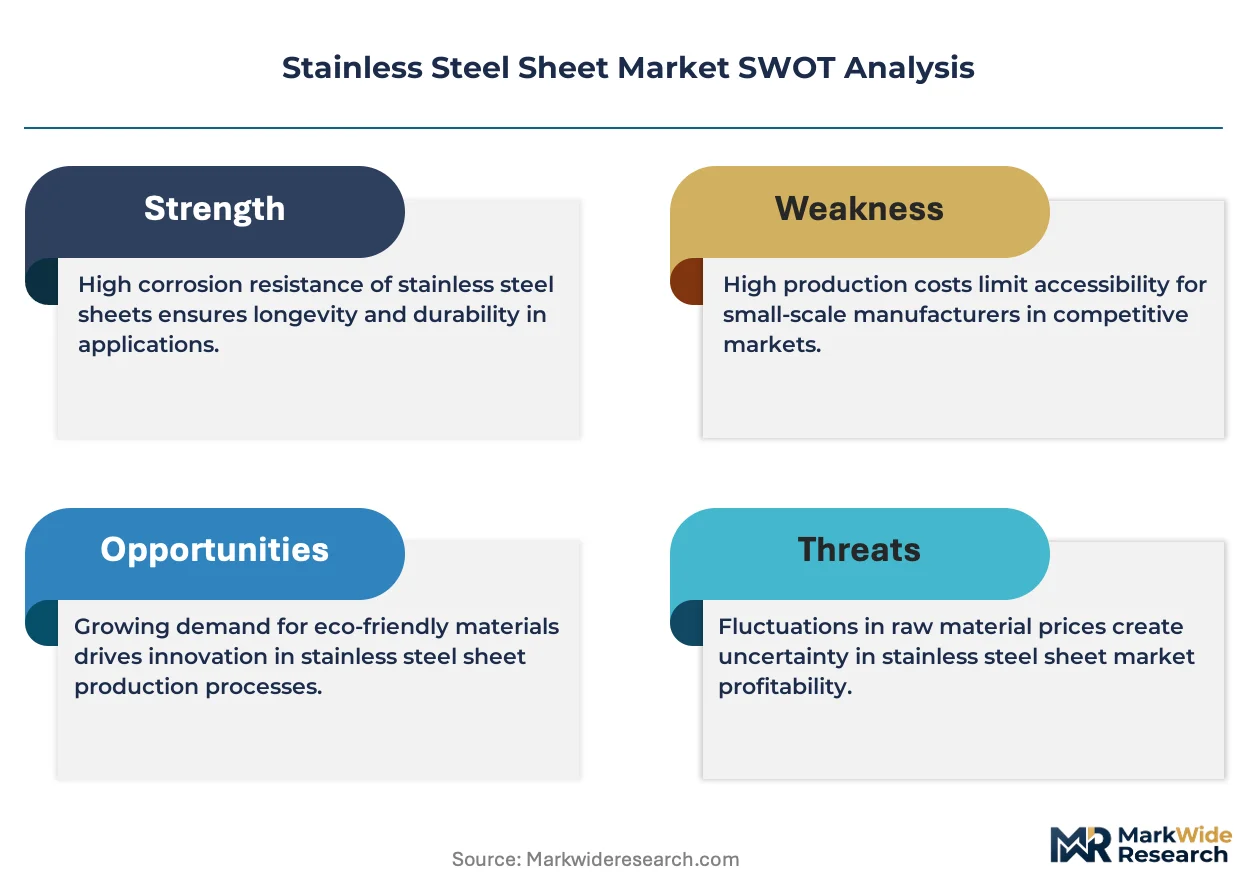
EU REACH and RoHS frameworks restrict hexavalent chromium surface treatments, redirecting specification toward trivalent passivation and electropolished alternatives. China's GB standards and MEE emissions protocols tighten effluent controls for pickling and annealing lines, raising compliance capital requirements for integrated producers. ASTM A240 and EN 10088-2 govern international cross-border acceptance, with third-party certification becoming a non-negotiable market access condition for Middle Eastern and Southeast Asian project contractors. Stakeholders must track alloy surcharge volatility against nickel and molybdenum exchange movements while assessing backward integration into ferrochrome or scrap processing as a hedge against raw material cyclicality.
Market Dynamics
Aerospace OEMs are consolidating procurement around mill-direct austenitic supply contracts, compressing distributor margins while elevating specification rigor for corrosion-resistant grades in airframe and engine applications.
Growth Catalysts
- EU Green Deal Emissions Benchmarks:European mills face tightening carbon intensity caps that favor electric arc furnace routes and scrap-fed production, redirecting capital toward low-carbon sheet capacity.
- Marine Infrastructure Renewal:Shipbuilders in South Korea and Japan specify molybdenum-enhanced 316L for ballast tanks and deck structures, extending service intervals in saltwater environments.
- Pharmaceutical Hygiene Mandates:FDA and EMA aseptic processing guidelines drive specification of electropolished 304 and 316L for bioreactor vessels and cleanroom cladding.
Market Restraints
- Nickel-Molybdenum Price Volatility:London Metal Exchange alloy surcharges swing with Indonesian ore export policies and South African ferrochrome supply disruptions, compressing mill margin predictability.
- Chromium Ore Concentration:Kazakhstan and South Africa control over seventy percent of metallurgical-grade chromite reserves, creating single-point vulnerability for austenitic grade cost structures.
- Ferritic Substitution in Automotive:409 and 439 grades displace austenitic sheet in exhaust systems where corrosion requirements permit lower alloy content and reduced unit economics.
Strategic Opportunities
- Hydrogen Storage Vessel Fabrication:German and Dutch energy infrastructure developers specify high-pressure 316L and duplex grades for electrolyzer and pipeline applications, opening premium tonnage channels.
- India PLI Scheme for Specialty Steel:Production-linked incentives cover cold-rolled stainless capacity expansion for railway coach and kitchenware export manufacturing.
- Digital Service Center Networks:Automated slitting and blanking operations with real-time inventory visibility enable just-in-time delivery to tier-two appliance and automotive stampers.
Industry Challenges
- Pickling Line Emissions Compliance:China's MEE effluent protocols require closed-loop acid regeneration and fume capture retrofits, demanding capital deployment without immediate yield recovery.
- Third-Party Certification Timelines:ASTM A240 and EN 10088-2 accreditation for Middle Eastern project contractors extends qualification cycles by six to nine months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Sheet Market |
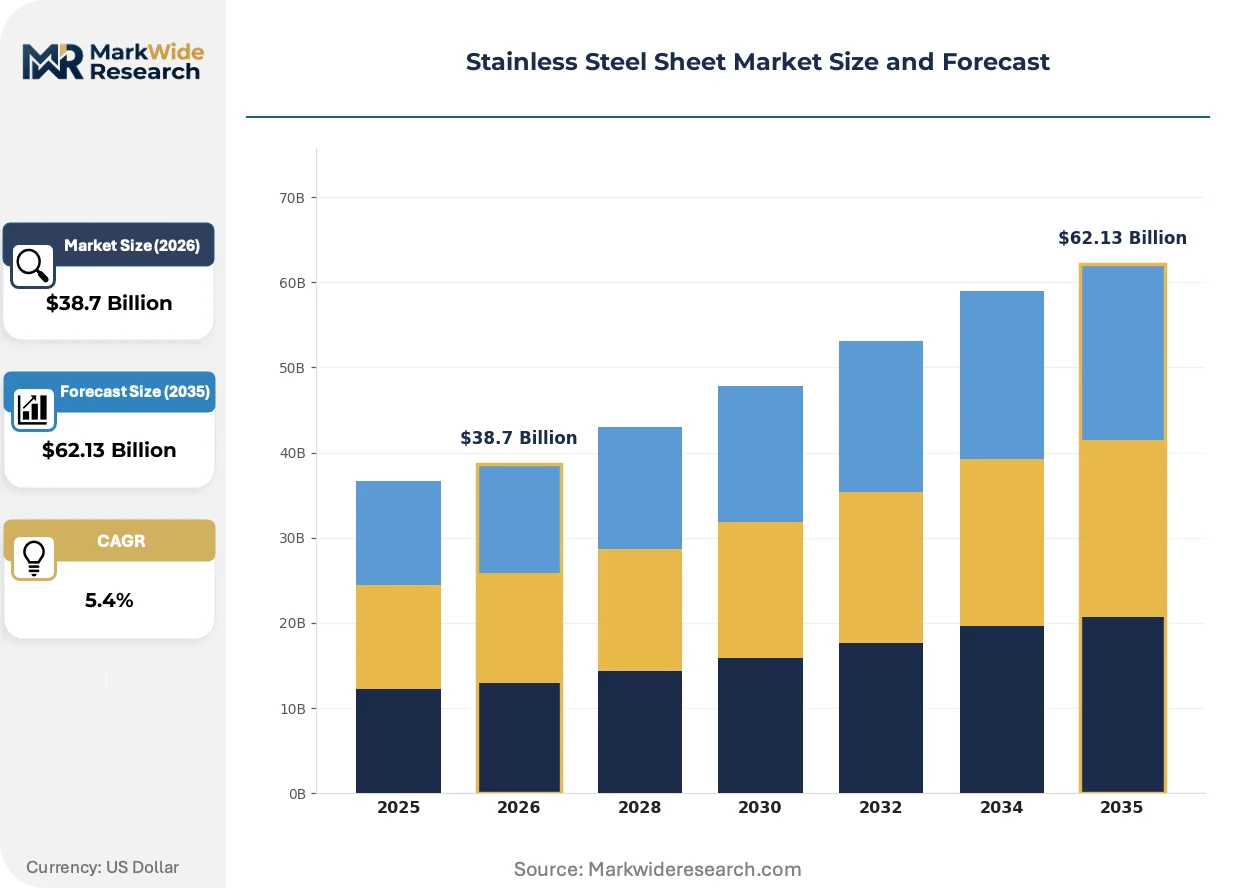
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Grade: 304, 316, 430, 201 Form: Hot Rolled, Cold Rolled, Annealed, Pickled Application: Construction, Automotive, Aerospace, Electronics Delivery Mode: Direct Supply, Retail Distribution, Online Sales, Wholesale |
| Companies Covered | POSCO, Aperam S.A., Nippon Steel Corporation, Outokumpu Oyj, Acerinox S.A., Baosteel Group, Tata Steel Ltd, ArcelorMittal, Jindal Stainless Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Sheet Market Emerging Trajectories
Digital alloy design and surface engineering are compressing development cycles for application-specific grades, while regulatory chemistry restrictions force passivation technology substitution across European and North American supply chains.
Precision cold rolling with inline thickness gauging is expanding into automotive exhaust and appliance panel applications where dimensional tolerance below fifty microns enables downstream stamping without secondary grinding. Tier-one suppliers in Germany and Japan adopt these lines for just-in-time delivery to OEM assembly plants. The technology is compressing traditional hot-rolled-to-cold-rolled conversion economics for thin-gauge commodity grades.
REACH Annex XVII restrictions on hexavalent chromium surface treatments redirect specification toward trivalent passivation and electropolished finishes for food contact and medical device applications. European fabricators face reformulation costs and process revalidation requirements. North American exporters to EU markets align surface treatment protocols with ECHA guidance to maintain cross-border access.
Consolidated mill-direct contracting displaces multi-source distributor procurement among aerospace and pharmaceutical OEMs seeking lot traceability and alloy surcharge transparency. Long-term agreements now index to London Metal Exchange nickel and molybdenum movements with monthly adjustment clauses. This concentration is most visible in Germany and Switzerland where medical device and precision engineering clusters dominate premium sheet consumption.
Stainless Steel Sheet Market Segmentation
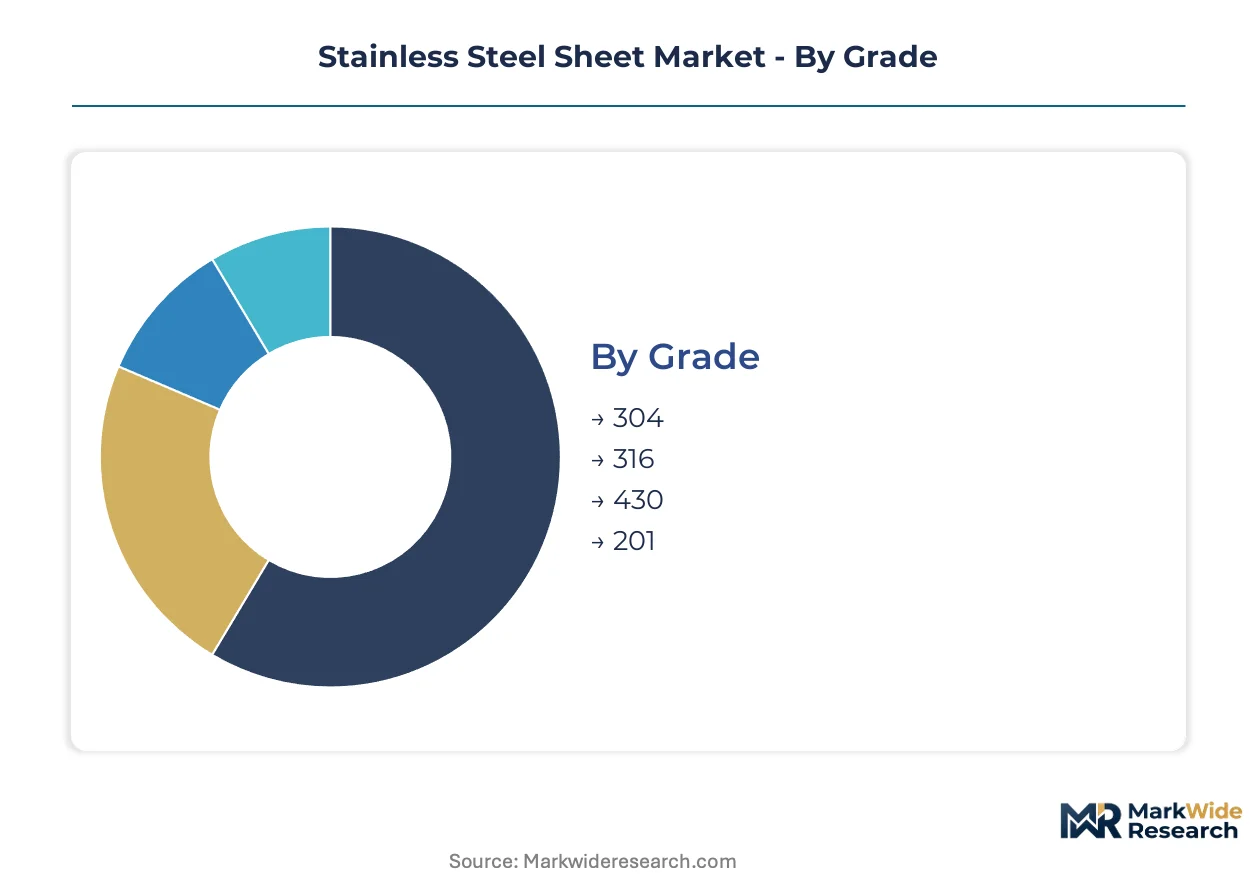
Stainless steel sheet procurement patterns diverge sharply by end-use tolerance for corrosion, surface finish, and lot traceability. Specification-grade buyers prioritize alloy chemistry certification, while commodity purchasers optimize for gauge availability and freight economics.
Grade:
Buyers in this category differentiate primarily by corrosion resistance requirements and molybdenum content tolerance in their unit economics.
- 304:Austenitic grade containing 18% chromium and 8% nickel delivers versatile oxidation resistance across food processing equipment and architectural cladding. Demand concentrates in China's eastern coastal fabrication clusters serving export kitchenware OEMs and domestic construction, though nickel surcharge volatility compresses margin predictability for toll processors.
- 316:Molybdenum-enhanced formulation provides superior pitting resistance in chloride environments, commanding premium positioning in marine ballast tanks and pharmaceutical bioreactor vessels. South Korean and Japanese shipbuilders specify 316L for deck structures requiring extended saltwater service intervals without scheduled replacement.
- 430:Ferritic grade with 16-18% chromium and minimal nickel offers cost-efficient corrosion resistance for automotive exhaust systems and appliance panels where formability requirements permit lower alloy content.
- 201:Manganese-substituted austenitic grade reduces nickel dependency through higher nitrogen content, finding volume in price-sensitive decorative applications and low-duty kitchenware across Indian and Southeast Asian markets.
304 leads volumes today; 316 is gaining share fastest in premium specification channels.
Form:
Processing route selection hinges on downstream dimensional tolerance requirements and surface aesthetic demands.
- Hot Rolled:Continuous casting above recrystallization temperature yields heavy-gauge plate for tank fabrication and structural construction where surface finish is secondary to mechanical strength and weldability.
- Cold Rolled:Precision rolling below recrystallization temperature achieves thickness tolerance below fifty microns and bright reflective surfaces demanded by automotive exhaust stampers and appliance panel OEMs in Germany and Japan.
- Annealed:Heat treatment relieves work hardening from cold rolling, restoring ductility for deep-drawn sink and cookware forming operations across India's Punjab and Gujarat manufacturing belts.
- Pickled:Acid descaling removes oxide scale from hot rolling, preparing surfaces for subsequent cold rolling or direct sale to fabricators requiring clean weld preparation without secondary blasting.
Hot rolled maintains absolute throughput leadership; cold rolled captures superior margin pools per ton.
Application:
End-use sectors impose divergent certification burdens, from ASTM A240 traceability in aerospace to hygiene compliance in food contact.
- Construction:Architectural cladding and structural framing specify 304 and 316 for facade longevity in coastal environments, with EU Green Deal carbon intensity caps favoring scrap-fed electric arc furnace supply for green building certification credits.
- Automotive:Exhaust system fabricators in Germany and the US displace austenitic grades with 409 and 439 ferritic sheet where corrosion requirements permit reduced alloy content and lower unit economics per vehicle.
- Aerospace:Airframe and engine OEMs consolidate procurement around mill-direct austenitic contracts with lot-level chemistry traceability, compressing distributor margins while elevating specification rigor for corrosion-resistant grades.
- Electronics:Cleanroom equipment and semiconductor tooling demand electropolished 304 and 316L surfaces meeting FDA and EMA aseptic processing guidelines for particle contamination control.
Construction anchors current volume; aerospace and electronics are climbing the fastest on value per ton.
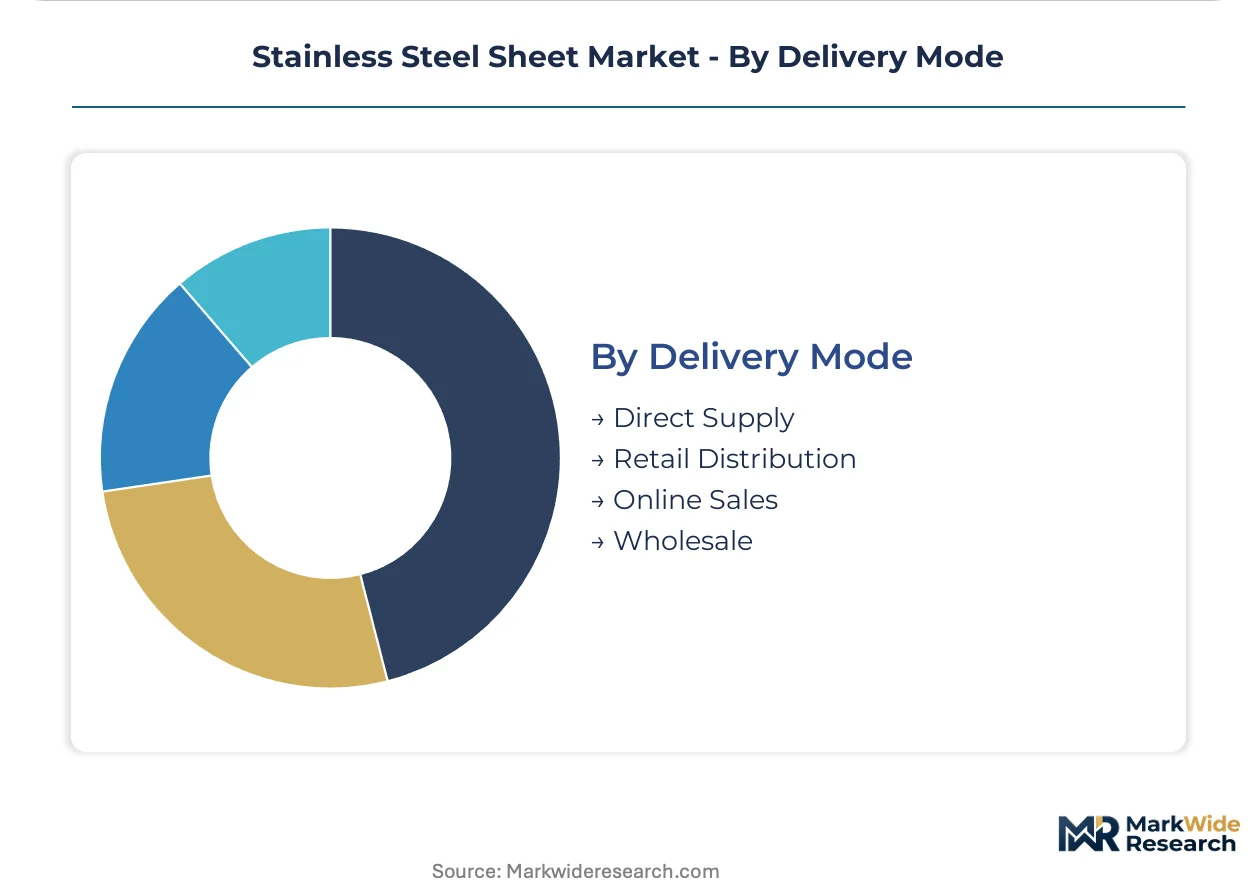
Delivery Mode:
Channel selection reflects buyer scale, inventory carrying capacity, and urgency tolerance in supply planning.
- Direct Supply:Mill-direct contracting with indexed alloy surcharge clauses serves aerospace and pharmaceutical OEMs requiring monthly price transparency and lot traceability for regulatory audit trails.
- Retail Distribution:Service center networks with slitting and blanking capabilities support just-in-time delivery to tier-two appliance and automotive stampers lacking warehouse infrastructure.
- Online Sales:Digital platforms with real-time inventory visibility enable small fabricators and maintenance shops to procure standard gauges without minimum order quantity constraints.
- Wholesale:Volume aggregation through distributor consignment stock serves construction contractors with irregular project timing and limited working capital for inventory prepayment.
Direct supply commands the premium channel; online sales are expanding most quickly among fragmented buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redirecting stainless steel sheet production toward jurisdictions with lower carbon-intensity compliance costs, while EU Green Deal benchmarks accelerate mill consolidation in higher-regulation environments.
China
Eastern coastal fabrication clusters in Jiangsu and Zhejiang provinces dominate export kitchenware OEM supply and domestic construction demand. GB standards and MEE emissions protocols tighten effluent controls for pickling and annealing lines, raising capital requirements for integrated producers. Shandong Peninsula mills expand cold-rolled capacity to serve automotive exhaust stampers with sub-fifty-micron dimensional tolerance.
Germany
Precision engineering and medical device clusters in Baden-Württemberg and North Rhine-Westphalia specify electropolished 316L for bioreactor vessels and cleanroom cladding. EU Green Deal carbon intensity caps favor scrap-fed electric arc furnace routes for green building certification credits. Ruhr Valley distribution networks consolidate mill-direct contracting with monthly alloy surcharge indexing to LME nickel movements.
India
Punjab and Gujarat manufacturing belts drive deep-drawn sink and cookware forming operations using annealed 304 sheet. PLI scheme production-linked incentives cover cold-rolled stainless capacity expansion for railway coach and kitchenware export manufacturing. Jindal Stainless Group dominates Indian flat-rolled supply through integrated melt-to-strip operations.
South Korea
Shipbuilders in Ulsan and Geoje specify molybdenum-enhanced 316L for ballast tanks and deck structures requiring extended saltwater service intervals. POSCO leverages captive chromium sourcing to sustain cost discipline in austenitic grades for domestic and export markets. Busan service centers automate slitting operations for just-in-time delivery to tier-two appliance stampers.
United States
Automotive exhaust fabricators in Michigan and Ohio displace austenitic grades with 409 and 439 ferritic sheet where corrosion requirements permit reduced alloy content. EPA emissions frameworks and OSHA workplace standards govern pickling line operations without REACH-equivalent chemistry restrictions. Gulf Coast petrochemical construction sustains heavy-gauge hot-rolled demand for tank fabrication.
Stainless Steel Sheet Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty-grade certification and digital service center networks. The vendor base stratifies across integrated mills with captive ferrochrome supply, regional toll processors dependent on spot alloy surcharges, and service-center operators consolidating slitting and blanking capabilities. Three archetypes dominate: backward-integrated chromite owners, scrap-fed electric arc furnace specialists, and precision cold-rolling technology licensors. Competitive moves concentrate on long-term procurement contracting with aerospace OEMs and hydrogen storage vessel qualification for energy infrastructure developers.
Among Asia-Pacific integrated producers, POSCO and Baosteel Group exemplify scale-driven positions anchored to captive raw material access and coastal export logistics. European specialists including Outokumpu Oyj and Acerinox S.A. occupy premium-tier positioning through EN 10088-2 certification depth and pharmaceutical-grade surface finish capabilities. Jindal Stainless Group represents the emerging-market archetype with domestic volume leadership and PLI-scheme capacity expansion into railway and kitchenware export channels.
| Leading Market Players |
|---|
| POSCO |
| Aperam S.A. |
| Nippon Steel Corporation |
| Outokumpu Oyj |
| Acerinox S.A. |
| Baosteel Group |
| Tata Steel Ltd |
| ArcelorMittal |
| Jindal Stainless Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon intensity benchmarks gate qualified supply for European mills while simultaneously creating premium-tier pricing access for scrap-fed electric arc furnace producers with verified low-carbon output. This regulatory filter compresses margin pools for high-emission integrated producers while elevating price realization for certified green sheet tonnage in construction and automotive channels.
Pricing Analysis
London Metal Exchange alloy surcharges pass through directly to contract pricing, with nickel and molybdenum volatility driving monthly adjustments in mill-direct agreements. Three-tier pricing structure across premium specification, standard commercial, and economy ferritic grades separates aerospace lot-traceability contracts from commodity construction tonnage. Cost compression in standard austenitic grades is intensifying because Indonesian ore export policy shifts disrupt nickel cost predictability. Automotive exhaust fabricators exhibit highest price sensitivity, prioritizing ferritic substitution where corrosion requirements permit, while pharmaceutical OEMs show lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing patterns by incentivizing local cold-rolled capacity expansion for railway and kitchenware export manufacturing. Geographic supply concentrates in China, India, and South Korea, with each hub serving distinct regional fabrication clusters. Raw material dependencies center on South African ferrochrome, Indonesian nickel laterite, and Kazakh chromite concentrates. Single-source vulnerability in metallurgical-grade chromite reserves creates structural risk for austenitic grade cost structures. Distribution runs through mill-direct contracting for large OEMs and automated service center networks for tier-two stampers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal emissions benchmarks and FDA aseptic processing guidelines simultaneously constrain supply eligibility and expand specification-grade demand.
For Market Incumbents: Deepen backward integration into captive ferrochrome supply to hedge against South African and Kazakh chromite concentration risk. Expand cold-rolled precision capacity in Germany and South Korea to capture automotive and appliance OEM just-in-time requirements. Certify electropolished surface finishes under EN 10088-2 and ASTM A240 to defend aerospace and pharmaceutical contract positions against emerging toll processors. For New Entrants and Emerging Players: Enter via hydrogen storage vessel qualification programs in Germany and the Netherlands, where high-pressure 316L and duplex grade demand outpaces certified supply. Target digital service center automation for tier-two appliance stampers in India's Punjab and Gujarat belts, where fragmented procurement lacks real-time inventory visibility. Pursue PLI scheme incentives for railway coach and kitchenware export capacity as the go-to-market anchor. For Investors and Strategic Acquirers: Roll-up economics work for scrap-fed electric arc furnace specialists because EU Green Deal carbon intensity caps create structural preference for low-carbon production routes over integrated blast furnace assets. Long-term viability favors producers with verified green certification and pharmaceutical-grade surface finish capabilities. Watch Indonesian nickel export policy announcements as the inflection signal for austenitic grade margin compression or recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrochrome | Captive chromite supply hedges POSCO and Jindal against Kazakh and South African concentration risk. |
| Precision Cold-Rolling Capacity Expansion | Sub-fifty-micron tolerance lines in Shandong and Baden-Württemberg capture automotive exhaust stampers. |
| Hydrogen Storage Vessel Qualification | German and Dutch energy developers specify 316L and duplex grades for electrolyzer fabrication. |
| Digital Service Center Automation | Real-time inventory visibility enables just-in-time delivery to tier-two appliance manufacturers in Busan. |
| Trivalent Passivation Technology Transition | REACH Annex XVII compliance redirects European food contact and medical device surface treatment protocols. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with stainless steel procurement managers at aerospace OEMs, pharmaceutical equipment fabricators, shipyard material planners, and automotive exhaust system engineers with secondary validation. Sources included customs and trade flow databases, mill production disclosures, SEC filings from listed producers, and alloy surcharge tracking from London Metal Exchange publications. Bottom-up demand modeling across end-use applications triangulated against top-down capacity and output estimates from integrated producers.
Historical reference periods anchored the projection framework to observed alloy surcharge volatility patterns and regulatory implementation timelines across the analysis window. Segmentation dimensions modeled include grade tier, processing route, end-use application, and delivery mode. CAGRs derived from regression analysis of volume trajectories against industrial production indices and fixed investment cycles. Forecast inputs incorporated nickel and molybdenum price scenario modeling alongside emissions compliance cost assumptions for European mill operations.
Inputs from primary stakeholder interviews and published mill disclosures were available through the study window; gaps in real-time alloy surcharge contract terms and unannounced capacity expansion timelines introduce uncertainty bands around near-term price trajectory assumptions. Forecasts reflect documented analytical assumptions regarding regulatory enforcement intensity and raw material supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Titanium Market
Metals
Steel Drums and Ibcs Market
Metals
Beryllium Copper Plate Market
Metals
Industrial Metal Strips Market
Metals
Global Tool Steel Market
Metals
Arc Ferrite Magnet Market
Metals
High Carbon Bearing Steel Market
Metals
Global Flat Carbon Steel Market
Metals
Bismuth Oxide Market
Metals
Tin Chloride Market
Metals
Global Superconducting Wire Market
Metals
Global Bronze Market
Metals
China Copper Market
Metals
Japan Aluminium Powder Market
Metals
Ferrite Market
Metals
Aluminum Sheet Market