
 North America Electrical Steel Market | 2026-2036
North America Electrical Steel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electrical Steel Market Analytics
The widening performance gap between premium grain-oriented steel and commodity low-carbon grades is repositioning procurement strategies across the transformer supply chain. ArcelorMittal leverages its integrated North American melt shop-to-coating footprint to dominate high-efficiency transformer core supply. Cleveland-Cliffs Inc. anchors regional feedstock security through its Minnesota ore-to-steel verticality. Nippon Steel Corporation competes on ultra-low core loss specifications refined at its Japanese research centers and exported to US transformer OEMs.
North America electrical steel comprises iron-silicon alloys engineered with precise grain orientation control to minimize hysteresis and eddy current losses, typically containing 1-4.5% silicon by weight and annealed under hydrogen atmospheres to achieve permeability values exceeding 30,000 at 1.5 Tesla. Grain-oriented steel commands premium pricing in power transformer cores where core loss reductions of fractions of a watt per kilogram justify material cost escalation. Non-grain oriented steel leads volume absorption across traction motors and appliance applications where isotropic magnetic properties enable complex lamination geometries. Advanced coated technologies capture expanding margin pools as epoxy and phosphate insulation layers extend lamination stack thermal endurance.
The US Department of Energy appliance efficiency standards and Canada's Natural Resources Canada CAN/CSA-C802 transformer loss limits collectively compress allowable core loss coefficients, forcing steel mills toward thinner gauge production and domain-refined microstructures. State-level renewable portfolio standards in California, Texas, and New York amplify interconnection transformer demand, tightening electrical steel availability for industrial motor applications. Stakeholders must monitor EPA Section 232 tariff modifications and domestic content incentives under the Inflation Reduction Act, as these instruments determine whether North American melt capacity expands or import dependency deepens for critical magnetic alloys.
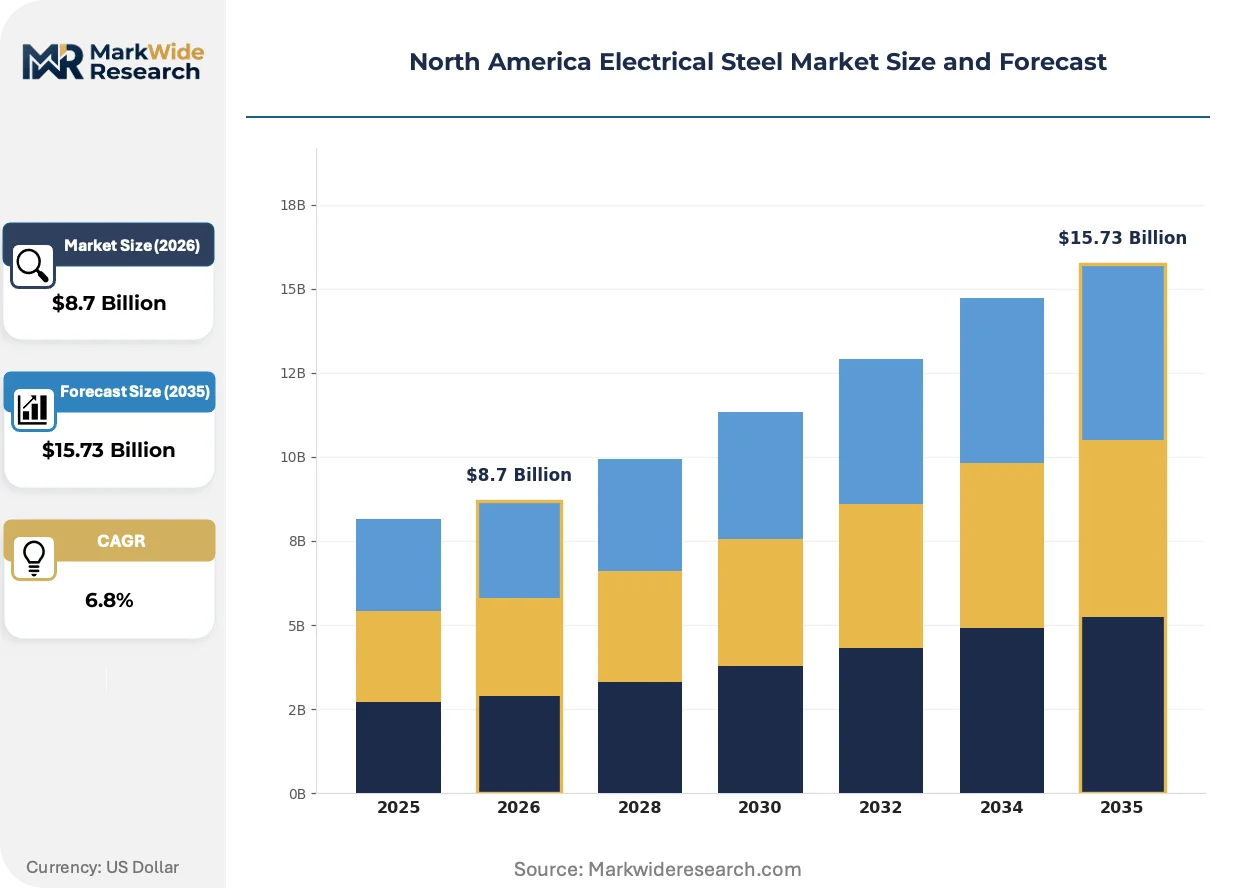
Market Dynamics
The US Department of Energy's escalating efficiency mandates are compressing allowable core loss coefficients, forcing steel mills toward thinner gauge production and domain-refined microstructures while electric vehicle motor procurement accelerates for non-grain oriented grades.
Growth Catalysts
- IRA Domestic Content Incentives:The Inflation Reduction Act's clean energy manufacturing tax credits are accelerating melt shop investments across Indiana and Ohio. Transformer OEMs are qualifying domestic coil supply for federal project eligibility.
- Zero-Emission Vehicle Mandates:California's Advanced Clean Trucks regulation and similar state-level statutes are pulling non-grain oriented steel volumes into traction motor laminations. Motor manufacturers are locking multi-year supply agreements.
- Grid Interconnection Surge:Renewable portfolio standards in Texas and New York are amplifying demand for interconnection transformers. Distribution utilities are procuring high-efficiency core materials to manage variable renewable integration.
Market Restraints
- Silicon Metal Price Volatility:Ferrosilicon input costs fluctuate with Chinese smelter output and energy pricing. Mills lack pass-through mechanisms for raw material spikes in long-term transformer supply contracts.
- Single-Source Coating Dependency:Hydrogen annealing furnace capacity concentrates among three integrated producers. Specialty coating chemistries for high-temperature endurance remain captive to limited domestic technical expertise.
- Thin-Gauge Rolling Limitations:Below 0.23mm thickness, cold rolling mills encounter strip breakage rates that degrade yield economics. Domain refinement through laser scribing adds process complexity and capital intensity.
Strategic Opportunities
- Canadian Transformer Export Channel:Hydro-Québec and Ontario Power Generation procurement standards align with US DOE efficiency trajectories. Mills with cross-border logistics capabilities can capture provincial utility demand without tariff exposure.
- Solid-State Transformer Architecture:Medium-voltage silicon carbide power electronics are enabling transformer designs with higher frequency operation. Electrical steel suppliers can develop optimized alloys for reduced core mass in these systems.
- Appliance Motor Premiumization:Heat pump compressor and high-efficiency washing machine manufacturers are specifying lower core loss grades. Appliance OEMs represent a price-tolerant segment distinct from commodity construction motor buyers.
Industry Challenges
- Metallurgical Talent Scarcity:Grain orientation control and texture engineering expertise resides with a shrinking cohort of senior process engineers. Universities have dismantled dedicated magnetic materials programs.
- Extended DOE Certification Timelines:New grade qualification for federal procurement requires 18-24 month core loss verification protocols. Product development cycles misalign with utility procurement windows.
- Legacy Lamination Equipment Integration:Transformer OEMs operate stamping presses optimized for 0.35mm legacy gauges. Thinner advanced grades require press retrofits or new capital deployment that strains mid-tier fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electrical Steel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Steel, Low Carbon Steel, Grain-Oriented Steel, Non-Grain Oriented Steel End User: Power Generation, Transformers, Motors, Generators Technology: Conventional, Advanced Coated, Nano-crystalline, Amorphous Packaging Type: Sheets, Coils, Strips, Pallets |
| Companies Covered | ArcelorMittal, Cleveland-Cliffs Inc., Nippon Steel Corporation, POSCO, United States Steel Corporation, Steel Dynamics, Thyssenkrupp AG, JFE Steel Corporation, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electrical Steel Market Evolving Landscape
Domain-refined grain-oriented steel and ultra-thin non-grain oriented alloys are reshaping competitive positioning across transformer and motor applications, while regulatory efficiency mandates accelerate material specification upgrades.
Advanced laser scribing technology is electrifying the performance frontier for power transformer cores. This process creates controlled magnetic domain refinement that reduces core loss by 10-15% without silicon content increases. Major utilities in Texas and California are specifying laser-scribed grades for new interconnection assets. The technology is electrifying procurement criteria from first-cost minimization toward lifecycle loss-cost optimization.
The US Department of Energy's amended Appendix A efficiency standards are mandating reduced no-load losses for liquid-immersed distribution transformers. Manufacturers must qualify new core steel grades or surrender federal and state utility procurement eligibility. Small and medium transformer OEMs in the Great Lakes corridor are experiencing the steepest compliance cost compression.
Automotive tier-one suppliers are consolidating electrical steel purchasing through mill-direct contracts rather than service center intermediation. This disintermediation reflects volume certainty from multi-platform electric vehicle programs and the technical collaboration required for motor lamination optimization. The pattern is most pronounced among drivetrain suppliers serving Detroit Three electrification commitments.
North America Electrical Steel Market Segmentation
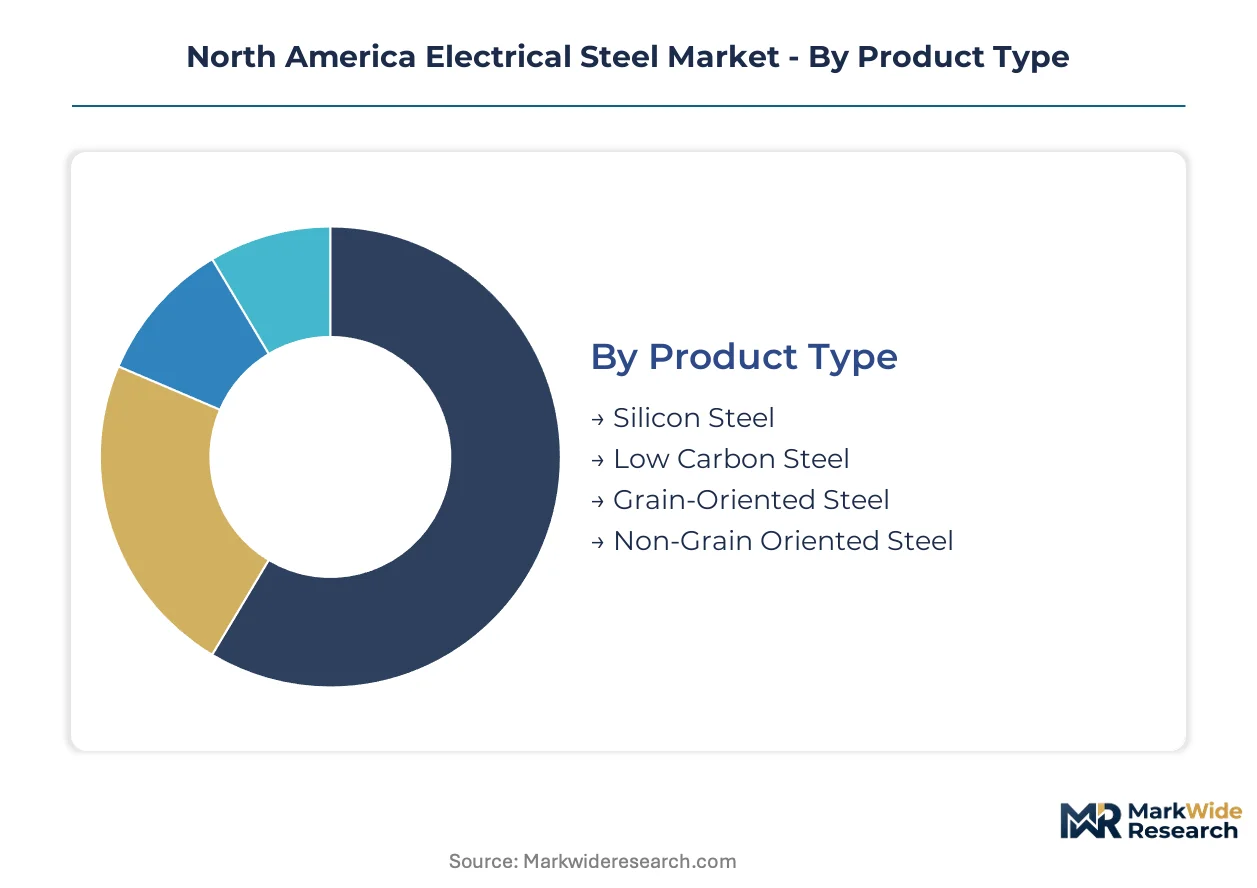
Electrical steel procurement strategies diverge sharply across product grades and end-use specifications. Transformer OEMs prioritize core loss coefficients while motor manufacturers optimize for isotropic magnetic properties and lamination formability.
Product Type:
Material selection hinges on the trade-off between magnetic anisotropy requirements and cost-per-watt of core loss reduction.
- Grain-Oriented Steel:Silicon-iron alloys with controlled <001> crystallographic texture achieve permeability exceeding 30,000 at 1.5 Tesla. Demand concentrates in US Great Lakes power transformer manufacturing where DOE efficiency mandates compress allowable no-load loss coefficients.
- Non-Grain Oriented Steel:Isotropic magnetic properties enable complex motor lamination geometries without directional performance degradation. Procurement accelerates across Indiana and Ohio electric vehicle motor plants as Detroit Three electrification commitments scale traction motor volumes.
- Silicon Steel:Broad-category iron-silicon alloys containing 1-4.5% silicon by weight serve legacy transformer and appliance motor applications.
- Low Carbon Steel:Unalloyed grades with higher core loss coefficients retain cost-sensitive construction motor and general industrial applications.
Grain-oriented steel leads on scale; non-grain oriented steel leads on momentum.
End User:
Application-specific loss specifications and duty cycle profiles determine grade selection and supplier qualification requirements.
- Transformers:Liquid-immersed distribution and interconnection assets demand ultra-low core loss grades. Procurement tightens across Texas and California utilities managing renewable portfolio standard compliance.
- Motors:Traction motor laminations require high-frequency performance and mechanical strength for rotor slot integrity. Electric vehicle drivetrain suppliers in the US Midwest are locking multi-year coil supply agreements.
- Power Generation:Generator core applications balance efficiency with centrifugal stress tolerance in rotating machinery.
- Generators:Large turbogenerator and hydroelectric unit manufacturers specify domain-refined grades for stator and rotor core assemblies.
Transformers dominate procurement volume; motors are climbing the fastest.
Technology:
Process innovation intensity separates premium-grade producers from commodity suppliers in customer qualification protocols.
- Advanced Coated:Epoxy and phosphate insulation layers extend lamination stack thermal endurance and electrical resistance. Adoption concentrates among high-efficiency transformer OEMs qualifying for federal procurement under amended Appendix A standards.
- Conventional:Standard annealing and surface treatment processes serve cost-optimized distribution transformer and appliance motor segments.
- Nano-crystalline:Rapid solidification alloys achieve ultra-low core loss at elevated frequencies for specialized power electronics integration.
- Amorphous:Metallic glass structures virtually eliminate hysteresis losses in distribution transformer cores where first-cost sensitivity limits deployment.
Conventional technology retains volume dominance; advanced coated grades show steepest expansion trajectory.
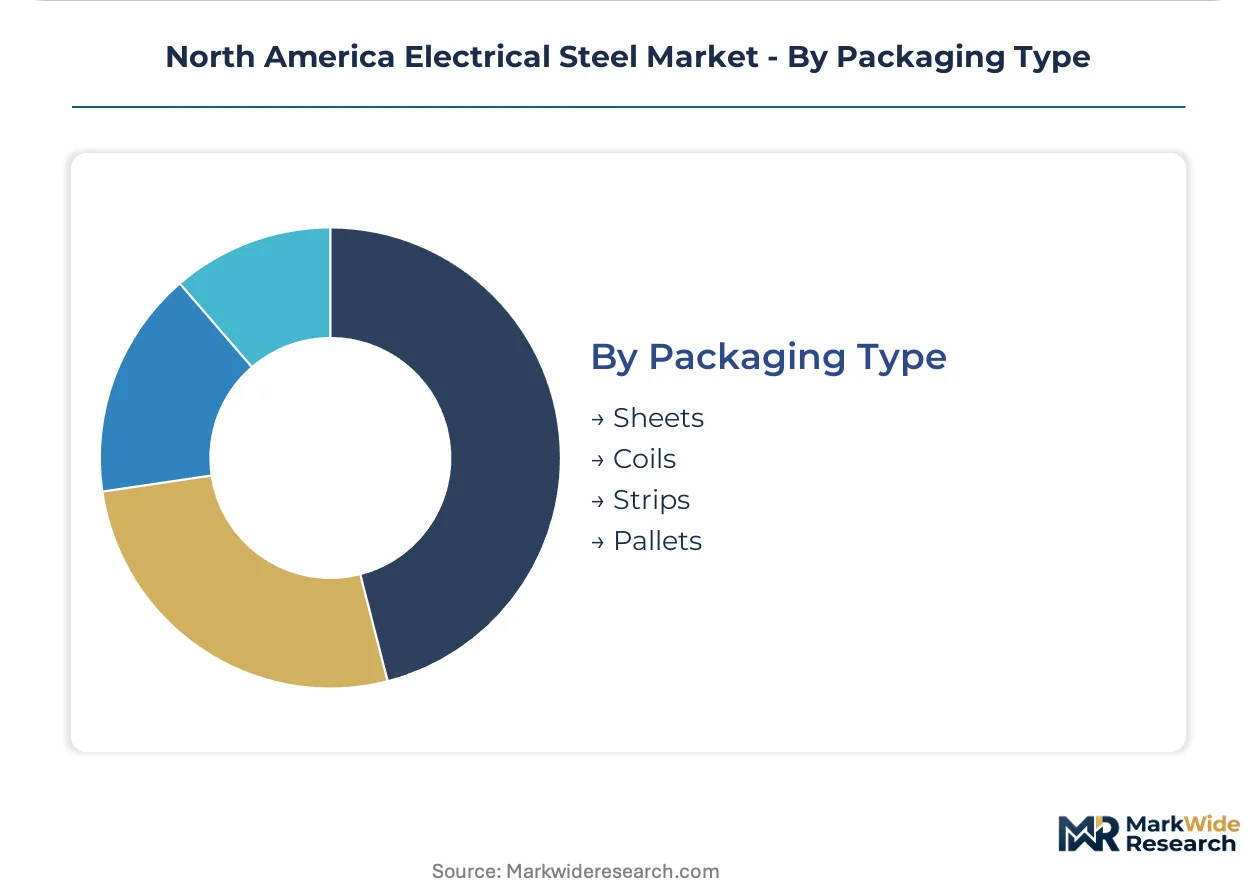
Packaging Type:
Logistics configuration and inventory velocity requirements vary across stamping press integration models and coil processing capabilities.
- Coils:Continuous wound strip enables high-speed automated stamping operations. Great Lakes transformer OEMs prefer mill-direct coil supply to minimize slitting waste and inventory carrying costs.
- Sheets:Precut rectangular blanks serve smaller fabricators with legacy press equipment lacking precision coil feeding systems.
- Strips:Narrow-width slit products target specialized motor lamination houses and aftermarket repair applications.
- Pallets:Unitized bulk shipment configurations support high-volume appliance motor manufacturers with integrated blanking operations.
Coils lead on throughput efficiency; sheets retain share among mid-tier stampers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands procurement volume across transformer and motor applications, while Canada leverages hydroelectric infrastructure and cross-border logistics to capture utility-grade demand.
United States
Great Lakes manufacturing corridors in Indiana and Ohio concentrate electric vehicle motor production and distribution transformer fabrication. The US Department of Energy's amended Appendix A efficiency standards compress allowable core loss coefficients for liquid-immersed transformers. Detroit Three automakers and tier-one drivetrain suppliers in Michigan are locking multi-year coil supply agreements for traction motor laminations.
Canada
Hydro-Québec and Ontario Power Generation procurement standards align with US DOE efficiency trajectories for interconnection transformers. Natural Resources Canada CAN/CSA-C802 transformer loss limits mandate reduced no-load losses comparable to American federal mandates. Cross-border logistics capabilities through Ontario and Quebec enable mills to capture provincial utility demand without tariff exposure under USMCA provisions.
Mexico
Appliance motor manufacturing clusters in Nuevo León and the Bajío Region absorb non-grain oriented steel for compressor and washing machine applications. Mexican federal energy efficiency programs through CONUEE establish minimum performance standards for distribution transformers. Nearshoring trends are pulling stamping press operations to Querétaro and Guanajuato to serve US appliance OEMs.
North America Electrical Steel Market Competitive Landscape
Top-tier vendors anchor integrated melt shop-to-coating footprints, while mid-tier producers compete on regional feedstock security and specialized gauge capabilities. The vendor base concentrates among three hydrogen annealing furnace operators with captive technical expertise in domain refinement. Strategic archetypes include ore-to-steel verticalists, coating technology licensors, and mill-direct automotive suppliers. Competitive moves center on capacity expansion across Indiana and Ohio corridors and strategic partnerships for solid-state transformer alloy development.
Within the integrated producer tier, ArcelorMittal, Cleveland-Cliffs Inc., and Nippon Steel Corporation exemplify divergent geographic and technological positioning. ArcelorMittal occupies a position as a North American-anchored multinational with melt shop integration spanning the Great Lakes corridor. Cleveland-Cliffs Inc. represents the ore-to-steel verticalist archetype through Minnesota mining and pellet operations feeding regional flat-rolled capacity. Nippon Steel Corporation anchors the ultra-low core loss specification segment, with Japanese research center capabilities exported to US transformer OEMs through qualified supply agreements.
| Leading Market Players |
|---|
| ArcelorMittal |
| Cleveland-Cliffs Inc. |
| Nippon Steel Corporation |
| POSCO |
| United States Steel Corporation |
| Steel Dynamics |
| Thyssenkrupp AG |
| JFE Steel Corporation |
| Nucor Corporation |
| Others |
Value Network & Pricing Analysis
US DOE efficiency mandates for transformer core loss coefficients gate qualified supply access and premium-tier pricing power, compressing procurement eligibility to mills with hydrogen annealing furnace capacity and domain-refinement expertise while elevating laser-scribed grade premiums.
Pricing Analysis
Capacity additions in Indiana and Ohio are reshaping price floors for non-grain oriented steel as electric vehicle motor procurement accelerates. Three-tier pricing structure across premium laser-scribed, standard grain-oriented, and economy low-carbon levels separates qualified federal procurement grades from commodity construction motor supply. Cost compression in standard grades is intensifying because ferrosilicon input volatility lacks pass-through mechanisms in long-term transformer contracts. Appliance motor manufacturers represent the most price-sensitive segment, while utilities specifying interconnection transformers for renewable integration show least sensitivity.
Supply Chain Analysis
The Inflation Reduction Act's domestic content incentives are reshaping sourcing patterns, compelling transformer OEMs to qualify North American coil supply for federal project eligibility. Supply concentrates in the United States, Canada, and Japan, with Japanese research centers exporting ultra-low core loss specifications to US transformer OEMs. The supply chain draws from Minnesota iron ore, Great Lakes melt shop capacity, and captive hydrogen annealing furnace operations. Single-source coating dependency for high-temperature endurance chemistries creates structural vulnerability. Distribution runs through mill-direct coil agreements with Great Lakes transformer OEMs and automotive tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through laser-scribed grade premiumization and thin-gauge yield improvements as DOE efficiency mandates eliminate commodity-grade procurement eligibility.
For Market Incumbents: Anchor hydrogen annealing furnace capacity expansion across Indiana and Ohio corridors to capture IRA-driven domestic content demand. Defend against Nippon Steel's ultra-low core loss specification imports by accelerating domain-refinement R&D collaboration with Detroit Three drivetrain suppliers. Prioritize coating chemistry captive production to eliminate single-source vulnerability.
For New Entrants and Emerging Players: Enter via Canadian provincial utility procurement channels, where Hydro-Québec and Ontario Power Generation standards align with US DOE trajectories without tariff exposure under USMCA provisions. Target solid-state transformer alloy development partnerships with silicon carbide power electronics manufacturers as the most penetrable white-space application. Pursue technical collaboration models with automotive tier-one suppliers seeking mill-direct disintermediation.
For Investors and Strategic Acquirers: Roll-up economics work for ore-to-steel verticalists because Minnesota pellet operations feed regional flat-rolled capacity with captive feedstock security. Long-term viability centers on mills with integrated melt shop-to-coating footprints qualified for federal transformer procurement. Watch EPA Section 232 tariff modifications as the inflection signal determining whether domestic melt capacity expands or import dependency deepens.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Annealing Furnace Expansion | Captures IRA tax credits while qualifying supply for DOE Appendix A procurement standards. |
| Laser Scribing Technology Licensing | Enables 10-15% core loss reduction without silicon content increases for Texas and California utilities. |
| Cross-Border Canadian Logistics Investment | Positions mills to serve Hydro-Québec demand without USMCA tariff exposure. |
| Solid-State Transformer Alloy Development | Addresses silicon carbide power electronics frequency requirements for reduced core mass designs. |
| Mill-Direct Automotive Supply Agreements | Locks multi-year coil volumes from Detroit Three electrification platform commitments. |
Research Methodology
Multiple input streams — primary interviews with transformer OEM procurement directors, electric vehicle drivetrain supplier engineers, and steel mill technical sales leads; secondary validation through US DOE efficiency standard filings, FERC interconnection queue data, and SEC steel producer disclosures; and customs trade flow records — were reconciled through bottom-up and top-down triangulation.
Historical production capacity and core loss coefficient trends were cross-referenced against panel input from Great Lakes corridor plant managers to model volume and value outputs across the projection horizon. Segmentation dimensions included grain orientation control, end-use application, coating technology tier, and regional manufacturing cluster. CAGRs were derived from supply-demand balance analysis incorporating electric vehicle motor procurement trajectories and renewable portfolio standard interconnection transformer demand.
Inputs from federal regulatory filings and utility procurement databases were available through the study window; gaps in real-time ferrosilicon spot pricing and private mill yield data introduce uncertainty bands around thin-gauge production economics. Forecasts reflect documented assumptions regarding IRA domestic content incentive continuity and DOE efficiency mandate enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Europe Metal Casting Market
Metals
Galvanized Steel Coil Market
Metals
Galvanized Steel Market
Metals
Copper Chromium Black Market
Metals
Lightweight Aluminium Pistons Market
Metals
Amorphous Metal Cores Market
Metals
Ferrosilicon Market
Metals
Global Aluminum Extruded Products Market
Metals
Bismuth Market
Metals
Silver Enamel Market
Metals
High Purity Boron Market
Metals
Lithium Foil Market
Metals
Niobium Oxide Market
Metals
Global Wire Rods Market
Metals
Ore Metals Market
Metals
Beryllium Copper Plate Market