
 Asia-Pacific Metallurgical Grade Fluorspar Market | 2026-2036
Asia-Pacific Metallurgical Grade Fluorspar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Metallurgical Grade Fluorspar Market Outlook
A capital-intensity divergence between integrated miners and trading-dependent processors is reorganizing competitive tiers across the Asia-Pacific Metallurgical Grade Fluorspar Market. China Kings Resources Group Co., Ltd. leverages captive mine-to-port infrastructure across Hunan and Jiangxi provinces. Maharashtra Minerals Corporation Limited anchors its position through long-term offtake agreements with Indian steel mills. Inner Mongolia Huatong Fluorspar Co. Ltd. competes on raw ore cost structures from its northern Mongolian basin deposits.
Metallurgical grade fluorspar denotes calcium fluoride ore graded between 60% and 85% CaF₂ content, processed through gravity separation and flotation to serve as a fluxing agent that lowers the melting point of raw materials in high-temperature metallurgical reactions. The application dimension shows steel making commanding the dominant volume share due to sustained blast furnace and electric arc furnace operations across China and India, while aluminum production represents the fastest-growing demand channel as Southeast Asian smelter capacity expands. Within product type, Metallurgical-Spar retains the core revenue pool, though Acid-Spar commands premium pricing where dual-use refining capabilities exist.
China's MIIT enforces GB standards on fluorite mining emissions, while India's CEA regulates mineral beneficiation discharge under environmental clearance protocols; both frameworks elevate compliance costs for smaller producers and favor scaled operators with in-house treatment systems. Japan's METI maintains JIS standards for imported metallurgical flux materials that constrain market access for sub-grade suppliers. Stakeholders must monitor how China's dual carbon goals reshape domestic mining license allocations and whether India's PLI scheme for specialty steel broadens fluorspar specification requirements.
Market Dynamics
China's MIIT environmental enforcement is compressing domestic fluorspar mining licenses, forcing capacity consolidation toward Zhejiang and Jiangxi processing clusters while steelmakers in India and Vietnam expand consumption for blast furnace flux applications.
Growth Catalysts
- India's PLI Scheme for Specialty Steel:The production-linked incentive framework broadens fluorspar specification requirements as domestic steelmakers upgrade metallurgical processes for high-grade alloy output.
- Acid-Spar Dual-Use Refining:Processors with hybrid metallurgical-acid grade capabilities capture premium pricing pools as Southeast Asian aluminum smelter capacity expands.
- Vietnam Steel Sector Expansion:Electric arc furnace investments by Formosa Ha Tinh and Hoa Phat Group drive sustained fluorspar offtake for slag fluidity control in high-temperature reactions.
Market Restraints
- GB Standards Compliance Burden:China's MIIT emission thresholds on fluorite mining operations elevate capital requirements for tailings treatment, disadvantaging smaller basin operators in northern Mongolia.
- CaF₂ Ore Grade Depletion:Declining head grades at mature Hunan and Jiangxi deposits force processors to absorb higher beneficiation costs or accept lower recovery rates.
- Synthetic Flux Substitution:Steelmakers in Japan and South Korea trial synthetic slag conditioners that reduce metallurgical fluorspar intensity per ton of crude steel output.
Strategic Opportunities
- Indonesia Aluminum Smelter Buildout:Greenfield capacity at Morowali and Bintan creates untapped demand channels for metallurgical-grade flux in electrolytic reduction cells.
- Long-Term Offtake Structuring:Indian steel mills seek 5-7 year supply agreements with fixed-grade specifications, rewarding processors with proven beneficiation consistency.
- Flotation Technology Convergence:Integration of sensor-based ore sorting with conventional flotation circuits improves recovery from marginal ore bodies in depleted Chinese deposits.
Industry Challenges
- Process Engineer Scarcity:Fluorspar beneficiation expertise concentrates at legacy Chinese and Indian operators, constraining expansion timelines for new entrants in Vietnam and Indonesia.
- JIS Certification Timelines:Japan's METI import standards require 18-24 month qualification protocols for new metallurgical flux suppliers, delaying market access for emerging processors.
- Beneficiation Capex Intensity:Gravity separation and flotation circuit upgrades demand $15-25 million per 100,000 ton annual capacity, limiting balance sheet capacity for mid-scale traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Metallurgical Grade Fluorspar Market |
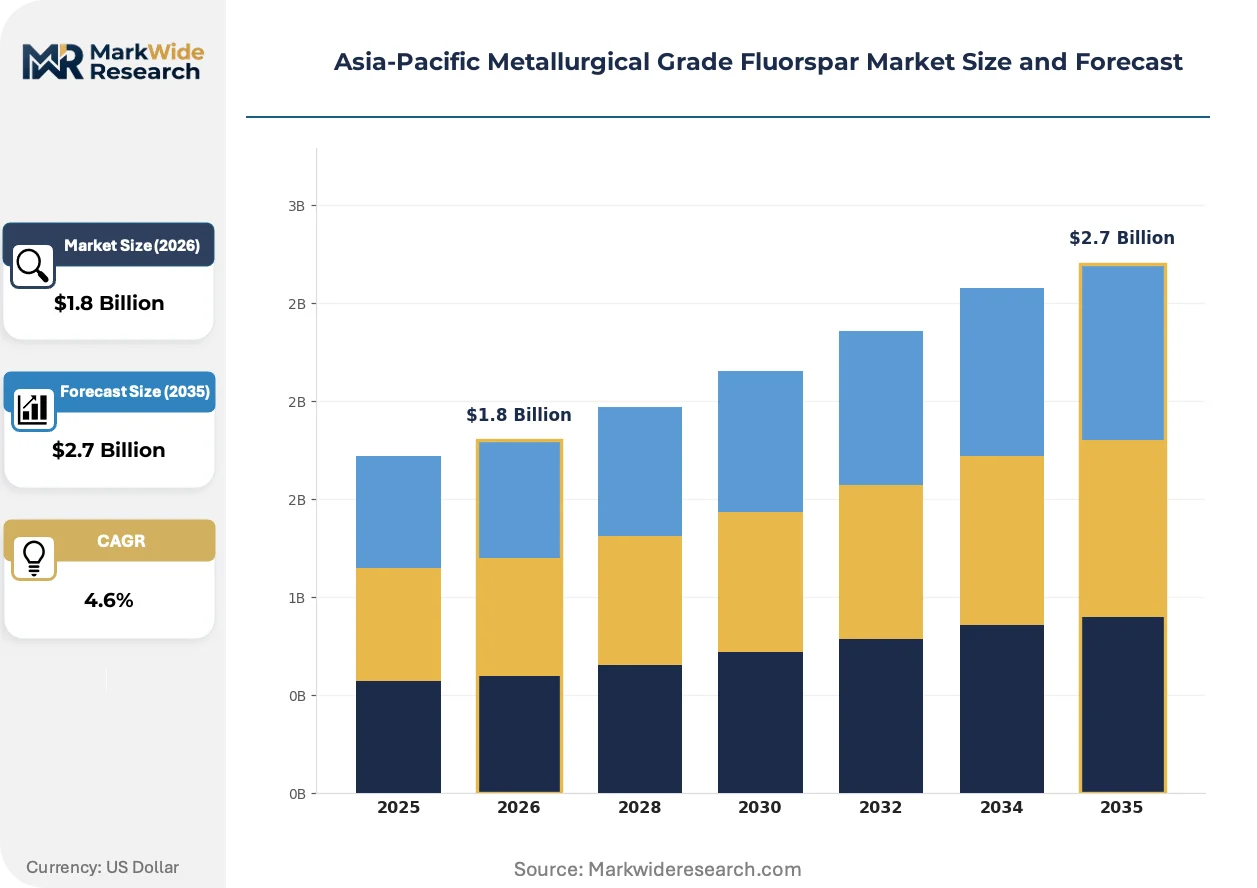
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acid-Spar, Metallurgical-Spar, Ceramic-Spar, Others Application: Aluminum Production, Steel Making, Cement Manufacturing, Glass Production End User: Construction, Automotive Parts, Chemical Industry, Electronics Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | China Kings Resources Group Co., Ltd., Maharashtra Minerals Corporation Limited, Steyuan Mineral Resources Group Ltd., Zhengzhou Rongsheng Kiln Refractory Co., Ltd., ORBIA, China National Fluorine Chemical Group Corporation, Jiangxi Shangfeng Fluorine Chemical Co. Ltd., Hunan Nonferrous Metals Corporation Limited, Inner Mongolia Huatong Fluorspar Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Metallurgical Grade Fluorspar Market Strategic Shifts
Metallurgical fluorspar markets are experiencing active restructuring through beneficiation technology diffusion, regulatory emission tightening, and buyer procurement consolidation across Asia-Pacific steel and aluminum value chains.
Sensor-based ore sorting is fragmenting traditional processing economics in Chinese fluorspar operations. Hunan and Jiangxi miners deploy X-ray transmission and laser-induced breakdown spectroscopy systems to pre-concentrate run-of-mine ore before flotation circuits. Mid-scale operators lacking capital for integrated sorting-flotation trains face margin compression as larger competitors achieve 15-20% lower unit processing costs through automated grade control.
China's dual carbon goals are reshaping mining license allocation priorities under MIIT and MEE coordination. Stricter energy consumption benchmarks for fluorite beneficiation operations favor processors with captive renewable power or grid access in low-carbon intensity provinces. Zhejiang-based integrated miners with hydroelectric supply contracts secure preferential license renewals while coal-dependent northern basin operators face accelerated phase-out timelines.
Steel mill procurement consolidation is compressing supplier bases across India and Vietnam. Tata Steel, JSW, and Hoa Phat Group centralize fluorspar purchasing through dedicated raw materials divisions, displacing fragmented trader-mediated spot markets. Long-term framework agreements with defined CaF₂ content bands and quarterly price adjustment mechanisms now dominate eastern Indian steel corridors, reducing spot market liquidity and rewarding processors with certified laboratory capabilities.
Asia-Pacific Metallurgical Grade Fluorspar Market Segmentation
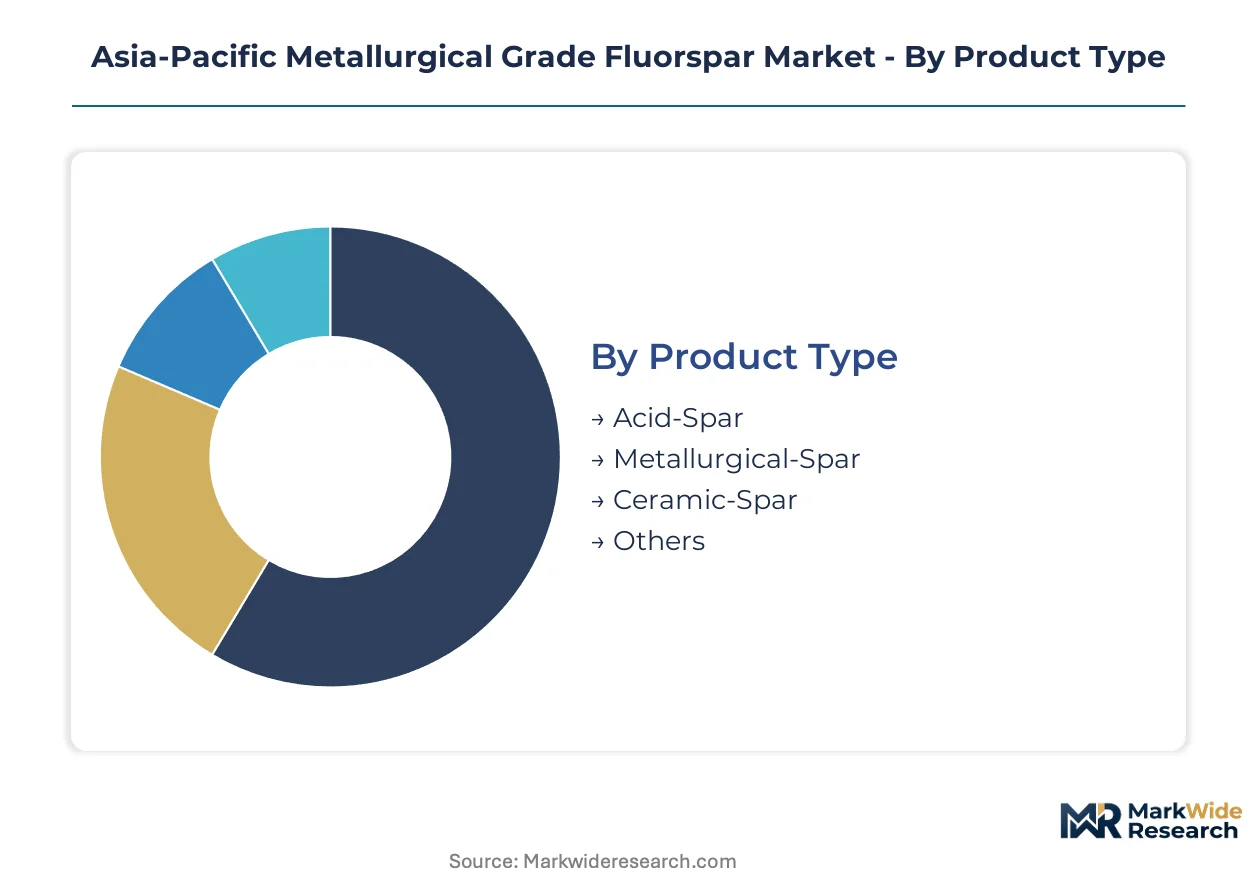
Fluorspar grade specifications determine regulatory compliance pathways and end-use eligibility across Asia-Pacific metallurgical markets. Steelmakers and aluminum smelters impose distinct CaF₂ thresholds that fragment supplier certification requirements by product category.
Product Type:
China's MIIT emission standards and Japan's METI import protocols create divergent compliance costs across fluorspar grades, favoring processors with dual-certification capabilities.
- Acid-Spar:Calcium fluoride ore exceeding 97% CaF₂ purity serves hydrofluoric acid feedstock for fluorochemical manufacturing. Southeast Asian aluminum smelters at Morowali and Bintan drive premium offtake for electrolytic reduction applications requiring ultra-low silica content.
- Metallurgical-Spar:Graded between 60% and 85% CaF₂, this fluxing agent lowers melting points in blast furnace and electric arc furnace operations. Indian steel mills under the PLI scheme for specialty steel broaden specification requirements for high-grade alloy output.
- Ceramic-Spar:Intermediate purity grades serve enamel and ceramic glaze formulations with controlled iron oxide limits.
- Others:Niche optical and lapidary grades command artisanal pricing pools outside industrial volume channels.
Established volume favors Metallurgical-Spar; emerging adoption favors Acid-Spar.
Application:
Process temperature requirements and slag chemistry dictate fluorspar selection across metallurgical end-uses, with cost-per-ton-of-metal-produced driving procurement decisions.
- Steel Making:Blast furnace and electric arc furnace operations consume metallurgical-grade flux to improve slag fluidity and sulfur removal efficiency. Vietnam's Hoa Phat Group and Formosa Ha Tinh expand electric arc furnace capacity, sustaining regional offtake for high-temperature flux applications.
- Aluminum Production:Electrolytic reduction cells require low-silica acid-grade fluorspar for cryolite-alumina bath chemistry. Indonesia's greenfield smelter buildout at Morowali creates untapped demand channels for certified flux materials.
- Cement Manufacturing:Minor flux applications in clinker production absorb lower-grade materials with relaxed purity specifications.
- Glass Production:Optical glass and specialty container formulations utilize ceramic-grade fluorspar for refractive index control.
Steel Making anchors current procurement volumes; Aluminum Production climbs the fastest on capacity expansion timelines.
End User:
Downstream manufacturing intensity and just-in-time raw material requirements shape fluorspar logistics configurations across customer categories.
- Construction:Reinforced steel and aluminum structural products drive bulk flux consumption through integrated mill supply chains.
- Automotive Parts:High-strength steel and cast aluminum components require consistent CaF₂ specifications for metallurgical consistency.
- Chemical Industry:Hydrofluoric acid and fluoropolymer feedstock demand concentrates at coastal processing clusters with import terminal access.
- Electronics:Semiconductor etching gases and high-purity fluorochemicals require acid-spar with trace element certification.
Construction maintains dominant share; Electronics shows steepest expansion trajectory on fluorochemical demand.
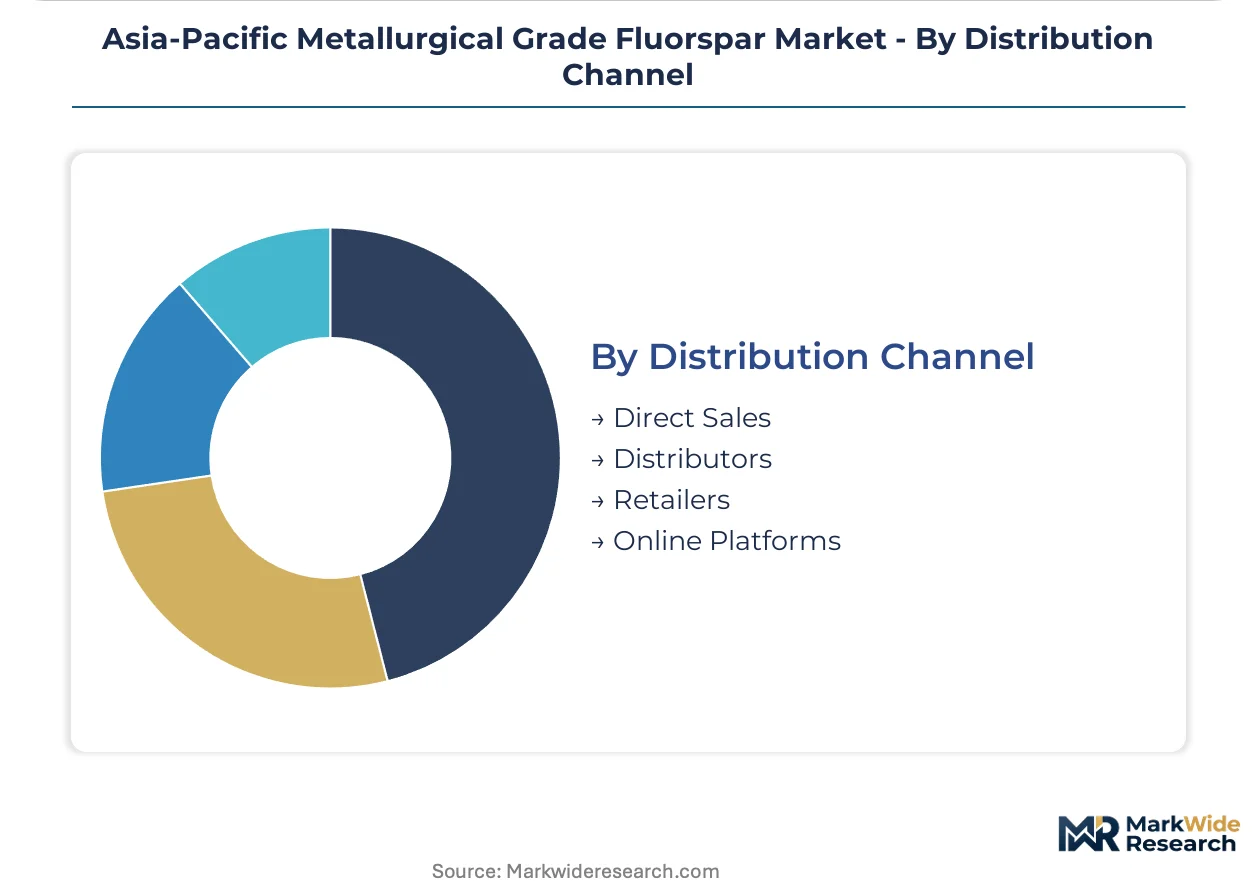
Distribution Channel:
Procurement consolidation at major steel and aluminum producers compresses intermediary margins and rewards direct supply relationships with technical service capabilities.
- Direct Sales:Tata Steel, JSW, and Hoa Phat Group centralize purchasing through dedicated raw materials divisions, displacing fragmented trader-mediated spot markets with framework agreements.
- Distributors:Regional traders serve mid-scale foundries and cement plants lacking volume thresholds for mill-direct negotiations.
- Retailers:Artisanal ceramic and glass producers procure bagged quantities through local mineral suppliers.
- Online Platforms:Emerging B2B marketplaces facilitate spot price discovery for standardized metallurgical grades.
Direct Sales commands procurement gravity; Online Platforms gain share fastest on price transparency improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steelmakers in Vietnam and Indonesia exhibit the highest price elasticity, switching flux sources rapidly on cost signals, while Japanese aluminum smelters prioritize grade consistency over unit economics, absorbing premium spreads for certified low-silica material.
China
Blast furnace operations at Baowu and Shagang Group sustain bulk fluorspar offtake for slag fluidity control. MIIT enforces GB standards on fluorite mining emissions, forcing capacity consolidation toward compliant operators. Processing clusters concentrate in Zhejiang and Jiangxi provinces where integrated miners with hydroelectric supply contracts secure preferential license renewals.
India
Tata Steel and JSW expand electric arc furnace capacity under the PLI scheme for specialty steel, broadening fluorspar specification requirements for high-grade alloy output. CEA regulates mineral beneficiation discharge under environmental clearance protocols, elevating compliance costs for smaller producers. Maharashtra Minerals Corporation Limited anchors supply relationships through long-term offtake agreements with western Indian steel corridors.
Vietnam
Formosa Ha Tinh and Hoa Phat Group drive sustained fluorspar consumption through electric arc furnace investments for slag fluidity control. The country's national mining regulator tightens environmental benchmarks on mineral extraction permits. Steel production concentrates in the northern provinces near Haiphong port infrastructure, reducing inland logistics costs for imported flux materials.
Indonesia
Greenfield aluminum smelter capacity at Morowali and Bintan creates untapped demand channels for metallurgical-grade flux in electrolytic reduction cells. The country's national investment coordinating board prioritizes downstream mineral processing under industrial downstreaming mandates. Smelter construction timelines in Central Sulawesi outpace domestic fluorspar beneficiation capacity, forcing reliance on imported acid-grade material.
Japan
Aluminum smelters and specialty steel producers impose strict CaF₂ thresholds that fragment supplier certification requirements. METI maintains JIS standards for imported metallurgical flux materials that constrain market access for sub-grade suppliers. Technical qualification protocols require 18-24 month approval timelines, delaying market entry for emerging processors from Southeast Asian supply bases.
Asia-Pacific Metallurgical Grade Fluorspar Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with captive mine-to-port infrastructure separating price-setters from margin-takers. The upper tier commands direct relationships with steel mill procurement divisions, while mid-scale traders compete on spot market liquidity and freight optimization. Three archetypes dominate: basin-integrated miners with renewable power access, trading-dependent processors with offtake flexibility, and hybrid metallurgical-acid grade refiners capturing premium pricing pools. Competitive moves concentrate on long-term framework agreements with fixed-grade specifications and flotation technology upgrades to recover marginal ore bodies.
Within the integrated miner tier, China Kings Resources Group Co., Ltd. and Inner Mongolia Huatong Fluorspar Co. Ltd. represent basin-anchored positions with captive infrastructure across Hunan, Jiangxi, and northern Mongolian deposits. Maharashtra Minerals Corporation Limited occupies a distinct position as an India-based specialist securing domestic steel mill relationships through volume commitment structures. These three entities exemplify how geographic proximity to demand clusters and regulatory compliance capabilities determine tier placement in a market consolidating toward direct procurement channels.
| Leading Market Players |
|---|
| China Kings Resources Group Co., Ltd. |
| Maharashtra Minerals Corporation Limited |
| Steyuan Mineral Resources Group Ltd. |
| Zhengzhou Rongsheng Kiln Refractory Co., Ltd. |
| ORBIA |
| China National Fluorine Chemical Group Corporation |
| Jiangxi Shangfeng Fluorine Chemical Co. Ltd. |
| Hunan Nonferrous Metals Corporation Limited |
| Inner Mongolia Huatong Fluorspar Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements with fixed-grade specifications lock in supply access for Indian steel mills while anchoring price visibility through quarterly adjustment mechanisms tied to CaF₂ content bands. These contract structures concentrate procurement power at Tata Steel and JSW, compressing spot market liquidity and forcing mid-scale traders toward freight optimization plays.
Pricing Analysis
After-sales technical service contracts drive lifetime value for processors with certified laboratory capabilities and on-site metallurgical support. Contract-based long-term offtake dominates, with price differentiation hinging on CaF₂ grade consistency and MIIT environmental compliance certification. Cost compression in standard-grade metallurgical-spar is intensifying because synthetic flux trials in Japan and South Korea reduce intensity per ton of crude steel. Vietnamese electric arc furnace operators show highest price elasticity, switching sources rapidly on cost signals, while Japanese aluminum smelters absorb premium spreads for certified low-silica material.
Supply Chain Analysis
China and Mongolia anchor fluorspar extraction, with Hunan and Jiangxi processing clusters feeding eastern Chinese steelmakers and Indian import demand. Beneficiation circuits draw from run-of-mine ore, hydroelectric power contracts, and flotation reagent supplies. Single-source vulnerability concentrates at Zhejiang integrated miners with captive mine-to-port infrastructure. Distribution runs through mill-direct procurement channels at major steel and aluminum producers, displacing fragmented trader-mediated spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's dual carbon goals are disrupting mining license allocation, compressing supply toward compliant operators with renewable power access and forcing consolidation that rewards scaled beneficiation investment.
For Market Incumbents: Secure preferential license renewals through MIIT emission compliance and captive hydroelectric supply contracts in Zhejiang and Jiangxi. Deepen upstream control over depleted Hunan deposits through sensor-based ore sorting integration, defending against margin compression from synthetic flux substitution trials at Japanese and South Korean steelmakers. For New Entrants and Emerging Players: Lead with Indonesia's greenfield aluminum smelter buildout at Morowali and Bintan, where domestic beneficiation capacity lags smelter construction timelines. Target acid-grade flux supply for electrolytic reduction cells, penetrating through JIS certification investment and 18-24 month qualification protocols for Japanese METI import standards. For Investors and Strategic Acquirers: Capital is best deployed toward basin-integrated miners with renewable power access and dual-certification capabilities spanning metallurgical-spar and acid-spar grades. Over the projection horizon, processors with hybrid refining capabilities capture premium pricing pools as Southeast Asian aluminum capacity expands. Watch for MIIT license consolidation announcements as inflection indicators for competitive tier reorganization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mining | China Kings Resources secures ore supply autonomy across Hunan and Jiangxi basins. |
| Sensor-Based Ore Sorting Deployment | Hunan operators achieve 15-20% lower unit processing costs through automated grade control. |
| Long-Term Offtake Structuring | Maharashtra Minerals Corporation anchors western Indian steel corridor relationships through volume commitments. |
| JIS Certification Investment | Processors unlock Japanese aluminum smelter procurement after 18-24 month METI qualification timelines. |
| Dual-Grade Refining Capability | Hybrid metallurgical-acid grade refiners capture premium pricing from Morowali electrolytic reduction demand. |
Study Parameters
Operator-level perspectives from mine managers, steel mill procurement directors, flotation process engineers, and logistics coordinators anchored the qualitative base for this study. Primary fieldwork combined with secondary validation from customs trade data, MIIT emission compliance filings, CEA environmental clearance protocols, and steel industry association reports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across the analysis window.
Sensitivity analysis tested forecast robustness against variables including CaF₂ ore grade depletion trajectories, MIIT license consolidation pace, and synthetic flux substitution adoption rates. The analytical framework segmented by product type, application, and regional production hub, with CAGRs derived from steel production forecasts and aluminum smelter buildout timelines. Input assumptions incorporated PLI scheme implementation for Indian specialty steel and Indonesia's industrial downstreaming mandates.
Forecasts assume regulatory continuity in China's MIIT emission standards and India's CEA beneficiation protocols; material policy shifts would require re-modeling. Specific risks include accelerated synthetic flux adoption, JIS certification timeline extensions, and renewable power contract renegotiations at Zhejiang processing clusters. Recalibration cycles align with material shifts in mining license allocations and smelter construction completions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
United States Aluminum Extrusion Market
Metals
North America Metal Casting Market
Metals
Global Chromium Market
Metals
Aluminum Tubes Market
Metals
Global Duplex Stainless Steel Market
Metals
Grain Oriented Electrical Steel Market
Metals
North America Iron Casting Market
Metals
Steel Ingots Market
Metals
Copper and Copper Alloy Powder Market
Metals
Gold Smelting Market
Metals
Medium Carbon Steel Market
Metals
China Neodymium Iron Boron Magnet Market
Metals
Asia-Pacific Aluminum Casting Market
Metals
Brazil Aluminum Market
Metals
Global Tin Market
Metals
Recycled Metal Market