
 Titanium Fluoride Phosphate Market | 2026-2036
Titanium Fluoride Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Fluoride Phosphate Market Analytics
Specialty chemical distribution networks serving battery electrolyte and advanced ceramics formulators is rewriting procurement geography for titanium fluoride phosphate. Tronox Holdings Plc anchors North American feedstock supply through integrated titanium mineral processing. Arkema S.A. differentiates via fluorochemical expertise and European regulatory compliance infrastructure. Solvay SA controls pharmaceutical-grade certification pathways that competitors struggle to replicate.
Titanium fluoride phosphate denotes an inorganic salt combining titanium, fluoride, and phosphate moieties, typically synthesized through controlled precipitation or hydrothermal methods yielding crystalline powders with defined particle size distributions below 50 microns; manufacturers engineer this compound for catalytic activity in chemical synthesis and as a precursor in functional ceramic coatings. Industrial grade material dominates volume throughput owing to established specification tolerances and bulk chemical purchasing patterns, while pharmaceutical grade commands premium positioning as dental applications and biomedical coatings tighten purity requirements beyond standard assay thresholds. Coating formulations represent the fastest-expanding application segment as automotive and electronics manufacturers adopt fluoride-phosphate conversion layers for corrosion resistance.
EPA oversight under the Toxic Substances Control Act governs commercial manufacture and importation in the United States, while REACH registration mandates in Europe compel full toxicological dossiers for market access. FDA scrutiny of dental and pharmaceutical applications elevates documentation burdens for grades entering medical channels. Stakeholders must weigh regulatory compliance investments against segment-specific margin structures when allocating capacity across industrial and certified-grade production lines.
Market Dynamics
REACH compliance deadlines in Europe and tightening EPA purity thresholds in the United States are forcing simultaneous reformulation across industrial and pharmaceutical-grade production lines, compressing supplier qualification timelines and reshaping procurement risk assessments.
Growth Catalysts
- Coating Formulation Demand:Automotive and electronics manufacturers in Germany's industrial corridor around Ludwigshafen and Leverkusen are accelerating adoption of fluoride-phosphate conversion layers for corrosion resistance specifications.
- REACH Registration Mandates:Full toxicological dossier requirements for European market access are elevating barriers for unqualified suppliers, consolidating volume toward compliant producers with established ECHA documentation infrastructure.
- Hydrothermal Synthesis Methods:Controlled precipitation techniques yielding sub-50-micron crystalline powders are enabling tighter particle size distributions for catalytic applications in specialty chemical synthesis.
Market Restraints
- Feedstock Concentration:Titanium mineral processing capacity concentrates among integrated North American suppliers, creating captive supply dependencies for fluoride-phosphate compound manufacturers without backward integration into ore refining.
- Fluorochemical Input Volatility:Hydrogen fluoride and fluorosilicic acid pricing fluctuations directly compress margins for precipitation-based synthesis routes, particularly affecting industrial-grade volume producers.
- Substitution Pressure:Zirconium-based conversion coatings and cerium-based rare-earth alternatives are displacing titanium fluoride phosphate in select automotive pretreatment specifications where color requirements permit.
Strategic Opportunities
- Biomedical Coating Certification:FDA 510(k) pathway expansion for dental implant surface treatments creates premium positioning for pharmaceutical-grade material with documented biocompatibility profiles.
- Battery Electrolyte Formulation:Solid-state lithium-metal battery developers are evaluating titanium fluoride phosphate as a lithium-ion conductivity enhancer in ceramic-polymer composite electrolytes.
- Distribution Network Reconfiguration:Direct procurement relationships between specialty chemical formulators and synthesis houses are bypassing traditional distributor markups in North American and European supply channels.
Industry Challenges
- Cross-Contamination Control:Pharmaceutical-grade production lines require dedicated equipment and cleaning validation protocols that extend batch turnaround times and elevate working capital requirements.
- Analytical Method Harmonization:Divergent assay specifications between industrial customers and FDA-submission requirements force dual quality systems that complicate capacity allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Fluoride Phosphate Market |
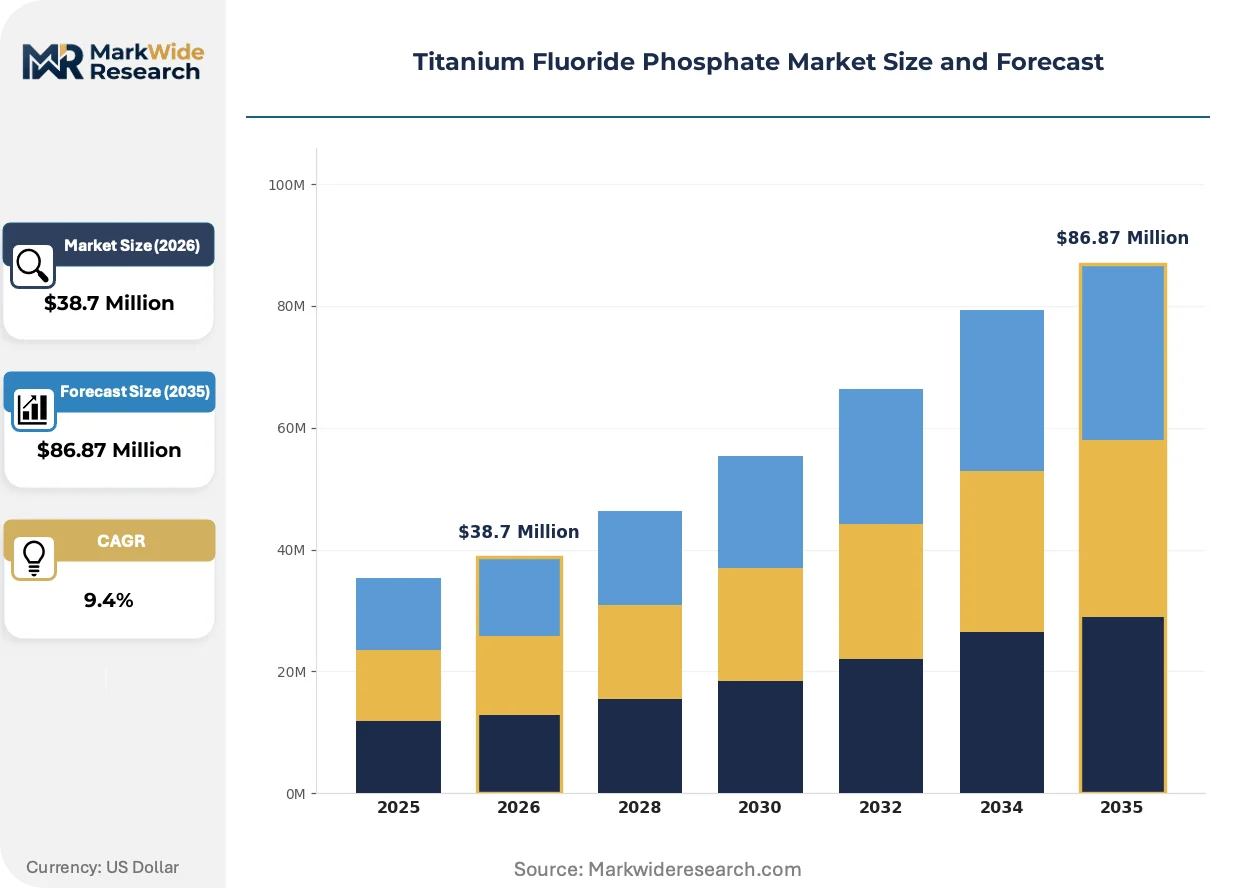
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Laboratory Grade, Food Grade Application: Chemical Synthesis, Surface Treatment, Dental Applications, Coating Formulations End User: Pharmaceuticals, Chemicals, Electronics, Automotive Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Tronox Holdings Plc, Arkema S.A., The Chemours Company, Mitsubishi Chemical Corporation, Solvay SA, Huntsman International LLC, LANXESS AG, Umicore NV, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Fluoride Phosphate Market Evolving Landscape
Continuous flow synthesis methods and in-situ crystallization monitoring are collapsing batch-to-batch variability while enabling real-time purity adjustments that static reactor configurations cannot achieve.
Continuous flow reactor technology is collapsing residence time distributions from hours to minutes in titanium fluoride phosphate precipitation. Specialty ceramic manufacturers in Japan's advanced materials sector are adopting these systems for sub-10-micron particle specifications. The compression of synthesis cycle times is collapsing working capital requirements for mid-volume producers.
EPA Toxic Substances Control Act Section 5 pre-manufacture notification requirements are tightening for new chemical entities with fluoride content. Industrial-grade importers face extended review timelines that delay market entry for non-established suppliers. Battery electrolyte formulators are responding by qualifying domestic synthesis sources to circumvent import notification bottlenecks.
Direct technical service relationships between compound manufacturers and coating formulators are displacing traditional distributor-led specification support. Automotive OEM pretreatment engineering teams in Germany now engage synthesis houses for joint development of conversion layer chemistries. This channel compression is most visible in the Rhine-Neckar metropolitan region where surface treatment R&D clusters concentrate.
Titanium Fluoride Phosphate Market Segmentation
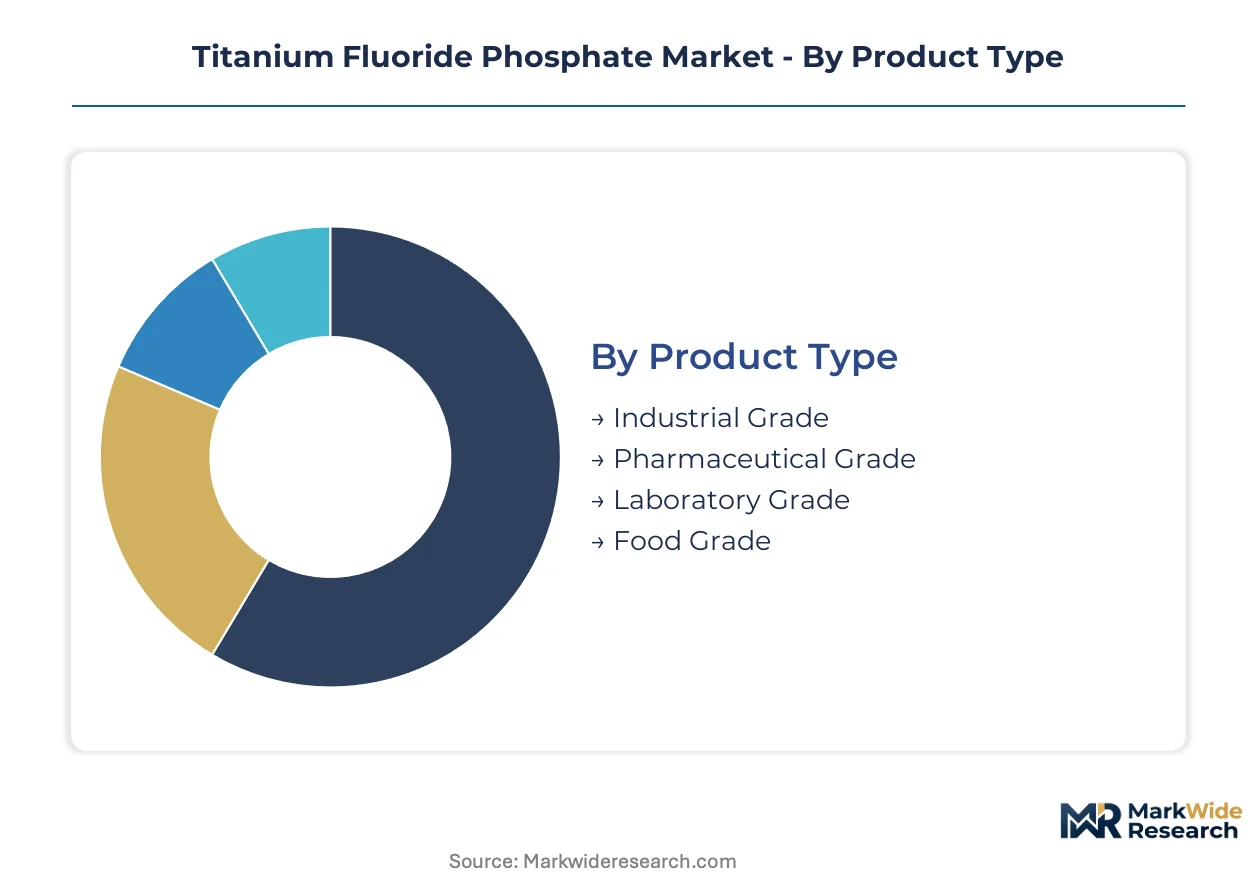
Segmentation in titanium fluoride phosphate markets separates volume-driven industrial procurement from premium-certified grades where regulatory documentation commands price multiples. Each category reflects distinct technical specifications, qualification burdens, and customer relationship structures that shape supplier strategy.
Product Type:
Mature industrial specifications dominate current throughput, while emerging pharmaceutical and food-grade certifications are rewriting purity thresholds and documentation requirements.
- Industrial Grade:Crystalline powders with sub-50-micron particle distributions serve catalytic applications in specialty chemical synthesis. Established specification tolerances and bulk purchasing patterns in Germany's Ludwigshafen-Leverkusen corridor anchor volume demand for corrosion-resistant conversion coatings.
- Pharmaceutical Grade:FDA-scrutinized material for dental implants and biomedical coatings requires biocompatibility documentation and dedicated production lines with cleaning validation protocols. Premium positioning reflects purity thresholds beyond standard assay requirements and extended batch turnaround times.
- Laboratory Grade:Small-batch material for R&D and analytical applications with flexible specification windows.
- Food Grade:Emerging certification pathway for specialized additive applications with evolving safety dossier requirements.
Industrial grade handles the majority of throughput; pharmaceutical grade is the fastest mover on share.
Application:
Cost-tier differentiation separates commodity surface treatment from high-value coating formulations where automotive and electronics OEMs specify performance.
- Coating Formulations:Fluoride-phosphate conversion layers for corrosion resistance command premium positioning in automotive pretreatment specifications. Electronics manufacturers in Japan's advanced materials sector adopt sub-10-micron particle systems for precision coating requirements.
- Chemical Synthesis:Catalytic applications in specialty materials production leverage controlled precipitation methods yielding defined crystalline structures. Hydrothermal synthesis routes enable tighter particle size distributions for reaction efficiency.
- Surface Treatment:Industrial metal finishing operations with established specification tolerances and volume pricing structures.
- Dental Applications:Implant surface treatments requiring FDA 510(k) pathway documentation and biocompatibility profiles.
Surface treatment handles the majority of throughput; coating formulations are climbing the fastest on share.
End User:
Customer-type concentration clusters demand around chemical sector procurement patterns versus electronics and automotive specification engineering.
- Chemicals:Specialty material formulators and synthesis houses drive bulk purchasing for catalytic and precursor applications. Direct procurement relationships are bypassing traditional distributor markups in North American and European channels.
- Pharmaceuticals:Dental and biomedical coating developers require pharmaceutical-grade certification with full toxicological dossiers for regulatory submission.
- Electronics:Solid-state battery developers evaluate titanium fluoride phosphate as lithium-ion conductivity enhancers in ceramic-polymer composite electrolytes.
- Automotive:OEM pretreatment engineering teams engage synthesis houses directly for joint development of conversion layer chemistries.
Chemicals handles the majority of throughput; electronics is gaining share fastest.
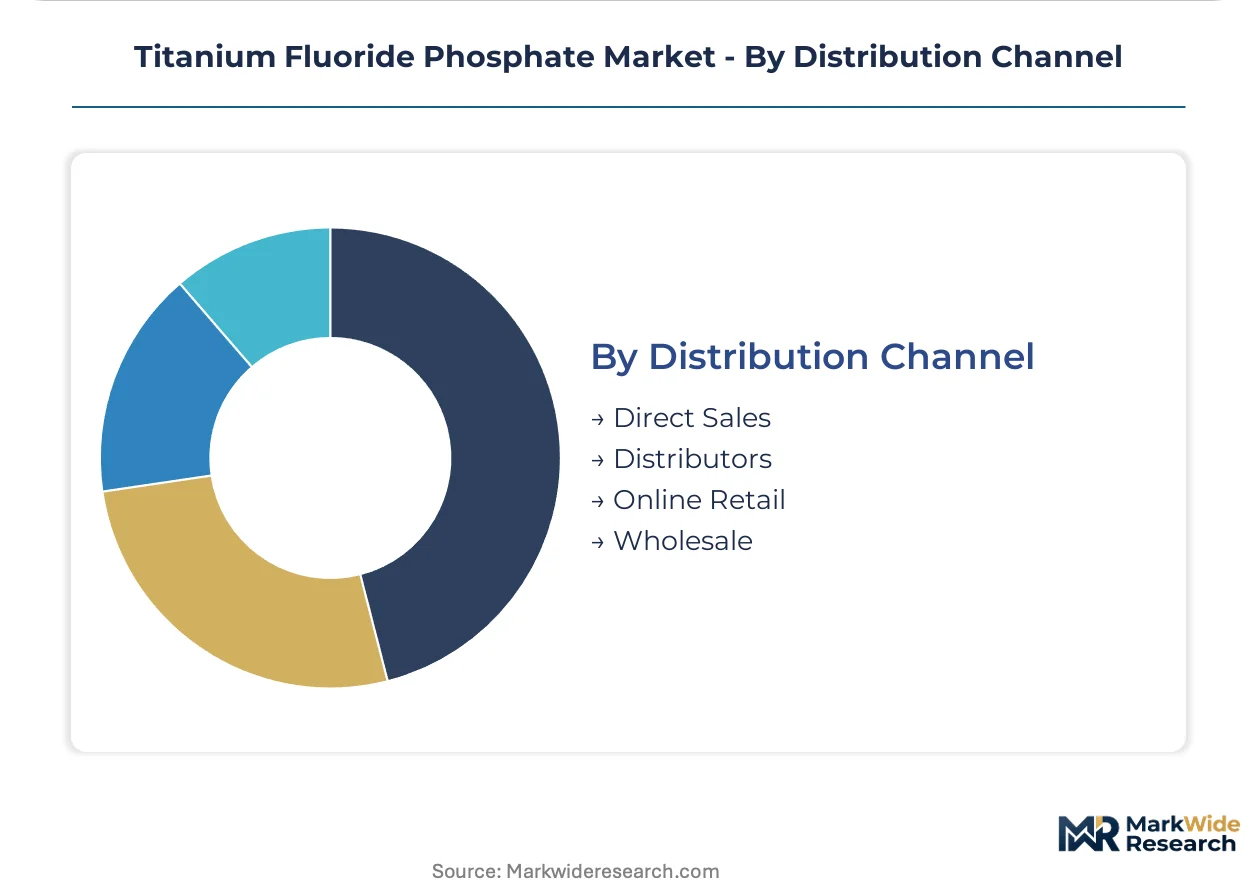
Distribution Channel:
Supply concentration favors direct relationships for qualified volumes, while fragmented channels serve spot purchasing and geographic expansion.
- Direct Sales:Technical service relationships between compound manufacturers and coating formulators displace distributor-led specification support. Automotive OEM engineering teams in Germany's Rhine-Neckar region now engage synthesis houses for joint chemistry development.
- Distributors:Specialty chemical distribution networks serve battery electrolyte and advanced ceramics formulators with regional inventory positioning.
- Online Retail:Laboratory-grade and small-volume procurement with limited specification support.
- Wholesale:Bulk industrial-grade volume with standardized delivery terms and minimal technical service.
Direct sales handles the majority of throughput; distributors are expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH mandates from ECHA anchor European demand qualification, while EPA Toxic Substances Control Act enforcement reshapes North American supplier access. Japan's METI oversight and China's evolving chemical registration frameworks complete the regulatory perimeter governing titanium fluoride phosphate trade.
Germany
Automotive pretreatment engineering teams at BMW and Volkswagen drive coating formulation specifications for corrosion-resistant conversion layers. REACH registration dossiers submitted to ECHA require full toxicological profiles for industrial-grade import authorization. The Rhine-Neckar metropolitan region clusters surface treatment R&D facilities near Ludwigshafen and Leverkusen where formulators engage synthesis houses directly.
United States
Battery electrolyte developers evaluate titanium fluoride phosphate for solid-state lithium-metal conductivity enhancement. EPA Section 5 pre-manufacture notification requirements extend review timelines for fluoride-containing chemical entities. The Gulf Coast petrochemical corridor concentrates hydrofluoric acid feedstock supply, anchoring precipitation-based synthesis capacity for domestic producers.
Japan
Advanced ceramics manufacturers adopt continuous flow reactor systems for sub-10-micron particle specifications in precision coating applications. METI industrial standards govern fluorochemical handling protocols in manufacturing facilities. The Nagoya-Chubu region hosts specialty material formulators serving electronics OEMs with direct technical service relationships.
China
Titanium mineral processing capacity supports backward-integrated feedstock supply for fluoride-phosphate compound manufacturers. MEE environmental compliance inspections tighten wastewater discharge standards for hydrothermal synthesis operations. The Yangtze River Delta concentrates chemical synthesis houses serving both domestic coating formulators and export-oriented pharmaceutical-grade producers.
Titanium Fluoride Phosphate Market Competitive Landscape
Integrated mineral processors and specialty fluorochemical houses split the market along feedstock control versus formulation expertise vectors. Three archetypes dominate: titanium ore refiners with captive chemical derivative capacity, European regulatory compliance specialists with ECHA documentation infrastructure, and Asian synthesis houses leveraging continuous flow process technology. Competitive moves concentrate on backward integration into ore refining and direct technical service relationships that bypass distributor channels.
Among North American feedstock-integrated players, Tronox Holdings Plc occupies a position exemplifying mineral-to-chemical vertical control. Arkema S.A. and Solvay SA represent the European compliance-specialist archetype, with the latter anchoring pharmaceutical-grade certification pathways that competitors struggle to replicate. These three companies illustrate how geographic regulatory alignment and feedstock access stratify competitive positioning across industrial and certified-grade segments.
| Leading Market Players |
|---|
| Tronox Holdings Plc |
| Arkema S.A. |
| The Chemours Company |
| Mitsubishi Chemical Corporation |
| Solvay SA |
| Huntsman International LLC |
| LANXESS AG |
| Umicore NV |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's container pricing volatility compresses margins for industrial-grade producers sourcing fluorochemical inputs from German ports while amplifying price premiums for pharmaceutical-grade material with dedicated cold-chain documentation. This logistics cost dynamic concentrates procurement power among backward-integrated suppliers with captive titanium mineral processing, forcing spot-market buyers into steeper customization premiums or volume-commitment contracts.
Pricing Analysis
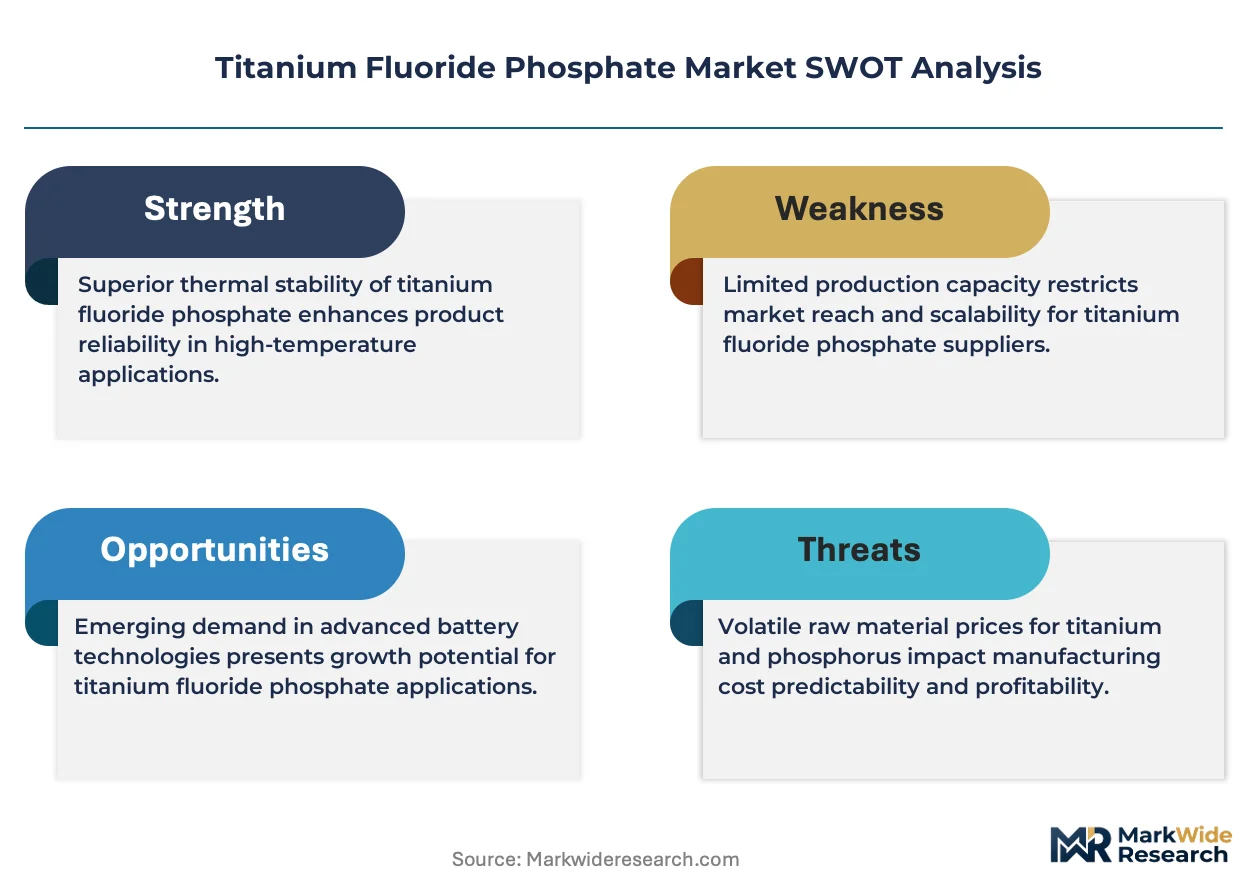
Configured-to-order pricing for pharmaceutical-grade batches with FDA 510(k) documentation runs three to five multiples above standard industrial-grade spot quotes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden, with REACH-registered European material commanding tier-one positioning. Cost compression in industrial-grade channels is intensifying because hydrogen fluoride feedstock volatility feeds directly into precipitation-based synthesis economics. Battery electrolyte formulators exhibit lowest price sensitivity due to performance-specification lock-in, while metal-finishing job shops face acute margin pressure from zirconium-substitution alternatives.
Supply Chain Analysis
Export-control restrictions on hydrofluoric acid purification technology limit technology transfer to emerging synthesis houses, constraining capacity expansion outside established regulatory jurisdictions. Feedstock supply concentrates in Australia, South Africa, and China for titanium mineral concentrates, while fluorochemical processing clusters in Germany, Japan, and the United States. Hydrogen fluoride, fluorosilicic acid, and high-purity titanium tetrachloride constitute the critical input trio. Single-source vulnerability pervades pharmaceutical-grade production where dedicated equipment requirements prevent rapid supplier switching. Distribution runs through direct technical service relationships for qualified volumes, with specialty chemical distributors serving geographic expansion and spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Titanium fluoride phosphate sits in early-cycle expansion as solid-state battery developers accelerate qualification timelines for ceramic-polymer electrolyte formulations. Coating formulators in automotive pretreatment represent a parallel penetration vector with established specification pathways.
For Market Incumbents: Pre-empt zirconium-based substitution in automotive conversion coatings by embedding joint-development clauses into OEM pretreatment engineering contracts. Deepen backward integration into titanium mineral processing to escape hydrogen fluoride margin volatility. Arkema S.A. and Solvay SA demonstrate how ECHA documentation infrastructure becomes a defendable moat when REACH deadlines compress supplier qualification windows. For New Entrants and Emerging Players: Mid-volume pharmaceutical-grade production for dental implant surface treatments represents the most penetrable entry point, as FDA 510(k) pathway specialization rewards focused compliance investment over scale. Continuous flow synthesis technology for sub-10-micron particle specifications opens technical differentiation against batch-reactor incumbents. A technical-service-led go-to-market model bypasses distributor markups while capturing specification influence at coating formulator R&D labs. For Investors and Strategic Acquirers: REACH registration deadline acceleration reshapes the acquisition landscape toward targets with existing ECHA dossier infrastructure rather than greenfield compliance builds. Five-to-ten-year viability hinges on positioning within battery electrolyte supply chains as solid-state chemistry transitions from R&D to pilot production. Watch for qualification announcements from lithium-metal battery developers as the inflection signal separating speculative from contracted demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Mineral Processing | Captive ore refining insulates margin from feedstock volatility and secures supply continuity. |
| Continuous Flow Reactor Deployment | Sub-10-micron particle specifications meet Japanese electronics OEM precision coating requirements. |
| FDA 510(k) Pathway Investment | Biocompatibility documentation unlocks premium positioning in dental implant surface treatment markets. |
| Direct Technical Service Relationships | Bypassing distributor channels captures specification influence at automotive pretreatment engineering teams. |
| REACH Registration Dossier Completion | Full ECHA toxicological documentation becomes mandatory for European industrial-grade market access. |
Research Methodology
A standing panel of titanium mineral procurement directors, fluorochemical plant managers, coating formulator R&D leads, and battery electrolyte development scientists provided ongoing calibration across primary fieldwork phases. Secondary validation drew from customs trade databases, SEC 10-K filings of integrated mineral processors, ECHA registration dossiers, and ACC sector reports. Bottom-up volume estimates from synthesis house capacity utilization triangulated against top-down demand modeling from end-use application consumption patterns.
Scenario-bracketing anchored the analytical framework with low, base, and high penetration assumptions across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, regional production hub, and particle size specification band. CAGRs derived from slope-intercept fitting of historical price-volume elasticities and forward capacity expansion announcements. Industry-specific inputs incorporated REACH compliance timeline uncertainty and solid-state battery developer qualification progress.
Macroeconomic conditions sit as an overlay; deviation in industrial chemical demand cycles, freight rate volatility, or fluorochemical feedstock pricing would shift the trajectory. Forecasts reflect assumptions around regulatory deadline adherence and technology substitution thresholds. Material shifts in EPA Section 5 enforcement intensity or ECHA dossier acceptance rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Polyquaternium 6 Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Specialty Plasticizer Market
Specialty Chemicals
Fatty Alcohol Alkoxylates Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Insoluble Fibers Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Sophorolipids Market