
 Global Hydrogen Fluoride Market | 2026-2036
Global Hydrogen Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrogen Fluoride Market Outlook
The capital-intensity divergence between integrated fluorspar-to-derivative producers and standalone hydrogen fluoride refiners is redrawing competitive boundaries across the industry. Solvay leverages captive access to Belgian fluorspar reserves and vertical integration into fluoropolymer downstream units to sustain margin capture across the value chain. Dongyue Group anchors its position through massive integrated manufacturing complexes in Shandong province, while Honeywell International Inc. differentiates via proprietary process technologies for ultra-high-purity grades demanded by semiconductor fabricators.
Hydrogen fluoride is an inorganic compound with the chemical formula HF, existing as a colorless gas or fuming liquid with a boiling point of 19.5 degrees Celsius and a strong tendency to form hydrogen-bonded oligomers; industrially it is produced primarily through the reaction of fluorspar (calcium fluoride) with sulfuric acid, serving as the foundational feedstock for nearly all fluorine-containing chemicals including refrigerants, pharmaceuticals, and agrochemicals. Anhydrous hydrogen fluoride commands premium positioning due to its essential role in fluoropolymer and fluorocarbon production where moisture sensitivity eliminates aqueous alternatives. Electronics end users represent the fastest-expanding demand pool as semiconductor etching and cleaning applications require sub-ppb purity grades that command substantial price premiums over standard industrial specifications.
EPA regulations under the Clean Air Act and Toxic Substances Control Act impose stringent emissions controls and workplace exposure limits that shape capital deployment decisions for US-based production assets. REACH registration requirements and the EU F-Gas Regulation are simultaneously constraining certain fluorocarbon applications while redirecting investment toward fluoropolymer and battery-electrolyte fluoride salts. Stakeholders must monitor the evolving interface between fluorochemical phase-down mandates and emerging demand from lithium-ion battery electrolyte formulations to calibrate long-term capacity and product-mix decisions.
Market Dynamics
Fluoropolymer demand from semiconductor lithography and electric vehicle battery electrolytes is pulling anhydrous hydrogen fluoride capacity toward ultra-high-purity grades, compressing margins for standard industrial specifications and forcing technology upgrades across the supply base.
Growth Catalysts
- Fluoropolymer feedstock demand:PTFE and PVDF synthesis for automotive wire coatings and lithium-ion battery binders is expanding offtake from integrated chemical complexes.
- China MEE environmental enforcement:Tighter emissions standards under the Ministry of Ecology and Environment are accelerating consolidation toward large-scale producers with advanced scrubbing systems.
- Semiconductor etching applications:Sub-ppb purity requirements for wafer cleaning and oxide removal are creating premium pricing tiers for electronics-grade material.
Market Restraints
- Fluorspar supply concentration:Reserves in Mexico, Mongolia, and South Africa limit feedstock security for refiners lacking captive mining assets or long-term offtake contracts.
- EU F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon refrigerants are constraining traditional fluorocarbon demand pools and redirecting capital toward alternative fluorine derivatives.
- Moisture sensitivity in handling:Anhydrous hydrogen fluoride requires specialized carbon-steel or Monel alloy infrastructure, elevating capital costs versus aqueous alternatives.
Strategic Opportunities
- India specialty chemical expansion:PLI scheme incentives for domestic manufacturing and import substitution are attracting greenfield investment in fluorochemical intermediates.
- Battery electrolyte fluoride salts:Lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide synthesis for EV batteries represents an emerging high-value application channel.
- Japan semiconductor reshoring:METI subsidies for domestic chip fabrication are expanding local demand for ultra-high-purity etching gases and cleaning reagents.
Industry Challenges
- Process safety certification timelines:OSHA Process Safety Management compliance and EPA Risk Management Plan approvals extend project commissioning by 12-18 months for US-based assets.
- Purification technology integration:Retrofitting existing sulfuric acid-fluorspar reactors with distillation and adsorption systems for electronics-grade output requires substantial reconfiguration of legacy infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrogen Fluoride Market |
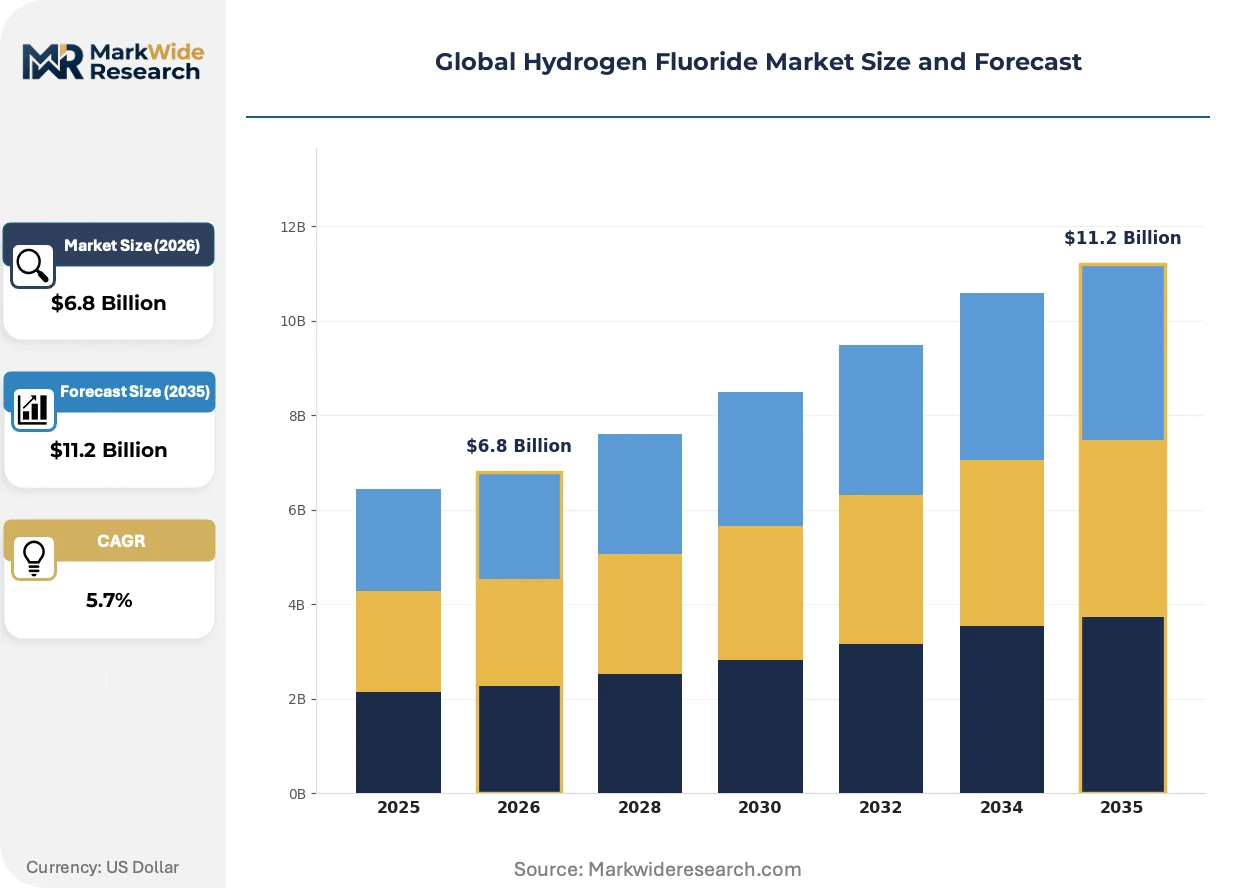
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Hydrogen Fluoride, Hydrofluoric Acid, Aqueous Hydrogen Fluoride, Hydrogen Fluoride Gas Application: Aluminum Production, Fluoropolymers, Oil Refining, Glass Etching End User: Chemicals, Refineries, Electronics, Pharmaceuticals Delivery Mode: Compressed Cylinders, Bulk Transport, Storage Tanks, Rail Tankers |
| Companies Covered | LANXESS, Orbia Fluor & Energy Materials, Honeywell International Inc., Navin Fluorine International Limited, The Linde Group, Solvay, Dongyue Group, Stella Chemifa Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrogen Fluoride Market Strategic Shifts
Process intensification and digital process control are compressing unit economics for high-purity production, while regulatory phase-downs in fluorocarbons redirect technical investment toward battery and polymer applications.
Membrane-based purification systems employing perfluorinated ionomer barriers are supplanting traditional multi-stage distillation for electronics-grade hydrogen fluoride production. Semiconductor fabricators in Taiwan and South Korea are specifying membrane-refined material for 3nm and below process nodes. This transition is compressing capital requirements for new entrants while raising purity thresholds that incumbent distillation-based producers must match.
REACH registration requirements and the EU F-Gas Regulation are simultaneously constraining refrigerant applications while redirecting investment toward fluoropolymer and battery-electrolyte fluoride salts. Chemical producers are reformulating product portfolios to emphasize non-refrigerant fluorine derivatives. Western European capacity is pivoting toward specialty grades with higher technical barriers and reduced regulatory exposure.
Long-term offtake agreements with semiconductor foundries are displacing spot-market transactions as the dominant procurement mechanism for electronics-grade material. Tier-one chip manufacturers in Japan and the United States are securing dedicated supply lines with purity guarantees extending five to seven years. This contractual shift is visible most acutely in East Asian chemical clusters where integrated producers anchor supply security for major fabricators.
Global Hydrogen Fluoride Market Segmentation
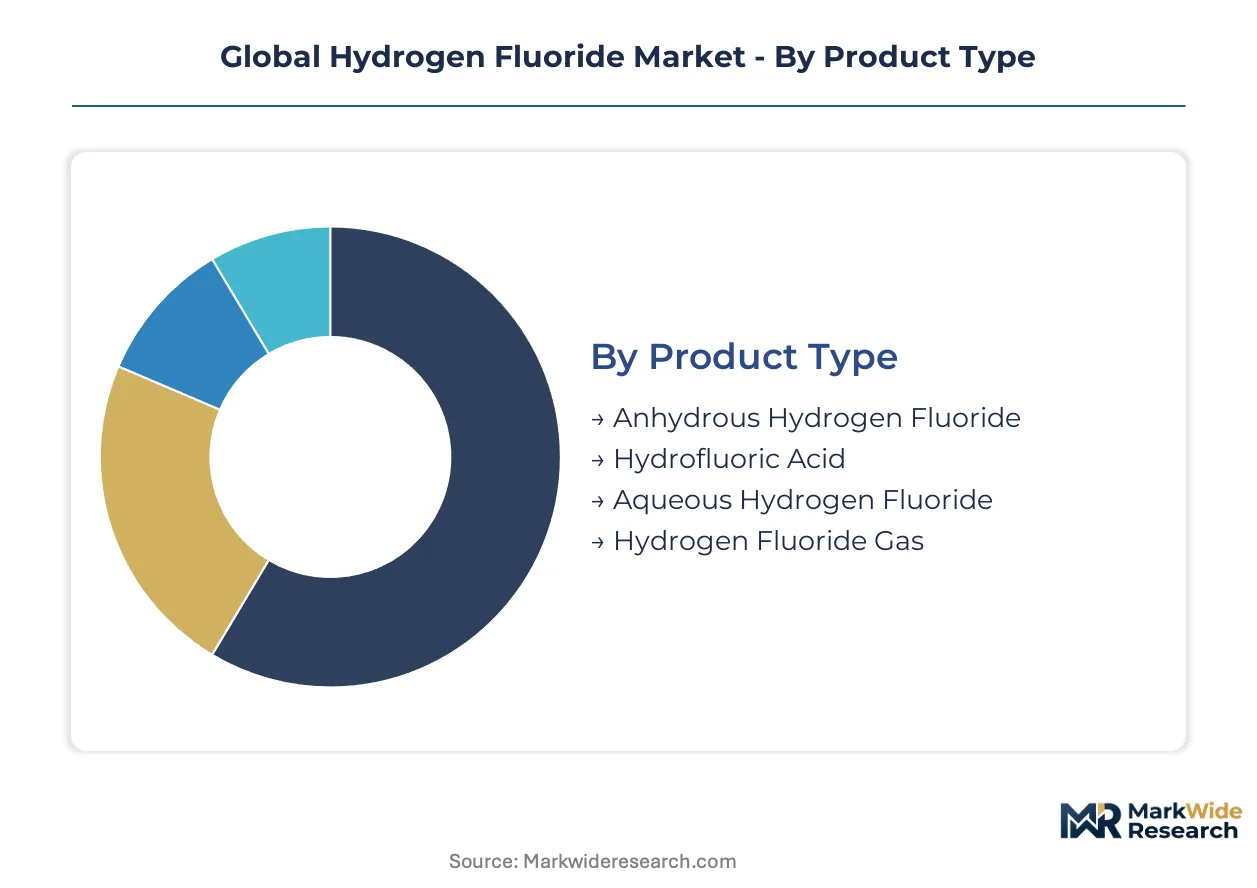
Hydrogen fluoride segmentation reveals how product specifications, application purity requirements, and delivery logistics fragment margin capture across the value chain. Producers must align capacity configurations with the divergent technical and regulatory demands of aluminum smelters, semiconductor fabricators, and pharmaceutical synthesizers.
Product Type:
Anhydrous grades command the steepest price premiums due to moisture-sensitive downstream applications, while aqueous variants serve cost-sensitive industrial etching and metal treatment markets.
- Anhydrous Hydrogen Fluoride:Contains less than 0.5% water by weight, requiring carbon-steel or Monel alloy handling infrastructure. Fluoropolymer and battery-electrolyte salt manufacturers in Zhejiang province and Texas Gulf Coast chemical clusters drive offtake, with sub-ppb electronics specifications capturing margins five to seven times above industrial grades.
- Hydrofluoric Acid:Aqueous solutions at 49-70% concentration dominate aluminum fluoride production and petroleum alkylation catalyst regeneration. Refiners along the US Gulf Coast and aluminum smelters in Quebec represent concentrated demand pools where volume contracts offset lower unit margins.
- Aqueous Hydrogen Fluoride:Dilute solutions below 50% concentration serve glass etching and metal pickling applications with reduced handling complexity.
- Hydrogen Fluoride Gas:Cylinder-supplied material for laboratory and small-scale pharmaceutical fluorination reactions where batch scale precludes bulk delivery economics.
Anhydrous hydrogen fluoride holds installed capacity concentration among integrated fluorspar-to-derivative producers. Hydrofluoric acid is rotating up the share rankings as aluminum smelter restarts and refinery alkylation expansions accelerate in India and the Middle East.
Application:
Application segmentation tracks how fluorine chemistry migrates from commodity metal processing toward high-value polymer and electronics materials.
- Fluoropolymers:PTFE and PVDF synthesis consumes anhydrous material at multi-thousand-tonne scale for wire insulation, battery binders, and semiconductor component housings. Automotive electrification and lithium-ion battery manufacturing expansion in South Korea and Germany are concentrating demand growth.
- Electronics:Wafer etching and chamber cleaning specifications demand sub-ppb metal ion purity with dedicated supply chain segregation from industrial grades. Taiwan Semiconductor Manufacturing and Samsung Foundry long-term offtake agreements are displacing spot procurement for 3nm and below process nodes.
- Aluminum Production:Synthetic cryolite and aluminum fluoride manufacturing from fluorspar-derived hydrogen fluoride supports primary smelting electrolyte chemistry.
- Oil Refining:Alkylation unit catalyst regeneration and acid-soluble oil removal in gasoline production consumes recurring volumes with regional concentration around major refining hubs.
Fluoropolymer applications hold installed capacity among integrated chemical complexes with captive anhydrous production. Electronics-grade material is climbing the fastest as semiconductor fabricators reshore and expand leading-edge capacity in Japan, the United States, and Taiwan.
End User:
End-user segmentation exposes divergent procurement patterns between spot-market chemical traders and long-term contract semiconductor supply chains.
- Electronics:Semiconductor and display panel manufacturers specify multi-year purity guarantees with dedicated logistics and contamination prevention protocols. METI subsidies for Japanese domestic chip fabrication and CHIPS Act incentives in the United States are expanding this user category fastest.
- Chemicals:Fluorochemical intermediate and refrigerant producers purchase standard industrial grades through quarterly contract structures with limited purity requirements.
- Refineries:Petroleum alkylation operations consume hydrofluoric acid under recurring supply agreements indexed to regional fluorspar feedstock costs.
- Pharmaceuticals:Active pharmaceutical ingredient fluorination employs small-lot anhydrous gas or specialized reagent grades with batch-scale delivery and stringent documentation requirements.
Chemical sector end users hold installed capacity absorption through legacy fluorocarbon and refrigerant production lines. Electronics end users are gaining share fastest as semiconductor capital expenditure cycles concentrate demand among ultra-high-purity qualified suppliers.
Delivery Mode:
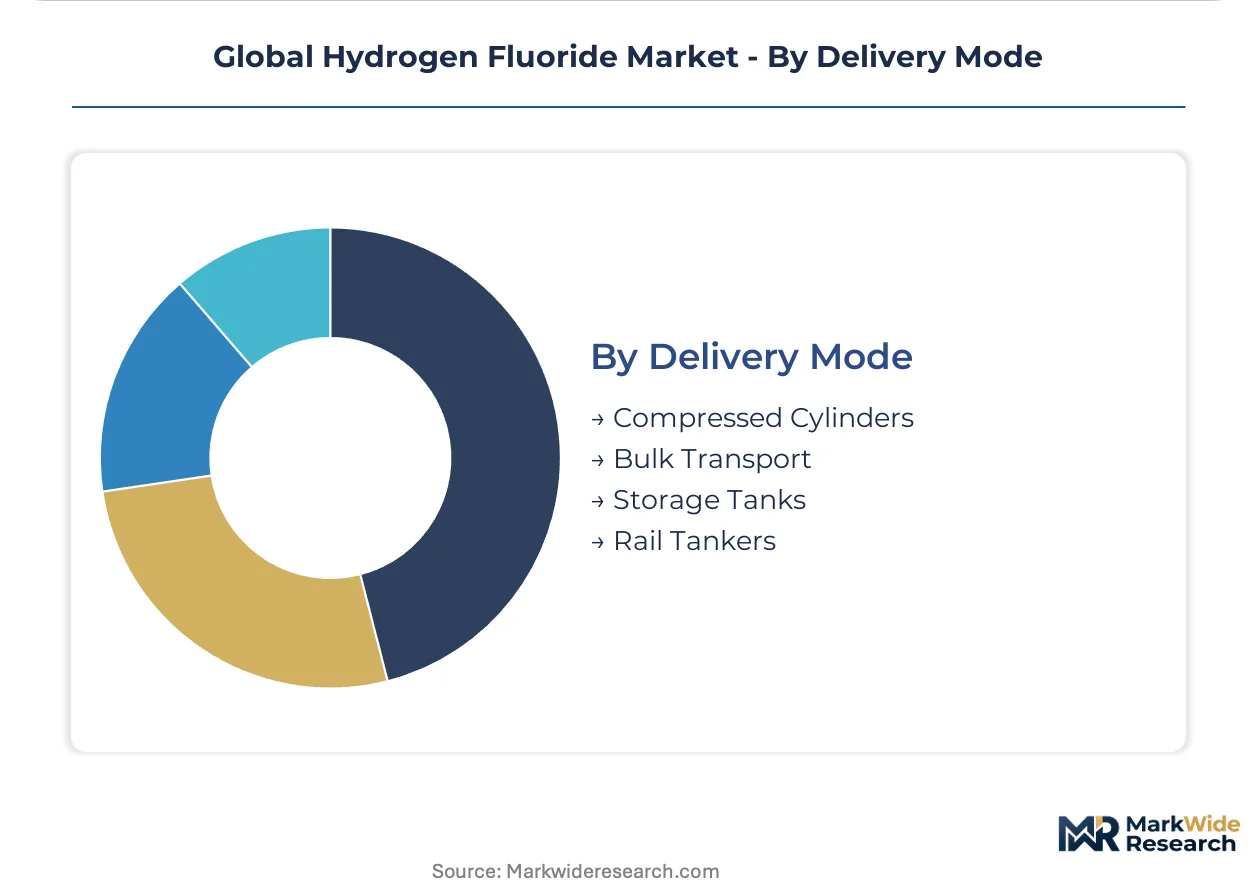
Delivery infrastructure segmentation reflects the tension between bulk economies of scale and contamination risks in high-purity supply chains.
- Bulk Transport:Dedicated tanker truck and pipeline delivery of anhydrous material to integrated fluorochemical complexes achieves lowest unit logistics costs. Dongyue Group and Chemours operate captive pipeline networks connecting production to downstream derivative units in Shandong and West Virginia.
- Compressed Cylinders:High-pressure steel or aluminum cylinders for electronics-grade material enable contamination-free delivery to semiconductor fabs with rigorous cylinder cleaning and certification protocols.
- Storage Tanks:On-site bulk tanks at aluminum smelters and refineries reduce delivery frequency and enable inventory management against fluorspar price volatility.
- Rail Tankers:Long-haul bulk movement of industrial-grade material serves inland chemical clusters with pipeline-inaccessible locations.
Bulk transport infrastructure holds installed capacity concentration among coastal integrated producers. Compressed cylinder delivery is expanding share fastest as semiconductor fabrication disperses beyond East Asian chemical clusters toward Arizona, Saxony, and Kumamoto.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for electronics-grade material concentrates in East Asian chemical clusters, while North American and European producers capture premiums through regulatory compliance and supply security guarantees rather than scale economics.
China
Integrated fluorochemical complexes in Zhejiang and Jiangsu provinces consume the majority of domestic anhydrous hydrogen fluoride output for PTFE and PVDF synthesis. MEE enforcement of dual carbon goals is shuttering small standalone refiners and consolidating capacity around Shandong-based producers with captive fluorspar access and advanced scrubbing infrastructure.
United States
Semiconductor fabricators in Arizona and Texas are driving fastest-growing demand for sub-ppb purity grades as CHIPS Act subsidies expand domestic wafer production. EPA Risk Management Plan requirements and OSHA Process Safety Management compliance extend project timelines, creating structural advantages for incumbent producers with certified infrastructure along the Gulf Coast.
Japan
METI subsidies for domestic chip fabrication reshoring are expanding local demand for ultra-high-purity etching gases and cleaning reagents. Kyushu and Tohoku chemical clusters are upgrading distillation capacity to meet 3nm process node specifications, with long-term offtake agreements displacing spot procurement from Japanese semiconductor foundries.
Germany
EU F-Gas Regulation phase-downs are redirecting investment from refrigerant applications toward battery-electrolyte fluoride salts and fluoropolymer production. Western European capacity is pivoting toward specialty grades with reduced regulatory exposure, with BASF and Solvay leveraging integrated complexes in Ludwigshafen and Antwerp for higher technical barrier segments.
South Korea
Samsung Foundry and SK Hynix are securing dedicated supply lines with five-to-seven-year purity guarantees, concentrating procurement among qualified suppliers in the Busan-Ulsan chemical cluster. Membrane-based purification systems are supplanting traditional distillation for 3nm and below process nodes, compressing capital requirements for new entrants.
Global Hydrogen Fluoride Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated fluorspar-to-derivative producers capture margin across the value chain while standalone refiners compete on volume. The market consolidates around three strategic archetypes: captive-resource integrated majors, technology-differentiated specialists, and regional scale players. Dominant competitive moves include backward integration into fluorspar mining assets and purification technology licensing for electronics-grade certification.
Among European-headquartered chemical conglomerates, Solvay and Arkema occupy positions emphasizing specialty fluoropolymer downstream integration. Honeywell International Inc. represents the technology-differentiated archetype through proprietary process technologies for ultra-high-purity grades. Dongyue Group anchors the scale-driven end among Chinese integrated producers with massive manufacturing complexes in Shandong province.
| Leading Market Players |
|---|
| LANXESS |
| Orbia Fluor & Energy Materials |
| Honeywell International Inc. |
| Navin Fluorine International Limited |
| The Linde Group |
| Solvay |
| Dongyue Group |
| Stella Chemifa Corporation |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
Membrane-based purification replacing multi-stage distillation for electronics-grade material is simultaneously shifting production geography toward Taiwan and South Korea while compressing capital barriers that once protected incumbent pricing power. This substitution dynamic enables new entrants to match sub-ppb purity specifications without legacy infrastructure investments, fragmenting premium capture across the value chain.
Pricing Analysis
Configured-to-order electronics-grade material commands spreads five to seven times above standard industrial specifications, with contract-based long-term offtake agreements dominating procurement for semiconductor fabricators. Price differentiation rests on certification tier and volume scale, with sub-ppb metal ion purity requirements and dedicated supply chain segregation justifying substantial premiums. Cost compression in industrial-grade hydrofluoric acid is intensifying because aluminum smelter and refinery buyers wield concentrated purchasing power through quarterly contract structures. Chemical sector purchasers exhibit highest price sensitivity due to commoditized fluorocarbon applications, while electronics end users prioritize supply security over unit cost.
Supply Chain Analysis
China and Mexico anchor fluorspar mining output, with Mongolian and South African reserves providing secondary feedstock streams for refiners lacking captive assets. Hydrogen fluoride production draws from sulfuric acid and fluorspar dependencies, with specialized carbon-steel or Monel alloy handling infrastructure creating fixed-cost barriers for new capacity. Single-source vulnerability concentrates in fluorspar supply, where geopolitical disruptions or export restrictions in any major producing country would cascade through derivative chemical chains. Distribution runs through dedicated tanker networks for integrated complexes and compressed cylinder systems for contamination-sensitive electronics deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication reshoring across Japan, the United States, and Germany is fragmenting demand geography and creating specialized supply niches that reward targeted capability investments over scale economies.
For Market Incumbents: Secure long-term offtake agreements with tier-one chip manufacturers through purity guarantees extending five to seven years, insulating revenue from spot-market volatility. Deepen backward integration into fluorspar mining assets or binding offtake contracts to defend against feedstock cost spikes. Invest in membrane-based purification certification to match emerging technology entrants threatening electronics-grade margins.
For New Entrants and Emerging Players: Lead with battery-electrolyte fluoride salt production for electric vehicle supply chains, where lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide demand outpaces qualified supply. Target India's specialty chemical expansion under PLI scheme incentives, where domestic manufacturing mandates create protected demand pools. Pursue joint venture structures with established semiconductor foundries to secure qualification pathways and dedicated offtake.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional scale players lacking electronics-grade certification but holding fluorspar access and coastal logistics infrastructure. Five-to-ten-year viability hinges on successful purification technology licensing or acquisition to access premium semiconductor supply chains. Monitor EPA Risk Management Plan approval timelines and MEE environmental enforcement actions as inflection indicators for competitive capacity rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Captive feedstock access insulates Dongyue Group and Solvay from price volatility in Mexican and Mongolian supply. |
| Membrane Purification Technology Licensing | Perfluorinated ionomer barrier systems enable new entrants to match Samsung Foundry sub-ppb specifications without distillation assets. |
| Long-term Supply Agreement with Semiconductor Foundries | Taiwan Semiconductor Manufacturing and SK Hynix five-to-seven-year contracts displace spot procurement and anchor revenue visibility. |
| Green Manufacturing Transition | Advanced scrubbing infrastructure satisfies MEE dual carbon enforcement and qualifies producers for EU battery supply chain eligibility. |
| Joint Venture for Battery Electrolyte Salts | Partnerships with lithium-ion cell manufacturers in South Korea and Germany capture fastest-expanding fluorine derivative demand channel. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fluorochemical plant managers, semiconductor procurement leads at tier-one foundries, distribution channel partners, and technical R&D directors specializing in purification systems. Secondary validation drew from customs and trade data, SEC 10-K filings, chemical industry association reports, and EPA Risk Management Plan disclosures. Bottom-up capacity and consumption modeling triangulated against top-down value chain analysis to ensure consistency across segmentation dimensions.
Across the analysis window, projections incorporate grade tier, end-use industry, regional production hub, and purity certification level as core segmentation dimensions. CAGRs were derived from historical demand elasticity patterns and forward-looking capacity expansion announcements. Forecast inputs include semiconductor capital expenditure cycles, electric vehicle battery production schedules, and fluorspar reserve depletion rates from major producing jurisdictions.
Forecasts assume regulatory continuity in EPA emissions controls, REACH registration requirements, and MEE environmental enforcement; material policy shifts would require re-modeling demand trajectories for refrigerant and battery applications. Specific risks include EU F-Gas Regulation acceleration, fluorspar export restrictions, and semiconductor fabrication node transitions beyond current purification capabilities. Recalibration cycles align with material shifts in CHIPS Act subsidy disbursements and METI domestic chip fabrication incentives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Zinc Pyrithione Market
Chemicals
Global Syringaldehyde Market
Chemicals
Mining Flotation Chemicals Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Global Aluminum Chloro Hydrate (ACH) Market
Chemicals
CHPTAC Market
Chemicals
Para Cresol Market
Chemicals
Hexachloroethane Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Global Cysteine Market
Chemicals
Global Glycol Ether Market
Chemicals
Etching Chemicals Market
Chemicals
Dicaprylyl Carbonate Market
Chemicals
Cupric Chloride Market