
 Lithium-Ion Battery's Electrolyte Solvent Market | 2026-2036
Lithium-Ion Battery's Electrolyte Solvent Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery's Electrolyte Solvent Market Foresight
Battery-grade purity specifications is reorganizing competitive dynamics across the electrolyte solvent value chain. Mitsubishi Chemical Corporation leverages its integrated carbonate synthesis capabilities to sustain supply security for Japanese cell manufacturers. Guangzhou Tinci Materials Technology Co., Ltd. anchors domestic Chinese demand through captive purification assets and direct cathode-electrolyte coordination. BASF SE differentiates via its European manufacturing footprint and REACH-compliant product streams for automotive OEM qualification programs.
Lithium-ion battery electrolyte solvents are carbonate-based organic compounds—primarily ethylene carbonate, dimethyl carbonate, and diethyl carbonate—formulated as polar aprotic media that dissolve lithium salts and enable ionic transport between electrodes at operating voltages above 4.2V. These solvents require moisture content below 10 ppm and acid values under 50 ppm to prevent lithium hexafluorophosphate decomposition and electrode corrosion in assembled cells. Ethylene carbonate dominates formulation bases due to its high dielectric constant, though dimethyl carbonate gains share in fast-charging electrolyte blends where lower viscosity improves low-temperature conductivity. Electric vehicle applications command the largest volume pull, while energy storage systems represent the fastest-expanding demand segment as grid-scale lithium iron phosphate installations multiply. Battery-grade purity captures the dominant margin pool, with technical grade relegated to industrial capacitor and specialty chemical offtake.
China's SAMR enforces GB/T standards for battery material purity, while REACH in Europe mandates full substance registration and hazard communication for carbonate imports. The EPA in the United States monitors volatile organic compound emissions from solvent manufacturing under Clean Air Act permits, pressuring producers to deploy carbon capture or thermal oxidizer retrofits. Stakeholders must track evolving fluorinated solvent substitution trials and solid-state battery electrolyte roadmaps that could displace conventional liquid carbonate demand in premium cell architectures.
Market Dynamics
Battery-grade purity thresholds are compressing the supplier base as electric vehicle OEMs enforce sub-10 ppm moisture specifications, forcing carbonate producers to retrofit distillation trains or exit the qualification pool entirely.
Growth Catalysts
- GB/T standard enforcement:China's SAMR mandates trace metal limits below 5 ppm for electrolyte-grade carbonates, accelerating domestic purification capacity buildouts in Jiangsu and Shandong provinces.
- Fast-charging electrolyte formulations:Dimethyl carbonate blends with reduced viscosity enable sub-15-minute charge protocols, pulling volume from ethylene carbonate-heavy legacy recipes.
- Grid-scale energy storage procurement:Lithium iron phosphate installations for utility-scale buffering require high-volume carbonate offtake with multi-year supply agreements.
Market Restraints
- Ethylene oxide feedstock volatility:Ethylene carbonate synthesis depends on petrochemical ethylene oxide pricing, exposing margin structures to olefin market swings.
- Purification asset concentration:Ultra-high purity distillation capacity clusters in China's eastern coastal provinces, creating geographic single-point vulnerability.
- Solid-state electrolyte substitution trajectory:Sulfide and oxide solid-state cell architectures threaten to displace liquid carbonate demand in premium automotive segments.
Strategic Opportunities
- European REACH-compliant supply gaps:Domestic carbonate purification within the EU remains underdeveloped relative to cell manufacturing expansion, creating import-substitution potential.
- Fluorinated solvent co-formulation:Fluoroethylene carbonate additives for high-voltage cathode stability represent adjacent chemistry expansion beyond conventional carbonates.
- Direct cathode-electrolyte coordination:Integrated cell design workflows enable solvent producers to lock in formulation specifications during cathode material selection phases.
Industry Challenges
- Analytical chemistry talent scarcity:Purity verification at sub-ppm levels requires specialized gas chromatography-mass spectrometry expertise that outpaces training pipeline output.
- Multi-jurisdiction certification lag:Simultaneous qualification under China's GB/T, EU REACH, and US EPA Clean Air Act permits extends commercialization timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery's Electrolyte Solvent Market |
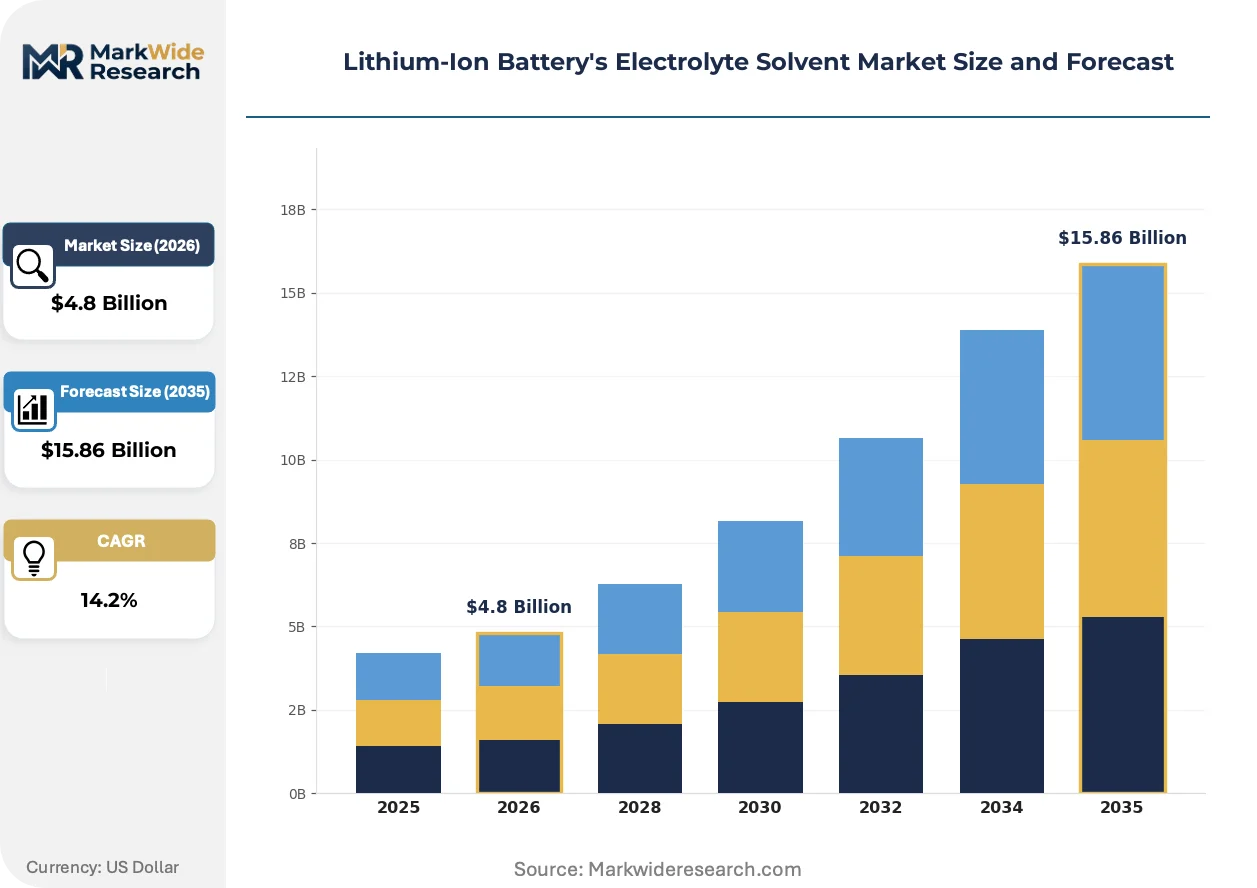
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solvent Type: Propylene Carbonate, Ethylene Carbonate, Dimethyl Carbonate, Diethyl Carbonate Application: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Power Tools Purity Grade: Battery Grade, Technical Grade, Industrial Grade, Pharmaceutical Grade End User: Aerospace, Automotive, Construction, Electronics |
| Companies Covered | Shenzhen Capchem Technology Co., Ltd., Guangzhou Tinci Materials Technology Co., Ltd., Mitsubishi Chemical Corporation, Dongwha Electrolyte, BASF SE, UBE Corporation, Shandong Shida Shenghua Chemical Group Co., Ltd., OUCC, Zhangjiagang Guotai Huarong New Chemical Materials Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery's Electrolyte Solvent Market Shifts & Advancements
Electrolyte solvent innovation is splitting along performance-versus-cost axes as cell manufacturers diverge between premium fast-charging platforms and cost-optimized energy storage systems.
Fluoroethylene carbonate additives for high-voltage cathode protection are bifurcating the formulation market. NCM 811 and lithium-rich manganese oxide cathode adopters specify 3-5% FEC content for cycle life extension above 4.3V operation. This chemistry split is compressing commodity dimethyl carbonate margins while enabling premium pricing for fluorinated co-solvent blends.
REACH substance registration deadlines are tightening import documentation for carbonate solvents entering European cell plants. ECHA's 2024 update to dossier requirements for reproductive toxicity endpoints forced Asian exporters to commission new vertebrate studies. Automotive OEM qualification programs now demand full supply chain registration numbers before contract execution.
Long-term offtake contracting is displacing spot market purchasing for battery-grade carbonates. Tier 1 cell manufacturers in Germany and South Korea now secure 5-7 year volume commitments with price collars indexed to ethylene oxide feedstock. This shift concentrates procurement leverage among the top five global cell producers while marginalizing mid-tier electrolyte formulators without balance sheet depth for upstream commitments.
Lithium-Ion Battery's Electrolyte Solvent Market Segmentation
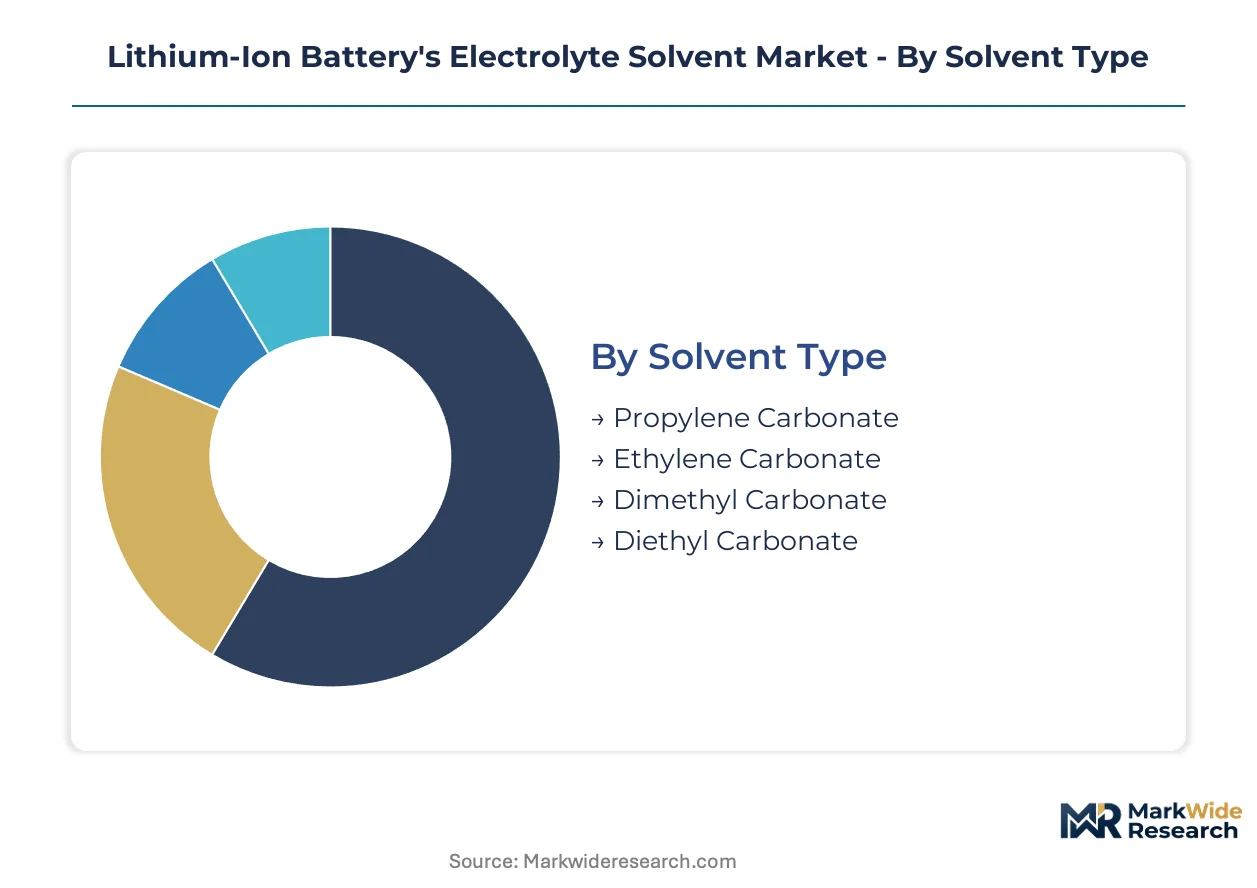
Electrolyte solvent segmentation reveals divergent vulnerability profiles across the value chain. Substitution pressures from solid-state architectures and fluorinated additives hit certain segments harder than others, reshaping investment priorities for purification capacity.
Solvent Type:
Ethylene carbonate faces the most acute substitution threat from fast-charging formulations that favor lower-viscosity co-solvents, while propylene carbonate contends with limited high-voltage cathode compatibility.
- Ethylene Carbonate:High dielectric constant carbonate serving as the primary formulation base for conventional lithium-ion cells. Demand concentrates in NCM 811 cathode applications across South Korean cell manufacturing clusters, though its elevated viscosity limits adoption in sub-15-minute fast-charging protocols.
- Dimethyl Carbonate:Low-viscosity linear carbonate enabling improved ionic conductivity at sub-zero temperatures. Procurement from Chinese Jiangsu province formulators is accelerating as electric vehicle OEMs specify reduced-resistance electrolyte blends for cold-climate performance.
- Diethyl Carbonate:Co-solvent modifier for flash point and viscosity adjustment in high-energy density pouch cells.
- Propylene Carbonate:Alternative cyclic carbonate with wider liquid range but restricted graphite anode compatibility.
Ethylene carbonate anchors the volume base while dimethyl carbonate gains share at the steepest rate.
Application:
Cost tier stratification separates premium automotive qualification requirements from commoditized industrial offtake, with energy storage systems occupying an intermediate position on price-performance curves.
- Electric Vehicles:High-purity carbonate consumption driven by cylindrical and prismatic cell formats for passenger vehicle traction batteries. Procurement from CATL and LG Energy Solution manufacturing lines in China and South Korea enforces sub-10 ppm moisture specifications through multi-year supply agreements.
- Energy Storage Systems:Grid-scale lithium iron phosphate installations requiring high-volume carbonate offtake with relaxed purity tolerances relative to automotive grades. Utility procurement in Texas and California is pulling volume through dedicated technical-grade supply channels.
- Consumer Electronics:Polymer and cylindrical cell applications for smartphones and laptops with established supply chains.
- Power Tools:Cordless equipment batteries with moderate cycle life requirements and price-sensitive formulation standards.
Electric vehicles command the dominant revenue pool while energy storage systems expand most quickly.
Purity Grade:
Supply concentration in China's eastern coastal provinces creates geographic chokepoints for battery-grade qualification, forcing technical-grade producers toward industrial capacitor and specialty chemical markets.
- Battery Grade:Ultra-high purity carbonates with moisture below 10 ppm and acid values under 50 ppm for lithium hexafluorophosphate stability. Chinese SAMR GB/T enforcement is compressing the qualified supplier base as domestic purification assets in Shandong province scale to meet trace metal limits below 5 ppm.
- Technical Grade:Intermediate purity specifications for supercapacitor and industrial battery applications with reduced cycle life requirements.
- Industrial Grade:Standard purity carbonates for solvent extraction and chemical synthesis outside electrochemical applications.
- Pharmaceutical Grade:GMP-compliant solvent production for drug formulation and medical device manufacturing.
Battery grade captures the dominant margin pool while technical grade serves residual demand from non-automotive segments.
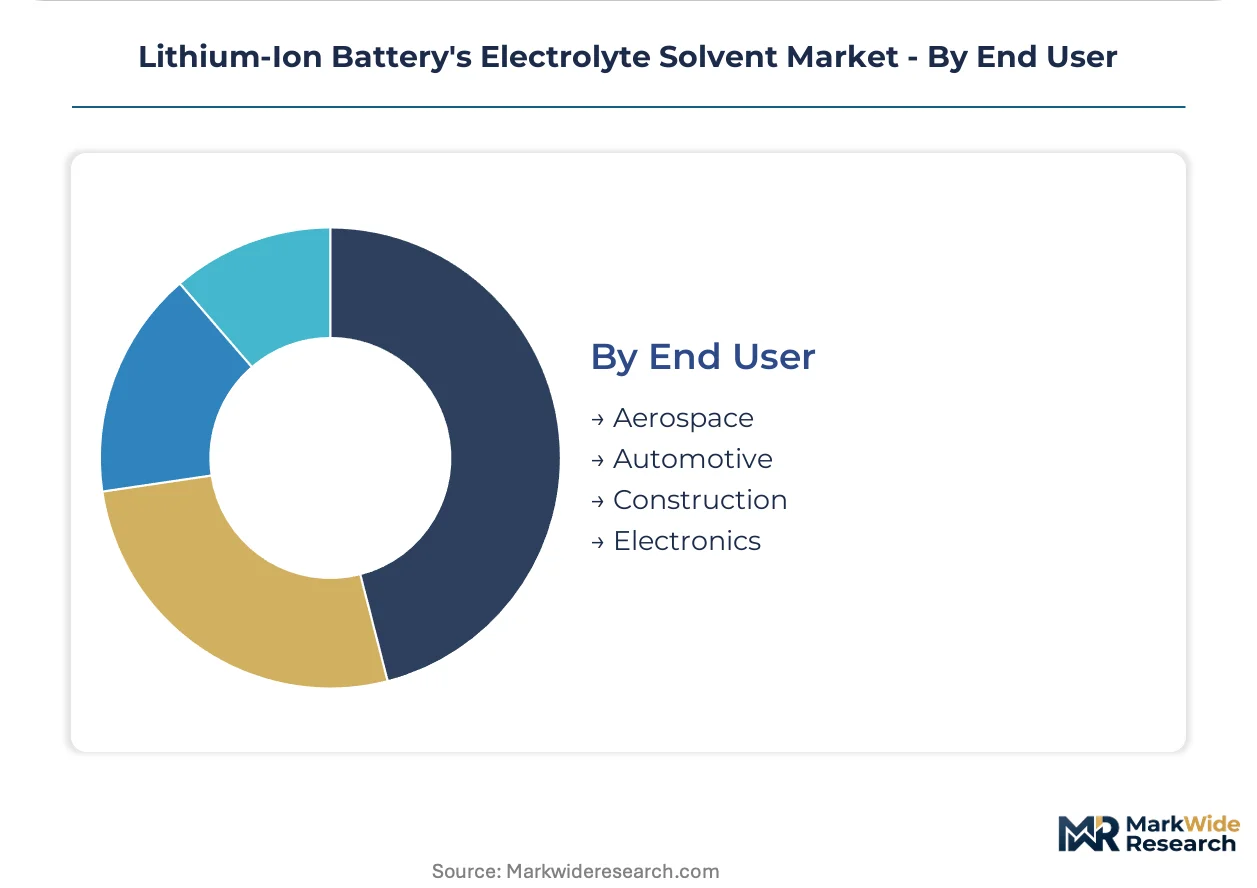
End User:
Customer type segmentation aligns procurement leverage with volume scale, concentrating bargaining power among automotive OEMs while fragmenting electronics and construction demand.
- Automotive:Tier 1 cell manufacturer qualification programs requiring full REACH registration and multi-jurisdiction certification. German and South Korean automotive OEMs now enforce 5-7 year offtake commitments with ethylene oxide-indexed pricing collars.
- Electronics:Consumer device manufacturers with established supply relationships and moderate purity requirements.
- Aerospace:Specialized high-reliability battery applications with stringent thermal stability specifications.
- Construction:Stationary equipment and backup power systems with dispersed, low-volume procurement patterns.
Automotive end users concentrate procurement leverage while electronics maintains the broadest supplier base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping electrolyte solvent procurement geography. China's surplus production capacity drives outbound shipments to European and North American cell plants, while import dependency persists for specialized fluorinated additives and ultra-high purity grades.
China
Jiangsu and Shandong province clusters supply the majority of global battery-grade carbonate output. SAMR's GB/T standards enforcement below 5 ppm trace metal limits is accelerating domestic purification asset expansion. Qingdao and Changzhou industrial zones now host integrated electrolyte formulation campuses serving CATL and BYD manufacturing lines.
Germany
Automotive OEM qualification programs in Stuttgart and Munich are pulling REACH-compliant carbonate volumes from Asian exporters. ECHA's 2024 reproductive toxicity dossier updates extended registration timelines for Chinese suppliers. BASF's Ludwigshafen complex anchors domestic formulation capacity for European cell manufacturing.
South Korea
LG Energy Solution and Samsung SDI procurement in Gyeonggi-do enforces sub-10 ppm moisture specifications through multi-year supply agreements. MFDS chemical substance notifications apply to imported carbonate blends. Ulsan industrial complexes concentrate electrolyte blending operations for cylindrical cell exports.
United States
EPA Clean Air Act permits for volatile organic compound emissions constrain domestic solvent manufacturing expansion. Texas and California utility-scale energy storage procurement is pulling technical-grade carbonate through dedicated supply channels. Domestic purification capacity remains underdeveloped relative to planned cell manufacturing in the Midwest and Southeast.
Japan
METI battery supply chain security initiatives prioritize domestic carbonate stockpiling for automotive cell production. Mitsubishi Chemical's integrated synthesis capabilities serve Toyota and Panasonic manufacturing in Osaka and Nagoya prefectures. Japanese formulators specify proprietary additive packages that limit supplier switching.
Lithium-Ion Battery's Electrolyte Solvent Market Competitive Landscape
Listed leaders compete with private specialists across purification capability and qualification speed. The supplier base compresses into three tiers: integrated petrochemical conglomerates with captive ethylene oxide feedstock, independent purification specialists with GB/T and REACH certification, and regional formulators serving technical-grade industrial demand. Strategic moves concentrate on backward integration into ethylene oxide supply and forward integration into electrolyte salt co-formulation.
Among Chinese specialists, Guangzhou Tinci Materials Technology Co., Ltd. and Shenzhen Capchem Technology Co., Ltd. exemplify the purification-focused archetype with domestic certification depth. Mitsubishi Chemical Corporation occupies a position representing integrated synthesis-to-formulation control for Japanese automotive qualification programs. These three anchors illustrate the geographic and capability segmentation that defines competitive positioning.
| Leading Market Players |
|---|
| Shenzhen Capchem Technology Co., Ltd. |
| Guangzhou Tinci Materials Technology Co., Ltd. |
| Mitsubishi Chemical Corporation |
| Dongwha Electrolyte |
| BASF SE |
| UBE Corporation |
| Shandong Shida Shenghua Chemical Group Co., Ltd. |
| OUCC |
| Zhangjiagang Guotai Huarong New Chemical Materials Co., Ltd. |
| Others |
Supply & Pricing Matrix
China's SAMR GB/T certification gates both supply qualification and price differentiation across the electrolyte solvent value chain, compressing margins for uncertified producers while enabling premium capture for trace-metal-compliant purification assets. Automotive OEM procurement teams leverage multi-jurisdiction certification requirements to extract ethylene oxide-indexed pricing collars from qualified suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with ethylene oxide feedstock indexing. Three-tier pricing structure across battery-grade, technical-grade, and industrial-grade purity levels separates qualified automotive suppliers from commodity industrial offtake. Cost compression in technical-grade tiers is intensifying because Chinese domestic capacity expansion outpaces non-automotive demand growth. Energy storage system procurement teams exhibit highest price sensitivity, while German automotive OEMs accept premium positioning for REACH-compliant supply security.
Supply Chain Analysis
Inventory lead times stretch 18-24 months for multi-jurisdiction certification completion, forcing cell manufacturers into advance purchase commitments. Geographic concentration centers on China, South Korea, and Japan for battery-grade purification capacity. Feedstock dependencies rest on petrochemical ethylene oxide, lithium hexafluorophosphate salt supply, and specialty fluorinated additive imports. Single-source vulnerability concentrates in Jiangsu province distillation clusters. Distribution runs through integrated electrolyte formulation campuses serving CATL, LG Energy Solution, and Samsung SDI manufacturing lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lithium-Ion Battery's Electrolyte Solvent Market represents a high-growth disruption as solid-state electrolyte roadmaps threaten to displace conventional liquid carbonate demand in premium automotive segments. SAMR's trace-metal limit enforcement below 5 ppm accelerates purification asset consolidation.
For Market Incumbents: Secure captive ethylene oxide supply through backward integration into petrochemical feedstock or long-term purchase agreements with olefin producers. Lock in 5-7 year offtake commitments with German and South Korean automotive OEMs before REACH registration deadlines compress the qualified supplier base further. Solid-state electrolyte substitution trajectories in NCM 811 cathode applications represent the priority threat vector requiring fluorinated co-solvent R&D investment. For New Entrants and Emerging Players: REACH fast-track certification for European automotive qualification programs opens white-space entry before 2024 dossier updates fully propagate. Target underdeveloped domestic purification capacity within the European Union, specifically serving BASF's Ludwigshafen complex and planned cell manufacturing expansion in Germany. Fluorinated solvent co-formulation for high-voltage cathode protection offers the most penetrable technology segment with premium pricing headroom. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ultra-high purity distillation capacity as sub-5 ppm trace metal requirements demand multi-stage retrofit investment. Five-to-ten year viability favors acquisition targets with existing GB/T and REACH certification depth rather than greenfield purification plays. Watch solid-state battery pilot production timelines as the critical inflection signal for liquid carbonate demand displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Mitsubishi Chemical's captive synthesis capabilities insulate margin structures from olefin volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB/T, REACH, and EPA qualification compresses commercialization timelines by 18-24 months. |
| Fluorinated Solvent Co-Formulation Expansion | Fluoroethylene carbonate additives for NCM 811 cathodes command premium pricing above 4.3V operation. |
| Long-Term Supply Agreement Structuring | Ethylene oxide-indexed price collars with German OEMs concentrate procurement leverage among top five cell producers. |
| Direct Cathode-Electrolyte Coordination | Guangzhou Tinci's integrated formulation campuses lock specifications during cathode material selection phases. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and SAMR regulatory bulletins preceded structured interviews with electrolyte formulation plant managers, automotive OEM procurement leads, and petrochemical feedstock traders. Primary fieldwork with Chinese purification asset operators in Jiangsu and Shandong provinces combined with secondary validation from ECHA registration databases and EPA Clean Air Act permit records. Bottom-up volume modeling triangulated against top-down ethylene oxide consumption estimates across the analysis window.
Variance decomposition across solvent type, application, and purity grade segmentation dimensions drove analytical framework construction throughout the projection horizon. CAGRs derived from ethylene oxide feedstock pricing trajectories, electric vehicle production forecasts, and grid-scale energy storage procurement pipelines. Solid-state electrolyte substitution rates and fluorinated additive penetration curves served as scenario-weighted inputs.
Underlying assumptions cover sustained electric vehicle production scaling and continued lithium iron phosphate dominance in utility storage, with deviation risk concentrated in solid-state battery commercialization acceleration and ethylene oxide supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Methyl Acetate Market
Solvents
Solvent Green 7 Market
Solvents
Japan Acetonitrile Market
Solvents
Aprotic Solvents Market
Solvents
Allyl Cyanide Market
Solvents
Ethyl Acetate Market
Solvents
Natural Distillates Market
Solvents
Monochlorobenzene Market
Solvents
Coating Solvents Market
Solvents
Propylene Glycol Ether Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
Benzyl Alcohol Market
Solvents
Ethane Market
Solvents
Global Droppers Market
Solvents
6-Xylenol Market
Solvents
Meta-Xylene Market