
 Japan Aluminium Powder Market | 2026-2036
Japan Aluminium Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Aluminium Powder Market Intelligence
Japan's carbon neutrality roadmap under METI is hardening material specifications across downstream industries. Toyal Group leverages its integrated atomization capacity to supply spherical grades for additive manufacturing. Sumitomo Electric Industries anchors demand through its powder metallurgy division serving precision automotive components. Showa Denko K.K. competes on high-purity flake production for electronics and coating applications.
Aluminium powder consists of finely divided metallic aluminium particles produced through atomization, milling, or flaking processes, with particle sizes typically ranging from sub-micron to several hundred microns depending on application requirements. The material functions primarily as a feedstock for powder metallurgy, pyrotechnics, chemical synthesis, and surface coating technologies where high surface-area-to-mass ratios enable reactivity or sintering performance. Atomized aluminium dominates volume flows due to established supply chains serving automotive and aerospace powder metallurgy, while spherical aluminium commands premium positioning from additive manufacturing qualification programs. Pharmaceutical applications represent a developing margin pool as inhalation-grade specifications tighten under PMDA guidance.
METI administers industrial standards through JIS certification requirements that govern particle size distribution and oxide content in aluminium powders for domestic manufacturing. PMDA oversight of pharmaceutical-grade materials shapes purity thresholds and documentation burdens for suppliers targeting medical applications. Stakeholders must monitor evolving JIS revisions and PMDA guidance alignment as qualification timelines extend and customer audit intensity escalates across end-use sectors.
Market Dynamics
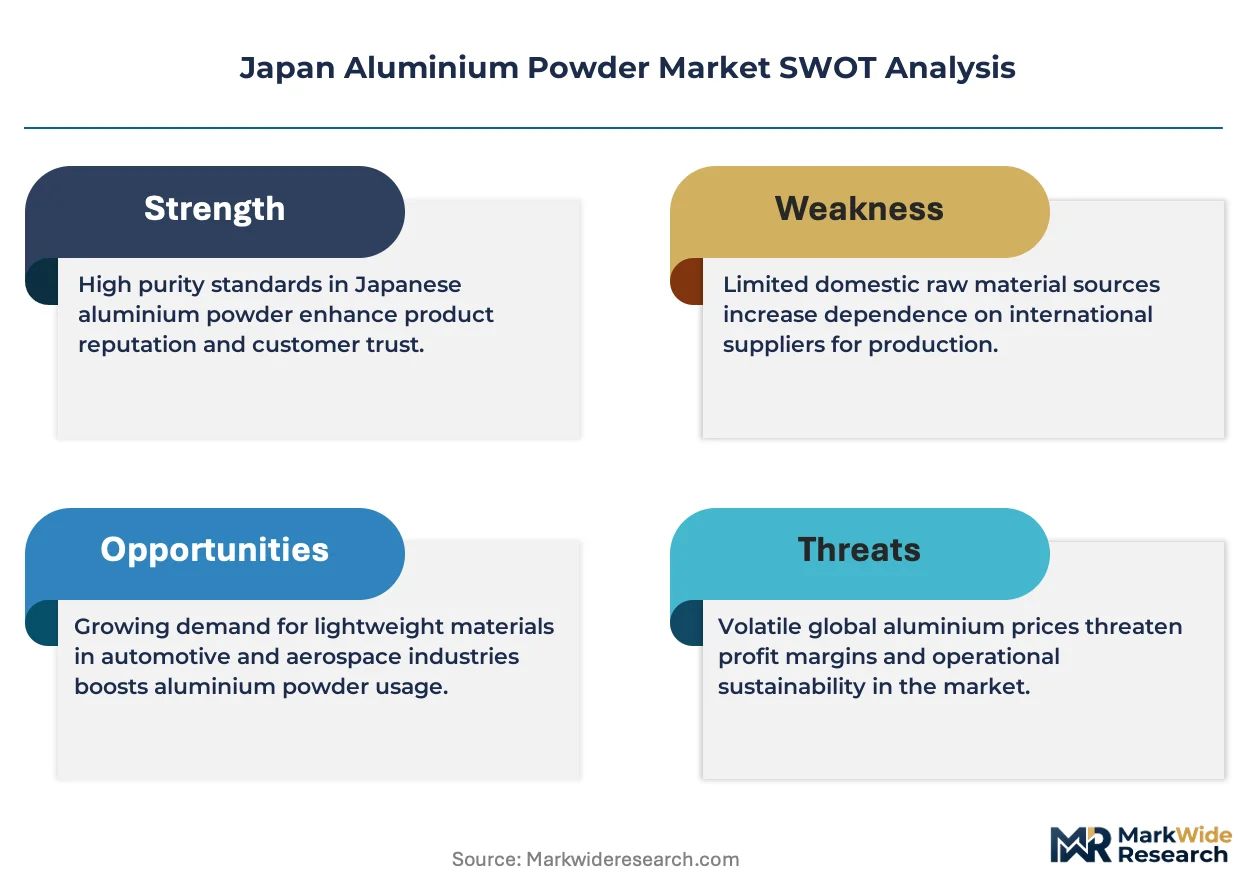
Automotive electrification targets under METI's carbon neutrality roadmap are compressing qualification timelines for lightweighting materials, forcing aluminium powder suppliers to accelerate atomization process validation for electric vehicle battery housings and structural components.
Growth Catalysts
- Lightweighting mandates:OEM electrification programs under METI guidelines are expanding powder metallurgy demand for battery tray assemblies and motor housings.
- JIS H2116 revisions:Updated particle size distribution standards for atomized grades are unlocking aerospace qualification pathways previously blocked by specification gaps.
- Kanto cluster expansion:Concentrated additive manufacturing infrastructure around Tokyo and Yokohama is absorbing premium spherical powder volumes at contract-manufacturing scale.
Market Restraints
- Primary aluminium price volatility:LME-linked input costs transmit directly to atomized powder pricing, compressing margin buffers for toll processors without backward integration.
- Chinese spherical powder imports:Low-cost gas-atomized grades from Shandong and Jiangsu provinces are penetrating Japanese additive manufacturing feedstock channels.
- Oxide content thresholds:JIS-mandated surface oxide limits below 0.5% by mass require controlled-atmosphere handling that elevates processing costs for flake production.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe industrial corridor lacks dedicated aluminium powder distribution infrastructure, creating first-mover advantage for localized atomization investment.
- Pharmaceutical-grade flake:PMDA inhalation powder guidance is tightening purity documentation requirements, opening margin pool for qualified suppliers.
- Hybrid sintering processes:Convergence of binder jetting and conventional press-and-sinter methods is enabling mid-volume automotive component production without full additive manufacturing capital commitment.
Industry Challenges
- Atomization specialist scarcity:Gas atomization process engineering expertise concentrates at legacy suppliers, constraining new entrant scale-up velocity.
- PMDA certification timelines:Pharmaceutical-grade qualification cycles now extend 18-24 months, freezing working capital and delaying revenue recognition.
- Legacy press-and-sinter integration:Conventional powder metallurgy equipment requires retrofitting for fine spherical feedstock compatibility, elevating capex burdens for tier-two automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Aluminium Powder Market |
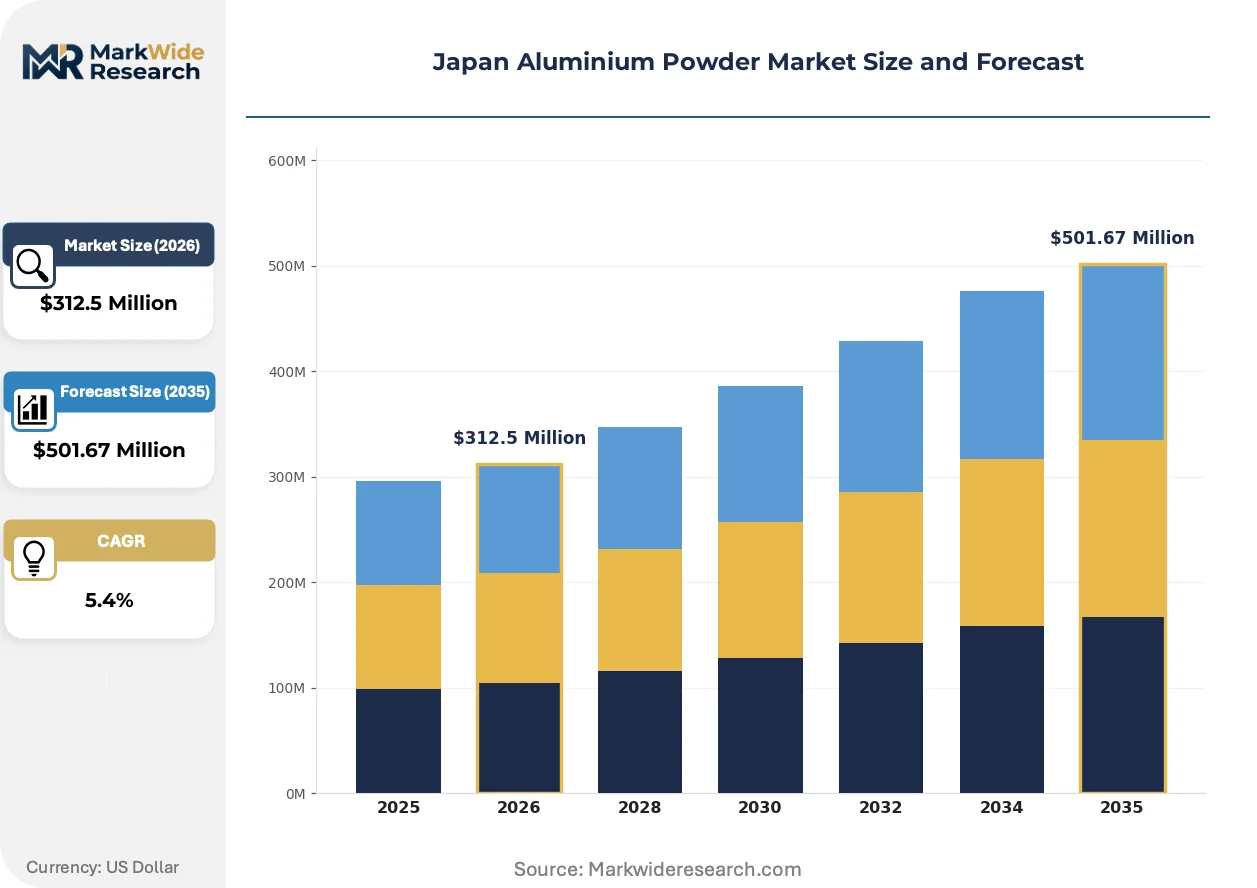
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized Aluminium, Flake Aluminium, Ground Aluminium, Spherical Aluminium Application: Automotive, Aerospace, Construction, Pharmaceuticals End User: Manufacturers, Distributors, Retailers, Contractors Form: Powder, Granules, Paste, Coating |
| Companies Covered | Toyal Group, Sumitomo Electric Industries, Ltd., Hitachi Metals, Showa Denko K.K., JFE Steel Corporation, Daido Steel Co., Ltd., Nippon Piston Ring Co., Ltd., Sandvik AB, Hoganas AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Aluminium Powder Market Strategic Shifts & Innovations
Digital process control and closed-loop atomization systems are compressing batch-to-batch variation, enabling specification-grade consistency that satisfies aerospace and medical qualification protocols without manual intervention.
Plasma rotating electrode atomization is modularizing production architecture for spherical aluminium grades. Tier-one aerospace contractors in Nagoya and Fukuoka prefectures are qualifying PREP-derived powders for turbine blade repair applications. The technology is modularizing capital deployment, allowing smaller batch runs without dedicated melt shop investment.
METI's Green Transformation bond framework is redirecting low-interest capital toward decarbonized atomization infrastructure. Industrial gas suppliers must now document renewable hydrogen feedstock ratios to access subsidized financing for new capacity. Powder metallurgy subcontractors in Aichi Prefecture are restructuring energy procurement contracts to satisfy GX bond eligibility criteria.
Consolidated procurement consortia among automotive tier suppliers are displacing fragmented spot purchasing for atomized grades. Three major component manufacturers in Toyota City have established collective buying agreements with fixed-volume, fixed-price terms spanning 36-month horizons. This concentration is most visible in precision sintered bearing applications where specification standardization permits pooled demand aggregation.
Japan Aluminium Powder Market Segmentation
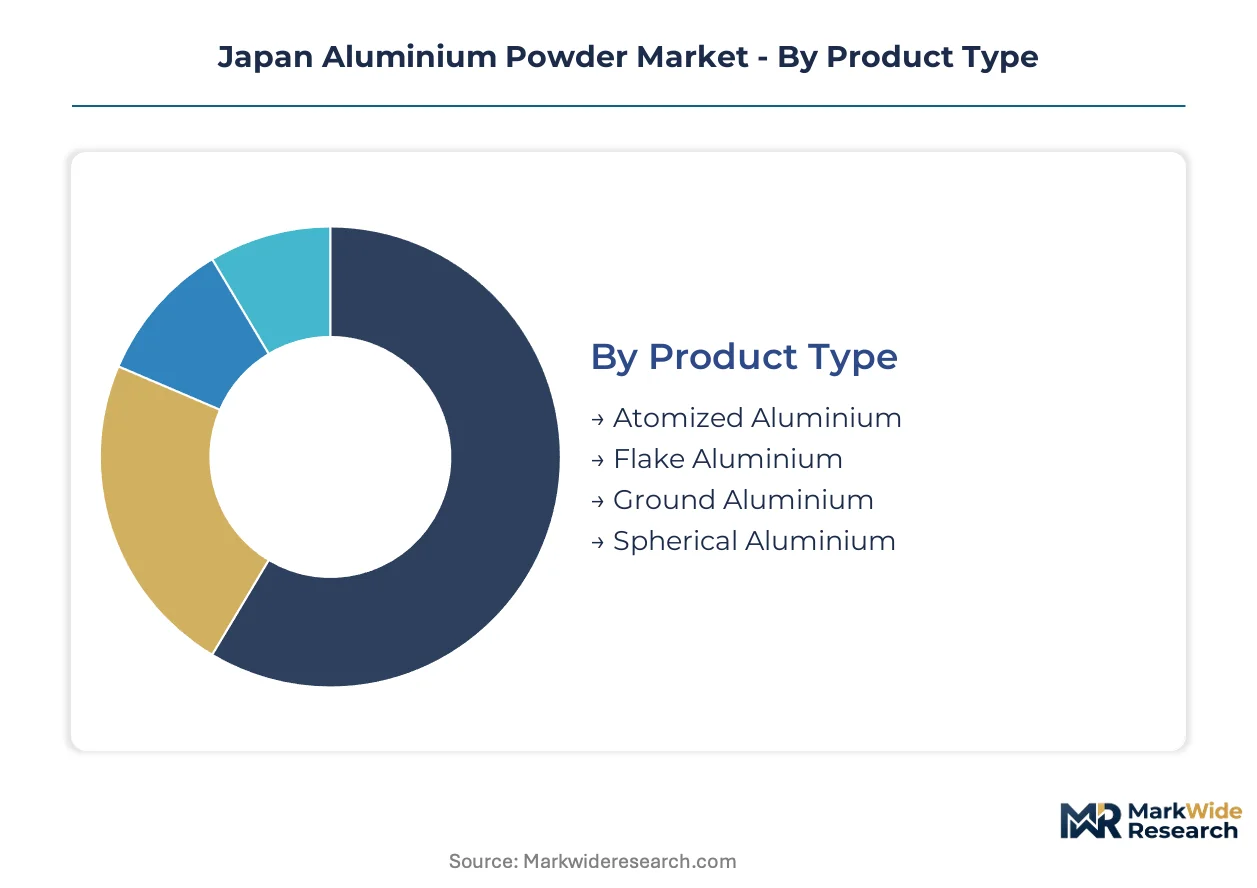
Segmentation in Japan's aluminium powder market reveals how specification intensity varies across end-use requirements. JIS certification tiers and PMDA purity thresholds create distinct commercial zones where technical qualification barriers outweigh price competition.
Product Type:
Customization intensity spans from commodity atomized grades to precision spherical powders requiring process engineering mastery.
- Atomized Aluminium:Produced through molten metal disintegration via gas or water jets, yielding irregular particles with oxide skins of 0.3-1.5% by mass. Demand concentrates in Aichi Prefecture automotive clusters where press-and-sinter operations feed Toyota and Honda supply chains, constrained by LME-linked input cost volatility.
- Spherical Aluminium:Gas atomization under inert atmosphere delivers near-perfect sphericity below 45 microns for additive manufacturing feedstock. Kanto corridor contract manufacturers absorb premium volumes as aerospace qualification programs in Nagoya and Fukuoka prefectures accelerate powder bed fusion adoption.
- Flake Aluminium:Ball-milled lamellar particles serve coating and electronics applications under tight oxide content ceilings.
- Ground Aluminium:Mechanical comminution of solid metal produces coarse fractions for pyrotechnics and chemical synthesis.
Leading the category by volume: Atomized Aluminium. Expanding most quickly: Spherical Aluminium.
Application:
Application segmentation tracks regulatory burden intensity from METI industrial standards to PMDA pharmaceutical oversight.
- Automotive:Powder metallurgy bearings, battery tray assemblies, and motor housings dominate tonnage flows. Toyota City tier suppliers are consolidating procurement through 36-month collective buying agreements, pressuring toll processors without backward integration into primary aluminium.
- Pharmaceuticals:Inhalation-grade flake demands sub-0.1% heavy metal contamination and 18-24 month PMDA qualification cycles. Osaka-Kobe corridor lacks dedicated distribution infrastructure, creating margin capture opportunities for qualified suppliers.
- Aerospace:Turbine blade repair applications in Nagoya are qualifying PREP-derived spherical powders under revised JIS H2116 standards.
- Construction:Protective coatings and concrete additives absorb lower-purity flake and ground grades.
Dominant by volume: Automotive. Steepest expansion trajectory: Pharmaceuticals.
End User:
End user structure reflects supply chain position and specification ownership authority.
- Manufacturers:OEMs and tier-one component producers hold direct JIS certification responsibility and qualification audit rights over suppliers.
- Distributors:Trading houses bridge atomization capacity in Kanto with consumption in Kansai and Chubu industrial corridors.
- Contractors:Construction and coating applicators purchase paste and coating formulations rather than raw powder.
- Retailers:Small-volume sales of pyrotechnic and hobbyist grades operate outside industrial certification frameworks.
Highest volume concentration: Manufacturers. Fastest channel growth: Distributors serving Kansai penetration gaps.
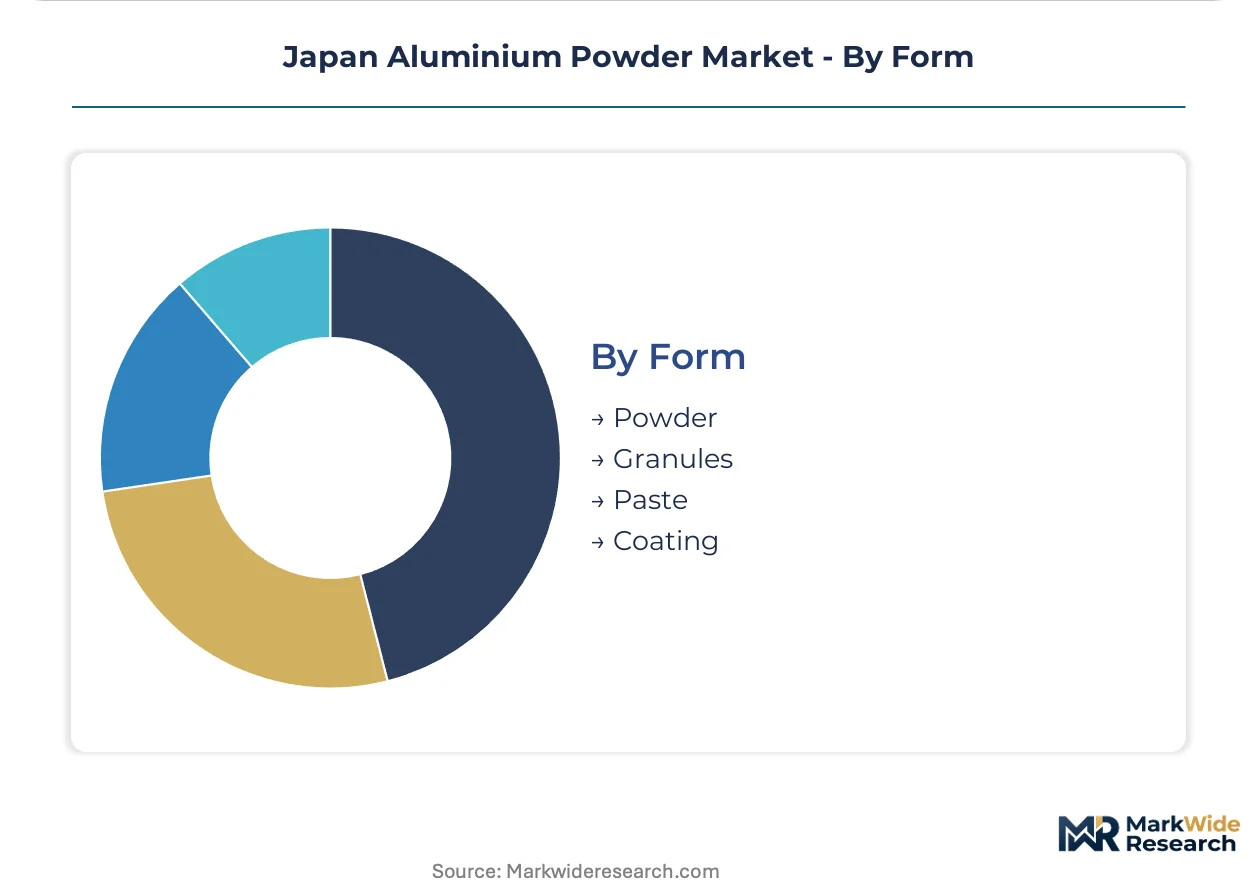
Form:
Form segmentation captures downstream processing depth and handling complexity trade-offs.
- Powder:Loose atomized and spherical grades require controlled-atmosphere storage and transport, elevating logistics costs for flake production below 0.5% oxide thresholds.
- Paste:Pre-dispersed aluminium in solvent or water carriers serves coating and printing ink manufacturers seeking handling simplification.
- Granules:Agglomerated forms reduce dust explosion hazards in chemical synthesis and pyrotechnics handling.
- Coating:Fully formulated protective and decorative finishes bypass customer-side compounding operations.
Volume leader: Powder. Gaining share fastest: Paste formulations in automotive coating applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese atomization capacity concentrates in Kanto and Chubu prefectures while consumption spreads across Kansai and Kyushu industrial corridors. This geographic mismatch creates logistics premiums for unintegrated toll processors serving western manufacturing clusters.
Kanto/Tokyo
Powder metallurgy and additive manufacturing clusters around Tokyo and Yokohama absorb premium spherical aluminium volumes. METI's Green Transformation bond eligibility requires documented renewable hydrogen ratios for subsidized financing. Contract manufacturers in Saitama and Kanagawa prefectures are consolidating PREP-derived powder qualifications for aerospace repair applications.
Kansai/Osaka
The Osaka-Kobe corridor lacks dedicated aluminium powder distribution infrastructure despite substantial automotive component demand. Pharmaceutical-grade flake specifications under PMDA guidance are tightening purity documentation requirements. Localized atomization investment here would capture margin pools currently lost to Kanto-based suppliers.
Chubu/Nagoya
Toyota City tier suppliers dominate press-and-sinter powder consumption for precision bearings and transmission components. Three major manufacturers have established 36-month collective buying agreements with fixed-volume terms. Aichi Prefecture subcontractors are restructuring energy procurement contracts to satisfy GX bond criteria for decarbonized capacity.
Kyushu
Fukuoka prefecture aerospace contractors are qualifying spherical powders for turbine blade repair under revised JIS H2116 standards. The region's industrial gas suppliers face pressure to document renewable hydrogen feedstock ratios. Nagasaki shipbuilding clusters represent latent demand for protective coating grades.
Tohoku
Sendai-based metalworking industries consume lower-purity ground aluminium for chemical synthesis applications. Regional trading houses bridge atomization capacity gaps through Kanto-sourced distribution. Oxide content thresholds below 0.5% by mass remain challenging for flake production without controlled-atmosphere handling infrastructure.
Japan Aluminium Powder Market Key Industry Players
The competitive structure tilts toward integrated industrial conglomerates with captive atomization capacity. Three tiers operate: legacy metal powder specialists with JIS certification authority, diversified steel and non-ferrous producers leveraging melt shop integration, and foreign trading houses facilitating import penetration. Dominant moves include backward integration into primary aluminium sourcing and qualification-driven partnerships with aerospace OEMs.
Within the integrated industrial tier, Toyal Group and Sumitomo Electric Industries, Ltd. occupy positions defined by process engineering depth and specification ownership. Showa Denko K.K. exemplifies the specialty chemicals pivot toward high-purity flake production. Foreign participants Sandvik AB and Hoganas AB represent the technology-licensing archetype, transferring atomization expertise through joint qualification programs rather than direct manufacturing investment.
| Leading Market Players |
|---|
| Toyal Group |
| Sumitomo Electric Industries, Ltd. |
| Hitachi Metals |
| Showa Denko K.K. |
| JFE Steel Corporation |
| Daido Steel Co., Ltd. |
| Nippon Piston Ring Co., Ltd. |
| Sandvik AB |
| Hoganas AB |
| Others |
Cost & Logistics Intelligence
Plasma rotating electrode atomization modularization is compressing capital requirements for spherical grade production while simultaneously fragmenting supply concentration away from legacy melt-integrated players. This technology shift enables toll processors to enter premium additive manufacturing feedstock channels without captive primary aluminium sourcing, reshaping pricing power distribution across atomization tiers.
Pricing Analysis
Margin tightening in spherical powder grades reflects Chinese gas-atomized import penetration from Shandong and Jiangsu provinces. Three-tier pricing structure across aerospace-qualified, industrial-grade, and commodity atomized levels tracks JIS certification intensity and oxide content thresholds. Cost-down pressure on flake production accelerates because controlled-atmosphere handling requirements elevate processing expenses. Automotive tier suppliers in Toyota City exhibit lowest price sensitivity due to 36-month collective buying agreements, while construction coating applicators face highest spot-market volatility.
Supply Chain Analysis
METI's Green Transformation bond eligibility criteria reshaping domestic-content documentation requirements for renewable hydrogen feedstock ratios in atomization operations. Primary aluminium supply concentrates in Japan, Australia, and Indonesia for regional smelting operations. Inert gas supply, atomization equipment, and JIS-certified testing services constitute critical input dependencies. Single-source vulnerability persists in gas atomization process engineering expertise concentrated at legacy suppliers. Distribution runs through trading houses bridging Kanto production capacity with Kansai and Kyushu consumption corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japanese aluminium powder market structure favors consolidation plays as LME-linked input cost volatility and extended PMDA qualification timelines force marginal toll processors toward exit. Surviving participants will capture specification-grade premium pools through JIS certification authority and captive atomization capacity.
For Market Incumbents: Hedge against Chinese spherical powder import erosion by securing backward integration into primary aluminium sourcing through offtake agreements with smelters. Accelerate PREP-derived powder qualifications with Nagoya and Fukuoka aerospace contractors before technology licensing erodes process moats. Prioritize GX bond financing eligibility through documented renewable hydrogen procurement restructuring. For New Entrants and Emerging Players: Digital distribution platforms serving Osaka-Kobe pharmaceutical-grade flake demand offer lowest barrier entry points given absence of dedicated regional infrastructure. Target PMDA inhalation powder qualification as margin capture opportunity with 18-24 month timeline acceptance. Pursue contract manufacturing partnerships with Kanto-based atomization capacity holders rather than greenfield melt shop investment. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified steel and non-ferrous producers seeking powder metallurgy vertical integration. Five-to-ten year viability window favors targets with established JIS H2116 certification authority and aerospace qualification records. Monitor Chinese import penetration rates in spherical additive manufacturing feedstock as inflection indicator for domestic margin compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminium | Captures LME-linked margin compression through smelter offtake control. |
| PREP Technology Qualification | Enables modular spherical powder entry without dedicated melt shop capital. |
| GX Bond Financing Restructuring | Unlocks METI-subsidized capital through renewable hydrogen documentation. |
| PMDA Pharmaceutical-Grade Certification | Opens inhalation flake margin pools with 18-24 month qualification cycles. |
| Kansai Distribution Infrastructure Investment | Captures Osaka-Kobe demand currently served through Kanto logistics premiums. |
Research Approach
Multi-period observation of atomization capacity utilization, JIS certification timelines, and PMDA qualification cycles anchored the trend analysis, supplemented by interviews with powder metallurgy plant managers, automotive tier supplier procurement leads, aerospace component engineers, and pharmaceutical manufacturing directors. Secondary validation drew from METI industrial statistics, JIS standard revision records, customs trade data, and SEC filings of listed industrial materials producers. Bottom-up segment sizing and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Segment-weighting across product type, application, end user, and form dimensions structured the analytical framework throughout the projection horizon. Spherical versus atomized versus flake grade splits, automotive electrification content per vehicle trajectories, and pharmaceutical inhalation powder specification tightening informed demand-side modeling. CAGRs were derived through regression analysis of historical production data against METI carbon neutrality roadmap milestones and OEM lightweighting program announcements.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time PMDA qualification cycle data and confidential aerospace contractor powder specifications introduce uncertainty bands around pharmaceutical and premium spherical segment forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Cerium Market
Metals
Aluminum Flat-Rolled Products Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Metallic Rope Cords Market
Metals
Transition Metals Market
Metals
Colloidal Metal Particles Market
Metals
Expanded Metal Foils Market
Metals
US Ferrochrome Market
Metals
Beryllium Market
Metals
Barium Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Global Bronze Market
Metals
GCC Metal Forging Market
Metals
Grain Oriented Electrical Steel Market
Metals
North America Electrical Steel Market