
 Nickel Nano Powder Market | 2026-2036
Nickel Nano Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Nano Powder Market Analysis
The capital-intensity divergence between plasma atomization specialists and conventional chemical reduction operators is unwinding competitive stability in nickel nano powder supply. Tekna leverages its proprietary RF plasma technology to sustain premium positioning in high-purity spherical powder for additive manufacturing. American Elements anchors North American supply through vertical integration into raw nickel feedstock and in-house reduction capabilities. Guangzhou Hongwu Material Technology dominates domestic Chinese distribution through direct cathode producer relationships and customized alloyed powder formulations.
Nickel nano powder comprises metallic nickel particles with diameters typically below 100 nanometers, produced through plasma atomization, chemical vapor synthesis, or hydrometallurgical reduction to achieve high surface area and enhanced catalytic reactivity for energy storage and surface engineering applications. The battery application segment leads current volume consumption as cathode manufacturers prioritize nickel-rich NMC and NCA formulations requiring precisely controlled particle morphology. High purity product types command margin concentration due to stringent trace-metal specifications from aerospace and medical device end users, while coated variants represent the fastest-growing structural category as producers seek oxidation resistance for extended shelf stability.
EPA oversight under the Toxic Substances Control Act shapes United States market access through pre-manufacture notification requirements for novel nano-scale nickel formulations, while REACH registration in the European Union mandates comprehensive dossiers on particle toxicity and environmental fate. China's SAMR enforces GB standards for nano-material classification and labeling that directly influence import clearance and domestic production licensing. Stakeholders must monitor evolving battery passport traceability requirements and carbon border adjustment mechanisms that will redefine qualified supplier status across major cathode manufacturing jurisdictions.
Market Dynamics
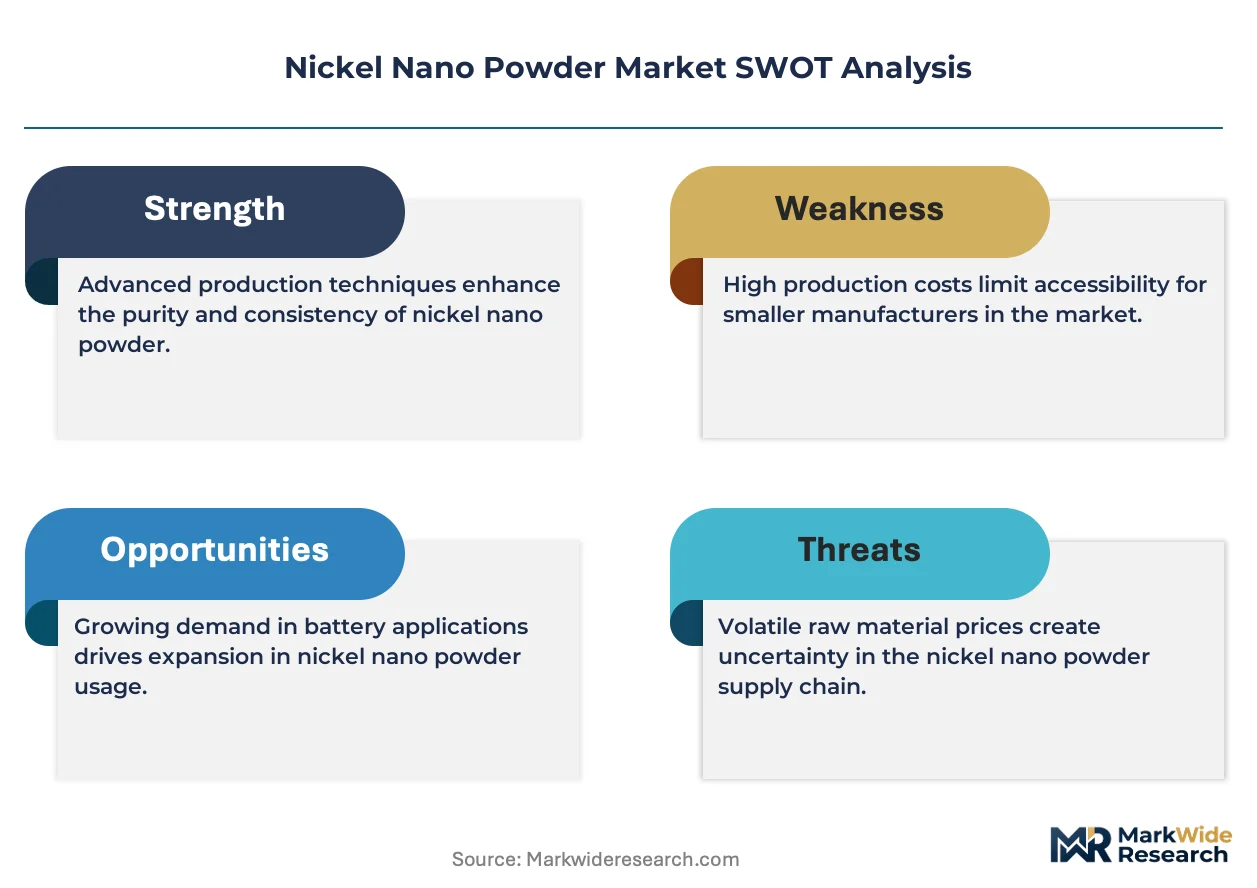
Battery-grade nickel nano powder procurement is tightening around cathode-active-material specifications, with plasma atomization capacity struggling to match the particle morphology precision demanded by nickel-rich NMC formulations.
Growth Catalysts
- IRA domestic content credits:United States battery manufacturers are qualifying cathode supply chains for tax credit eligibility, pulling North American nano powder demand forward.
- Solid-state electrolyte integration:Sulfide-based solid-state battery developers specify ultra-high-purity nickel nano powder for cathode-electrolyte interface engineering.
- China's dual carbon targets:Domestic cathode producers are securing long-term offtake agreements with regional nano powder specialists to lock in low-carbon qualified supply.
Market Restraints
- Plasma gas cost volatility:Argon and hydrogen feedstock price swings compress margins for RF plasma atomization operators dependent on high-purity spherical output.
- Chinese supply concentration:Hydrometallurgical reduction capacity clusters in Jiangsu and Zhejiang provinces, creating single-region dependency risk for global cathode supply chains.
- REACH registration burden:ECHA dossier requirements for nano-scale nickel toxicity data impose six-figure compliance costs that exclude smaller chemical reduction entrants.
Strategic Opportunities
- India PLI scheme cathode manufacturing:Reliance Industries and Ola Electric are qualifying nickel nano powder suppliers for proposed gigafactory complexes in Gujarat and Tamil Nadu.
- Surface coating service layer:Oxidation-resistant carbon and polymer coating capabilities represent unbundled value-add services separate from powder production.
- EU Battery Regulation traceability:Digital product passport mandates create first-mover advantage for producers with batch-level carbon footprint verification systems.
Industry Challenges
- Plasma physicist talent scarcity:RF torch operation and particle size distribution control require specialized expertise concentrated at Tekna and a handful of national laboratories.
- EPA PMN timeline compression:Pre-manufacture notification reviews for novel nano-scale alloys extend 12-18 months, delaying commercialization of customized cathode formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Nano Powder Market |
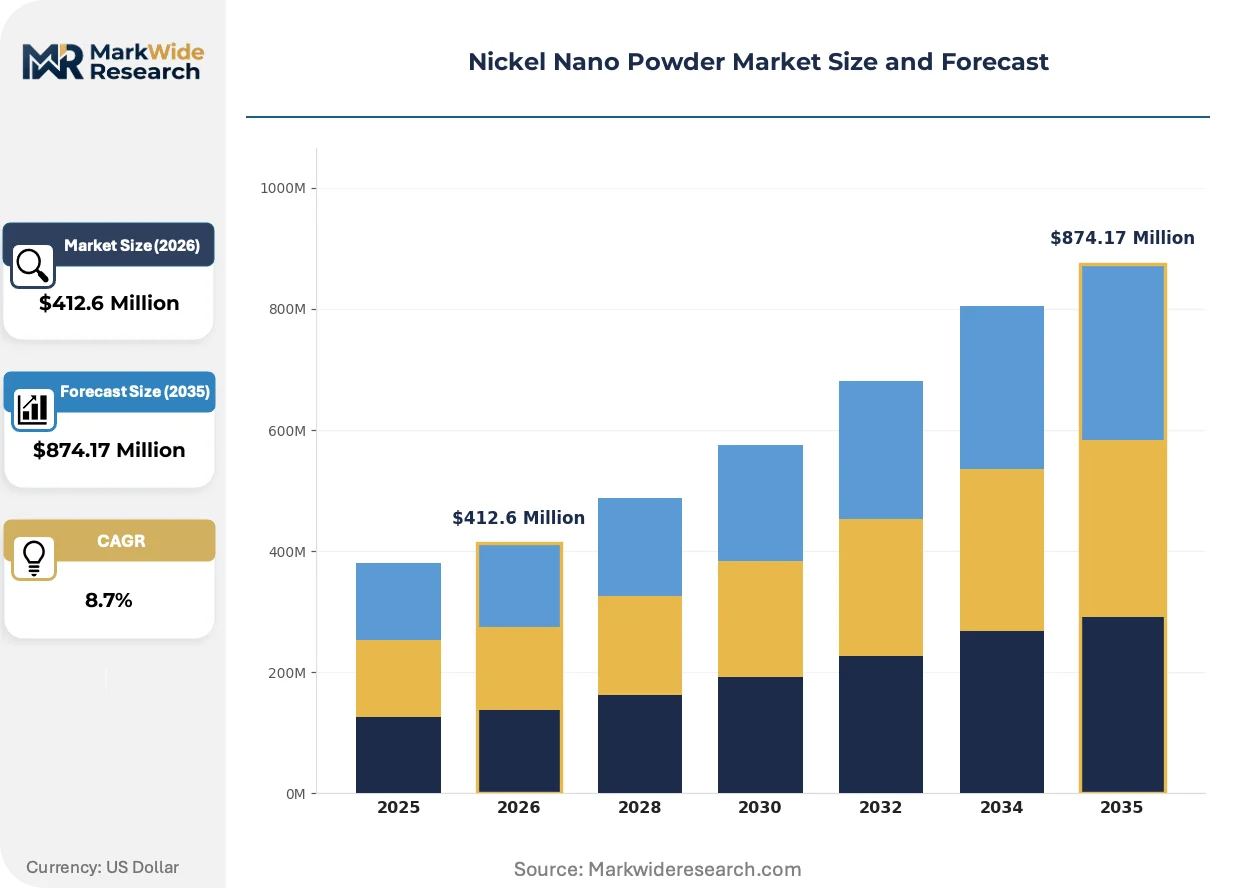
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Coated, Uncoated, Alloyed Application: Electronics, Catalysts, Coatings, Batteries End User: Aerospace, Automotive, Healthcare, Manufacturing Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Tekna, American Elements, Sky Spring Nanomaterials, Inc., Otto Chemie Pvt. Ltd., Sisco Research Laboratories Pvt. Ltd., Nanoshel LLC, ACS Material LLC, CVMR Corporation, Guangzhou Hongwu Material Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Nano Powder Market Emerging Trajectories
Particle morphology control is becoming the primary competitive battleground as cathode manufacturers reject off-spec powder batches that degrade cell cycle life.
Gas-phase plasma atomization is fragmenting the supplier base into equipment-locked specialists and toll-manufacturing intermediaries. Cathode producers with in-house plasma capacity are pulling high-value spherical powder production captive, while smaller battery startups rely on toll processors for development-scale batches. This bifurcation is compressing margins for mid-scale independent producers lacking either captive demand or equipment differentiation.
REACH Annex XVII restrictions on nickel compound classification are forcing reformulation of legacy nano powder surface treatments. ECHA's 2023 nanoform guidance requires updated safety data sheets and exposure scenario documentation for all imported powder above one ton annually. Battery material distributors in Germany and the Netherlands are absorbing compliance costs by consolidating supplier panels to three qualified producers per geography.
Long-term offtake contracting is displacing spot market purchasing for battery-grade material. Korean cathode producers are signing five-year supply agreements with fixed volume floors and price collars indexed to LME nickel. This shift is visible most acutely in binding supply negotiations for 2026-2028 delivery windows, where qualified supplier status now requires ISO 14064 carbon footprint verification alongside traditional purity certifications.
Nickel Nano Powder Market Segmentation
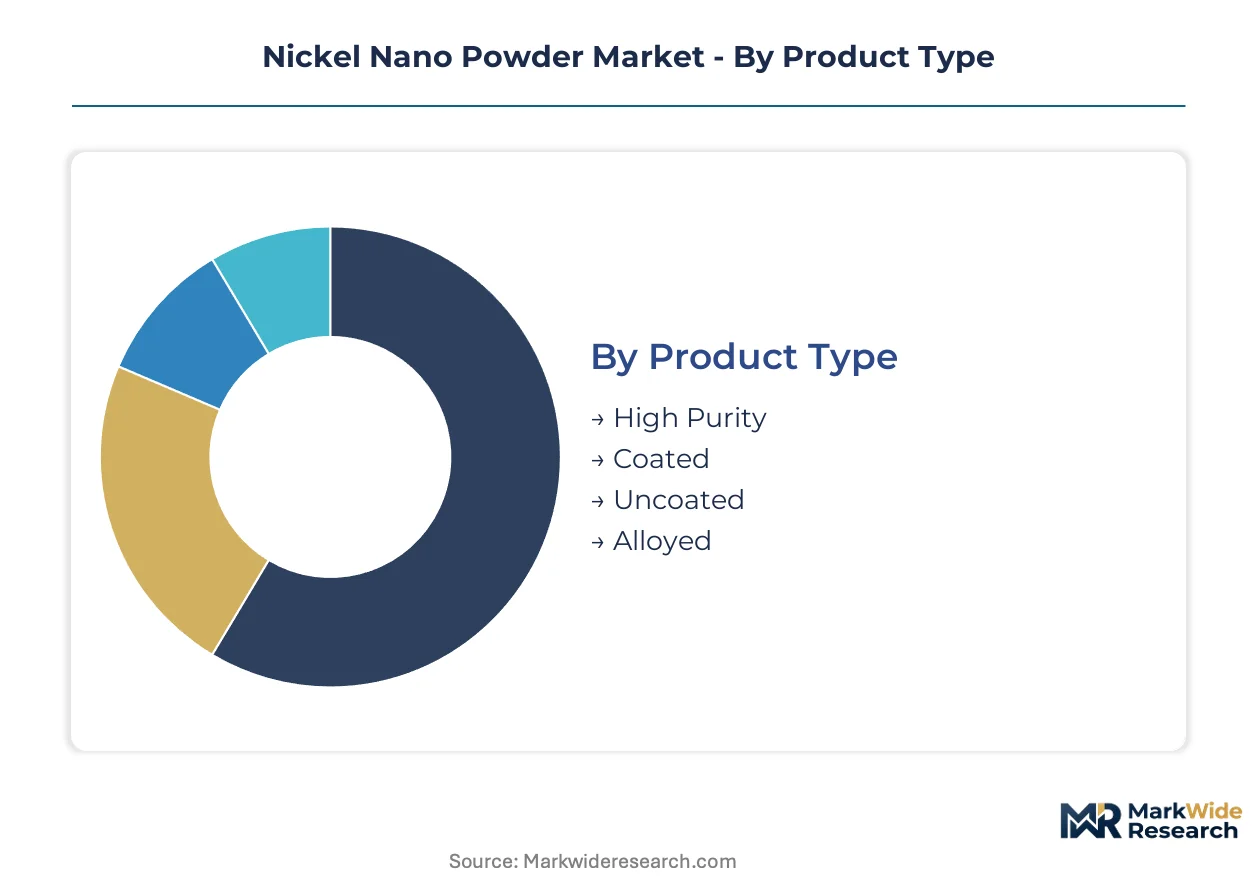
Segmentation in nickel nano powder procurement reflects divergent purity thresholds and handling protocols across battery cathode, aerospace, and medical applications. Regulatory filing requirements vary sharply by particle specification, forcing suppliers to maintain parallel production streams.
Product Type:
REACH registration in the European Union and EPA Toxic Substances Control Act oversight in the United States impose differentiated compliance burdens based on surface chemistry and trace metal content.
- High Purity:Metallic nickel content exceeds 99.9% with controlled iron, cobalt, and copper impurities below 50 ppm. Solid-state battery developers in South Korea and Japan specify this grade for cathode-electrolyte interface engineering where trace contamination degrades ionic conductivity.
- Coated:Carbon or polymer surface layers prevent oxidation during extended storage and atmospheric exposure. Battery material distributors in Germany are consolidating supplier panels to qualified producers who can demonstrate batch-level coating uniformity under ECHA nanoform guidance.
- Uncoated:Bare metallic particles produced through hydrometallurgical reduction offer lower unit costs for catalyst applications with immediate consumption cycles.
- Alloyed:Nickel-cobalt or nickel-iron compositions tailored for specific magnetic or catalytic properties in chemical process industries.
High purity handles the majority of throughput; coated is the fastest mover on share.
Application:
Volume concentration tracks cathode manufacturing expansion, with plasma atomization capacity struggling to match particle morphology precision demanded by nickel-rich NMC formulations.
- Batteries:Cathode active material production consumes spherical powder with tightly controlled particle size distribution for lithium-ion and emerging solid-state cell architectures. Chinese domestic producers are securing long-term offtake agreements with regional nano powder specialists to lock in low-carbon qualified supply under dual carbon targets.
- Catalysts:High surface area metallic nickel accelerates hydrogenation reactions in petrochemical and fine chemical synthesis. Refinery operators in India and the Middle East specify uncoated grades for immediate process integration.
- Electronics:Conductive pastes and electromagnetic shielding applications require controlled agglomeration behavior.
- Coatings:Surface engineering for wear resistance and corrosion protection in industrial machinery and tooling.
Batteries commands the dominant share of procurement volume; catalysts maintains stable demand through industrial process renewal cycles.
End User:
Customer qualification requirements separate aerospace and medical device buyers with stringent traceability protocols from automotive and general manufacturing purchasers.
- Automotive:Battery electric vehicle producers and tier-one cathode suppliers drive the largest absolute demand, with IRA domestic content credits pulling North American nano powder procurement forward. OEMs require ISO 14064 carbon footprint verification alongside traditional purity certifications.
- Aerospace:Additive manufacturing of nickel superalloy components for turbine engines demands spherical powder with extremely low oxygen and nitrogen content. Tekna's RF plasma technology sustains premium positioning in this segment.
- Healthcare:Medical device and diagnostic applications impose biocompatibility testing protocols that extend qualification timelines.
- Manufacturing:General industrial catalyst, coating, and electronics applications with standardized material specifications.
Automotive absorbs the greatest volume; aerospace extracts the highest margin per kilogram.
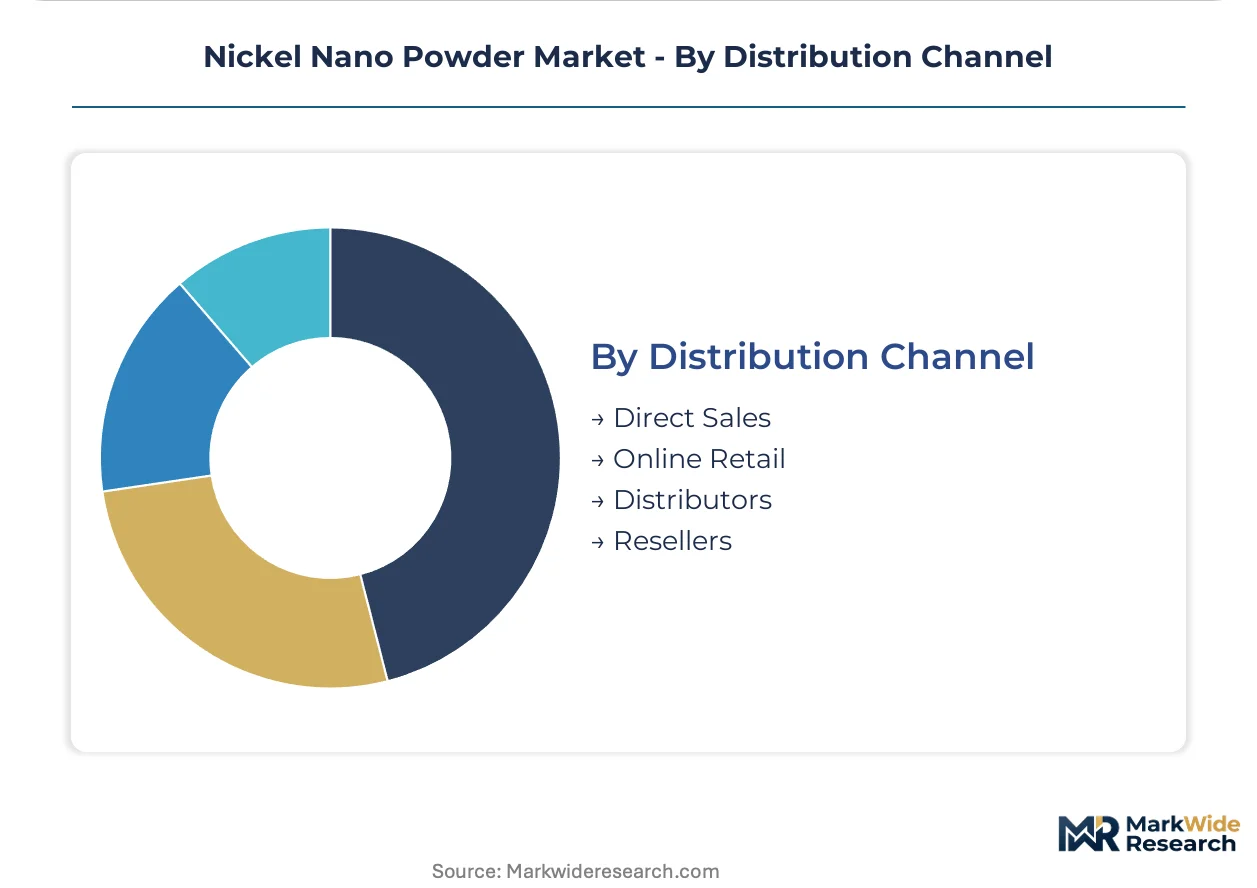
Distribution Channel:
Supply chain configuration separates qualified material flows for battery and aerospace end users from commodity-grade transactions.
- Direct Sales:Long-term offtake agreements with fixed volume floors and price collars indexed to LME nickel dominate battery-grade procurement. Korean cathode producers are signing five-year supply agreements for 2026-2028 delivery windows.
- Distributors:Battery material distributors in Germany and the Netherlands are absorbing REACH compliance costs by consolidating supplier panels to three qualified producers per geography.
- Online Retail:Research-scale quantities and development batches for university and startup laboratories.
- Resellers:Intermediary stocking for uncoated and alloyed grades in industrial catalyst markets.
Direct sales captures the majority of value; distributors is expanding most quickly as compliance complexity favors intermediaries with regulatory expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for nickel nano powder varies sharply across geographies, with Chinese cathode producers absorbing price premiums for qualified supply while Indian refiners prioritize uncoated grades on unit cost metrics.
China
Jiangsu and Zhejiang provinces host concentrated hydrometallurgical reduction capacity serving domestic NMC cathode manufacturers. SAMR enforces GB standards for nano-material classification that directly influence production licensing and import clearance. Guangzhou-based nano powder specialists are locking in five-year offtake agreements with CATL and BYD supply chains under dual carbon targets.
United States
IRA domestic content credits are pulling North American procurement forward as battery manufacturers qualify cathode supply chains for tax eligibility. EPA pre-manufacture notification requirements under TSCA extend 12-18 months for novel nano-scale alloys, delaying customized formulations. The Great Lakes industrial corridor hosts additive manufacturing demand from aerospace turbine producers seeking spherical powder with ultra-low oxygen content.
Germany
Battery material distributors in Germany and the Netherlands are consolidating supplier panels to three qualified producers per geography to absorb REACH compliance costs. ECHA's 2023 nanoform guidance mandates updated safety data sheets for all imported powder above one ton annually. The Ruhr industrial basin maintains catalyst demand from petrochemical hydrogenation processes specifying immediate-consumption uncoated grades.
South Korea
Solid-state battery developers in South Korea specify ultra-high-purity nickel nano powder for cathode-electrolyte interface engineering. Korean cathode producers are signing five-year supply agreements with fixed volume floors and price collars indexed to LME nickel. The Gyeonggi-do cluster around Seoul anchors binding negotiations for 2026-2028 delivery windows requiring ISO 14064 carbon footprint verification.
India
Reliance Industries and Ola Electric are qualifying nickel nano powder suppliers for proposed gigafactory complexes in Gujarat and Tamil Nadu under the PLI scheme. Refinery operators in India and the Middle East specify uncoated grades for immediate process integration in hydrogenation reactions. The Gujarat Special Economic Zone is emerging as a qualification hub for cathode manufacturing equipment and material suppliers.
Nickel Nano Powder Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with plasma atomization specialists commanding premium positioning against chemical reduction operators on purity metrics. The market structure separates equipment-locked producers with captive RF torch technology from toll-manufacturing intermediaries serving development-scale batches. Three archetypes dominate: vertically integrated raw material processors, plasma technology specialists, and regional distribution-integrated formulators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as producers secure long-term offtake agreements with cathode manufacturers.
Among North American suppliers, American Elements occupies a position exemplifying backward integration into raw nickel feedstock, while Tekna represents the plasma technology specialist archetype with proprietary RF capabilities. Guangzhou Hongwu Material Technology anchors the regional distribution-integrated tier through direct cathode producer relationships in China. These three entities collectively illustrate how geographic concentration, technology differentiation, and supply chain positioning define competitive boundaries in qualified battery-grade supply.
| Leading Market Players |
|---|
| Tekna |
| American Elements |
| Sky Spring Nanomaterials, Inc. |
| Otto Chemie Pvt. Ltd. |
| Sisco Research Laboratories Pvt. Ltd. |
| Nanoshel LLC |
| ACS Material LLC |
| CVMR Corporation |
| Guangzhou Hongwu Material Technology Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Cathode-grade powder substitution for legacy micron-scale nickel is redrawing procurement geography and compressing margin structures across production tiers. Chinese hydrometallurgical operators capture volume pricing through Jiangsu-Zhejiang cluster density, while plasma atomization specialists in North America and Europe defend premium positioning via purity certification moats.
Pricing Analysis
Coating and surface treatment service tiers now drive lifetime value capture beyond base powder transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon footprint verification status and batch-level traceability documentation. Cost compression in standard-grade uncoated powder intensifies because Jiangsu province hydrometallurgical capacity expansion outpaces cathode qualification timelines. Automotive OEMs exhibit highest price sensitivity through indexed long-term offtake negotiations, while aerospace additive manufacturers accept premium positioning for oxygen-controlled spherical specifications.
Supply Chain Analysis
China and South Korea anchor cathode-active-material powder fabrication, with Japan retaining specialized solid-state electrolyte interface grades. Argon and hydrogen feedstock sourcing draws from industrial gas majors with regional liquefaction infrastructure. Single-region dependency risk concentrates in Jiangsu province hydrometallurgical reduction corridors, where environmental licensing constraints could disrupt qualified supply flows. Distribution runs through direct sales channels for battery-grade volumes and consolidated distributor panels for REACH-compliant European material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat, where REACH dossier completion and EPA pre-manufacture notification timelines exclude marginal entrants from qualified supplier status.
For Market Incumbents: Secure five-year offtake agreements with Korean cathode producers before 2026-2028 delivery window negotiations conclude, locking in volume floors against emerging Indian PLI-qualified competitors. Expand in-house plasma atomization capacity in the Great Lakes corridor to capture IRA domestic content credit pull-through from US battery manufacturers. For New Entrants and Emerging Players: Oxidation-resistant carbon coating service capabilities represent an unbundled white-space opportunity where incumbent plasma specialists under-serve development-scale battery startups. Target India's Gujarat Special Economic Zone cathode qualification hub through toll-manufacturing partnerships with Reliance Industries and Ola Electric supply chains, leveraging uncoated grade cost advantages for immediate process integration catalyst markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed plasma technology specialists possessing captive RF torch intellectual property but lacking cathode producer relationships. Five-to-ten year viability hinges on carbon border adjustment mechanism compliance infrastructure buildout. Watch for ISO 14064 verification system deployment as the signal separating acquisition-ready targets from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Nickel Feedstock | American Elements' captive supply of refined nickel ore insulates margin structures from LME price volatility. |
| Long-term Supply Agreement with Cathode Producers | CATL and BYD binding offtake contracts with Guangzhou Hongwu lock in dual carbon target compliance. |
| Carbon Footprint Verification System Deployment | ISO 14064 batch-level documentation qualifies producers for EU Battery Regulation digital passport mandates. |
| RF Plasma Capacity Expansion | Tekna's proprietary torch technology sustains premium positioning in aerospace spherical powder specifications. |
| Surface Coating Service Layer Development | Carbon and polymer oxidation resistance capabilities capture unbundled value from development-scale battery startups. |
Methodological Framework
Operator-level perspectives from plasma atomization plant managers, cathode producer procurement leads, battery material distribution channel partners, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against customs trade data for nano-material import flows, SEC 10-K filings from publicly traded chemical producers, SAMR GB standard documentation, and IEA critical mineral supply chain assessments. Bottom-up cathode demand modeling and top-down nano powder production capacity surveys converged on volume estimates.
Sensitivity analysis around argon feedstock cost scenarios and REACH registration timeline delays shaped projection boundaries across the modeling period. Segmentation dimensions modeled include purity tier, surface chemistry configuration, cathode application specification, and regional regulatory cluster. CAGRs derived from weighted average of demand elasticity coefficients and supply constraint functions, with solid-state battery commercialization pace and IRA credit qualification thresholds as key forecast inputs.
Underlying assumptions cover sustained nickel-rich NMC cathode chemistry dominance, with deviation risk concentrated in sulfide-based solid-state electrolyte interface specification changes and Chinese environmental licensing enforcement intensity. Recalibration cycles align with material shifts in battery passport traceability mandates and carbon border adjustment mechanism implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Recycled Aluminum Market
Metals & Minerals
Global Magnesium Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Global Nickel Hydroxide Market
Metals & Minerals
Phosphorus Ore Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
20MnCr5 Steel Market