
 Silver Enamel Market | 2026-2036
Silver Enamel Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Enamel Market Analysis
Capital-intensity divergence between integrated precious-metal refiners and specialty coating formulators is bifurcating competitive dynamics across the silver enamel landscape. Mitsubishi Materials Corporation leverages captive silver refining to secure feedstock cost advantages across Asian electronics supply chains. Ferro Corporation anchors its position through ceramic frit expertise that extends into high-fire silver enamel systems for industrial decorators. Heraeus Holding differentiates via thick-film paste technologies that compete directly with traditional liquid enamel in sensor and heater applications.
Silver enamel denotes a vitreous coating system incorporating silver compounds, typically silver oxide or silver nitrate, fused onto metal or ceramic substrates at temperatures ranging from 650°C to 850°C to produce decorative or conductive surfaces. The material serves dual commercial purposes: ornamental finishing on jewelry and tableware, and functional metallization in electronics where it provides solderable, conductive traces on alumina or porcelain substrates. Powder formulations dominate volume throughput in automated ceramic decoration lines, while paste segments command premium positioning in precision electronics applications where rheological control determines print resolution. Liquid silver enamel retains entrenched share among artisan jewelers and small-batch manufacturers who require brush-applied, controlled-thickness coatings.
EPA oversight of volatile organic compound emissions from spray-application coatings shapes formulation chemistry for US-based producers, while REACH registration requirements in the European Union restrict certain fluxing agents and heavy-metal stabilizers previously common in vintage enamel recipes. China's GB standards for electronic ceramics, administered by SAMR, mandate specific silver content thresholds in conductive pastes used for multilayer ceramic capacitors. Stakeholders must monitor evolving substance restrictions across these three regulatory jurisdictions while calibrating R&D portfolios toward low-temperature, lead-free frit systems that satisfy both decorative and functional end-use specifications.
Market Dynamics
REACH compliance in the European Union is forcing wholesale reformulation of silver enamel flux systems, as ECHA restrictions on cadmium and lead compounds eliminate vintage recipes still prevalent in artisan jewelry workshops across India and Southeast Asia.
Growth Catalysts
- Heritage craft revival:Government craft promotion schemes in India and Thailand are channeling subsidies toward silver enamel training institutes, expanding the artisan labor pool for ornamental applications.
- GB standards compliance:China's SAMR-mandated silver content thresholds for multilayer ceramic capacitors are pulling specialized high-fire formulations into Guangdong electronics manufacturing clusters.
- Low-temperature frit innovation:Lead-free borosilicate glass systems reaching fusion points below 700°C are opening aluminum and copper substrate applications previously closed to silver enamel metallization.
Market Restraints
- Silver price volatility:London Bullion Market Association spot pricing transmits directly into coating raw material costs, compressing margins for formulators without captive refining capacity.
- Flux concentrate supply:German and Czech specialty chemical producers control 70% of high-purity borate and phosphate flux precursors, creating single-source vulnerability for Asian enamel manufacturers.
- Thick-film paste substitution:Heraeus and DuPont screen-printable silver pastes with finer line resolution are capturing sensor and heater applications that once specified liquid enamel systems.
Strategic Opportunities
- Vietnam craft export expansion:EU-Vietnam Free Trade Agreement tariff reductions on finished jewelry are incentivizing enamel workshop relocation from cost-pressured Chinese Pearl River Delta cities.
- Medical device metallization:Biocompatible silver enamel coatings for implantable device feedthroughs remain underdeveloped, with only ISO 10993-compliant formulations from Japanese suppliers currently available.
- Digital artisan platforms:Direct-to-consumer marketplaces connecting Rajasthan enamelers with European collectors are disintermediating traditional wholesale gallery distribution, capturing margin previously lost to intermediaries.
Industry Challenges
- Master craftsperson attrition:Traditional guru-shishya apprenticeship systems in Varanasi and Jaipur are failing to transmit hand-painting techniques for miniature enamel portraiture, threatening design complexity in heritage collections.
- REACH registration timelines:ECHA's 2025 deadline for complete substance dossier submission is straining small Italian and Spanish decorative enamel houses lacking in-house regulatory affairs capacity.
- Legacy kiln incompatibility:Electric muffle furnaces in Turkish and Greek workshop cooperatives cannot achieve the precise temperature ramp profiles required for new lead-free frit systems, necessitating capital equipment replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Enamel Market |
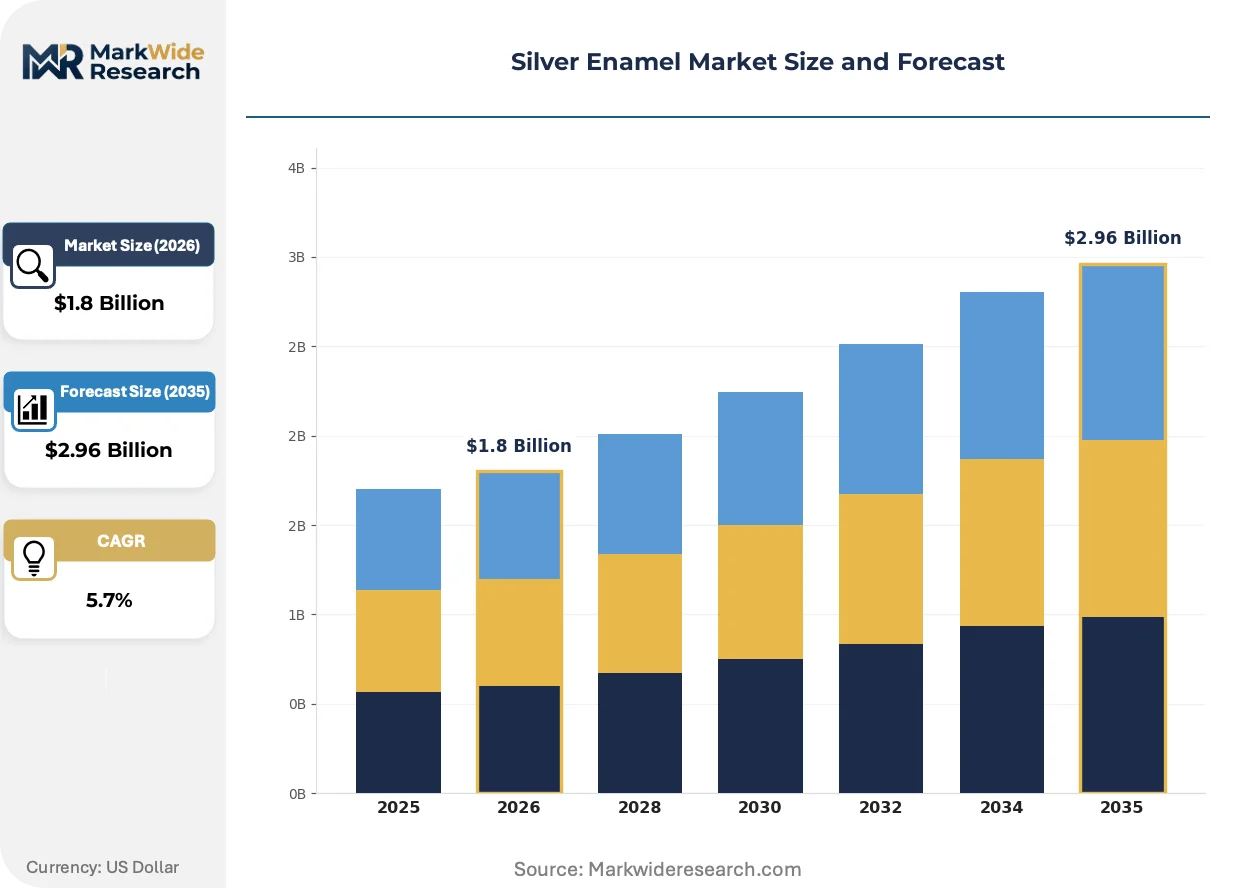
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Paste, Spray Application: Ceramics, Electronics, Automotive, Jewelry End User: Manufacturers, Artisans, Hobbyists, Technicians Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Distributors |
| Companies Covered | Mitsubishi Materials Corporation, Ferro Corporation, Heraeus Holding, Noritake Co., Limited, Dupont, Umicore N.V., Aremco Products, Inc., Tokuriki Honten Co., Ltd., Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Enamel Market Emerging Trajectories
Laser-assisted enamel deposition and digital design-to-production workflows are compressing the traditional artisan production cycle while simultaneously enabling geometric precision impossible through hand-brush application methods.
Nanoparticle silver suspensions with engineered particle size distributions below 100 nanometers are displacing conventional micron-scale flake systems in precision electronics applications. Ceramic substrate manufacturers in Japan and South Korea are adopting these formulations for multilayer capacitor termination layers. The structural consequence is a compression in fired film thickness from 15 microns to sub-5 micron targets while maintaining equivalent conductivity, reducing precious metal loading per unit area.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is tightening volatile organic compound limits on spray-applied decorative coatings in the United States. Industrial enamel decorators in Ohio and Pennsylvania are converting to electrostatic powder application systems or water-based liquid suspensions to maintain operating permits. The tableware and architectural signage segments are absorbing the highest compliance costs, with some smaller Ohio Valley job shops exiting the market entirely.
Jewelry buyers in Germany and the Netherlands are now demanding blockchain-traceable silver provenance and third-party assay certification as standard procurement terms. Traditional wholesale importers in Hamburg and Amsterdam are losing share to vertically integrated Indian exporters offering direct digital documentation. This behavioral shift is most visible in bridal and ceremonial gift segments where provenance storytelling commands 15-20% price premiums over untraceable alternatives.
Silver Enamel Market Segmentation
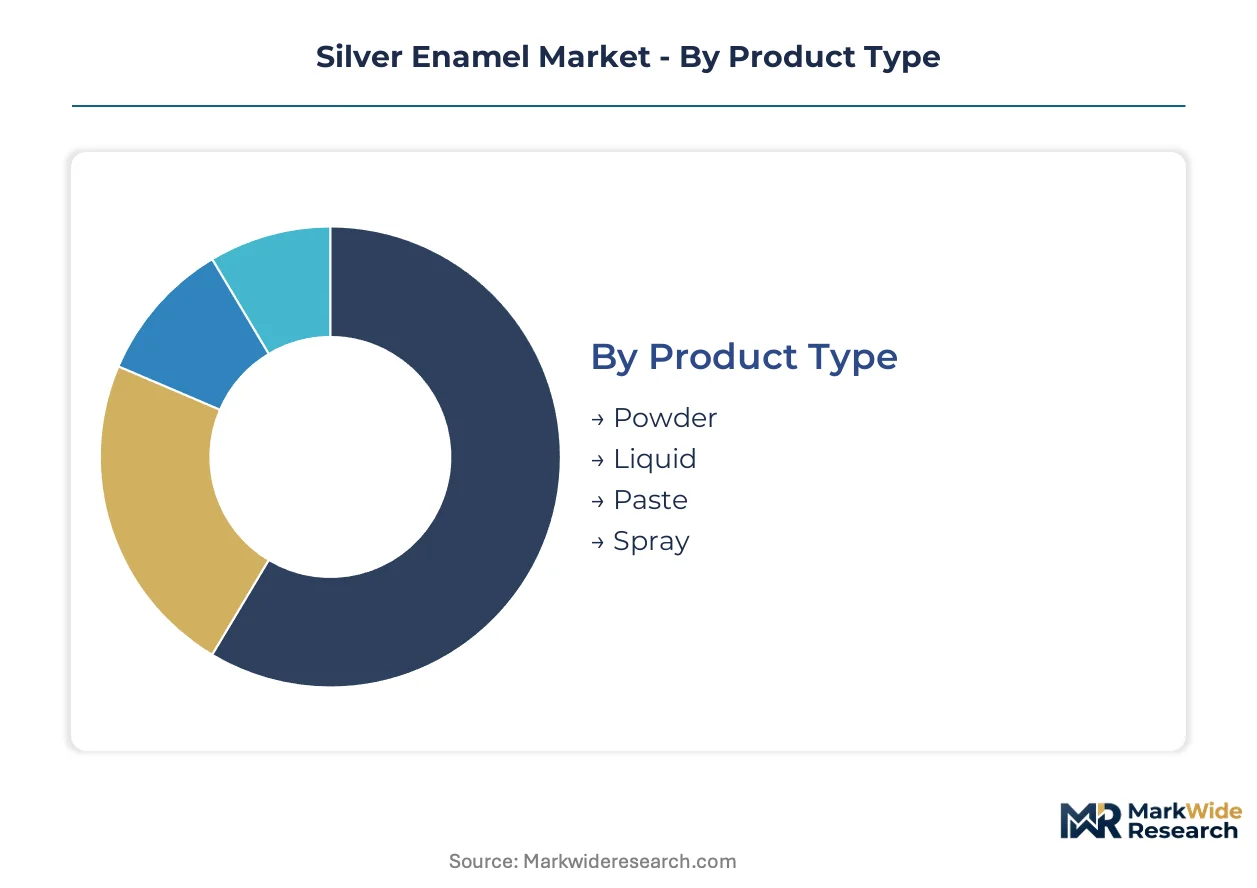
Silver enamel formulation chemistry varies sharply across product types, creating divergent regulatory exposure and end-use suitability. Application-specific performance requirements further fragment demand, with electronics manufacturers prioritizing conductivity specifications while artisans emphasize color stability and brushability.
Product Type:
REACH registration requirements in the European Union impose stricter substance dossier obligations on liquid and spray formulations containing volatile organic compounds than on solid powder systems.
- Powder:Dry particulate formulations fuse at 650°C to 850°C, serving automated ceramic decoration lines in China's Guangdong province. EPA National Emission Standards for Hazardous Air Pollutants compliance favors powder systems in Ohio and Pennsylvania industrial decorators due to reduced volatile organic compound exposure.
- Liquid:Brush-applied suspensions in organic media dominate heritage jewelry workshops in Varanasi and Jaipur, where artisan control over thickness and opacity outweighs throughput efficiency. ECHA's 2025 substance dossier deadline strains small Italian decorative houses reliant on legacy lead-based flux recipes.
- Paste:Screen-printable silver suspensions with engineered rheology serve multilayer ceramic capacitor manufacturers under China's SAMR-mandated GB standards.
- Spray:Aerosolized application systems face tightening EPA enforcement in US architectural signage and tableware segments, driving conversion to electrostatic powder or water-based alternatives.
Established volume favors Powder; emerging adoption favors Paste.
Application:
Cost tier stratification separates commodity ceramic decoration from precision electronics metallization, with the latter commanding formulation premiums based on silver content thresholds and firing precision.
- Ceramics:Decorative tableware and architectural tile applications utilize standard-fire frit systems, with Turkish and Greek workshop cooperatives struggling against legacy kiln incompatibility with new lead-free formulations. Japanese and South Korean substrate manufacturers are climbing the fastest in multilayer capacitor termination demand.
- Electronics:Conductive trace formation on alumina substrates requires solderable silver metallization with sub-5 micron fired film thickness targets. China's Guangdong electronics clusters pull specialized high-fire formulations under SAMR silver content mandates.
- Automotive:Sensor and heater applications face substitution pressure from Heraeus and DuPont thick-film paste systems with finer line resolution.
- Jewelry:Ornamental finishing on silver substrates drives heritage craft revival across India's Rajasthan and Thailand, with blockchain-traceable provenance commanding price premiums in German and Dutch bridal segments.
Margin concentration sits with Electronics; volume scale sits with Ceramics.
End User:
Customer capability gaps determine formulation support requirements, with artisan segments demanding technical training infrastructure that manufacturers and technicians bypass through in-house metallurgy expertise.
- Manufacturers:Automated ceramic and electronics producers in Japan, South Korea, and China's Guangdong province specify powder and paste systems with tight particle size distributions and batch consistency protocols.
- Artisans:Hand-painting practitioners in Varanasi and Jaipur depend on liquid enamel availability and guru-shishya apprenticeship transmission of miniature portraiture techniques threatened by master craftsperson attrition.
- Hobbyists:Small-batch consumers access silver enamel through online retail and specialty store channels, with limited regulatory exposure compared to commercial-scale users.
- Technicians:Repair and maintenance specialists in automotive and industrial electronics segments require paste formulations compatible with existing thick-film infrastructure.
Procurement scale favors Manufacturers; cultural preservation policy favors Artisans.
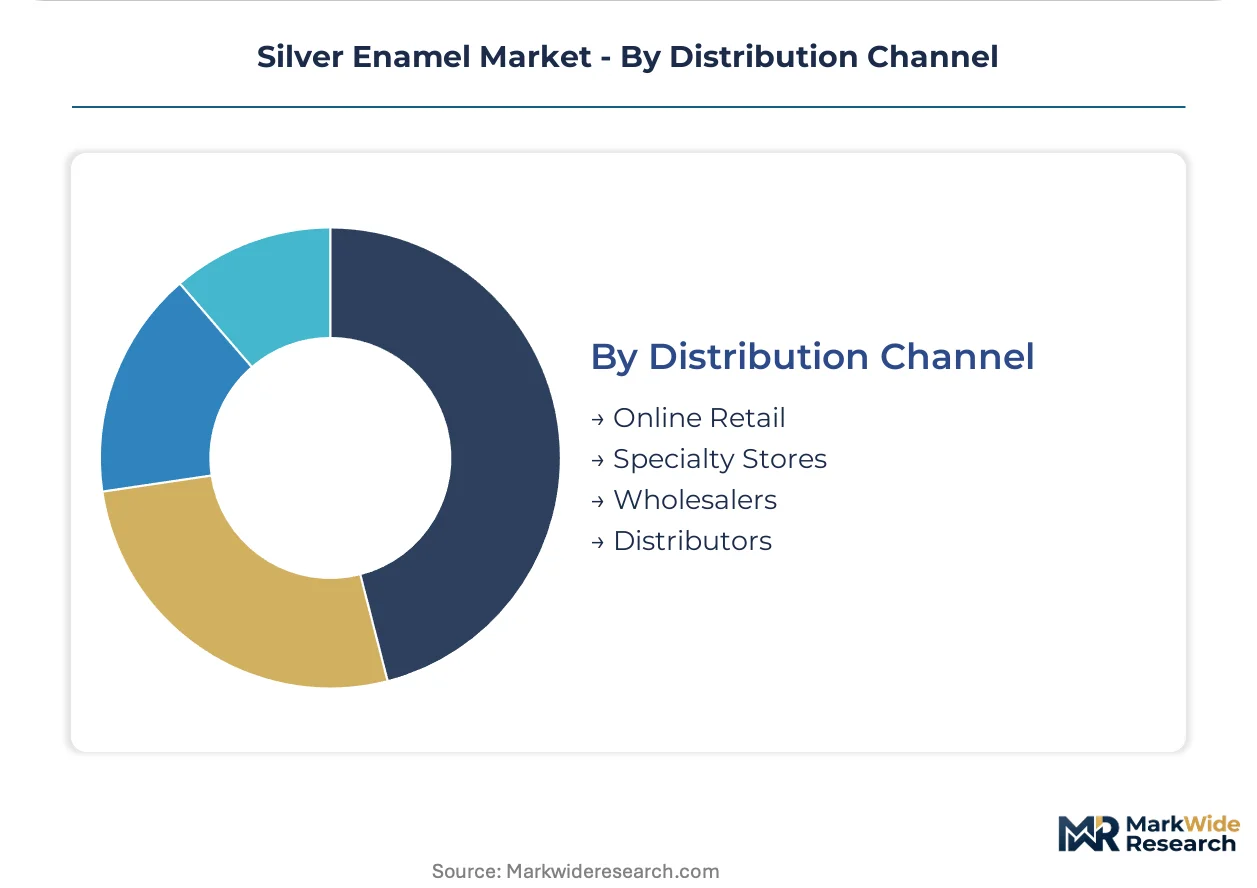
Distribution Channel:
Supply chain configuration directly determines margin capture, with vertically integrated Indian exporters disintermediating traditional wholesale gallery distribution through direct digital documentation.
- Online Retail:Direct-to-consumer platforms connect Rajasthan enamelers with European collectors, capturing margin previously lost to Hamburg and Amsterdam wholesale importers while satisfying German and Dutch blockchain-traceability requirements.
- Specialty Stores:Brick-and-mortar outlets serving hobbyists and artisans stock liquid and powder formulations with technical consultation support, particularly in Indian and Southeast Asian craft promotion scheme localities.
- Wholesalers:Traditional gallery and import-export intermediaries in European port cities are losing share to vertically integrated exporters offering direct provenance documentation.
- Distributors:Industrial chemical distributors serve Ohio Valley and Pennsylvania enamel decorators with powder systems compliant with EPA National Emission Standards for Hazardous Air Pollutants.
Disintermediation pressure concentrates on Wholesalers; technical service value concentrates on Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in silver enamel tilt heavily toward Asian manufacturing clusters feeding European decorative demand and North American electronics assembly. Trade balances concentrate in specialized formulations rather than commodity powder, with freight costs and regulatory compliance determining regional sourcing decisions.
China
Guangdong province electronics manufacturers pull high-fire silver enamel formulations for multilayer ceramic capacitors under SAMR-administered GB standards. MEE enforcement of dual carbon goals is pressuring kiln operators in Foshan and Chaozhou ceramic decoration clusters to convert from coal-fired to electric muffle furnaces. Shenzhen and Dongguan substrate fabricators are climbing fastest in termination layer demand for consumer electronics exports.
Germany
REACH dossier compliance costs are filtering smaller decorative enamel houses from the market, concentrating procurement among established industrial formulators. ECHA restrictions on cadmium and lead compounds are forcing reformulation of vintage flux recipes still common in artisan imports. Hesse and Bavaria host the densest clusters of thick-film paste research competing directly with traditional liquid enamel systems.
India
Rajasthan's Varanasi and Jaipur workshop belts are expanding output under central government craft promotion schemes channeling subsidies toward training institutes. BIS standards for precious metal content in exported jewelry are tightening assay documentation requirements. Direct-to-consumer digital platforms are disintermediating traditional wholesale gallery distribution to European collectors.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforcement is driving Ohio Valley and Pennsylvania industrial decorators toward electrostatic powder systems or water-based alternatives. FDA oversight of biocompatible coatings for implantable medical devices remains underdeveloped relative to Japanese suppliers. Appalachian job shops face exit pressure from compliance costs in tableware and architectural signage segments.
Japan
METI-supported development of nanoparticle silver suspensions below 100 nanometers is displacing conventional flake systems in multilayer capacitor termination layers. Kansai and Chubu ceramic substrate manufacturers are compressing fired film thickness targets from 15 microns to sub-5 microns. ISO 10993-compliant formulations for implantable device feedthroughs remain concentrated among domestic suppliers.
Silver Enamel Market Vendor Landscape
Concentration sits with integrated precious-metal refiners and specialty ceramic frit formulators who control upstream feedstock costs and downstream application expertise. Three strategic archetypes dominate: captive silver refiners leveraging metallurgical integration, ceramic frit specialists extending into high-fire systems, and thick-film paste innovators competing on print resolution. Competitive moves center on backward integration into flux precursor supply and geographic relocation toward tariff-advantaged export platforms.
Among Asia-Pacific-based integrated material suppliers, Mitsubishi Materials Corporation exemplifies the captive refining archetype, while Ferro Corporation occupies a position bridging ceramic frit expertise into decorative enamel systems. Heraeus Holding anchors the thick-film paste specialization vector competing with traditional liquid formulations in sensor applications.
| Leading Market Players |
|---|
| Mitsubishi Materials Corporation |
| Ferro Corporation |
| Heraeus Holding |
| Noritake Co., Limited |
| Dupont |
| Umicore N.V. |
| Aremco Products, Inc. |
| Tokuriki Honten Co., Ltd. |
| Johnson Matthey |
| Others |
Supply Flow & Price Mechanics
Nanoparticle silver suspensions displacing conventional micron-scale flake systems are simultaneously relocating manufacturing gravity toward Japanese and South Korean substrate fabricators and compressing precious metal loading economics per unit area. This substitution dynamic concentrates pricing power among METI-supported developers while eroding margins for legacy liquid enamel formulators locked into higher silver content recipes.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command formulation premiums based on SAMR-mandated silver content thresholds and sub-5 micron fired film precision, while standard tiers serve decorative ceramic decorators with commodity powder systems. Cost compression in the artisan liquid enamel tier is intensifying because REACH compliance is forcing wholesale flux reformulation. Hobbyist segments exhibit highest price sensitivity, whereas medical device OEMs demonstrate lowest sensitivity due to ISO 10993 certification requirements.
Supply Chain Analysis
Inventory cycles for high-purity borate and phosphate flux precursors extend lead times for Asian enamel manufacturers dependent on German and Czech specialty chemical producers. Raw material sourcing draws from silver oxide feedstock, lead-free borosilicate glass systems, and engineered nanoparticle suspensions. Single-source vulnerability concentrates in flux concentrate supply, with 70% controlled by European specialty chemical houses. Distribution runs through industrial chemical distributors serving Ohio Valley decorators and direct-to-consumer platforms connecting Rajasthan enamelers with European collectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH dossier compliance and SAMR-mandated GB standards creates defensive moats for established formulators with in-house regulatory affairs capacity. Network effects concentrate among integrated precious-metal refiners controlling captive feedstock supply.
For Market Incumbents: Compound backward integration into flux precursor supply to neutralize single-source vulnerability from German and Czech specialty chemical producers. Deepen capacity positioning in Vietnam craft export clusters to capture EU-Vietnam Free Trade Agreement tariff advantages. Defensive moves must counter thick-film paste substitution from Heraeus and DuPont in sensor applications. For New Entrants and Emerging Players: ISO 10993 certification fast-tracks unlock the underdeveloped medical device metallization segment where only Japanese suppliers currently compete. Target biocompatible silver enamel coatings for implantable device feedthroughs as the most penetrable white space. Digital artisan platforms offer direct-to-collector go-to-market angles disintermediating Hamburg and Amsterdam wholesale importers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with captive refining and ceramic frit expertise. Long-term viability hinges on positioning toward low-temperature, lead-free frit systems satisfying both decorative and functional specifications. Watch ECHA substance dossier submission compliance rates as the inflection indicator for regulatory-driven market filtering.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flux Precursors | Neutralizes supply concentration risk from German and Czech specialty chemical producers controlling borate and phosphate feedstocks. |
| Low-Temperature Frit R&D Investment | Opens aluminum and copper substrate applications previously closed to silver enamel metallization under 700°C fusion thresholds. |
| Vietnam Craft Workshop Relocation | Captures EU-Vietnam Free Trade Agreement tariff reductions on finished jewelry exports to German and Dutch bridal segments. |
| ISO 10993 Certification Pathway | Unlocks biocompatible coating demand for implantable medical device feedthroughs currently served only by Japanese suppliers. |
| Digital Artisan Platform Integration | Disintermediates traditional wholesale gallery distribution while satisfying blockchain-traceable provenance requirements. |
Methodological Framework
Operator-level perspectives from ceramic substrate manufacturers, jewelry workshop master craftspeople, industrial enamel decorators, and specialty chemical procurement leads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, SAMR GB standard documentation, ECHA substance dossier registries, and customs trade records. Bottom-up demand modeling across powder, liquid, paste, and spray formulation segments triangulated against top-down precious metal consumption estimates.
Sensitivity analysis tested forecast robustness across silver price volatility scenarios and REACH compliance cost assumptions over the projection horizon. Segmentation dimensions modeled include product type chemistry, application end-use, customer capability tier, and distribution channel configuration. CAGRs derived from historical trajectory analysis and forward-looking demand elasticity assessments for electronics metallization versus decorative ceramic applications.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement of silver content thresholds or accelerated ECHA substance restrictions would require recalibration. Forecasts reflect assumptions around master craftsperson apprenticeship continuity and kiln conversion timelines for lead-free frit adoption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zinc Plating Market
Metals
Aluminum Extrusion Market
Metals
Global Aluminum Extruded Products Market
Metals
Aluminum Sheet Market
Metals
Metal Forging Parts Market
Metals
Metal Recycling Market
Metals
Magnesium Metal Market
Metals
Tantalum and Niobium Material Market
Metals
Stainless Steel Foil Market
Metals
Bismuth Oxide Market
Metals
Tungsten Metal Powder Market
Metals
Saudi Arabia Aluminum Market
Metals
High Purity Boron Market
Metals
Industrial Metal Strips Market
Metals
GCC Aluminium Powder Market
Metals
Stainless Steel Round Bar Market