
 High-End Copper Foil Market | 2026-2036
High-End Copper Foil Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Copper Foil Market Outlook
Consumer electronics buyers is collapsing as electric vehicle battery manufacturers capture the dominant share of high-end copper foil procurement. Mitsui Mining & Smelting Co. Ltd. anchors Japan's electrode foil supply through integrated smelting-to-foil operations. ILJIN Materials Co. Ltd. dominates South Korea's battery-grade foil segment with ultra-thin rolling capabilities. SKC differentiates through chemical vapor deposition processes for next-generation current collectors.
High-end copper foil denotes electrolytically deposited or rolled copper sheet engineered to thickness tolerances below six microns, with tensile strength exceeding 400 MPa and surface roughness controlled for adhesive bonding in printed circuit boards and lithium-ion battery electrodes. Its primary purpose centers on minimizing electrical resistance while maximizing mechanical integrity in miniaturized electronics and high-energy-density cells. Electrode foil leads application value pools as battery manufacturers prioritize ultra-thin gauges for silicon-anode compatibility. Flexible foil occupies the fastest-expanding product tier, driven by foldable display substrates and wearable device interconnects. Aerospace-grade high-purity foil sustains premium margins through AS9100 certification barriers and limited qualified suppliers.
The EU Battery Regulation and REACH compliance frameworks in Europe mandate recycled content thresholds and restricted substance declarations for copper foil entering battery supply chains. China's SAMR enforces GB standards for foil thickness uniformity and surface oxidation limits in domestic electronics manufacturing. Japan's METI coordinates JIS standards with PMDA medical-device material requirements for implantable electronic components. Stakeholders must monitor evolving carbon-border adjustment mechanisms and qualification timelines for next-generation solid-state battery architectures.
Market Dynamics
Electrolytic copper foil below six microns is decomposing legacy rolling-mill capacity as battery cathode specifications harden around silicon-anode compatibility. This thickness compression is redrawing qualification timelines and capital allocation across the supply base.
Growth Catalysts
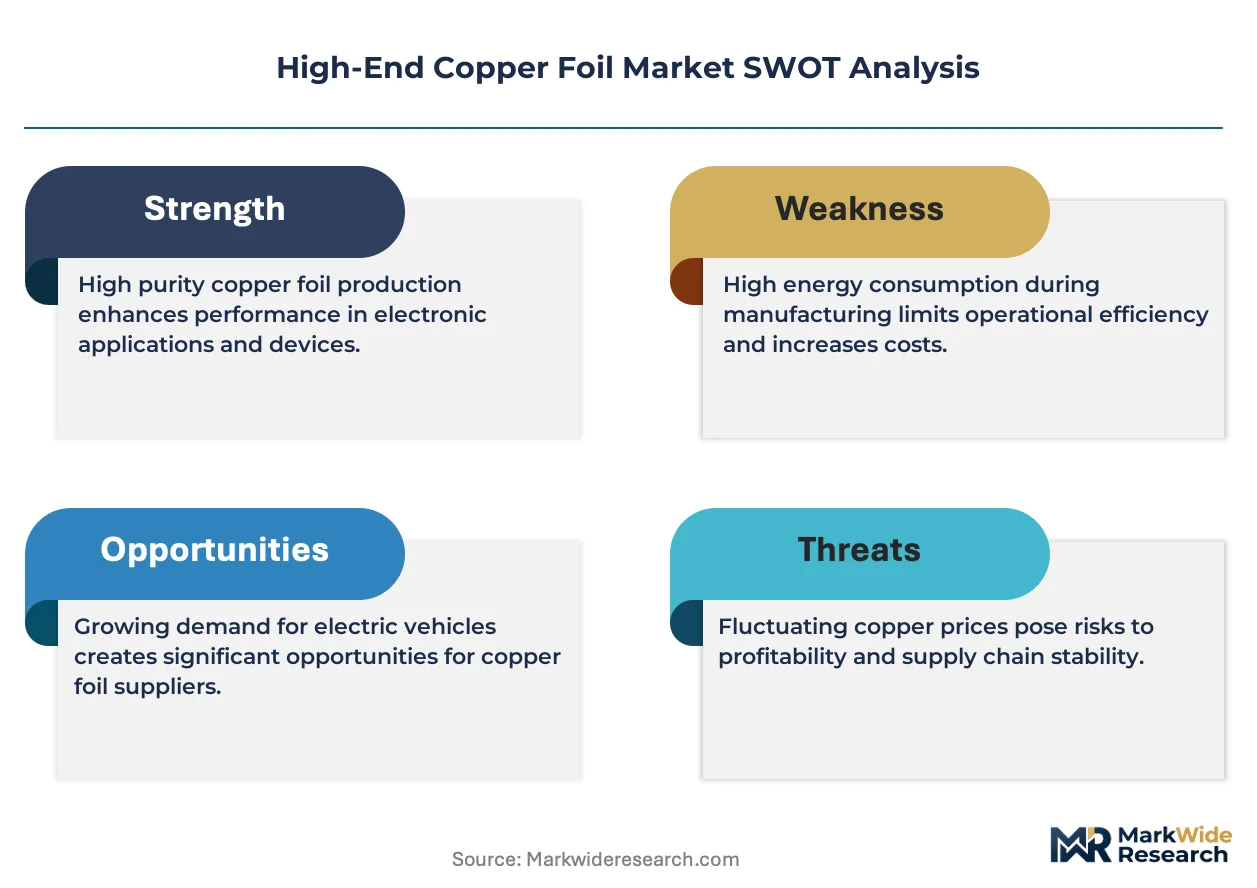
- EU Battery Regulation:Recycled content mandates and carbon-footprint disclosure rules are forcing cathode foil qualification toward European-qualified suppliers with verified Scope 3 data.
- Silicon-anode battery chemistries:Next-generation lithium-ion cells require ultra-thin current collectors with tensile strength exceeding 400 MPa, pulling foil specifications below four microns.
- South Korean cathode procurement:SK Innovation and LG Energy Solution anchor concentrated demand for battery-grade foil, creating volume commitments that stabilize rolling-mill utilization.
Market Restraints
- Copper cathode price volatility:LME copper fluctuations transmit directly to foil margins, compressing rolling-mill economics during raw material spikes.
- Chinese supply concentration:Electrolytic foil capacity clusters in Jiangsu and Guangdong provinces, creating geographic single-point vulnerability for non-Chinese battery supply chains.
- Thickness uniformity limits:Current electrodeposition processes struggle to maintain sub-six-micron tolerances across wide web widths, constraining yield rates.
Strategic Opportunities
- India battery manufacturing:PLI scheme incentives for cell production are creating virgin demand for qualified foil suppliers without incumbent relationships.
- Solid-state battery architectures:Next-generation cells require modified current collector surface chemistry, opening qualification windows for chemical vapor deposition specialists.
- Carbon-border adjustment mechanisms:EU CBAM implementation rewards low-carbon foil production with tariff preferences, advantaging hydropower-smelted copper feedstock.
Industry Challenges
- Electrochemical engineering talent scarcity:Foil manufacturers compete with battery cell producers for specialists in electrodeposition process control.
- AS9100 aerospace certification timelines:High-purity foil for satellite applications requires eighteen-to-twenty-four-month qualification cycles that lock working capital.
- Legacy ERP integration:Rolling-mill operators struggle to connect thickness-gauge digital twins with existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Copper Foil Market |
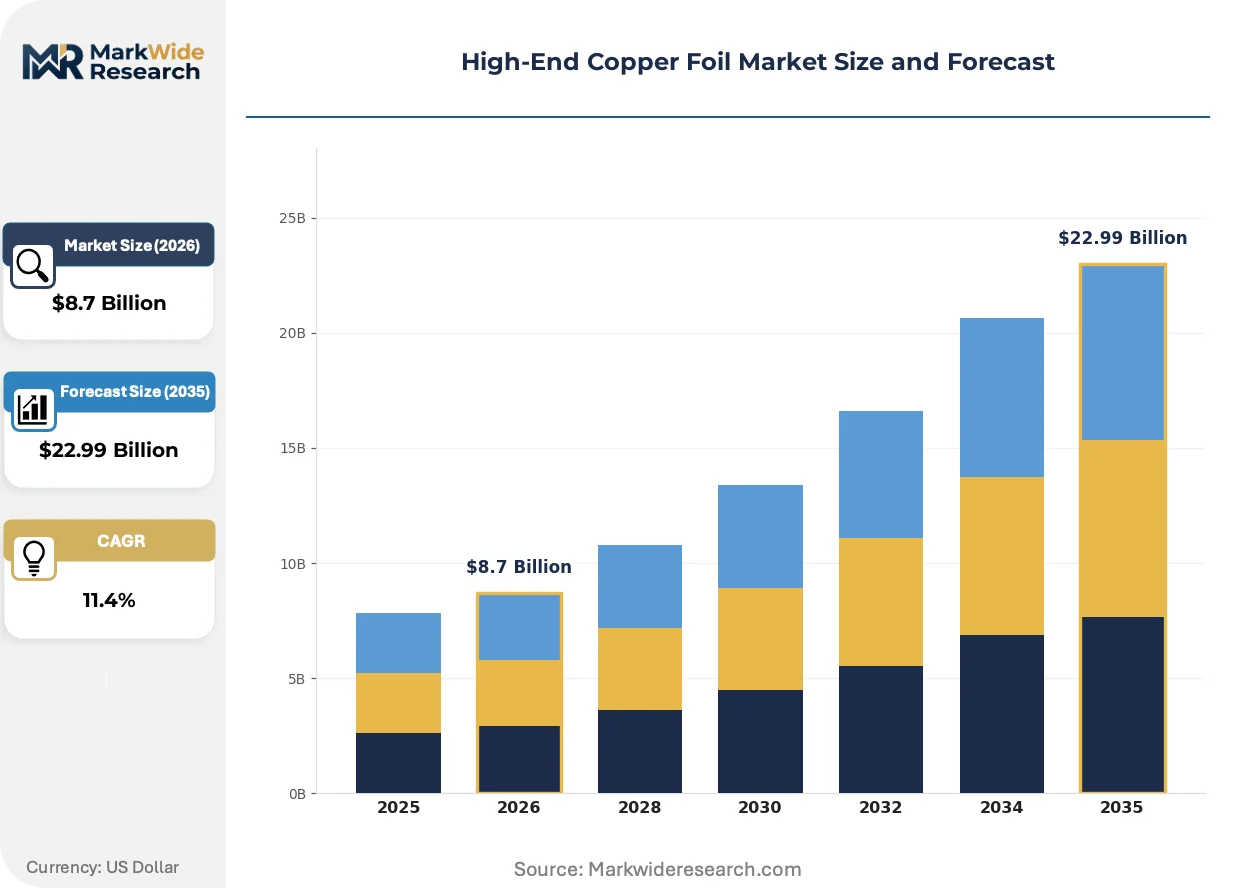
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrode Foil, Flexible Foil, Rigid Foil, High-Purity Foil Application: Electronics, Automotive Components, Renewable Energy, Aerospace End User: Telecommunications, Consumer Electronics, Industrial Manufacturing, Aerospace & Defense Thickness: Thin, Ultra-Thin, Standard, Heavy Duty |
| Companies Covered | ILJIN Materials Co. Ltd., Mitsui Mining & Smelting Co. Ltd., SKC, Doosan Corporation, Chang Chun Group, LS Mtron Ltd., JX Nippon Mining & Metals Corporation, Nuode New Materials Co. Ltd., Furukawa Electric Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Copper Foil Market Strategic Shifts
Manufacturing process control is migrating from statistical sampling to real-time digital twin monitoring. This shift is compressing defect detection latency and enabling closed-loop thickness adjustment.
Electrochemical vapor deposition for composite current collectors is decomposing traditional rolled-copper foil demand in premium battery segments. SKC and Japanese specialty chemical houses are scaling CVD capacity for silicon-anode cells requiring mechanical flexibility beyond pure copper. This deposition technology is decomposing the historical thickness-strength tradeoff that constrained rolling-mill product roadmaps.
China's SAMR enforcement of GB standards for surface oxidation limits is tightening import acceptance criteria for non-domestic foil. Battery manufacturers in Ningbo and Shenzhen are rejecting shipments exceeding revised oxide-threshold specifications. Japanese and South Korean suppliers are responding with in-line plasma surface treatment investments to maintain market access.
Direct cathode-foil procurement from rolling mills is displacing distributor intermediaries in South Korean and Japanese battery supply chains. LG Energy Solution and SK Innovation now contract directly for twelve-to-eighteen-month volume commitments with price collars. This disintermediation concentrates supplier relationship management within cell engineering teams rather than commodity procurement functions.
High-End Copper Foil Market Segmentation
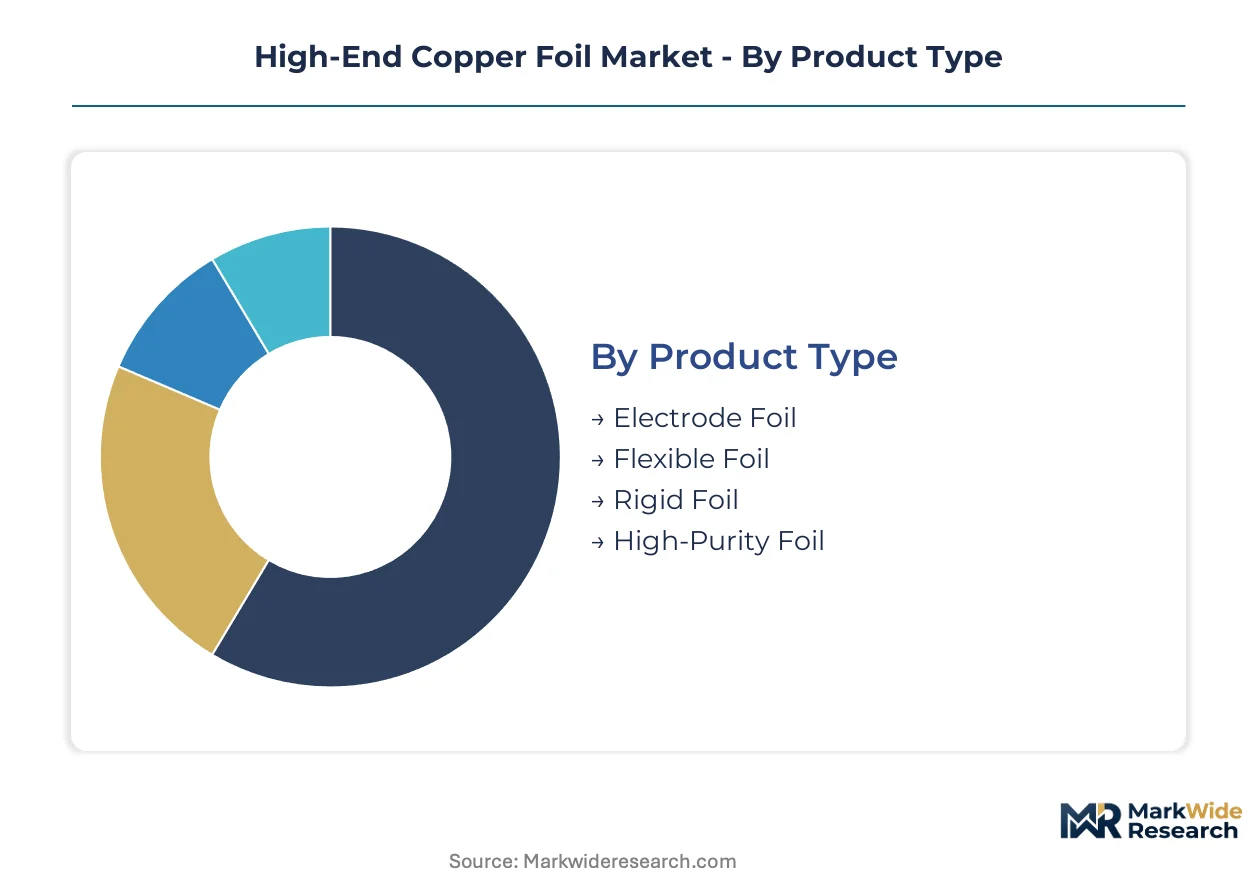
High-end copper foil procurement patterns diverge sharply across thickness tolerances, purity grades, and end-use certification requirements. Battery cathode specifications and aerospace qualification barriers create distinct commercial segments with incompatible supplier bases and pricing architectures.
Product Type:
Regulatory differentiation separates electrode foil for EU Battery Regulation compliance from aerospace-grade material governed by AS9100 certification. China's SAMR enforces GB standards on surface oxidation limits that filter import eligibility across all product tiers.
- Electrode Foil:Electrolytically deposited copper sheet engineered below six microns with tensile strength exceeding 400 MPa for lithium-ion cathode current collectors. Demand concentrates in South Korea where SK Innovation and LG Energy Solution anchor direct procurement contracts with twelve-to-eighteen-month volume commitments.
- Flexible Foil:Rolled copper with controlled grain structure enabling repeated bending without fracture, specified for foldable display substrates and wearable interconnects. Adoption is climbing fastest in Japanese consumer electronics supply chains where METI-coordinated JIS standards govern material traceability.
- Rigid Foil:Higher-gauge electrolytic or rolled material for traditional printed circuit board laminates with less stringent thickness uniformity.
- High-Purity Foil:Ultra-refined copper exceeding 99.99% purity for satellite and implantable medical applications under PMDA and FAA oversight.
Established volume favors electrode foil; emerging adoption favors flexible foil.
Application:
Cost tier separation distinguishes premium aerospace material from standard electronics-grade foil, with automotive battery applications commanding intermediate pricing with the strictest lot-traceability requirements.
- Electronics:Printed circuit board and semiconductor packaging material governed by IPC standards and REACH substance restrictions. Procurement is concentrating in Shenzhen and Ningbo manufacturing clusters where SAMR oxide-threshold enforcement rejects non-compliant imports.
- Automotive Components:Battery-grade foil for electric vehicle cathodes requiring silicon-anode compatibility below four microns. Demand is accelerating fastest in European cell plants subject to EU Battery Regulation recycled content mandates and carbon-footprint disclosure rules.
- Renewable Energy:Collector material for grid-scale battery storage with relaxed thickness tolerances but extended durability specifications.
- Aerospace:AS9100-certified high-purity foil for satellite bus bars and avionics with eighteen-to-twenty-four-month qualification cycles.
Electronics commands the largest procurement volumes; automotive applications are expanding most quickly.
End User:
Customer type determines certification burden and contract structure, with defense procurement requiring ITAR compliance and medical applications triggering PMDA material master files.
- Telecommunications:Base station and fiber-optic infrastructure material with intermediate purity requirements and multi-year supply agreements.
- Consumer Electronics:Smartphone and laptop battery foil subject to rapid specification churn and concentrated buyer power among device OEMs.
- Industrial Manufacturing:Motor winding and transformer material with standardized JIS or IEC specifications and price-sensitive tender procurement.
- Aerospace & Defense:Satellite and military avionics material requiring dual-use export control compliance and qualified supplier lists.
Consumer electronics maintains the broadest supplier base; aerospace and defense sustains the highest margin premiums.
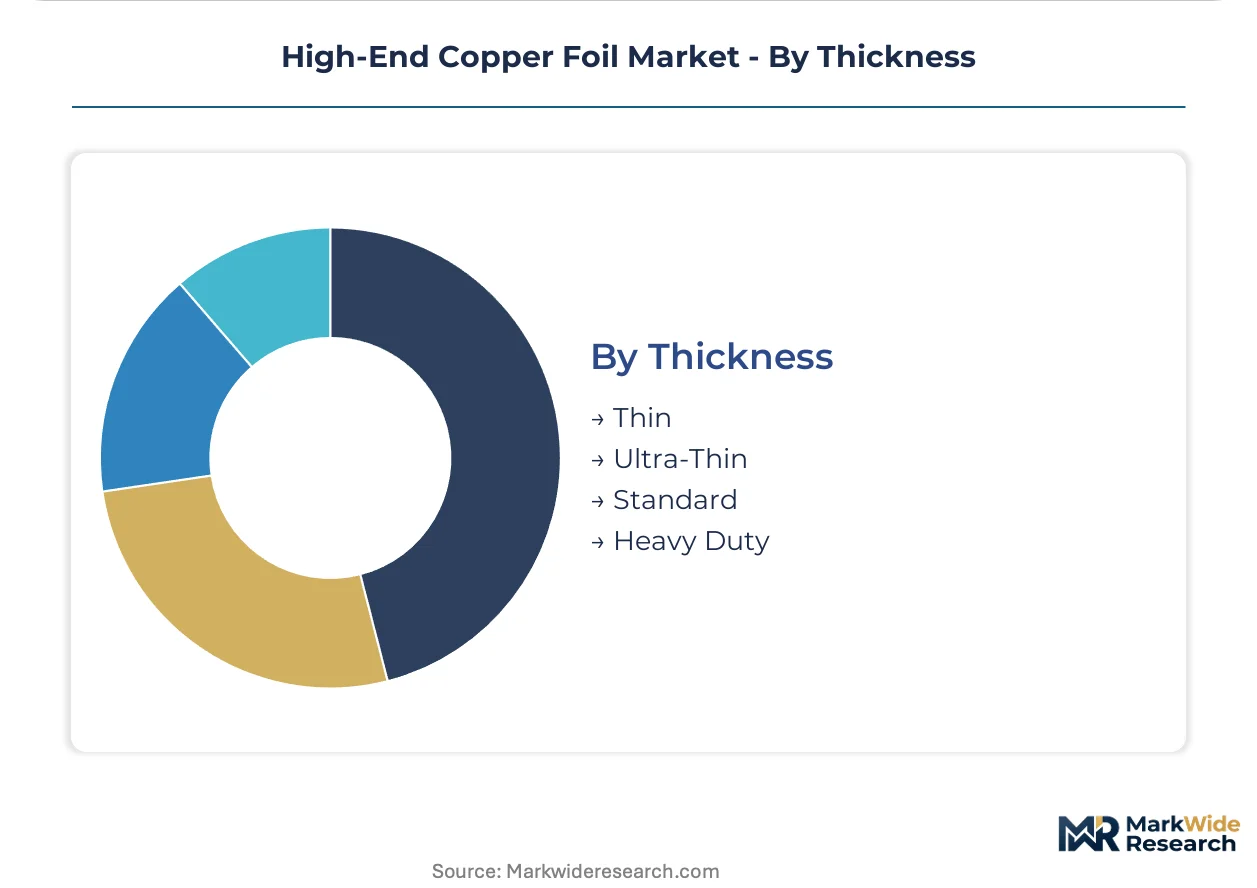
Thickness:
Supply concentration clusters at the ultra-thin frontier where electrodeposition yield rates constrain viable production to specialized rolling mills and chemical vapor deposition specialists.
- Ultra-Thin:Below four microns for silicon-anode battery compatibility, produced through advanced electrodeposition or SKC-style CVD processes. Manufacturing is concentrating in South Korea and Japan where process control talent scarcity limits new entrant qualification.
- Thin:Four-to-six micron range for standard lithium-ion cathodes with established electrolytic foil capacity in Jiangsu and Guangdong provinces.
- Standard:Six-to-twelve microns for consumer electronics and industrial applications with commoditized pricing and distributor-mediated procurement.
- Heavy Duty:Above twelve microns for power electronics and traditional PCB laminates with minimal technical differentiation.
Standard thickness dominates current rolling-mill utilization; ultra-thin specifications are gaining share fastest in qualified battery supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolytic foil capacity clusters in China's Jiangsu and Guangdong provinces, creating geographic concentration that battery manufacturers in South Korea and Japan must navigate through dual-sourcing strategies. European cell plants face qualification bottlenecks as EU Battery Regulation carbon-footprint rules favor suppliers with verified Scope 3 data. North American demand remains import-dependent with limited domestic electrodeposition capacity.
China
Jiangsu and Guangdong provinces host the dominant share of electrolytic foil manufacturing, with Ningbo and Shenzhen battery manufacturers enforcing SAMR's revised surface oxidation limits through import rejection protocols. The country's dual carbon goals are tightening carbon-footprint disclosure requirements for copper feedstock entering battery supply chains. Domestic rolling mills are expanding sub-six-micron capacity to capture silicon-anode qualification windows.
South Korea
SK Innovation and LG Energy Solution anchor concentrated cathode foil procurement through direct twelve-to-eighteen-month volume commitments with price collars. The Busan-Ulsan industrial corridor houses specialized rolling mills with ultra-thin gauge capabilities for silicon-anode compatibility. MFDS-coordinated standards for implantable medical devices create adjacent demand for high-purity foil segments.
Japan
METI coordinates JIS standards with PMDA medical-device material requirements, creating certification barriers for imported foil in implantable electronics applications. The Kanto and Kansai regions maintain integrated smelting-to-foil operations that supply both domestic battery manufacturers and aerospace qualified supplier lists. Process control talent scarcity limits new entrant qualification in electrodeposition technology.
Germany
European cell plants subject to EU Battery Regulation recycled content mandates are driving cathode foil qualification toward suppliers with verified carbon-footprint data. The country's automotive OEMs are consolidating procurement relationships through direct mill contracts rather than distributor intermediaries. REACH compliance frameworks restrict substance declarations for copper foil entering battery supply chains.
United States
Limited domestic electrodeposition capacity forces battery manufacturers to rely on South Korean and Japanese imports for sub-six-micron specifications. The Southeast and Midwest manufacturing corridors are attracting rolling mill investments through IRA-linked clean energy manufacturing incentives. FAA oversight of satellite applications sustains demand for AS9100-certified high-purity foil with extended qualification cycles.
High-End Copper Foil Market Competitive Environment
Concentration sits with integrated mining-to-foil conglomerates and specialized electrodeposition houses that control sub-six-micron yield rates. The supply base separates into three archetypes: smelter-integrated producers with captive copper feedstock, independent rolling mills with chemical vapor deposition capabilities, and regional electrolytic specialists serving single-country demand pools. Competitive moves center on backward integration into copper cathode supply and qualification partnerships with silicon-anode battery developers.
Among South Korea-based fabricators, ILJIN Materials Co. Ltd. and SKC occupy positions within the ultra-thin foil specialization tier, while Japan's Mitsui Mining & Smelting Co. Ltd. exemplifies the smelter-integrated archetype with upstream control over copper feedstock purity. These three companies represent the geographic and technological poles that structure procurement relationships in qualified battery supply chains.
| Leading Market Players |
|---|
| ILJIN Materials Co. Ltd. |
| Mitsui Mining & Smelting Co. Ltd. |
| SKC |
| Doosan Corporation |
| Chang Chun Group |
| LS Mtron Ltd. |
| JX Nippon Mining & Metals Corporation |
| Nuode New Materials Co. Ltd. |
| Furukawa Electric Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Electrolytic foil capacity utilization above eighty percent in Jiangsu and Guangdong provinces anchors price floors for sub-six-micron specifications. South Korean battery manufacturers leverage twelve-to-eighteen-month volume commitments to compress supplier margins while locking rolling-mill output.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified aerospace material from battery-grade electrode foil and commodity PCB laminates. Price differentiation hinges on certification grade and volume scale, with silicon-anode compatibility below four microns commanding premium positioning. Cost compression in standard-gauge electronics foil is intensifying because Chinese rolling mills are expanding six-to-twelve-micron capacity. Industrial manufacturing buyers exhibit highest price sensitivity, while aerospace and defense procurement sustains lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Container availability constraints on the Shanghai-Busan trade lane elevate inbound logistics costs for Japanese and South Korean battery manufacturers sourcing from Chinese electrodeposition houses. Supply concentrates in China, South Korea, and Japan, with raw material dependencies on LME copper cathodes, sulfuric acid for electrolytic baths, and titanium anode substrates. Single-source vulnerability sits with Jiangsu province electrolytic foil clusters subject to SAMR enforcement actions. Distribution runs through direct mill contracts displacing distributor intermediaries in qualified battery supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with solid-state battery architectures creating qualification windows for chemical vapor deposition specialists outside incumbent electrolytic foil supply bases.
For Market Incumbents: Consolidate backward integration into copper cathode supply to offset LME price volatility transmitting directly to rolling-mill margins. Expand sub-four-micron electrodeposition capacity in Busan-Ulsan corridor to capture silicon-anode qualification timelines before CVD specialists scale. Lock process control talent through apprenticeship pipelines competing with battery cell producers. For New Entrants and Emerging Players: AS9100 certification fast-track for high-purity foil segments opens white-space targets in satellite bus bar applications with eighteen-to-twenty-four-month qualification cycles that deter rapid incumbent response. India's PLI scheme for cell production creates virgin demand without incumbent relationship barriers. Lead with plasma surface treatment capabilities to satisfy SAMR oxide-threshold enforcement for Chinese market access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors chemical vapor deposition specialists with silicon-anode partnerships over legacy rolling-mill operators facing thickness-strength tradeoff constraints. Long-term viability across the next decade rests on qualification velocity for solid-state architectures rather than scale economies in commodity gauges. Watch for EU CBAM implementation accelerating low-carbon foil procurement shifts as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Cathode Supply | Mitsui Mining & Smelting's captive smelting-to-foil operations insulate margins from LME volatility. |
| Silicon-Anode Qualification Partnership | SKC's CVD process development with South Korean cell manufacturers opens next-generation current collector specifications. |
| Plasma Surface Treatment Investment | Japanese suppliers deploy in-line oxidation control to maintain Ningbo and Shenzhen market access under SAMR enforcement. |
| Direct Mill Contract Consolidation | LG Energy Solution's twelve-to-eighteen-month volume commitments with price collars stabilize Busan-Ulsan rolling-mill utilization. |
| Low-Carbon Feedstock Certification | Hydropower-smelted copper sourcing positions European-qualified suppliers for EU CBAM tariff preferences. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade records, and copper industry association disclosures. Primary interviews engaged rolling-mill operations directors, cathode procurement managers at battery cell producers, and electrochemical engineering specialists. Secondary validation drew from LME warehouse data, SAMR regulatory bulletins, and EU Battery Regulation implementation guidance. Bottom-up capacity assessments triangulated against top-down demand modeling from electric vehicle production forecasts.
Segmentation dimensions modeled include thickness tier, purity grade, end-use certification requirement, and regional production hub across the analysis window. CAGRs derived from rolling-mill capacity expansion pipelines weighted against silicon-anode battery chemistry adoption curves. Forecast inputs incorporated electrodeposition yield rate improvements and carbon-border adjustment mechanism implementation timelines.
Underlying assumptions cover sustained electric vehicle production scaling, stable LME copper price corridors, and gradual solid-state battery commercialization, with deviation risk concentrated in Chinese supply chain disruption and process control talent scarcity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Lightweight Aluminium Pistons Market
Metals
United States Metal Casting Market
Metals
Expanded Metal Foils Market
Metals
Palladium Market
Metals
Scandium Market
Metals
Global Flat Steel Market
Metals
Global Aluminum Extruded Products Market
Metals
Monel Alloy Market
Metals
Metal Powder Market
Metals
Stainless Steel Market
Metals
Global Hot Rolled Coil Steel Market
Metals
Lithium Tungstate Market
Metals
Vietnam Aluminum Market
Metals
High Carbon Bearing Steel Market
Metals
Smelting Chemicals Market
Metals
Silver-Platinum Paste Market