
 Global Aluminium Wire Rod Market | 2026-2036
Global Aluminium Wire Rod Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminium Wire Rod Market Analysis
Multi-source procurement for primary aluminium feedstock is pivoting toward captive smelter partnerships as volatility in LME pricing strains converter margins. UC Rusal leverages Siberian hydro-powered capacity to supply low-carbon wire rod billet to European cable makers. Hindalco Industries Limited anchors South Asian demand through integrated mining-to-rod operations spanning Odisha and Uttar Pradesh. Rio Tinto competes on certified low-emission aluminium grades that command premium placement in Nordic and German transmission projects.
Aluminium wire rod is a continuously cast or rolled semi-finished product with diameters typically spanning 9.5 mm to 32 mm and purity grades from EC grade to alloyed variants containing magnesium or silicon for tensile adjustment; it serves as the feedstock for drawing into electrical conductors, mechanical cable, and fasteners. Bare wire rod dominates volume in overhead transmission line applications where conductivity-to-weight ratios outweigh corrosion concerns, while coated variants capture margin pools from marine and industrial environments requiring anodized or polymer barrier protection. The 5 mm to 10 mm diameter band leads construction and component demand, whereas sub-1 mm fine rod is the fastest-growing slice for automotive OEM harness miniaturization.
The EU Green Deal and REACH compliance frameworks are reshaping import eligibility by requiring carbon footprint disclosure for aluminium entering European cable supply chains. China's MEE enforces dual carbon targets that restrict coal-powered smelter output, tightening wire rod billet availability for non-integrated converters. India's BIS certification mandates for electrical conductors are raising quality barriers for imported rod in state tender programs. Stakeholders must monitor how carbon border adjustments and national content rules fragment procurement strategies across major demand centers.
Market Dynamics
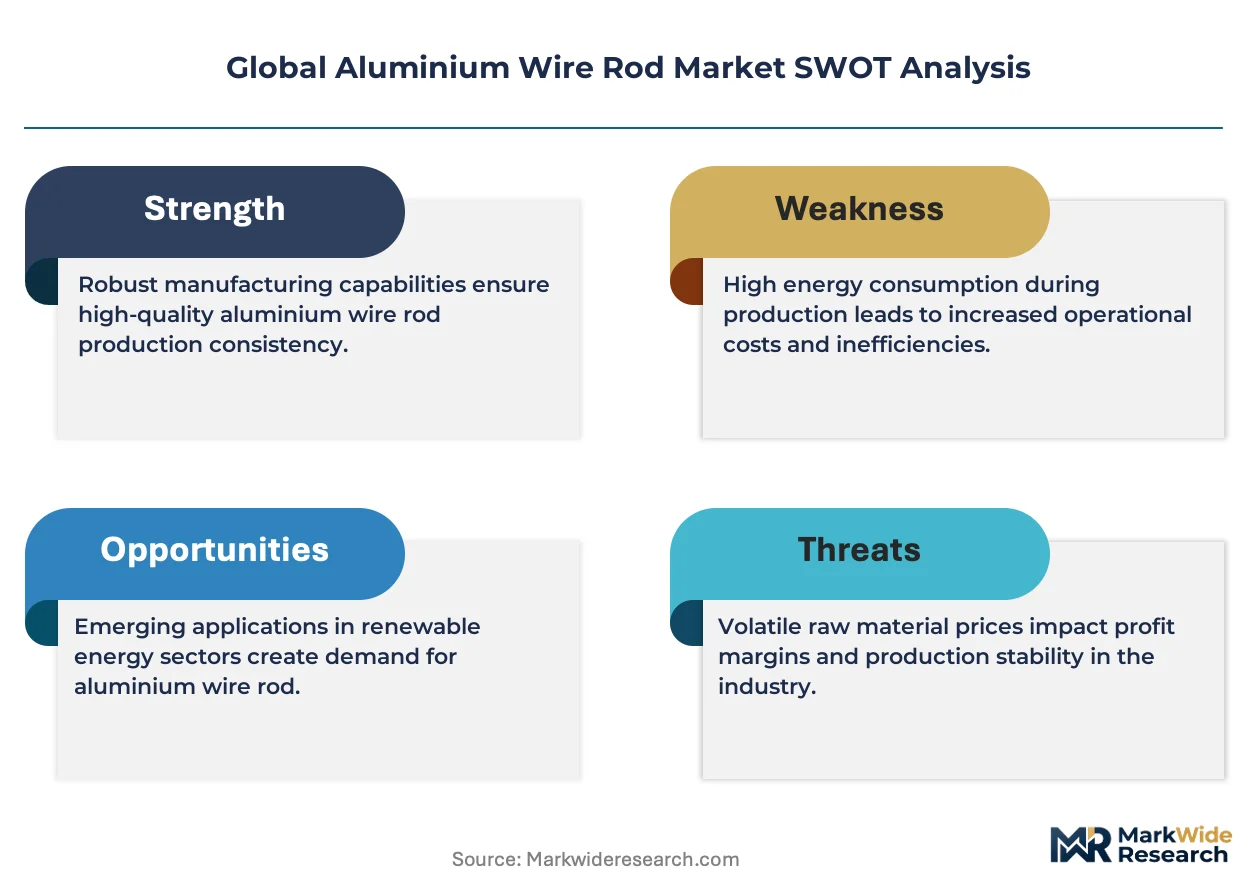
Primary aluminium smelter consolidation around renewable energy assets is compressing billet supply chains and forcing wire rod converters into long-term offtake arrangements with hydro-powered producers in Canada, Norway, and Iceland.
Growth Catalysts
- Grid Modernization Mandates:India's CEA rural electrification targets and state-level tender programs are absorbing EC-grade rod volumes for 11 kV and 33 kV distribution lines.
- Carbon Border Adjustments:The EU Green Deal's embodied carbon disclosure rules are redirecting procurement toward low-carbon billet sources certified under ISO 14064.
- Automotive Harness Miniaturization:Sub-1 mm fine rod demand from EV OEMs is accelerating drawing capacity expansion for high-conductivity alloy variants.
Market Restraints
- LME Price Volatility:Primary aluminium input cost swings exceeding 20% quarterly amplitude are eroding converter margins and destabilizing contract pricing.
- Smelter Concentration Risk:Russian and Chinese hydro-powered capacity accounts for disproportionate low-carbon billet supply, exposing European cable makers to geopolitical disruption.
- Copper Substitution Ceiling:High-voltage underground cable applications remain locked into copper due to thermal cycling performance requirements that aluminium alloys cannot yet match.
Strategic Opportunities
- US Inflation Reduction Act:Domestic content bonuses for transmission infrastructure are creating captive demand for North American smelted rod in FERC-jurisdictional projects.
- Floating Offshore Wind:Dynamic marine cable applications require anodized rod with specialized magnesium-silicon alloys for salt-spray resistance.
- Direct-to-Utility Digital Platforms:B2B marketplaces are disintermediating traditional distributor networks for standard EC-grade volumes in Southeast Asian markets.
Industry Challenges
- Metallurgical Talent Scarcity:Continuous casting process engineers with alloy formulation expertise are concentrated among retiring cohorts at legacy European and Japanese equipment suppliers.
- BIS Certification Timelines:Indian state tender eligibility requires 12-18 month testing cycles for imported rod that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminium Wire Rod Market |
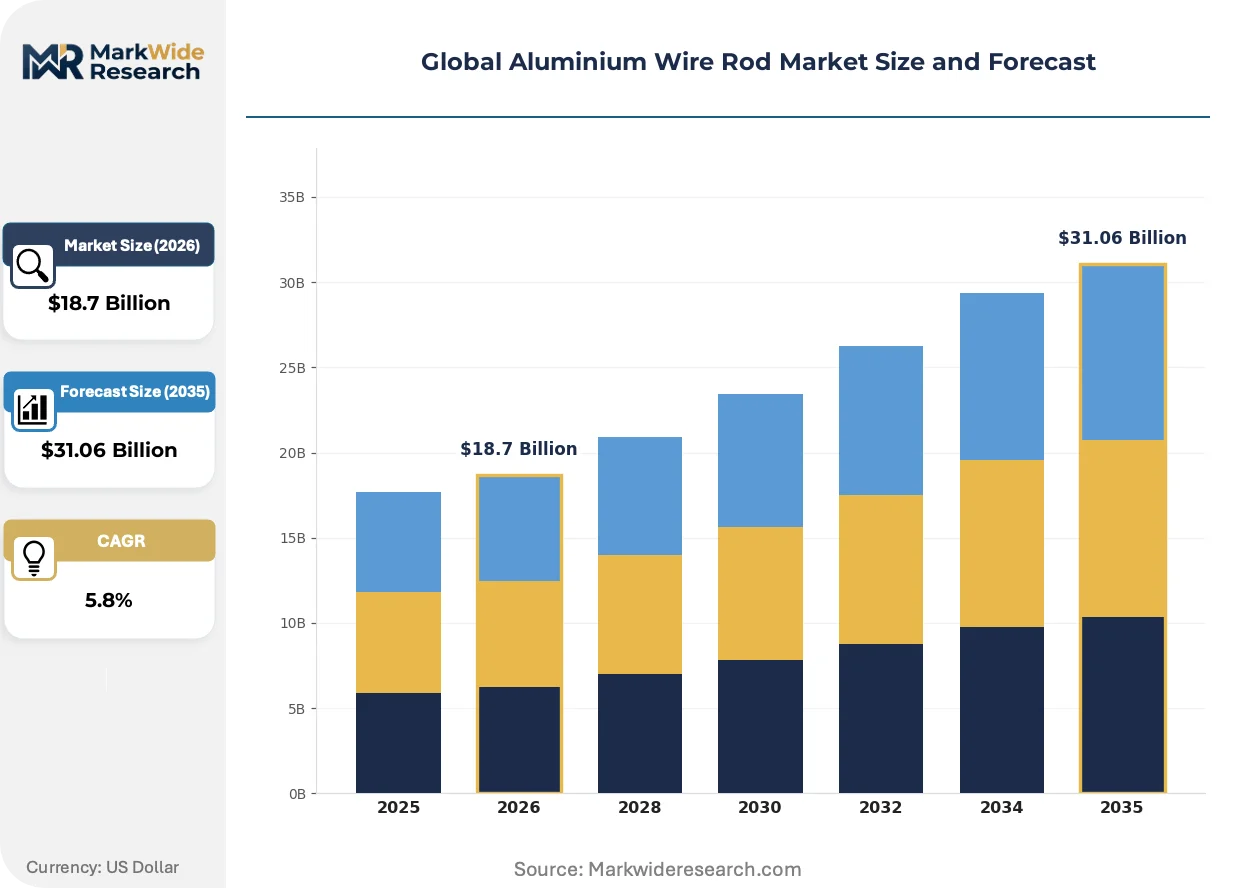
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bare, Coated, Alloy, Stranded End User: Aerospace, Automotive OEMs, Electrical, Construction Diameter: Less than 1 mm, 1 mm to 5 mm, 5 mm to 10 mm, Above 10 mm Application: Transmission Lines, Cables, Components, Building Wires |
| Companies Covered | UC Rusal, Hindalco Industries Limited, Rio Tinto, Southwire Company LLC, China Hongqiao Group Limited, Alcoa Corporation, Vedanta Resources Limited, Emirates Global Aluminium, Norsk Hydro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminium Wire Rod Market Emerging Trajectories
Electrification infrastructure buildouts and embodied carbon accounting are simultaneously pulling wire rod specification toward traceable low-carbon grades and automated quality assurance systems.
Machine vision inspection integrated with eddy-current testing is automating surface defect detection in continuous casting lines. European cable makers adopting these systems are reducing downstream drawing breakage rates and compressing incoming quality assurance timelines from days to hours. The technology is automating manual sorting operations that previously required skilled metallurgical technicians.
REACH compliance extensions for persistent organic pollutants in polymer coatings are forcing reformulation of marine-grade rod barrier systems. ECHA's revised restriction proposals affect anodizing chemistries used in North Sea offshore cable applications. Nordic transmission project developers are accelerating qualification of alternative ceramic-based coatings ahead of enforcement deadlines.
Long-term power purchase agreements tied to renewable generation are displacing spot-market billet procurement among integrated European converters. German and Austrian cable manufacturers are locking decade-long aluminium supply contracts with Icelandic and Norwegian smelters to secure carbon footprint credentials. This contracting shift is visible in transmission project bids where embodied carbon disclosure now determines technical scoring weightings.
Global Aluminium Wire Rod Market Segmentation
Aluminium wire rod specifications fragment across conductivity grades, coating technologies, and dimensional tolerances that determine converter eligibility for grid tenders and automotive harness contracts. Procurement teams segment supply by carbon intensity certification and alloy traceability rather than commodity pricing alone.
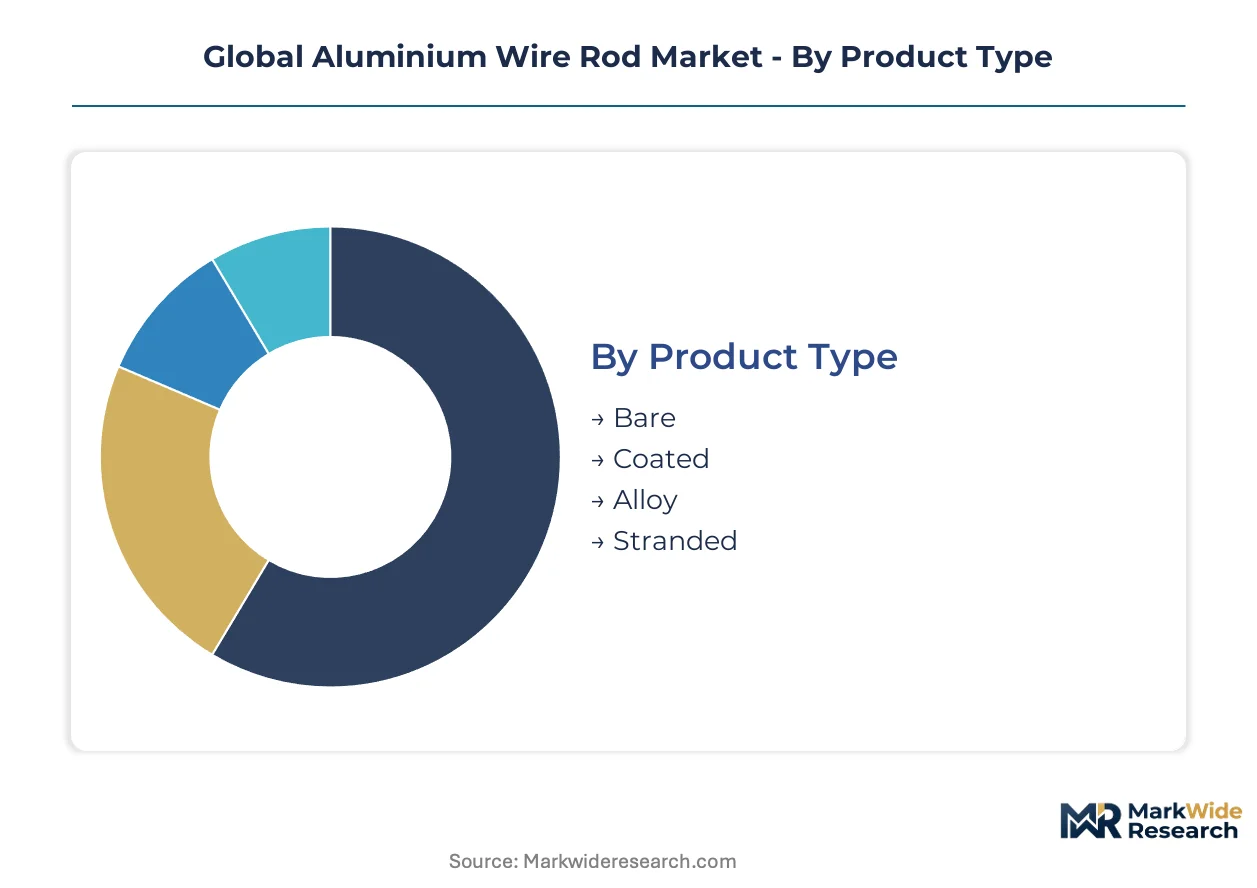
Product Type:
Supply concentration around hydro-powered smelters is reshaping product type availability, with low-carbon billet allocation favoring integrated rod categories.
- Bare:Unprotected EC-grade rod with conductivity exceeding 61% IACS dominates overhead transmission procurement from Indian state utilities and Southeast Asian grid operators. Volume concentrates in 9.5 mm to 15 mm diameters for 11 kV and 33 kV distribution line construction.
- Coated:Anodized or polymer-barrier variants command premium placement in North Sea offshore wind and marine cable applications where salt-spray resistance outweighs material cost. REACH compliance extensions are forcing ceramic-based coating reformulations ahead of enforcement deadlines.
- Alloy:Magnesium-silicon formulations adjust tensile strength for mechanical cable and fastener applications requiring fatigue resistance.
- Stranded:Pre-twisted configurations reduce field installation labor for utility contractors in rural electrification programs.
Today's leader: Bare. Tomorrow's challenger: Coated.
End User:
Cost tier stratification separates premium-certified rod for automotive harnesses from standard-grade utility volumes.
- Electrical:State power distributors in India and transmission utilities across Southeast Asia absorb the majority of EC-grade rod output for grid modernization. India's CEA rural electrification targets and state-level tender programs specify BIS-certified conductors.
- Automotive OEMs:EV manufacturers drive sub-1 mm fine rod demand for harness miniaturization, requiring high-conductivity alloy variants with precise dimensional tolerances. Drawing capacity expansion is accelerating for this specification band.
- Construction:Building wire applications consume mid-diameter rod for residential and commercial electrical distribution.
- Aerospace:Specialized alloy grades with stringent fatigue specifications serve airframe cabling and control systems.
Electrical utilities currently dominate procurement volumes; automotive OEMs are expanding most quickly.
Diameter:
Application requirements dictate diameter selection, with transmission infrastructure favoring heavier gauges and electronics miniaturization pushing fine wire limits.
- 5 mm to 10 mm:The construction and component workhorse band serves building wire extrusion and mechanical cable fabrication. Continuous casting lines optimize throughput at this diameter range.
- Less than 1 mm:Fine rod for automotive harness miniaturization and consumer electronics wiring demands precision drawing equipment with automated quality assurance. Machine vision inspection systems are compressing incoming quality timelines from days to hours.
- 1 mm to 5 mm:Intermediate diameters bridge power transmission and control cable applications.
- Above 10 mm:Heavy-gauge rod serves high-voltage transmission conductor cores and industrial busbar fabrication.
The 5 mm to 10 mm band anchors current capacity utilization; sub-1 mm fine rod is gaining share fastest.
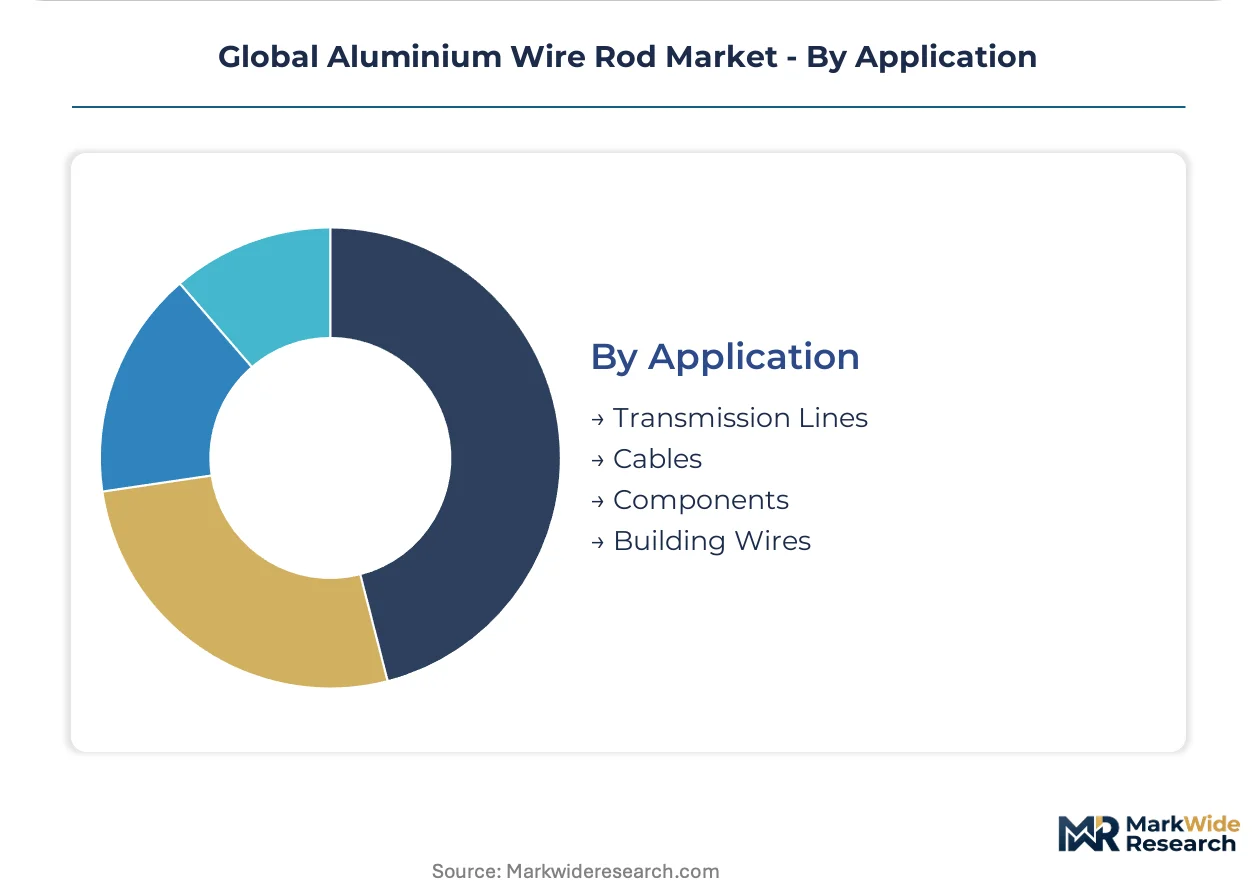
Application:
Geography determines application priority, with emerging economies emphasizing transmission expansion and mature markets focusing on grid reliability upgrades.
- Transmission Lines:Overhead high-voltage conductors represent the largest volume outlet, with India's state distributors and Southeast Asian utilities replacing copper with cost-effective aluminium for 66 kV and above. Carbon border adjustments are redirecting European procurement toward certified low-carbon billet sources.
- Cables:Underground and submarine cable applications require specialized alloy formulations for thermal cycling performance. Copper substitution ceilings persist in high-voltage underground segments where aluminium alloys cannot yet match thermal performance.
- Components:Fastener and mechanical hardware applications consume alloyed rod with tailored tensile properties.
- Building Wires:Residential and commercial electrical distribution represents a stable, price-sensitive demand segment.
Transmission lines command today's volume; cables present the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Odisha's integrated mining-to-rod corridor anchors global aluminium wire rod production capacity, drawing feedstock from captive smelters and serving transmission infrastructure across South Asia and beyond.
India
Rural electrification drives EC-grade rod absorption through state power distributors modernizing 11 kV and 33 kV distribution networks. CEA mandates and BIS certification requirements structure tender eligibility for imported and domestic supply. Uttar Pradesh and Odisha host integrated converter operations feeding grid infrastructure projects.
China
Dual carbon enforcement through MEE restricts coal-powered smelter output, tightening wire rod billet availability for non-integrated converters. GB standards and SAMR oversight shape quality benchmarks for electrical conductor applications. Shandong and Xinjiang smelter clusters pivot toward renewable-powered capacity to maintain supply continuity.
Germany
Transmission utilities prioritize certified low-emission aluminium grades for Nordic and domestic grid projects under EU Green Deal procurement rules. ECHA REACH compliance extensions affect coating chemistries for marine cable applications. North Rhine-Westphalia cable manufacturers lock decade-long supply contracts with Icelandic and Norwegian smelters.
United States
FERC-jurisdictional transmission projects generate captive demand for North American smelted rod through IRA domestic content bonuses. EPA environmental standards and FERC grid reliability mandates shape converter compliance burdens. Georgia and Texas host drawing capacity expansion serving Southeast and Southwest utility markets.
Norway
Hydro-powered smelter capacity supplies premium low-carbon billet to European cable makers seeking ISO 14064 certification for carbon disclosure. Norwegian producers leverage long-term power purchase agreements to secure embodied carbon credentials. Søderberg and Høyanger facilities anchor Nordic supply to German and Benelux transmission developers.
Global Aluminium Wire Rod Market Vendor Landscape
Global majors compete with regional champions across feedstock security and carbon certification dimensions. Market structure tilts toward integrated producers controlling mining-to-rod value chains, with converters dependent on long-term billet offtake arrangements. Three archetypes dominate: hydro-powered primary aluminium suppliers, integrated mining-to-rod operators, and regional drawing specialists. Consolidation through captive smelter partnerships and strategic capacity co-location near renewable energy assets represents the primary competitive dynamic.
Within the integrated operator tier, Hindalco Industries Limited and Vedanta Resources Limited exemplify mining-to-rod vertical control spanning Indian bauxite deposits and domestic converter networks. UC Rusal occupies a position as the archetypal low-carbon billet supplier leveraging Siberian hydro-powered smelter capacity for European cable maker procurement. Among scale-driven primary producers, Rio Tinto and Norsk Hydro represent certified low-emission grade positioning for premium transmission project placement.
| Leading Market Players |
|---|
| UC Rusal |
| Hindalco Industries Limited |
| Rio Tinto |
| Southwire Company LLC |
| China Hongqiao Group Limited |
| Alcoa Corporation |
| Vedanta Resources Limited |
| Emirates Global Aluminium |
| Norsk Hydro |
| Others |
Supply Flow & Price Mechanics
LME primary aluminium pricing volatility cascades through converter margins into three distinct procurement tiers: long-term offtake contracts with hydro-powered smelters, spot-market billet purchases, and integrated captive supply. Carbon certification premiums now separate contract tiers more sharply than volume discounts, with EU Green Deal disclosure requirements forcing European cable makers to absorb higher input costs for ISO 14064-certified rod.
Pricing Analysis
Input-cost pass-through from primary aluminium billet to finished rod operates on quarterly contract adjustments indexed to LME spot movements. Three-tier pricing structure across premium, standard, and economy levels reflects carbon intensity certification, alloy traceability, and volume commitment scale. Pricing pressure stems from smelter consolidation around renewable assets, compressing low-carbon billet availability. State power distributors in India exhibit highest price sensitivity through tender-driven procurement, while German transmission utilities accept certification premiums for Nordic-sourced rod.
Supply Chain Analysis
Primary aluminium feedstock rests on hydro-powered smelter capacity concentrated in Canada, Norway, and Iceland, with Russian Siberian output supplying European converters despite geopolitical exposure. Billet availability, continuous casting equipment, and magnesium-silicon alloy additives constitute critical input dependencies. Single-source vulnerability runs through concentrated low-carbon smelter ownership, exposing cable makers to disruption. Distribution runs through long-term offtake arrangements displacing spot procurement, with integrated converters in India and China bypassing merchant billet markets entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminium wire rod has matured into a quality-differentiated market where premium specifications for carbon-certified rod command structural margin advantages over commodity-grade volumes. This shift favors producers with captive renewable energy supply and integrated mining-to-rod control.
For Market Incumbents: Acquire hydro-powered smelter capacity or secure decade-long power purchase agreements to lock in carbon certification credentials before EU border adjustments tighten. Defend against emerging low-carbon entrants by accelerating BIS certification timelines for Indian state tenders and investing in machine vision quality systems that reduce drawing breakage rates for automotive harness contracts. For New Entrants and Emerging Players: Capture stranded renewable energy sites in Southeast Asia where grid infrastructure expansion outruns domestic smelter capacity. White-space exists in sub-1 mm fine rod drawing for EV harness miniaturization, with entry through specialized alloy formulation partnerships rather than commodity EC-grade competition. Direct-to-utility digital platforms in Indonesia and Vietnam disintermediate traditional distributor networks for standard volumes. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated operators controlling bauxite-to-rod value chains in India and captive hydro-powered smelters in Nordic markets. Long-term viability hinges on carbon intensity positioning rather than scale alone, with five-to-ten year windows favoring assets with renewable energy offtake already contracted. Watch LME price volatility amplitude as the signal for converter margin compression that triggers consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks decade-long billet offtake with Icelandic and Norwegian smelters for carbon disclosure compliance. |
| Backward Integration | Captures captive bauxite mining and smelter capacity in Odisha to bypass LME price volatility exposure. |
| Green Certification Program | Secures ISO 14064 credentials for premium placement in German and Nordic transmission project bids. |
| Capacity Expansion | Adds sub-1 mm fine rod drawing lines to serve EV OEM harness miniaturization demand. |
| Joint Venture | Partners with Southeast Asian utilities on direct-to-procurement digital platforms for standard EC-grade volumes. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with smelter operations managers, cable manufacturer procurement leads, state utility tender officers, and continuous casting equipment engineers with secondary validation. Sources included LME price databases, Indian CEA rural electrification tender records, EU ETS carbon border adjustment proposals, and SEC filings from integrated aluminium producers. Bottom-up volume estimates from converter capacity utilization triangulated against top-down demand projections from grid infrastructure investment pipelines.
Segment-weighting across the projection horizon applied dimensional analysis by product type (bare, coated, alloy, stranded), end user (electrical utilities, automotive OEMs, construction, aerospace), diameter band, and application category. CAGRs derived from historical price-volume relationships and forward-looking infrastructure investment schedules, with specific inputs from EV production forecasts for harness miniaturization demand and India's CEA rural electrification targets for transmission line conductor absorption.
Geopolitical disruption to Russian hydro-powered supply, enforcement delays in EU carbon border adjustments, and metallurgical talent scarcity in continuous casting operations are the dominant revision risks to the outlook. Forecasts embed assumptions about renewable energy capacity expansion sustaining low-carbon billet availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
North America Grain Oriented Electrical Steel Market
Metals
Monel Alloy Market
Metals
316 Stainless Steel Container Market
Metals
Aluminium Powder Market
Metals
Medium Carbon Steel Market
Metals
Silver Nitrate Market
Metals
Ferrochrome Market
Metals
GCC Metal Forging Market
Metals
North America Metal Casting Market
Metals
Global Brazing Consumable Market
Metals
Titanium Powder Market
Metals
Bearing Steel Market
Metals
Ferrosilicon Magnesium Market
Metals
Copper and Copper Alloy Foil Market
Metals
China Copper Market
Metals
Global High Purity Titanium Powder Market