
 Titanium Market | 2026-2036
Titanium Market Size, Share, and Industry Trends Forecast 2026-2036
Titanium Market Intelligence
China's expansion of titanium sponge production capacity is reshaping competitive positioning across the global supply chain. VSMPO-AVISMA leverages its deep vertical integration and long-term aerospace agreements to maintain market leadership. Titanium Metals Corporation (Timet) focuses on a diversified portfolio spanning both aerospace and industrial applications. Allegheny Technologies (ATI) competes through its specialized high-performance materials and advanced alloy development for defense platforms.
Titanium is a lustrous transition metal, element 22, recognized for its superior strength-to-density ratio and exceptional resistance to corrosion, especially in saltwater environments. Its primary industrial purpose is the production of strong, lightweight alloys for critical performance environments where failure is not an option. Aerospace Grade specifications command the highest value, driven by strict certification requirements for flight-critical parts like landing gear. The market for Medical Grade titanium is expanding, specifically for biocompatible orthopedic and dental implants.
Material and application standards are stringent and geographically specific. The FAA in the United States and EASA in Europe mandate specific alloy certifications for all flight-critical aerospace components. In parallel, global ISO 5832 standards govern the precise composition of titanium alloys used in surgical implants. These complex regulatory frameworks create significant barriers to market entry and favor established, certified producers.
Market Dynamics
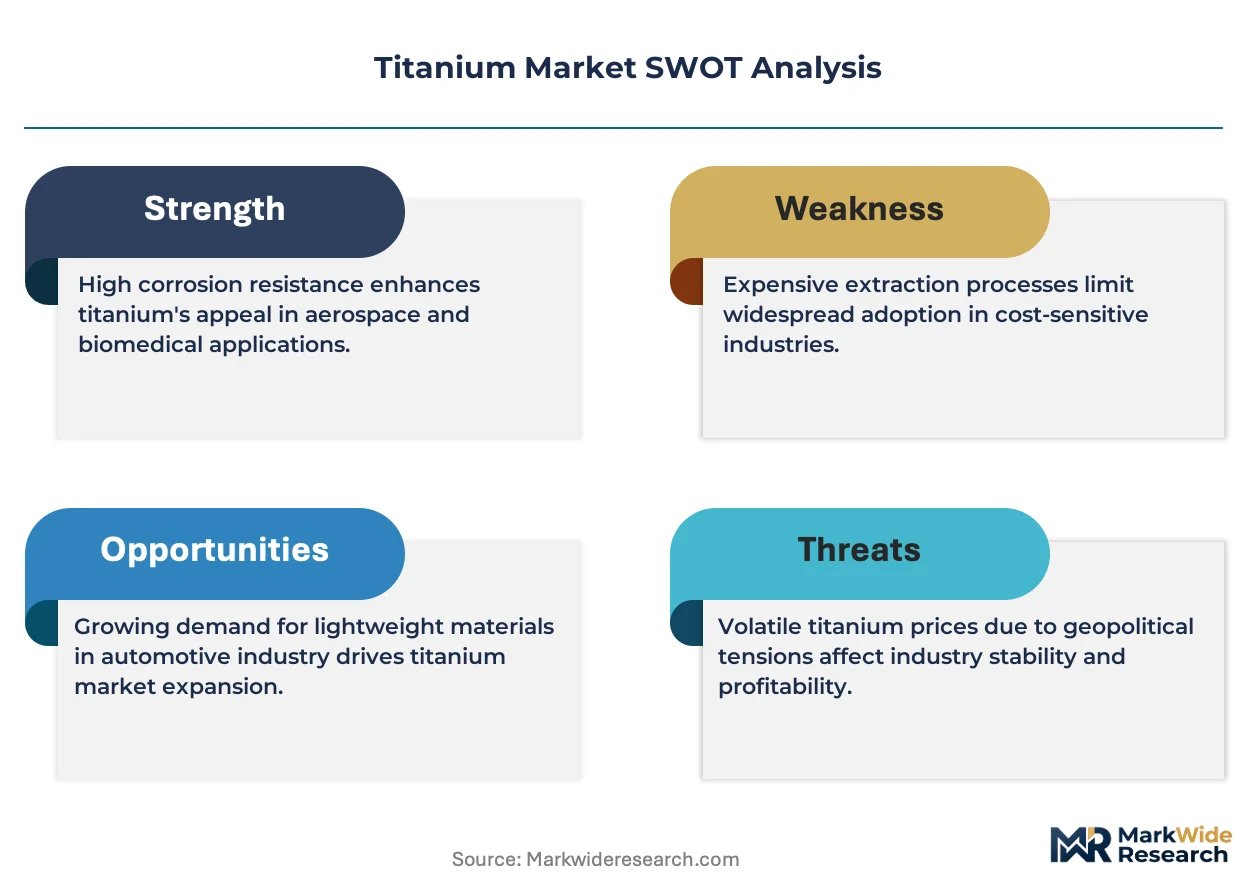
The central tension in the titanium market is the divergence between high-specification aerospace demand and the increasing commoditization of industrial-grade material, driven by massive production capacity expansion within China for its domestic chemical and power sectors.
Growth Catalysts
- Aerospace Programs:Sustained demand for next-generation commercial aircraft and military platforms, particularly for engine and airframe components, requires a continuous supply of high-strength, certified titanium alloys.
- Industrial Expansion in China:Government-backed expansion of the chemical processing and desalination industries in China creates a large, concentrated source of demand for corrosion-resistant, industrial-grade titanium.
- Medical Device Innovation:The expanding use of titanium in biocompatible applications, governed by ISO 5832 standards, for orthopedic and dental implants provides a stable, high-value demand segment.
Market Restraints
- High Production Costs:The energy-intensive nature of the Kroll process for producing titanium sponge results in a high intrinsic cost floor for the primary metal, limiting its use in cost-sensitive applications.
- Substitution by Composites:In certain aerospace structural applications, advanced carbon fiber composites present a viable lightweight alternative, capping potential titanium volume in specific airframe sections.
- Supply Chain Concentration:A limited number of large, vertically integrated producers of aerospace-grade sponge and mill products creates supply chain risks and significant pricing power for incumbent suppliers.
Strategic Opportunities
- Additive Manufacturing:The development of qualified titanium alloy powders for 3D printing opens new opportunities for producing complex, lightweight components for medical implants, satellites, and performance automotive parts.
- Automotive Lightweighting:Stricter emissions regulations globally create an opportunity for titanium alloys in niche, high-performance automotive components like exhaust systems and suspension springs where weight reduction is critical.
- Defense Modernization in India:India's focus on domestic defense manufacturing and space exploration presents an underpenetrated market for specialized titanium alloys for military aircraft, naval vessels, and launch vehicles.
Industry Challenges
- Qualification and Certification Timelines:The extensive and costly process of qualifying new alloys and production facilities with bodies like the FAA and EASA creates significant delays and barriers to entry for new materials.
- Specialized Labor Scarcity:A shortage of skilled welders and machinists with experience handling titanium's unique properties can create production bottlenecks and increase manufacturing costs for fabricators.
- Capital Intensity:Establishing or expanding titanium sponge and melting facilities requires exceptionally high capital investment, deterring new entrants and concentrating capacity among established players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Titanium Market |
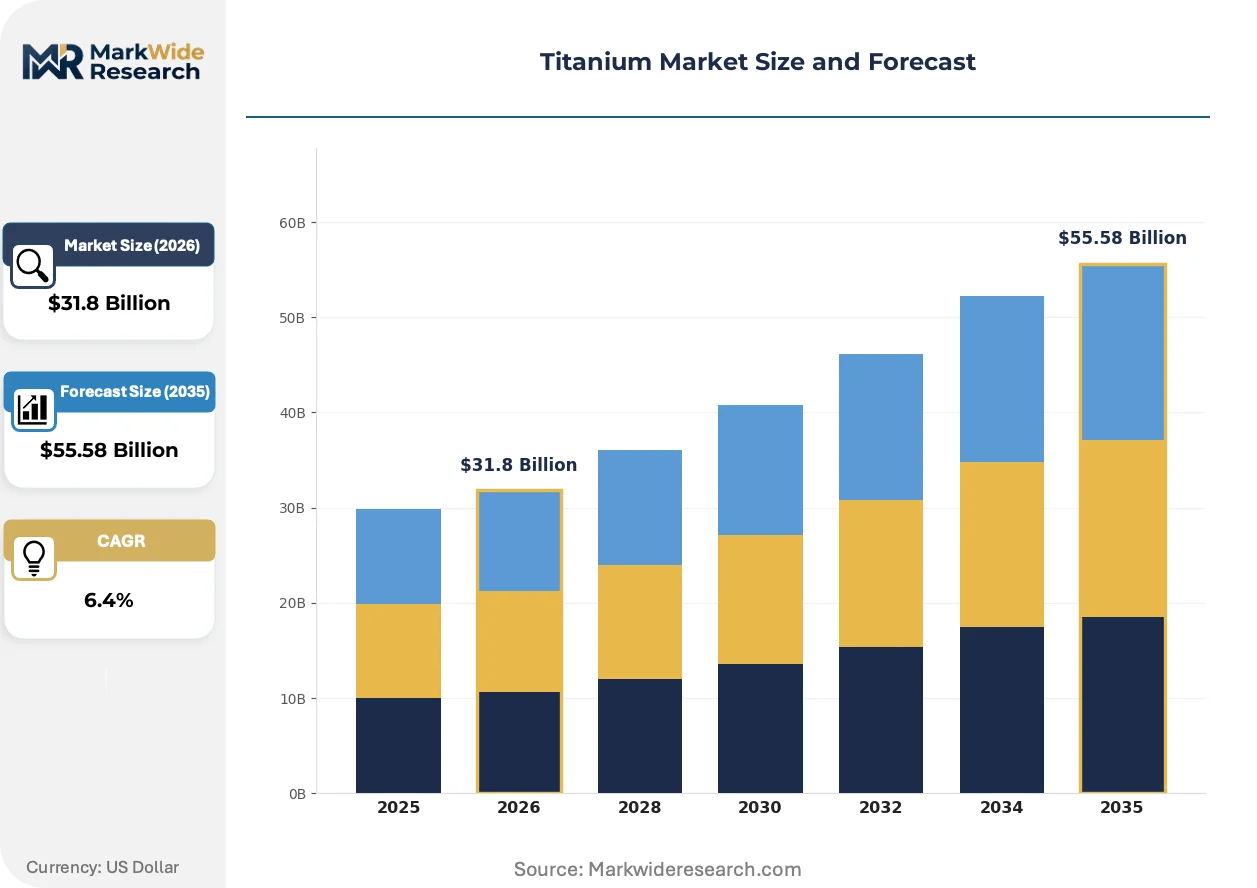
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Titanium Sponge, Titanium Slab, Titanium Ore, Titanium Powder, Titanium Scrap Grade: Commercially Pure, Aerospace Grade, Medical Grade, Industrial Grade, Marine Grade Application: Aerospace Components, Medical Implants, Chemical Processing Equipment, Sports Goods, Consumer Electronics End User: Aircraft Manufacturers, Healthcare Providers, Chemical Manufacturing, Sports Equipment Producers, Electronics Manufacturers |
| Companies Covered | OSAKA Titanium Technologies Co., Ltd., Kronos Worldwide, Inc., VSMPO-AVISMA Corporation, Titanium Metals Corporation (Timet), Venator Materials PLC., The Chemours Company, Allegheny Technologies (ATI), Toho Titanium Co., Ltd., Tronox Holdings Plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Titanium Market Strategic Shifts & Innovations
Process innovation and evolving certification requirements are creating distinct performance and cost tiers. These shifts are transforming how material is specified, sourced, and qualified across aerospace, medical, and industrial end markets.
Digital twin technology enables the virtual modeling of titanium alloy behavior under specific load and environmental conditions. Aerospace and defense contractors are the primary adopters, integrating these models into their design workflows. This technology is digitizing the entire material qualification process, significantly reducing the reliance on expensive and time-consuming physical prototype testing.
The European Union's Circular Economy Action Plan is creating a strong incentive for improved material lifecycle management. This policy directly encourages investment in advanced sorting and recycling technologies to recover high-purity titanium scrap from end-of-life aircraft and industrial equipment. European aerospace manufacturers are most affected, developing closed-loop systems to secure a secondary supply source and meet sustainability mandates.
Long-term supply agreements for certified-grade material are becoming the dominant procurement model in aerospace. This model displaces transactional, spot-market purchasing for critical flight components, requiring suppliers to guarantee supply continuity and manage inventory. This behavior is most visible within the North American and European aerospace sectors, driven by OEM efforts to de-risk supply chains amid production ramp-ups.
Titanium Market Segmentation
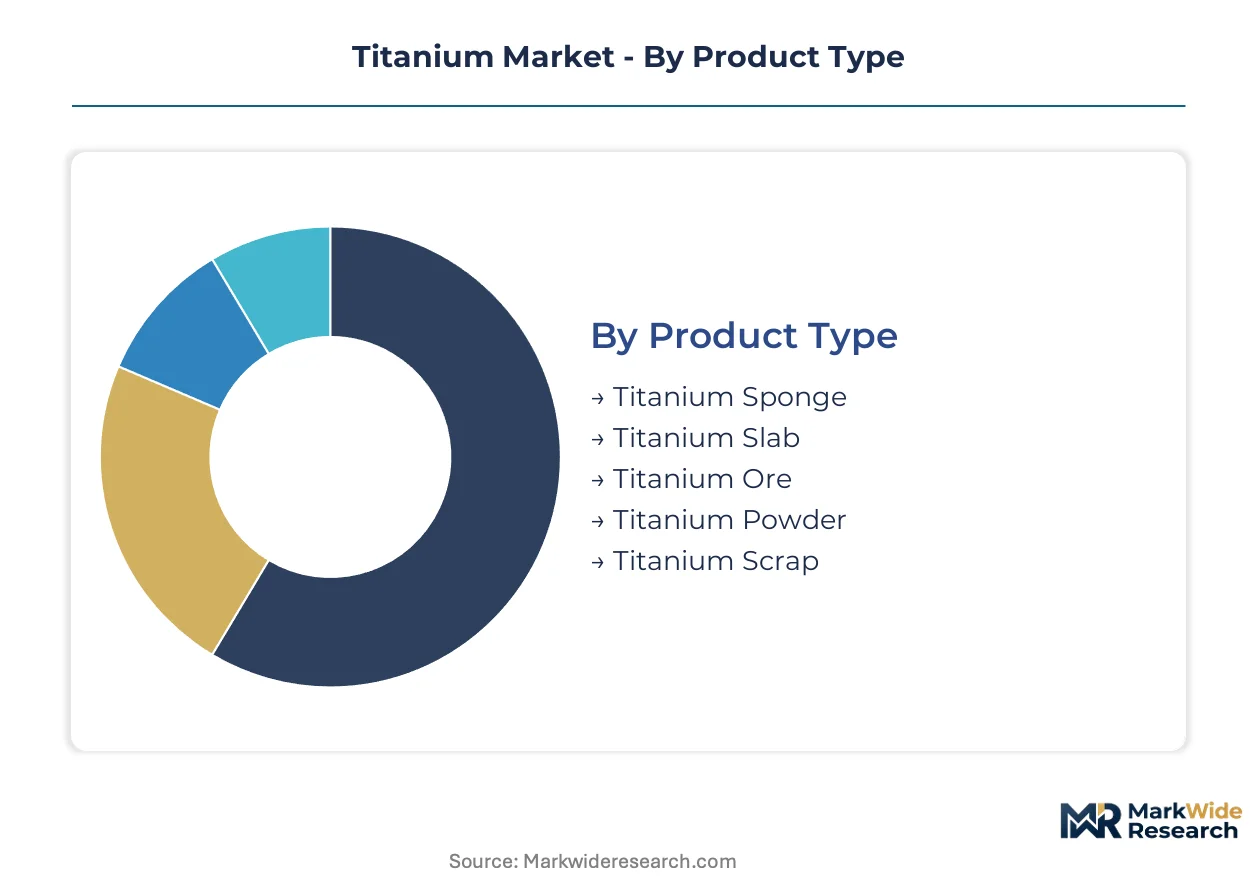
The Titanium Market exhibits distinct performance tiers driven by material specifications and end-use requirements. Understanding these segments is critical for assessing market dynamics and identifying specific value pools. Each segment operates under unique regulatory frameworks and supply chain configurations, influencing pricing and competitive strategies.
Product Type:
The intensity of after-sales service and ongoing qualification needs varies significantly across different titanium product forms. Downstream processing requirements dictate the complexity of material handling and certification throughout the supply chain.
- Titanium Sponge:This is the primary, porous metallic form produced from titanium ore, typically via the Kroll process. Its purity and consistency are foundational for all subsequent titanium products, with global cost structures heavily influenced by Chinese production expansion.
- Titanium Slab:An intermediate product formed by melting titanium sponge and often alloying elements, then cast into large ingots for further rolling. Demand is concentrated in aerospace and industrial applications, serving as the raw material for plate, sheet, and bar products.
- Titanium Ore:The naturally occurring mineral containing titanium, such as ilmenite and rutile, which forms the upstream source for all titanium production.
- Titanium Powder:Fine particulate titanium, increasingly vital for additive manufacturing processes in medical and aerospace sectors.
- Titanium Scrap:Recycled titanium material recovered from manufacturing waste or end-of-life products, crucial for reducing overall production costs and environmental impact.
Titanium Sponge holds the largest share; momentum sits with Titanium Powder.
Grade:
Titanium grades are differentiated primarily by their mechanical properties, chemical composition, and the stringent performance requirements of their intended applications. This stratification directly impacts material cost and market entry barriers.
- Aerospace Grade:Characterized by exceptional strength-to-weight ratios and fatigue resistance, these alloys meet rigorous FAA and EASA certification for flight-critical components. Demand is sustained by new commercial aircraft orders and military platform upgrades.
- Medical Grade:These biocompatible alloys, primarily CP titanium and Ti-6Al-4V ELI, adhere to ISO 5832 standards for orthopedic and dental implants. The expanding global healthcare sector drives consistent, high-value demand for these materials.
- Commercially Pure:Unalloyed titanium, known for its excellent corrosion resistance and formability, finds use in less demanding industrial and consumer applications.
- Industrial Grade:Designed for corrosion resistance in harsh environments, this grade is heavily utilized in chemical processing, power generation, and desalination plants in China.
- Marine Grade:Specifically engineered for superior corrosion resistance in saltwater, finding applications in naval vessels, offshore platforms, and subsea equipment.
Aerospace Grade titanium maintains a premium pricing structure, while Medical Grade demand is expanding significantly.
Application:
The value concentration within the titanium market varies widely across different end-use applications, reflecting the material's performance criticality and the associated certification costs. Each application segment presents unique engineering challenges.
- Aerospace Components:This segment includes airframes, engine parts, and landing gear, demanding the highest quality, certified titanium alloys for safety and performance. Sustained commercial aircraft production and military modernization programs are primary volume drivers.
- Medical Implants:Titanium's biocompatibility and corrosion resistance make it ideal for orthopedic, spinal, and dental implants, governed by strict ISO standards. Innovation in implant design and an aging global population contribute to steady market expansion.
- Chemical Processing Equipment:Titanium's corrosion resistance is crucial for heat exchangers, pipes, and tanks in chemical plants, especially in China's expanding industrial base.
- Sports Goods:Niche applications include golf club heads, bicycle frames, and tennis rackets, where lightweight strength provides a competitive advantage.
- Consumer Electronics:Limited, high-end use in smartphone casings and luxury watches, leveraging titanium's premium feel and durability.
Aerospace Components command the highest value per ton, and Medical Implants show consistent, stable growth.
End User:
Different end-user segments are characterized by distinct procurement strategies, regulatory compliance burdens, and demand cycles, shaping supplier engagement and product development priorities across the titanium market.
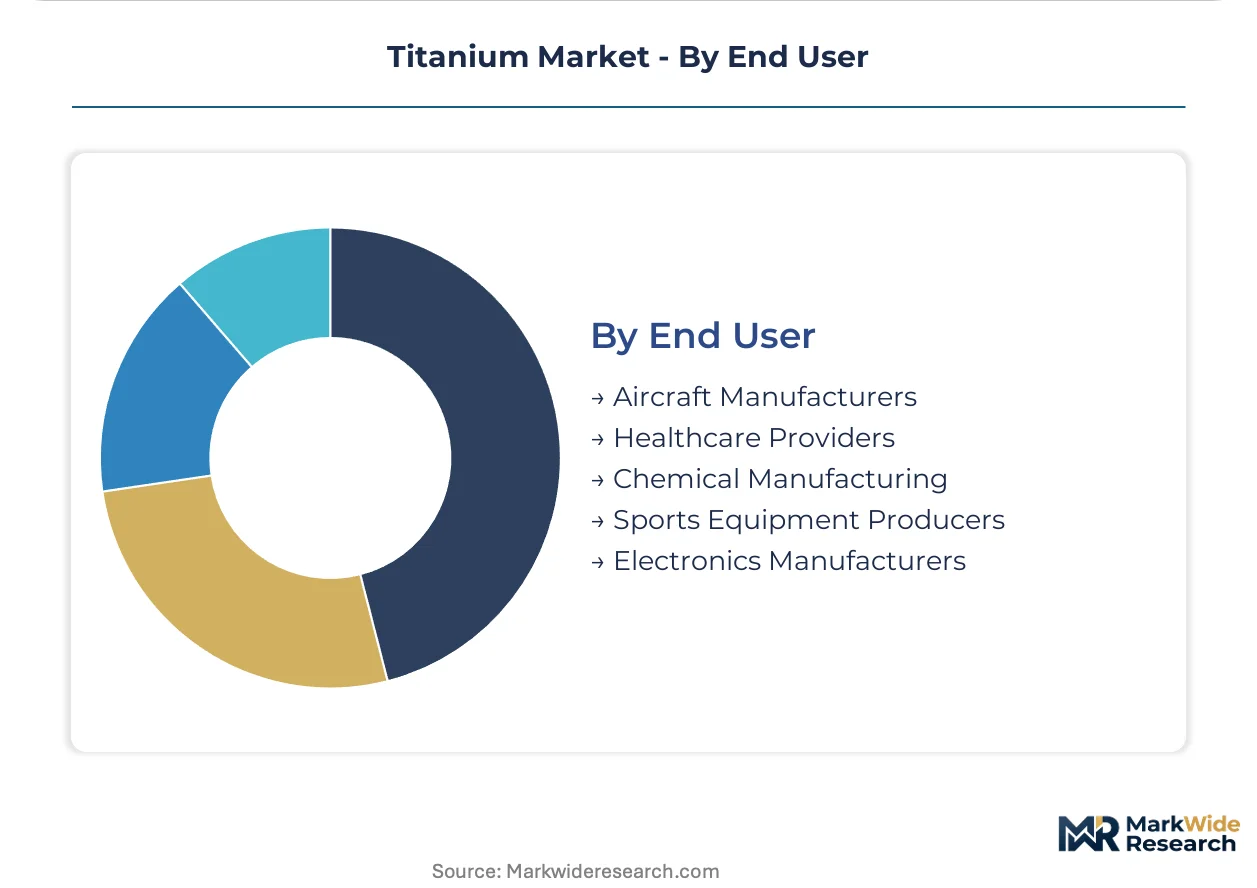
- Aircraft Manufacturers:These companies require long-term supply agreements for certified aerospace-grade titanium, adhering to stringent FAA and EASA standards for flight safety. Boeing and Airbus lead demand for large volumes of high-performance alloys.
- Healthcare Providers:Hospitals and clinics utilize titanium implants and surgical instruments, driven by biocompatibility requirements and ISO 5832 specifications. Demand is influenced by demographics and advancements in medical procedures.
- Chemical Manufacturing:Companies in this sector procure industrial-grade titanium for corrosion-resistant equipment, especially within China's expanding chemical and power generation industries.
- Sports Equipment Producers:Manufacturers source titanium for performance-enhancing products, prioritizing lightweight and durable material properties for competitive advantage.
- Electronics Manufacturers:This segment uses titanium for premium product lines, focusing on aesthetics, strength, and hypoallergenic properties for consumer appeal.
Aircraft Manufacturers represent the largest volume purchasers, with Healthcare Providers demonstrating robust expenditure growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Aviation Administration (FAA) in the United States sets stringent certification standards, influencing global aerospace titanium demand. This framework drives specialized alloy production and advanced material qualification across major manufacturing hubs. High-value aerospace applications anchor significant market portions.
United States
Demand for aerospace-grade titanium alloys remains robust, driven by commercial aircraft orders and military platforms. The FAA mandates specific alloy certifications for flight-critical components, ensuring material integrity. Manufacturers in Wichita, Kansas, and Seattle, Washington, concentrate on airframe and engine component production.
China
Industrial-grade titanium consumption expands rapidly, fueled by investment in chemical processing and power generation infrastructure. China's dual carbon goals incentivize material efficiency and localized production. Major industrial clusters in the Yangtze River Delta drive significant demand for corrosion-resistant equipment.
France
European aerospace programs, particularly Airbus production, sustain high demand for certified titanium alloys. The European Union Aviation Safety Agency (EASA) enforces rigorous material and component qualification processes. Toulouse, a primary aerospace hub, sees consistent procurement for airframe and engine fabrication.
India
Defense modernization efforts and an expanding space exploration program generate new opportunities for specialized titanium alloys. India's PLI scheme supports domestic manufacturing capabilities for advanced materials. Production centers in Bengaluru focus on military aircraft and space launch vehicle development.
Japan
Advanced manufacturing and a focus on high-performance materials drive demand for titanium in niche applications. The Ministry of Economy, Trade and Industry (METI) supports research into new alloy development. Industrial zones around Osaka specialize in producing high-purity titanium sponge and advanced mill products.
Titanium Market Key Industry Players
Capability concentration sits with one tier, focusing on highly certified aerospace-grade alloys; scale advantage sits with another, dominating industrial-grade material production. The market exhibits a tiered structure, ranging from upstream sponge producers to downstream alloy fabricators. Archetypes include vertically integrated aerospace specialists, diversified material suppliers, and niche high-performance alloy developers. Long-term supply agreements, strategic capacity expansions, and continuous alloy development are dominant competitive moves.
Vertically integrated producers like VSMPO-AVISMA Corporation exemplify market leadership through deep supply chain control and long-standing aerospace agreements, particularly for critical flight components. Titanium Metals Corporation (Timet) occupies a position as a diversified supplier, serving both the demanding aerospace sector and various industrial applications with a broad material portfolio. Allegheny Technologies (ATI) represents a specialized high-performance materials developer, focusing on advanced alloy development for critical defense platforms and other high-specification environments. These established companies anchor different segments of the global titanium supply chain, leveraging their expertise and certifications to maintain market presence.
| Leading Market Players |
|---|
| OSAKA Titanium Technologies Co., Ltd. |
| Kronos Worldwide, Inc. |
| VSMPO-AVISMA Corporation |
| Titanium Metals Corporation (Timet) |
| Venator Materials PLC. |
| The Chemours Company |
| Allegheny Technologies (ATI) |
| Toho Titanium Co., Ltd. |
| Tronox Holdings Plc. |
| Others |
Cost & Logistics Intelligence
China's expansion of titanium sponge production capacity significantly influences global cost structures and where margin pools sit downstream. Vertically integrated aerospace specialists command premium margins due to stringent certification requirements and long-term agreements.
Pricing Analysis
Geographic price spreads reflect the divergence between high-specification aerospace demand and commoditized industrial-grade material. The dominant pricing model for aerospace is contract-based long-term offtake, while industrial-grade material often trades on a commodity spot market. Price differentiation stems from certification level (FAA/EASA), material quality grade, and after-sales qualification needs. Cost compression in industrial-grade material intensifies due to massive Chinese production capacity. Industrial-grade buyers exhibit high price sensitivity, whereas aerospace component manufacturers prioritize performance and certification.
Supply Chain Analysis
Single-source vulnerability for aerospace-grade sponge and mill products creates a structural supply chain risk. Geographic supply concentrates in China for industrial-grade sponge, Russia for aerospace-grade material, and Japan for high-purity sponge. The supply chain depends on titanium ore extraction and the energy-intensive Kroll process for primary metal production. Distribution for certified-grade material runs through long-term supply agreements with major aerospace original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The titanium market presents a defensive moat, anchored by significant regulatory entrenchment through stringent certification requirements. This structural advantage favors established producers with deep qualification histories.
For Market Incumbents:Entrench vertical integration into titanium sponge production and advanced alloy development to counter commodity price volatility. Secure long-term supply agreements with aerospace original equipment manufacturers, insulating against emerging composite substitution threats. Invest in digital twin technology to reduce qualification timelines and maintain a competitive edge in material innovation.
For New Entrants and Emerging Players:India's defense modernization and space exploration programs represent a significant underpenetrated market for specialized titanium alloys. Focus on additive manufacturing techniques for complex, lightweight components in medical implants and performance automotive parts. Develop partnerships with local manufacturers to navigate certification processes and access domestic supply chains effectively.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across upstream sponge and melting facilities, favoring established players with existing infrastructure. Long-term viability rests with companies possessing deep certification expertise and diversified end-market exposure. Target vertically integrated specialists with strong intellectual property in advanced alloys and additive manufacturing capabilities. The signal to watch is the pace of new alloy qualification by aerospace regulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Secures demand for certified aerospace-grade titanium and de-risks OEM supply chains. |
| Capacity Expansion | Addresses sustained demand for industrial-grade material in China's chemical processing sector. |
| Advanced Alloy Development | Creates high-performance materials for critical defense platforms and medical implants. |
| Additive Manufacturing Investment | Unlocks new design possibilities for complex, lightweight titanium components in diverse applications. |
| Recycling Technology Development | Supports circular economy mandates and provides a secondary, sustainable supply source. |
Research Approach
Initial hypotheses were tested against primary input from aerospace engineers, medical device manufacturers, chemical plant operators, and raw material suppliers, then refined. This involved deep-dive interviews combined with secondary validation from FAA and EASA certification documents, ISO 5832 standards, and national trade statistics. A bottom-up and top-down triangulation approach ensured robust market sizing and segmentation.
Demand-supply balance was modeled across the analysis window, considering production capacity and end-use consumption patterns. The analytical framework segmented the market by product type, grade, application, end-user, and regional regulatory environment. Forecasted CAGRs incorporated historical growth trends and anticipated shifts in aerospace build rates and industrial expansion. Key forecast inputs included commercial aircraft order backlogs and China's industrial investment plans.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new entrants or material innovators would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and sustained investment in key end-use sectors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Galvanized Steel Market
Metals
Aluminum Casting Market
Metals
High Magnetic Induction Grain-Oriented Silicon Steel Market
Metals
Gold Smelting Market
Metals
Global Oxygen-Free Copper Market
Metals
High Purity Iron Powder Market
Metals
Potassium Platinochloride Market
Metals
Electrodeposited Copper Foil Market
Metals
Osmium Market
Metals
Crude Steel Market
Metals
Nickel Powder Plating Market
Metals
Refined Nickel Market
Metals
North America Metal Casting Market
Metals
Aluminum Welding Market
Metals
Metallurgical Silicon Market
Metals
Global Wire Rods Market