
 Brown Fused Alumina Market | 2026-2036
Brown Fused Alumina Market Size, Share, and Industry Trends Forecast 2026-2036
Brown Fused Alumina Market Analysis
Market Context
Chinese smelter capacity is shifting toward higher-purity output as environmental compliance costs reshape the cost curve for brown fused alumina production. Henan Ruishi Renewable Resources Group leverages integrated bauxite sourcing to sustain cost advantages across refractory and abrasive grades. Saint-Gobain competes through specialized product lines targeting aerospace surface treatment applications. Washington Mills anchors North American supply with domestic fusion capabilities and tight quality control over metallurgical additive specifications.
Technical Definition and Segment Structure
Brown fused alumina is an artificial corundum produced by electric arc fusion of calcined bauxite at temperatures exceeding 2000°C, yielding a hardness of 9 on the Mohs scale and alumina content typically ranging from 95% to 97%. The material serves primarily as an abrasive grain for grinding wheels and coated abrasives, and as an aggregate in high-temperature refractory linings for steel ladles and cement kilns. Alumina abrasives dominate value capture due to established demand from automotive manufacturing and metal fabrication, while refractory materials represent the volume anchor tied to cyclical steel and cement capacity investments. Ceramic products and metallurgical additives occupy narrower margin pools where specification stringency and batch consistency command premium positioning.
Regulatory Frame and Outlook
China's MEE enforces emissions caps on fused alumina smelters through the dual carbon policy framework, while India's BIS certification requirements for refractory-grade imports create compliance barriers for non-standardized supply sources. REACH registration obligations in Europe restrict unregistered abrasive grain imports, channeling trade toward established producers with full substance dossiers. Stakeholders must monitor how carbon border adjustments and evolving national standards for refractory performance reshape sourcing economics and supplier qualification timelines.
Market Dynamics
China's dual carbon policy framework is forcing a structural recalibration of brown fused alumina smelter economics, compressing marginal capacity while elevating compliance costs for high-emission fusion operations. This regulatory pressure is redrawing the competitive map for refractory-grade supply.
Growth Catalysts
- Steel decarbonization mandates:European steelmakers under EU Green Deal carbon border adjustments are retrofitting blast furnaces with high-alumina refractory linings, pulling demand for premium-grade fused alumina aggregates.
- India's PLI scheme for abrasives:Domestic manufacturing incentives are accelerating local fusion capacity build-out, reducing import dependence for coated abrasive producers in Tamil Nadu and Gujarat clusters.
- Bauxite beneficiation advances:Pre-fusion calcination upgrades are expanding the addressable ore base, lowering feedstock costs for smelters operating on lower-grade diasporic bauxite deposits.
Market Restraints
- Petroleum coke price volatility:Carbon electrode costs for electric arc furnaces swing with crude oil derivatives, compressing smelter margins during energy price spikes.
- Henan supply concentration:Over 60% of Chinese fusion capacity clusters in a single province, exposing buyers to localized environmental enforcement actions and forced shutdowns.
- White fused alumina substitution:Higher-purity synthetic corundum variants are capturing aerospace surface-finishing applications where batch consistency requirements exceed brown alumina capabilities.
Strategic Opportunities
- Vietnam infrastructure build-out:Cement kiln capacity expansion along the Red River Delta is creating unmet demand for refractory-grade aggregates, with local supply chains still developing.
- Recycled abrasive reclamation:Closed-loop grinding swarf recovery systems are opening service-based revenue streams for distributors with sorting and re-fusion capabilities.
- MEE emissions trading integration:Early compliance with China's carbon market is positioning select smelters for tradable credit generation, offsetting abatement investments.
Industry Challenges
- Fusion technician scarcity:Electric arc furnace operation requires specialized thermal engineering expertise that aging workforces in traditional producing regions cannot replenish.
- REACH dossier maintenance:European abrasive importers face escalating registration costs for substance volume bands, squeezing mid-tier traders without captive fusion assets.
- Refractory lining specification divergence:Cement and steel end-users are fragmenting technical standards, forcing suppliers to maintain multiple product qualification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brown Fused Alumina Market |
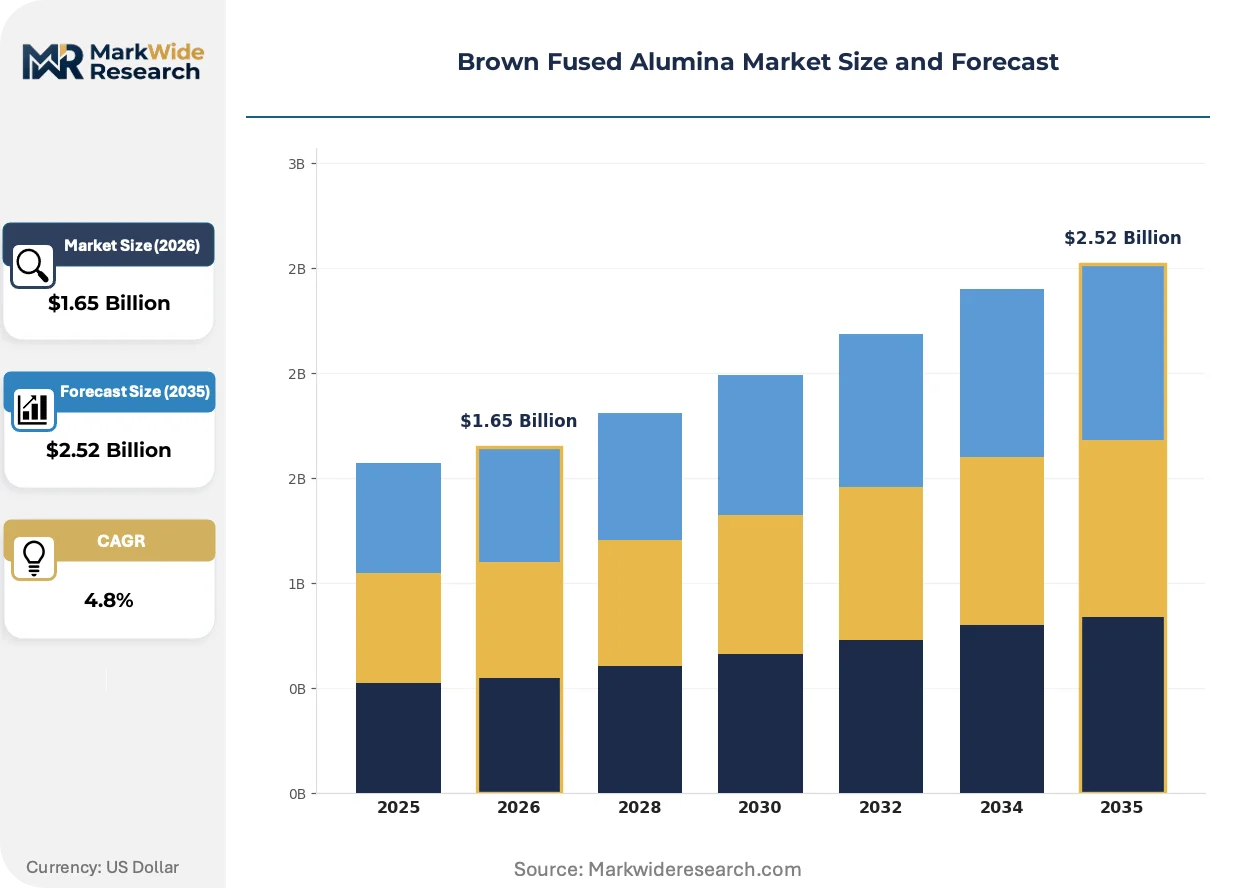
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina Abrasives, Refractory Materials, Ceramic Products, Metallurgical Additives End User: Aerospace, Automotive Manufacturing, Construction, Electrical Application: Grinding, Sandblasting, Surface Treatment, Coating Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Carborundum Universal Limited, Norton Abrasives, Saint-Gobain, Henan Ruishi Renewable Resources Group, Rusal, Imerys, Almatis, Sibelco, Washington Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brown Fused Alumina Market Emerging Trajectories
Digital process control and emissions monitoring systems are penetrating brown fused alumina production, compressing quality variance while enabling real-time compliance documentation for carbon-accounted supply chains.
Closed-loop water-cooling systems with AI-driven temperature modulation are rewriting energy efficiency benchmarks in electric arc fusion. Henan-based smelters adopting these retrofits report 12-18% electrode consumption reduction. The technology is compressing the cost gap between compliant and legacy operations, accelerating marginal capacity exit.
REACH authorization requirements for chromium-bearing refractory alternatives are tightening entry barriers for non-European abrasive suppliers. The regulation is redirecting trade flows toward registered producers with full substance dossiers. Coated abrasive manufacturers in Germany and Italy are consolidating supplier panels to reduce compliance audit burden.
Steel mills are compressing refractory procurement cycles from annual tenders to quarterly price negotiations, unbundling technical service from material supply. This behavior is disintermediating traditional distributor networks in favor of direct mill-to-smelter contracts. The shift is most visible in Indian integrated steel plants seeking inventory flexibility amid volatile alumina input costs.
Brown Fused Alumina Market Segmentation
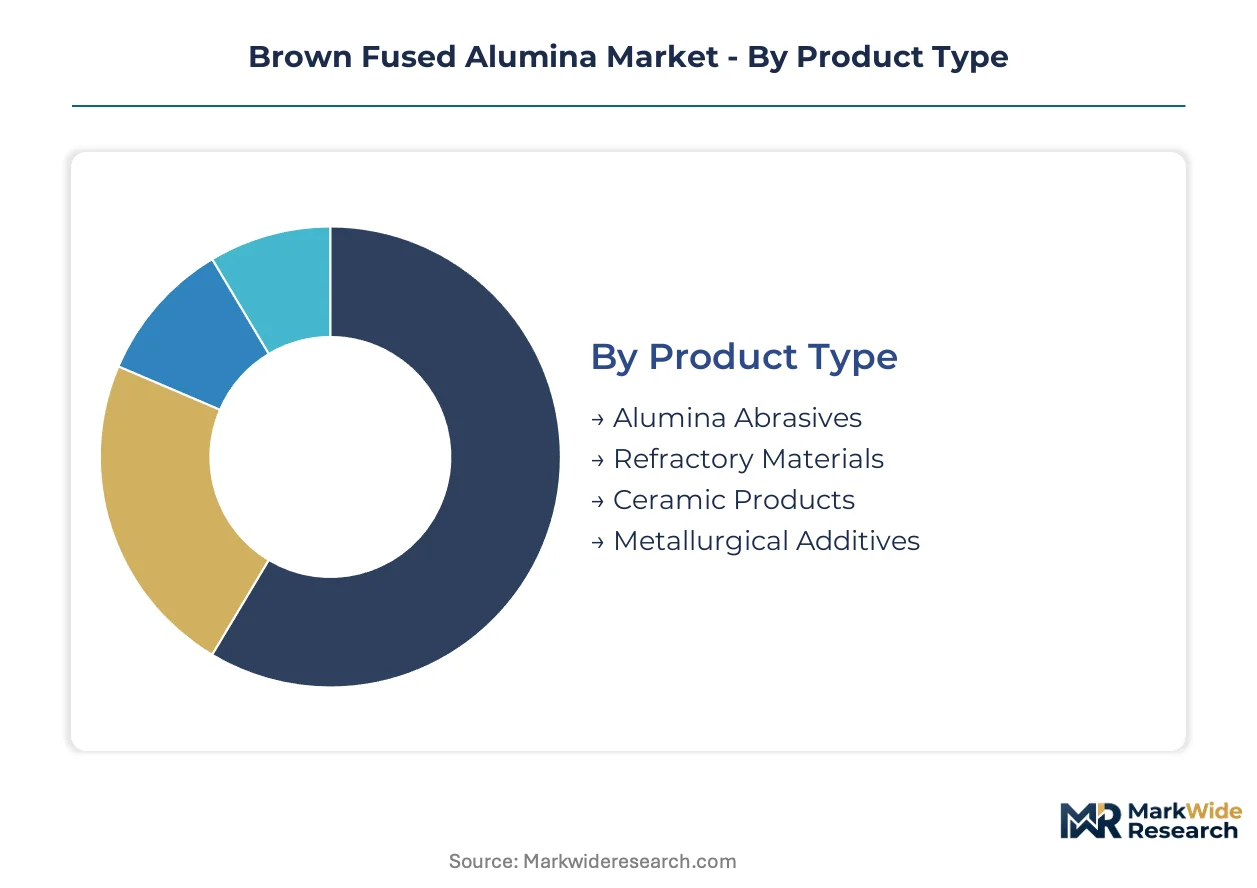
Segmentation in brown fused alumina reveals how capital intensity, specification stringency, and channel economics fragment value capture across the supply chain. Smelters must align furnace configuration and quality control systems with the technical requirements of each segment to optimize asset utilization.
Product Type:
Electric arc fusion capacity demands the heaviest upfront investment for segments requiring precise temperature control and batch consistency.
- Refractory Materials:Aggregates with 95-97% alumina content serve steel ladle linings and cement kiln bricks where thermal shock resistance determines performance. Demand concentrates in Indian integrated steel plants and Vietnamese cement kiln expansions along the Red River Delta, driven by infrastructure build-out and furnace retrofit cycles.
- Alumina Abrasives:Fused grains for grinding wheels and coated abrasives require controlled crystalline structure for hardness uniformity. Automotive manufacturing clusters in Tamil Nadu and Gujarat absorb volume through domestic abrasives producers qualifying under India's PLI scheme.
- Ceramic Products:High-purity grades for technical ceramics command premium positioning in specialized industrial applications.
- Metallurgical Additives:Lower-specification fused alumina functions as deoxidizing agents and slag conditioners in steel refining.
Refractory materials absorb the bulk of installed capacity; alumina abrasives is expanding most quickly.
End User:
Specification divergence across end-use industries forces smelters to maintain parallel qualification tracks for aerospace batch consistency versus construction volume throughput.
- Automotive Manufacturing:Metal fabrication and surface finishing operations consume coated abrasives for body panel preparation and component deburring. Production lines in Germany and Italy consolidate supplier panels to reduce REACH compliance audit burden.
- Aerospace:Surface treatment applications demand exceptional batch consistency for turbine blade finishing and airframe preparation. European steelmakers under EU Green Deal carbon border adjustments are retrofitting blast furnaces, indirectly pulling premium-grade aggregate demand through refractory supply chains.
- Construction:Cement kiln refractory linings and abrasive applications for building materials processing.
- Electrical:Insulating components and substrate materials for electronic applications.
Automotive manufacturing commands the largest volume commitment; aerospace maintains the steepest expansion trajectory.
Application:
Process intensity varies dramatically, with grinding operations requiring the most sophisticated grain morphology control.
- Grinding:Precision abrasive grains for bonded and coated grinding wheels demand tight particle size distribution and friability control. Closed-loop grinding swarf recovery systems are opening service-based revenue streams for distributors with sorting capabilities.
- Surface Treatment:Aerospace and automotive finishing operations require consistent abrasive performance for automated blasting systems.
- Sandblasting:General industrial surface preparation and cleaning applications.
- Coating:Substrate preparation and functional coating applications.
Grinding anchors volume absorption; surface treatment is gaining share fastest.
Distribution Channel:
Channel selection determines working capital intensity and technical service bundling requirements.
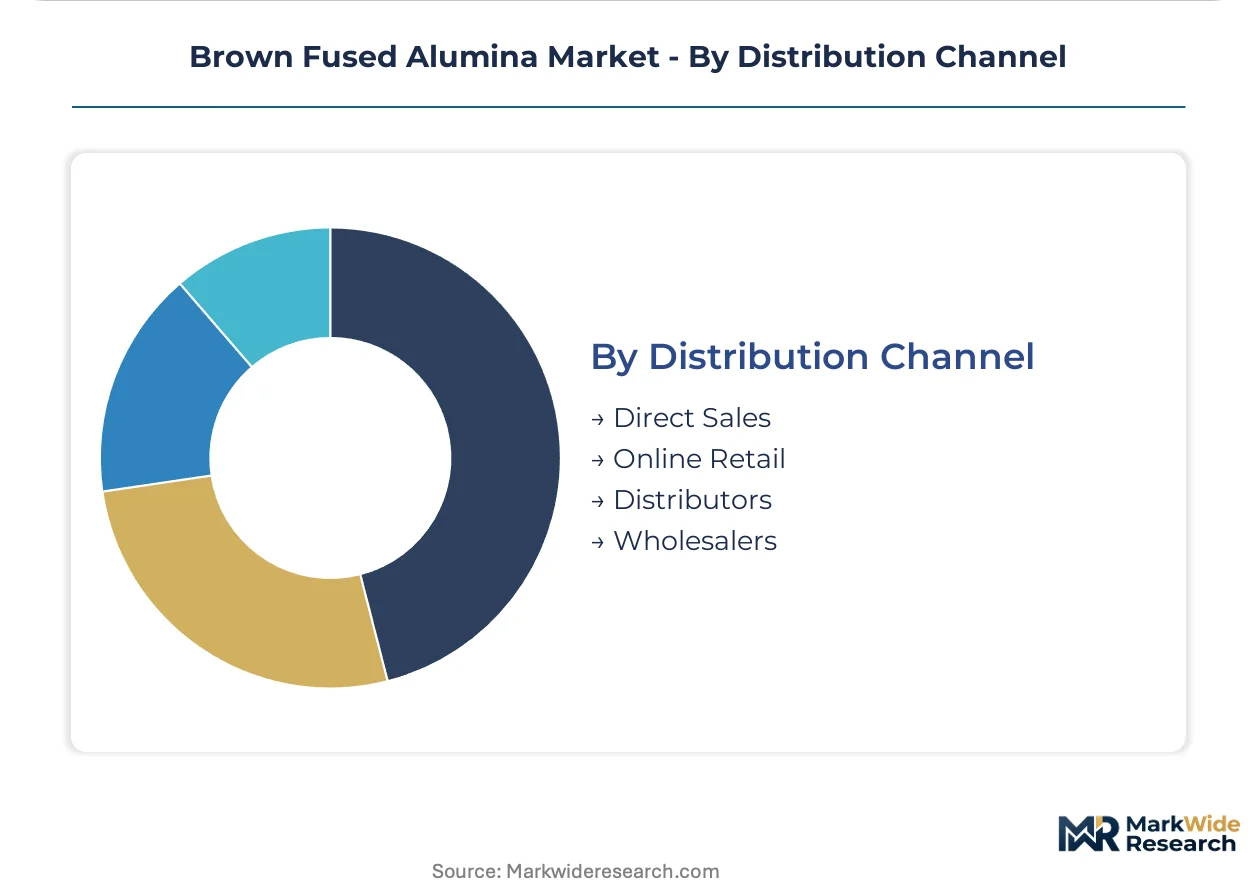
- Direct Sales:Mill-to-smelter contracts are displacing traditional distributor networks as Indian steel plants compress procurement cycles from annual to quarterly negotiations. This shift unbundles technical service from material supply.
- Distributors:Traditional networks face margin compression but retain value in fragmented customer bases requiring inventory flexibility.
- Wholesalers:Volume aggregation for standardized grades serving smaller industrial consumers.
- Online Retail:Emerging channel for standardized abrasive products and small-lot procurement.
Direct sales captures the largest transaction value; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite deposits in Henan Province anchor Chinese brown fused alumina production, while refractory demand concentrates in Indian steel corridors and Vietnamese cement belts.
China
Steel ladle relining cycles and cement kiln retrofits absorb refractory-grade aggregates from Henan smelters. MEE emissions trading integration forces marginal capacity exit while rewarding early compliance investments. Zhengzhou fusion clusters report 12-18% electrode consumption reductions through AI-driven cooling retrofits.
India
Tamil Nadu and Gujarat abrasives manufacturers scale coated abrasive output under PLI scheme incentives. BIS certification requirements for refractory-grade imports filter non-standardized supply sources. Integrated steel plants in Odisha and Jharkhand compress procurement cycles from annual to quarterly negotiations.
United States
Automotive metal fabrication clusters in Michigan and Ohio sustain bonded abrasive grain consumption. EPA emissions standards for electric arc furnace operations elevate compliance costs for domestic fusion capacity. Washington Mills anchors North American supply with captive fusion assets and metallurgical additive specifications.
Germany
EU Green Deal carbon border adjustments push steelmakers toward high-alumina refractory linings for blast furnace retrofits. REACH registration obligations channel abrasive grain trade toward dossier-compliant producers. Stuttgart and Munich automotive finishing operations consolidate supplier panels to reduce compliance audit burden.
Vietnam
Cement kiln capacity expansion along the Red River Delta creates unmet demand for refractory-grade aggregates. Local supply chains remain underdeveloped, opening import windows for standardized Chinese and Indian material. Hai Phong port infrastructure supports bulk aggregate handling for northern cement producers.
Brown Fused Alumina Market Vendor Landscape
Global majors compete with regional champions across feedstock access and emissions compliance capabilities. The vendor base stratifies into three tiers: integrated bauxite-to-fusion operators, specialized abrasive grain producers, and trading-focused distributors without captive smelting assets. Strategic moves concentrate on backward integration into bauxite beneficiation and M&A targeting REACH-registered European abrasive suppliers.
Within the integrated feedstock tier, Henan Ruishi Renewable Resources Group exemplifies Chinese operators leveraging captive bauxite sourcing to sustain cost advantages. Saint-Gobain occupies a position representing European majors competing through specialized product lines and full regulatory dossiers. Washington Mills anchors North American supply with domestic fusion capabilities and quality control systems for metallurgical specifications.
| Leading Market Players |
|---|
| Carborundum Universal Limited |
| Norton Abrasives |
| Saint-Gobain |
| Henan Ruishi Renewable Resources Group |
| Rusal |
| Imerys |
| Almatis |
| Sibelco |
| Washington Mills |
| Others |
Supply Flow & Price Mechanics
Fusion technician scarcity in Henan Province compresses labor-cost differentials between premium-grade and standard-grade brown fused alumina, widening pricing-tier spreads as smelters pass specialized workforce premiums through to aerospace and automotive buyers.
Pricing Analysis
Technical service bundling once anchored long-term contracts between Indian steel mills and Henan smelters; quarterly procurement cycles now unbundle these services, compressing margins for distributors without captive fusion assets. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered aerospace grades from construction-grade aggregates and metallurgical additives. Pricing pressure stems from petroleum coke volatility feeding carbon electrode costs, with spot-market buyers in Vietnam cement corridors showing highest price sensitivity versus long-term offtake agreements from European refractory specifiers.
Supply Chain Analysis
Specialized thermal engineering expertise for electric arc furnace operation concentrates in aging workforces across Henan and Zhengzhou clusters, constraining capacity expansion despite demand pull from Indian steel corridors. Raw material flows draw from calcined bauxite deposits in Henan Province, petroleum coke derivatives for carbon electrodes, and alumina feedstock from integrated beneficiation operations. Single-source vulnerability concentrates in Henan Province where over sixty percent of Chinese fusion capacity faces localized MEE environmental enforcement actions. Distribution runs through direct mill-to-smelter contracts displacing traditional distributor networks in Indian integrated steel plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brown fused alumina production is transitioning from legacy electric arc fusion toward AI-driven temperature modulation systems that reduce electrode consumption and enable real-time emissions compliance documentation.
For Market Incumbents: Cement cost advantages through backward integration into bauxite beneficiation and captive calcination capacity, insulating margin structures from petroleum coke volatility. Invest in REACH dossier maintenance and MEE emissions trading integration to defend positioning against white fused alumina substitution in aerospace surface-finishing applications where batch consistency requirements are tightening. For New Entrants and Emerging Players: Enter via Vietnam's Red River Delta cement kiln expansions where local supply chains remain underdeveloped and import windows for standardized refractory-grade aggregates are widening. Target recycled abrasive reclamation services requiring lower capital intensity than greenfield fusion capacity, leveraging closed-loop grinding swarf recovery systems to capture service-based revenue streams from fragmented automotive metal fabrication clusters. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-registered European abrasive specialists given EU Green Deal carbon border adjustments redirecting trade flows toward dossier-compliant producers. Long-term viability favors integrated bauxite-to-fusion operators with MEE compliance positioning and AI-driven cooling retrofits already deployed. Watch for forced shutdowns in Henan Province as inflection indicators for supply-constraint-driven pricing resets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Beneficiation | Henan smelters with captive ore sourcing sustain cost advantages against feedstock volatility. |
| AI-Driven Cooling System Retrofit | Zhengzhou fusion clusters report electrode consumption reductions through temperature modulation. |
| REACH Dossier Investment | Registered producers capture redirected trade flows as authorization requirements tighten. |
| Recycled Abrasive Reclamation Service | Distributors with sorting capabilities open revenue streams from closed-loop swarf recovery. |
| Direct Mill-to-Smelter Contracting | Indian steel plants compress procurement cycles from annual to quarterly negotiations. |
Methodological Framework
Trade databases, MEE emissions filings, and BIS certification records formed the secondary backbone, cross-referenced with primary interviews involving fusion plant managers, refractory procurement leads at Indian integrated steel plants, abrasive grain distributors in Tamil Nadu and Gujarat, and technical R&D directors at European coated abrasive manufacturers. Bottom-up and top-down triangulation validated production capacity estimates against customs data for bauxite and calcined alumina flows.
Bottom-up modeling built volume projections from individual smelter capacity utilization, grade-mix assumptions, and end-use demand curves across steel ladle relining cycles and cement kiln retrofits. Segmentation dimensions included product type, end-user industry, application process intensity, and distribution channel structure. CAGRs were derived from slope analysis of annual demand increments against capacity expansion timelines, incorporating petroleum coke price elasticity and MEE compliance cost curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement actions or sustained petroleum coke price spikes. Material deviation in Chinese environmental policy stringency or Indian PLI scheme extension timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics & Fibers
Feldspar Market
Ceramics & Fibers
Melamine Pyrophosphate Market
Ceramics & Fibers
Global Fireclay Tiles Market
Ceramics & Fibers
Global Ceramic Fiber Paper Market
Ceramics & Fibers
Zabuyelite Market
Ceramics & Fibers
Hollow Fiber Ceramic Membrane Market
Ceramics & Fibers
Fly Ash Microspheres Market
Ceramics & Fibers
Global Zircon Sand Market
Ceramics & Fibers
Silicon Carbide Fiber Market
Ceramics & Fibers
Rutile Market
Ceramics & Fibers
Ceramic Matrix Composites Market
Ceramics & Fibers
Synthetic Quartz Market
Ceramics & Fibers
Fluorite Pellets Market
Ceramics & Fibers
Global Rice Husk Ash Market