
 Base Metals Market | 2026-2036
Base Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Base Metals Market Analysis
Geologist and metallurgical engineer shortages across major mining jurisdictions are unwinding project timelines and forcing capital discipline. BHP Group leverages its Olympic Dam polymetallic complex to sustain copper concentrate output despite labor tightness in South Australia. Rio Tinto anchors its growth profile through the Oyu Tolgoi underground expansion in Mongolia, while Glencore competes by controlling a diversified trading and mining footprint that spans zinc, nickel, and copper assets.
Base metals comprise non-ferrous metallic elements—principally copper, aluminum, nickel, and zinc—typically extracted from sulfide or oxide ores and refined to purity thresholds exceeding 99% for industrial use. These metals conduct electricity, resist corrosion, and form alloys, serving as irreplaceable inputs for power transmission, construction framing, battery cathodes, and galvanized steel coatings. Aluminum sheets and rods dominate volume flows due to their lightweight properties in transportation applications, while high-grade copper wires command premium positioning amid electrification trends. Recycled grade volumes are expanding fastest as scrap collection infrastructure matures and smelters blend secondary feedstock to lower carbon intensity.
EPA emissions standards in the United States, REACH chemical registration requirements in Europe, and China's MEE environmental compliance audits are tightening allowable sulfur dioxide and particulate thresholds for smelter operations. These frameworks raise capital costs for new capacity while advantaging producers with existing emission control investments or hydrometallurgical routes. Stakeholders must monitor regulatory divergence between jurisdictions, as carbon border adjustments and traceability mandates will increasingly determine which metal units clear customs and which face exclusion.
Market Dynamics
China's dual carbon goals are forcing smelters to retrofit facilities or face output caps, while Indonesia's nickel processing corridor concentrates supply and hydrometallurgical routes displace pyrometallurgical methods. This dual pressure—regulatory compliance and process transition—defines current competitive positioning across copper, nickel, and aluminum value chains.
Growth Catalysts
- EPA emissions standards:Tightening sulfur dioxide thresholds in the United States are accelerating capital deployment into emission control retrofits, advantaging producers with existing scrubber infrastructure.
- Electric vehicle battery chemistries:Higher nickel content cathodes are pulling procurement volumes toward Indonesia's processing corridor and away from traditional cobalt-dominant supply chains.
- Scrap collection infrastructure:Mature secondary feedstock networks allow smelters to blend recycled grades, lowering carbon intensity per ton and qualifying output for EU carbon border adjustments.
Market Restraints
- Geologist and metallurgical engineer shortages:Labor tightness across South Australia and Mongolia is unwinding project timelines and forcing capital discipline on brownfield expansions.
- Power transmission grade copper:High-purity cathode production remains concentrated among integrated miners with captive concentrate supply, limiting new entrant participation.
- Pyrometallurgical route lock-in:Existing smelter fleets face stranded asset risk as hydrometallurgical refineries achieve lower opex and compliance costs in Indonesia.
Strategic Opportunities
- India's construction and automotive fabrication:Underpenetrated galvanized steel coating demand offers white space for zinc alloy producers as infrastructure spending accelerates.
- EU Green Deal traceability mandates:Carbon border adjustments will increasingly determine which metal units clear customs, advantaging producers with verified low-carbon production routes.
- Battery cathode-to-recycling convergence:Closed-loop nickel and cobalt recovery from end-of-life EV batteries creates new feedstock channels independent of mined supply.
Industry Challenges
- Underground expansion execution:Block cave mining complexity at depth requires specialized contractor capabilities that concentrate among a narrow pool of engineering firms.
- REACH chemical registration timelines:European alloy additive compliance is extending product qualification cycles and freezing formulation changes mid-development.
- Legacy ERP integration with traceability platforms:Smelters struggle to graft blockchain-based provenance tracking onto decades-old production accounting systems without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Base Metals Market |
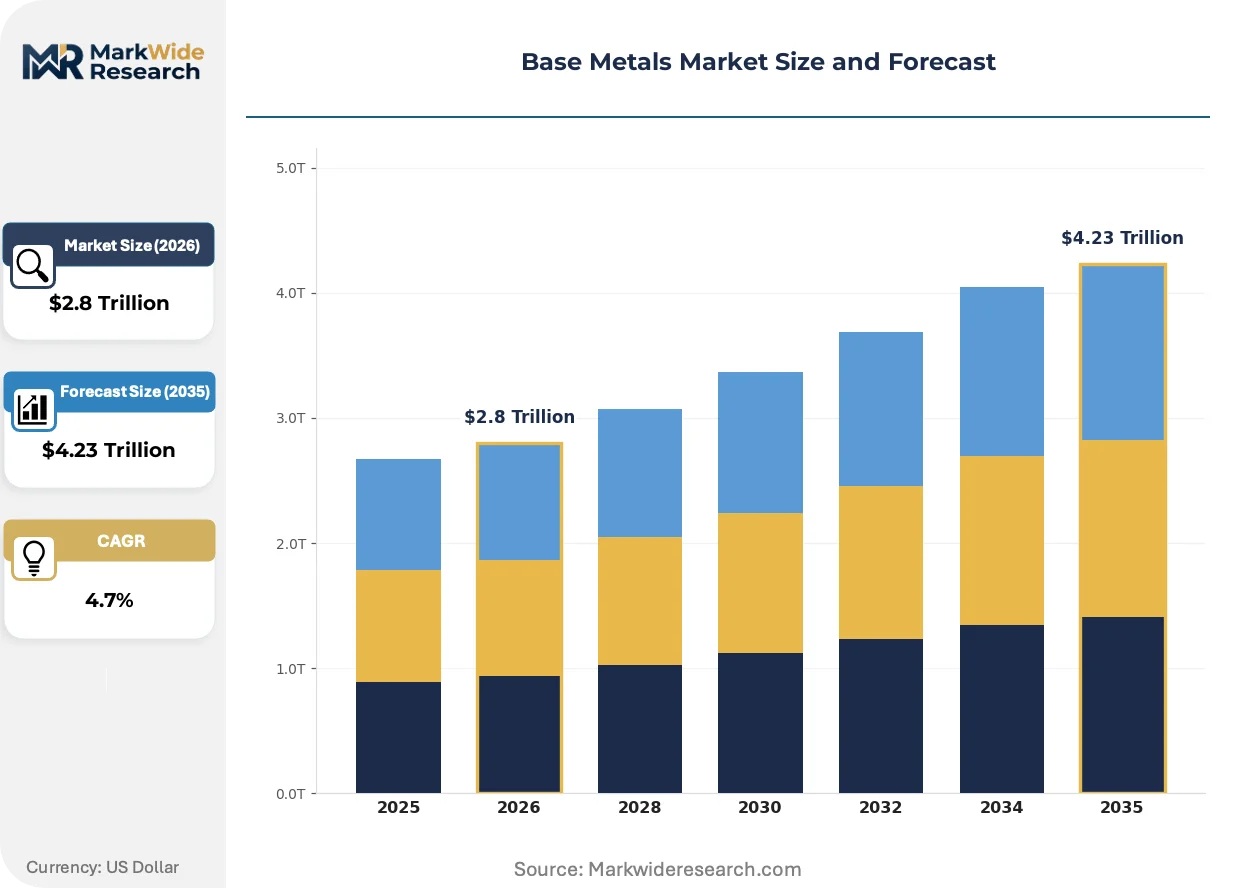
| Market Size in 2026 | $2.8 Trillion |
| Market Size in 2035 | $4.23 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper, Aluminum, Nickel, Zinc End Use Industry: Construction, Transportation, Electronics, Manufacturing Form: Ingots, Sheets, Rods, Wires Grade: High-Grade, Low-Grade, Recycled, Alloy |
| Companies Covered | BHP Group, Rio Tinto, Glencore, Vale S.A., Freeport-McMoRan Inc., China Molybdenum Co., Ltd., Southern Copper Corporation, Corporación Nacional del Cobre de Chile, First Quantum Minerals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Base Metals Market Emerging Trajectories
Process metallurgy and emissions compliance are converging to redefine competitive advantage. Producers now compete on carbon intensity per ton rather than grade alone, while digital traceability layers reshape how metal units qualify for premium market access.
Hydrometallurgical pressure leaching is decomposing the traditional roast-smelt-refine sequence for nickel laterites. Battery cathode manufacturers are qualifying hydrometallurgical mixed hydroxide precipitate at accelerated pace, compressing the payback period for refinery conversions and marginalizing pyrometallurgical ferronickel output from older facilities.
REACH chemical registration requirements in Europe are tightening substance authorization for process reagents used in sulfide ore flotation. Industrial consequence includes reformulation of collector chemicals and frothers across concentrator circuits, with high-purity copper and zinc producers most affected as they pursue EU market access for battery and electronics grades.
Long-term offtake contracting is fragmenting as battery makers pursue direct mine-to-cathode partnerships that bypass traditional merchant trading houses. Spot market liquidity is thinning for standard-grade cathodes while premium-grade units with verified carbon footprints command dedicated bilateral supply agreements, with this pattern most visible in European and North American EV supply chain procurement.
Base Metals Market Segmentation
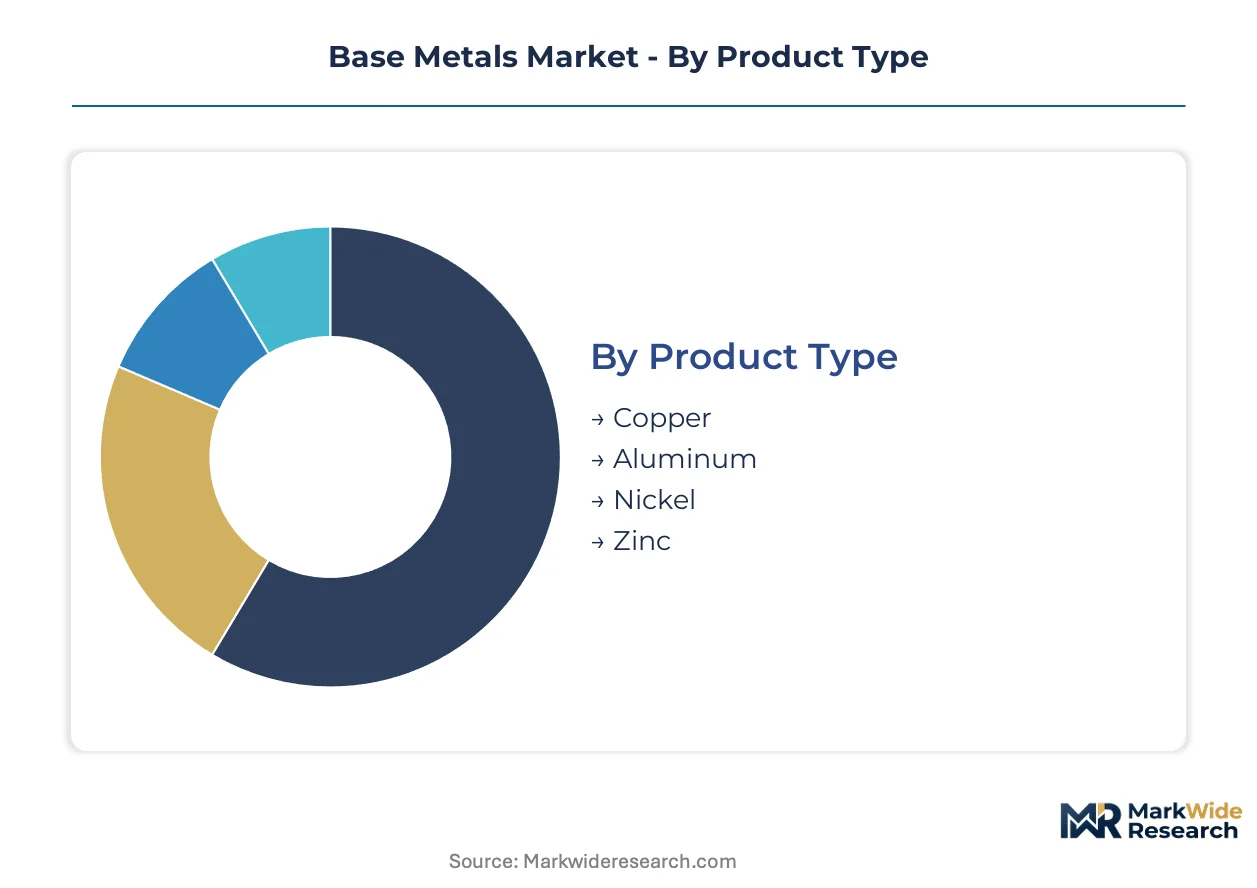
Base metals segmentation reveals how margin pools concentrate in high-purity grades and specialized forms serving electrification and lightweighting applications. Product type and grade classifications increasingly determine access to premium offtake channels, particularly as carbon border adjustments reshape procurement criteria across battery and automotive supply chains.
Product Type:
Margin pools concentrate in copper and nickel as electrification demand outpaces traditional construction-grade aluminum and zinc, though lightweighting applications sustain aluminum volume leadership.
- Copper:High-conductivity cathode with purity thresholds exceeding 99.99% serves power transmission and EV motor windings. Demand concentrates in renewable energy interconnectors and charging infrastructure across Germany, the United States, and China as grid modernization accelerates.
- Nickel:Class 1 cathode and mixed hydroxide precipitate feed battery cathode manufacturing with nickel content rising in NMC and NCA chemistries. Procurement is rotating toward Indonesia's hydrometallurgical processing corridor as pyrometallurgical ferronickel loses qualification for battery-grade supply.
- Aluminum:Lightweight structural metal dominates by volume in transportation framing and packaging. Primary smelters with captive renewable power in Iceland, Norway, and Quebec capture premium positioning for EU carbon border adjustment compliance.
- Zinc:Galvanizing-grade metal provides corrosion protection for steel in construction and automotive applications. Galvanized coating demand in India's infrastructure build-out offers white space expansion as domestic smelter capacity lags consumption growth.
Copper holds installed capacity concentration among integrated miners with captive concentrate supply. Nickel is rotating up the share rankings as battery chemistry evolution pulls procurement volumes from cobalt-dominant supply chains.
End Use Industry:
Application-driven segmentation shows transportation and electronics commanding premium pricing power as electrification and miniaturization requirements tighten material specifications.
- Construction:Structural framing, roofing, and galvanized steel coatings absorb standard-grade aluminum and zinc in volume. China's property sector correction and India's infrastructure acceleration create divergent regional demand trajectories.
- Transportation:EV battery cathodes, motor windings, and lightweight body panels require high-purity copper, nickel, and aluminum grades. Automotive OEMs in Germany, Japan, and South Korea are qualifying suppliers through direct mine-to-cathode partnerships that bypass traditional merchant channels.
- Electronics:High-conductivity copper wire and foil serve printed circuit boards, semiconductors, and data center power distribution. Taiwan and South Korea fabrication clusters drive specification tightening for oxygen-free copper grades.
- Manufacturing:Industrial machinery, consumer appliances, and packaging applications consume standard-grade aluminum sheets and zinc coatings. Mature scrap collection networks in the United States and Europe enable secondary feedstock blending that lowers carbon intensity per ton.
Construction holds installed demand volume across mature economies. Transportation is climbing the fastest as EV penetration rates accelerate cathode material procurement.
Form:
Physical form determines downstream processing economics and logistics cost structures, with continuous cast shapes and precision-drawn products capturing value-add premiums.
- Ingots:Primary cast shapes serve remelting and alloying operations for secondary fabrication. Smelters in Indonesia, China, and Russia dominate ingot trade flows as intermediate feedstock for regional rolling and drawing facilities.
- Sheets:Rolled flat products supply automotive body panels, construction cladding, and appliance housings. Aluminum sheet demand from Tesla, BYD, and European OEMs is expanding most quickly as vehicle lightweighting targets tighten.
- Rods:Continuous cast and extruded round products feed wire drawing, forging, and machining operations. Copper rod mills in the United States and Germany concentrate capacity to serve regional cable and magnet wire manufacturers.
- Wires:Drawn products with precise dimensional tolerances serve electrical conductors, welding electrodes, and steel reinforcement. High-purity copper wire for EV motor windings commands dedicated bilateral supply agreements with verified carbon footprints.
Ingots hold installed capacity as the dominant intermediate trade form. Sheets are gaining share fastest as automotive aluminum penetration accelerates beyond historical levels.
Grade:
Grade stratification increasingly separates premium market access from commodity pricing, as carbon intensity certification and traceability mandates reshape procurement qualification.
- High-Grade:Purity thresholds exceeding 99.9% for copper and 99.8% for nickel serve battery cathodes, semiconductors, and power transmission. LME-registered cathode producers with integrated mine-to-metal operations in Chile, Peru, and Indonesia control qualification bottlenecks.
- Low-Grade:Standard commercial purity metals serve construction, packaging, and general industrial applications. Chinese smelter output dominates this tier as capacity rationalization lags environmental compliance cost escalation.
- Recycled:Secondary feedstock refined from scrap collection networks lowers carbon intensity per ton and qualifies for EU carbon border adjustments. Mature scrap infrastructure in the United States, Germany, and Japan enables smelter blending ratios rising toward operational limits.
- Alloy:Engineered compositions combining base metals with controlled additive elements serve specialized mechanical, corrosion, or electrical properties. Brass and bronze producers face REACH chemical registration timelines in Europe that extend product qualification cycles.
High-Grade holds installed capacity concentration among integrated producers with captive concentrate supply. Recycled is expanding most quickly as scrap collection infrastructure matures and carbon border adjustments reward verified low-carbon production routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper consumption tilts toward power transmission in Germany and charging infrastructure in the United States, while nickel demand concentrates in battery cathode fabrication across South Korea and Japan. This geographic divergence in end-use mix shapes smelter investment patterns and regulatory compliance priorities.
China
Dual carbon goals are forcing smelters in Jiangxi and Shandong provinces to retrofit sulfur dioxide scrubbers or accept output caps from MEE audits. Battery cathode manufacturers in the Yangtze River Delta are locking long-term offtake with Indonesian nickel processors to secure Class 1 cathode supply. Hydrometallurgical pressure leaching investments in the processing corridor are displacing pyrometallurgical routes as compliance costs escalate.
United States
EPA emissions standards are accelerating capital deployment into scrubber retrofits at legacy smelters in Arizona and New Mexico. Power transmission grade copper demand concentrates in Texas and California grid modernization projects. Rod mills in the Midwest are blending rising ratios of secondary feedstock to qualify output for carbon-conscious procurement from EV manufacturers.
Germany
EU Green Deal traceability mandates are reshaping which metal units clear customs at Hamburg and Rotterdam ports. REACH chemical registration timelines are extending qualification cycles for brass and bronze alloy producers in the Ruhr industrial cluster. High-purity copper cathode from integrated Chilean and Peruvian miners commands dedicated bilateral agreements with automotive OEMs in Bavaria.
Indonesia
Hydrometallurgical refineries in the Sulawesi and Halmahera processing corridor are achieving lower opex and compliance costs than pyrometallurgical competitors. MHP output is qualifying for battery cathode manufacturing at accelerated pace, compressing payback periods for refinery conversions. Chinese and South Korean capital is concentrating in this corridor to secure nickel units outside traditional cobalt-dominant supply chains.
India
Galvanized steel coating demand in Maharashtra and Gujarat infrastructure projects offers white space expansion as domestic zinc smelter capacity lags consumption growth. BIS standards are tightening purity thresholds for electrical-grade copper imports from Chile and Peru. Construction-grade aluminum fabrication clusters in Tamil Nadu are expanding sheet and extrusion capacity to serve automotive lightweighting targets.
Base Metals Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that trades concentrate and refined metal through merchant channels. The upper tier controls captive mine-to-smelter infrastructure that qualifies for premium cathode offtake, while specialists arbitrage grade differentials and logistics spreads. Three archetypes dominate: diversified mining conglomerates with polymetallic complexes, pure-play copper or nickel developers with single-asset concentration, and trading houses with asset-backed logistics networks. Competitive moves center on brownfield capacity expansions and direct cathode partnerships that bypass traditional merchant markets.
Among diversified mining conglomerates, BHP Group and Rio Tinto exemplify the integrated archetype with polymetallic asset portfolios spanning copper, nickel, and zinc. Glencore occupies a distinct position as a trading-integrated operator with logistics networks that complement mining assets. Vale S.A. represents the large-scale Brazilian producer archetype with significant nickel exposure to battery supply chains.
| Leading Market Players |
|---|
| BHP Group |
| Rio Tinto |
| Glencore |
| Vale S.A. |
| Freeport-McMoRan Inc. |
| China Molybdenum Co., Ltd. |
| Southern Copper Corporation |
| Corporación Nacional del Cobre de Chile |
| First Quantum Minerals Ltd. |
| Others |
Supply Flow & Price Mechanics
Ninety-day concentrate inventory cycles at Chilean and Peruvian mine sites concentrate pricing power among integrated producers with captive smelter networks, while spot market liquidity thins for standard-grade cathodes. This lead-time compression rewards producers with verified low-carbon production routes that qualify for EU carbon border adjustments and dedicated bilateral EV supply agreements.
Pricing Analysis
Long-term offtake contracting fragments as battery makers pursue direct mine-to-cathode partnerships that bypass traditional merchant trading houses. Three-tier pricing structure across premium LME-registered cathode, standard commercial purity, and recycled-grade metal separates producers by carbon intensity certification and traceability compliance. Cost compression in standard-grade Chinese smelter output intensifies because MEE environmental audits force retrofit investments or output caps. Automotive OEMs in Germany and South Korea show least price sensitivity for high-purity copper and Class 1 nickel with verified carbon footprints, while construction-grade aluminum buyers in India remain most price-sensitive.
Supply Chain Analysis
Port congestion at Jakarta and Surabaya elevates inbound logistics costs for nickel laterite feedstock moving into Sulawesi hydrometallurgical refineries. Supply concentrates in Indonesia for nickel processing, Chile and Peru for copper concentrate, and China for aluminum smelting. Raw material flows draw from sulfide and oxide ore deposits, sulfuric acid for pressure leaching circuits, and petroleum coke for anode production. Single-source vulnerability concentrates in Indonesia's nickel processing corridor where Chinese and South Korean capital dominates refinery ownership. Distribution runs through LME warehouse networks in Rotterdam, Singapore, and New Orleans for cathode trade, with direct rail and barge links serving regional rod mills and rolling facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base metals markets face high-growth disruption as battery chemistry evolution toward higher nickel content restructures procurement patterns and marginalizes legacy pyrometallurgical capacity. EPA emissions standards and EU carbon border adjustments accelerate this inflection by advantaging producers with low-carbon production routes and verified traceability systems.
For Market Incumbents: Consolidate control over captive concentrate supply and hydrometallurgical processing capacity to defend against stranded asset risk from pyrometallurgical route lock-in. BHP Group and Rio T demonstrate this through Olympic Dam polymetallic complex optimization and Oyu Tolgoi underground expansion execution. Prioritize brownfield capacity additions in Indonesia's processing corridor and Quebec renewable-powered aluminum smelting to capture EU Green Deal traceability premiums. For New Entrants and Emerging Players: Anchor in India's galvanized steel coating demand white space as infrastructure spending accelerates and domestic zinc smelter capacity lags consumption growth in Maharashtra and Gujarat. Target battery cathode-to-recycling convergence for closed-loop nickel and cobalt recovery from end-of-life EV batteries, creating feedstock channels independent of mined supply. Pursue direct qualification partnerships with South Korean and Japanese cathode manufacturers seeking non-Indonesian nickel units. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-intensity-arbitrage play because regulatory divergence between jurisdictions will increasingly determine which metal units clear customs and command premium pricing. Acquisition targets should emphasize integrated miners with captive concentrate supply and existing emission control investments, or hydrometallurgical specialists with Indonesia processing corridor presence. Watch for accelerated MHP qualification timelines at battery cathode manufacturers as the inflection signal indicating payback period compression for refinery conversions.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrometallurgical Refinery Conversion | Indonesian MHP output qualifies for battery cathode manufacturing at accelerated pace, compressing payback periods. |
| Direct Mine-to-Cathode Partnership | Automotive OEMs in Germany and South Korea bypass traditional merchant channels for verified low-carbon supply. |
| Scrap Collection Infrastructure Expansion | Mature secondary feedstock networks in the United States and Germany enable smelter blending ratios rising toward operational limits. |
| Emission Control Retrofit Deployment | EPA standards accelerate capital deployment into scrubber infrastructure at legacy smelters in Arizona and New Mexico. |
| Renewable-Powered Smelting Capacity | Primary aluminum smelters in Iceland, Norway, and Quebec capture premium positioning for EU carbon border adjustment compliance. |
Methodological Framework
Desk research of customs and trade flow databases, SEC 10-K filings, and LME warehouse stock reports preceded structured interviews with mine planning engineers, smelter operations managers, battery cathode procurement leads, and commodity trading desk heads. Secondary validation drew from national geological surveys, environmental regulatory filings with EPA and MEE, and industry association technical publications. Bottom-up concentrate supply modeling triangulated against top-down end-use demand aggregation across construction, transportation, electronics, and manufacturing sectors.
Variance decomposition across product type, grade tier, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume and value trajectories. Forecast inputs incorporated EV penetration rate assumptions, grid modernization investment pipelines, and smelter capacity rationalization schedules under tightening emissions standards.
Decision-makers should treat outputs as directional under base assumptions of sustained electrification demand, continued Indonesian nickel processing corridor expansion, and progressive EU carbon border adjustment implementation; material deviation in battery chemistry evolution or regulatory enforcement intensity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Steel Sheet for Home Appliances Market
Metals
Cold Drawn Wire Market
Metals
GCC Aluminium Powder Market
Metals
Neodymium Market
Metals
Rubidium Market
Metals
High Purity Aluminium Market
Metals
Iron Ore Market
Metals
Aluminum Extrusion Market
Metals
Asia-Pacific Metallurgical Grade Fluorspar Market
Metals
North America Electrical Steel Market
Metals
Ferro Vanadium Market
Metals
Europe Aluminum Extrusion Market
Metals
Aluminium Rolled Products Market
Metals
India Special Steel Market
Metals
Copper Clad Aluminum Wire Market
Metals
Beryllium Copper for Industrial Equipment Market