
 316 Stainless Steel Container Market | 2026-2036
316 Stainless Steel Container Market Size, Share, and Industry Trends Forecast 2026-2036
316 Stainless Steel Container Market Outlook
REACH compliance is repositioning the cost-of-entry calculus for European suppliers of pharmaceutical-grade vessels. Thielmann leverages captive forging capacity to sustain margin control across its drum and intermediate bulk container lines. Eagle Stainless specializes in electropolished bottles for bioprocessing applications, while ArcelorMittal anchors raw material supply through integrated stainless melt shops in Belgium and Brazil.
316 stainless steel containers are fabricated from austenitic chromium-nickel-molybdenum alloy containing 2-3% molybdenum by weight, delivering superior chloride corrosion resistance for sterile and aggressive chemical environments. The alloy's 16-18% chromium content forms a passive oxide layer that withstands repeated sanitization cycles in pharmaceutical cleanrooms. Drums and intermediate-capacity vessels dominate the product type landscape due to their centrality in chemical and food ingredient logistics. The pharmaceutical end use segment commands premium positioning as batch integrity requirements harden across FDA and EMA jurisdictions.
FDA 21 CFR Part 211, EMA GMP Annex 1, and ISO 15378 collectively dictate surface finish, material traceability, and cleaning validation protocols for primary packaging and process vessels. These frameworks compel container manufacturers to maintain lot-certified mill test reports and electropolish documentation for audit readiness. Stakeholders must monitor evolving EMA guidance on single-use versus reusable containment systems as sustainability pressures intersect with sterility assurance requirements.
Market Dynamics
EMA's sterile manufacturing mandates are compressing upgrade cycles for pharmaceutical-grade vessels, forcing container fabricators to certify electropolished surfaces and material traceability protocols ahead of equipment replacement schedules.
Growth Catalysts
- EMA GMP Annex 1 revisions:Updated sterility assurance requirements are accelerating replacement of legacy carbon steel vessels with 316-grade electropolished containers across European parenteral drug facilities.
- Coastal chemical processing expansion:Molybdenum-enhanced chloride resistance is displacing 304-grade alloys in desalination and marine chemical plants operating in high-salinity environments.
- India's pharmaceutical output scaling:CDSCO-aligned manufacturing investments are driving drum and intermediate bulk container demand for active pharmaceutical ingredient exports.
Market Restraints
- Nickel-molybdenum price volatility:Raw material cost swings in stainless steel melt inputs compress fabrication margins and complicate long-term contract pricing for vessel suppliers.
- Electropolishing capacity concentration:Certified surface finish providers cluster in Germany and the United States, creating geographic bottlenecks for pharmaceutical-grade container delivery timelines.
- High-purity polymer substitution:Single-use bioprocessing bags from Sartorius and Thermo Fisher are capturing small-batch biologics applications that previously required stainless steel containment.
Strategic Opportunities
- ASEAN pharmaceutical manufacturing:Singapore and Thailand are expanding sterile fill-finish capacity under PIC/S harmonization, creating demand for validated 316-grade process vessels.
- Hydrogen economy infrastructure:Electrolyzer and fuel cell manufacturing requires high-purity 316 containers for electrolyte handling and hydrogen storage applications.
- EU Green Deal circularity mandates:Reusable containment systems gain preference over single-use alternatives as EMAS-registered facilities face Scope 3 emissions accounting requirements.
Industry Challenges
- Welder certification scarcity:ASME Section IX-qualified orbital welders for pharmaceutical-grade vessel fabrication are concentrated in aging workforces across Belgium and Switzerland.
- Multi-jurisdiction audit fatigue:Container manufacturers face overlapping FDA 21 CFR Part 211, EMA GMP Annex 1, and ISO 15378 inspection schedules that strain quality documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 316 Stainless Steel Container Market |
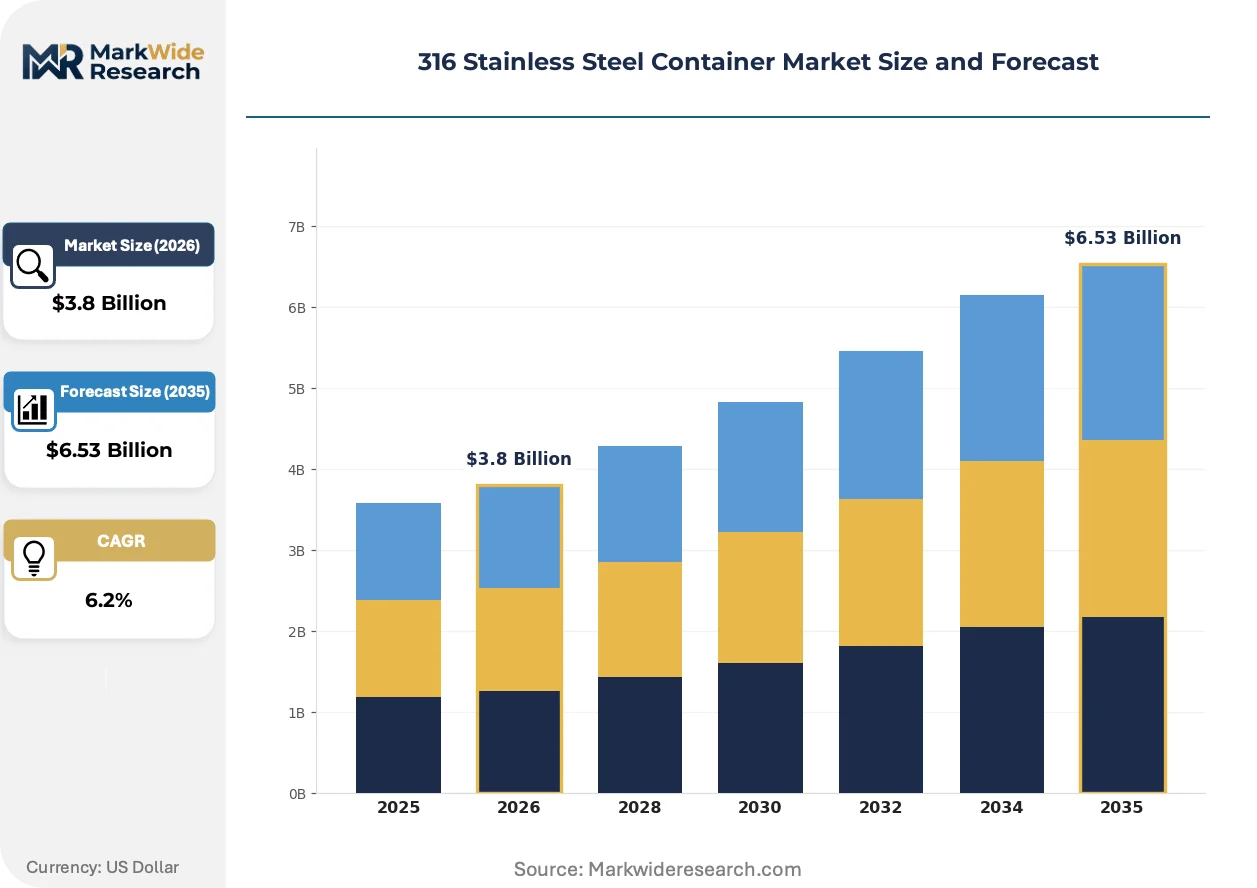
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Cans, Drums, Jars End Use Industry: Food & Beverage, Chemicals, Pharmaceuticals, Electronics Capacity: 100ml, 1L, 5L, 20L Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Eagle Stainless, ArcelorMittal, SCHÄFER WERKE Group, Scoya Pharmatech, Pharma Hygiene Products, Thielmann, Servolift GmbH, Bhuvan Engineering, SeAH Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
316 Stainless Steel Container Market Strategic Shifts
Digital traceability systems and advanced surface engineering are redefining how pharmaceutical and chemical buyers validate container integrity across extended supply chains.
Additive manufacturing is converging with traditional forging for complex vessel geometries. Specialized fabricators in Germany and Switzerland are adopting laser powder bed fusion for prototype manway flanges and custom nozzle configurations. This hybrid production model is converging with electrochemical polishing workflows to compress lead times for low-volume, high-specification pharmaceutical vessels from 16 weeks to 9 weeks.
REACH substance restriction proposals are tightening molybdenum compound reporting thresholds for European stainless steel producers. ECHA's 2024-2025 consultation on critical raw materials is forcing melt shops to document recycled content ratios and conflict mineral status in mill test reports. German and Belgian fabricators are responding by securing dual-certified feedstock from ArcelorMittal's Ghent and Timoteo integrated facilities.
Biopharma procurement teams are consolidating vendor panels around full-service containment partners. Large molecule manufacturers in Massachusetts and North Carolina are replacing transactional drum purchases with multi-year service agreements bundling vessel leasing, cleaning validation, and reverse logistics. This vendor consolidation pattern is most visible in monoclonal antibody production facilities where batch sizes exceed 10,000 liters and contamination events carry multi-million dollar write-off exposure.
316 Stainless Steel Container Market Segmentation
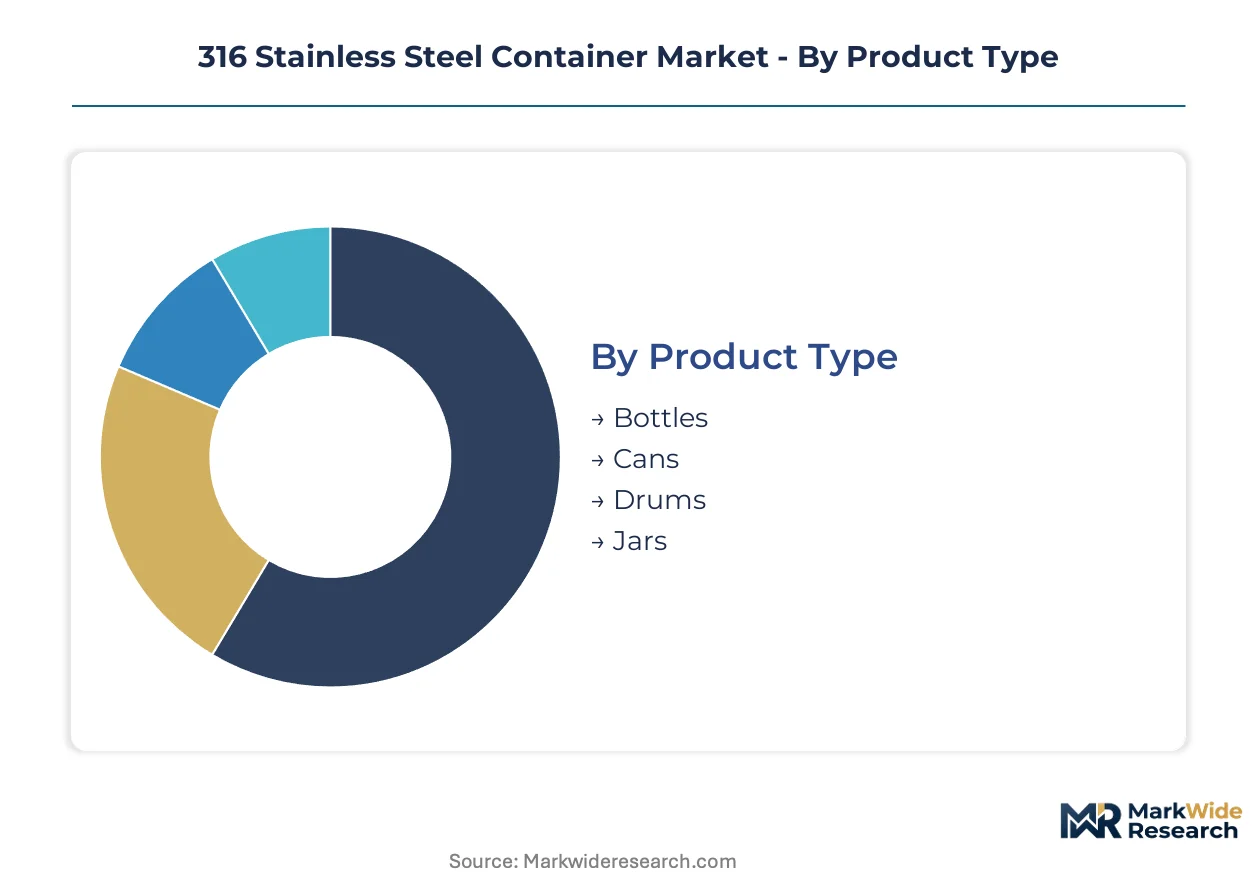
Container selection in 316-grade stainless steel hinges on sterility assurance, chemical compatibility, and handling logistics across divergent end-use environments. Each segmentation dimension reveals distinct procurement patterns tied to regulatory compliance burdens and operational scale.
Product Type:
Buyers prioritize corrosion resistance specifications and surface finish grades when selecting vessel geometries for specific containment tasks.
- Drums:Cylindrical vessels ranging 30-55 gallons dominate bulk chemical and pharmaceutical ingredient logistics. Demand concentrates in German and Indian pharmaceutical manufacturing clusters where EMA GMP Annex 1 and CDSCO mandates require electropolished interiors for parenteral drug storage.
- Bottles:Narrow-neck cylindrical containers with precision-machined closures serve bioprocessing sampling and laboratory reagent storage. Massachusetts and North Carolina biologics manufacturers are consolidating vendor panels around electropolished bottle suppliers certified to FDA 21 CFR Part 211.
- Cans:Short cylindrical containers with removable lids handle specialty chemical and food ingredient packaging. Coastal chemical processors in Belgium specify molybdenum-enhanced 316-grade cans for chloride-rich marine environments.
- Jars:Wide-mouth cylindrical vessels accommodate viscous pharmaceutical creams and specialty chemical pastes. Swiss cosmetic chemical facilities favor jar configurations for high-viscosity API handling.
Volume sits with drums; growth tilts toward bottles.
End Use Industry:
Regulatory stringency and contamination risk exposure drive purchasing authority concentration in specific verticals.
- Pharmaceuticals:Parenteral drug, vaccine, and biologics manufacturing commands premium-grade electropolished vessels with full material traceability. FDA and EMA inspection schedules compel container fabricators to maintain lot-certified mill test reports and surface finish documentation.
- Chemicals:Specialty and agrochemical processing requires chloride-resistant containment for aggressive solvents and halogenated compounds. Coastal desalination and marine chemical plants in Brazil are displacing 304-grade alloys with 316-grade alternatives.
- Food & Beverage:High-acid and saline food ingredient storage utilizes 316-grade corrosion resistance for extended shelf-life applications. FSSAI-registered Indian facilities specify 316-grade drums for spice oleoresin exports.
- Electronics:High-purity chemical handling for semiconductor etching and cleaning processes demands ultra-low metallic ion leaching. Belgian and German fabs specify 316L electropolished containers for photoresist and solvent storage.
Revenue concentrates in pharmaceuticals; expansion is steepest in chemicals.
Capacity:
Batch scale and handling automation determine volume selection across manufacturing configurations.
- 20L:Intermediate bulk containers serve pilot-scale bioprocessing and specialty chemical synthesis. Singapore pharmaceutical fill-finish facilities under PIC/S harmonization are scaling 20L vessel fleets for monoclonal antibody production.
- 5L:Bench-scale and clinical trial manufacturing vessels balance portability with sufficient batch volume. North Carolina contract development organizations specify 5L electropolished containers for phase-III drug substance production.
- 1L:Laboratory-scale reagent storage and sampling containers support analytical and quality control operations. German research chemical distributors maintain 1L bottle inventories for HPLC-grade solvent distribution.
- 100ml:Small-volume diagnostic and reference standard containment requires precision-machined closures and minimal headspace. Swiss diagnostic manufacturers specify 100ml 316-grade vials for calibrator solution packaging.
Procurement volume centers on 20L; fastest adoption occurs at 5L.
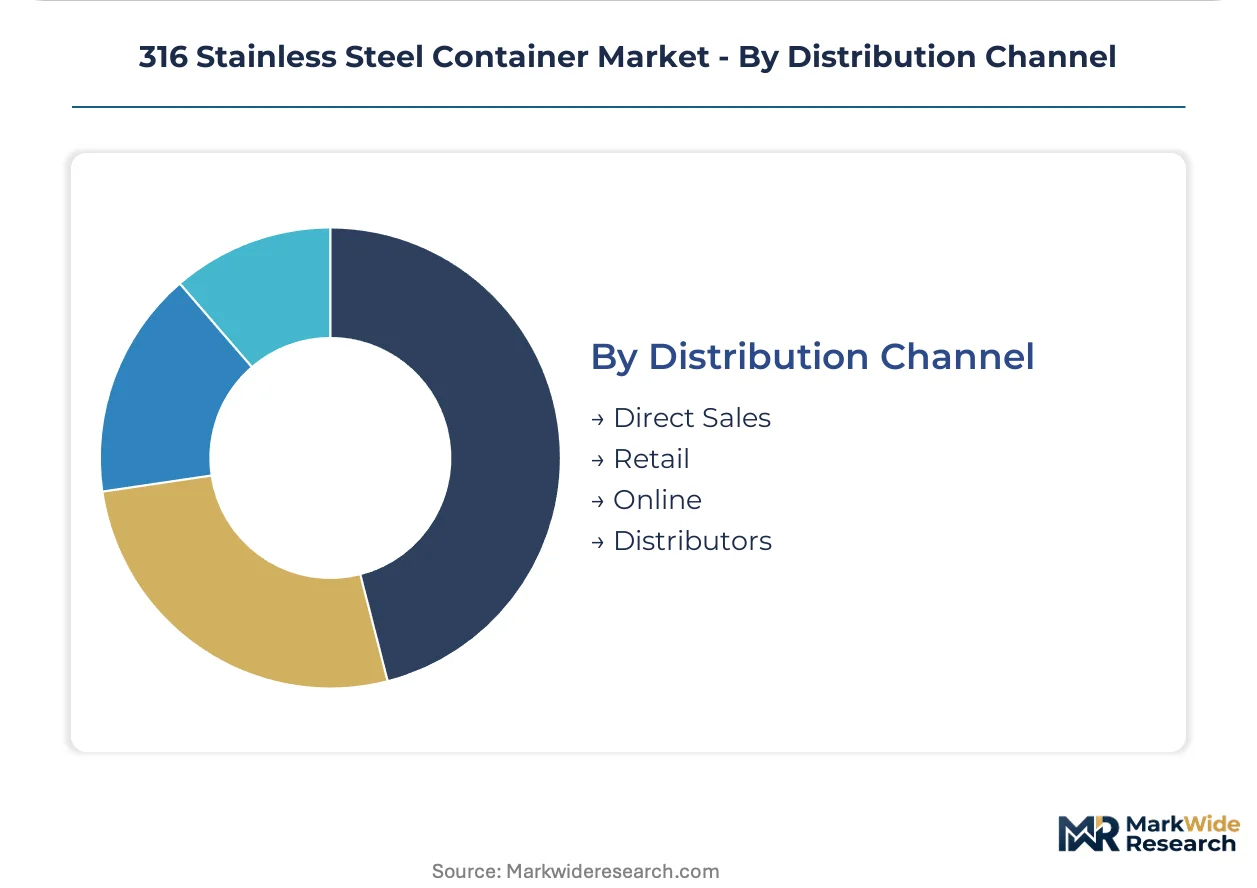
Distribution Channel:
Relationship intensity and technical support requirements shape channel selection for compliance-critical applications.
- Direct Sales:Manufacturer-to-end-user relationships dominate pharmaceutical-grade vessel procurement requiring custom electropolishing and documentation bundles. Thielmann and Eagle Stainless maintain direct sales teams for FDA and EMA audit support.
- Distributors:Authorized technical distributors serve mid-scale chemical and food processors with standardized drum and can configurations. Belgian industrial chemical distributors stock 316-grade vessels for just-in-time delivery to Antwerp and Ghent manufacturing clusters.
- Online:E-commerce platforms capture standard-capacity laboratory bottle and jar sales with expedited fulfillment. Indian research supply portals are expanding 316-grade bottle listings for CDSCO-registered API laboratories.
- Retail:Limited retail presence serves small-scale food processing and home brewing applications with non-electropolished 316-grade containers. German specialty kitchen retailers stock 316-grade jars for artisanal food preservation.
Transaction value aggregates through direct sales; channel expansion is strongest in distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in India and China's coastal provinces are accelerating pharmaceutical-grade vessel manufacturing concentration. These designated zones offer tax holidays and duty exemptions that attract stainless steel fabricators serving export-oriented drug manufacturers. The resulting geographic clustering is reshaping procurement patterns for 316-grade containers across three continents.
United States
Massachusetts and North Carolina biologics manufacturers are scaling monoclonal antibody production facilities. FDA 21 CFR Part 211 inspections are compressing vendor qualification timelines for electropolished vessel suppliers. Greater Boston contract development organizations are consolidating procurement around full-service containment partners with integrated cleaning validation capabilities.
Germany
EMA GMP Annex 1 revisions are forcing parenteral drug facilities in Baden-Württemberg to replace legacy carbon steel vessels. REACH substance restriction proposals are tightening molybdenum compound reporting thresholds for Stuttgart-area fabricators. The Rhine-Neckar pharmaceutical cluster is driving demand for lot-certified mill test reports and surface finish documentation.
India
Hyderabad and Ahmedabad pharmaceutical manufacturing zones are expanding sterile fill-finish capacity for CDSCO-registered API exports. Production-Linked Incentive schemes for active pharmaceutical ingredients are attracting 316-grade drum and intermediate bulk container investments. Gujarat's Dahej Special Economic Zone hosts multiple stainless steel vessel fabricators serving export-oriented generic drug manufacturers.
Belgium
Antwerp chemical processors are specifying molybdenum-enhanced 316-grade containers for chloride-rich marine environments. ECHA's critical raw materials consultation is forcing Ghent-area melt shops to document recycled content ratios in mill test reports. The Port of Antwerp chemical cluster is displacing 304-grade alloys with 316-grade alternatives in desalination and marine chemical applications.
Switzerland
Swissmedic inspection schedules are compelling Basel-area biopharma manufacturers to maintain rigorous vessel traceability protocols. Swiss cosmetic chemical facilities in Visp are favoring wide-mouth jar configurations for high-viscosity API handling. The Basel-Landschaft pharmaceutical corridor is consolidating vendor panels around electropolished bottle suppliers with full audit support capabilities.
316 Stainless Steel Container Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across multiple tiers of the 316 stainless steel container market. The vendor base organizes around three strategic archetypes: integrated steel producers with captive melt capacity, specialized pharmaceutical-grade fabricators with electropolishing certification, and regional drum manufacturers serving chemical and food processing industries. Dominant competitive moves include backward integration into stainless steel melt shops and geographic expansion through authorized distributor networks.
Among European-based fabricators, Thielmann and Eagle Stainless exemplify the premium-tier specialist archetype. Thielmann leverages captive forging capacity for margin control across drum and intermediate bulk container lines. Eagle Stainless occupies a position within the electropolished bottle segment for bioprocessing applications. ArcelorMittal anchors the integrated producer tier through stainless melt shops in Belgium and Brazil, representing the raw material supply consolidation pattern visible across pharmaceutical-grade vessel supply chains.
| Leading Market Players |
|---|
| Eagle Stainless |
| ArcelorMittal |
| SCHÄFER WERKE Group |
| Scoya Pharmatech |
| Pharma Hygiene Products |
| Thielmann |
| Servolift GmbH |
| Bhuvan Engineering |
| SeAH Group |
| Others |
Value Chain & Pricing Dynamics
ASME Section IX-qualified orbital welders concentrated in Belgium and Switzerland create labor-cost differentials that separate premium electropolished vessel pricing from standard-grade drum alternatives. This workforce scarcity widens pricing-tier spreads as pharmaceutical buyers absorb certification premiums while chemical processors migrate toward commoditized 304-grade substitutes.
Pricing Analysis
Lead-time premiums command substantial markups in pharmaceutical-grade vessel procurement, with electropolished containers requiring 16-week production cycles drawing pricing premiums over spot inventory held by authorized distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA 21 CFR Part 211-compliant electropolished surfaces anchor the top tier, while standard mill-finish drums serve chemical processing mid-tier demand. Cost compression in the standard tier is intensifying because Indian fabricators are scaling capacity under Production-Linked Incentive schemes. Contract development organizations in Massachusetts exhibit lowest price sensitivity due to batch-integrity write-off exposure, whereas coastal chemical processors in Brazil demonstrate highest sensitivity to nickel-molybdenum alloy surcharges.
Supply Chain Analysis
Reverse logistics flows for leased pharmaceutical vessels—cleaning validation, refurbishment, and redeployment—are consolidating around full-service containment partners in Massachusetts and North Carolina. Primary manufacturing concentrates in Germany, India, and Belgium, with Ghent-area melt shops and Gujarat's Dahej Special Economic Zone anchoring raw material conversion. Supply chains draw from nickel ore processing in Indonesia, ferrochrome from South Africa, and molybdenum concentrate from Chile. Single-source vulnerability concentrates in electropolishing capacity clustered in Stuttgart and Boston suburbs. Distribution runs through authorized technical distributors serving Antwerp and Hyderabad manufacturing clusters with just-in-time drum delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
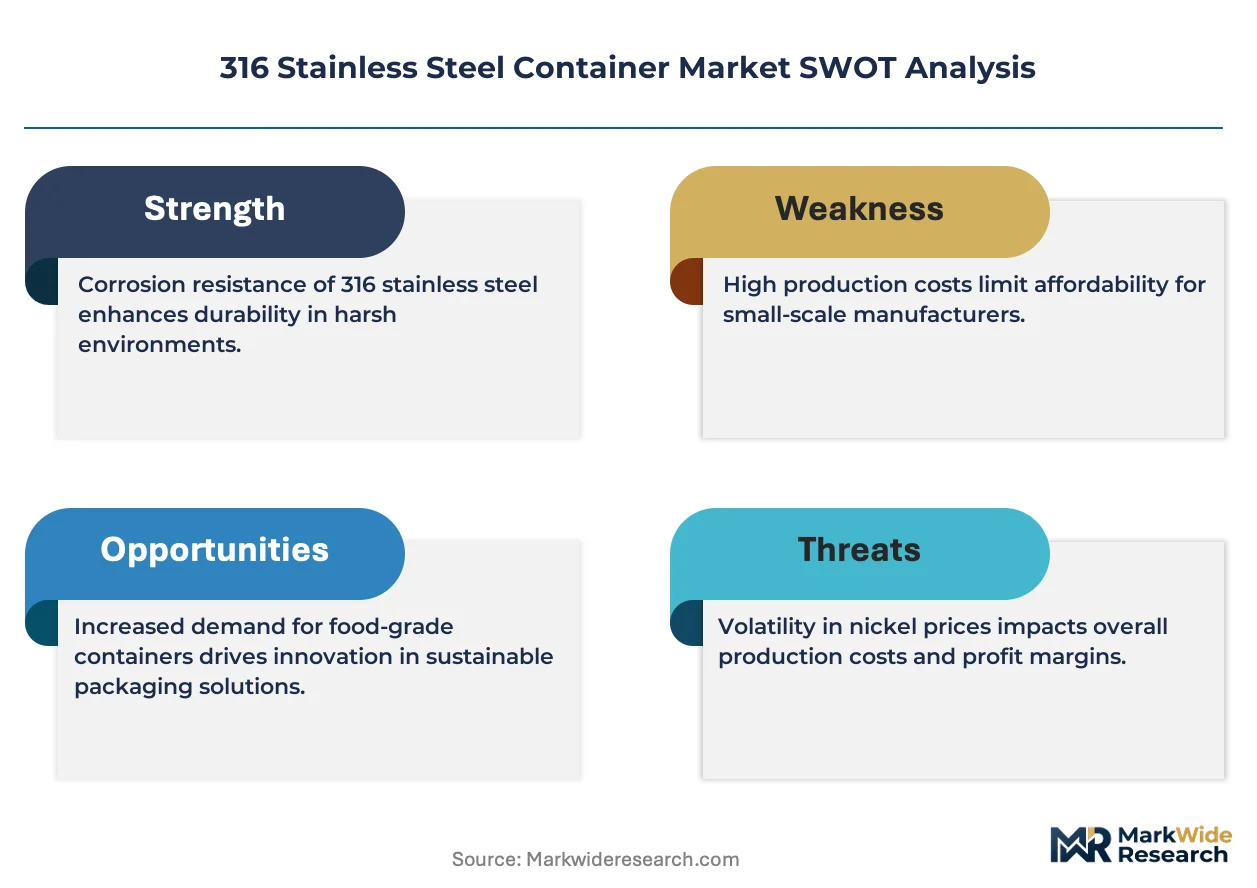
EMA GMP Annex 1 revisions have erected a cost-of-compliance moat that rewards incumbent fabricators with certified electropolishing infrastructure while screening out capital-constrained entrants lacking audit documentation systems.
For Market Incumbents: Hedge against single-use bioprocessing bag substitution by bundling vessel leasing with cleaning validation services for monoclonal antibody manufacturers. Secure captive molybdenum feedstock through backward integration into ArcelorMittal's Ghent or Timoteo melt shops to defend margin position against nickel price volatility.
For New Entrants and Emerging Players: Authorized technical distributors in Belgium and India represent the most accessible channel partners for penetrating mid-tier chemical processing demand without electropolishing certification investments. Target ASEAN pharmaceutical manufacturing expansion in Singapore and Thailand under PIC/S harmonization, where validated 316-grade vessel demand outstrips certified local supply.
For Investors and Strategic Acquirers: The window for entry favors specialized pharmaceutical-grade fabricators with ASME Section IX welder rosters and EMA audit support capabilities over commodity drum manufacturers facing polymer substitution pressure. Monitor ECHA critical raw materials consultation outcomes for molybdenum compound reporting thresholds as an inflection indicator for European melt shop consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melt Capacity | ArcelorMittal's Ghent and Timoteo facilities secure molybdenum-enhanced feedstock for margin control. |
| Electropolishing Certification Investment | FDA 21 CFR Part 211 and EMA GMP Annex 1 compliance opens pharmaceutical premium tier access. |
| Full-Service Containment Partnerships | Massachusetts biologics manufacturers are consolidating vendor panels around integrated leasing and validation bundles. |
| ASEAN Geographic Expansion | Singapore and Thailand PIC/S harmonization creates validated vessel demand without certified local supply. |
| Reverse Logistics Infrastructure Buildout | Cleaning validation and refurbishment capabilities capture recurring revenue from leased pharmaceutical vessel fleets. |
Study Parameters
Document review covered EMA GMP Annex 1 revision drafts, FDA 21 CFR Part 211 guidance documents, and REACH substance restriction proposals, complemented by interviews with pharmaceutical manufacturing executives, stainless steel procurement leads at chemical processors, ASME-certified welding contractors, and electropolishing service providers. Secondary validation drew from customs trade data, SEC filings of integrated steel producers, and CDSCO manufacturing registration databases. Bottom-up vessel demand modeling triangulated against top-down alloy consumption forecasts.
Cross-referencing historical pharmaceutical capital expenditure patterns with panel input from bioprocessing procurement directors shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type hierarchy, end-use industry regulatory burden, capacity tier, and geographic production cluster. CAGRs were derived from alloy price elasticity coefficients and replacement cycle compression factors under evolving sterility assurance mandates.
Caveats apply where nickel-molybdenum price volatility, ECHA critical raw materials consultation outcomes, or single-use bioprocessing bag technology advances could materially shift the outlook beyond modeled assumptions. Practitioners should monitor EMA guidance evolution on reusable versus single-use containment systems and ASEAN PIC/S implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Stainless Steel Lashing Wire Market
Metals
Metal Powder Market
Metals
Steel Ingots Market
Metals
Global Wire Rods Market
Metals
Nickel Powder Plating Market
Metals
Aluminium Forging Market
Metals
Europe Aluminium Powder Market
Metals
Copper and Copper Alloy Powder Market
Metals
Steel Drums Market
Metals
Beryllium Copper Billet Market
Metals
Copper and Copper Alloy Market
Metals
Weathering Steel Market
Metals
North America Electrical Steel Market
Metals
TMCP Steel Market
Metals
Lithium Foil Market
Metals
Motor Lamination Material Market