
 Global Hot Rolled Coil Steel Market | 2026-2036
Global Hot Rolled Coil Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hot Rolled Coil Steel Market Analysis
Long-term supply agreements bundled with logistics and technical support services is consolidating buyer relationships around integrated mill offerings. ArcelorMittal leverages its European and North American footprint to anchor premium-grade contracts with automotive OEMs. POSCO competes through specialized high-strength product lines serving shipbuilding and offshore engineering clients across Northeast Asia.
Hot rolled coil steel is carbon or low-alloy steel processed above recrystallization temperature, typically 900–1,100°C, into continuous strips 1.2–25 mm thick for downstream forming and welding. The material serves as primary feedstock for structural sections, automotive body panels, and pressure vessels requiring ductility and weldability. Steel coils occupy the largest value share within product type segmentation, reflecting their centrality to automated stamping and roll-forming operations. Medium-thickness grades dominate volume flows into construction applications, while thin-coil demand accelerates fastest within automotive manufacturing as OEMs pursue weight reduction targets.
China's MEE enforces emissions intensity benchmarks that constrain output from older blast furnace routes, while the EU's CBAM imposes embedded carbon costs on imported coil entering European fabrication chains. India's BIS certification requirements for structural steel grades create compliance barriers for non-domestic suppliers seeking infrastructure project participation. Buyers and mills must monitor evolving carbon accounting rules and regional certification standards to preserve market access across fragmented regulatory environments.
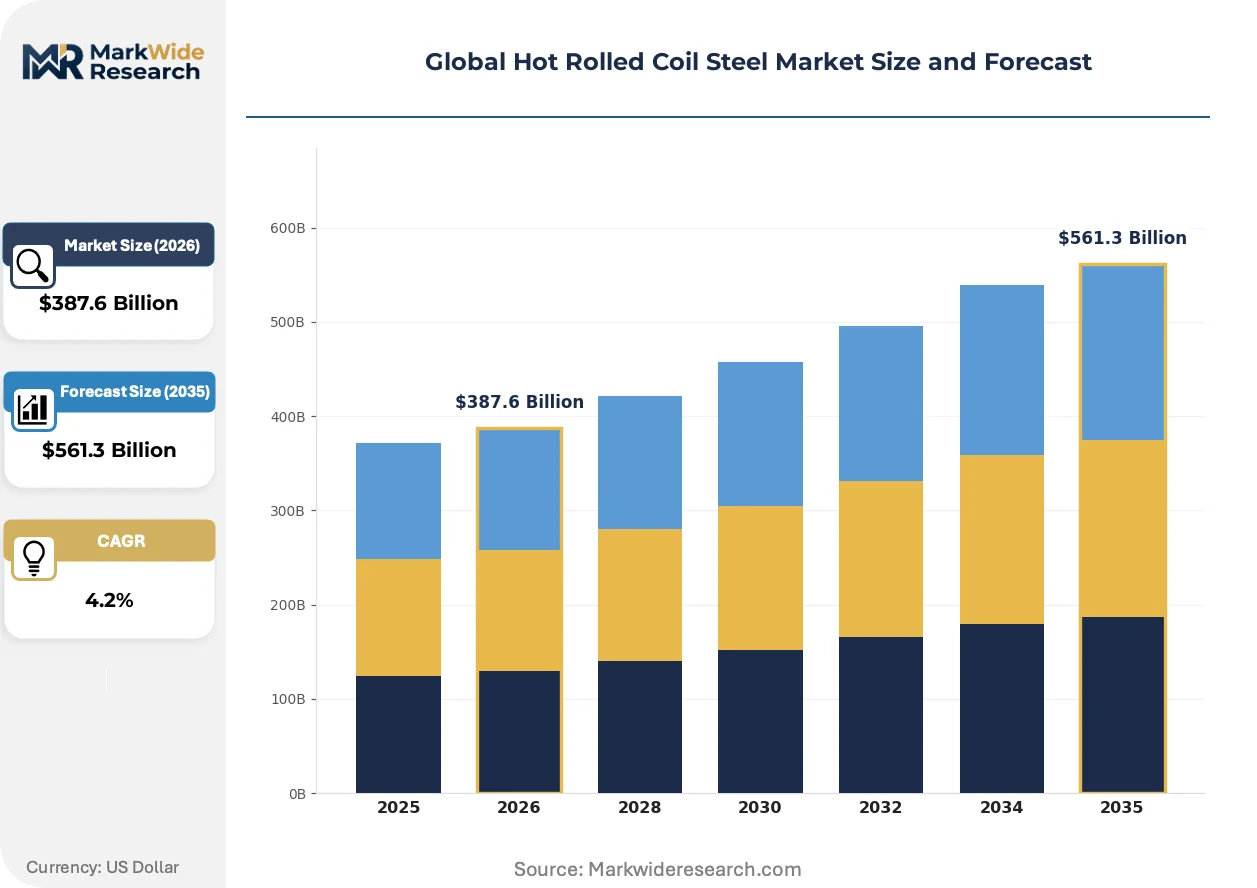
Market Dynamics
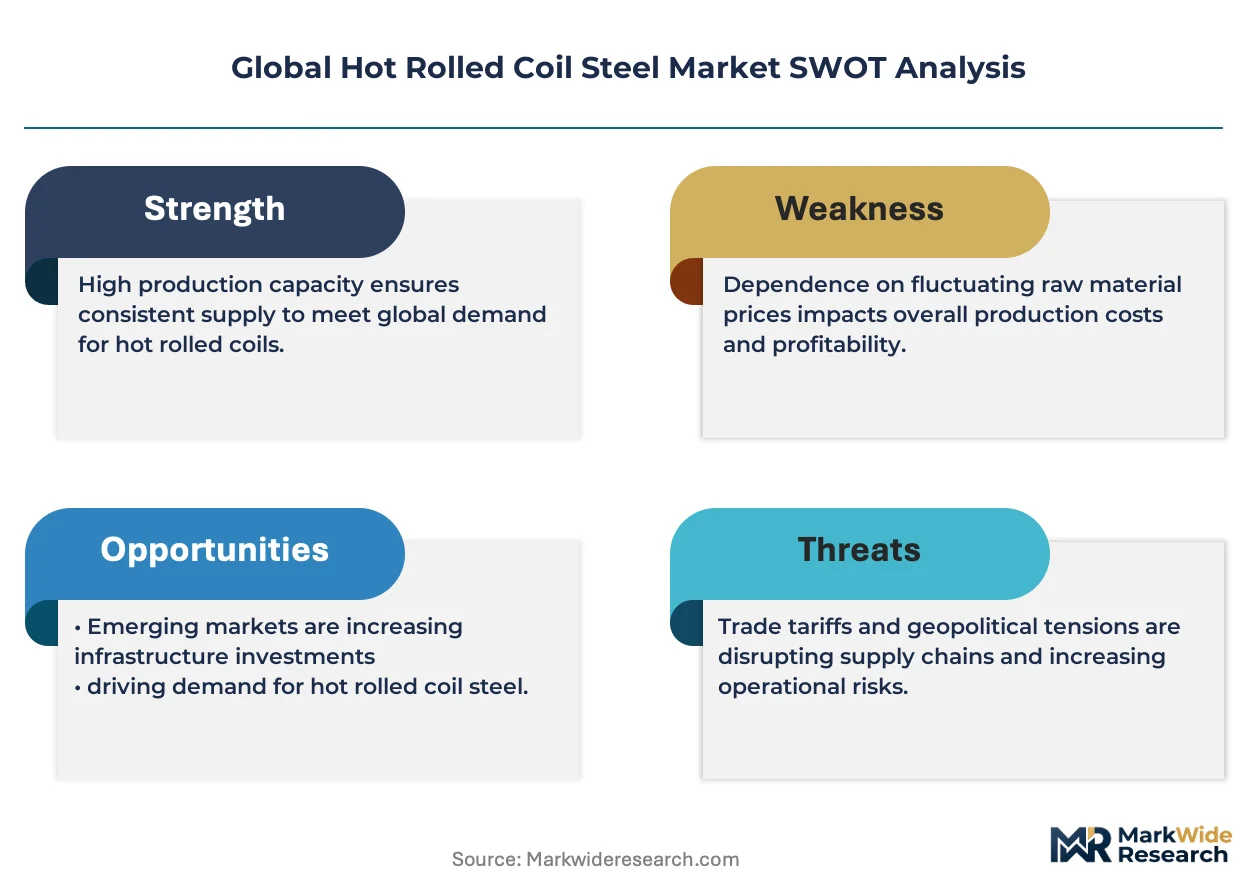
Carbon accounting mandates from the EU's CBAM and China's MEE are forcing mills to reconfigure blast furnace operations, redirecting capital toward electric arc furnace retrofits and hydrogen-based direct reduction trials.
Growth Catalysts
- Automotive lightweighting:Electric vehicle platforms consume advanced high-strength grades for battery enclosure structures and body-in-white assemblies, tightening specifications for thin-gauge coil supply.
- India's PLI scheme:Domestic manufacturing incentives for construction equipment and appliance production expand offtake for medium-thickness structural grades.
- EU Carbon Border Adjustment Mechanism:Embedded carbon cost exposure on imported coil incentivizes European fabricators to source from low-emission domestic and premium import suppliers.
Market Restraints
- Iron ore price volatility:Blast furnace operators face margin compression from seaborne ore benchmark fluctuations, particularly affecting integrated mills in coastal China.
- Supply concentration in Hebei Province:Output curtailments under provincial emissions quotas create regional availability shocks that propagate through Asian spot markets.
- Scrap quality limitations:Electric arc furnace routes struggle with residual element control for automotive surface-critical applications, constraining grade expansion.
Strategic Opportunities
- Southeast Asia infrastructure build-out:Vietnam, Indonesia, and Philippines megaprojects generate uncontracted demand for construction-grade coil as domestic rolling capacity lags.
- Hydrogen direct reduction:Convergence of green hydrogen supply and shaft furnace technology enables near-zero-emission primary steel for premium automotive and energy sector contracts.
- Digital mill services:Predictive metallurgy platforms and automated coil tracking create new subscription revenue streams from technical support bundling.
Industry Challenges
- Metallurgical talent scarcity:Deep expertise in thermomechanical processing and microstructure engineering concentrates at legacy integrated mills, constraining new entrant capability building.
- Multi-certification complexity:Simultaneous compliance with India's BIS structural grades, EU CE marking, and automotive OEM proprietary specs extends qualification timelines for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hot Rolled Coil Steel Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $561.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Coils, Steel Sheets, Plates, Strips End User: Construction, Automotive, Appliances, Shipbuilding Thickness: Thin, Medium, Thick, Extra Thick Application: Structural, Manufacturing, Fabrication, Engineering |
| Companies Covered | China Baowu Steel Group, ArcelorMittal, Nippon Steel Corporation, POSCO, Hesteel Group, JFE Steel Corporation, Hyundai Steel, Tata Steel, Nucor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hot Rolled Coil Steel Market Emerging Trajectories
Process electrification and embedded carbon traceability are compressing the technology frontier for primary steelmaking, while procurement consolidation among large fabricators restructures traditional spot-market liquidity.
Direct reduced iron-electric arc furnace complexes paired with renewable power purchase agreements are electrifying the cost structure of flat steel production. Automotive OEMs in Germany and South Korea now specify mass-balance-certified low-emission coil for new platform launches. This shift is compressing the premium achievable by legacy blast furnace routes in European and Northeast Asian contract negotiations.
REACH authorization requirements for process chemicals and the EU's CSRD disclosure mandates are tightening supply chain documentation burdens. Coil importers into European fabrication chains must now verify embedded emissions through accredited third-party auditors. Automotive stamping operations and offshore wind tower fabricators face the steepest compliance cost escalations, driving preferential sourcing from mills with certified environmental product declarations.
Long-term offtake contracts with fixed-volume, floating-price mechanisms are displacing traditional quarterly spot negotiations among large construction and appliance manufacturers. Tier-one fabricators in Japan and the US Midwest now anchor supply security through equity-linked procurement partnerships rather than merchant market exposure. This behavioral pivot concentrates volume commitment around integrated mill systems with guaranteed logistics and technical service bundling.
Global Hot Rolled Coil Steel Market Segmentation
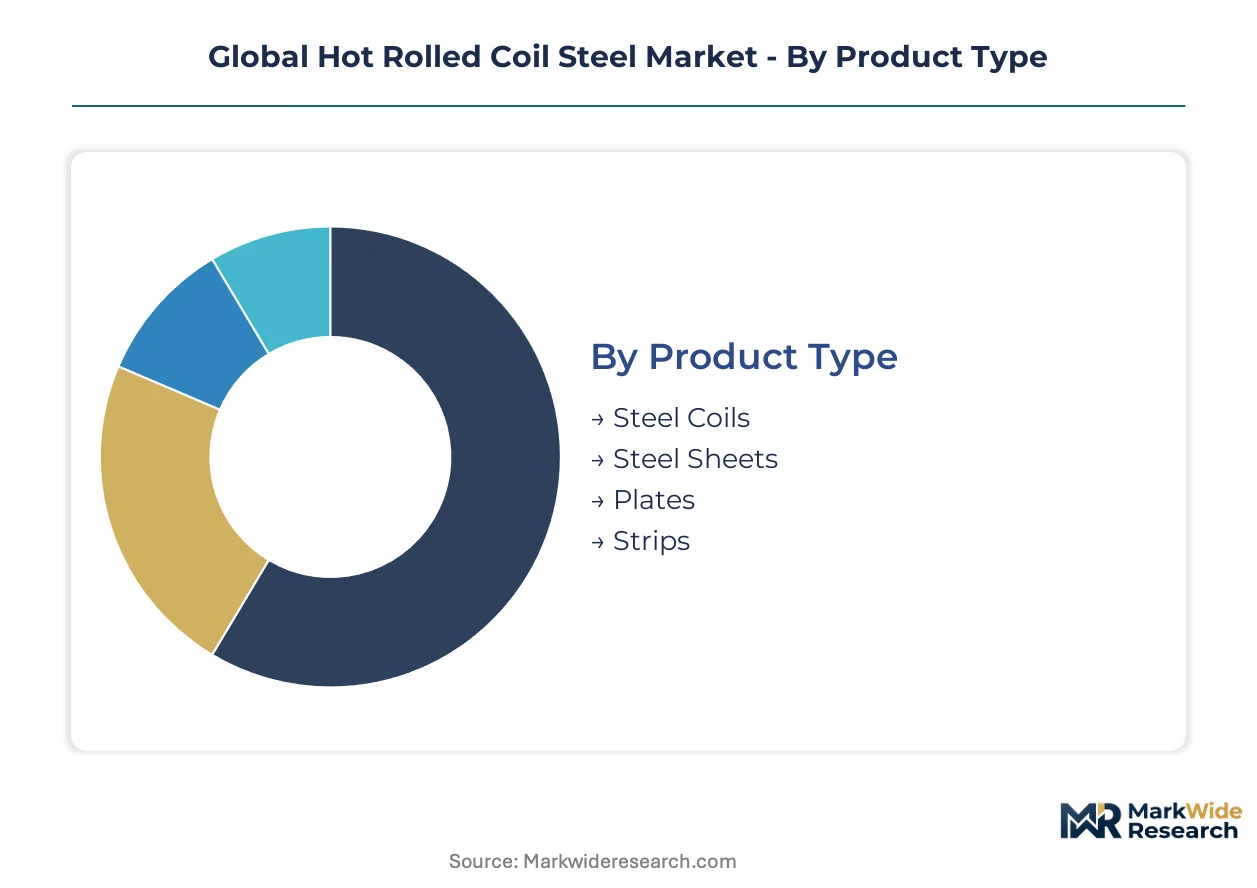
Hot rolled coil steel procurement decisions hinge on thickness tolerances, surface quality requirements, and forming characteristics that vary sharply across automotive stamping versus structural fabrication. Each segmentation dimension carries distinct certification burdens and logistics constraints that reshape supplier qualification workflows.
Product Type:
Buyers prioritize coil geometry and edge condition based on downstream automation requirements and scrap minimization targets.
- Steel Coils:Continuous wound strips optimized for automated uncoiling and progressive die operations. Automotive OEMs in Germany and South Korea specify mass-balance-certified low-emission coil for battery enclosure platforms, tightening supplier environmental documentation requirements.
- Steel Sheets:Cut-to-length flat products serving fabrication shops without slitting capability. Demand concentrates in India's infrastructure build-out where domestic manufacturing incentives expand offtake for structural-grade sheet supply.
- Plates:Heavier gauge material for pressure vessel and heavy equipment applications.
- Strips:Narrow-width coil segments for specialized roll-forming and tube mill feedstock.
Volume sits with steel coils; growth tilts toward steel sheets.
End User:
Application-specific metallurgical requirements drive grade selection and surface quality premiums.
- Construction:Structural grades emphasizing yield strength consistency and weldability for beam and column fabrication. India's BIS certification requirements for structural steel grades create compliance barriers for non-domestic suppliers seeking infrastructure project participation.
- Automotive:Advanced high-strength grades for body-in-white and battery enclosure structures. Electric vehicle platforms consume thin-gauge coil supply as OEMs pursue weight reduction targets, tightening specifications for surface-critical applications.
- Appliances:Formable grades for refrigerator and washing machine panels requiring consistent cosmetic surfaces.
- Shipbuilding:Specialized grades for hull plates and offshore structures with enhanced toughness at low temperatures.
Construction commands the largest volume position; automotive exhibits the steepest expansion trajectory.
Thickness:
Gauge selection determines rolling mill configuration requirements and minimum order quantity economics.
- Thin:Sub-3mm gauges for automotive body panels and precision stampings. European fabricators source from low-emission domestic and premium import suppliers under EU Carbon Border Adjustment Mechanism exposure.
- Medium:3-12mm range dominating construction and general fabrication. Southeast Asian megaprojects in Vietnam, Indonesia, and Philippines generate uncontracted demand as domestic rolling capacity lags.
- Thick:12-25mm material for heavy structural and pressure vessel applications.
- Extra Thick:Above 25mm gauges for specialized industrial equipment and offshore platforms.
Medium thickness carries the volume base; thin gauges are gaining share fastest.
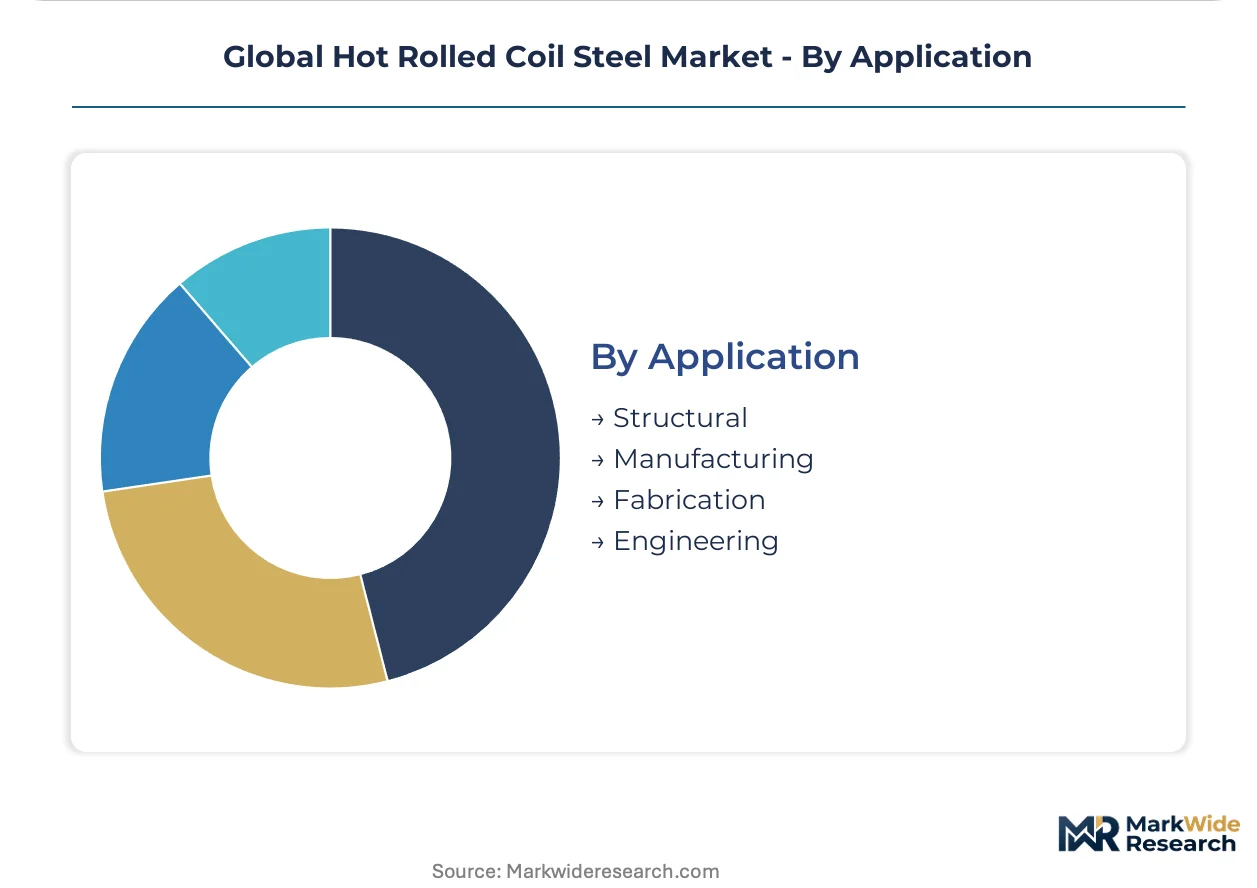
Application:
Functional end-use dictates certification depth and technical support bundling requirements.
- Structural:Load-bearing applications requiring seismic-grade certification and traceability documentation. China's MEE emissions intensity benchmarks constrain output from older blast furnace routes serving this segment.
- Manufacturing:OEM feedstock for machinery and equipment production with tight dimensional tolerances. Japanese tier-one fabricators anchor supply security through equity-linked procurement partnerships rather than merchant market exposure.
- Fabrication:Job shop and contractor supply with flexible quantity and delivery scheduling.
- Engineering:Project-specific material with custom testing and third-party inspection protocols.
Structural applications dominate volume flows; manufacturing commands the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China produces roughly half of global hot rolled coil steel output yet domestic consumption growth is slowing, while India's infrastructure build-out and automotive expansion are accelerating import demand and new mill investments.
China
Blast furnace operators in Hebei Province face recurring output curtailments under provincial emissions quotas enforced by the MEE. The dual carbon goals mandate steel intensity reductions that favor electric arc furnace retrofits and scrap-based production in coastal clusters. Tangshan and Handan mills are consolidating capacity into larger, lower-emission facilities while redirecting export volumes toward Southeast Asian markets.
India
Infrastructure megaprojects and domestic manufacturing incentives under the PLI scheme are expanding appetite for construction-grade and automotive coil. BIS certification requirements for structural steel grades create compliance barriers for non-domestic suppliers seeking public project participation. Odisha and Jharkhand host the fastest-growing greenfield integrated mill complexes targeting both domestic offtake and export positioning.
United States
Electric arc furnace operators dominate flat-rolled production, with Nucor Corporation and Cleveland-Cliffs anchoring supply to automotive and construction fabricators. The Inflation Reduction Act's domestic content provisions for clean energy infrastructure are redirecting procurement toward low-emission domestic coil. The Gulf Coast and Midwest corridors concentrate new capacity investments targeting renewable energy and automotive OEM demand.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify mass-balance-certified low-emission coil for battery enclosure platforms and body-in-white assemblies. The EU Carbon Border Adjustment Mechanism imposes embedded carbon costs on imported coil, incentivizing sourcing from domestic mills and premium low-emission suppliers. Thyssenkrupp and Salzgitter are trialing hydrogen direct reduction at Duisburg and Peine to secure automotive contract eligibility.
South Korea
POSCO and Hyundai Steel serve shipbuilding and offshore engineering clients across Northeast Asia with specialized high-strength grades. The country's national steel regulator aligns with automotive OEM specifications for surface-critical applications. The Pohang and Gwangyang mill complexes are expanding thin-gauge capacity to capture electric vehicle platform demand from domestic and export automakers.
Global Hot Rolled Coil Steel Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across integrated and electric arc furnace routes. The market structures around three tiers: global integrated giants with multi-continent footprints, regional champions dominating domestic procurement, and niche specialists in high-strength or certified low-emission grades. Strategic moves concentrate on hydrogen direct reduction partnerships, long-term offtake contracting with automotive OEMs, and backward integration into iron ore or scrap supply.
Within the global integrated tier, ArcelorMittal and Nippon Steel Corporation occupy positions anchoring premium-grade automotive contracts across European and Northeast Asian markets. POSCO exemplifies the regional champion archetype, concentrating specialized high-strength production for shipbuilding and offshore engineering. Among electric arc furnace specialists, Nucor Corporation represents the scale-driven scrap-based model dominating North American flat-rolled supply.
| Leading Market Players |
|---|
| China Baowu Steel Group |
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| Hesteel Group |
| JFE Steel Corporation |
| Hyundai Steel |
| Tata Steel |
| Nucor Corporation |
| Others |
Supply Flow & Price Mechanics
Tier-one automotive OEM procurement teams in Germany and South Korea anchor contract negotiations through mass-balance-certified low-emission specifications, compressing spot-market liquidity and elevating long-term offtake premiums for compliant mills.
Pricing Analysis
Margin tightening in blast furnace routes reflects iron ore benchmark volatility and EU Carbon Border Adjustment Mechanism exposure on imported coil. Contract-based long-term offtake with floating-price mechanisms now dominates large-fabricator procurement, displacing quarterly spot negotiations. Price differentiation rests on certification grade and embedded carbon documentation, with automotive stamping operations showing least price sensitivity while general fabrication buyers prioritize volume discounts.
Supply Chain Analysis
Freight cost escalation on seaborne iron ore from Australia and Brazil feeds into integrated mill cost structures, while scrap-based electric arc furnace routes in the United States draw from domestic shredded supply. Raw material dependencies center on iron ore pellets, metallurgical coal, and high-quality scrap grades. Single-source vulnerability concentrates in Hebei Province blast furnace output, with distribution running through mill-direct contracts and service-center intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Hot Rolled Coil Steel Market functions as a cost-of-compliance arena where EU Carbon Border Adjustment Mechanism documentation requirements erect durable barriers against non-certified imports, entrenching incumbent positions.
For Market Incumbents: Extend certification coverage across CE marking, automotive OEM proprietary specs, and India's BIS structural grades to preempt qualification bottlenecks. Backward integration into captive scrap processing or hydrogen direct reduction trials secures low-emission feedstock against substitute technology threats from green steel startups. For New Entrants and Emerging Players: Southeast Asian fabricators in Vietnam, Indonesia, and Philippines present the most penetrable buyer archetype, as domestic rolling capacity lags infrastructure megaproject demand. Hydrogen direct reduction partnerships with renewable power providers unlock premium automotive contract eligibility without legacy blast furnace retrofit burdens. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric arc furnace specialists with scrap supply control in the United States Gulf Coast corridor. Watch hydrogen direct reduction pilot commissioning rates as the inflection signal for premium-grade contract viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Direct Reduction Partnership | Thyssenkrupp and Salzgitter trials at Duisburg and Peine secure automotive eligibility under EU CBAM. |
| Long-term Offtake Contracting | Japanese tier-one fabricators anchor supply security through equity-linked procurement partnerships. |
| Scrap Quality Upgradation | Electric arc furnace routes invest in residual element control for surface-critical automotive applications. |
| Digital Mill Services Platform | Predictive metallurgy subscriptions create recurring revenue from technical support bundling. |
| Renewable Power Purchase Agreement | Direct reduced iron-electric arc furnace complexes electrify cost structures for flat steel production. |
Methodological Framework
Independent corroboration across mill procurement directors, automotive platform engineers, and shipbuilding specification officers underwrites the qualitative findings. Secondary validation draws from customs trade data, SEC 10-K filings, and EIA energy consumption reports. Bottom-up volume modeling triangulates against top-down macroeconomic steel intensity benchmarks.
Rate-of-change decomposition across thickness grades, end-use applications, and regional production clusters structures the analytical framework. CAGRs derive from segment-level volume trajectories calibrated to automotive platform launch schedules and infrastructure investment pipelines. Forecast inputs incorporate China's MEE emissions intensity enforcement and India's PLI scheme disbursement pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen direct reduction technology maturation and EU CBAM tariff-rate finalization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Osmium Market
Metals
Stainless Steel Panels Market
Metals
Neodymium Market
Metals
High Carbon Bearing Steel Market
Metals
North America Aluminum Casting Market
Metals
Transition Metals Market
Metals
Aluminum Slugs Market
Metals
Brazil Aluminum Market
Metals
Cerium Market
Metals
Aluminium Rolled Products Market
Metals
Silver Enamel Market
Metals
Copper Clad Aluminum Wire Market
Metals
Zinc Plating Market
Metals
Galvanized Steel Coil Market
Metals
Colloidal Metal Particles Market
Metals
US Copper Scrap Market