
 Reconditioned Steel Drums Market | 2026-2036
Reconditioned Steel Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Reconditioned Steel Drums Market Analytics
UN 1A2/X certification for steel drums is unwinding informal reconditioners from supply chains serving hazardous chemical shippers. Mauser Packaging Solutions leverages captive collection networks across North America to secure feedstock for its reconditioning plants. Greif sustains integrated drum life-cycle management from new manufacture through reconditioning to recycling. Jakacki Bag & Barrel, Inc. specializes in Midwest industrial accounts requiring documented chain-of-custody for regulated waste containment.
Reconditioned steel drums are used carbon-steel containers, typically 0.9–1.2 mm thick, that undergo cleaning, dent removal, re-rolling, and hydrostatic testing to restore UN performance standards for liquid and solid hazardous materials transport. Tight head drums dominate chemical sector procurement due to their permanent lid construction and superior leak resistance under pressure-vacuum transit conditions. Open head drums capture food and agriculture demand where frequent access simplifies residue cleaning and product changeover. The 55-gallon capacity anchors volume economics, as reconditioning fixed costs spread across standardized units that match global shipping module dimensions.
EPA hazardous waste manifest rules and DOT 49 CFR packaging requirements shape US reconditioner operating permits and testing protocols, while EU REACH downstream user obligations extend producer responsibility to drum traceability. India's BIS certification and China's GB/T 325.1 drum standards create divergent compliance costs for exporters serving both markets. Stakeholders must monitor how carbon-border adjustment mechanisms and recycled-content mandates redefine cost parity between virgin and reconditioned steel packaging.
Market Dynamics
UN certification mandates are systematically expelling informal reconditioners from hazardous chemical supply chains, concentrating feedstock access among operators with documented collection networks and hydrostatic testing capabilities.
Growth Catalysts
- REACH downstream user obligations:EU chemical producers now bear extended producer responsibility for drum traceability, forcing documented reconditioning partnerships over spot-market sourcing.
- Carbon-steel feedstock localization:India's western industrial corridor generates concentrated drum retirement volumes from Gujarat's solvent-handling clusters, creating captive supply pools for certified reconditioners.
- Dual carbon goals:China's MEE enforcement of recycled-content benchmarks in heavy industry procurement specifications elevates reconditioned packaging in state-owned chemical enterprise tenders.
Market Restraints
- Hot-rolled coil volatility:Virgin steel price swings compress reconditioning margin spreads when new drum production costs dip below restoration economics.
- Feedstock concentration:North American collection networks remain dominated by integrated packaging conglomerates, limiting independent reconditioner access to retired drum supply.
- Cross-standard incompatibility:India's BIS certification and China's GB/T 325.1 requirements diverge on hydrostatic test pressures, fragmenting export reconditioner compliance costs.
Strategic Opportunities
- Underpenetrated ASEAN chemical corridors:Vietnam's emerging petrochemical complexes lack established reconditioning infrastructure, creating first-mover positioning for certified operators.
- Digital chain-of-custody platforms:Blockchain-tracked drum lifecycle records enable premium pricing from pharmaceutical shippers requiring audit trails for FDA compliance.
- Open-head drum food-grade expansion:Agricultural processors in Brazil's grain belt seek UN-certified reconditioned units for pesticide and fertilizer handling.
Industry Challenges
- Skilled inspector scarcity:Hydrostatic testing technicians with UN 1A2/X certification command wage premiums that strain mid-cap reconditioner labor costs.
- Legacy equipment retrofit timelines:Automated dent-removal and re-rolling machinery requires 18-24 month deployment cycles, delaying compliance with tightening test-frequency mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconditioned Steel Drums Market |
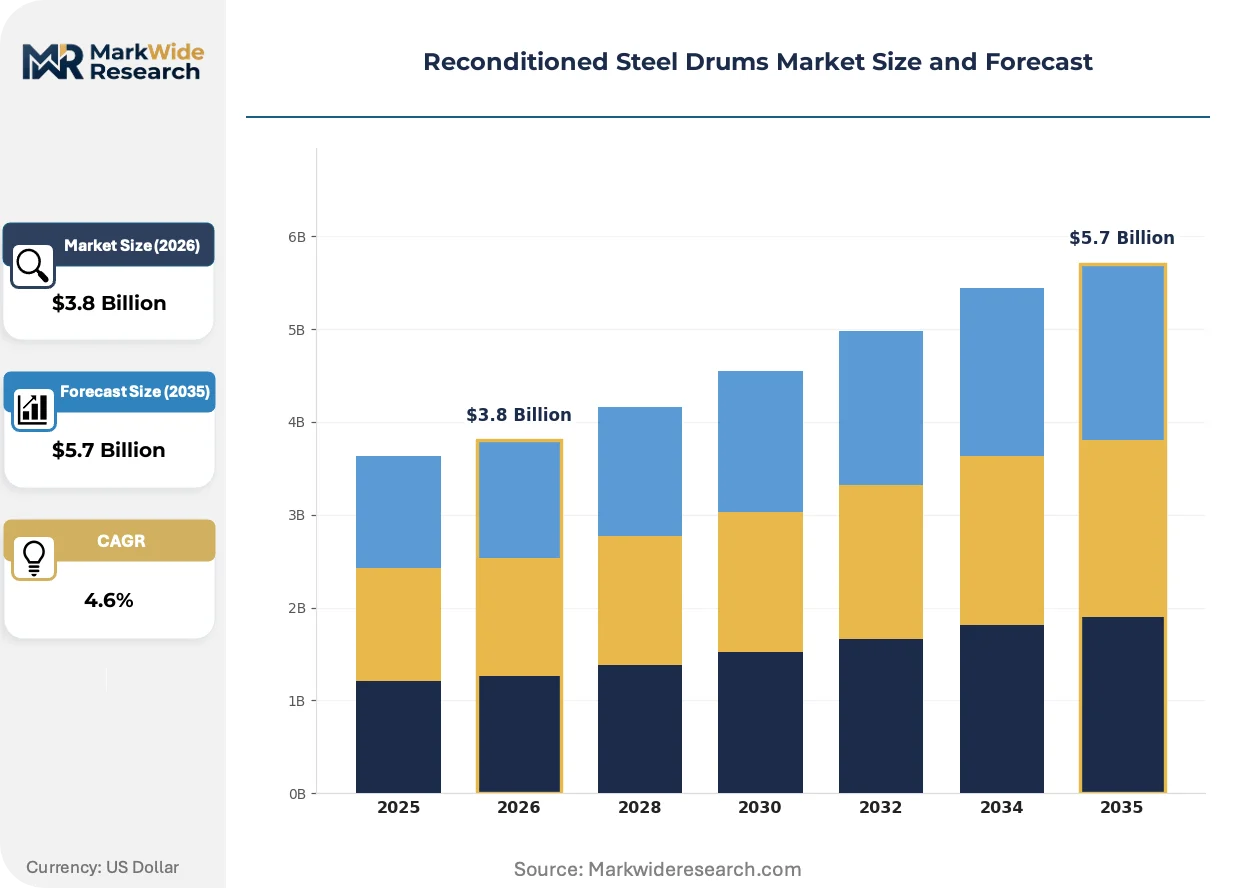
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Head Drums, Tight Head Drums, Specialty Drums, Composite Drums End User: Chemicals, Food & Beverages, Pharmaceuticals, Agriculture Capacity: 10 Gallon, 20 Gallon, 30 Gallon, 55 Gallon Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | The Cary Company, Mauser Packaging Solutions, Jakacki Bag & Barrel, Inc., BascoUSA, North Coast Container, Rahway Steel Drum Company, Kelly Drums, Greif, Container Distributors, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconditioned Steel Drums Market Evolving Landscape
Automation in drum inspection and restoration is compressing unit economics while digital traceability tools are redefining buyer-supplier contracting terms across hazardous material logistics.
Laser-based wall-thickness measurement systems are displacing manual ultrasonic spot-checking in high-volume reconditioning plants. Chemical shippers in Germany's Rhine-Ruhr industrial zone now mandate laser-verified thickness documentation for solvent drum acceptance. This technology is displacing legacy gauge-and-record protocols that allowed subjective inspector discretion.
EU F-Gas Regulation amendments extending containment requirements to fluorinated solvent transport are tightening drum pressure-test specifications. Reconditioners serving refrigeration chemical distributors must now maintain dual certification for both standard hydrocarbon and fluorinated compound handling. The Netherlands' chemical logistics sector is absorbing these compliance costs through longer-term reconditioning contracts.
Consolidated procurement by multinational chemical distributors is compressing supplier rosters to single-digit approved reconditioner lists. Regional drum service providers in Texas and Louisiana are losing direct plant access as buyers centralize packaging decisions at headquarters level. This concentration is most visible in agricultural chemical distribution, where three distributors control two-thirds of North American reconditioned drum volume.
Reconditioned Steel Drums Market Segmentation
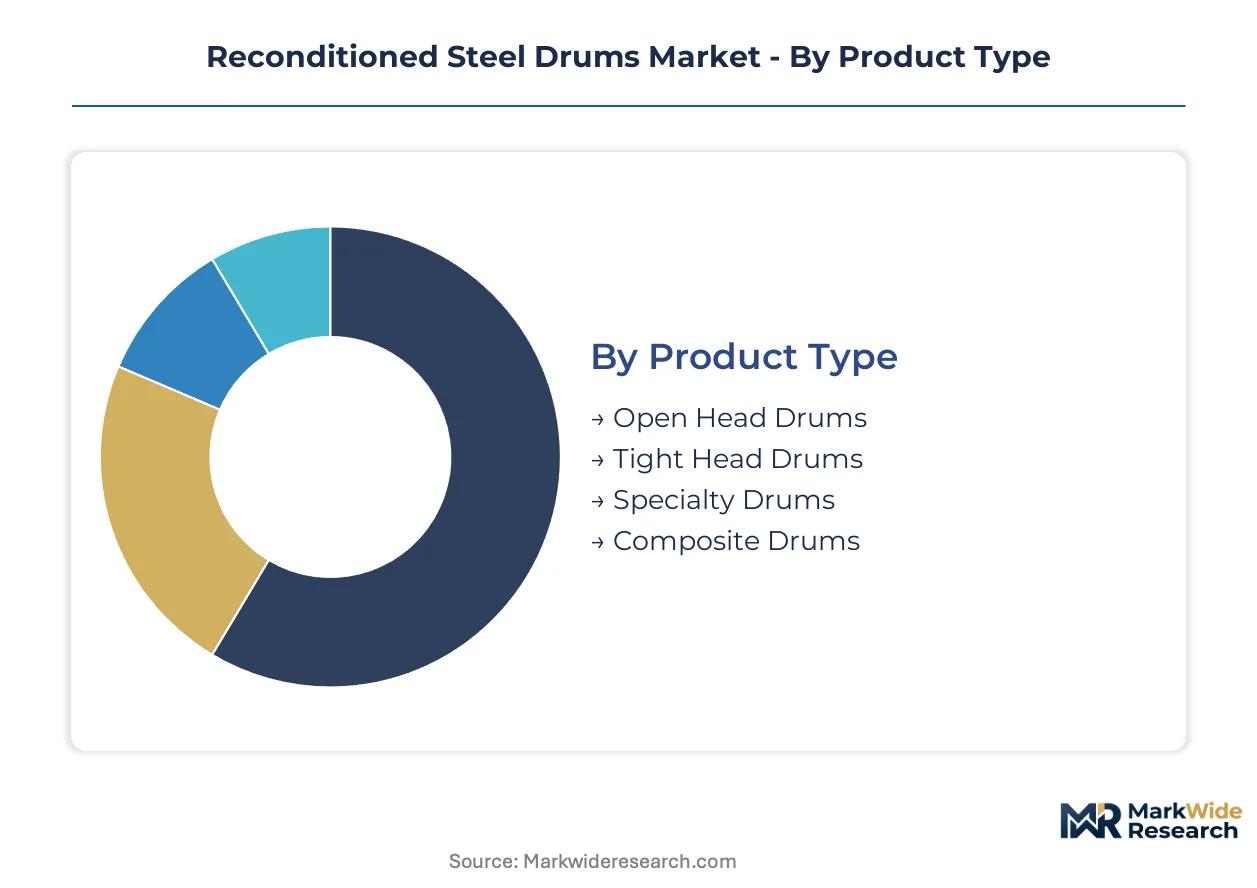
Segmentation in reconditioned steel drums reveals how UN certification tiers, feedstock availability, and end-use hazard classifications create distinct commercial battlegrounds. Procurement patterns diverge sharply between chemical shippers requiring documented chain-of-custody and agricultural buyers prioritizing cost-per-unit economics.
Product Type:
Domestic chemical manufacturers in India and China drive tight head drum volumes, while export-oriented reconditioners in Vietnam and Indonesia specialize in open head formats for ASEAN food processors.
- Tight Head Drums:Permanent lid construction with rolled seams delivers superior leak resistance under pressure-vacuum transit conditions. Demand concentrates in Gujarat's solvent-handling clusters where UN 1A2/X certification is mandatory for hazardous chemical export to EU markets.
- Open Head Drums:Removable lids with bolt-ring or lever-lock closures enable frequent residue cleaning and product changeover. Agricultural processors in Brazil's grain belt and India's Punjab region source these units for pesticide rotation cycles.
- Specialty Drums:Linings, coatings, or modified aperture configurations serve niche pharmaceutical and electronics chemical applications.
- Composite Drums:Steel-plastic hybrid construction addresses lightweight shipping requirements for non-hazardous liquid transport.
Tight head drums hold the largest share; momentum sits with open head drums as agricultural chemical distributors consolidate procurement.
End User:
Chemical sector procurement operates on three-year framework contracts with certified reconditioners, while food and agriculture buyers remain fragmented across spot-market transactions.
- Chemicals:Solvent manufacturers, petrochemical refiners, and specialty chemical formulators constitute the core demand base. REACH downstream user obligations in Germany and the Netherlands now mandate documented reconditioning partnerships with hydrostatic testing traceability.
- Food & Beverages:Edible oil processors and beverage concentrate handlers require food-grade lining restoration with FDA or FSSAI compliance documentation.
- Pharmaceuticals:Active pharmaceutical ingredient shippers demand blockchain-tracked drum lifecycle records for FDA compliance audits.
- Agriculture:Fertilizer and pesticide distributors in India's western corridor and Brazil's Midwest prioritize cost efficiency over certification depth.
Chemicals command the largest share; pharmaceuticals are expanding most quickly as digital traceability requirements harden.
Capacity:
Standardization economics favor 55-gallon units in intermodal shipping corridors, while smaller formats serve localized batch processing in fragmented agricultural markets.
- 55 Gallon:Global shipping module compatibility spreads reconditioning fixed costs across standardized units. India's chemical clusters and US Gulf Coast refiners anchor volume procurement.
- 30 Gallon:Mid-scale batch chemical production and specialty lubricant blending in Japan and South Korea.
- 20 Gallon:Pilot plant operations and sample shipment logistics for chemical R&D facilities.
- 10 Gallon:Laboratory-scale chemical handling and artisanal food processing in fragmented European markets.
55-gallon drums dominate volume; 30-gallon formats are gaining share fastest in precision chemical manufacturing.
Distribution Channel:
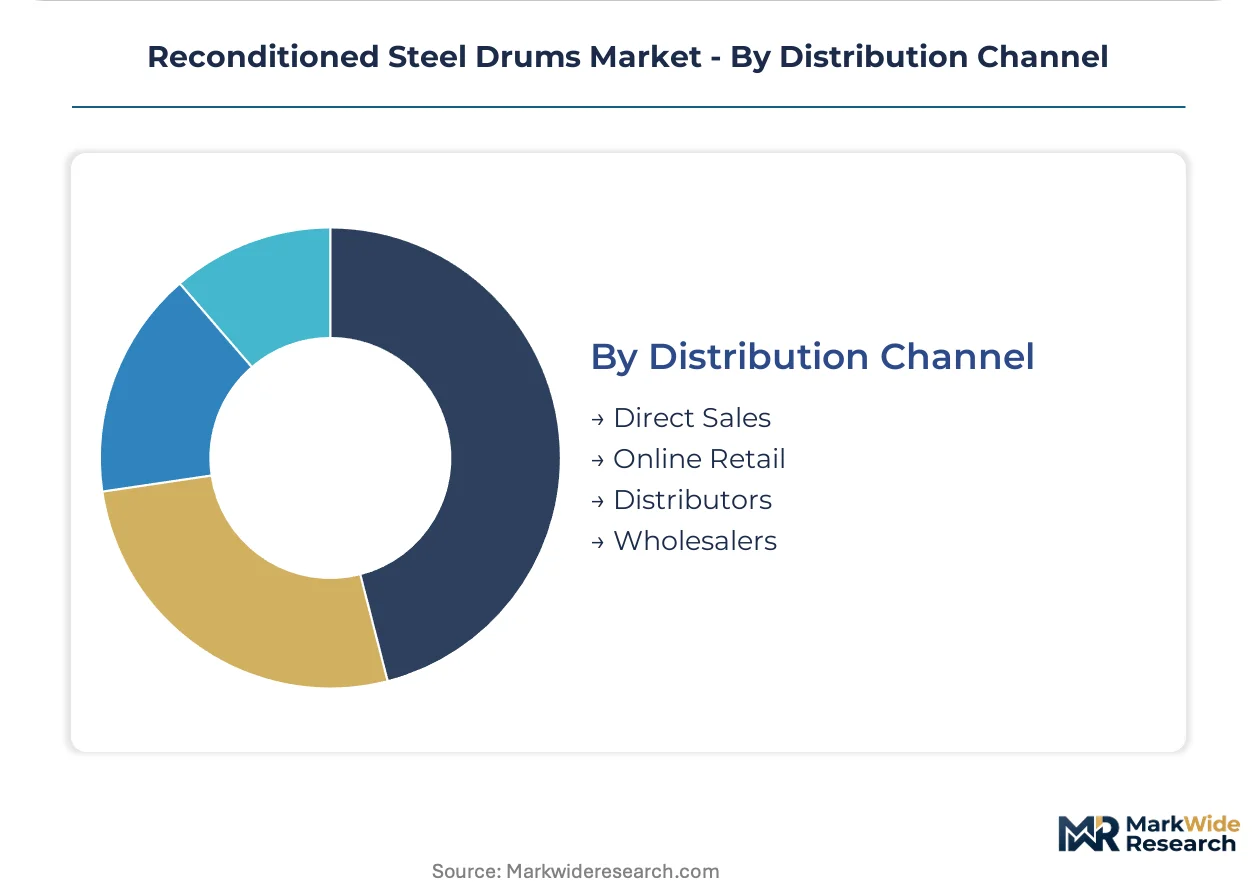
Direct sales relationships with multinational chemical distributors are displacing regional drum service providers as procurement centralizes at headquarters level.
- Direct Sales:Framework contracts with Mauser Packaging Solutions and Greif provide captive collection networks and guaranteed feedstock access. Three agricultural chemical distributors now control two-thirds of North American reconditioned drum volume through direct channels.
- Distributors:Regional aggregators serve mid-cap chemical formulators lacking volume for direct reconditioner relationships.
- Wholesalers:Inventory buffers for spot-market agricultural buyers in Brazil and India.
- Online Retail:Digital platforms emerging for standardized open head drum procurement in fragmented food processing segments.
Direct sales hold the largest share; distributor consolidation is accelerating as procurement decisions centralize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational chemical distributors concentrate procurement decisions in headquarters locations, while regional reconditioners compete for feedstock access through certified collection networks. This geographic split between decision-making authority and operational execution shapes competitive positioning across major markets.
United States
Gulf Coast petrochemical refiners and agricultural chemical blenders drive demand for UN-certified tight head drums. EPA hazardous waste manifest rules and DOT 49 CFR packaging requirements govern reconditioner operating permits across Texas and Louisiana. Houston's chemical logistics corridor anchors the largest concentration of hydrostatic testing facilities serving solvent exporters.
Germany
Rhine-Ruhr industrial zone chemical shippers mandate laser-verified wall thickness documentation for solvent drum acceptance. EU REACH downstream user obligations extend producer responsibility to drum traceability, forcing documented reconditioning partnerships. Leverkusen and Dusseldorf host integrated packaging service providers with captive collection networks.
China
State-owned chemical enterprises elevate reconditioned packaging in procurement specifications under MEE enforcement of recycled-content benchmarks. GB/T 325.1 drum standards for hazardous material transport accelerate formal sector consolidation. Yangtze River Delta petrochemical clusters generate concentrated drum retirement volumes for certified reconditioners.
India
Gujarat's chemical clusters source reconditioned 55-gallon units for bulk solvent handling under tightening UN-certified packaging mandates. BIS quality mark requirements for hazardous material transport disqualify informal reconditioners from export supply chains. Mumbai-Pune industrial corridor distributors consolidate procurement through direct framework contracts with certified operators.
Brazil
Agricultural processors in the grain belt seek UN-certified reconditioned open head drums for pesticide and fertilizer handling. ANVISA pharmaceutical regulations extend traceability requirements to active ingredient shippers. São Paulo state's chemical distributors centralize packaging decisions, compressing regional drum service provider access.
Reconditioned Steel Drums Market Competitive Landscape
Player mix skews toward integrated packaging conglomerates with captive collection networks and independent reconditioners serving spot-market agricultural buyers. Market structure concentrates feedstock access among operators with documented hydrostatic testing capabilities and UN certification maintenance. Three archetypes dominate: vertically integrated life-cycle managers, regional specialists with documented chain-of-custody expertise, and scale-driven commodity reconditioners. Competitive moves center on collection network expansion through strategic partnerships and automation deployment to compress unit restoration economics.
Within the integrated life-cycle management tier, Mauser Packaging Solutions and Greif exemplify operators controlling drum flow from new manufacture through reconditioning to recycling. Jakacki Bag & Barrel, Inc. occupies a specialist position serving Midwest industrial accounts with regulated waste containment requirements. These three anchors illustrate how certification depth and geographic coverage determine competitive positioning.
| Leading Market Players |
|---|
| The Cary Company |
| Mauser Packaging Solutions |
| Jakacki Bag & Barrel, Inc. |
| BascoUSA |
| North Coast Container |
| Rahway Steel Drum Company |
| Kelly Drums |
| Greif |
| Container Distributors, Inc. |
| Others |
Value Network & Pricing Analysis
Substitution of laser-based wall-thickness measurement systems for manual ultrasonic spot-checking is redrawing supply geography toward Germany's Rhine-Ruhr industrial zone while compressing restoration economics for reconditioners lacking capital for automated inspection deployment.
Pricing Analysis
Cost-plus contracts indexed to hot-rolled coil futures govern long-term procurement between Gulf Coast petrochemical refiners and integrated packaging conglomerates. Pricing stratifies across UN 1A2/X-certified premium tiers, standard BIS-compliant grades for Indian chemical exports, and economy open-head units for Brazilian agricultural buyers. Cost compression in the economy tier is intensifying as informal reconditioners in South Asia undercut certified operators on spot-market transactions. Agricultural distributors in Brazil and India's Punjab region exhibit highest price sensitivity, while German solvent shippers prioritize documented chain-of-custody over unit cost.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta port congestion and container availability constraints on Asia-Europe trade lanes are elevating landed costs for Indian reconditioners sourcing feedstock from Chinese petrochemical clusters. Supply concentrates in India, China, and the United States as formal sector consolidation expels informal operators. Feedstock draws from retired 55-gallon drums generated by Gujarat's solvent-handling clusters, Texas Gulf Coast refiners, and Leverkusen chemical logistics corridors. Single-source vulnerability from Mauser Packaging Solutions and Greif captive collection networks in North America fragments independent reconditioner access. Distribution runs through direct framework contracts with multinational chemical distributors, compressing regional drum service provider participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-tracked drum lifecycle platforms are creating platform-economics inflection as pharmaceutical shippers demand audit-trail interoperability with FDA compliance systems.
For Market Incumbents: Secure hydrostatic testing technician pipelines through apprenticeship partnerships with German TÜV certification bodies before wage premiums erode mid-cap operator margins. Deepen backward integration into captive collection networks across India's western industrial corridor to defend feedstock access against emerging ASEAN competitors. Counter threat from digital-native reconditioners by embedding laser-verified thickness documentation into standard contract terms. For New Entrants and Emerging Players: UN 1A2/X certification fast-track through Netherlands-based Notified Body partnerships opens first-mover positioning in Vietnam's emerging petrochemical corridors where established reconditioning infrastructure remains absent. Target Brazil's grain belt agricultural processors with open-head drum food-grade restoration capabilities. Pursue white-label digital chain-of-custody platform licensing to pharmaceutical distributors seeking FDA-compliant audit trails without captive technology investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated life-cycle managers with documented collection networks over commodity reconditioners exposed to hot-rolled coil volatility. Long-term viability hinges on regulatory enforcement trajectories rather than demand cyclicality. Prioritize acquisition targets possessing dual UN 1A2/X and BIS certification maintenance capabilities spanning India and EU export corridors. Watch MEE enforcement intensity on China's recycled-content benchmarks as inflection indicator for state-owned enterprise procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Collection Networks | Mauser Packaging Solutions and Greif control feedstock access across North American chemical corridors. |
| Laser-Based Inspection Technology Deployment | German Rhine-Ruhr shippers now mandate automated wall-thickness verification for solvent drum acceptance. |
| Dual Certification Maintenance (UN 1A2/X + BIS) | Indian chemical exporters require both marks for Gujarat cluster access to EU and domestic markets. |
| Digital Chain-of-Custody Platform Development | Blockchain-tracked lifecycle records enable premium pricing from pharmaceutical FDA compliance shippers. |
| ASEAN Geographic Expansion | Vietnam's petrochemical complexes lack established reconditioning infrastructure for first-mover positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with reconditioning plant managers, procurement leads at multinational chemical distributors, hydrostatic testing technicians with UN 1A2/X certification, and regulatory compliance officers at BIS and GB standards bodies. Secondary validation drew from customs and trade data on steel drum movements, SEC filings of integrated packaging conglomerates, EPA hazardous waste manifest databases, and ECHA REACH downstream user obligation guidance documents. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across the analysis window.
Across the modeling period, forecasts incorporate reconditioning throughput capacity by plant certification tier, hot-rolled coil price index trajectories, and UN mandate enforcement intensity by national regulator. Segmentation dimensions include tight head versus open head drum formats, chemical versus agricultural end-use sectors, 55-gallon standard versus specialty capacity units, and direct sales versus distributor channel structures. CAGRs derive from regression analysis against feedstock availability indices and regulatory compliance cost escalation curves.
Decision-makers should treat outputs as directional under assumptions of continued UN certification mandate tightening and formal sector consolidation in India and China; material deviation through regulatory rollback or virgin steel price collapse would warrant model refresh. Forecasts reflect base-case assumptions on MEE enforcement trajectories and EU F-Gas Regulation amendment implementation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
North America Metal Casting Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Iron Casting Market
Metals
Global Copper Sputtering Target Market
Metals
High Purity Iron Powder Market
Metals
Tungsten Metal Powder Market
Metals
Carbon Steel Market
Metals
High Purity Base Metals Market
Metals
Global Mercury Market
Metals
Global Steel Market
Metals
Aluminium Conductors Market
Metals
Anodized Titanium Market
Metals
Platinum Compounds Market
Metals
Wear Steel Plate Market
Metals
Barium Market
Metals
Ore Metals Market