
 Nickel Oxide Target Market | 2026-2036
Nickel Oxide Target Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel Oxide Target Market Analysis
REACH chemical registration is recalibrating the cost-of-entry calculus for European nickel oxide target suppliers, forcing reformulation investments and supply chain documentation upgrades. Sumitomo Metal Mining Co leverages captive nickel refining to sustain cost advantages across electronics-grade target production. Norilsk Nickel anchors its position through Arctic mining assets that control upstream feedstock access. Mitsubishi Materials Corporation differentiates via precision sintering capabilities for high-purity disc and pellet geometries.
A nickel oxide target is a consolidated ceramic or metallic disc, pellet, or sheet composed primarily of nickel monoxide (NiO) with controlled stoichiometry, typically exceeding 99.9% purity for electronics applications, manufactured through hot isostatic pressing or vacuum sintering for use as a cathode material in physical vapor deposition systems. Battery-grade targets command widening demand from solid-state lithium-ion research programs, while electronics-grade formulations retain the largest revenue pool due to semiconductor foundry qualification cycles. Powder-form feedstock competes aggressively on unit economics, though pellet and disc configurations capture margin premiums from sputtering equipment OEMs seeking pre-qualified geometries.
EPA hazardous substance reporting and China's GB standards for electronic materials impose divergent testing protocols that fragment certification costs across export-bound producers. Japan's METI energy storage directives and South Korea's MFDS industrial chemical frameworks further complicate multi-jurisdiction compliance for target manufacturers. Stakeholders must monitor evolving purity thresholds in next-generation battery chemistries and deposition equipment scaling requirements before committing capacity expansion decisions.
Market Dynamics
Physical vapor deposition equipment scaling and next-generation battery chemistry qualification cycles are compressing target specification timelines while fragmenting certification requirements across East Asian manufacturing clusters.
Growth Catalysts
- Solid-state battery research programs:South Korean cathode manufacturers are expanding sputtering target procurement for lithium-metal anode interface layers, pulling high-purity nickel oxide demand into pilot production lines.
- EU REACH chemical registration:The framework's substance evaluation protocols are forcing electronics-grade target reformulation, creating first-mover advantages for suppliers with pre-registered dossiers.
- Hot isostatic pressing advances:Japanese sintering equipment OEMs are qualifying next-generation HIP cycles that reduce grain boundary contamination below 50ppm thresholds.
Market Restraints
- Arctic feedstock concentration:Primary nickel refining capacity clusters in Russian Arctic mining districts, exposing target manufacturers to sanctions-related supply interruption risks.
- EPA hazardous substance reporting:The Toxic Substances Control Act inventory update requirements impose documentation burdens that lengthen export qualification timelines for US-bound shipments.
- Powder-form substitution:Battery researchers are evaluating direct powder deposition methods that bypass sputtering targets entirely in certain solid-state cell architectures.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:The production-linked incentive framework is attracting cathode material investments that will require localized sputtering target supply.
- Thin-film photovoltaic integration:Perovskite-silicon tandem cell manufacturers are evaluating nickel oxide buffer layers, opening deposition equipment qualification outside traditional semiconductor channels.
- China's dual carbon goals:The MIIT energy storage deployment mandates are accelerating grid-scale battery manufacturing, expanding target demand from research into volume production.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous compliance with China's GB standards, Japan's JIS specifications, and EU REACH dossier requirements stretches technical documentation teams across 18-24 month qualification windows.
- Sintering furnace capacity constraints:Electronics-grade target production requires specialized vacuum furnaces with 99.999% atmosphere purity, equipment that carries 24-month delivery lead times from German and Japanese suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel Oxide Target Market |
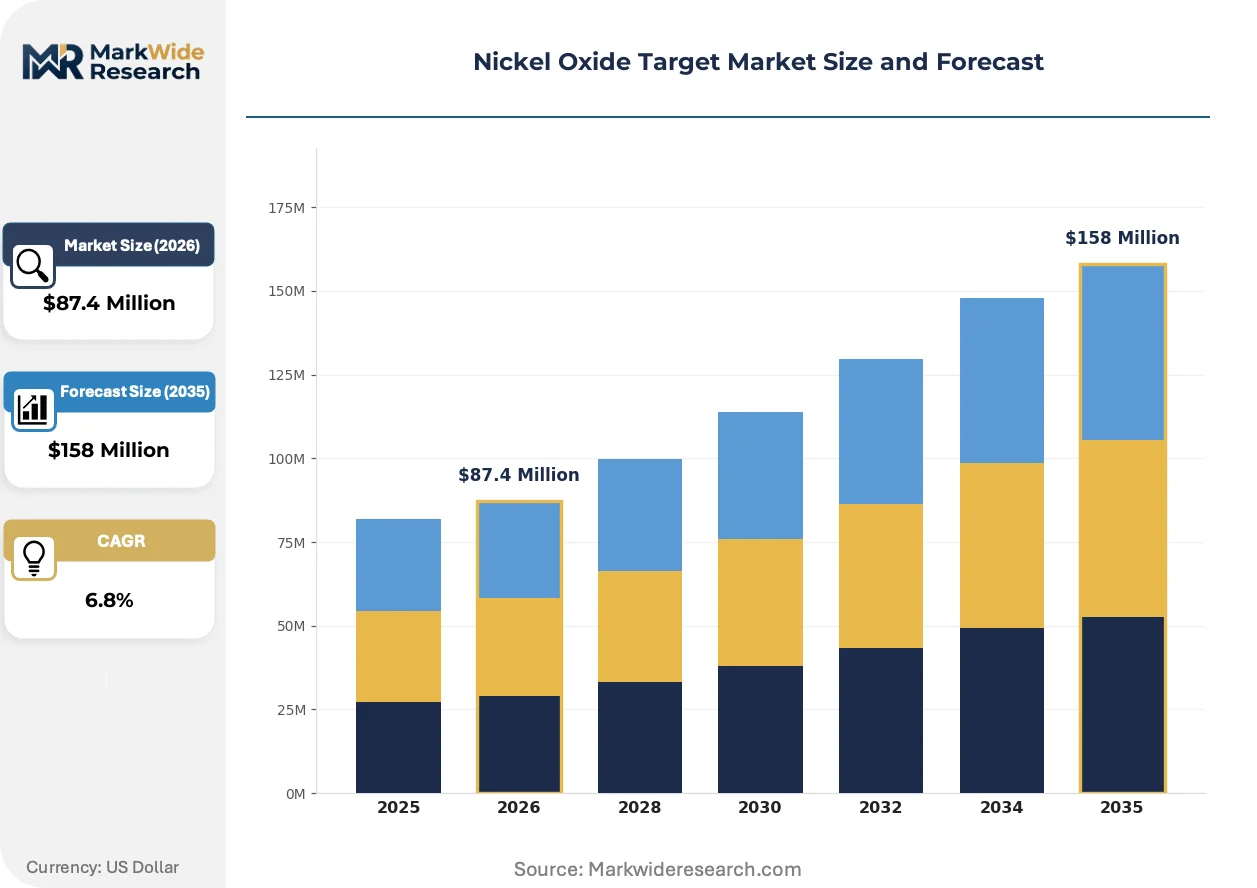
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Electronics Grade, Battery Grade, Catalyst Grade Application: Ceramics, Batteries, Electronics, Coatings End User: Manufacturers, Research Laboratories, Electronics Firms, Automotive Suppliers Form: Powder, Pellets, Sheets, Discs |
| Companies Covered | Stanford Advanced Materials, Sumitomo Metal Mining Co, Norilsk Nickel, Umicore, Mitsubishi Materials Corporation, Cathay Advanced Materials Limited, Materion, Able Target Limited, Testbourne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel Oxide Target Market Emerging Trajectories
Deposition equipment OEMs are tightening geometric tolerance specifications while battery researchers push stoichiometry boundaries, forcing target manufacturers to reconcile conflicting purity and form-factor demands.
Hot isostatic pressing with argon atmosphere control is consolidating vacuum sintering as the dominant consolidation method for sub-100nm grain structures. Semiconductor foundries in Taiwan and South Korea are mandating HIP-certified suppliers for 3nm node barrier layer deposition. The technology is consolidating supplier bases by disqualifying conventional pressureless sintering operations from advanced node qualification lists.
China's GB standards for electronic materials are tightening trace metal specifications below 10ppm for cobalt and copper contaminants. The MIIT standards revision imposes batch-level testing protocols that extend manufacturing cycle times by 15-20%. Japanese sputtering target fabricators are responding by establishing in-country testing laboratories to bypass cross-border certification delays.
Long-term supply agreements are displacing spot market procurement for battery-grade targets as cathode manufacturers lock in qualification-matched supply streams. South Korean battery OEMs are consolidating vendor lists to three approved suppliers per chemistry type, forcing mid-tier target manufacturers into tolling arrangements with qualified peers. The shift is most visible in Gwangju and Ochang industrial complexes where cathode production capacity has quadrupled since 2022.
Nickel Oxide Target Market Segmentation
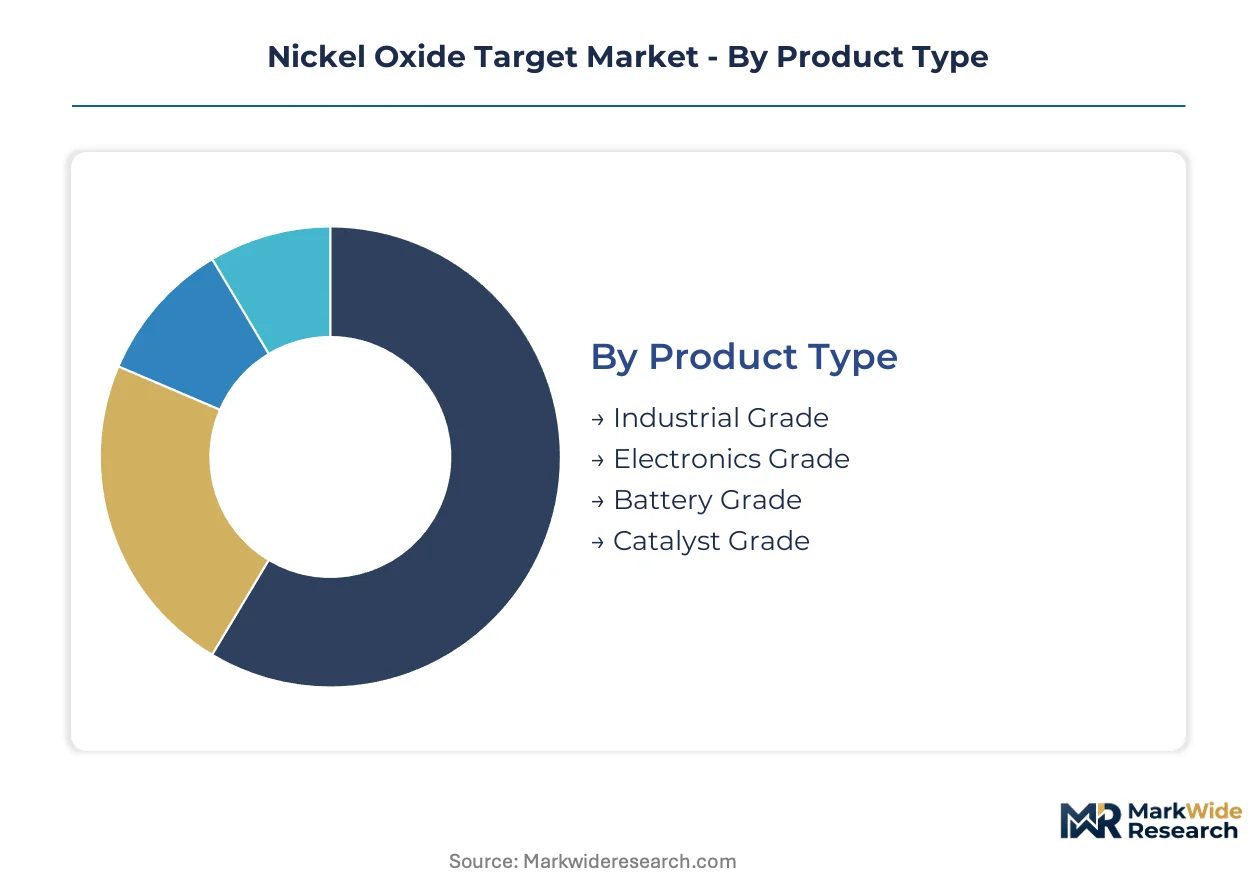
Target specification diverges sharply across deposition equipment generations and battery chemistry platforms, forcing suppliers to maintain parallel production lines with incompatible purity protocols. Sputtering equipment OEMs and cathode manufacturers now drive segmentation through qualification-matched procurement rather than commodity spot purchasing.
Product Type:
Buyer procurement teams weight purity thresholds against deposition yield losses and battery cycle degradation risks when selecting grade tiers.
- Electronics Grade:Targets exceed 99.9% purity with controlled stoichiometry for semiconductor barrier layer deposition. Taiwan and South Korea foundries mandate HIP-certified suppliers for 3nm node qualification, compressing vendor lists to pre-approved dossiers.
- Battery Grade:Formulations balance nickel monoxide ratios for solid-state lithium-ion interface layers. South Korean cathode manufacturers in Gwangju and Ochang industrial complexes are locking in multi-year supply agreements for pilot production lines.
- Industrial Grade:Standard purity levels serve ceramic pigment and general coating applications with less stringent trace metal limits.
- Catalyst Grade:Controlled surface area specifications support chemical process applications outside electronics and energy storage channels.
Volume sits with Electronics Grade; growth tilts toward Battery Grade.
Application:
End-use specification timelines stretch from 6-month ceramic qualification cycles to 24-month semiconductor foundry certification windows.
- Electronics:Physical vapor deposition for thin-film transistors and barrier layers dominates revenue concentration. Japanese sputtering target fabricators maintain qualification advantages through in-country testing laboratories that bypass cross-border certification delays.
- Batteries:Solid-state research programs and grid-scale manufacturing expansion are pulling high-purity demand from pilot into volume production. China's MIIT energy storage mandates accelerate cathode material investments requiring matched target supply.
- Ceramics:Traditional refractory and pigment applications maintain steady procurement with established purity protocols.
- Coatings:Functional surface treatments for corrosion resistance operate at lower specification tiers than electronics or battery channels.
Electronics commands current procurement volumes; battery applications are climbing the fastest.
End User:
Procurement authority concentrates with technical qualification teams rather than commodity purchasing departments across all user categories.
- Electronics Firms:Semiconductor foundries and display panel manufacturers impose geometric tolerance specifications below 50ppm grain boundary contamination thresholds. Taiwan-based deposition equipment OEMs are consolidating approved supplier lists to three vendors per chemistry type.
- Automotive Suppliers:Battery cell manufacturers are extending qualification-matched supply agreements to secure cathode material consistency for electric vehicle programs. South Korean battery OEMs have quadrupled cathode production capacity since 2022.
- Research Laboratories:Solid-state battery research programs in university and national lab settings drive small-batch procurement for stoichiometry experimentation.
- Manufacturers:Industrial ceramic and coating producers maintain spot market purchasing with shorter qualification cycles.
Electronics Firms anchor procurement volumes; Automotive Suppliers are gaining share fastest.
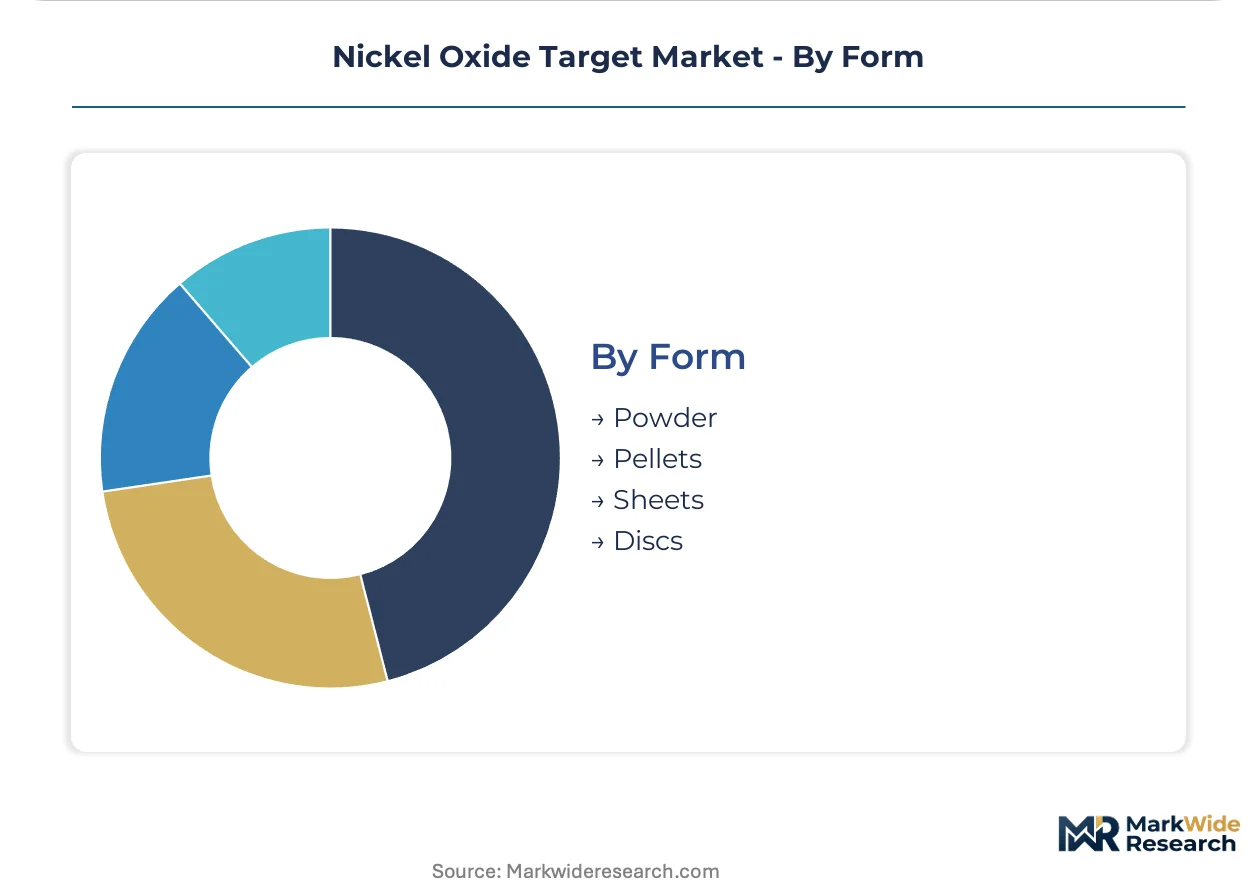
Form:
Equipment integration requirements and deposition method selection determine form factor procurement across user segments.
- Discs:Precision-sintered geometries for rotating cathode sputtering systems capture margin premiums from equipment OEMs seeking pre-qualified configurations. Japanese suppliers differentiate through vacuum sintering capabilities for sub-100nm grain structures.
- Pellets:Cylindrical configurations serve electron beam evaporation and specialized PVD systems with intermediate purity requirements between powder and disc specifications.
- Powder:Direct powder deposition methods compete aggressively on unit economics for certain solid-state cell architectures, though sputtering targets retain qualification advantages in volume production.
- Sheets:Planar geometries support planar magnetron sputtering configurations for large-area coating applications.
Discs dominate revenue concentration; powder forms are expanding most quickly in battery research channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian electronics manufacturing clusters concentrate procurement volumes for nickel oxide targets, with South Korean battery cathode facilities and Japanese sputtering target fabrication centers anchoring demand-side density.
China
MIIT energy storage deployment mandates accelerate grid-scale battery manufacturing, expanding target demand from research into volume production. GB standards for electronic materials tighten trace metal specifications below 10ppm for cobalt and copper contaminants. Yangtze River Delta industrial zones host cathode material investments requiring localized sputtering target supply chains.
Japan
METI energy storage directives drive solid-state lithium-ion research programs, pulling high-purity nickel oxide demand into pilot production lines. JIS specifications for sputtering targets mandate batch-level testing protocols that extend manufacturing cycle times. Kanto and Kansai regions concentrate precision sintering capabilities for sub-100nm grain structures.
South Korea
Battery OEMs quadruple cathode production capacity since 2022, consolidating vendor lists to three approved suppliers per chemistry type. MFDS industrial chemical frameworks complicate multi-jurisdiction compliance for target manufacturers. Gwangju and Ochang industrial complexes anchor qualification-matched procurement for solid-state battery interface layers.
United States
EPA hazardous substance reporting under the Toxic Substances Control Act imposes documentation burdens that lengthen export qualification timelines. Semiconductor foundries mandate HIP-certified suppliers for advanced node barrier layer deposition. Pacific Northwest and Southwest regions host thin-film photovoltaic research evaluating nickel oxide buffer layers for perovskite-silicon tandem cells.
Germany
EU REACH chemical registration framework forces electronics-grade target reformulation, creating first-mover advantages for suppliers with pre-registered dossiers. ECHA substance evaluation protocols recalibrate cost-of-entry calculus for European nickel oxide target suppliers. Bavaria and Baden-Württemberg industrial corridors concentrate deposition equipment OEMs tightening geometric tolerance specifications.
Nickel Oxide Target Market Vendor Landscape
East Asian producers anchor the premium-tier supply base; European and North American specialists hold positions in regional compliance-heavy segments. The vendor structure consolidates around three strategic tiers: diversified mining conglomerates with captive nickel refining, precision ceramics fabricators with HIP-certified production lines, and regional tolling specialists serving mid-tier cathode manufacturers. Capacity expansion and qualification-matched supply agreements represent the dominant competitive moves as battery OEMs lock in multi-year procurement streams.
Within the diversified mining conglomerate tier, Norilsk Nickel and Sumitomo Metal Mining Co exemplify upstream-integrated positioning through Arctic mining assets and captive refining operations respectively. Mitsubishi Materials Corporation anchors the precision ceramics fabricator archetype, representing Japanese sintering capabilities for high-purity disc and pellet geometries. Stanford Advanced Materials occupies a position among North American suppliers navigating EPA documentation requirements for US-bound qualification cycles.
| Leading Market Players |
|---|
| Stanford Advanced Materials |
| Sumitomo Metal Mining Co |
| Norilsk Nickel |
| Umicore |
| Mitsubishi Materials Corporation |
| Cathay Advanced Materials Limited |
| Materion |
| Able Target Limited |
| Testbourne |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals and MIIT energy storage mandates gate qualified supply for nickel oxide targets, restricting premium-tier pricing access to manufacturers with verified low-carbon refining credentials and GB standards compliance. Electronics-grade formulations command substantial premiums from semiconductor foundries, while battery-grade suppliers face margin compression from cathode manufacturers consolidating vendor lists.
Pricing Analysis
Short lead-time premiums dominate pricing structures, with 24-month sintering furnace delivery cycles from German and Japanese OEMs forcing buyers to pay substantial markups for spot availability versus contracted allocation. Three-tier pricing structure across premium, standard, and economy levels separates HIP-certified electronics-grade targets from battery-grade formulations and industrial-grade powder. Cost compression in battery-grade tiers is intensifying because South Korean cathode manufacturers have consolidated procurement to three approved suppliers per chemistry type. Research laboratories exhibit highest price sensitivity due to small-batch procurement volumes, while semiconductor foundries show lowest sensitivity given qualification-matched supply requirements.
Supply Chain Analysis
Certification and qualification gating fragments supply chains, with GB standards, JIS specifications, and EU REACH dossier requirements stretching technical documentation across 18-24 month windows. Primary supply concentrates in China, Japan, and South Korea, where Yangtze River Delta, Kanto, and Gwangju industrial zones anchor cathode and sputtering target fabrication. Feedstock draws from Arctic nickel refining districts and captive Southeast Asian refining operations. Single-source vulnerability runs through Russian Arctic mining assets exposed to sanctions-related interruption. Distribution runs through long-term supply agreements displacing spot procurement as battery OEMs lock in qualification-matched streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vacuum furnace capacity constraints prop pricing power for qualified suppliers, creating a supply-constrained market structure favoring incumbents with secured equipment allocation.
For Market Incumbents: Anchor defensive positioning through captive nickel refining integration and pre-registered EU REACH dossiers that create first-mover advantages against reformulation requirements. Sumitomo Metal Mining Co exemplifies upstream control sustaining cost advantages; competitors should mirror this through backward integration into feedstock. Powder-form substitution threats from direct deposition battery research demand accelerated R&D in stoichiometry-controlled interface layers. For New Entrants and Emerging Players: Direct-to-research-laboratory digital channels offer the most penetrable entry vector, bypassing 24-month semiconductor foundry qualification cycles. India's PLI scheme for advanced chemistry cells presents white-space demand as cathode investments require localized sputtering target supply. Thin-film photovoltaic integration for perovskite-silicon tandem cells offers second entry angle outside traditional electronics channels. Technical content marketing through deposition equipment OEM partnerships provides the strongest go-to-market mechanism. For Investors and Strategic Acquirers: South Korean battery OEM vendor list consolidation to three approved suppliers per chemistry type is the leading indicator that qualification-matched supply agreements are becoming the dominant procurement mode. Long-term viability rests on positioning within 5-10 year solid-state battery commercialization windows. Acquisition targets should display precision sintering capabilities with HIP certification and established relationships with Taiwan or South Korea foundries. Watch for MIIT standards revision implementation as the signal triggering capacity expansion decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Refining | Captive feedstock access insulates against Arctic supply disruption risks from sanctions exposure. |
| HIP Certification Investment | Taiwan foundries mandate HIP-certified suppliers for 3nm node barrier layer qualification. |
| India PLI Localization | Production-linked incentives attract cathode investments requiring matched sputtering target supply. |
| EU REACH Dossier Pre-registration | ECHA substance evaluation protocols reward first-movers with reformulation cost advantages. |
| Perovskite Photovoltaic Qualification | Deposition equipment OEMs outside semiconductor channels expand addressable market scope. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across sputtering equipment OEMs, cathode procurement leads, vacuum furnace operators, semiconductor foundry qualification teams, and battery R&D directors. SEC 10-K disclosures, MIIT standards documentation, ECHA registration databases, and Japanese METI policy filings provided validation layers. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates.
Granularity-level modeling operated at product type, application, end user, and form factor dimensions, with additional resolution for purity grade tiers and geographic regulatory clusters. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion across the analysis window. Forecast inputs incorporated sintering furnace delivery lead times, solid-state battery research program funding trajectories, and deposition equipment scaling requirements from Taiwan and South Korea foundries.
The model holds under stable regulatory enforcement timelines and continued semiconductor node advancement; deviation in Arctic feedstock access restrictions or powder-form deposition technology breakthroughs would shift capacity planning assumptions. Forecasts reflect documented qualification cycle durations, furnace capacity constraints, and cathode manufacturer vendor consolidation patterns. A model refresh is warranted upon material change in EU REACH substance evaluation protocols or MIIT energy storage deployment mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Wire Rods Market
Metals
Galvanizing Market
Metals
Metal Casting Market
Metals
Global Galvanized Steel Wire Market
Metals
Global Welding Powder Market
Metals
Nickel Market
Metals
Lightweight Aluminium Pistons Market
Metals
Amorphous Metal Cores Market
Metals
Saudi Arabia Aluminum Market
Metals
Refined Nickel Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Steel Ingots Market
Metals
Niobium Market
Metals
Flat-Rolled Stainless Steel Market
Metals
Medium Carbon Steel Market
Metals
Galvanized Steel Market