
 Ultrafine Tungsten Wire for Medical Applications Market | 2026-2036
Ultrafine Tungsten Wire for Medical Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrafine Tungsten Wire for Medical Applications Market Intelligence
The EU Green Deal and associated medical device sustainability reporting under CSRD is decoupling procurement from legacy suppliers lacking carbon-transparent refining. Elmet Technologies leverages captive tungsten powder processing to sustain cost advantages in drawn wire grades. Plansee anchors European supply through its Austrian refractory metals complex. Nippon Tungsten Co. competes on ultra-fine diameter consistency below 25 microns for neurovascular catheter cores.
Ultrafine tungsten wire for medical applications denotes pure or doped tungsten filaments typically manufactured below 100 microns through diamond die drawing, intermediate annealing, and surface oxide reduction to achieve tensile strengths exceeding 400 ksi for load-bearing catheter components. Drawn wire dominates current volume due to its use in guidewire cores requiring high modulus and radiopacity, while alloyed wire containing rhenium captures expanding margin pools in neurostimulation leads demanding enhanced fatigue resistance. Endoscopy applications remain mature with stable replacement demand, whereas radiation therapy positioning wires represent the fastest structural expansion as proton beam systems proliferate.
FDA quality system regulation under 21 CFR Part 820 and EU MDR technical documentation requirements are elevating batch-level material certification as a market access gate, forcing wire producers to implement automated dimensional inspection and full chemical assay reporting. Japan's PMDA and METI coordinate on tungsten biocompatibility testing protocols for permanent implant leads, adding regulatory layers distinct from North American and European pathways. Stakeholders must monitor evolving MDR notified body capacity constraints and FDA inspection backlogs that could delay supplier qualification timelines for new wire specifications.
Market Dynamics
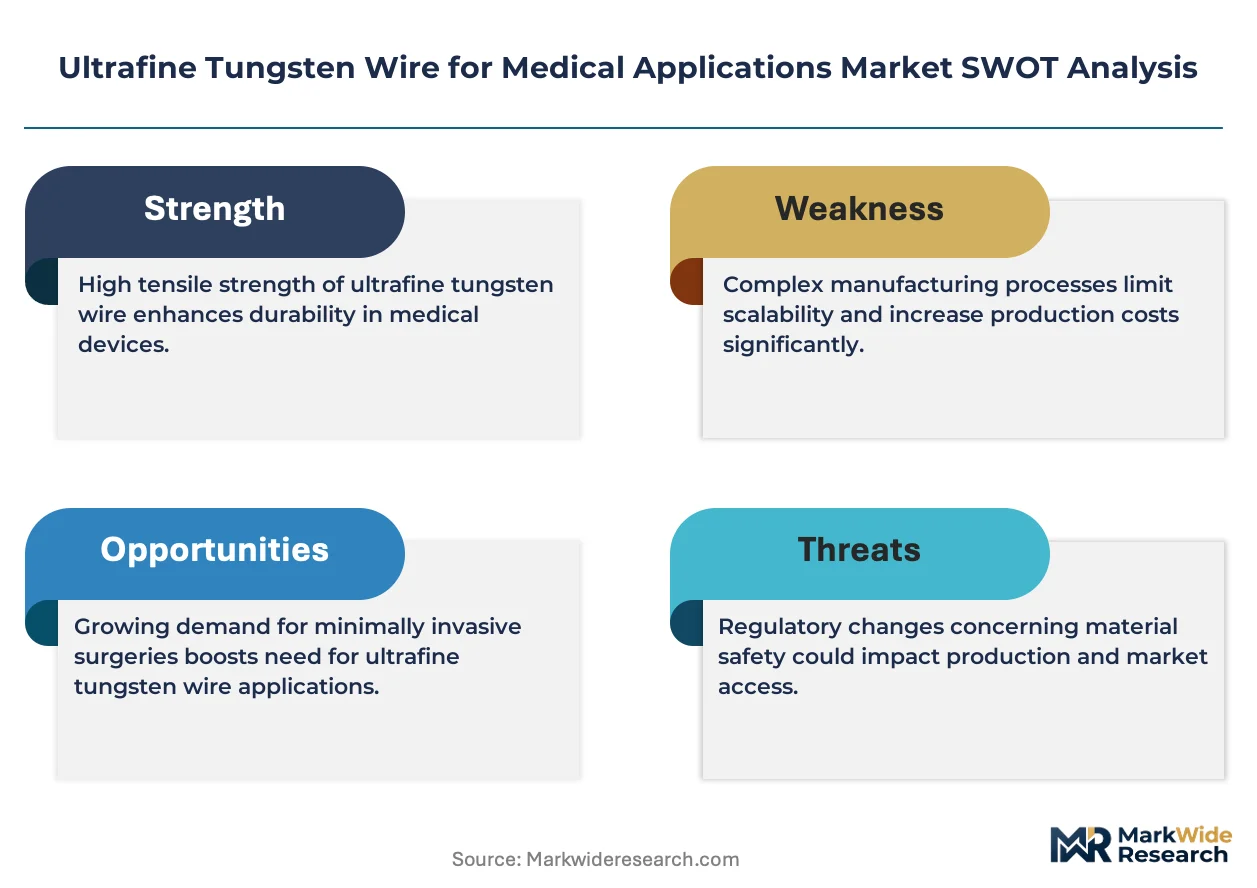
EU MDR batch-level material certification requirements are restructuring supplier qualification timelines, forcing wire producers to deploy automated dimensional inspection systems and full chemical assay reporting before market access.
Growth Catalysts
- Neurostimulation lead demand:Device manufacturers are expanding procurement of drawn wire configurations for deep-brain and spinal cord stimulation systems requiring fatigue-resistant cores.
- EU Green Deal carbon transparency:Medical device sustainability reporting under CSRD is decoupling procurement from legacy suppliers lacking carbon-transparent refining credentials.
- Proton beam therapy proliferation:Radiation therapy positioning wires represent structural expansion as precision oncology infrastructure deploys across tertiary care networks.
Market Restraints
- Tungsten concentrate supply concentration:Primary ore processing concentrates in China, creating geopolitical exposure for European and North American wire draw operations.
- EU MDR notified body capacity constraints:Limited certification bandwidth is extending supplier qualification timelines for new wire specifications by 12-18 months.
- Rhenium alloy cost volatility:Rhenium-doped wire grades face input cost pressure from aerospace superalloy competition for the same scarce refractory metal feedstock.
Strategic Opportunities
- Japan permanent implant protocols:PMDA-METI biocompatibility testing frameworks for tungsten leads create first-mover advantage for suppliers completing extended cytotoxicity and sensitization studies.
- Guidewire core miniaturization:Sub-25 micron diameter consistency capabilities unlock neurovascular catheter OEM contracts currently served by limited qualified suppliers.
- CSRD-aligned carbon accounting:Captive tungsten powder processing with documented Scope 3 emissions positions suppliers for premium tier procurement from sustainability-mandated hospital networks.
Industry Challenges
- Diamond die drawing expertise scarcity:Intermediate annealing and surface oxide reduction process control requires specialized metallurgists with 10+ years refractory wire experience.
- FDA 21 CFR Part 820 inspection backlogs:Quality system audits for new wire specifications face scheduling delays that compress product launch windows.
- Legacy ERP integration with automated inspection:Batch-level material certification requires real-time dimensional data feeds that conflict with established manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrafine Tungsten Wire for Medical Applications Market |
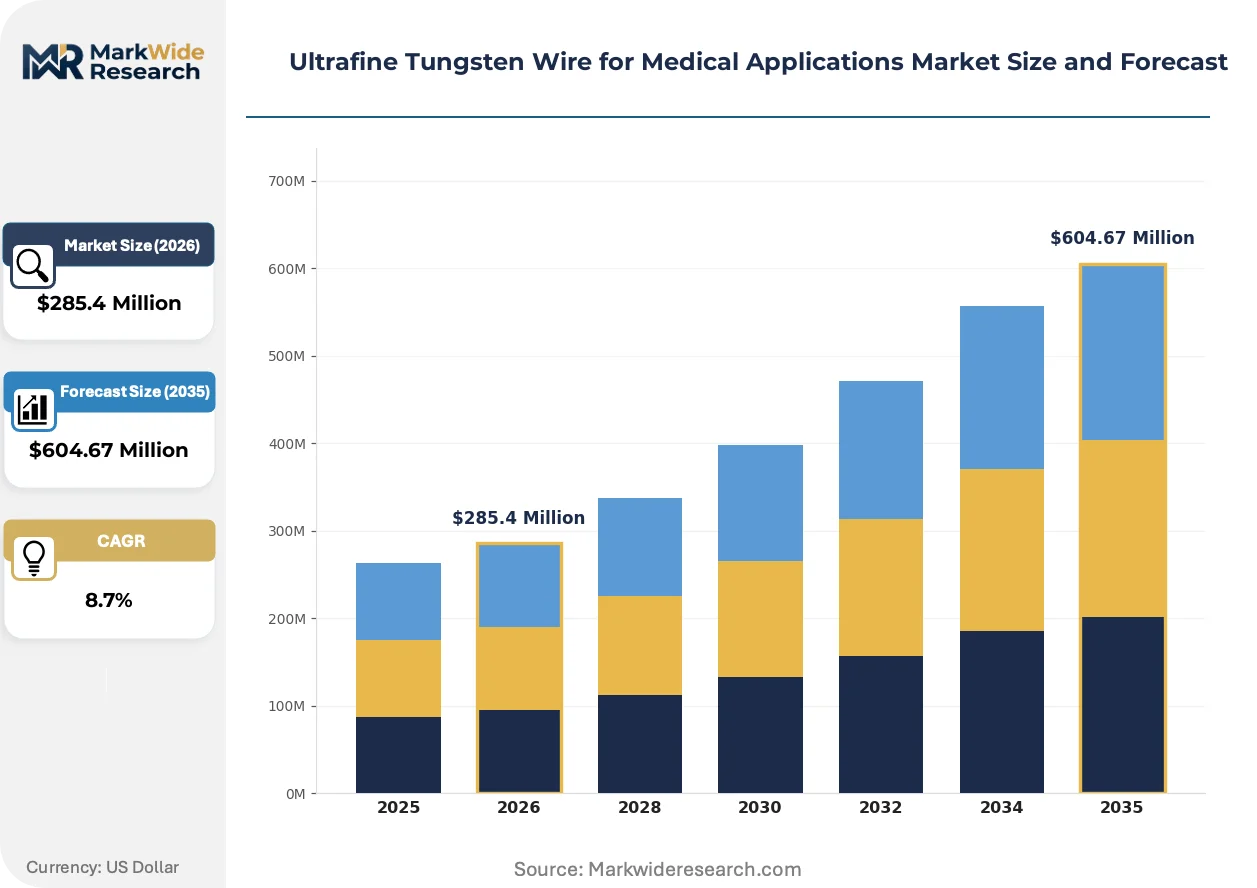
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drawn Wire, Alloyed Wire, Heat Treated Wire, Annealed Wire Application: Endoscopy, Neurostimulation, Surgical Instruments, Radiation Therapy End User: Medical Device Manufacturers, Surgical Centers, Diagnostic Laboratories, Research Institutes Deployment: Custom Orders, Standard Stock, Bulk Supply, Just-in-Time Delivery |
| Companies Covered | Luma Metall AB, Elmet Technologies, Xiamen Honglu Tungsten Molybdenum Industry Co., Nippon Tungsten Co., Ltd., Plansee, Sumitomo Electric Industries, California Fine Wire Company, Ulbrich Stainless Steels and Special Metals Inc., Midwest Tungsten Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrafine Tungsten Wire for Medical Applications Market Strategic Shifts & Innovations
Diamond die drawing with in-line laser micrometry is compressing tolerance bands and enabling real-time process adjustment that was previously impossible with offline metrology cycles.
Laser-based diameter monitoring is overtaking contact micrometry for ultrafine wire production. Neurovascular catheter OEMs in Germany and Japan now specify non-contact measurement protocols for sub-50 micron cores. This technology is overtaking mechanical inspection by eliminating deformation risk during measurement and reducing lot rejection rates.
EU MDR technical documentation requirements are elevating batch-level material certification as a market access gate. Wire producers must implement automated dimensional inspection and full chemical assay reporting to maintain supply relationships with notified body-audited device manufacturers. European guidewire and electrode OEMs are consolidating supplier bases to those with pre-validated quality management systems.
Hospital network procurement consolidation is compressing vendor qualification cycles. Integrated delivery networks in the United States now mandate single-source wire supply for entire catheter and lead product families, displacing multi-supplier strategies. This concentration is most visible in academic medical center supply agreements where standardization reduces sterilization validation burden.
Ultrafine Tungsten Wire for Medical Applications Market Segmentation
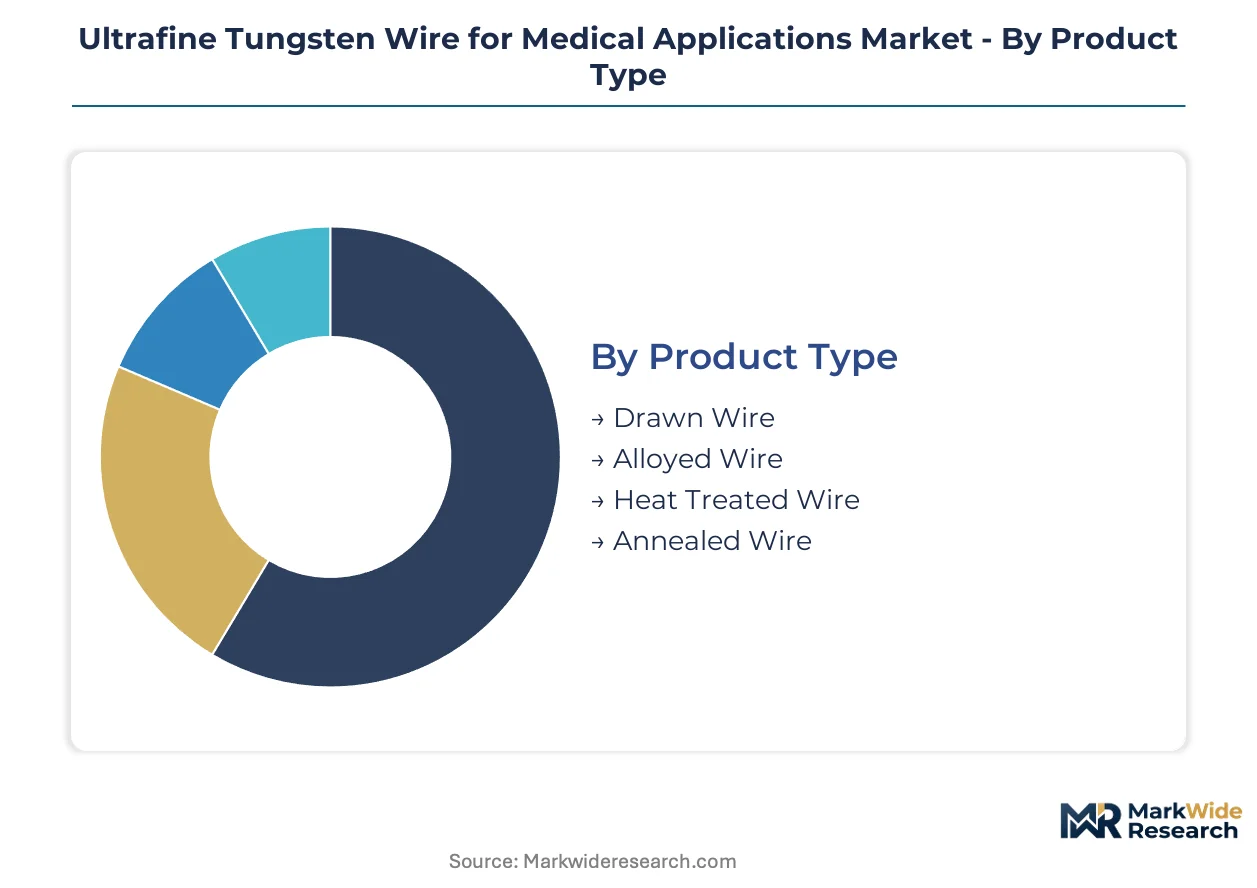
Ultrafine tungsten wire markets fragment across specification hierarchies that determine qualification pathways and margin capture. Diameter tolerance, alloy composition, and surface finish requirements create distinct procurement tiers with diverging supplier bases and certification burdens.
Product Type:
Diamond die drawing precision and thermal processing history define the specification axis for medical-grade tungsten wire.
- Drawn Wire:Pure tungsten filaments manufactured through multi-pass diamond die reduction achieve tensile strengths exceeding 400 ksi for guidewire cores. Demand concentrates in Germany and Japan where neurovascular catheter OEMs require sub-25 micron diameter consistency for tortuous vessel navigation.
- Alloyed Wire:Rhenium-doped compositions enhance fatigue resistance for permanent implant leads. Procurement is expanding for deep-brain and spinal cord stimulation systems as device manufacturers seek extended cycle life under mechanical stress.
- Heat Treated Wire:Controlled atmosphere annealing optimizes grain structure for specific modulus requirements in radiation therapy positioning applications.
- Annealed Wire:Softened ductility grades serve forming-intensive surgical instrument components requiring complex bend geometries.
Mature deployment sits with drawn wire configurations. Newer deployment is concentrated in alloyed wire grades for neurostimulation leads.
Application:
Clinical use case determines radiopacity requirements, biocompatibility testing depth, and regulatory pathway complexity.
- Neurostimulation:Deep-brain and spinal cord stimulation leads demand rhenium-alloyed cores with enhanced fatigue resistance under cyclic loading. FDA 21 CFR Part 820 quality system requirements and EU MDR technical documentation elevate batch-level material certification as a supply gate.
- Radiation Therapy:Proton beam positioning wires require precise dimensional stability under thermal cycling. Tertiary care network expansion across the United States and Germany is driving structural demand growth for precision oncology infrastructure.
- Endoscopy:Guidewire cores for diagnostic and therapeutic scopes represent stable replacement demand with established supply relationships.
- Surgical Instruments:Electrocautery electrodes and grasping tool components utilize annealed grades for formability.
Volume concentration remains with endoscopy applications. Steepest expansion trajectory belongs to radiation therapy positioning systems.
End User:
Procurement sophistication and quality system maturity separate customer tiers in medical wire supply.
- Medical Device Manufacturers:Catheter and electrode OEMs in Germany, Japan, and the United States consolidate supplier bases to pre-validated quality management systems under EU MDR and FDA jurisdiction. Integrated delivery networks now mandate single-source supply for entire product families.
- Surgical Centers:Sterilization validation requirements drive standardization toward qualified wire specifications with documented biocompatibility.
- Diagnostic Laboratories:Research-grade wire purchases for prototype development operate outside formal device quality systems.
- Research Institutes:Experimental neurostimulation and imaging studies generate small-batch demand for specialized alloy compositions.
Contract value concentrates with medical device manufacturers. Emerging procurement sophistication is visible in surgical center networks.
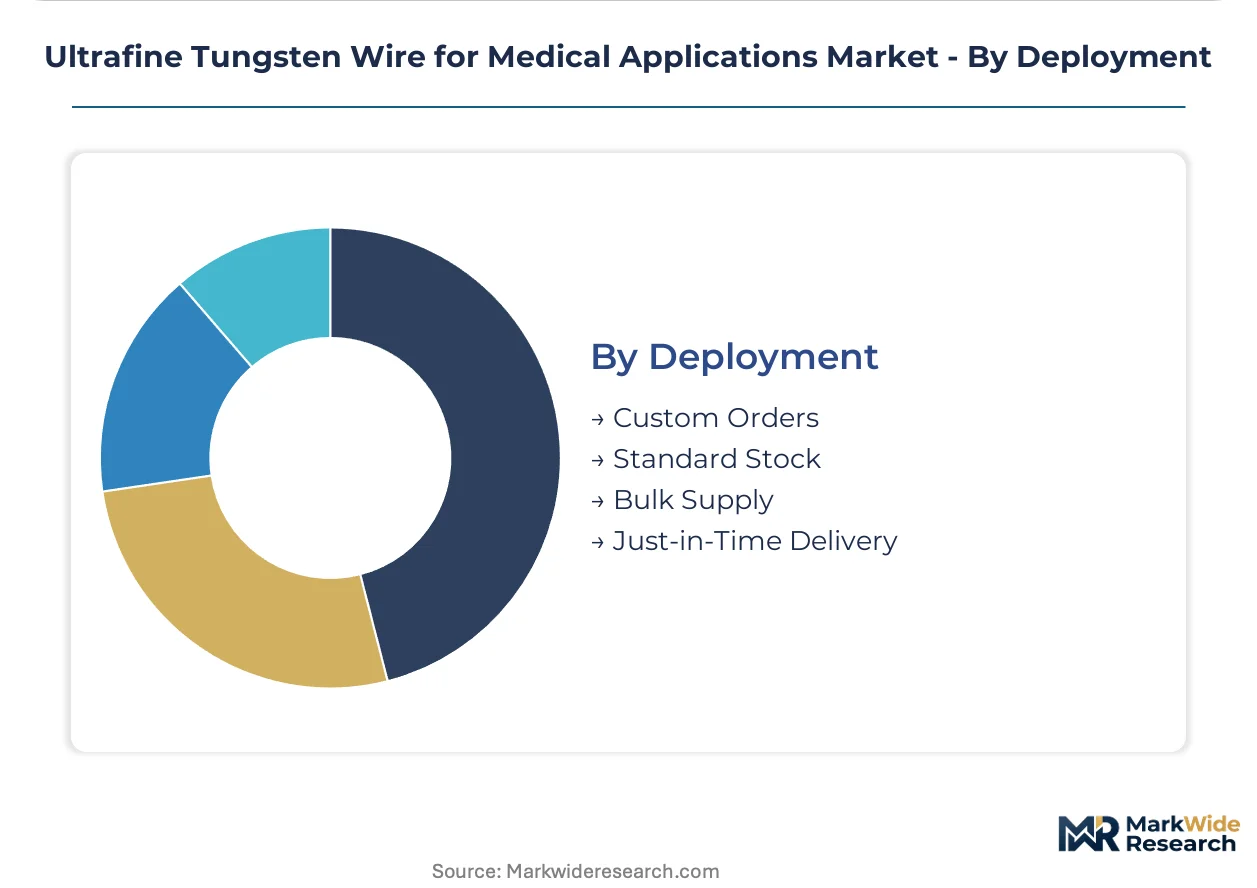
Deployment:
Supply chain configuration and inventory risk allocation differentiate commercial arrangements.
- Just-in-Time Delivery:Synchronized production with catheter assembly lines minimizes working capital for high-volume OEMs. German and Japanese manufacturers leverage this model for neurovascular device production.
- Custom Orders:Specification-defined batches with dedicated diameter, surface finish, and certification packages serve neurostimulation lead development programs.
- Standard Stock:Pre-qualified grades with documented mechanical properties support rapid prototype iteration.
- Bulk Supply:Volume commitments with annual pricing frameworks stabilize input costs for mature endoscopy product lines.
Operational maturity sits with bulk supply arrangements. Strategic shift is concentrating in just-in-time delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary ore processing concentrates in China, yet precision wire fabrication clusters serve catheter and electrode OEMs in Germany, Japan, and the United States. These three markets consume the majority of medical-grade drawn and alloyed wire specifications.
United States
Neurostimulation device manufacturers in Minnesota and Massachusetts expand procurement of fatigue-resistant wire cores. FDA 21 CFR Part 820 quality system audits create scheduling delays that compress product launch windows. Boston and Minneapolis-St. Paul host guidewire engineering clusters where sub-25 micron diameter consistency commands premium tier positioning.
Germany
Neurovascular catheter OEMs in Baden-Württemberg and Bavaria specify non-contact laser micrometry protocols for sub-50 micron cores. EU MDR notified body capacity constraints extend supplier qualification timelines by 12-18 months. The Stuttgart precision engineering corridor concentrates diamond die drawing expertise for tortuous vessel navigation applications.
Japan
PMDA and METI coordinate on tungsten biocompatibility testing protocols for permanent implant leads. Extended cytotoxicity and sensitization studies create first-mover advantage for qualified suppliers. The Chubu-Nagoya region anchors ultra-fine diameter consistency capabilities below 25 microns for neurovascular catheter cores.
China
Tungsten concentrate supply concentration creates geopolitical exposure for downstream wire draw operations. NMPA medical device regulations tighten material traceability requirements for export-oriented manufacturers. Xiamen and Zhengzhou host refractory metals processing complexes serving both domestic and international OEM supply chains.
Ultrafine Tungsten Wire for Medical Applications Market Key Industry Players
The competitive structure tilts toward vertically integrated refractory metals specialists with captive powder processing capabilities. Market access gates favor producers with pre-validated quality management systems under EU MDR and FDA jurisdiction. Two strategic archetypes dominate: Austrian and German refractory metals complexes with full supply chain control, and Japanese precision wire specialists competing on diameter consistency. Competitive moves concentrate on backward integration into tungsten powder production and automated dimensional inspection system deployment.
Among European-based fabricators, Plansee anchors supply through its Austrian refractory metals complex, while Elmet Technologies leverages captive tungsten powder processing to sustain cost advantages. Nippon Tungsten Co., Ltd. occupies a position within the Japanese precision tier, exemplifying the specialization archetype focused on ultra-fine diameter consistency below 25 microns. These three companies represent the dominant competitive positioning vectors: integrated supply chain control, cost-advantaged captive processing, and sub-micron precision specialization.
| Leading Market Players |
|---|
| Luma Metall AB |
| Elmet Technologies |
| Xiamen Honglu Tungsten Molybdenum Industry Co. |
| Nippon Tungsten Co., Ltd. |
| Plansee |
| Sumitomo Electric Industries |
| California Fine Wire Company |
| Ulbrich Stainless Steels and Special Metals Inc. |
| Midwest Tungsten Service |
| Others |
Cost & Logistics Intelligence
Diamond die drawing metallurgists with decade-long refractory wire experience concentrate in Germany's Stuttgart corridor and Japan's Chubu-Nagoya region, and this workforce scarcity widens pricing spreads between premium certified grades and standard commercial offerings.
Pricing Analysis
Cost-down pressure on drawn wire grades accelerates because hospital network procurement consolidation mandates single-source supply agreements that compress vendor margins. Three-tier pricing structure across premium, standard, and economy levels separates EU MDR-certified batches with full chemical assay reporting from standard stock grades with limited documentation. Price differentiation hinges on certification tier and volume scale, with neurostimulation lead OEMs least price-sensitive due to fatigue-resistance requirements and endoscopy device makers most sensitive given mature replacement demand cycles.
Supply Chain Analysis
Specialized diamond die craftsmen availability constrains capacity expansion in Austrian and German refractory metals complexes. Primary tungsten concentrate processing draws from China, while precision wire fabrication clusters in Germany, Japan, and the United States serve catheter and electrode OEMs. Raw material dependencies rest on tungsten powder, rhenium feedstock for alloyed grades, and synthetic diamond dies for drawing operations. Single-source vulnerability concentrates in Chinese ore processing, exposing European and North American draw operations to geopolitical disruption. Distribution runs through just-in-time delivery models synchronized with catheter assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser-based diameter monitoring is displacing contact micrometry for sub-50 micron core production, and this metrology transition rewards suppliers with in-line process control capabilities over legacy offline inspection systems.
For Market Incumbents: Extend captive tungsten powder processing capabilities to secure cost advantages as EU Green Deal carbon transparency requirements decouple procurement from legacy suppliers lacking documented Scope 3 emissions. Defend against Japanese precision specialists by deploying automated dimensional inspection systems that compress tolerance bands for neurovascular catheter OEMs. Anchor supply relationships through pre-validated quality management systems under FDA and EU MDR jurisdiction. For New Entrants and Emerging Players: Research institutes running experimental neurostimulation studies represent an underserved buyer archetype with small-batch demand for specialized alloy compositions outside formal device quality systems. Penetrate this segment through custom order capabilities with dedicated diameter, surface finish, and certification packages. Build technical credibility via extended cytotoxicity and sensitization studies aligned with PMDA-METI biocompatibility protocols for permanent implant leads. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated refractory metals specialists given EU MDR notified body capacity constraints extending supplier qualification timelines. Long-term viability favors producers with captive powder processing and automated inspection deployment across the analysis window. Target acquisition archetypes include Austrian and German complexes with full supply chain control. Monitor FDA 21 CFR Part 820 inspection backlog resolution as inflection indicator for new wire specification launch windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Powder Processing | Captive supply of carbon-transparent refined powder secures premium tier procurement from CSRD-mandated hospital networks. |
| Automated Dimensional Inspection Deployment | In-line laser micrometry eliminates deformation risk during measurement for sub-25 micron neurovascular cores. |
| EU MDR Quality System Pre-Validation | Pre-audited manufacturing execution systems compress supplier qualification timelines by 12-18 months. |
| PMDA-METI Biocompatibility Protocol Completion | Extended cytotoxicity studies unlock first-mover positioning for permanent implant lead contracts in Japan. |
| Just-in-Time Delivery Model Implementation | Synchronized production with catheter assembly lines captures integrated delivery network single-source mandates. |
Research Approach
Independent corroboration across primary interviews with diamond die drawing specialists, catheter OEM procurement directors, and biomedical engineers, plus secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and hospital GPO contract records, underwrites the qualitative findings. Bottom-up demand modeling from end-use application volumes and top-down supply assessment from refractory metals processing capacity triangulate market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type hierarchy, clinical application, end-user procurement sophistication, and deployment configuration. CAGRs derive from normalized historical trajectory analysis adjusted for regulatory inflection points. Forecast inputs incorporate proton beam therapy infrastructure deployment schedules and neurostimulation lead fatigue-resistance specification evolution.
Revisions become necessary when EU MDR notified body capacity constraints deepen, FDA inspection backlogs extend, or tungsten concentrate supply disruptions from Chinese ore processing materialize. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
High Purity Tungsten Market
Metals
Armour Steel Plate Market
Metals
Metal Injection Molding (Mim) Powders Market
Metals
Hafnium Foil Market
Metals
Global Duplex Stainless Steel Market
Metals
Global Aluminum Extruded Products Market
Metals
Grain Oriented Electrical Steel Market
Metals
Global Metal and Metal Manufactured Products Market
Metals
Silver Sulphate Market
Metals
High Carbon Bearing Steel Market
Metals
Ferrochrome Market
Metals
Aluminum Plates and Sheet Coils Market
Metals
Colloidal Metal Particles Market
Metals
Aluminum Flat-Rolled Products Market
Metals
TMCP Steel Market
Metals
Industrial Silver Market