
 Alkaline Water Electrolysis Market | 2026-2036
Alkaline Water Electrolysis Market Size, Share, and Industry Trends Forecast 2026-2036
Alkaline Water Electrolysis Market Intelligence
Modularization of electrolyzer stacks is pivoting buyer preference towards scalable, containerized solutions for phased project development. Thyssenkrupp Nucera leverages its deep engineering expertise to deliver large-scale, standardized 20 MW modules for industrial clients. Nel Hydrogen competes with a focus on both alkaline and PEM technologies, offering a broader portfolio to capture diverse project requirements. Cummins utilizes its global manufacturing and service network to support deployments across the power and transport sectors.
Alkaline water electrolysis is an electrochemical process that uses a liquid alkaline electrolyte, typically a 25-30% potassium hydroxide (KOH) solution, to separate water. Its primary industrial purpose is the cost-effective production of high-purity hydrogen gas for applications requiring large volumes. Hydrogen Generation for industrial feedstocks remains the dominant application, while Power-to-Gas for grid balancing represents the fastest-growing segment. Pressurized Cell designs are gaining traction in new projects for chemical plants and refineries due to higher operational efficiency.
Government incentives like the United States' Inflation Reduction Act (IRA) and the EU's Green Deal Industrial Plan directly subsidize green hydrogen production. China's dual carbon goals, enforced by bodies like the MEE, create significant domestic demand for electrolyzer technology. Navigating the complex qualification criteria for these subsidies while managing the supply of critical components like catalysts and membranes remains the central challenge for manufacturers.
Market Dynamics
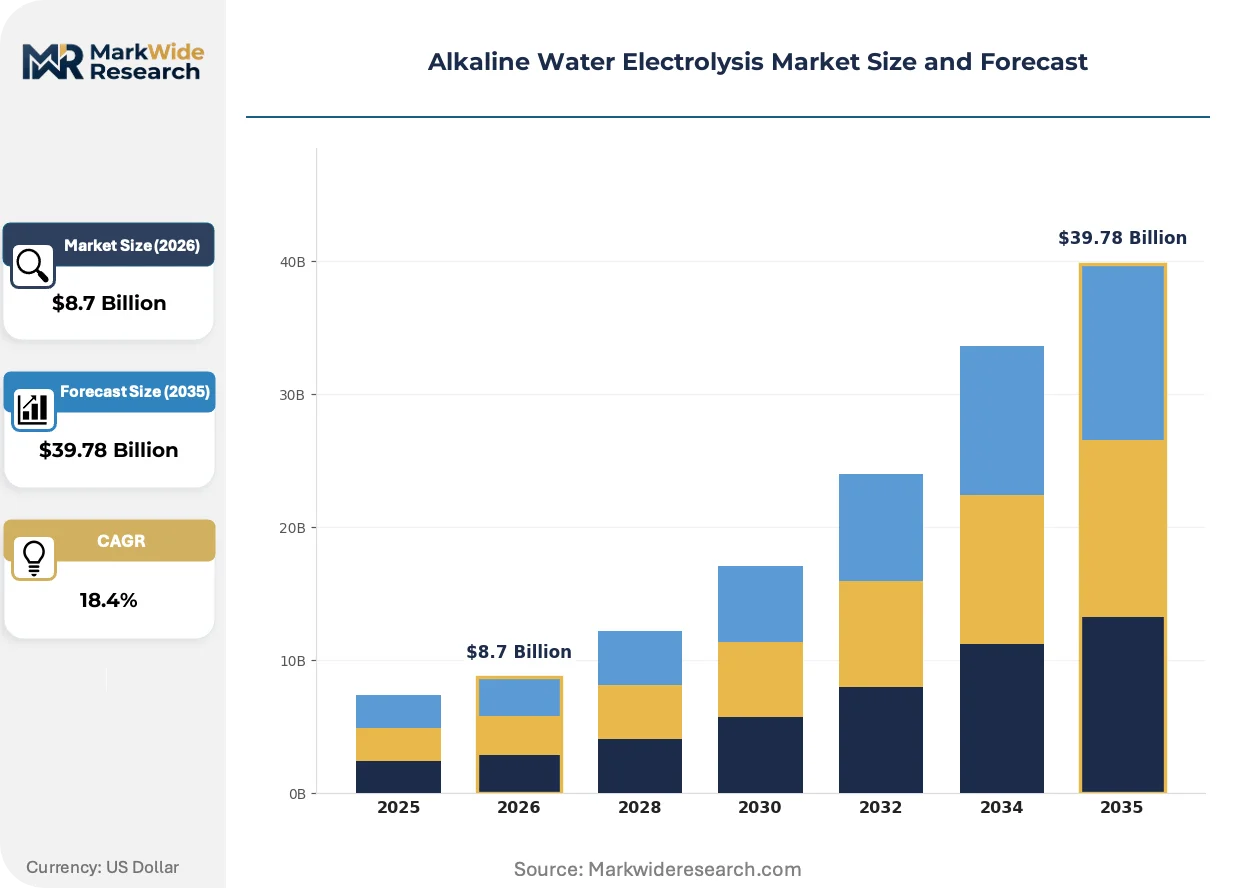
The central dynamic shaping the alkaline water electrolysis market is the pressure to rapidly scale manufacturing capacity for standardized modules. This urgency is a direct response to a surge in demand from industrial-scale green hydrogen projects, which are outpacing the existing supply chain's ability to deliver critical components like membranes and catalysts.
Growth Catalysts
- Government Decarbonization Policies:National-level incentives, including the United States' Inflation Reduction Act (IRA) and the EU Green Deal, provide direct subsidies and tax credits that improve the economic viability of green hydrogen production for industrial users.
- Industrial Feedstock Demand:The chemical and refining industries require immense volumes of hydrogen and are turning to green hydrogen from electrolysis to meet corporate and regulatory emissions reduction targets for producing ammonia, methanol, and cleaner fuels.
- Technological Standardization:The shift towards modular, containerized electrolyzer systems, such as standardized 20 MW blocks, allows for faster deployment, phased capital expenditure, and simplified project scaling compared to bespoke, site-built plants.
Market Restraints
- Input Material Volatility:The cost and availability of critical raw materials, including high-purity potassium hydroxide (KOH) electrolyte and platinum-group metals used in advanced catalysts, introduce significant price uncertainty into electrolyzer manufacturing.
- Renewable Energy Dependency:The economic case for alkaline electrolysis depends on access to low-cost, high-capacity-factor renewable electricity, structurally limiting viable project locations to regions with abundant solar or wind resources and robust grid infrastructure.
- Critical Component Bottlenecks:The global supply of high-performance, durable diaphragms and advanced ion-exchange membranes remains concentrated among a few specialized manufacturers, creating potential chokepoints for the entire industry.
Strategic Opportunities
- Grid Balancing Services:Deploying electrolyzers as flexible loads for Power-to-Gas applications creates a new revenue stream for operators, who can sell grid stabilization services by absorbing surplus electricity from renewables during periods of oversupply.
- Emerging Geographic Markets:Nations with exceptional renewable resources but nascent hydrogen economies, such as Australia, Chile, and Oman, represent significant greenfield opportunities for large-scale electrolyzer deployments aimed at export markets.
- Direct Integration with E-Fuels:Co-locating and integrating alkaline electrolyzers directly with new green ammonia and e-methanol synthesis plants provides a dedicated, high-volume offtake for hydrogen, de-risking project financing and long-term operation.
Industry Challenges
- Specialized Talent Shortages:A scarcity of chemical engineers and project managers with specific expertise in integrating multi-megawatt electrolysis systems with complex industrial facilities acts as a significant operational bottleneck for project developers.
- High Capital Intensity:The substantial upfront investment required for large-scale electrolyzer stacks, purification systems, and balance-of-plant infrastructure necessitates complex and lengthy project financing cycles.
- Complex Subsidy Qualification:Manufacturers and project developers face significant administrative hurdles in navigating and documenting compliance with the stringent criteria of programs like the US IRA's 45V tax credit to certify hydrogen production pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alkaline Water Electrolysis Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Cell, Pressurized Cell, Bipolar Stack, Monopolar Stack, Zero Gap Cell Technology: Polymer Membrane, Electrocatalyst Coating, Gas Diffusion Layer, Separator Material, Stack Design Application: Hydrogen Generation, Power-to-Gas, Renewable Integration, Energy Storage, Industrial Gas Supply End User Type: Refineries, Chemical Plants, Fuel Cell Manufacturers, Power Plants, Aerospace Sector |
| Companies Covered | Cummins, Asahi Kasei, Nel Hydrogen, PERIC Hydrogen Technologies, Green Hydrogen Systems, Thyssenkrupp Nucera, McPhy Energy, LONGi Hydrogen, ITM Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alkaline Water Electrolysis Market Strategic Shifts & Innovations
The market is undergoing a fundamental transition from custom-engineered projects toward productized, scalable solutions. This shift is driven by the imperative to accelerate deployment timelines and reduce levelized costs of hydrogen to meet ambitious decarbonization goals in heavy industry and transport.
Pressurized alkaline electrolyzer cell design is a key product evolution. These systems operate at elevated pressures, which significantly reduces the energy and capital cost required for downstream hydrogen compression, a major factor in total system expense. Industrial end-users in chemical plants and refineries are rapidly adopting this technology to improve the overall efficiency of their green hydrogen production facilities. This advanced cell architecture is expanding into large-scale industrial feedstock applications that were previously the domain of less efficient atmospheric systems.
China's "dual carbon" policy framework, enforced by the Ministry of Ecology and Environment (MEE), is a powerful regulatory force. The policy creates enormous, state-directed domestic demand for electrolyzer technology, particularly within state-owned enterprises in the steel, chemical, and power generation sectors. The equipment manufacturing segment is most affected, as this policy accelerates domestic production scale and fuels intense price competition within the Chinese market.
A clear behavioral shift in project development involves adopting phased deployments built around modular, containerized units. This approach is displacing the traditional model of constructing large, monolithic, site-built electrolysis plants from the ground up. Buyers now prefer to procure standardized blocks, often in 20 MW increments, allowing them to scale their investment with market demand and financing availability. This trend is most apparent in industrial clusters across Germany and the Netherlands.
Alkaline Water Electrolysis Market Segmentation
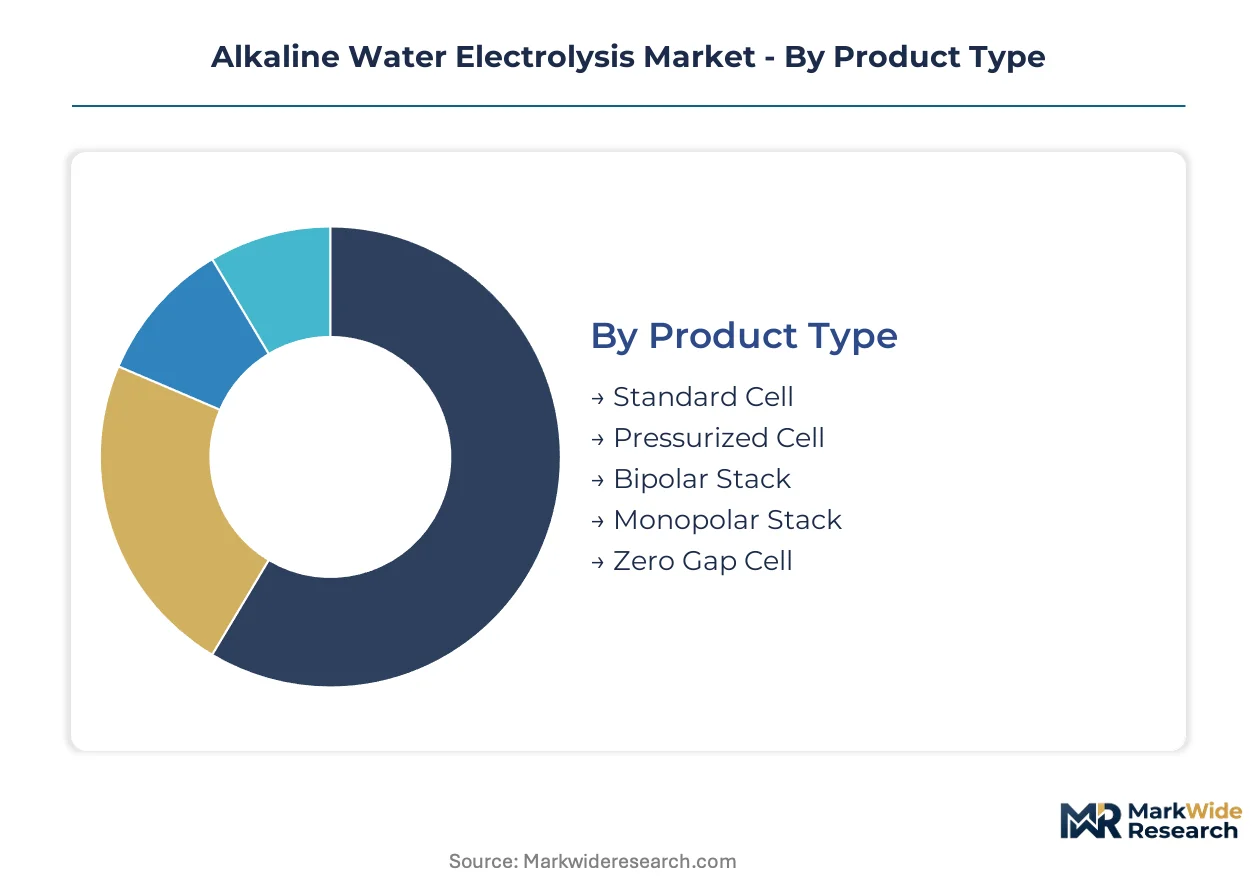
The segmentation of the alkaline water electrolysis market provides a granular understanding of the technologies, applications, and end-user demands shaping its expansion. Analyzing these distinct segments helps stakeholders identify key growth vectors and tailor product development to specific industry requirements for green hydrogen.
Product Type:
The alkaline water electrolysis market's product type segmentation reflects ongoing innovation and replacement cycles, with older designs gradually yielding to more efficient, high-performance units.
- Pressurized Cell:These systems operate at elevated internal pressures, reducing downstream hydrogen compression costs and improving overall energy efficiency. Chemical plants and refineries in Germany are adopting this technology for improved operational efficiency in green hydrogen production.
- Zero Gap Cell:This advanced cell design minimizes the distance between electrodes and membrane, decreasing ohmic losses and boosting energy efficiency. Industrial users seeking to optimize energy consumption for large-scale hydrogen generation projects prioritize this configuration.
- Standard Cell:Traditional atmospheric pressure electrolyzers provide reliable hydrogen generation for less demanding industrial applications.
- Bipolar Stack:Multiple cells are connected in series within a compact module, offering high voltage operation and scalability.
- Monopolar Stack:Cells are connected in parallel, allowing for easier maintenance and individual cell replacement within the system.
Pressurized Cell sits at the top of the volume ranking, with Zero Gap Cell climbing the fastest.
Technology:
Technology segmentation reveals how different material and design choices influence the overall cost structure and performance capabilities of alkaline electrolyzers.
- Electrocatalyst Coating:This layer enhances reaction rates at the electrodes, reducing overpotential and improving system efficiency. Manufacturers are focused on developing platinum-group metal-free catalysts to lower material costs for large-scale deployments.
- Stack Design:The physical arrangement and integration of cells, electrodes, and flow fields define the electrolyzer's operational characteristics and scalability. Modular stack designs are gaining traction for faster deployment in industrial clusters like the Netherlands.
- Polymer Membrane:Selectively permits ion transport while separating hydrogen and oxygen gases within the electrochemical cell.
- Gas Diffusion Layer:Facilitates reactant gas delivery and product gas removal from the electrode surface.
- Separator Material:Prevents mixing of hydrogen and oxygen while maintaining ionic conductivity within the electrolyte solution.
Electrocatalyst Coating advancements are critical for cost reduction, while innovative Stack Design drives deployment speed.
Application:
The application landscape for alkaline water electrolysis is driven by the sheer volume requirements of industrial processes and the emerging demands of energy system decarbonization.
- Hydrogen Generation:This application involves producing high-purity hydrogen primarily for industrial feedstock use in chemical and refining sectors. Demand from green ammonia production in China is a significant driver for this segment.
- Power-to-Gas:Electrolyzers convert surplus renewable electricity into hydrogen, which can be stored or injected into gas grids. Grid balancing services in Germany represent a key revenue stream for Power-to-Gas operators.
- Renewable Integration:Electrolysis systems absorb intermittent renewable power, stabilizing grid operations and optimizing asset utilization.
- Energy Storage:Hydrogen produced via electrolysis serves as a long-duration energy carrier, addressing seasonal or multi-day storage needs.
- Industrial Gas Supply:Provides on-site, high-purity hydrogen for various manufacturing processes, reducing reliance on fossil-fuel-derived sources.
Hydrogen Generation commands the largest volume, with Power-to-Gas experiencing the steepest expansion trajectory.
End User Type:
End-user segmentation highlights the diverse customer base for alkaline electrolyzers, each with specific purity, volume, and operational requirements.
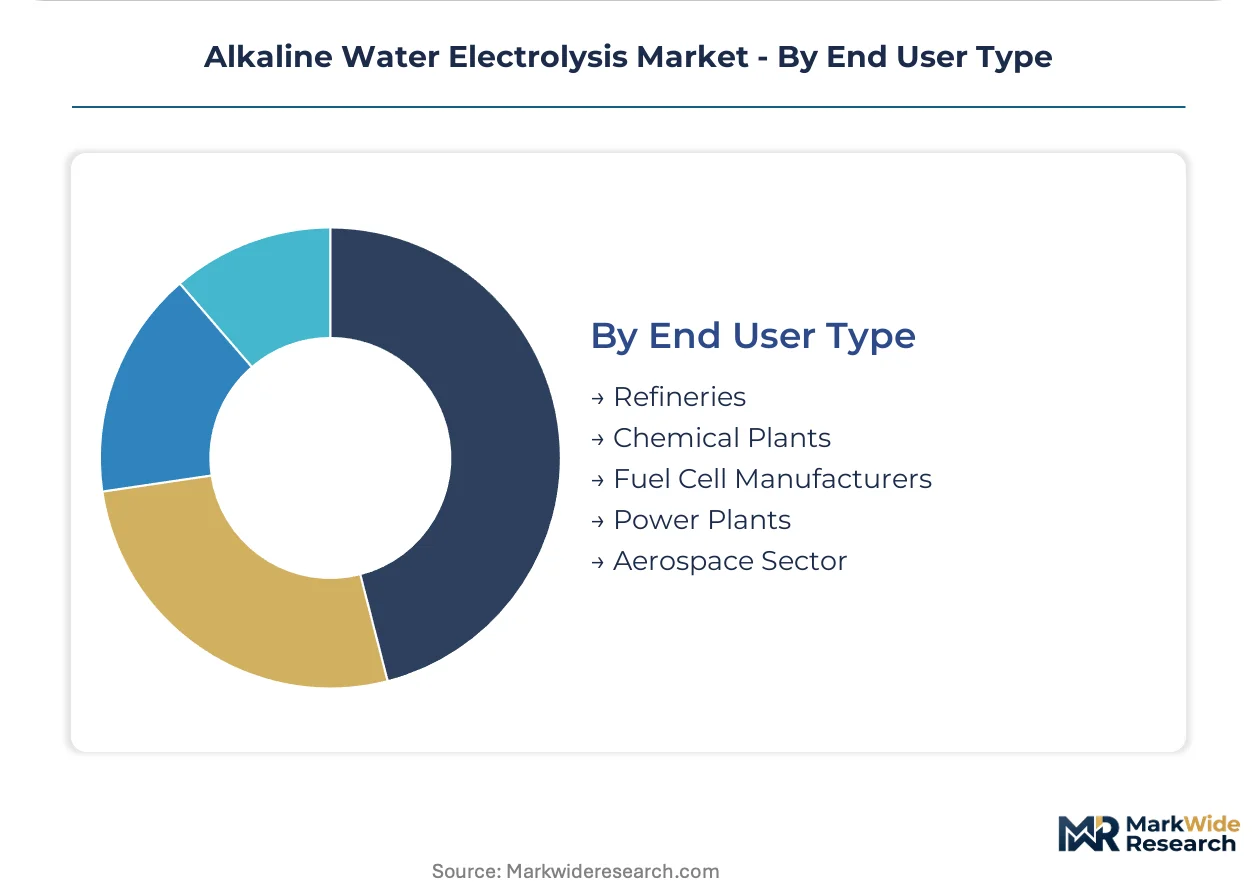
- Chemical Plants:These facilities utilize green hydrogen as a critical feedstock for producing ammonia, methanol, and other chemicals. The EU Green Deal policies are accelerating green hydrogen adoption in chemical production across Europe.
- Refineries:Green hydrogen replaces grey hydrogen in hydrocracking and desulfurization processes, helping refineries meet emissions reduction targets. The Inflation Reduction Act (IRA) in the United States incentivizes green hydrogen use in refining operations.
- Fuel Cell Manufacturers:Require high-purity hydrogen for testing and operating fuel cell stacks in various mobility and stationary applications.
- Power Plants:Integrate electrolyzers for grid stabilization, energy storage, and potential co-firing with natural gas to lower carbon intensity.
- Aerospace Sector:Explores green hydrogen as a sustainable aviation fuel component or direct fuel for future aircraft propulsion systems.
Chemical Plants represent the largest end-user segment, while Refineries are rapidly increasing their green hydrogen procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alkaline water electrolysis technology, originating in the late 19th century, first scaled for industrial hydrogen production in Europe. Early deployments focused on chemical synthesis and fertilizer manufacturing. Now, the market experiences renewed expansion driven by global decarbonization efforts.
Germany
Demand for green hydrogen drives significant electrolyzer deployments in German chemical plants. The EU Green Deal and national policies support these projects. Industrial clusters in the Rhine-Ruhr region are becoming focal points for new modular electrolyzer installations. Grid balancing services also represent a key revenue stream for Power-to-Gas operators there.
China
China's dual carbon goals create immense domestic demand for electrolyzer technology. The Ministry of Ecology and Environment (MEE) enforces policies accelerating green hydrogen adoption. State-owned enterprises in steel and chemical sectors drive large-scale deployments. Shandong province and Inner Mongolia show significant investment in new alkaline electrolysis capacity.
United States
The United States sees rising demand for green hydrogen in its refining sector. The Inflation Reduction Act (IRA) provides direct subsidies for clean hydrogen production. Chemical plants and oil refineries in the Gulf Coast region are rapidly integrating electrolyzers. These facilities aim to reduce emissions and meet corporate sustainability targets.
Netherlands
Industrial clusters in the Netherlands prioritize scalable, containerized electrolyzer solutions. The EU Green Deal policies encourage green hydrogen production for industrial feedstocks. The Port of Rotterdam is a major hub for large-scale electrolyzer projects. Phased deployments built around standardized 20 MW blocks are common here.
Australia
Australia presents significant greenfield opportunities for large-scale electrolyzer deployments. Its abundant renewable resources position it for future hydrogen export markets. Government initiatives support hydrogen hubs and pilot projects. Western Australia and Queensland are developing major green hydrogen production facilities.
Alkaline Water Electrolysis Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and project integration capabilities. The market structure is tiered, with established industrial giants coexisting with specialized green hydrogen startups. Strategic archetypes include large engineering firms, pure-play electrolyzer manufacturers, and diversified energy technology providers. Dominant competitive moves involve rapid capacity expansion and strategic partnerships for project delivery.
Scale-driven players like Cummins, with its extensive global manufacturing and service network, exemplify a broad market presence across power and transport sectors. This US-based company leverages its existing infrastructure for green hydrogen deployments. Meanwhile, Nel Hydrogen, a Norwegian-based specialist, represents a focused approach, offering a diverse portfolio across both alkaline and PEM technologies to capture varied project requirements. German engineering giant Thyssenkrupp Nucera anchors the high-end industrial segment, delivering large-scale, standardized 20 MW modules for complex industrial clients. These companies collectively illustrate the varied strategies for market penetration and technology leadership.
| Leading Market Players |
|---|
| Cummins |
| Asahi Kasei |
| Nel Hydrogen |
| PERIC Hydrogen Technologies |
| Green Hydrogen Systems |
| Thyssenkrupp Nucera |
| McPhy Energy |
| LONGi Hydrogen |
| ITM Power |
| Others |
Cost & Logistics Intelligence
Premium-margin players in alkaline water electrolysis drive pricing for advanced, modular solutions, while commodity-margin players compete on scale for standard systems. This bifurcation shapes both component sourcing strategies and downstream project costs.
Pricing Analysis
Project-based pricing dominates the alkaline water electrolysis market, reflecting the custom integration required for large industrial deployments. Technical sophistication, particularly for pressurized cell designs, and the breadth of a manufacturer's global service network drive price differentiation. Pricing softness stems from intense competition, especially within the Chinese market, as manufacturers scale production. Large industrial users prioritize operational efficiency and reliability, making them less price-sensitive than smaller, less demanding applications.
Supply Chain Analysis
Regional distribution hubs facilitate the deployment of modular electrolyzer units, optimizing logistics for large-scale industrial projects. Component manufacturing concentrates in China, Germany, and the Netherlands, drawing from critical inputs like high-purity KOH, advanced catalysts, and specialized membranes. Single-source vulnerability for high-performance diaphragms and ion-exchange membranes creates a structural risk, with direct delivery to industrial clusters and refineries representing the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alkaline water electrolysis market is evolving into a late-cycle quality story, driven by industrial demand for highly efficient, pressurized cell designs. This demand shift prioritizes operational reliability and lower total cost of ownership.
For Market Incumbents: Extend global manufacturing and service networks to support large-scale deployments. Prioritize R&D into platinum-group metal-free catalysts to mitigate input material volatility. Strategic partnerships for project delivery can counteract the high capital intensity and complex financing cycles. This defends against emerging entrants offering aggressive pricing and reduces critical component bottlenecks.
For New Entrants and Emerging Players: Begin with modular, containerized solutions targeting emerging geographic markets like Australia. Focus on Power-to-Gas applications for grid balancing services, leveraging regions with abundant renewable electricity. This strategy allows faster deployment and reduces upfront capital expenditure. Emphasize simplified project scaling to address the talent shortages in complex multi-megawatt system integration.
For Investors and Strategic Acquirers: Consolidation pressure builds where critical component manufacturing remains concentrated among a few specialized players. The market offers long-term viability as a foundational technology for heavy industry decarbonization over the next decade. Target acquisition profiles include specialized component manufacturers or firms with proven project integration capabilities. Watch for the successful qualification of large-scale green hydrogen projects under subsidy schemes like the US IRA 45V tax credit.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Manufacturers scale production of standardized modules to meet surging demand from industrial green hydrogen projects. |
| Technology Licensing | This accelerates adoption of advanced pressurized cell designs in emerging geographic markets. |
| Joint Venture | De-risking large-scale project financing and sharing specialized talent becomes feasible for complex deployments. |
| Green Certification Program | Ensuring compliance with stringent subsidy criteria, such as the US IRA 45V, is critical for project viability. |
| Long-term Supply Agreement | Securing critical raw materials like high-purity KOH and specialized membranes mitigates input volatility. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and industry reports — were reconciled to build this market analysis. Interviews included chemical plant managers, refinery procurement leads, electrolyzer R&D directors, and government policy analysts. Secondary data sources comprised MEE policy documents, EU Green Deal reports, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data accuracy and consistency.
The analytical framework integrated historical data with future growth catalysts, reconciling diverse data streams across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user type, and regional deployment patterns. Compound annual growth rates were derived from a proprietary algorithm weighting historical trends, policy impacts, and technological adoption rates. Green hydrogen production targets and renewable energy capacity additions served as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid breakthroughs in alternative hydrogen production methods. Forecasts reflect assumptions regarding stable government subsidy programs and renewable energy price trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
On-Site Hydrogen Generator Market