
 Hydrogen Generation Market | 2026-2036
Hydrogen Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Generation Market Analysis
Power-to-X demand from ammonia and steel producers is shifting the hydrogen generation customer base away from traditional refinery buyers. Linde plc leverages its global industrial gas infrastructure to anchor large-scale hydrogen supply contracts. Siemens Energy AG specializes in electrolyzer manufacturing and sustains technology leadership in proton exchange membrane systems. Nel ASA competes aggressively on modular electrolyzer design for distributed production sites.
Hydrogen generation encompasses the production of molecular hydrogen through thermochemical, electrochemical, or biological processes, typically yielding purity grades from 99.9% to 99.999% depending on the application. Steam methane reforming currently dominates installed capacity due to its mature economics, though electrolysis is displacing thermal routes in markets with abundant renewable electricity. The application split shows fuel cells capturing premium pricing in mobility, while industrial processes absorb the largest volume share. Production method segmentation reveals renewable-energy-linked electrolysis as the fastest-growing category, with fossil-fuel-based routes facing margin compression from carbon pricing mechanisms.
The EU Green Deal and F-Gas Regulation shape European electrolyzer deployment timelines, while the US IRA production tax credits redirect capital toward domestic manufacturing. Japan's METI hydrogen roadmap and South Korea's hydrogen economy policy establish import infrastructure standards that filter back to generation equipment specifications. Stakeholders must monitor regulatory arbitrage between jurisdictions as subsidy design determines project finance viability and equipment sourcing geography.
Market Dynamics
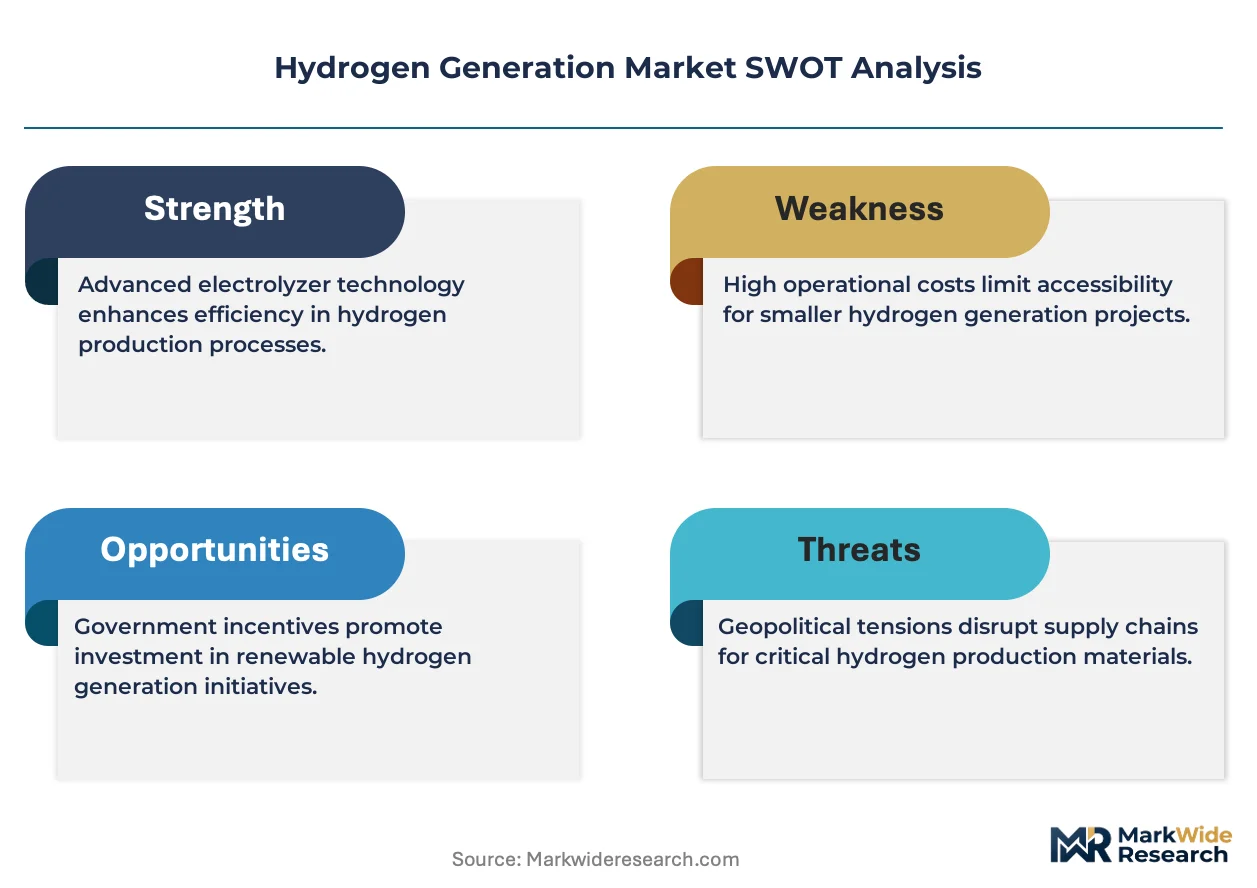
Electrolyzer deployment is accelerating as steel decarbonization mandates and EU carbon border adjustments force industrial hydrogen procurement toward renewable production routes, compressing the economic viability of steam methane reforming in carbon-priced jurisdictions.
Growth Catalysts
- EU Green Deal carbon border mechanism:Industrial importers into the European Union face embedded carbon tariffs that elevate green hydrogen economics relative to gray hydrogen alternatives.
- Steel sector decarbonization:Direct reduced iron producers in coastal industrial clusters are contracting dedicated hydrogen supply to replace metallurgical coke in blast furnace operations.
- Proton exchange membrane advances:Improved catalyst loading and membrane durability are compressing electrolyzer capital costs and enabling modular deployment at distributed production sites.
Market Restraints
- Renewable electricity cost volatility:Offtake agreements for dedicated wind and solar capacity face basis risk that undermines levelized hydrogen cost projections in merchant power markets.
- Electrolyzer supply concentration:Stack manufacturing capacity concentrates in European and Chinese facilities, creating equipment delivery bottlenecks for projects in North American and Middle Eastern jurisdictions.
- Pipeline retrofit incompatibility:Existing natural gas transmission infrastructure requires material upgrades to handle hydrogen embrittlement, limiting immediate offtake pathways for new production assets.
Strategic Opportunities
- US IRA production tax credits:The Inflation Reduction Act's clean hydrogen production incentives redirect capital toward domestic electrolyzer manufacturing and greenfield project development.
- Ammonia export corridors:Maritime fuel and fertilizer producers are contracting long-term hydrogen supply for ammonia synthesis at port-adjacent facilities.
- Offshore wind-to-hydrogen hubs:Grid-constrained renewable generation in the North Sea is finding offtake through dedicated electrolyzer platforms with subsea pipeline connections.
Industry Challenges
- Electrolyzer technician scarcity:Stack assembly and membrane maintenance require specialized labor pools that remain underdeveloped relative to projected installation timelines.
- Certification timeline compression:Pressure equipment directives and ATEX compliance for hydrogen service are extending project development cycles beyond original financing assumptions.
- Legacy asset integration:Refinery hydrogen networks designed for captive steam methane reforming face technical and contractual friction when blending electrolytic supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Generation Market |
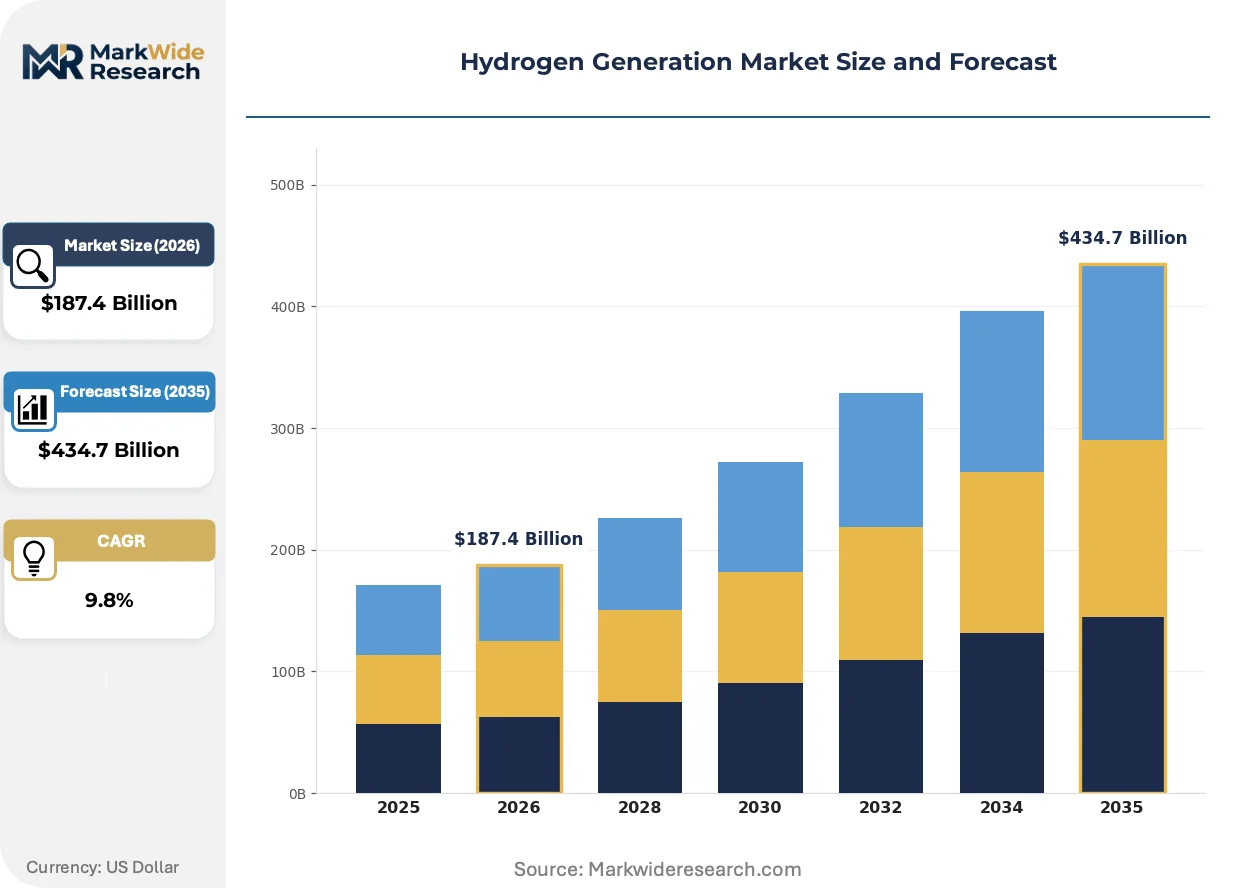
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $434.7 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Gasification, Biomass Gasification Application: Fuel Cells, Industrial Processes, Chemical Production, Transportation End User: Energy Sector, Manufacturing, Transportation Sector, Utilities Production Method: Renewable Energy, Fossil Fuels, Thermal Processes, Others |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Siemens Energy AG, Shell plc, Saudi Arabian Oil Co., Cummins Inc., Nel ASA, Plug Power Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Generation Market Emerging Trajectories
Solid oxide electrolysis is advancing toward commercial scale as developers target efficiency gains from high-temperature operation, while regulatory frameworks in major economies are hardening carbon intensity standards for hydrogen qualification.
Solid oxide electrolysis cells operate at elevated temperatures to reduce electrical energy requirements for water splitting. Chemical producers with available waste heat streams are piloting integrated systems for ammonia and methanol synthesis feedstock. This technology is expanding into industrial clusters where process heat integration improves overall system efficiency.
The EU F-Gas Regulation is tightening fluorinated gas containment standards for cooling systems in electrolyzer facilities. Equipment suppliers are redesigning thermal management architectures to comply with phasedown schedules. Proton exchange membrane manufacturers face reformulation pressure for membrane materials and sealing technologies.
Long-term offtake contracting is displacing spot market exposure for hydrogen producers. Steel and ammonia buyers are securing fifteen-to-twenty-year supply agreements with fixed-price escalation mechanisms. This pattern concentrates in European and East Asian markets where end-users face binding decarbonization compliance deadlines.
Hydrogen Generation Market Segmentation
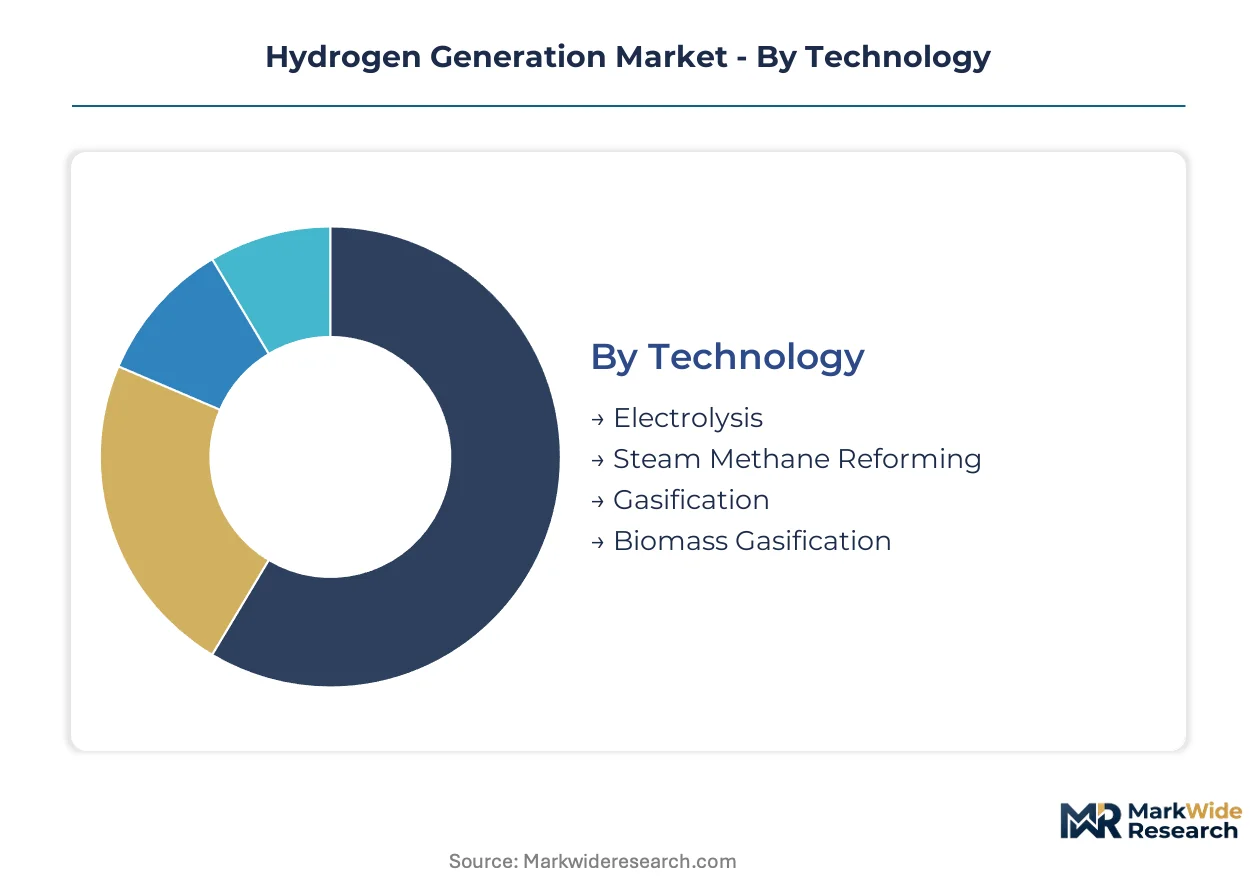
Hydrogen generation technologies serve divergent customer economics across industrial clusters, mobility corridors, and power-to-X installations. Segment boundaries blur as electrolyzer manufacturers pivot from demonstration projects toward multi-gigawatt supply contracts for steel and ammonia offtakers.
Technology:
Steam methane reforming commands volume leadership while electrolysis captures premium pricing in carbon-regulated jurisdictions.
- Electrolysis:Electrochemical water splitting using alkaline, proton exchange membrane, or solid oxide cell architectures. Demand concentrates in coastal industrial clusters where offshore wind feeds dedicated hydrogen hubs, driven by EU carbon border adjustments and steel decarbonization mandates. Alkaline systems dominate utility-scale installations; PEM units penetrate distributed mobility fueling.
- Steam Methane Reforming:Catalytic conversion of natural gas with steam at elevated temperatures, yielding hydrogen and carbon dioxide. Refinery hydrogen networks and ammonia synthesis plants in the US Gulf Coast and Middle Eastern industrial zones sustain installed base economics, though margin compression from carbon pricing accelerates retrofit discussions.
- Gasification:Partial oxidation of coal or petroleum coke to syngas with subsequent water-gas shift.
- Biomass Gasification:Thermochemical conversion of agricultural residues and woody biomass.
Today's leader: Steam Methane Reforming. Tomorrow's challenger: Electrolysis.
Application:
Industrial processes absorb bulk volume while fuel cells extract pricing premiums from mobility and backup power segments.
- Industrial Processes:Direct reduced iron production, petroleum refining hydrotreating, and glass manufacturing annealing. German steelmakers at Duisburg and Rotterdam port clusters are contracting dedicated hydrogen supply to replace metallurgical coke, with offtake agreements spanning fifteen-to-twenty-year horizons.
- Fuel Cells:Electrochemical power generation for heavy-duty trucking, maritime propulsion, and stationary backup. South Korean fuel cell deployment for urban bus fleets and Japanese stationary installations for building resilience sustain membrane electrode assembly demand.
- Chemical Production:Ammonia synthesis for fertilizer and methanol reforming for marine fuel.
- Transportation:Direct hydrogen combustion and fuel cell electric vehicle propulsion systems.
Industrial Processes anchor current procurement volumes; Fuel Cells are climbing the fastest as mobility infrastructure scales.
End User:
Energy sector procurement concentrates in generation and storage, while manufacturing drives purity-grade specifications.
- Energy Sector:Grid balancing, seasonal storage, and power-to-gas installations. Grid-constrained offshore wind in the North Sea finds offtake through electrolyzer platforms with subsea pipeline connections to continental demand centers.
- Manufacturing:Steel, cement, and chemicals production requiring process heat and reducing agents. Direct reduced iron producers face binding decarbonization compliance deadlines that elevate green hydrogen contracting priority.
- Transportation Sector:Heavy-duty freight, maritime shipping, and aviation fuel synthesis.
- Utilities:Blending into natural gas distribution networks and dedicated hydrogen pipeline injection.
Manufacturing sets purity standards today; Energy Sector applications are expanding most quickly as renewable curtailment drives storage economics.
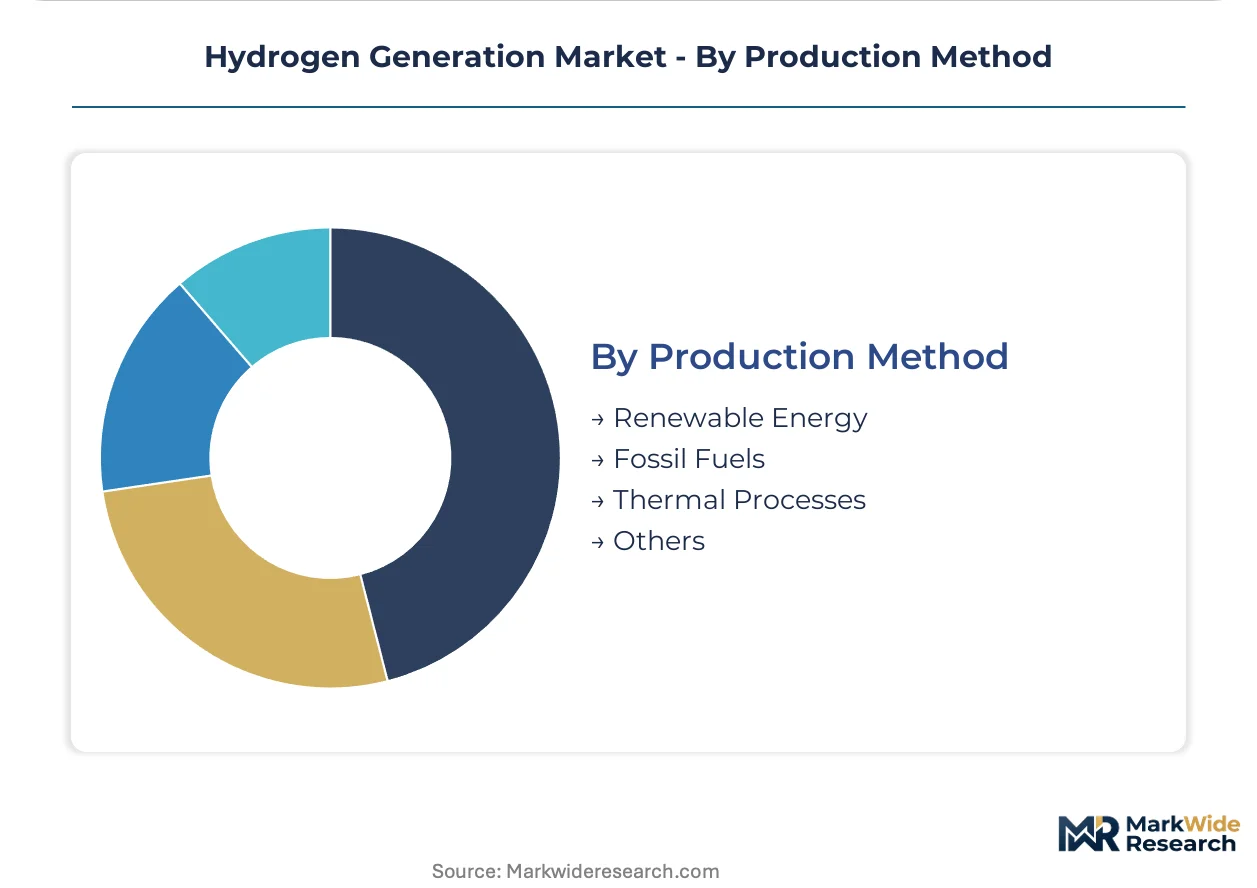
Production Method:
Fossil-fuel routes retain cost advantage while renewable-energy-linked electrolysis gains share fastest under subsidy acceleration.
- Renewable Energy:Wind, solar, and hydro-powered electrolysis with near-zero Scope 2 emissions. US IRA production tax credits redirect capital toward domestic electrolyzer manufacturing and greenfield project development, compressing levelized cost gaps with gray hydrogen alternatives.
- Fossil Fuels:Natural gas reforming and coal gasification with unabated or partially captured carbon dioxide.
- Thermal Processes:Nuclear high-temperature electrolysis and concentrated solar thermochemical cycles.
- Others:Biological fermentation, photoelectrochemical, and emerging plasma-assisted routes.
Fossil Fuels dominate current output; Renewable Energy is gaining share fastest as carbon pricing hardens and electrolyzer manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between carbon-priced European jurisdictions and subsidy-rich North American markets is redirecting electrolyzer manufacturing investment and green hydrogen project development toward jurisdictions with the most favorable production tax credit structures.
Germany
Steel decarbonization at ThyssenKrupp's Duisburg complex and chemical sector demand from BASF's Ludwigshafen operations anchor hydrogen procurement volumes. The national hydrogen strategy accelerates electrolyzer deployment through IPCEI funding windows. Coastal clusters at Hamburg and Rostock integrate offshore wind connections into dedicated hydrogen import terminals.
United States
Texas Gulf Coast refineries and California heavy-duty trucking corridors sustain demand for low-carbon hydrogen supply. The Inflation Reduction Act's production tax credits compress levelized costs for electrolytic routes below unabated steam methane reforming. Project developers concentrate in Houston and the Pacific Northwest where renewable curtailment feeds dedicated production assets.
China
State-owned refinery operators and ammonia synthesis plants in Ningxia and Inner Mongolia sustain installed capacity for gray hydrogen production. Dual carbon goals and provincial renewable energy targets accelerate electrolyzer manufacturing scale-up in Jiangsu and Zhejiang. Demonstration projects at Zhangjiakou and Ordos test grid-scale renewable hydrogen integration.
Japan
METI's hydrogen roadmap establishes import infrastructure standards that filter back to generation equipment specifications for domestic suppliers. Fuel cell deployment for stationary power and urban bus fleets sustains premium hydrogen demand in Tokyo and Osaka. Coastal industrial zones at Yokohama and Kawasaki pilot ammonia co-firing and hydrogen direct reduction steelmaking.
Saudi Arabia
NEOM's renewable-powered ammonia export facility and existing refinery hydrogen networks sustain project development momentum. The national hydrogen strategy targets blue and green hydrogen exports to European and East Asian offtakers. Industrial zones at Jubail and Yanbu integrate carbon capture with existing steam methane reforming capacity for lower-carbon output.
Hydrogen Generation Market Vendor Landscape
Capacity expansion dominates the current landscape as electrolyzer manufacturers race to secure multi-gigawatt supply contracts before equipment delivery bottlenecks harden. The vendor base stratifies between integrated industrial gas conglomerates with captive demand and specialized electrolyzer pure-plays competing on modular system design. Three archetypes anchor competitive positioning: legacy industrial gas distributors leveraging existing hydrogen infrastructure, electrolyzer technology specialists competing on stack efficiency and manufacturing scale, and energy majors repurposing downstream assets for low-carbon hydrogen production. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with players seeking to anchor offtake relationships in coastal industrial clusters before rival suppliers capture long-term contracting windows.
Within the integrated industrial gas tier, Linde plc and Air Liquide occupy positions that exemplify infrastructure-led competitive advantage through existing hydrogen distribution networks and refinery relationships. Among technology specialists, Siemens Energy AG and Nel ASA represent divergent strategic bets on proton exchange membrane versus alkaline electrolyzer architectures. At the energy major end, Shell plc anchors a position that bridges upstream renewable project development with downstream hydrogen offtake integration.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Siemens Energy AG |
| Shell plc |
| Saudi Arabian Oil Co. |
| Cummins Inc. |
| Nel ASA |
| Plug Power Inc. |
| Others |
Supply Flow & Price Mechanics
Captive integration of electrolyzer stack manufacturing with renewable project development anchors both supply security and pricing power for hydrogen producers in carbon-regulated jurisdictions. This vertical control over membrane electrode assembly production and dedicated offtake contracting compresses margin leakage to equipment suppliers while locking in long-term cost visibility for steel and ammonia buyers.
Pricing Analysis
Distributor margins on electrolyzer systems compress as manufacturers pursue direct-to-project-developer sales channels for multi-gigawatt installations. Contract-based long-term offtake agreements with fifteen-to-twenty-year tenors dominate industrial procurement, with price differentiation driven by carbon intensity certification tier and volume scale commitments. Pricing pressure stems from Chinese stack manufacturers entering European markets through aggressive equipment financing. Ammonia producers exhibit highest price sensitivity due to thin fertilizer margins, while fuel cell mobility operators accept premium pricing for high-purity hydrogen.
Supply Chain Analysis
Refurbishment flows for proton exchange membrane stacks remain underdeveloped relative to projected installation volumes, creating aftermarket service gaps. Stack manufacturing concentrates in Germany, China, and Norway, while iridium catalyst and perfluorinated membrane materials draw from South African mining and Japanese chemical production. Single-source vulnerability in iridium supply chains threatens electrolyzer cost trajectories. Distribution runs through EPC contractors with integrated engineering and commissioning capabilities rather than traditional industrial gas distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen generation market functions as a geographic-arbitrage play where EU carbon border tariffs and US IRA production tax credits create divergent project economics that redirect capital toward jurisdictions with the most favorable subsidy structures.
For Market Incumbents: Deepen backward integration into iridium catalyst recycling and membrane electrode assembly production to defend against Chinese equipment cost compression. Anchor captive demand through fifteen-year offtake contracts with steel decarbonization projects at Rotterdam and Hamburg port clusters before emerging alkaline electrolyzer specialists capture industrial procurement windows.
For New Entrants and Emerging Players: The premium-to-economy price gap in distributed mobility fueling infrastructure offers white-space entry for modular proton exchange membrane systems with rapid deployment capabilities. Target California heavy-duty trucking corridors and Japanese urban bus fleet operators where fuel cell infrastructure subsidies sustain premium hydrogen demand. Pursue equipment-leasing models to bypass capital-intensive balance sheet requirements.
For Investors and Strategic Acquirers: Roll-up economics work for electrolyzer service specialists because technician scarcity and certification bottlenecks create fragmented aftermarket opportunities across installed base geographies. Target mid-scale alkaline system integrators with established relationships in European coastal industrial clusters. Monitor F-Gas Regulation compliance timelines as inflection indicators for membrane material substitution investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Multi-gigawatt production lines in Germany and China compress capital costs for steel sector offtakers. |
| Backward Integration into Catalyst Supply | In-house iridium sourcing hedges against South African mining concentration and price volatility. |
| Long-Term Offtake Contracting | Fifteen-year supply agreements with Rotterdam direct reduced iron producers lock in revenue visibility. |
| Green Certification Program | EU-approved carbon intensity auditing opens access to premium-priced industrial hydrogen procurement. |
| Joint Venture with Offshore Wind Developers | North Sea electrolyzer platforms secure dedicated renewable feedstock for continental pipeline injection. |
Methodological Framework
Direct dialogue with electrolyzer manufacturing executives, EPC project developers, steel sector procurement leads, and utility planning officers grounded qualitative findings in operational realities across European and North American deployment corridors. Secondary validation drew from EU IPCEI funding disclosures, FERC interconnection queues, IEA hydrogen project databases, and SEC filings from listed industrial gas conglomerates. Bottom-up electrolyzer shipment tallies and top-down hydrogen demand modeling from steel and ammonia sectors were triangulated against policy scenario frameworks.
Bottom-up volume estimates aggregated electrolyzer nameplate capacity by technology archetype across announced project pipelines, while top-down demand projections calibrated industrial hydrogen consumption against carbon pricing trajectories and steel decarbonization mandates. Segmentation modeling spanned production method, application end-use, and regional regulatory framework clusters. CAGRs were derived from least-cost technology switching curves under varying carbon price assumptions, with electrolyzer learning rate curves and renewable electricity cost forecasts as primary sensitivity inputs.
Caveats apply where IRA credit guidance revisions or EU carbon border adjustment implementation delays could materially shift the outlook for green hydrogen cost competitiveness. Periodic stress-testing of base assumptions against stack manufacturing capacity buildout timelines and iridium supply constraints is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Brown Hydrogen Market