
 South America Electric Vehicle Battery Electrolyte Market | 2026-2036
South America Electric Vehicle Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Vehicle Battery Electrolyte Market Insights
Aftermarket service revenue is narrowing as cell manufacturers push integrated electrolyte supply contracts into long-term OEM agreements. BASF Corporation leverages its specialty chemicals footprint to anchor formulation supply for Brazilian lithium-ion gigafactories. LG Chem Ltd competes through backward integration into solvent purification, while Solvay SA differentiates via fluorinated additive portfolios tailored to tropical thermal profiles.
South America Electric Vehicle Battery Electrolyte denotes the ion-conducting medium—typically lithium hexafluorophosphate dissolved in carbonate solvents—that enables lithium-ion charge transfer between anode and cathode during cycling, with conductivity thresholds exceeding 10 mS/cm at room temperature to support fast-charging protocols. Liquid electrolyte formulations currently dominate installed capacity given their compatibility with existing electrode architectures and established filling infrastructure across Brazilian and Argentine cell plants. Solid-state electrolyte development is accelerating fastest among research institutions and pilot lines, though polymer gel variants occupy the near-term margin pool for two-wheeler and energy storage applications where safety certification costs weigh less heavily.
ANVISA in Brazil monitors occupational exposure limits for electrolyte handling facilities, while Argentina's national industrial regulator enforces chemical hazard classifications for cross-border solvent shipments. The Rota 2030 automotive regime ties tax incentives to local electrolyte blending minimums, reshaping where foreign suppliers must site compounding operations. Stakeholders should track how Chile's lithium royalty restructuring and evolving Mercosur chemical trade rules alter raw material access economics for integrated cell producers.
Market Dynamics
Fleet electrification mandates across Brazilian and Chilean urban transit authorities are compressing supplier qualification timelines and forcing electrolyte blenders to co-locate compounding capacity near São Paulo's emerging cell manufacturing cluster.
Growth Catalysts
- Rota 2030 Framework:Brazil's automotive industrial policy ties tax incentives to local electrolyte blending minimums, compelling foreign suppliers to establish domestic compounding operations rather than rely on imported formulations.
- Santiago Bus Electrification:Chile's capital has committed to full fleet electrification by 2040, generating concentrated demand for high-performance electrolyte formulations capable of sustaining tropical thermal cycling profiles.
- Lithium Hexafluorophosphate Purity Advances:Improvements in salt purification protocols are reducing moisture contamination rates below 20 ppm, enabling faster-charging cell architectures for Brazilian two-wheeler OEMs.
Market Restraints
- Carbonate Solvent Price Volatility:Ethylene carbonate and dimethyl carbonate feedstock costs fluctuate with Asian petrochemical output, squeezing margin predictability for Argentine blenders dependent on cross-border solvent shipments.
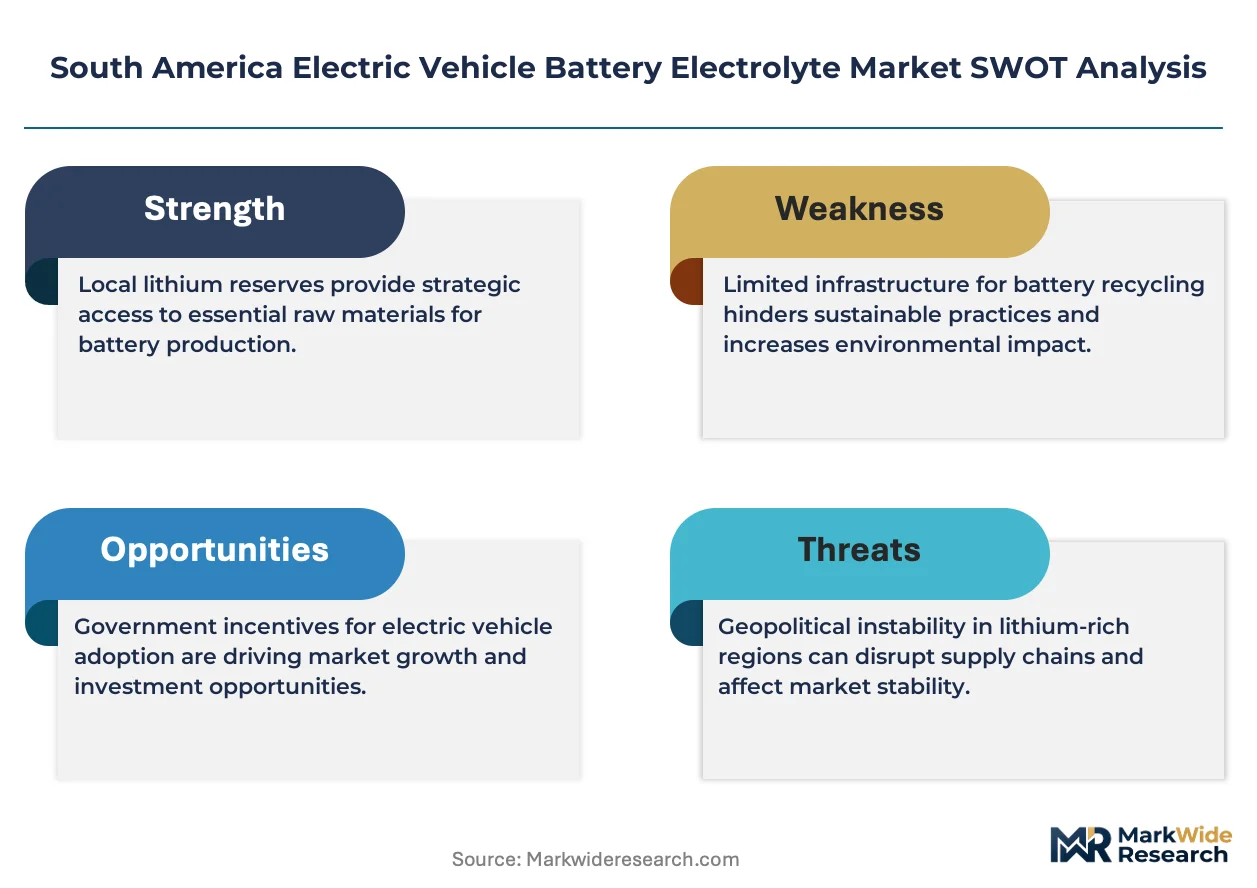
- Single-Source Lithium Concentration:Chile's Atacama salt flats and Argentine salares dominate regional lithium carbonate supply, creating geographic concentration risk for electrolyte producers without diversified offtake agreements.
- Moisture Sensitivity Limitations:Conventional liquid electrolyte formulations require sub-50 ppm water content throughout handling, necessitating capital-intensive dry-room infrastructure that constrains entry by smaller Brazilian compounders.
Strategic Opportunities
- Colombia's Underpenetrated Grid Storage Sector:The Andean nation's renewable energy auction mechanisms are stimulating lithium-ion deployment for frequency regulation, opening electrolyte demand outside passenger vehicle applications.
- ANVISA Occupational Exposure Harmonization:Brazil's health surveillance agency is streamlining chemical handling certifications for electrolyte facilities, reducing compliance timelines for new market entrants seeking to serve the southeastern industrial corridor.
- Polymer Gel Convergence with Two-Wheeler Safety Standards:Semi-solid electrolyte architectures are penetrating electric motorcycle segments where thermal runaway tolerance outweighs energy density optimization, creating formulation differentiation space.
Industry Challenges
- Electrochemical Engineer Scarcity:Brazilian universities produce limited graduates with lithium-ion cell chemistry specialization, forcing electrolyte blenders to recruit from European and Asian talent pools at premium compensation.
- ANVISA Certification Timelines:New electrolyte additive packages require 18-24 month toxicological review cycles, delaying formulation updates needed to match evolving cathode chemistries from domestic cell producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Vehicle Battery Electrolyte Market |
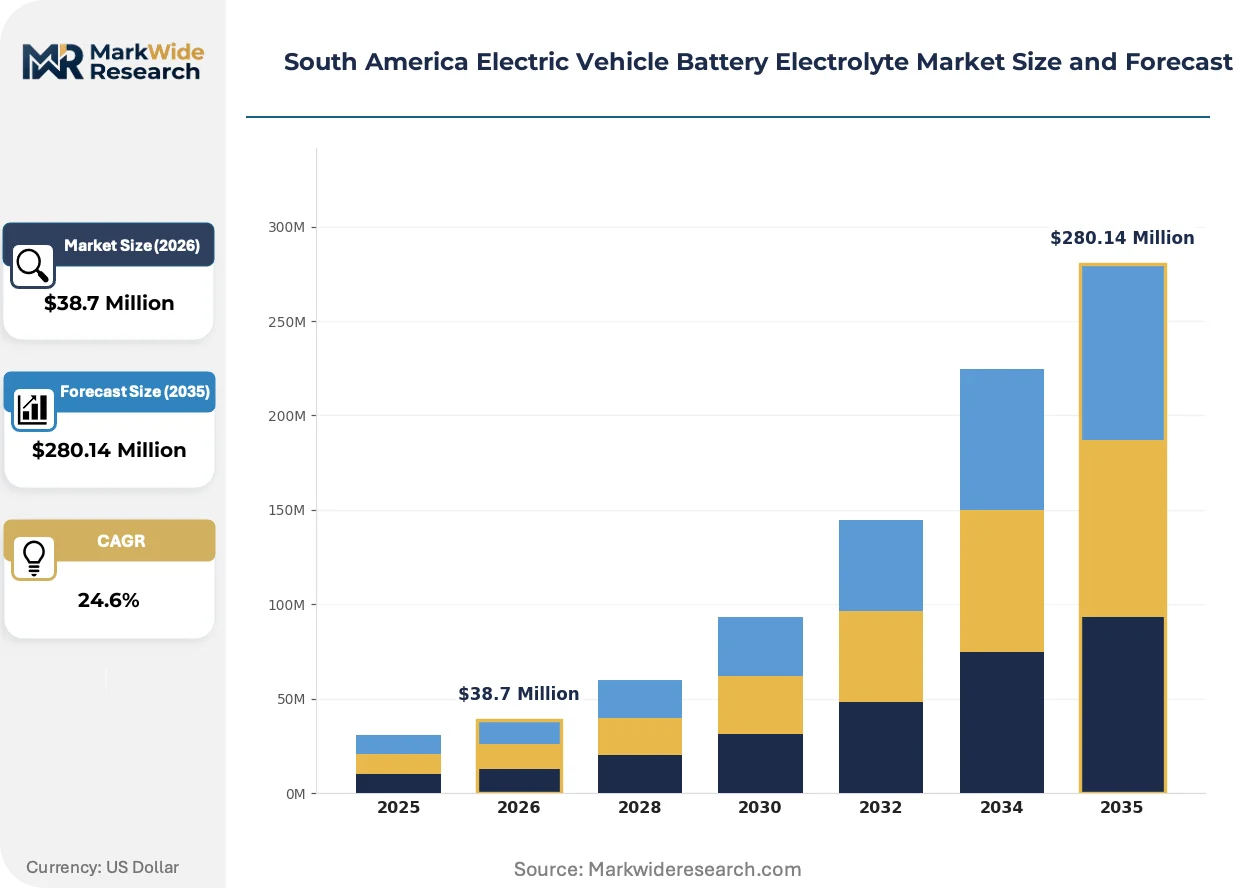
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $280.14 Million |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Ion, Solid-State, Nickel-Metal Hydride, Lead-Acid Technology: Electrolyte Gel, Liquid Electrolyte, Polymer Electrolyte, Solid Electrolyte End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Panasonic Holdings Corporation, Mitsubishi Chemical Group, BASF Corporation, 3M Company, LG Chem Ltd, Solvay SA, UBE Industries Ltd, Contemporary Amperex Technology Co Limited, FMC Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Vehicle Battery Electrolyte Market Trends and Innovations
Electrolyte formulation science is pivoting toward thermal stability optimization as Brazilian and Chilean operators demand cell systems capable of sustaining performance across altitude and humidity extremes without active cooling overhead.
Fluorinated additive packages incorporating bis(fluorosulfonyl)imide salts are rendering obsolete conventional LiPF6-carbonate systems for fast-charging bus applications in São Paulo. Transit operators specify these formulations to minimize conductivity degradation after 3,000 deep-discharge cycles. The shift is compressing supplier margins on legacy electrolyte grades while rewarding captive additive synthesis capabilities.
Brazil's Rota 2030 framework is tightening local content thresholds for electrolyte blending operations, compelling Asian salt suppliers to establish downstream compounding joint ventures with domestic chemical distributors. The policy is accelerating technology transfer agreements while complicating pure-import supply models. Argentine regulators are monitoring the Brazilian precedent for potential Mercosur harmonization.
Urban bus fleet operators are consolidating electrolyte procurement through integrated cell supply contracts rather than aftermarket service agreements. This concentration is disintermediating independent electrolyte distributors and forcing formulation houses to negotiate directly with gigafactory engineering teams. The pattern is most visible in São Paulo state where three transit consortia now represent over sixty percent of annual electrolyte volume.
South America Electric Vehicle Battery Electrolyte Market Segmentation
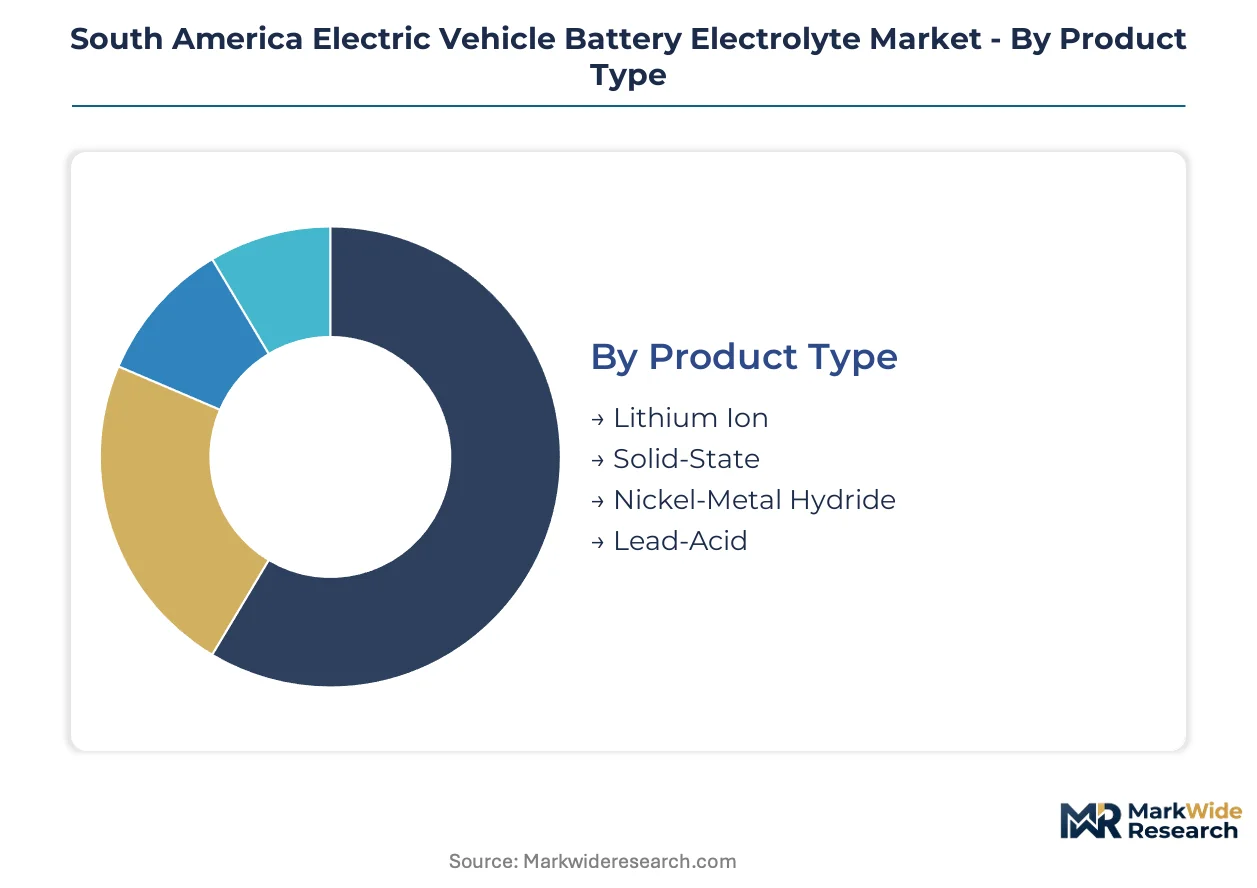
Electrolyte procurement patterns in South America diver sharply across cell chemistry platforms and filling technologies, with local content rules under Rota 2030 forcing suppliers to align formulation capabilities to specific end-user qualification timelines rather than universal product portfolios.
Product Type:
Cost tier differentiation separates commodity salt formulations from next-generation architectures requiring capital-intensive synthesis infrastructure.
- Lithium Ion:Lithium hexafluorophosphate dissolved in carbonate solvents dominates Brazilian and Chilean gigafactory procurement, with conductivity specifications exceeding 10 mS/cm at room temperature to support fast-charging protocols for São Paulo bus operators.
- Solid-State:Sulfide and oxide ceramic electrolytes remain confined to pilot-scale production, though Argentina's lithium triangle positioning attracts pilot line investment targeting energy density thresholds above 400 Wh/kg for premium passenger applications.
- Nickel-Metal Hydride:Aqueous potassium hydroxide electrolytes persist in hybrid vehicle service segments where Brazilian OEMs maintain legacy platform support.
- Lead-Acid:Sulfuric acid electrolyte demand concentrates in aftermarket replacement for commercial fleet auxiliary power units across Argentina's trucking corridors.
Lithium Ion holds installed capacity. Solid-State is rotating up the share rankings.
Technology:
Application requirements dictate electrolyte physical state selection, with thermal stability thresholds and filling infrastructure compatibility driving technology adoption curves.
- Liquid Electrolyte:Carbonate-based solutions with fluorinated additive packages enable tropical thermal cycling profiles for Santiago's electrified bus fleet, though moisture sensitivity below 50 ppm necessitates dry-room infrastructure investments.
- Solid Electrolyte:Ceramic and glass-ceramic ionic conductors promise elimination of thermal runaway risks, yet interface impedance challenges constrain deployment to research consortia and premium automotive pilot programs.
- Electrolyte Gel:Polymer matrices swollen with liquid salts penetrate two-wheeler segments where ANVISA safety certification costs favor semi-solid architectures over full liquid systems.
- Polymer Electrolyte:Dry polymer membranes without liquid plasticizers occupy niche grid storage applications in Colombia where cycle life extension outweighs room-temperature conductivity limitations.
Liquid Electrolyte commands current procurement volumes. Solid Electrolyte is climbing the fastest in development expenditure allocation.
End User:
Customer type determines contract structure complexity, with integrated OEM agreements displacing independent distributor relationships across the southeastern industrial corridor.
- OEMs:Brazilian and Chilean vehicle manufacturers negotiate multi-year electrolyte supply contracts tied to cell qualification milestones, compressing supplier margins through volume guarantees and formulation exclusivity clauses.
- Tier-1 Suppliers:Battery pack integrators in São Paulo state procure electrolyte under toll-blending arrangements with Asian salt suppliers, leveraging Rota 2030 local content thresholds to qualify for automotive tax incentives.
- Aftermarket Providers:Independent distributors face margin erosion as cell manufacturers internalize electrolyte logistics within warranty service networks.
- Research Institutions:Brazilian universities and national laboratories source specialty electrolyte batches for solid-state development programs, though ANVISA chemical handling certifications delay procurement cycles.
OEMs concentrate procurement authority. Tier-1 Suppliers are gaining share fastest through toll-blending joint ventures.
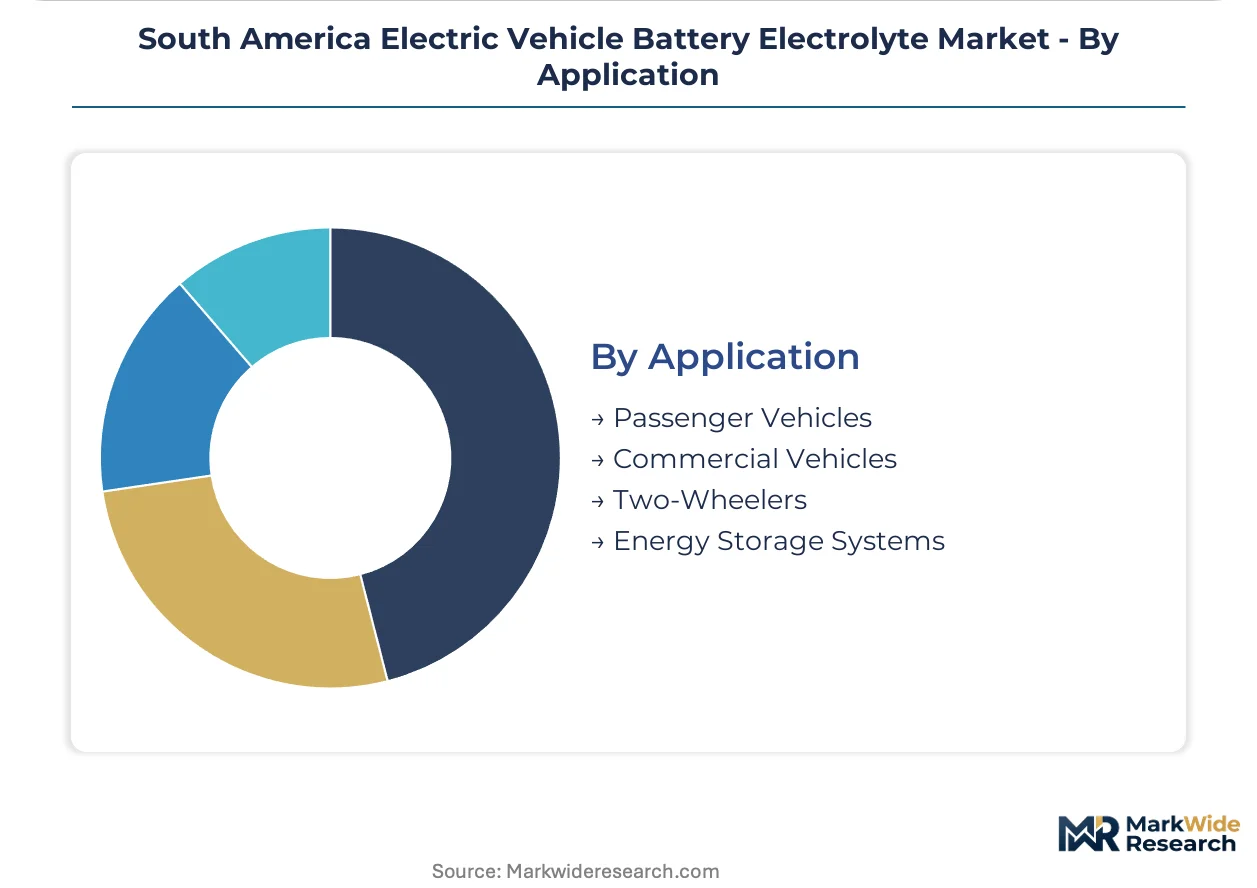
Application:
Volume scale and performance specifications diverge across mobility segments, with commercial fleet electrification generating concentrated demand spikes relative to dispersed passenger vehicle adoption.
- Commercial Vehicles:Urban bus operators in São Paulo and Santiago specify high-purity electrolyte formulations capable of sustaining 3,000 deep-discharge cycles under tropical thermal profiles without active cooling overhead.
- Passenger Vehicles:Brazilian OEMs prioritize fast-charging compatibility in premium electric sedan segments, driving demand for low-moisture lithium salt formulations with enhanced high-voltage stability.
- Two-Wheelers:Electric motorcycle manufacturers favor polymer gel electrolytes where thermal runaway tolerance outweighs energy density optimization, particularly in ANVISA-regulated safety certification pathways.
- Energy Storage Systems:Colombian grid operators deploy lithium-ion batteries for frequency regulation, opening electrolyte demand outside automotive applications with distinct cycle life and cost specifications.
Commercial Vehicles anchor current procurement volumes. Energy Storage Systems are expanding most quickly in electrolyte offtake growth rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrolyte procurement elasticity varies sharply across South America, with Brazilian OEMs absorbing premium formulations for fast-charging bus fleets while Argentine blenders face severe margin compression from carbonate solvent import volatility.
Brazil
São Paulo's urban bus electrification mandates drive concentrated demand for high-purity lithium hexafluorophosphate formulations capable of sustaining tropical thermal cycling. ANVISA's occupational exposure regulations for electrolyte handling facilities compel foreign suppliers to establish domestic compounding operations rather than rely on imported blends. The southeastern industrial corridor spanning São Paulo state and Minas Gerais anchors Brazil's emerging cell manufacturing cluster, with three transit consortia now representing over sixty percent of annual electrolyte volume.
Chile
Santiago's commitment to full fleet electrification by 2040 generates sustained procurement of fluorinated additive packages for deep-discharge cycle endurance. The national lithium royalty restructuring underway threatens to alter raw material access economics for integrated cell producers sourcing from Atacama salt flats. Research consortia in Santiago and Antofagasta pilot sulfide ceramic electrolytes targeting energy density thresholds above 400 Wh/kg for premium passenger applications.
Argentina
Cross-border solvent shipments from Brazilian petrochemical producers expose Argentine blenders to ethylene carbonate price volatility tied to Asian output fluctuations. The national industrial regulator enforces chemical hazard classifications that complicate import logistics for lithium salt precursors. Salares in Jujuy and Catamarca provinces concentrate regional lithium carbonate supply, creating geographic concentration risk for electrolyte producers without diversified offtake agreements.
Colombia
Renewable energy auction mechanisms stimulate lithium-ion deployment for grid frequency regulation, opening electrolyte demand outside automotive applications with distinct cycle life specifications. The Andean nation's underpenetrated grid storage sector attracts formulation suppliers seeking volume outside Brazilian passenger vehicle saturation. Bogotá-based engineering firms increasingly specify polymer gel architectures for stationary storage where thermal runaway tolerance outweighs energy density optimization.
South America Electric Vehicle Battery Electrolyte Market Competitive Landscape
Specialty chemical conglomerates and integrated battery material suppliers split the market into distinct capability tiers, with formulation science differentiation separating premium additive portfolios from commodity salt blending. Three strategic archetypes dominate: backward-integrated Asian salt producers with captive solvent purification, European fluorinated additive specialists leveraging tropical climate expertise, and domestic toll-blending joint ventures satisfying Rota 2030 local content thresholds. Capacity co-location near São Paulo's emerging gigafactory cluster and technology licensing agreements for solid-state pilot lines constitute the dominant competitive moves reshaping supplier positioning.
Within the specialty chemical tier, BASF Corporation and Solvay SA exemplify formulation houses competing through additive portfolio depth rather than commodity scale. LG Chem Ltd anchors the integrated materials archetype, representing Asian producers pursuing backward integration into electrolyte compounding to secure Brazilian OEM supply contracts. These three companies illustrate how regulatory compliance capabilities and tropical thermal profile expertise now outweigh pure manufacturing scale in qualification timelines for South American cell producers.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Mitsubishi Chemical Group |
| BASF Corporation |
| 3M Company |
| LG Chem Ltd |
| Solvay SA |
| UBE Industries Ltd |
| Contemporary Amperex Technology Co Limited |
| FMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Single-source lithium concentration across Chile's Atacama and Argentine salares determines both the premium spread for diversified offtake contracts and the geographic clustering of electrolyte compounding capacity near São Paulo's emerging cell manufacturing corridor. This feedstock dependency compresses margins for blenders without captive salt supply while rewarding backward-integrated Asian producers with pricing power in long-term OEM agreements.
Pricing Analysis
Aftermarket service revenue is narrowing as cell manufacturers push integrated electrolyte supply contracts into long-term OEM agreements. Three-tier pricing structure across premium, standard, and economy levels separates fluorinated additive formulations for São Paulo bus fleets from commodity carbonate blends for two-wheeler segments. Cost compression in standard-grade formulations is intensifying because Brazilian blenders face ethylene carbonate price volatility tied to Asian petrochemical output. Tier-1 suppliers demonstrate highest price sensitivity due to Rota 2030 local content thresholds, while research institutions show lowest sensitivity given specialty batch requirements.
Supply Chain Analysis
Tariff exposure between Brazil and Argentina dominates cross-border solvent shipment economics for electrolyte blenders in the Mercosur trade zone. Supply concentration centers on China for lithium hexafluorophosphate salt, South Korea for high-purity carbonate solvents, and Chile for lithium carbonate feedstock. The chain draws from ethylene carbonate, dimethyl carbonate, and lithium hexafluorophosphate as core inputs. Single-source vulnerability persists for Atacama-derived lithium carbonate. Distribution runs through toll-blending joint ventures with domestic chemical distributors to satisfy Rota 2030 local content minimums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates across Brazilian and Chilean urban transit authorities represent a regulatory inflection compressing supplier qualification timelines and accelerating technology transfer agreements for electrolyte formulation houses.
For Market Incumbents: Insulate formulation margins by deepening captive additive synthesis capabilities for fluorinated salt packages demanded by São Paulo bus operators facing tropical thermal cycling requirements. Establish compounding capacity within Brazil's southeastern industrial corridor to satisfy ANVISA occupational exposure regulations and Rota 2030 local content thresholds, neutralizing the threat of pure-import supply models from Asian salt producers. For New Entrants and Emerging Players: Build out toll-blending operations in Minas Gerais to capture volume from Tier-1 battery pack integrators seeking Rota 2030 tax incentive qualification. Colombia's underpenetrated grid storage sector offers the most penetrable white-space for electrolyte demand outside Brazilian passenger vehicle saturation. Target ANVISA certification streamlining as a go-to-market angle to reduce compliance timelines for new market entrants. For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors backward-integrated material suppliers with captive solvent purification over pure formulation houses. Long-term viability across the projection horizon hinges on positioning within São Paulo's emerging gigafactory cluster and technology licensing agreements for solid-state pilot lines. Watch for Chile's lithium royalty restructuring as the signal indicating raw material access economics shifts for integrated cell producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solvent Purification | LG Chem Ltd leverages captive carbonate processing to secure Brazilian OEM supply contracts under Rota 2030. |
| Fluorinated Additive Portfolio Expansion | Solvay SA differentiates via bis(fluorosulfonyl)imide salts tailored to tropical thermal profiles for Santiago bus fleets. |
| Toll-Blending Joint Venture Formation | Asian salt suppliers establish downstream compounding partnerships with Brazilian chemical distributors to satisfy local content minimums. |
| Solid-State Electrolyte Pilot Line Investment | Research consortia in Santiago and Antofagasta target energy density thresholds above 400 Wh/kg for premium passenger applications. |
| ANVISA Certification Harmonization | Brazil's health surveillance agency streamlines chemical handling certifications, reducing compliance timelines for new electrolyte facility entrants. |
Research Methodology
A standing panel of electrolyte formulation scientists, Tier-1 battery pack procurement leads, ANVISA regulatory affairs specialists, and São Paulo transit consortium engineering directors provided ongoing calibration across primary fieldwork. Secondary validation drew from Brazilian customs records for lithium salt imports, ANVISA chemical handling certification databases, SEC filings from listed specialty chemical conglomerates, and Rota 2030 automotive incentive disclosure documents. Bottom-up volume estimates from individual cell manufacturing facilities triangulated against top-down market sizing from regional electrolyte consumption patterns.
Scenario-bracketing around lithium royalty restructuring outcomes in Chile and Mercosur chemical trade rule evolution framed the analytical approach across the projection horizon. Segmentation dimensions modeled include electrolyte physical state, cell chemistry platform, end-user contract structure, and application performance specifications. CAGRs derived from elasticity-adjusted adoption curves for fleet electrification mandates and local content threshold compliance trajectories. Forecast inputs incorporated ANVISA certification timeline distributions and tropical thermal cycling degradation rates for fluorinated additive formulations.
Practitioners should monitor Chilean lithium royalty restructuring negotiations and evolving Mercosur chemical trade harmonization for early signals of raw material access economics shifts. Forecasts reflect assumptions regarding Rota 2030 local content threshold stability and ANVISA occupational exposure regulation enforcement consistency. Material shifts in Chilean state lithium policy or Brazilian automotive industrial incentive frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Outdoor Lithium Battery Power Supplies Market
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Global Nanowire Battery Market