
 On-Site Hydrogen Generator Market | 2026-2036
On-Site Hydrogen Generator Market Size, Share, and Industry Trends Forecast 2026-2036
On-Site Hydrogen Generator Market Analytics
Buyer concentration in the petrochemical sector is consolidating around integrated refineries seeking captive hydrogen supply. Linde plc leverages its industrial gas infrastructure to anchor large-scale on-site deployments. Nel ASA specializes in proton exchange membrane electrolyzers for distributed generation. BayoTech controls a compact reformer niche serving stranded industrial users.
An on-site hydrogen generator produces hydrogen at the point of consumption through electrolysis, steam methane reforming, or partial oxidation, typically delivering pressures between 30 and 700 bar for industrial feedstock or fuel cell supply. Electrolysis systems dominate technology investment flows as renewable power integration improves unit economics. Fuel cell vehicle applications are expanding fastest within the application matrix, though industrial processes still occupy the majority of installed capacity. Modular installation formats are gaining traction where pipeline infrastructure remains absent.
The US EPA and OSHA frameworks govern emissions and workplace safety for reformer-based installations, while the EU F-Gas Regulation and CE marking shape product standards for electrolyzer equipment sold across Europe. Japan's METI hydrogen roadmap and subsidy programs are directing capital toward domestic manufacturing scale-up. Stakeholders must track how national hydrogen strategies recalibrate eligibility criteria for production incentives and offtake guarantees.
Market Dynamics
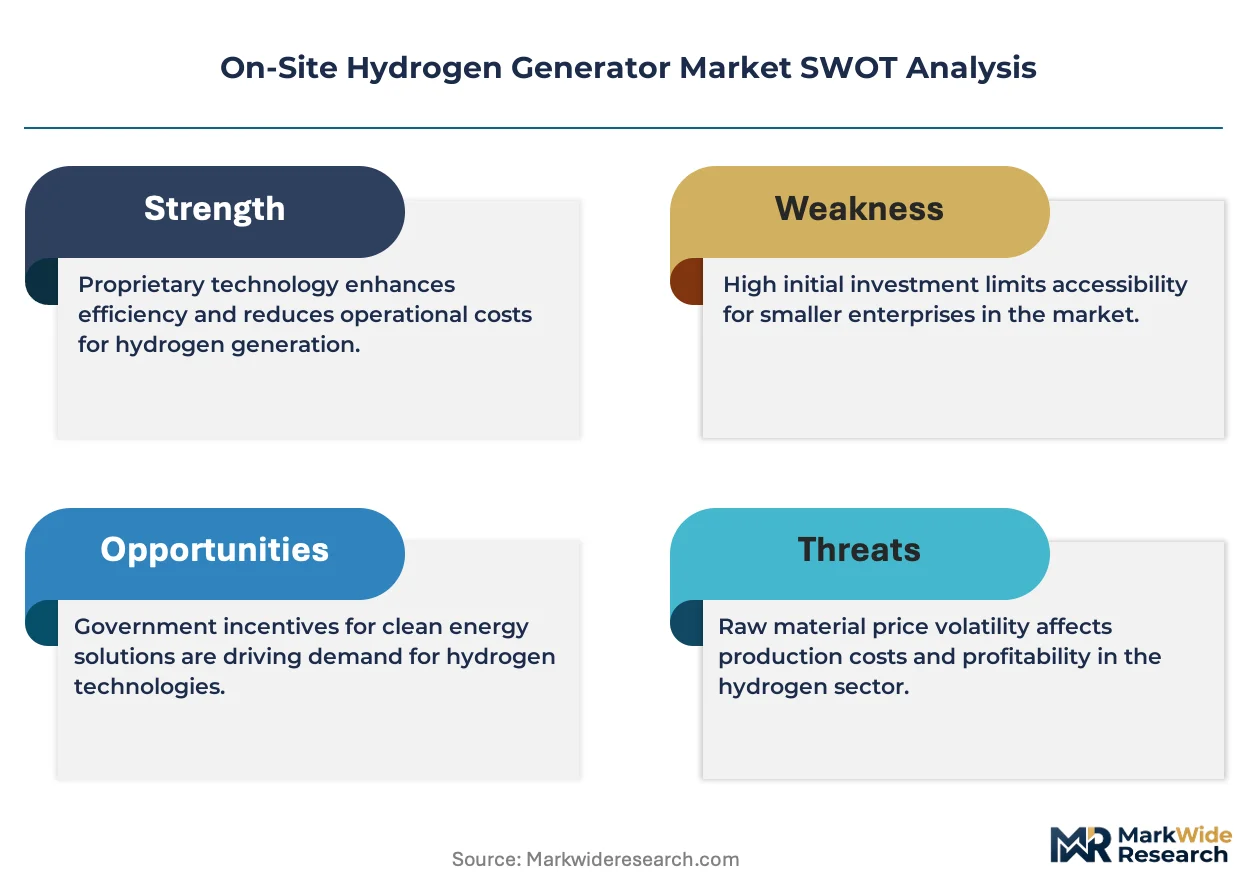
Electrolyzer technology maturation is compressing the cost gap with steam methane reforming, forcing incumbent hydrogen suppliers to reposition around carbon intensity guarantees rather than volume economics alone.
Growth Catalysts
- US Inflation Reduction Act Production Tax Credits:The IRA's tiered credit structure rewards electrolyzer projects with below-threshold carbon intensity, redirecting capital from grey hydrogen retrofits toward greenfield renewable-powered installations.
- Industrial cluster decarbonization mandates:EU F-Gas Regulation phase-down schedules and national hydrogen strategies in Germany and the Netherlands are binding large chemical users to replace naphtha crackers with hydrogen-fed processes.
- Proton exchange membrane scale-up:PEM stack manufacturing learning curves are compressing capital costs for sub-10 MW distributed units, unlocking stranded industrial sites without pipeline access.
Market Restraints
- Platinum group metal supply concentration:PEM electrolyzer catalyst dependency on South African and Russian ruthenium and iridium creates price volatility exposure that alkaline systems avoid.
- Renewable power offtake competition:Grid-scale battery storage and direct industrial electrification projects are bidding up PPA prices in prime solar and wind regions, eroding green hydrogen production margins.
- Pipeline infrastructure lock-in:Existing hydrogen pipeline networks in the US Gulf Coast and Rotterdam-Antwerp corridor perpetuate centralized production economics that disadvantage modular on-site alternatives.
Strategic Opportunities
- Japan METI hydrogen roadmap domestic manufacturing subsidies:Import substitution incentives for electrolyzer stack assembly are creating localized supply chain opportunities for foreign component suppliers establishing joint ventures.
- Fuel cell vehicle refueling network gaps:California's H2Hub program and Germany's National Hydrogen Strategy are funding distributed generation at trucking corridors where pipeline extension remains uneconomic.
- Biomass gasification convergence:Integration of pyrolysis and steam reforming systems is opening carbon-negative hydrogen pathways for hard-to-abate sectors seeking scope 3 emissions reductions.
Industry Challenges
- Electrolyzer stack degradation modeling:Predictive maintenance algorithms for membrane and catalyst lifetime remain underdeveloped, forcing operators into conservative replacement schedules that inflate opex.
- OSHA hydrogen safety compliance:Reforming facility siting and ventilation requirements vary across US state jurisdictions, complicating standardized engineering packages for multi-site deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Site Hydrogen Generator Market |
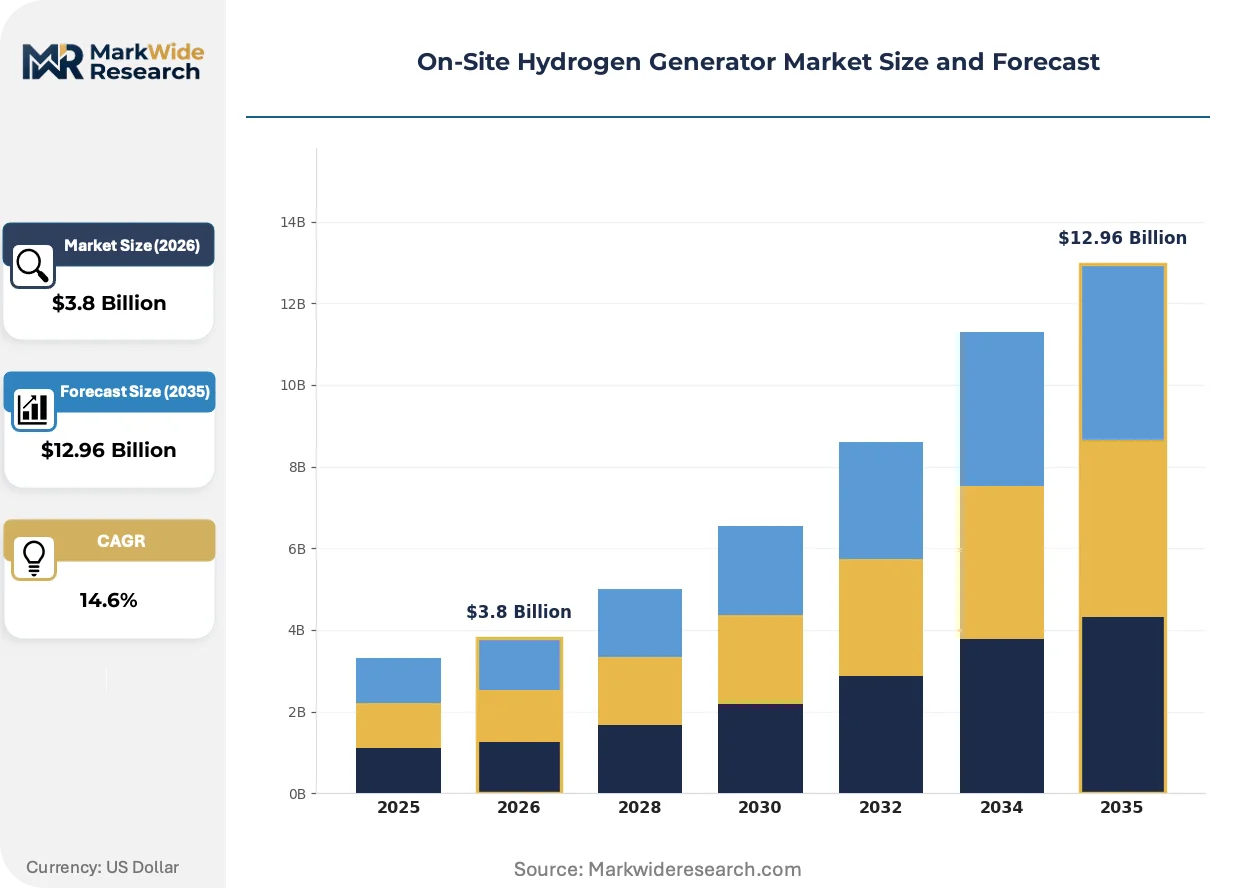
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Partial Oxidation, Biomass Gasification End User: Petrochemical Industry, Energy Sector, Electronics Manufacturing, Food Processing Application: Fuel Cell Vehicles, Industrial Processes, Power Generation, Chemical Production Installation: Fixed Systems, Modular Units, Portable Units, Off-Grid Solutions |
| Companies Covered | SENZA, Linde plc, Element 1, Nel ASA, Air Liquide, LNI Swissgas, Air Products, BayoTech, Millennium Reign Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Site Hydrogen Generator Market Evolving Landscape
Capital allocation patterns are pivoting from megaproject centralization toward modular, relocatable systems that match hydrogen production to intermittent renewable output without transmission infrastructure.
Solid oxide electrolysis is consolidating technical credibility for high-temperature industrial integration. Steel and cement producers with waste heat availability are piloting SOE units that cut electricity input requirements by 20-30 percent versus ambient-temperature alternatives. The technology is compressing the viable project size threshold for on-site generation below 5 MW.
Germany's national hydrogen import strategy is reshaping domestic electrolyzer deployment timelines. The 2024 update to the National Hydrogen Strategy prioritizes import terminals and pipeline corridors, diverting subsidy bandwidth from distributed generation toward centralized import infrastructure. Domestic electrolyzer OEMs are pivoting toward export markets in Scandinavia and Eastern Europe.
Buyers are unbundling hydrogen supply from equipment ownership. Chemical and refining operators are rejecting capex-heavy purchase models in favor of power purchase agreement-style hydrogen offtake contracts with guaranteed availability and carbon intensity. Equipment vendors are responding with lease-and-operate structures that retain performance risk and capture recurring revenue streams. This shift is most pronounced in California and the Netherlands where carbon accounting disclosure requirements intensify.
On-Site Hydrogen Generator Market Segmentation
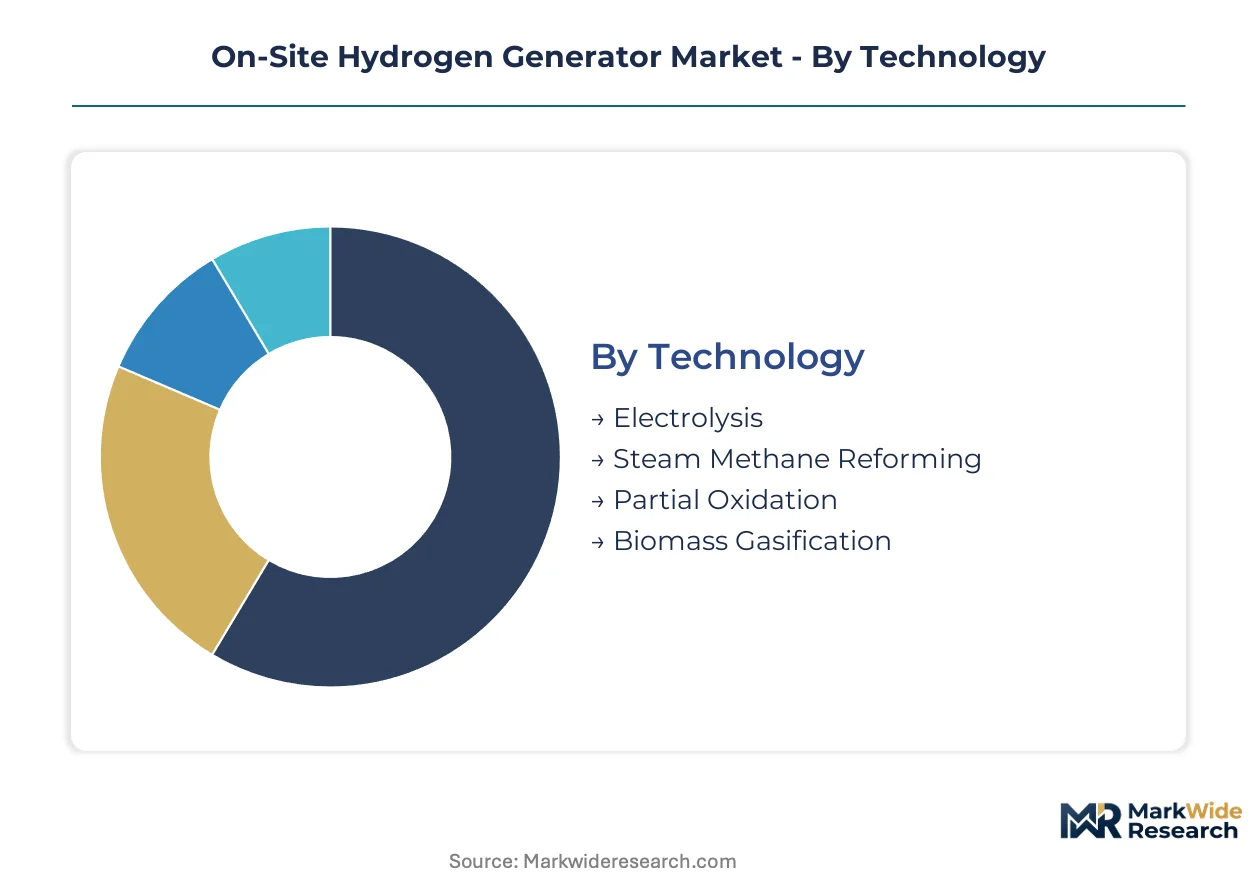
Technology selection dictates capital intensity and carbon footprint for on-site hydrogen installations. End-user concentration in refining and chemicals shapes equipment specifications. Installation format determines project feasibility where pipeline infrastructure remains absent.
Technology:
Standardization dominates at the megawatt scale while customization persists for integration with site-specific heat and power systems.
- Electrolysis:Water splitting via proton exchange membrane or alkaline stacks produces high-purity hydrogen without direct carbon emissions. Demand concentrates at German industrial clusters where EU F-Gas Regulation mandates low-carbon feedstock substitution. Renewable power purchase agreement availability constrains project economics.
- Steam Methane Reforming:Catalytic reaction of natural gas with steam yields hydrogen at scale with mature supply chains. US Gulf Coast refineries anchor demand where existing pipeline networks perpetuate centralized production models. Carbon capture retrofits face IRA credit eligibility uncertainty.
- Partial Oxidation:Heavy hydrocarbon feedstocks convert through oxygen-blown gasification for refinery residue processing.
- Biomass Gasification:Agricultural waste and woody biomass pyrolysis enables carbon-negative hydrogen pathways for hard-to-abate sectors.
Leading the category by volume: Steam Methane Reforming. Expanding most quickly: Electrolysis.
End User:
Volume concentration in commodity chemicals contrasts with margin capture in specialized electronics applications.
- Petrochemical Industry:Refinery hydrocracking and desulfurization operations consume hydrogen for sulfur removal and heavy oil upgrading. Japanese METI hydrogen roadmap subsidies accelerate captive production investments at integrated complexes. Feedstock flexibility requirements favor modular reformer configurations.
- Energy Sector:Grid-scale storage and synthetic fuel production integrate electrolyzers with intermittent renewable assets. California H2Hub program deployments target fuel cell vehicle corridors where pipeline extension costs prove prohibitive. Round-trip efficiency losses limit power-to-power economics.
- Electronics Manufacturing:Semiconductor fabs and flat-panel display lines require ultra-high purity hydrogen for annealing and reducing atmospheres.
- Food Processing:Hydrogenation of edible oils and fat hardening drives modest demand for food-grade hydrogen supply.
Category leadership sits with Petrochemical Industry volumes. Steepest expansion trajectory belongs to Energy Sector applications.
Application:
Process integration depth separates industrial feedstock demand from emerging mobility applications.
- Industrial Processes:Steel direct reduction, ammonia synthesis, and methanol production anchor baseline hydrogen consumption. Netherlands chemical cluster operators bind to national hydrogen strategy decarbonization timelines. Carbon intensity guarantees now outweigh pure volume pricing in procurement decisions.
- Fuel Cell Vehicles:Heavy-duty trucking and bus fleets require distributed refueling infrastructure at 350-700 bar dispensing pressures. Germany's National Hydrogen Strategy funds corridor stations where centralized supply remains uneconomic. Vehicle fleet scale-up lags station deployment commitments.
- Power Generation:Gas turbine co-firing and fuel cell stationary power provide grid balancing services.
- Chemical Production:Specialty chemical hydrogenation reactions and pharmaceutical intermediates synthesis drive smaller-scale demand.
Industrial Processes dominate installed capacity. Fuel Cell Vehicles gain share fastest among application categories.
Installation:
Capital commitment horizons distinguish permanent infrastructure from relocatable assets serving transient demand.
- Fixed Systems:Permanent reformer or electrolyzer installations integrate with site utilities and safety systems for multi-decade operation. Large US refineries prefer this format where hydrogen demand curves remain predictable. Siting permits face OSHA hydrogen safety compliance variability across state jurisdictions.
- Modular Units:Containerized or skid-mounted systems enable rapid deployment and capacity scaling without civil construction. Stranded industrial sites in Scandinavia and Eastern Europe adopt this format where pipeline access remains absent. Manufacturing learning curves compress capital costs below 10 MW thresholds.
- Portable Units:Trailer-mounted generators serve temporary construction or emergency backup requirements.
- Off-Grid Solutions:Remote mining and island installations pair electrolyzers with dedicated renewable microgrids.
Fixed Systems retain volume leadership. Modular Units climb the fastest as distributed generation economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hydrogen demand concentrates in refining corridors and chemical clusters where captive generation economics outperform pipeline delivery. Policy incentives in three continents are redirecting capital from centralized production toward distributed electrolyzer deployment.
United States
Texas and Louisiana refineries anchor reformer-based hydrogen supply for hydrocracking operations. The IRA production tax credits favor electrolyzer projects with verified low-carbon intensity. California's H2Hub program funds modular generation at trucking corridors where pipeline extension costs remain prohibitive.
Germany
Chemical producers in the Rhine-Ruhr cluster face binding decarbonization timelines under the EU F-Gas Regulation phase-down schedules. The 2024 National Hydrogen Strategy update prioritizes import terminals over domestic electrolyzer deployment. Domestic OEMs are pivoting toward export markets in Scandinavia and Eastern Europe.
Japan
Integrated refinery complexes drive captive hydrogen investments under METI hydrogen roadmap subsidy programs. Import substitution incentives for electrolyzer stack assembly are creating localized supply chain opportunities. The Kanto and Kansai industrial belts concentrate demand for modular systems at steel and cement facilities.
Netherlands
Rotterdam-Antwerp corridor operators bind to national hydrogen strategy mandates replacing naphtha crackers with hydrogen-fed processes. Carbon intensity guarantees now outweigh pure volume pricing in procurement decisions. The port authority is expanding electrolyzer capacity to serve bunker fuel and chemical feedstock demand.
China
State-owned refineries in Shandong and Guangdong provinces are piloting electrolyzer integration with dedicated renewable microgrids. Dual carbon goals under MIIT planning documents accelerate domestic stack manufacturing scale-up. Yangtze River Delta chemical parks are adopting containerized systems where pipeline infrastructure remains absent.
On-Site Hydrogen Generator Market Competitive Landscape
European industrial gas conglomerates anchor one tier; Nordic and North American specialists hold differentiated positions in electrolyzer technology and compact reformer systems. The market structure reflects a bifurcation between scale-driven infrastructure players and modular equipment innovators. Three archetypes dominate: integrated gas suppliers with captive hydrogen networks, pure-play electrolyzer stack manufacturers, and compact reformer specialists serving stranded industrial sites. Competitive moves center on lease-and-operate contract structures and cross-border joint ventures for localized assembly.
Within the industrial gas supplier tier, Linde plc and Air Liquide exemplify infrastructure-anchored positioning. Nel ASA occupies a specialist role in proton exchange membrane electrolyzer manufacturing. BayoTech represents the compact reformer archetype targeting distributed industrial applications without pipeline access.
| Leading Market Players |
|---|
| SENZA |
| Linde plc |
| Element 1 |
| Nel ASA |
| Air Liquide |
| LNI Swissgas |
| Air Products |
| BayoTech |
| Millennium Reign Energy |
| Others |
Value Network & Pricing Analysis
Sovereign-backed electrolyzer manufacturers in China and Germany anchor supply-side discipline, compressing margins for private-equity-rolled-up reformer specialists while their state subsidies enable aggressive pricing in export markets. This ownership pattern concentrates pricing power with capital-rich national champions and fragments negotiation leverage among stranded industrial buyers seeking modular units.
Pricing Analysis
Volume concentration in steam methane reforming competes with margin capture in proton exchange membrane electrolyzer deployments. Three-tier pricing structure across premium, standard, and economy levels separates carbon-intensity-certified units from uncertified alternatives from gray hydrogen retrofits. Cost compression in alkaline electrolyzer segments is intensifying because Chinese stack manufacturers are scaling domestic production. Refinery procurement teams exhibit highest price sensitivity due to feedstock margin pressures, while semiconductor fabs show least sensitivity given purity requirements.
Supply Chain Analysis
Platinum group metal supply rests on South African ruthenium producers and Russian iridium refiners, creating geographic concentration that PEM stack manufacturers cannot easily diversify. Electrolyzer production draws from Japanese membrane specialists, German power electronics suppliers, and Chinese steel component fabricators. Single-source vulnerability in catalyst supply exposes price volatility that alkaline systems avoid. Distribution runs through industrial gas conglomerates with captive hydrogen networks and direct OEM sales for modular units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The on-site hydrogen generator market sits in a technology-transition phase where electrolysis systems are displacing steam methane reforming for new capacity additions. This shift reconfigures competitive advantage around renewable power integration rather than natural gas access.
For Market Incumbents: To counter PEM electrolyzer cost compression from Chinese manufacturers, Linde plc and Air Liquide should deepen backward integration into renewable power development to secure low-cost electricity for green hydrogen production. Incumbents must also invest in carbon capture retrofits for existing reformer assets to maintain IRA credit eligibility against pure-play electrolyzer competitors.
For New Entrants and Emerging Players: Launch via lease-and-operate contract structures that retain performance risk and capture recurring revenue from chemical operators rejecting capex-heavy purchase models. Target stranded industrial sites in Scandinavia and Eastern Europe where pipeline infrastructure remains absent and modular deployment economics prove most favorable. Pursue joint ventures with Japanese component suppliers to access METI domestic manufacturing subsidies.
For Investors and Strategic Acquirers: Germany's 2024 National Hydrogen Strategy update prioritizing import terminals over domestic electrolyzer deployment is the leading indicator that domestic OEM pivot timing toward export markets has arrived. Five-to-ten year viability favors vertically integrated specialists with captive renewable power assets and electrolyzer stack manufacturing capability. Watch for IRA credit eligibility rulemakings as the inflection signal for capital reallocation between reformer retrofits and greenfield electrolyzer projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Power | Secures low-cost electricity supply for green hydrogen production competing with gray hydrogen economics. |
| Carbon Capture Retrofit Deployment | Maintains IRA production tax credit eligibility for existing steam methane reforming infrastructure. |
| Lease-and-Operate Contract Structure | Captures recurring revenue from chemical operators rejecting capex-heavy equipment ownership models. |
| Joint Venture for Domestic Manufacturing | Accesses Japan METI hydrogen roadmap subsidies for localized electrolyzer stack assembly. |
| Modular Unit Scale-Up Below 10 MW | Unlocks stranded industrial sites in pipeline-absent regions across Scandinavia and Eastern Europe. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced with primary interviews involving electrolyzer OEM technical directors, refinery hydrogen procurement managers, EPC contractors specializing in industrial gas installations, and renewable power offtake specialists. Bottom-up installation databases and top-down policy incentive modeling were triangulated against SEC filings from Linde plc and Nel ASA, EU F-Gas Regulation implementation timelines, and Japan METI subsidy disbursement records.
Technology, end-user industry, installation format, and regional regulatory framework were modeled at the country-cluster level across the analysis window. CAGRs were derived from segmented demand buildup incorporating IRA credit tier structures, EU industrial cluster decarbonization mandates, and PEM stack manufacturing learning curves. Forecast inputs included renewable power purchase agreement pricing trajectories and platinum group metal supply concentration risk factors.
IRA credit eligibility rulemakings, EU hydrogen import strategy revisions, and electrolyzer stack degradation rate surprises are the dominant revision risks that could shift deployment timelines. Forecasts reflect documented assumptions about policy continuity and technology cost curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market