
 Grid-Scale Stationary Battery Storage Market | 2026-2036
Grid-Scale Stationary Battery Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Grid-Scale Stationary Battery Storage Market Analysis
Project finance and long-term power purchase agreements with embedded storage clauses is rewriting competitive access for developers without utility balance sheets. CATL leverages its integrated cell-to-system manufacturing to dominate cost curves in containerized units. NextEra Energy Resources anchors its position through utility-scale deployment pipelines across multiple ISO territories. Siemens competes on digital grid integration, bundling power electronics with SCADA-compatible control architectures.
Grid-scale stationary battery storage denotes electrochemical systems rated at multi-megawatt capacity, permanently installed at substations or generation interconnection points, typically employing lithium iron phosphate or nickel manganese cobalt chemistries with four-to-eight hour discharge duration and cycle lives exceeding 6,000 operations. These assets buffer intermittency from wind and solar farms, defer transmission upgrades, and provide ancillary services to independent system operators. Lithium-ion chemistry leads installed capacity due to capital cost declines and supply chain scale, while flow batteries occupy niche roles in long-duration applications requiring 10-plus hour discharge. Utility companies represent the deepest customer segment, though commercial businesses are emerging as faster-growing adopters behind-the-meter for demand charge management.
The US Federal Energy Regulatory Commission Order 841 mandates market access for storage resources in wholesale markets, while the EPA greenhouse gas standards for power plants indirectly boost storage co-location with renewable projects. China's MIIT sets domestic lithium battery safety and performance benchmarks that cascade into export supply chains. Europe's EU Green Deal and F-Gas Regulation constrain fluorinated electrolyte chemistries, nosing R&D toward solid-state alternatives. Stakeholders must monitor how interconnection queue reform and evolving capacity market rules reshape project economics and developer returns.
Market Dynamics
Interconnection queue reform is compressing project timelines and forcing developers to front-load capital commitments before offtake certainty solidifies, fundamentally altering risk allocation between utilities, independent power producers, and storage technology suppliers.
Growth Catalysts
- Production Tax Credits:The US Inflation Reduction Act's standalone storage incentive structure is pulling lithium-ion manufacturing capacity toward domestic cell and module assembly facilities.
- Renewable Curtailment:Wind and solar developers in Texas and California are co-locating battery systems to capture otherwise wasted generation during negative pricing events.
- Capacity Market Reform:ISO New England and PJM Interconnection rule changes are allowing storage resources to bid into capacity auctions with shorter duration requirements than thermal plants.
Market Restraints
- Lithium Carbonate Volatility:Battery-grade lithium compound pricing swings are destabilizing project pro formas and triggering force majeure clauses in long-term supply contracts.
- Cell Manufacturing Concentration:Cathode active material and separator production clusters in specific East Asian jurisdictions are creating single-source vulnerabilities for non-integrated developers.
- Duration Arbitrage Limits:Four-hour lithium-ion systems face revenue caps in markets where peak demand periods extend beyond discharge capacity, constraining merchant project returns.
Strategic Opportunities
- Long-Duration Chemistries:Iron-air and vanadium flow battery technologies are opening 10-100 hour discharge segments currently unserved by lithium-ion economics.
- Behind-the-Meter Commercial:Industrial facilities in high-demand-charge utility territories are installing containerized systems to arbitrage time-of-use rates and participate in demand response programs.
- Transmission Deferral:Storage-sited generation is qualifying for FERC Order 1000 cost allocation in congested corridors where traditional line upgrades face permitting delays.
Industry Challenges
- Fire Safety Certification:UL 9540A test protocol compliance is extending product validation cycles by 8-14 months and requiring costly third-party witness testing at cell, module, and system levels.
- Grid Integration Expertise:Scarce power systems engineers capable of configuring inverter-based resources for frequency regulation and black-start capability are commanding premium compensation packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grid-Scale Stationary Battery Storage Market |
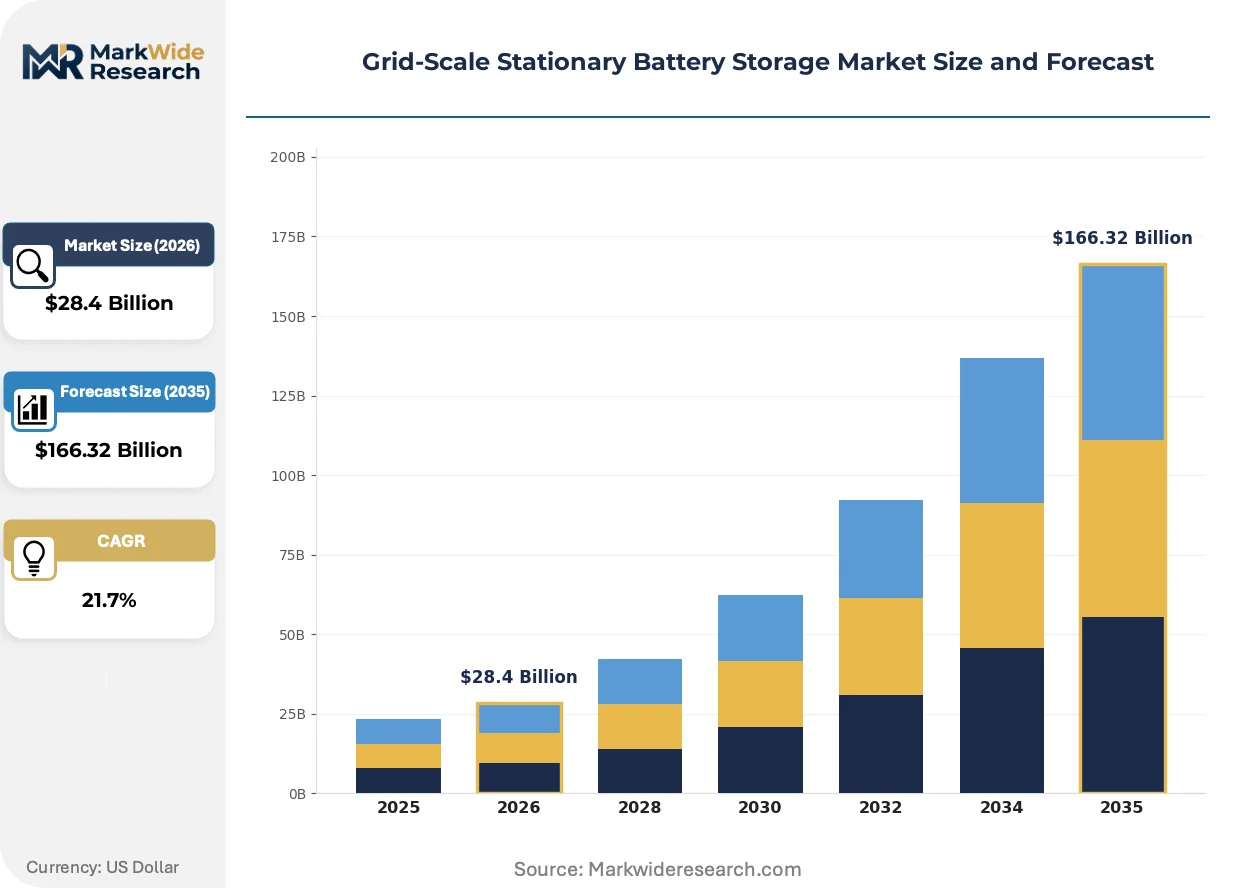
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $166.32 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Flow Batteries, Sodium-Sulfur Installation Type: Standalone Systems, Integrated Systems, Containerized Units, Modular Solutions Usage Objective: Peak Shaving, Frequency Regulation, Load Shifting, Renewable Integration Customer Type: Utility Companies, Commercial Businesses, Industrial Users, Government Agencies |
| Companies Covered | Sungrow, Toshiba, CATL, Delta Electronics, NextEra Energy Resources, BYD Energy Storage, GE Vernova, Hitachi, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grid-Scale Stationary Battery Storage Market Emerging Trajectories
Technology convergence between power electronics and digital control systems is compressing balance-of-plant costs while software-defined architectures are enabling remote firmware updates that extend asset lifecycles without hardware swaps.
Solid-state electrolyte formulations are collapsing thermal runaway risk profiles and enabling higher energy density pack designs. Automotive cell suppliers are repurposing pilot production lines for grid-scale qualification batches. This chemistry transition is collapsing insurance premium spreads between lithium-ion and alternative electrochemical systems in commercial deployments.
The EU F-Gas Regulation is phasing down hydrofluorocarbon-based thermal management fluids in favor of natural refrigerants and dielectric coolants. Module manufacturers are redesigning HVAC subsystems to accommodate CO2 and propane-based cooling loops. European project developers are absorbing first-mover costs for F-Gas-compliant systems to secure construction permits in Germany and the Netherlands.
Virtual power plant aggregation platforms are consolidating distributed storage assets into dispatchable portfolios that bid as single resources in wholesale markets. Commercial and industrial hosts are surrendering operational control to aggregators in exchange for guaranteed lease payments. This control transfer is most advanced in California where Rule 21 interconnection standards facilitate telemetry integration with CAISO market systems.
Grid-Scale Stationary Battery Storage Market Segmentation
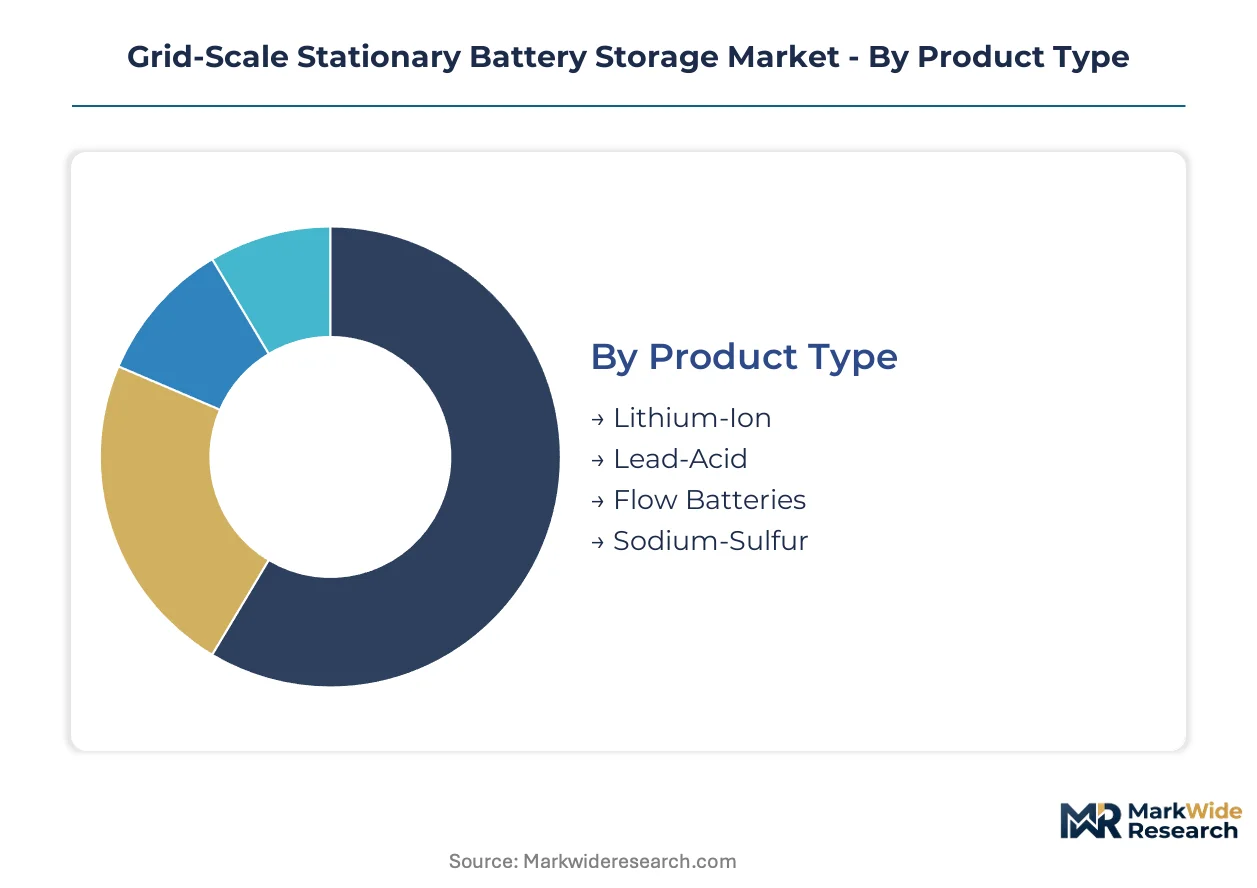
Technology selection and deployment architecture determine project returns across divergent grid service applications. Installation type and customer segment choices reshape capital deployment timelines and operational risk profiles.
Product Type:
Cycle times vary dramatically: lithium-ion systems turn over every 6,000-8,000 cycles while flow batteries stretch toward 20,000 cycles with slower degradation curves.
- Lithium-Ion:Lithium iron phosphate and nickel manganese cobalt chemistries dominate multi-megawatt deployments with four-to-eight hour discharge duration. Texas and California utilities are absorbing containerized lithium-ion capacity fastest where renewable curtailment creates urgent dispatchable storage need.
- Flow Batteries:Vanadium redox systems enable 10-100 hour discharge segments with electrolyte tanks decoupled from power stack rating. Long-duration applications requiring extended discharge are concentrating demand here as lithium-ion economics hit duration arbitrage limits.
- Lead-Acid:Mature technology with lower capital cost but constrained cycle life and energy density limits grid-scale competitiveness.
- Sodium-Sulfur:High-temperature operation requires thermal management infrastructure; niche deployment in specific utility territories with established maintenance protocols.
Lithium-ion dominates installed base. Flow batteries are where expansion concentrates for duration-extended applications.
Installation Type:
Cost tiers separate turnkey containerized units from custom-integrated substation installations with site-specific civil works.
- Containerized Units:Factory-integrated cell racks, thermal management, and power electronics ship as standard ISO-dimension modules. CATL leverages integrated cell-to-system manufacturing to compress balance-of-plant costs here.
- Integrated Systems:Co-located with solar or wind generation at interconnection points sharing transformers and switchyard infrastructure. Renewable developers in PJM and ISO New England territories favor this architecture for capacity market participation.
- Standalone Systems:Grid-connected assets at substations providing pure ancillary services without generation co-location.
- Modular Solutions:Scalable block configurations allowing phased capacity expansion matching load growth or market entry strategies.
Containerized units dominate installed base. Integrated systems are where expansion concentrates.
Usage Objective:
Application type determines revenue stack composition and hardware specification requirements.
- Renewable Integration:Co-located storage captures otherwise curtailed wind and solar generation during negative pricing events. California Rule 21 interconnection standards facilitate telemetry integration with CAISO market systems here.
- Peak Shaving:Discharge during maximum demand periods reduces capacity charges and defers transmission upgrades. Texas utilities deploy four-hour systems for ERCOT summer peak coverage.
- Frequency Regulation:Fast-responding assets maintain grid stability through automated AGC signals requiring sub-second response capability.
- Load Shifting:Arbitrage between low and high price periods demands predictable daily cycling economics.
Renewable integration dominates installed base. Peak shaving is where expansion concentrates.
Customer Type:
Procurement sophistication and balance sheet capacity create distinct contracting patterns across buyer categories.
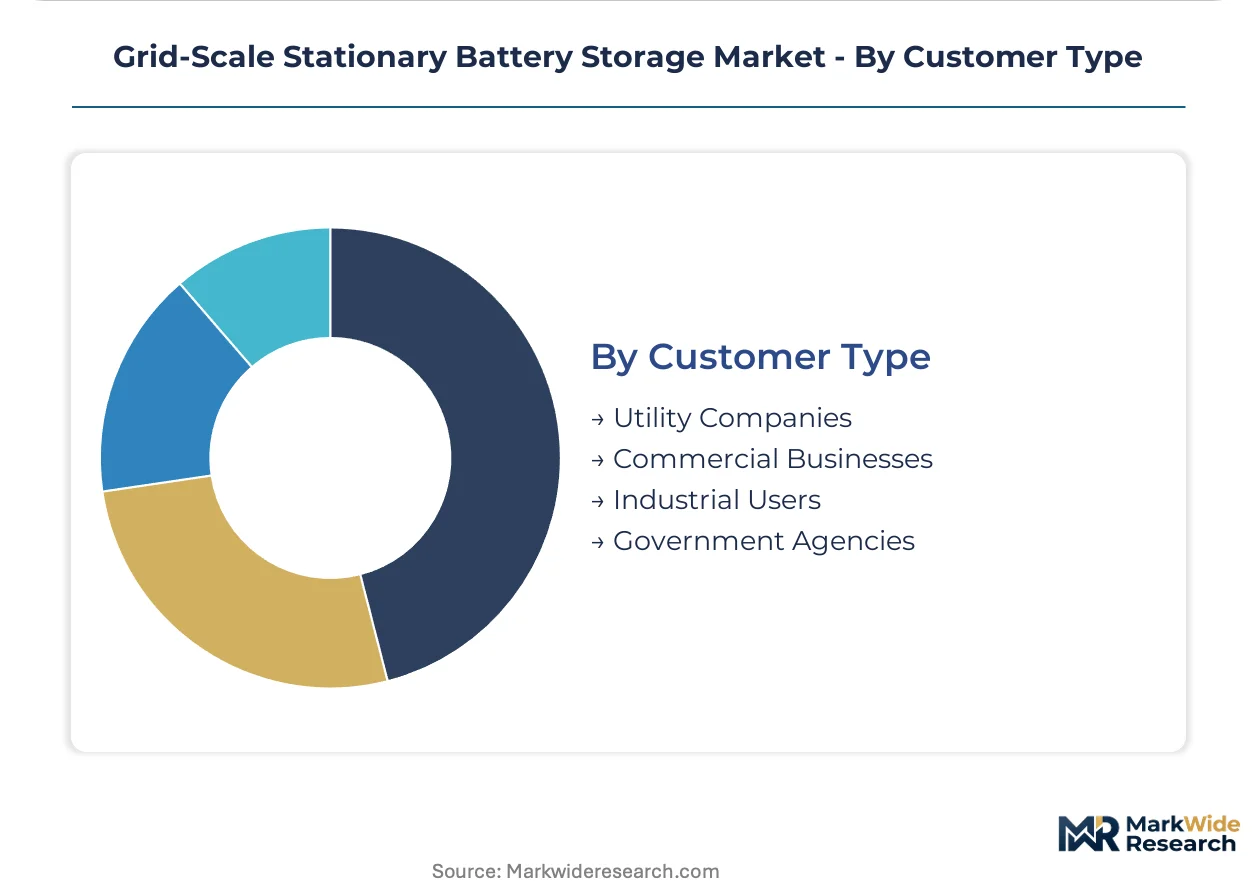
- Utility Companies:Regulated utilities and independent power producers with long-term resource planning horizons and access to tax-advantaged project finance. FERC Order 841 mandates wholesale market access for storage resources here.
- Commercial Businesses:Industrial facilities in high-demand-charge utility territories install behind-the-meter systems. Virtual power plant aggregation platforms are consolidating these distributed assets into dispatchable portfolios in California.
- Industrial Users:Energy-intensive manufacturing sites with predictable load profiles and captive renewable generation seeking demand charge management.
- Government Agencies:Federal and state entities procuring storage for resilience and decarbonization mandates with specific domestic content requirements.
Utility companies dominate installed base. Commercial businesses are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement offices and independent power producers concentrate demand in jurisdictions with volatile wholesale pricing and renewable curtailment events. Developers prioritize markets with streamlined interconnection processes and transparent capacity market rules.
United States
ERCOT price volatility and CAISO renewable curtailment drive utility-scale procurement in Texas and California. The Inflation Reduction Act's standalone storage production tax credits accelerate domestic cell and module assembly investment. Project pipelines cluster in Houston and Dallas-Fort Worth where grid instability creates urgent dispatchable capacity need.
China
MIIT safety benchmarks and dual carbon goals cascade into export supply chains as domestic manufacturers scale cell-to-system integration. The Yangtze River Delta hosts concentrated cathode active material production serving global demand. Shenzhen and Shanghai anchor containerized unit manufacturing for overseas utility contracts.
Germany
F-Gas Regulation phase-down of hydrofluorocarbon thermal management fluids forces HVAC subsystem redesigns for CO2 and propane cooling loops. Project developers absorb first-mover costs to secure construction permits in the Netherlands-adjacent corridor. Industrial Ruhr Valley facilities pilot behind-the-meter peak shaving for demand charge arbitrage.
Australia
Transmission congestion and coal plant retirement timelines compress deployment schedules in New South Wales and Victoria. AEMO market reforms enable storage participation in frequency control ancillary services. Melbourne and Sydney suburbs host virtual power plant aggregation pilots consolidating distributed commercial assets.
United Kingdom
Capacity market rule changes and CfD auction structures reshape developer returns for grid-connected assets. National Grid ESO procurement targets accelerate four-hour lithium-ion deployment for balancing services. Scottish wind farm co-location projects concentrate in Aberdeenshire where curtailment rates exceed grid absorption capacity.
Grid-Scale Stationary Battery Storage Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent customer segments. Integrated cell manufacturers leverage cost curve advantages against power electronics bundlers competing on grid integration capabilities. Three archetypes dominate: automotive spin-offs repurposing pilot lines, utility-affiliated developers securing pipeline access, and industrial conglomerates bundling SCADA architectures. Competitive moves center on manufacturing capacity expansion and strategic partnerships for interconnection queue positioning.
Within the integrated manufacturing tier, CATL and BYD Energy Storage exemplify cell-to-system cost compression through captive cathode supply chains. Siemens and GE Vernova occupy positions as power electronics bundlers competing on digital grid integration architectures. NextEra Energy Resources anchors the utility-affiliated developer archetype through multi-ISO territory deployment pipelines.
| Leading Market Players |
|---|
| Sungrow |
| Toshiba |
| CATL |
| Delta Electronics |
| NextEra Energy Resources |
| BYD Energy Storage |
| GE Vernova |
| Hitachi |
| Siemens |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cathode active material cluster anchors global lithium-ion cell pricing through captive precursor supply and integrated refining capacity. Downstream containerized system manufacturers in Shenzhen and Shanghai translate this upstream cost advantage into competitive bidding positions for utility-scale procurement in Texas and California.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate long-term offtake agreements between cell suppliers and project developers. Price differentiation separates UL 9540A-certified systems from pre-certified alternatives, with brand premiums attaching to integrated cell-to-system manufacturers versus power electronics bundlers. Pricing pressure stems from force majeure triggers in supply contracts when battery-grade lithium compound volatility destabilizes project pro formas. Merchant developers exhibit highest price sensitivity due to merchant project return caps, while regulated utilities with tax-advantaged project finance access absorb premium pricing for interconnection queue positioning.
Supply Chain Analysis
Export-control regimes limiting cathode active material and separator technology flows constrain supply diversification beyond East Asian manufacturing clusters. China, South Korea, and Japan anchor cell and component production, with the Yangtze River Delta and Gyeonggi Province hosting concentrated precursor refining. Raw material dependencies center on Chilean and Australian lithium spodumene, Indonesian nickel laterite, and DRC cobalt hydroxide. Single-source vulnerability concentrates in separator film extrusion and cathode precursor synthesis. Distribution runs through EPC contractors and turnkey integrators who bundle containerized units with installation services for utility procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against iron-air and vanadium flow battery technologies encroaching on 10-100 hour duration segments currently underserved by lithium-ion economics. Incumbents must navigate chemistry transitions that threaten to collapse their four-hour system value propositions.
For Market Incumbents: Entrench position through backward integration into cathode active material production and captive separator supply chains. Accelerate solid-state electrolyte R&D to collapse thermal runaway risk profiles and extend asset lifecycles through remote firmware architectures. Defend against flow battery substitution by securing long-duration pilot deployments with utilities in PJM and ISO New England territories.
For New Entrants and Emerging Players: Establish a beachhead in behind-the-meter commercial installations for demand charge arbitrage in high-tariff utility territories. Target industrial facilities in California and Texas where virtual power plant aggregation platforms consolidate distributed assets into wholesale market participation. Deploy modular block configurations allowing phased capacity expansion that matches customer load growth without front-loaded capital commitments.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive cell suppliers repurposing pilot production lines for grid-scale qualification batches. Long-term viability hinges on manufacturing scale and interconnection queue positioning rather than technology differentiation alone. Watch for FERC Order 841 implementation variance across ISO territories as the inflection signal for developer return compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Domestic cell and module assembly investment accelerates under IRA production tax credits in Texas and California. |
| Backward Integration | Captive cathode supply chains compress cost curves for integrated manufacturers competing on containerized unit economics. |
| Technology Licensing | Power electronics bundlers license SCADA-compatible control architectures to EPC contractors seeking grid integration capabilities. |
| Long-term Supply Agreement | Force majeure clauses in lithium carbonate contracts trigger renegotiation when pricing volatility destabilizes project finance. |
| Joint Venture | Utility-affiliated developers partner with automotive spin-offs to secure cell supply and interconnection queue positioning. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, IPP project developers, EPC contractors, grid operators, and cathode material procurement specialists. Primary interview insights triangulated against EIA deployment databases, FERC interconnection filings, IEA technology roadmaps, and customs trade records for lithium compound flows. Bottom-up project pipeline aggregation and top-down regulatory scenario modeling converged on segment-level capacity forecasts.
Calibration against historical deployment trajectories in ERCOT and CAISO territories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include discharge duration tier, installation architecture, customer balance sheet type, and regional regulatory framework. CAGRs derived from capacity-weighted average of utility procurement announcements and merchant project development timelines. Forecast inputs incorporated IRA credit phase-down schedules and FERC Order 841 implementation variance across ISO territories.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and construction cost inflation would shift the trajectory of merchant project returns. Forecasts reflect assumptions on interconnection queue reform timelines and lithium compound pricing mean-reversion. Material shifts in FERC Order 1000 cost allocation rules or EPA greenhouse gas standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
US Battery Energy Storage System Market
Energy Storage
Power Bank Market
Energy Storage
Battery Storage Boxes Market
Energy Storage
Home Solar Energy Storage Battery Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Residential Energy Storage System Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Australia Energy Storage Systems (ESS) Market
Energy Storage
Electric Double-Layer Capacitor (EDLC) Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Hydrogen Storage Cylinders Market
Energy Storage
Super Capacitor Energy Storage System Market
Energy Storage
Gravity Energy Storage Market
Energy Storage
Double Layer Super-Capacitor Market