
 US Energy Storage Market | 2026-2036
US Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
US Energy Storage Market Analysis
Aftermarket service revenue is reshaping competitive economics in the US energy storage sector. Tesla Inc. leverages its vertically integrated software-hardware stack to capture recurring optimization contracts across utility fleets. Fluence Energy anchors its position through proprietary AI-driven asset management platforms that sustain long-term customer relationships beyond initial hardware sales. NextEra Energy Resources dominates the utility-owned segment by controlling development, construction, and operational phases of large-scale projects.
US energy storage encompasses electrochemical systems designed to absorb, retain, and dispatch electrical energy with round-trip efficiencies typically exceeding 85% for lithium-ion configurations. These systems buffer intermittency from renewable generation and provide grid stabilization services across transmission and distribution networks. Lithium-ion technology occupies the dominant share of deployed capacity due to declining cell costs and established manufacturing scale. Utility end users represent the most capital-intensive segment, while residential installations are expanding fastest behind time-of-use rate restructuring and backup power requirements. Application demand concentrates in renewable integration and peak shaving where stacked revenue streams improve project returns.
The Federal Energy Regulatory Commission's Order 841 mandates market access for storage resources in wholesale markets, while the Inflation Reduction Act extends standalone storage eligibility for investment tax credits previously restricted to solar-paired systems. NERC reliability standards and state-level interconnection rules further shape equipment certification and deployment timelines. Stakeholders must monitor evolving state public utility commission rulings on storage mandate expansions and capacity credit valuations to anticipate procurement cycle shifts.
Market Dynamics
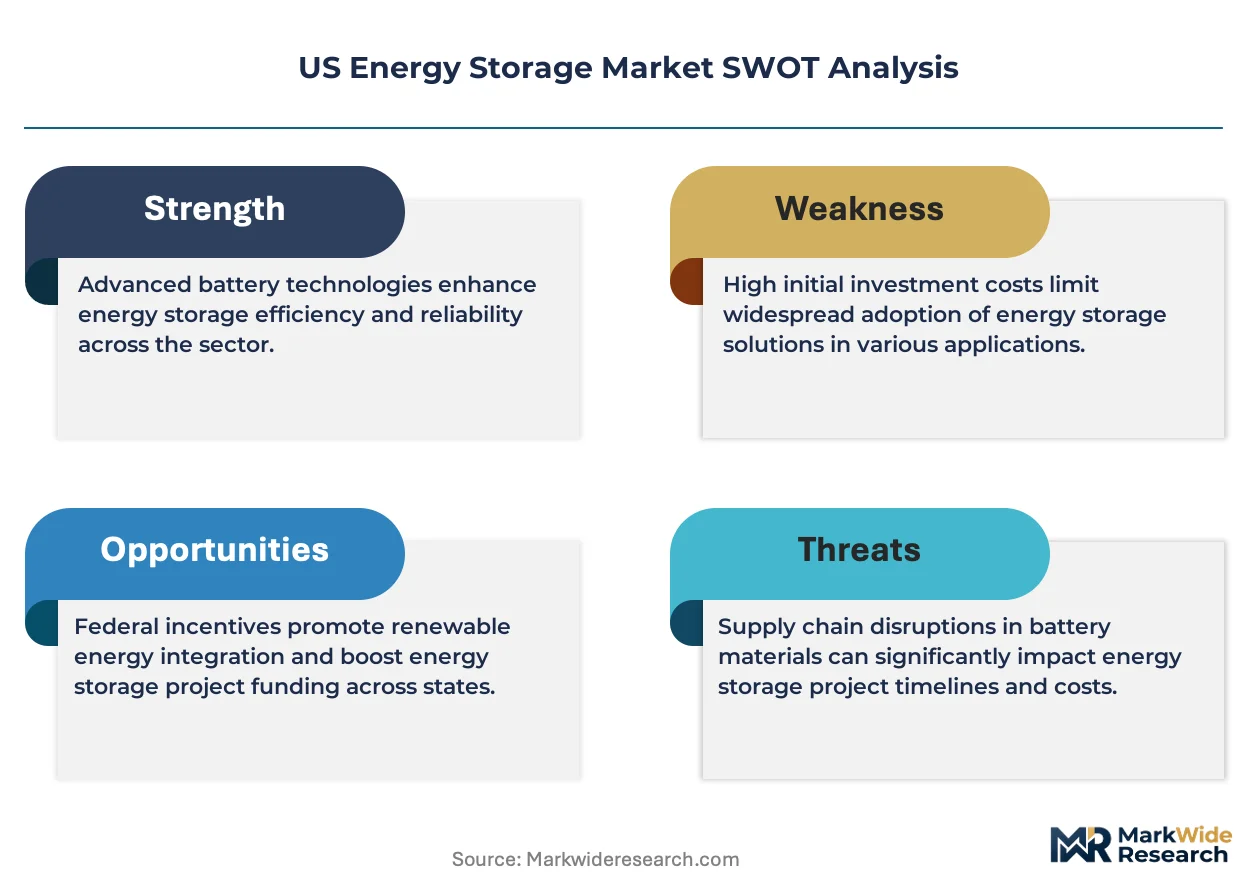
The Inflation Reduction Act's standalone storage tax credit eligibility is restructuring project finance economics and accelerating utility procurement cycles beyond solar-paired deployment constraints.
Growth Catalysts
- FERC Order 841:This mandate requires wholesale market operators to remove barriers for storage participation in capacity, energy, and ancillary service markets across US interconnections.
- Texas grid instability:ERCOT's reliability challenges following winter storms and summer peak demand events are forcing rapid battery procurement by municipal utilities and independent power producers.
- Lithium iron phosphate chemistry:LFP cells are displacing nickel-manganese-cobalt configurations in utility-scale projects due to improved thermal stability and extended cycle life under high-utilization duty cycles.
Market Restraints
- Lithium carbonate volatility:Raw material price swings between South American brine and Australian spodumene supply chains are compressing developer margins and delaying final investment decisions.
- Transformer and switchgear lead times:Electrical balance-of-plant equipment from domestic foundries currently extends beyond 18 months, creating interconnection bottlenecks for completed battery installations.
- Permitting fragmentation:State environmental review processes and local fire code variations create jurisdictional complexity that prolongs project development timelines in California and New York.
Strategic Opportunities
- Arizona renewable curtailment:High solar penetration in the Desert Southwest creates arbitrage opportunities for four-hour duration storage capturing otherwise spilled midday generation.
- Investment Tax Credit stacking:The IRA's domestic content bonus and energy community adders can compound base credits for projects sited in qualifying census tracts with prevailing wage compliance.
- Hybrid inverter architectures:Integration of solar PV and battery DC-coupled systems reduces conversion losses and balance-of-plant costs for co-located renewable plus storage developments.
Industry Challenges
- Electrochemical safety engineering:NFPA 855 fire code compliance and thermal runaway propagation testing require specialized expertise that remains scarce in regional engineering firms.
- Revenue stack optimization:Battery operators must simultaneously manage wholesale energy arbitrage, frequency regulation, and resource adequacy contracts across multiple market products with conflicting dispatch signals.
- Decommissioning liability:End-of-life cell recycling and hazardous material disposal obligations lack established cost recovery mechanisms in most utility rate structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Energy Storage Market |
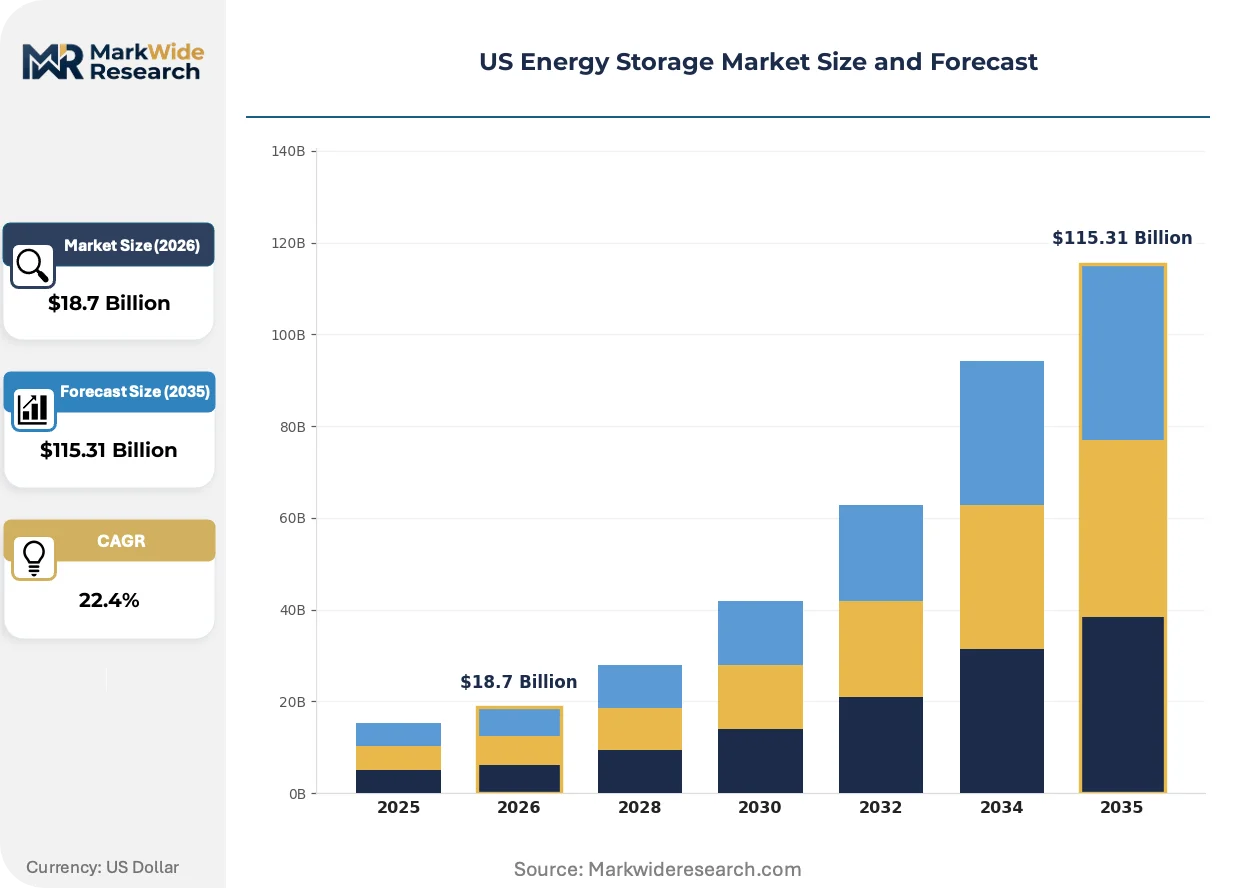
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Flow, Sodium-sulfur Application: Frequency Regulation, Peak Shaving, Renewable Integration, Backup Power End User: Utilities, Commercial, Residential, Industrial Installation: On-grid, Off-grid, Hybrid, Community |
| Companies Covered | Tesla Inc., Fluence Energy, LG Energy Solution Ltd, NextEra Energy Resources, Enphase Energy, Sungrow Power Supply Co. Ltd, BYD Co. Ltd, Powin Energy, AES Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Energy Storage Market Emerging Trajectories
Technology convergence between power electronics and predictive control software is compressing system integration timelines while enabling new revenue streams from stacked grid services.
Solid-state battery prototypes utilizing sulfide electrolytes are collapsing the safety-performance tradeoff that has constrained lithium-ion deployment in dense urban substations. Early-stage pilots by California municipal utilities demonstrate reduced thermal management overhead and extended calendar life. The technology is collapsing insurance premium differentials that previously disadvantaged battery siting near critical load centers.
The Inflation Reduction Act's domestic content requirements are forcing supply chain reconfiguration toward North American cell manufacturing and upstream mineral processing. Projects claiming full credit bonuses must demonstrate 40% domestic value capture for projects beginning construction, rising to 55% for 2025 starts. Developers are responding by offtaking from announced gigafactories in Nevada, Tennessee, and Michigan rather than Asian suppliers.
Long-term service agreements are unbundling from hardware procurement, with independent power producers preferring third-party asset managers over original equipment manufacturer service contracts. This shift fragments the vendor-customer relationship and creates openings for specialized software providers. Texas and California markets show the strongest migration toward performance-guaranteed operational contracts with availability-based compensation structures.
US Energy Storage Market Segmentation
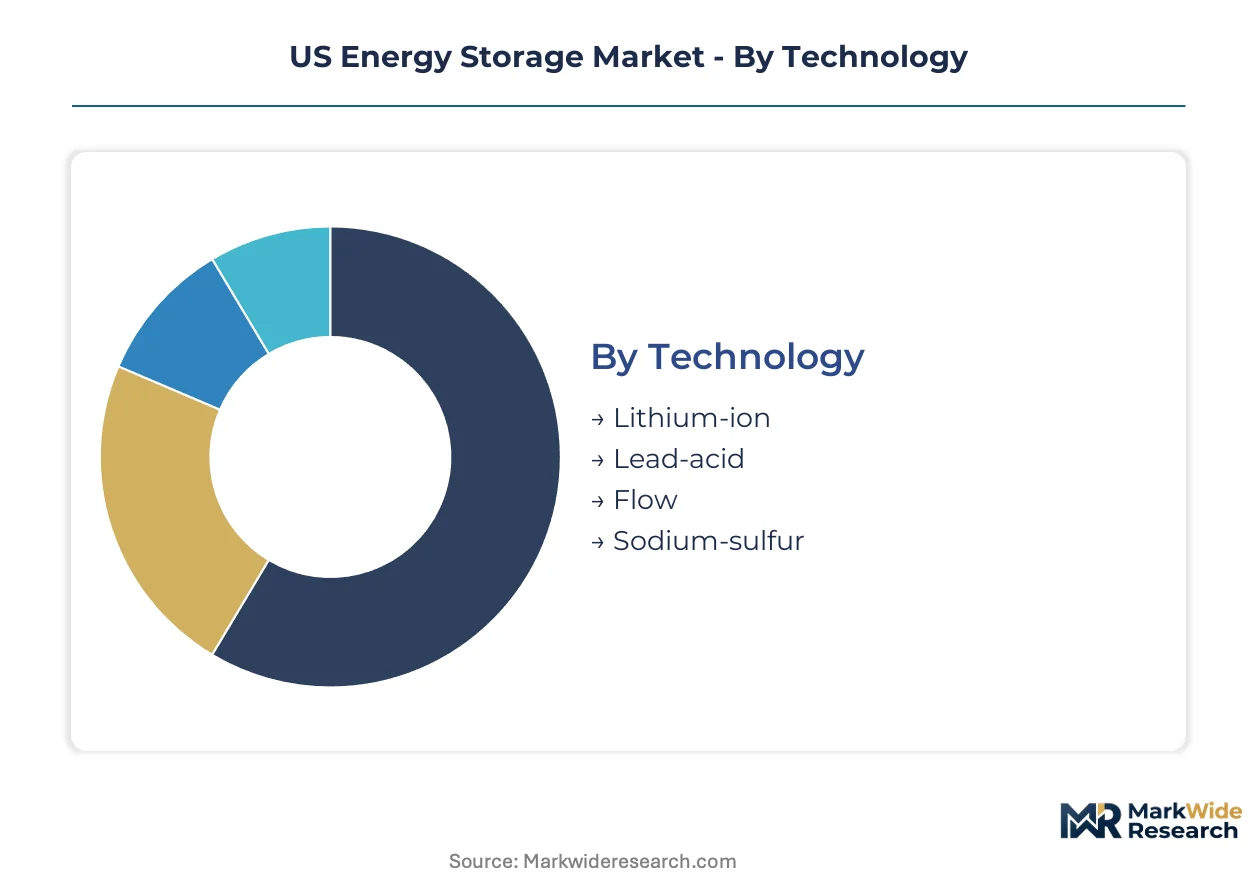
Technology choices in US energy storage lock in twenty-year operational economics and determine revenue stack eligibility across wholesale markets. Segment boundaries are blurring as hybrid inverter architectures enable multi-application dispatch from single installations.
Technology:
Lithium-ion systems turn over fastest through continuous cell chemistry evolution, while flow batteries operate on decade-long replacement cycles with electrolyte refurbishment.
- Lithium-ion:Dominant electrochemical configuration utilizing layered oxide cathodes and graphite anodes with energy densities exceeding 250 Wh/kg. ERCOT and CAISO interconnection queues show overwhelming concentration here as four-hour duration becomes standard for solar-plus-storage economics. IRA domestic content requirements are accelerating North American cell manufacturing commitments.
- Flow:Vanadium redox configurations decouple power and energy scaling through external electrolyte tanks, enabling 8-12 hour durations for renewable firming. Arizona and California utilities are piloting these for evening ramp coverage where lithium-ion degradation economics deteriorate. Slower capital recovery timelines limit developer appetite despite extended cycle life.
- Lead-acid:Mature flooded and valve-regulated designs persist in rural off-grid telecom and backup applications where capital constraints override efficiency requirements.
- Sodium-sulfur:High-temperature ceramic electrolyte systems from Japanese manufacturing bases serve niche utility-scale deployments requiring compact footprint and extreme temperature tolerance.
Lithium-ion dominates installed base. Flow configurations are where expansion concentrates for long-duration procurement.
Application:
Revenue stacking potential varies dramatically by application, with frequency regulation commanding the highest marginal returns per MW but requiring sub-second response capabilities.
- Peak Shaving:Demand charge reduction and coincident peak avoidance drive commercial and industrial deployments across Texas and California utilities with punitive demand ratchets. FERC Order 841 enables wholesale market participation that supplements behind-the-meter savings.
- Renewable Integration:Solar and wind curtailment mitigation plus evening ramp smoothing constitutes the fastest-expanding application category. Arizona and Nevada utilities mandate storage paired with new renewable interconnection requests.
- Frequency Regulation:Fast-responding battery fleets provide primary frequency response in PJM and ERCOT ancillary service markets with four-second AGC signal compliance.
- Backup Power:Resilience-driven procurement accelerates in California fire zones and Texas municipal utilities following grid reliability failures.
Renewable integration leads capacity additions. Backup power is climbing the fastest as climate-driven outages reshape customer willingness to pay.
End User:
Utility procurement operates on multi-year integrated resource planning cycles, while residential purchasing decisions compress to weeks during outage events or rate restructuring announcements.
- Utilities:Investor-owned and public power entities deploy transmission-connected and distribution-sited systems for resource adequacy and grid services. NextEra Energy Resources and independent power producers dominate this capital-intensive segment through build-transfer-operate structures.
- Residential:Single-family and multi-family installations behind the meter respond to time-of-use rate differentials and backup power requirements. California NEM 3.0 export compensation cuts are redirecting solar customers toward storage pairing.
- Commercial:Retail, hospitality, and office facilities target demand charge management and sustainability commitments with 100 kW-2 MW systems.
- Industrial:Manufacturing and data center loads prioritize power quality and uninterrupted operations with on-site battery fleets integrated with existing backup generation.
Utilities dominate installed base. Residential is where expansion concentrates as rate design and net metering reforms propagate.
Installation:
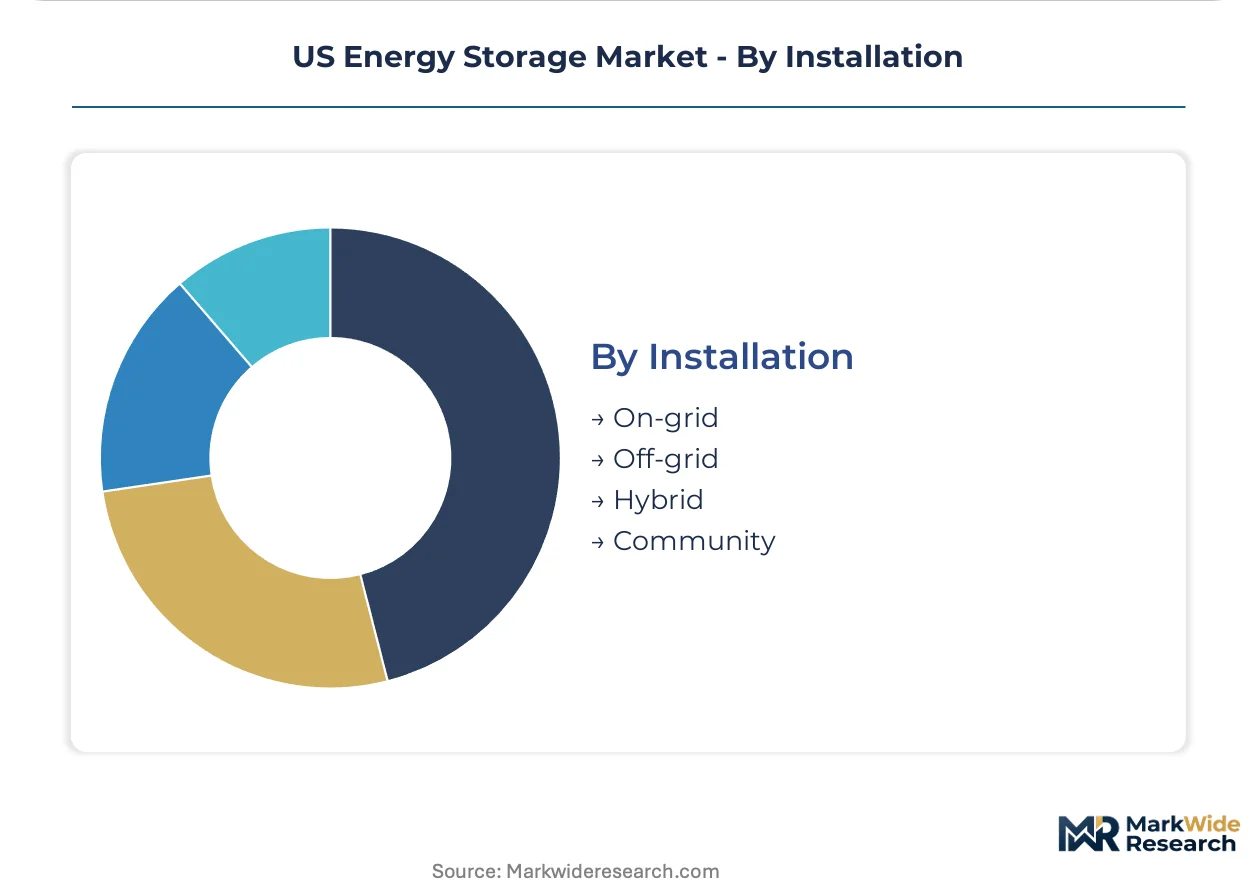
Interconnection complexity and permitting timelines create stark differentiation across installation types, with community models facing the most fragmented regulatory oversight.
- On-grid:Transmission and distribution-connected systems participate in wholesale markets and provide system-wide reliability services. FERC jurisdiction and NERC reliability standards govern these deployments with standardized interconnection procedures.
- Hybrid:Co-located solar PV and battery DC-coupled architectures reduce conversion losses and balance-of-plant costs. Texas and Southwest developers favor this configuration for single interconnection queue positions.
- Off-grid:Remote installations without utility interconnection serve rural residences, telecommunications, and mining operations with solar-diesel-battery microgrids.
- Community:Shared battery assets serving multiple retail customers through virtual net metering or subscription programs. California and New York regulatory frameworks are piloting these structures with unresolved cost allocation disputes.
On-grid dominates installed base. Hybrid is where expansion concentrates as developers optimize interconnection economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas buyers exhibit the lowest price elasticity, absorbing premium equipment costs to secure grid reliability, while California procurement shows higher sensitivity to domestic content bonus thresholds. Arizona and Nevada utilities fall between these extremes, responding to renewable curtailment economics rather than emergency-driven urgency.
California
CPUC storage mandates and NEM 3.0 export compensation cuts are accelerating behind-the-meter pairing with existing solar installations. The California Public Utilities Commission enforces resource adequacy requirements that favor four-hour lithium-ion configurations. The Imperial Valley and Central Valley host dense solar-plus-storage clusters where developers exploit land availability and transmission access.
Texas
ERCOT's scarcity pricing events and winter storm Uri aftermath have created emergency procurement timelines with minimal cost sensitivity. The Public Utility Commission of Texas oversees interconnection standards that favor rapid deployment over lengthy environmental review. The Permian Basin and Gulf Coast corridor concentrate utility-scale projects exploiting existing transmission infrastructure and landowner willingness.
Arizona
High solar penetration and evening ramp requirements are driving four-to-six hour duration procurement for renewable firming. The Arizona Corporation Commission oversees integrated resource planning that mandates storage paired with new renewable interconnection requests. Maricopa County and Yuma agricultural districts host co-located solar-storage developments capturing otherwise curtailed midday generation.
Nevada
NV Energy's renewable portfolio standards and federal land access are concentrating development in the southern desert. The Nevada Public Utilities Commission administers storage incentives tied to grid modernization investments. Clark County and Nye County host transmission-connected projects exploiting Bureau of Land Management permitting pathways and existing high-voltage corridors.
New York
Climate Leadership and Community Protection Act targets are forcing storage deployment despite challenging siting constraints and fire code complexity. The New York State Public Service Commission implements the Accelerated Renewable Energy Growth and Community Benefit Act for streamlined permitting. Long Island and the Hudson Valley host distributed storage pilots addressing urban substation congestion and coastal resilience requirements.
US Energy Storage Market Vendor Landscape
Capability concentration sits with vertically integrated technology developers; scale advantage sits with independent power producers and utility-affiliated entities. The market structure shows bifurcation between hardware-software stack owners and project development specialists. Three archetypes dominate: captive manufacturing platforms, independent power producers with operational control, and pure-play software-integrators. Competitive moves center on domestic supply chain offtake agreements and long-term service contract unbundling from initial equipment sales.
Within the integrated technology tier, Tesla Inc. and Fluence Energy exemplify contrasting approaches to capturing recurring revenue beyond hardware deployment. NextEra Energy Resources anchors the utility-affiliated development segment through build-transfer-operate structures that control project lifecycles from origination through decades-long operation. These three entities represent the dominant competitive vectors shaping procurement relationships and service contract structures across interconnection queues.
| Leading Market Players |
|---|
| Tesla Inc. |
| Fluence Energy |
| LG Energy Solution Ltd |
| NextEra Energy Resources |
| Enphase Energy |
| Sungrow Power Supply Co. Ltd |
| BYD Co. Ltd |
| Powin Energy |
| AES Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate volatility from South American brine and Australian spodumene supply chains compresses developer margins and determines both pricing tier spreads and supply chain shape across the US energy storage sector. This raw material instability forces tier differentiation between premium domestic-content-compliant systems and economy-grade imported configurations.
Pricing Analysis
Long-term service agreements and performance-guaranteed operational contracts drive lifetime value beyond initial hardware sales. Three-tier pricing structure across premium, standard, and economy levels separates Tesla and Fluence's integrated software-hardware stacks from commodity cell assemblers and white-label integrators. Cost compression in economy tiers intensifies because IRA domestic content bonus thresholds disqualify Asian-sourced cells from full credit stacking. Municipal utilities and rural electric cooperatives exhibit highest price sensitivity, while Texas independent power producers absorb premium equipment costs to secure grid reliability.
Supply Chain Analysis
Export-control restrictions on advanced battery manufacturing equipment and semiconductor components for battery management systems limit technology transfer from Chinese and South Korean suppliers. Cell production concentrates in China, South Korea, and emerging North American gigafactories in Nevada, Tennessee, and Michigan. Raw material dependencies span lithium brine from Chile and Argentina, cobalt from the Democratic Republic of Congo, and refined graphite from China. Single-source vulnerability around Chinese cathode active material processing creates structural risk. Distribution runs through original equipment manufacturer direct sales for utility-scale projects and regional integrators for commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US energy storage market sits in early-cycle expansion, with IRA standalone storage tax credit eligibility accelerating adoption beyond solar-paired deployment constraints. Penetration remains below saturation thresholds across Texas municipal utilities and California behind-the-meter installations.
For Market Incumbents: Harden domestic supply chain positions through offtake agreements with North American cell manufacturers to secure IRA domestic content bonuses. Lock in long-term service contract renewals before third-party asset managers fragment vendor-customer relationships. Vertical integration into upstream lithium processing mitigates raw material volatility exposure.
For New Entrants and Emerging Players: Establish a beachhead in Texas frequency regulation markets where scarcity pricing events create premium revenue opportunities. Target Arizona and Nevada renewable curtailment arbitrage segments where four-hour duration economics favor new technology configurations. Deploy hybrid inverter architectures as a go-to-market differentiator against legacy AC-coupled systems.
For Investors and Strategic Acquirers: The market sits at a capacity-buildout phase that favors independent power producers with operational control over project lifecycles. Five-to-ten-year viability hinges on sustained IRA incentive structures and state-level storage mandate expansions. Acquisition target archetypes include specialized software-integrators with AI-driven asset management platforms. Signal to watch: FERC Order 841 implementation pace across regional transmission organizations as inflection indicator for market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Compliance Buildout | IRA bonus credit eligibility requires 40-55% North American value capture for projects beginning construction. |
| Long-Duration Storage Technology Licensing | Vanadium redox and emerging iron-air configurations address 8-12 hour renewable firming requirements in California and Arizona. |
| Grid-Scale Power Purchase Agreements | Utility offtake contracts with NextEra and independent power producers anchor project finance for ERCOT and CAISO interconnection queues. |
| Vertical Integration into Cell Manufacturing | Tesla and LG Energy Solution's captive production secures supply certainty and domestic content qualification for utility-scale deployments. |
| AI-Driven Asset Management Platforms | Fluence's proprietary optimization software sustains recurring revenue relationships beyond initial hardware procurement cycles. |
Methodological Framework
A spread of perspectives from utility planning officers, independent power producer project developers, EPC contractors, and grid operators converged on the working assumptions driving this analysis. Primary interviews with FERC and state public utility commission staff supplemented developer and operator viewpoints. Secondary validation drew from EIA electricity storage databases, IEA renewable integration reports, FERC Order 841 implementation filings, and project development tracking services. Bottom-up capacity and deployment tallies triangulated against top-down market sizing from regulatory mandate trajectories and interconnection queue analysis.
Demand-supply balance framing anchors the forecast framework across the analysis window. Segmentation dimensions modeled include technology chemistry, application type, end-user category, and installation configuration alongside regional regulatory framework differentiation. CAGRs derive from deployment pipeline velocity, policy incentive durability assessments, and technology cost curve trajectories. Key inputs include lithium-ion cell price forecasts, IRA domestic content compliance thresholds, and state-level storage mandate expansion schedules.
Sensitivities concentrate around lithium carbonate price volatility, transformer and switchgear lead time extensions, and state-level interconnection rule modifications. Forecasts reflect documented assumptions on IRA incentive continuity and NERC reliability standard evolution. Material shifts in federal tax credit structures or FERC market access rulings would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Management System
Asia-Pacific Automotive Battery Thermal Management System Market
Battery Management System
Latin America Battery Energy Storage System Market
Battery Management System
North America Battery Management System Market
Battery Management System
South America Battery Energy Storage System Market
Battery Management System
Battery Energy Management System Market
Battery Management System
Energy Storage Technologies Market
Battery Management System
United States Rechargeable Battery Market
Battery Management System
Automotive Energy Storage System Market
Battery Management System
Power Battery Management System Market
Battery Management System
Middle-East and Africa Battery Energy Storage System Market
Battery Management System
North America Energy Storage Market
Battery Management System
Battery Management Market
Battery Management System
EV Battery Management Market
Battery Management System
AC Coupled Solar Battery System Market
Battery Management System
Europe Electric Vehicle Battery Management System Market
Battery Management System
Automotive Lithium-Ion Battery Management System Market