
 Hydrogen for Mobility Market | 2026-2036
Hydrogen for Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen for Mobility Market Insights
Fleet procurement by municipal transit authorities and logistics operators is rebalancing toward long-haul hydrogen contracts away from scattered pilot deployments. Toyota Motor Corporation anchors the passenger fuel cell segment through captive stack production and dealer network control. Hyundai Motor Company leverages integrated megawatt-scale electrolyzer partnerships to secure station throughput commitments. Ballard Power Systems specializes in heavy-duty module architecture that dominates North American bus and truck retrofits.
Hydrogen for mobility encompasses the production, storage, and onboard conversion of hydrogen into mechanical energy for vehicles, typically through proton-exchange membrane fuel cells operating at 60-80°C with 50-60% system efficiency or through modified internal combustion engines with compressed gas at 350-700 bar. Fuel cell systems command the dominant share of deployed commercial vehicles due to superior energy conversion efficiency and zero tailpipe emissions, while hydrogen internal combustion engines occupy a niche in retrofit-heavy freight corridors where battery-electric range falls short. Public transportation leads application deployment through dedicated depot refueling and predictable route profiles, whereas freight transport represents the fastest-expanding segment as logistics companies seek diesel displacement for 500+ kilometer hauls.
The US Department of Transportation coordinates with the EPA under the National Electric Vehicle Infrastructure program to standardize hydrogen station interoperability and funding access. Japan's METI enforces the Green Growth Strategy with specific hydrogen supply chain targets that shape automotive manufacturer R&D allocations. The EU Green Deal and F-Gas Regulation together compress timelines for zero-emission fleet mandates while restricting fluorinated gases used in certain cooling-dependent storage systems. Stakeholders must weigh electrolyzer capacity buildouts against station network density before committing to vehicle platform investments.
Market Dynamics
The hydrogen for mobility sector pivots on electrolyzer capacity buildouts racing against station network density, with fleet operators delaying vehicle commitments until refueling infrastructure achieves corridor-scale coverage. This supply-demand sequencing tension dictates platform investment timing across transit and freight segments.
Growth Catalysts
- EU Green Deal fleet mandates:Binding zero-emission targets for municipal bus procurement in Germany, the Netherlands, and Denmark are compressing diesel replacement timelines and anchoring hydrogen fuel cell orders.
- Long-haul freight corridors:Logistics operators spanning the Rhine-Alpine and Mediterranean freight axes are contracting hydrogen supply to displace diesel on 500+ kilometer routes where battery-electric range proves insufficient.
- Solid-state storage patents:Japanese automotive laboratory breakthroughs in metal hydride compression are shrinking refueling windows toward diesel parity, removing a critical adoption friction point.
Market Restraints
- Electrolyzer input cost volatility:Proton-exchange membrane stacks rely on platinum group metal catalysts concentrated in South African and Russian mining operations, exposing supply chains to geopolitical price shocks.
- Fluorinated gas restrictions:The EU F-Gas Regulation phases down hydrofluorocarbon use in cooling-dependent hydrogen liquefaction systems, forcing storage technology retrofits with uncertain cost trajectories.
- Station network concentration risk:Hydrogen refueling infrastructure deployment clusters in South Korea, Japan, and Germany, leaving freight corridors in Eastern Europe, the US Southeast, and inland China without viable route coverage.
Strategic Opportunities
- Underpenetrated US freight corridors:The I-10 and I-95 trucking routes between Texas and Florida lack hydrogen station density, creating first-mover positioning for electrolyzer-station integrated developers.
- Japan METI supply chain targets:Specific hydrogen import and domestic production quotas under the Green Growth Strategy are redirecting automotive R&D budgets toward fuel cell stack cost reduction programs.
- Depot-based captive production:Municipal bus operators in California and South Korea are deploying on-site electrolyzers to circumvent merchant hydrogen delivery premiums and secure supply certainty.
Industry Challenges
- High-voltage fuel cell technician shortage:The specialized skill set combining proton-exchange membrane diagnostics with high-pressure gas handling outpaces vocational training program output in Germany, Japan, and California.
- Station commissioning timelines:Permitting complexity for 700-bar compression equipment and cryogenic storage systems stretches California Air Resources Board approval cycles, delaying network expansion.
- Legacy fleet integration friction:Retrofit of hydrogen internal combustion engines into existing diesel truck chassis requires chassis reinforcement and tank placement engineering that voids original manufacturer warranties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen for Mobility Market |
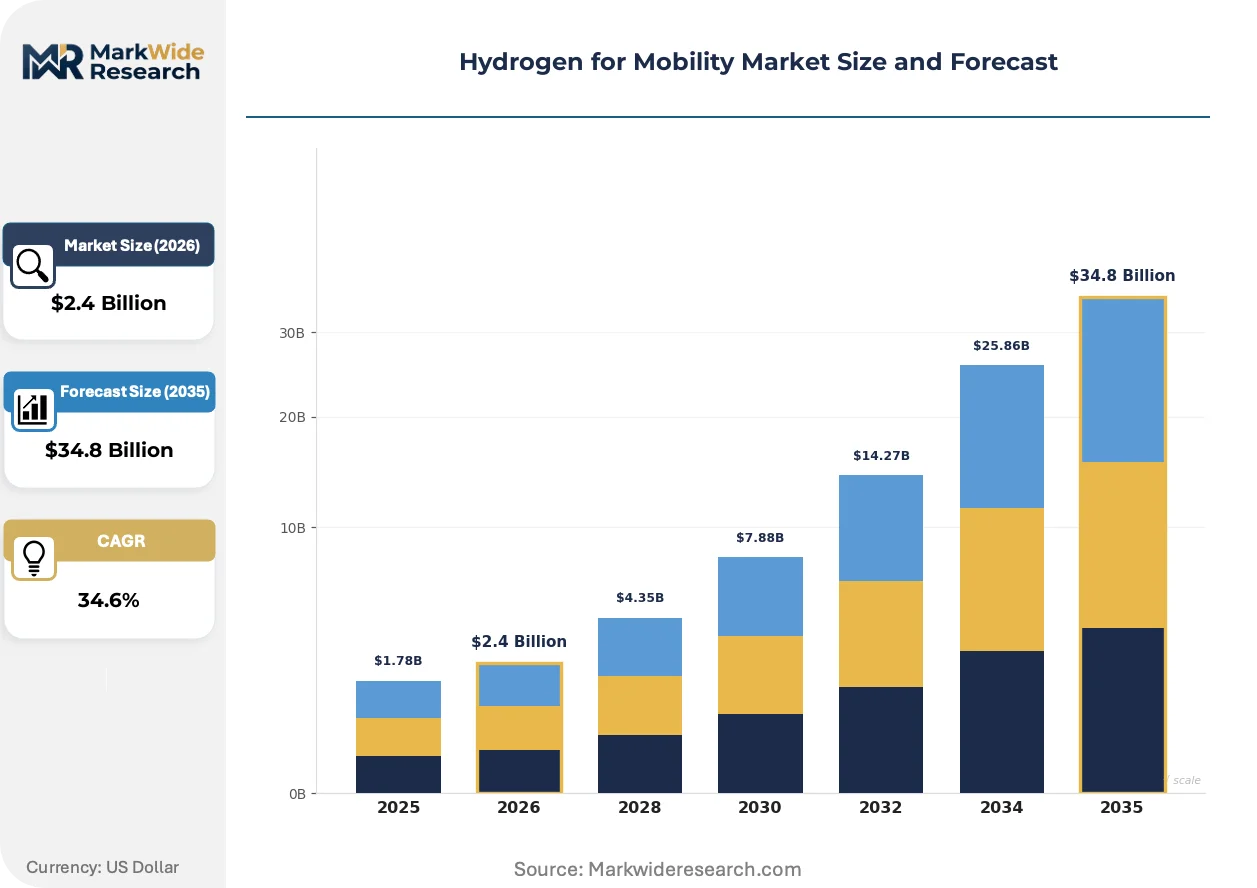
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $34.8 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fuel Cells, Hydrogen Internal Combustion Engines, Hydrogen Storage Systems, Compression Technologies Application: Public Transportation, Freight Transport, Passenger Vehicles, Rail Systems End User: Government Agencies, Logistics Companies, Automotive Manufacturers, R&D Institutions Distribution Channel: Direct Sales, Partnerships, Online Platforms, Distributors |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Honda Motor Corporation, BMW, Ballard Power Systems, Cummins Inc., Daimler AG, SAIC Motor Company, Kia Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen for Mobility Market Trends and Innovations
Technology trajectories in hydrogen mobility center on compression efficiency gains, regulatory compression of fluorinated gas use, and procurement model evolution toward integrated electrolyzer-vehicle contracts that internalize supply risk.
Metal hydride solid-state storage systems are decentralizing hydrogen distribution economics by enabling lower-pressure onboard containment. Municipal bus operators in Germany and South Korea are piloting these systems to reduce depot safety zoning requirements. The structural consequence is compressing the capital intensity gap between hydrogen and battery-electric depot infrastructure.
The EU F-Gas Regulation imposes phasedown mandates on hydrofluorocarbon coolants used in hydrogen liquefaction plants. Industrial gas suppliers are retrofitting storage facilities with magnetic refrigeration or Stirling cycle alternatives. The freight transport segment faces the steepest compliance cost exposure, accelerating interest in compressed gas delivery over liquid hydrogen for 350-bar truck applications.
Fleet procurement is consolidating around electrolyzer-throughput contracts that bundle vehicle supply with station hydrogen offtake guarantees. Logistics operators are displacing scattered pilot deployments with 10-year supply agreements that lock in delivered fuel pricing. This pattern is most visible in California, where the US Department of Transportation NEVI program requires station interoperability certification as a funding condition.
Hydrogen for Mobility Market Segmentation
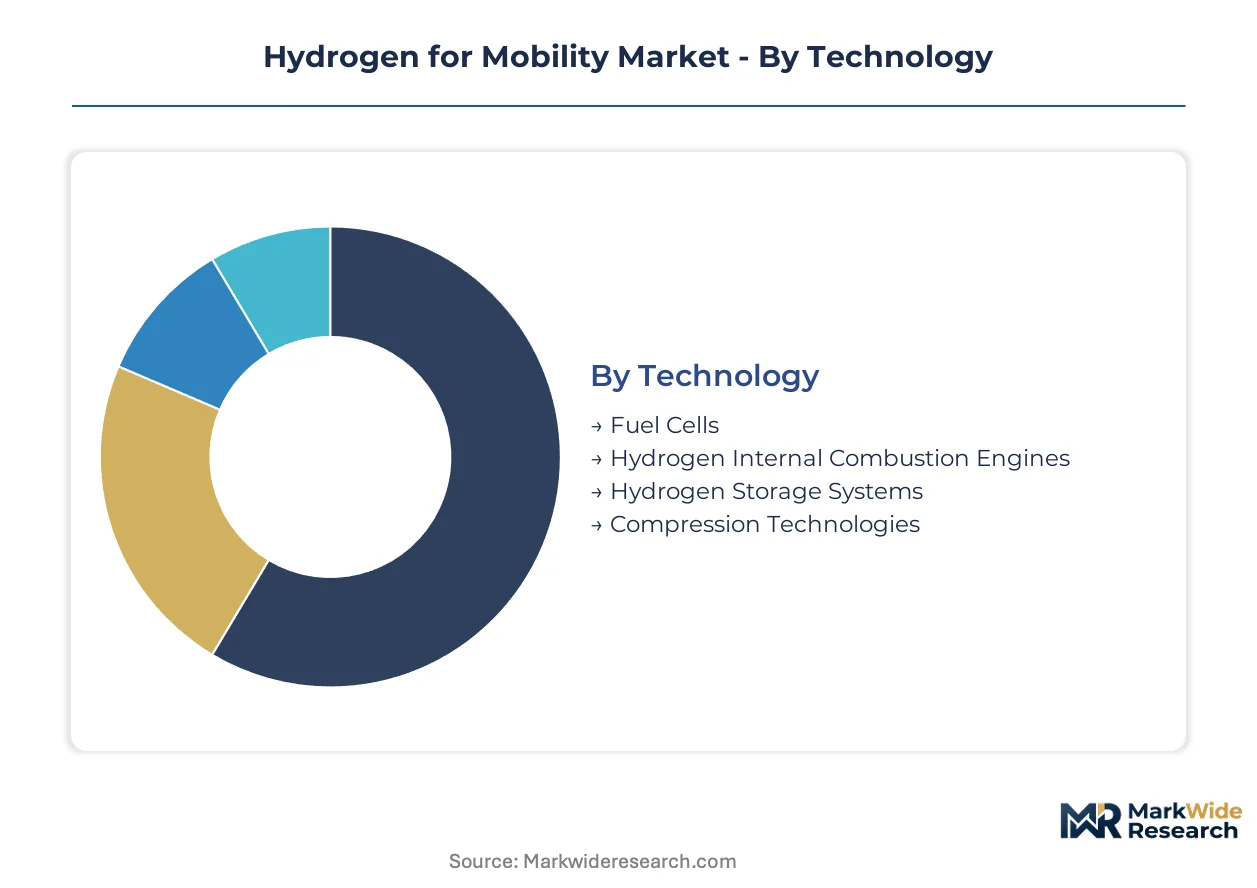
Technology choice dictates infrastructure requirements and total cost of ownership across hydrogen mobility deployments. Application context determines refueling architecture, while end-user procurement power shapes contract structures and supply security mechanisms.
Technology:
Proton-exchange membrane efficiency thresholds and storage pressure specifications differentiate competitive positioning across vehicle platforms.
- Fuel Cells:Electrochemical conversion systems operating at 60-80°C with 50-60% efficiency dominate municipal bus procurement in Germany and California. South Korea's government-backed deployment corridors anchor stack production scale.
- Hydrogen Internal Combustion Engines:Modified compression-ignition platforms using 350-700 bar compressed gas occupy retrofit-heavy freight corridors where battery-electric range falls short. Warranty voiding risks constrain chassis integration engineering.
- Hydrogen Storage Systems:Metal hydride solid-state containment enables lower-pressure onboard distribution. Depot safety zoning requirements shrink versus compressed gas alternatives.
- Compression Technologies:700-bar dispensing equipment and cryogenic liquefaction systems face EU F-Gas Regulation compliance retrofitting. Magnetic refrigeration alternatives are displacing hydrofluorocarbon-dependent cooling.
Mature deployment sits with fuel cells. Newer deployment is concentrated in hydrogen internal combustion engines.
Application:
Route predictability and depot access determine refueling model economics across mobility segments.
- Public Transportation:Dedicated depot refueling with predictable duty cycles anchors municipal fleet procurement. German transit authorities compress diesel replacement timelines under EU Green Deal mandates.
- Freight Transport:500+ kilometer hauls between Texas and Florida lack station density, creating positioning openings for electrolyzer-station integrated developers. Logistics operators contract long-haul hydrogen supply to displace diesel on Rhine-Alpine corridors.
- Passenger Vehicles:Toyota Motor Corporation anchors segment through captive stack production. Dealer network control constrains competitive entry.
- Rail Systems:Fixed-route electrification alternatives face infrastructure cost comparisons. Hydrogen traction competes where overhead catenary installation proves uneconomical.
Public transportation captures established deployment. Freight transport shows the steepest expansion trajectory.
End User:
Procurement scale and supply security requirements fragment contract structures across buyer categories.
- Government Agencies:Municipal transit authorities in California and South Korea deploy on-site electrolyzers to circumvent merchant hydrogen premiums. Clean transport mandates compress fleet procurement timelines.
- Logistics Companies:Integrated electrolyzer-vehicle contracts bundle 10-year supply agreements with delivered fuel pricing locks. Scattered pilot deployments are consolidating under corridor-scale coverage requirements.
- Automotive Manufacturers:Hyundai Motor Company leverages megawatt-scale electrolyzer partnerships to secure station throughput commitments. R&D allocations follow METI supply chain targets in Japan.
- R&D Institutions:Solid-state storage patents from Japanese automotive labs compress refueling windows toward diesel parity. Metal hydride breakthroughs reshape distribution economics.
Government procurement anchors volume concentration. Logistics companies are gaining share fastest in contract innovation.
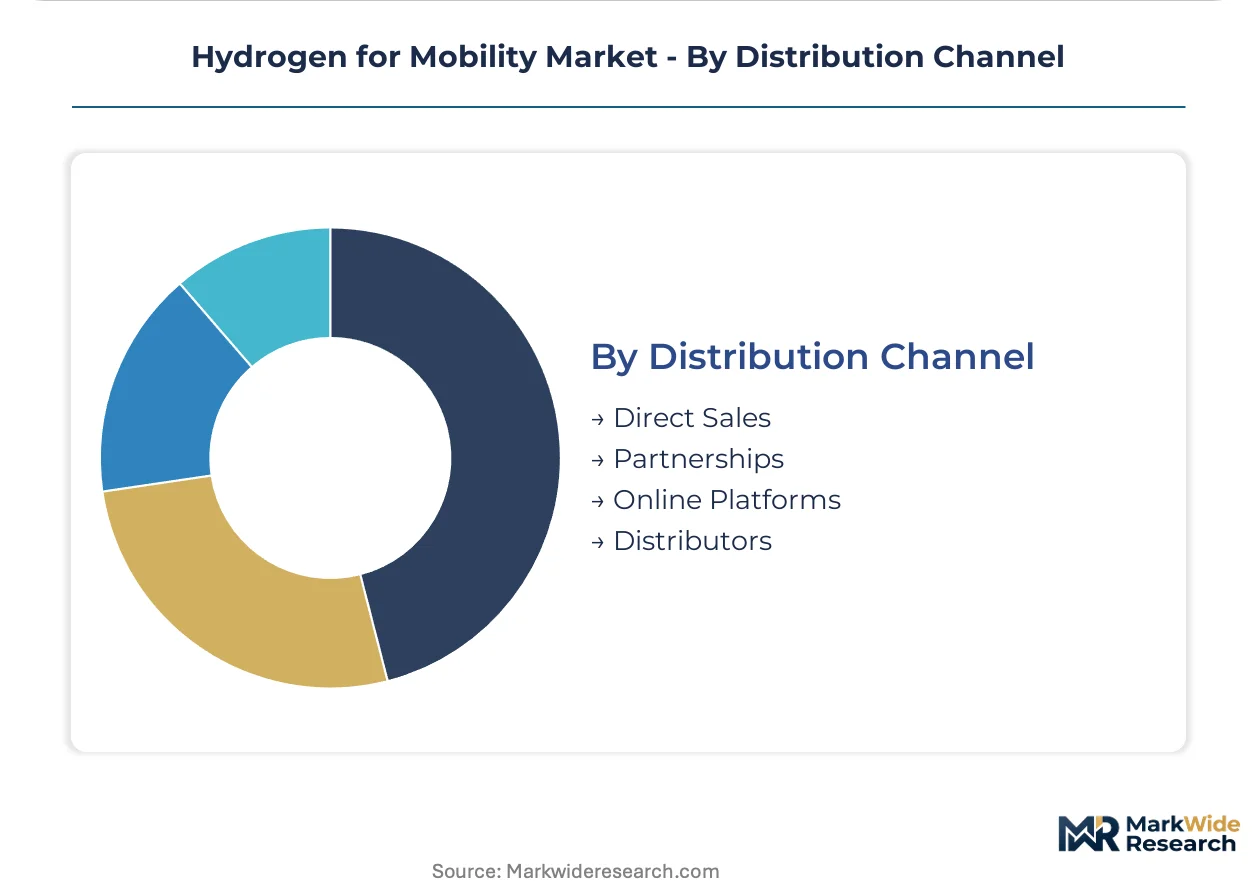
Distribution Channel:
Supply chain control requirements and technical complexity determine channel selection across customer segments.
- Direct Sales:Heavy-duty module architecture from Ballard Power Systems reaches North American bus and truck retrofits without intermediary markup. Technical specification negotiation demands direct manufacturer engagement.
- Partnerships:Electrolyzer-throughput contracts bundle vehicle supply with station hydrogen offtake guarantees. California NEVI program interoperability certification shapes partnership structures.
- Online Platforms:Standardized component procurement for maintenance parts and retrofit kits. High-voltage fuel cell technician shortage limits self-service adoption.
- Distributors:Geographic coverage extension in underpenetrated US freight corridors. Inventory carrying costs for 700-bar compression equipment constrain working capital.
Direct sales dominate heavy-duty deployment. Partnerships are expanding most quickly in integrated supply contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum group metal deposits in South African and Russian mining operations anchor catalyst supply chains for proton-exchange membrane stacks deployed across hydrogen mobility corridors. This feedstock geography shapes manufacturing investment patterns and price volatility exposure for fleet operators worldwide.
United States
California's municipal bus operators deploy on-site electrolyzers under Air Resources Board mandates to circumvent merchant hydrogen premiums. The US Department of Transportation coordinates NEVI program interoperability standards that shape station funding access. The I-10 and I-95 freight corridors between Texas and Florida lack hydrogen station density, creating positioning openings for integrated electrolyzer-station developers.
Germany
Municipal transit authorities compress diesel replacement timelines under binding EU Green Deal zero-emission fleet mandates. The KBA enforces type-approval standards for 700-bar compression equipment that stretches station commissioning cycles. Rhine-Alpine freight corridors anchor logistics operator contracting for 500+ kilometer hydrogen supply to displace diesel haulage.
Japan
METI enforces Green Growth Strategy hydrogen supply chain targets that redirect automotive R&D budgets toward fuel cell stack cost reduction. Solid-state storage patents from domestic automotive labs compress refueling windows toward diesel parity. Government-backed deployment corridors concentrate station infrastructure investment around metropolitan clusters.
South Korea
Megawatt-scale electrolyzer partnerships secure station throughput commitments for heavy-duty fleet procurement. The MFDS coordinates safety standards for high-pressure gas handling that outpace vocational training program output. Depot-based captive production systems expand across municipal bus networks to secure supply certainty.
China
Dual carbon goals under MEE oversight accelerate zero-emission fleet mandates for municipal transit procurement. State-backed deployment corridors concentrate hydrogen infrastructure investment in eastern coastal manufacturing zones. Domestic automotive manufacturers leverage integrated supply chain control to compress fuel cell system production costs.
Hydrogen for Mobility Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electrolyzer-station integration and solid-state storage specialization. The market structures around captive stack production, heavy-duty module architecture, and integrated megawatt-scale partnerships. Three archetypes dominate: automotive manufacturers with captive fuel cell programs, independent power module specialists, and industrial gas suppliers pivoting into mobility infrastructure. Competitive moves concentrate on electrolyzer-throughput contracting and station interoperability certification.
Within the automotive manufacturer tier, Toyota Motor Corporation and Hyundai Motor Company exemplify divergent strategic positioning. Ballard Power Systems occupies a position among independent module specialists serving retrofit-heavy North American corridors. These three entities represent distinct archetypes: captive vertical integration, partnership-based throughput security, and heavy-duty architecture specialization.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Honda Motor Corporation |
| BMW |
| Ballard Power Systems |
| Cummins Inc. |
| Daimler AG |
| SAIC Motor Company |
| Kia Motor Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive electrolyzer production by municipal transit authorities and integrated logistics operators anchors both supply security and pricing power across hydrogen mobility corridors. This backward integration choice compresses delivered fuel costs while insulating fleet operators from merchant hydrogen premiums and spot market volatility.
Pricing Analysis
Warranty bundling separates fuel cell system procurement into comprehensive service contracts versus unbundled hardware transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with EU Green Deal fleet mandates compressing standard-tier pricing through aggregated municipal procurement. Cost compression in economy-tier retrofit systems is intensifying because chassis reinforcement engineering voids original manufacturer warranties. Logistics companies contracting 10-year electrolyzer-throughput agreements show least price sensitivity; small fleet operators dependent on merchant hydrogen delivery exhibit highest sensitivity to per-kilogram fuel fluctuations.
Supply Chain Analysis
Platinum group metal catalyst supply rests on South African and Russian mining operations, tethering proton-exchange membrane stack production to geopolitically exposed feedstock corridors. Electrolyzer manufacturing concentrates in China, Germany, and Japan, while high-pressure compression equipment sources from specialized German and Japanese industrial gas technology suppliers. Single-source vulnerability runs through South African platinum refining capacity concentrated in a handful of processing facilities. Distribution runs through integrated electrolyzer-station developers in California and South Korea, with merchant hydrogen delivery retaining share in German Rhine-Alpine freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen mobility has become a vertical-integration race where control over electrolyzer capacity and station throughput determines competitive survival. Players are pursuing captive production of green hydrogen as the decisive upstream lever to lock in fuel cost positions and secure fleet procurement contracts.
For Market Incumbents: Lock in electrolyzer-throughput contracting relationships with municipal transit authorities in Germany and California before integrated logistics operators consolidate corridor-scale demand. Defend stack production scale through METI-aligned R&D allocations in Japan, while adding captive metal hydride storage capacity to offset fluorinated gas restriction compliance costs threatening legacy liquefaction assets.
For New Entrants and Emerging Players: Capture I-10 and I-95 freight corridor white space between Texas and Florida where hydrogen station density remains insufficient for battery-electric alternatives. Target depot-based captive production systems for municipal bus operators seeking supply certainty outside merchant hydrogen markets. Lead with solid-state storage specialization to compress refueling windows and reduce depot safety zoning capital intensity versus compressed gas competitors.
For Investors and Strategic Acquirers: Exit pathways concentrate in electrolyzer-station integrated developers with demonstrated throughput commitments from logistics operators. Long-term viability hinges on green hydrogen production cost curves achieving parity with gray hydrogen across the analysis window. Acquisition target archetype: mid-cap specialists with metal hydride patents and California Air Resources Board certification progress. Watch station commissioning timeline acceleration as the critical inflection signal for network expansion feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Station Integration | NEVI program interoperability certification in California mandates bundled infrastructure-vehicle procurement structures. |
| Solid-State Storage Patent Development | Japanese automotive laboratory breakthroughs compress refueling windows toward diesel parity for freight adoption. |
| Captive Hydrogen Production Deployment | South Korean municipal bus operators circumvent merchant premiums through on-site electrolyzer installation. |
| Fuel Cell Stack Cost Reduction Program | METI supply chain targets redirect automotive R&D budgets toward proton-exchange membrane efficiency gains. |
| Long-Haul Corridor Supply Contracting | Rhine-Alpine logistics operators displace diesel through 500+ kilometer hydrogen supply agreements. |
Research Methodology
Trade databases, regulatory filings, and patent registries formed the secondary backbone for hydrogen mobility market sizing. Primary interviews with fleet procurement directors at municipal transit authorities, electrolyzer project developers, fuel cell stack engineering leads, and station infrastructure permitting officers combined with secondary validation from California Air Resources Board certification records, EU Green Deal implementation reports, and METI hydrogen supply chain disclosures. Bottom-up unit deployment tracking across Germany, California, Japan, and South Korea triangulated against top-down electrolyzer capacity buildout projections.
Bottom-up modeling segmented deployments by technology platform, application duty cycle, and end-user procurement scale across the projection horizon. Fuel cell system efficiency thresholds, hydrogen storage pressure specifications, and compression technology compliance requirements shaped segment-level growth trajectories. CAGRs were derived from electrolyzer capacity expansion schedules correlated with station network density milestones and fleet operator vehicle commitment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum group metal price volatility and fluorinated gas regulation phase-down timelines. Forecasts reflect documented assumptions around station commissioning acceleration and vocational training program output scaling. Electrolyzer input cost shocks, geopolitical supply disruptions, and permitting timeline extensions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Alkaline Water Electrolysis Market