
 GCC Natural Gas Market | 2026-2036
GCC Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Natural Gas Market Analysis
Downstream monetization revenue is tilting from simple pipeline sales toward integrated LNG and petrochemical value chains. QatarEnergy leverages its North Field expansion to sustain export dominance across Asian offtake markets. ADNOC Gas anchors the UAE's position through Ruwais industrial complex supply and expanding LNG liquefaction trains. Saudi Aramco competes by extending its Master Gas System into new manufacturing zones and blue hydrogen pilot projects.
Natural gas consists primarily of methane, typically containing 70-90% CH4 by volume alongside ethane, propane, butane, and non-combustible constituents such as nitrogen and carbon dioxide, extracted through conventional drilling, hydraulic fracturing, or associated recovery from oil reservoirs and processed through amine treating and cryogenic separation for pipeline or liquefied distribution to industrial and power generation consumers. Pipeline infrastructure carries the largest volume share across GCC states, though LNG technology commands premium margins for export-oriented producers serving distant markets. Power generation applications absorb the dominant domestic share, while manufacturing sector end users in petrochemicals and fertilizers represent the fastest-growing demand pool as governments diversify from crude dependency.
The UAE's Ministry of Energy and Infrastructure, Saudi Arabia's Ministry of Energy, and Qatar's Ministry of Environment and Climate Change enforce methane intensity standards and flaring reduction mandates that reshape field development economics and facility upgrade timelines. Saudi Vision 2030 and UAE Net Zero by 2050 commitments are embedding carbon capture requirements into new gas project approvals, altering contractor selection criteria and capital allocation priorities. Stakeholders must track how national hydrogen strategies redirect gas feedstock commitments between power, export, and emerging synthetic fuel pathways.
Market Dynamics
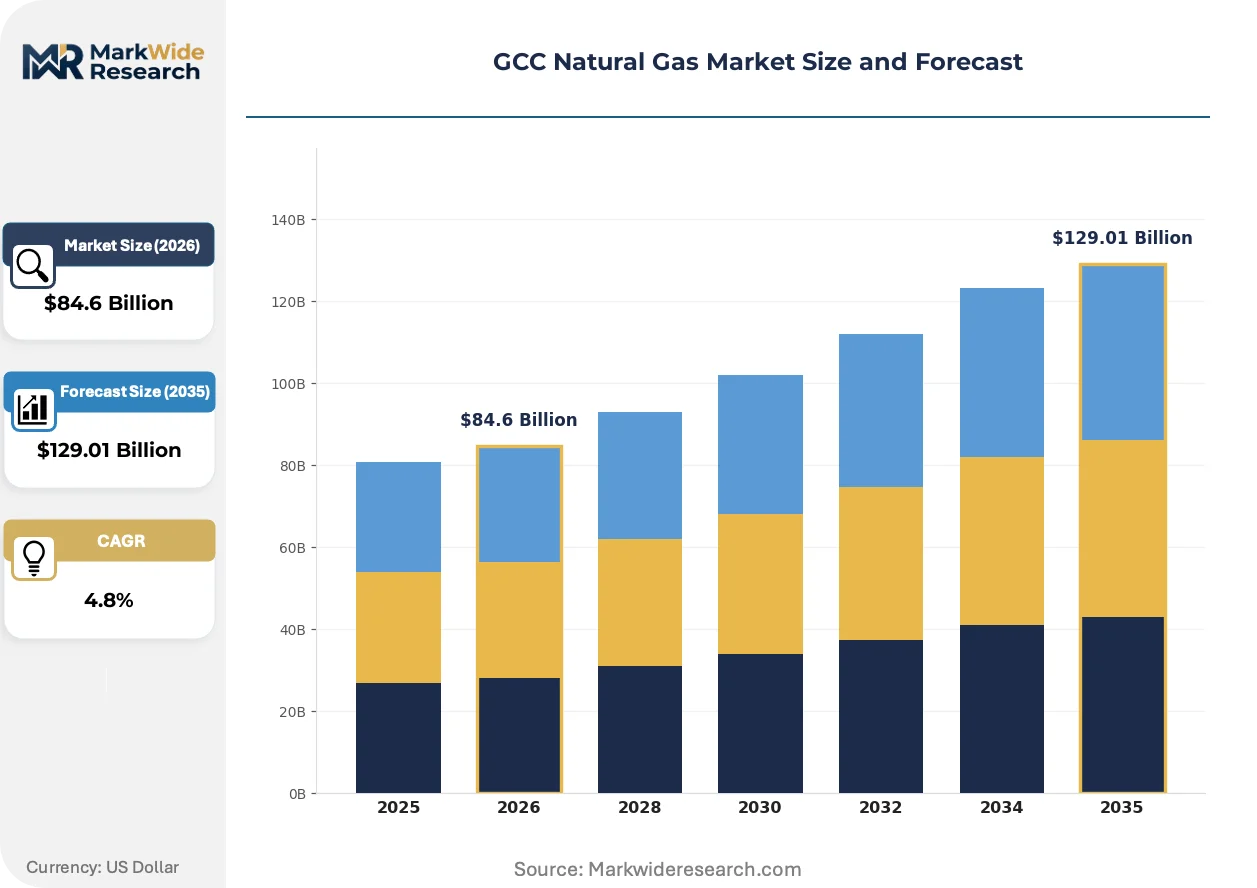
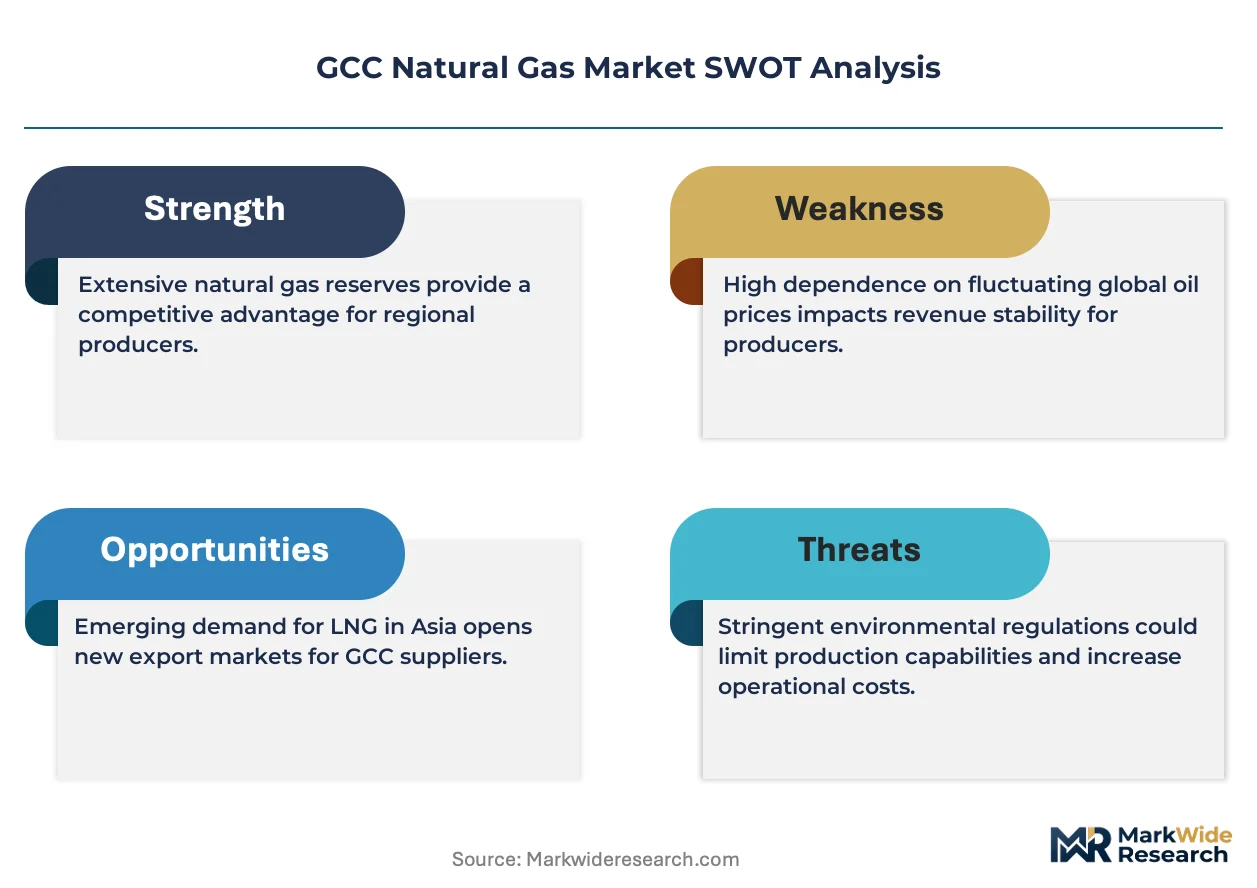
Qatar's North Field expansion and Saudi Arabia's Master Gas System extension are concentrating capital flows toward integrated LNG and blue hydrogen infrastructure, altering how GCC states monetize gas reserves.
Growth Catalysts
- Power sector load growth:Saudi Electricity Company and Qatar General Electricity and Water Corporation are adding combined-cycle capacity to serve summer peak demand and desalination loads.
- SFDA methane intensity standards:Saudi Arabia's flaring reduction mandates are forcing field operators to deploy vapor recovery units and closed-flare systems, upgrading facility economics.
- Petrochemical feedstock demand:Ruwais and Jubail industrial cities are expanding ethane cracker capacity, pulling additional gas volumes into domestic manufacturing chains.
Market Restraints
- Upstream capital intensity:Offshore sour gas development in the UAE's Hail and Ghasha fields requires multi-billion dollar processing trains before commercial flow.
- Single-source liquefaction dependence:Qatar dominates regional LNG export capacity, creating offtake concentration risk for Asian buyers during supply disruptions.
- Renewable substitution pressure:Saudi Vision 2030 solar and wind targets are compressing gas-fired power dispatch hours in coastal load centers.
Strategic Opportunities
- Kuwait underinvestment gap:The country's stalled Jurassic gas development creates entry points for technical service contractors with sour gas expertise.
- UAE Net Zero by 2050 carbon capture mandates:New project approvals now require integrated CCUS, favoring engineering firms with amine-capture and sequestration capabilities.
- Hydrogen export corridor emergence:Blue ammonia synthesis at Ras Laffan and Jubail is opening alternative monetization routes for stranded gas reserves.
Industry Challenges
- Specialized welding and metallurgy shortages:Sour service pipeline construction requires certified crews that remain scarce across the Arabian Peninsula.
- Legacy SCADA integration:New digital field architectures must interface with decades-old distributed control systems at Saudi Aramco and ADNOC facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Natural Gas Market |
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $129.01 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Power Generation, Industrial Heating, Residential Heating, Transportation Technology: CNG, LNG, Pipeline, Biogas End User: Utilities, Manufacturing Sector, Commercial Sector, Agriculture Distribution Channel: Direct Sales, Wholesalers, Online Platforms, Brokers |
| Companies Covered | Kuwait Petroleum Corporation (KPC), Bahrain Petroleum Company, Saudi Aramco, Oman LNG, Dolphin Energy, QatarEnergy, Petroleum Development Oman, ADNOC Gas, Abu Dhabi National Oil Company (ADNOC), Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Natural Gas Market Emerging Trajectories
Digital twin deployment and modular liquefaction units are compressing project development timelines while methane monitoring satellites are exposing operational gaps previously hidden from regulators.
Digital twin platforms are virtualizing offshore platform operations across Qatar's North Field East expansion. QatarEnergy's engineering teams are running real-time reservoir simulations that compress well placement optimization cycles from months to weeks. This virtualization is reducing dry-hole risk and accelerating plateau production targets without additional physical survey campaigns.
UAE Net Zero by 2050 commitments are embedding carbon capture requirements into new gas project approvals issued by the Ministry of Energy and Infrastructure. Contractors must now front-load amine treating and sequestration engineering into front-end design packages, altering bid evaluation criteria and vendor selection timelines. Greenfield developments in Abu Dhabi's offshore blocks are most affected, with feasibility studies now requiring integrated CCUS cost curves.
Long-term offtake contracting is fragmenting as Asian utilities diversify supply sources beyond traditional Qatar-Saudi-Kuwait corridors. Japanese and South Korean buyers are shortening contract tenors and introducing destination flexibility clauses, displacing the twenty-year fixed-destination framework that dominated regional LNG trade. This pattern is most visible in spot market participation from Tokyo Gas and KOGAS, which now blend short-term purchases with residual base load commitments.
GCC Natural Gas Market Segmentation
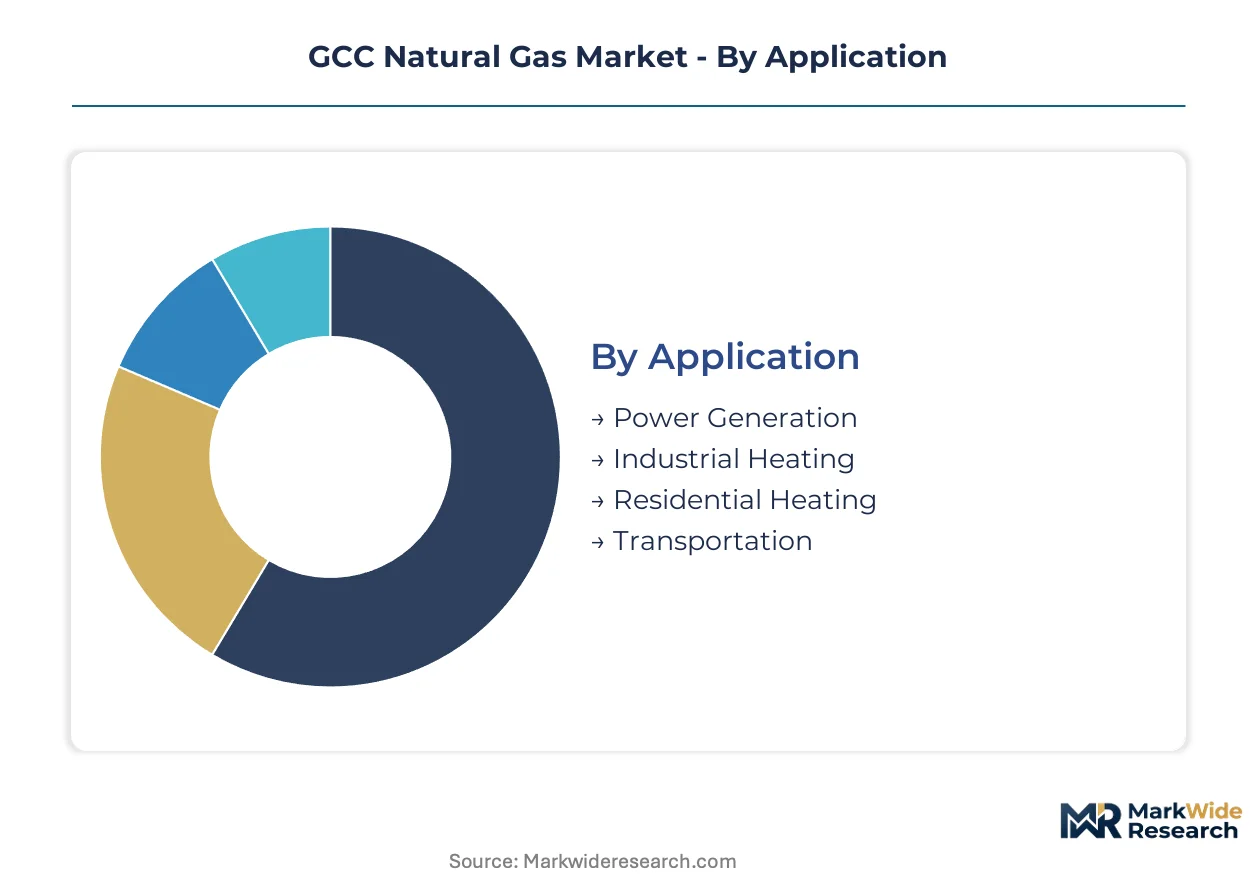
Segmentation reveals how GCC gas flows diverge between mature bulk infrastructure and emerging specialized channels. Understanding these splits exposes where capital efficiency concentrates and where new monetization models are forming.
Application:
Mature baseload applications anchor throughput while emerging use cases reshape demand curves.
- Power Generation:Combined-cycle turbines at Saudi Electricity Company and Qatar General Electricity and Water Corporation absorb the dominant share of regional gas offtake. This segment handles the majority of throughput; Industrial Heating is the fastest mover on share.
- Industrial Heating:Ethane crackers at Ruwais and Jubail industrial complexes pull increasing volumes for petrochemical feedstock. Desalination co-generation plants in the UAE and Kuwait add steady thermal demand.
- Residential Heating:Limited penetration outside northern Saudi Arabia and highland UAE due to climate. Distribution networks at Saudi Aramco's Master Gas System serve concentrated urban corridors.
- Transportation:CNG bus fleets at Emirates Transport and Saudi Public Transport Company pilot commercial adoption. LNG trucking corridors between Qatar and UAE industrial zones test long-haul viability.
Technology:
Cost tiers separate established pipeline networks from premium liquefaction and nascent biogas alternatives.
- Pipeline:The Master Gas System and Qatar's North Field gathering networks carry the largest volume share across GCC states. SFDA methane intensity standards are forcing vapor recovery upgrades on legacy trunk lines.
- LNG:QatarEnergy's Ras Laffan trains command premium margins for Asian offtake markets. ADNOC Gas is expanding liquefaction capacity at Das Island to capture spot market premiums.
- CNG:Vehicle fueling infrastructure concentrates in Dubai and Riyadh metropolitan zones. ADNOC Distribution and Saudi Aramco retail networks anchor station deployment.
- Biogas:Waste-to-energy pilots at Dubai's Warsan and Saudi landfill sites remain experimental. Scaling depends on organic waste stream aggregation economics.
End User:
Customer type determines contract structure, with utilities locking in long-term supply and manufacturing seeking flexible term arrangements.
- Utilities:Saudi Electricity Company and Qatar General Electricity and Water Corporation dominate procurement through government-negotiated supply agreements. This segment handles the majority of throughput; Manufacturing Sector is gaining share fastest.
- Manufacturing Sector:SABIC and Borouge petrochemical complexes drive the steepest demand expansion trajectory. Fertilizer producers at Ma'aden and QAFCO add seasonal offtake volatility.
- Commercial Sector:Hotels, hospitals, and district cooling operators in Dubai and Doha purchase through bundled energy service contracts. Smaller volume per account limits direct pipeline access.
- Agriculture:Greenhouse heating and irrigation pumping in Saudi Arabia's Tabuk and Al-Jouf regions represent niche demand. Desalination-powered hydroponics reduces direct gas dependence.
Distribution Channel:
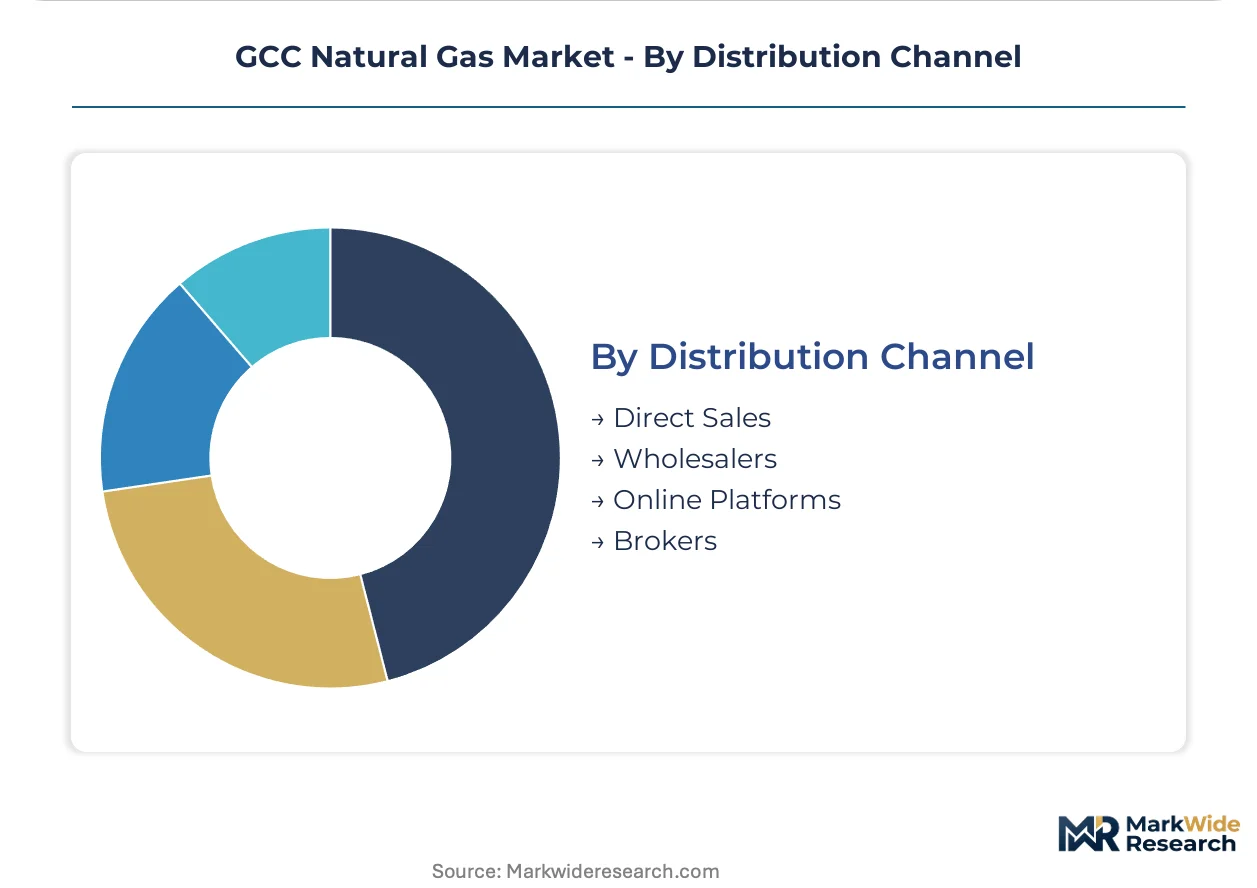
Supply concentration favors direct producer-to-consumer relationships, with intermediaries filling geographic and credit gaps.
- Direct Sales:QatarEnergy and Saudi Aramco negotiate long-term offtake with integrated utilities and industrial complexes. This channel handles the majority of throughput; Online Platforms are expanding most quickly.
- Wholesalers:Regional traders aggregate volumes for smaller industrial consumers in Bahrain and Oman. Credit intermediation and logistics bundling justify margin capture.
- Online Platforms:ADNOC's B2B portal and emerging spot market digitization enable real-time price discovery. Liquidity remains thin outside Qatar and UAE hubs.
- Brokers:Intermediaries match stranded production with opportunistic buyers during maintenance windows. Regulatory transparency gaps limit formal market development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qatar and Saudi Arabia consume natural gas through diverging pathways. Qatar channels volumes toward LNG export liquefaction and petrochemical feedstock. Saudi Arabia prioritizes domestic power generation and industrial manufacturing clusters.
Qatar
QatarEnergy's North Field expansion absorbs the majority of incremental gas production capacity. The Ministry of Environment and Climate Change enforces methane intensity caps on offshore platform operations. Ras Laffan industrial city concentrates LNG train construction and blue ammonia pilot facilities.
Saudi Arabia
Saudi Electricity Company and SABIC compete for Master Gas System allocations during summer peak periods. SFDA flaring reduction mandates accelerate vapor recovery unit deployment at Ghawar and Safaniya fields. Jubail industrial complex expands ethane cracker capacity to capture downstream margin.
United Arab Emirates
ADNOC Gas balances Ruwais petrochemical supply obligations against expanding Das Island LNG export commitments. The Ministry of Energy and Infrastructure embeds carbon capture requirements into offshore block approvals. Abu Dhabi onshore fields feed the Taweelah power and desalination complex.
Oman
Petroleum Development Oman redirects associated gas from mature oil fields toward domestic industrialization. Sultanate environmental regulations tighten venting standards at remote wellhead locations. Sohar industrial port hosts fertilizer and methanol plants drawing pipeline-delivered feedstock.
Kuwait
Kuwait Petroleum Corporation struggles to commercialize Jurassic sour gas reserves amid technical complexity. The national oil company defers field development timelines pending contractor qualification for high-H2S processing. Al-Zour refinery integration plans remain contingent on upstream supply certainty.
GCC Natural Gas Market Vendor Landscape
Capability concentration sits with integrated national oil companies holding reserve access; scale advantage sits with specialized gas processors and LNG operators serving export markets. The competitive structure divides between upstream resource holders, midstream infrastructure operators, and downstream monetization specialists. Three archetypes dominate: vertically integrated NOCs controlling full value chains, joint-venture LNG exporters pooling technical expertise, and industrial gas suppliers serving captive manufacturing demand. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Within the integrated NOC tier, QatarEnergy and Saudi Aramco exemplify reserve-to-market control. ADNOC Gas occupies a position bridging upstream Abu Dhabi National Oil Company assets with downstream Ruwais industrial supply. Oman LNG represents the joint-venture export model, pooling state equity with international technical participation.
| Leading Market Players |
|---|
| Kuwait Petroleum Corporation (KPC) |
| Bahrain Petroleum Company |
| Saudi Aramco |
| Oman LNG |
| Dolphin Energy |
| QatarEnergy |
| Petroleum Development Oman |
| ADNOC Gas |
| Abu Dhabi National Oil Company (ADNOC) |
| Others |
Supply Flow & Price Mechanics
Ras Laffan's liquefaction capacity concentration grants QatarEnergy substantial leverage over Asian contract negotiations, compressing margin flexibility for buyers seeking alternative supply. This geographic supply dominance translates into pricing power that ripples through downstream petrochemical and power generation procurement across the Gulf states.
Pricing Analysis
Long-term offtake contracts with destination clauses still dominate QatarEnergy's Asian portfolio, though spot market participation from Tokyo Gas and KOGAS introduces price discovery volatility. Price differentiation hinges on volume scale and methane intensity certification tier, with SFDA-compliant volumes commanding premiums from sustainability-focused buyers. Cost compression in pipeline-delivered domestic supply is intensifying because Saudi Aramco's Master Gas System expansion adds marginal volume. Industrial utilities prove most price-sensitive due to seasonal demand swings, while LNG exporters show least sensitivity given captive offtake relationships.
Supply Chain Analysis
Single-source liquefaction dependence on Qatar dominates regional supply chain risk, with limited redundancy for Asian buyers during unplanned outages. Geographic supply concentration centers on Qatar, Saudi Arabia, and the UAE for upstream reserves, with Oman and Kuwait as secondary contributors. Raw material dependencies include specialized sour service steel alloys, cryogenic heat exchanger components, and amine treating chemicals. Distribution runs through integrated NOC-controlled pipelines and LNG shipping corridors rather than third-party intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC natural gas market is emerging from a capital-intensive expansion cycle, with project commissioning timelines and methane regulatory tightening serving as the primary cyclical recovery drivers.
For Market Incumbents: Pre-empt margin erosion from modular liquefaction disruptors by accelerating carbon capture integration into existing train retrofits. Secure captive ethane supply through backward integration into Saudi Aramco's Master Gas System extensions before SABIC and Borouge expand cracker capacity. Lock in 15-year offtake visibility with Japanese utilities before contract tenors fragment further. For New Entrants and Emerging Players: Kuwait's stalled Jurassic sour gas development offers the most penetrable white space for technical service contractors with high-H2S processing expertise. Target carbon capture engineering for ADNOC's offshore block approvals, where CCUS mandates create first-mover advantage for amine-capture specialists. Lead with integrated feasibility studies that bundle reservoir characterization, processing design, and sequestration planning. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure yield play because contracted cash flows from LNG trains and pipeline networks generate stable returns through commodity cycles. Target midstream gas processors with established relationships to QatarEnergy or ADNOC Gas. Monitor Japanese buyer contract tenor preferences as the inflection signal for pricing power shifts between producers and consumers.| Strategic Initiative | Industry Significance |
|---|---|
| North Field Expansion Capacity Buildout | QatarEnergy's Ras Laffan trains cement export dominance across Asian offtake markets. |
| Carbon Capture Integration Mandate | UAE Ministry of Energy requirements reshape contractor selection for offshore developments. |
| Master Gas System Extension | Saudi Aramco's pipeline expansion feeds Jubail petrochemical complex growth and blue hydrogen pilots. |
| Blue Ammonia Export Corridor | Ras Laffan and Jubail facilities open alternative monetization for stranded gas reserves. |
| Digital Twin Deployment | QatarEnergy's virtualization compresses well placement cycles from months to weeks. |
Methodological Framework
Operator-level perspectives from reservoir engineers, LNG commercial officers, EPC contractors, and utility procurement managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation across SEC filings from integrated NOCs, IEA natural gas market reports, SFDA methane intensity disclosures, and project development databases. Bottom-up field-by-field production estimates and top-down regional demand projections were triangulated to constrain forecast variance.
Scenario bracketing around Qatar's North Field East plateau timing and Saudi renewable substitution rates bounded the projection horizon. Segmentation modeling spanned application type, technology tier, end-user contract structure, and distribution channel concentration. CAGRs were derived from least-squares fitting of annual volume trajectories, with sensitivity testing against SFDA regulatory stringency and Asian buyer diversification patterns.
Practitioners should monitor methane satellite detection coverage expansion and Japanese utility contract tenor preferences for early signals of operational standard shifts. Forecasts reflect assumptions about QatarEnergy's expansion schedule and ADNOC's carbon capture deployment pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Asia-Pacific Oil and Gas Storage Tank Market
Oil & Gas
GCC Oil and Gas Separation Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Southeast Asia Oil and Gas Midstream Market
Oil & Gas
Europe Oilfield Services Market