
 Hydrogen Energy Storage Market | 2026-2036
Hydrogen Energy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Energy Storage Market Analysis
A capital-intensity divergence between electrolyzer manufacturers and tank system providers is bifurcating competitive returns in hydrogen storage. Air Liquide leverages integrated liquid hydrogen production and distribution to sustain margin capture across the value chain. Nel ASA anchors its position through alkaline and PEM electrolyzer specialization, while Linde plc competes through large-scale cryogenic storage infrastructure deployed near industrial offtake.
Hydrogen energy storage encompasses technologies that retain hydrogen in compressed gas, liquid, cryogenic, or solid-state metal hydride forms for subsequent energy conversion through fuel cells or combustion, typically operating at pressures from 350 to 700 bar for compressed systems or temperatures below minus 253 degrees Celsius for liquid storage. Compressed hydrogen dominates utility-scale installations due to lower infrastructure barriers, while metal hydrides command premium segments requiring compact, stationary density. Power grids represent the fastest-growing application as renewable curtailment drives investment in long-duration seasonal storage.
The EU Green Deal and F-Gas Regulation shape equipment standards and carbon intensity thresholds for imported hydrogen, while Japan's METI enforces JIS certification for storage vessel safety. The US EPA and Department of Energy coordinate on hydrogen hub funding criteria that privilege projects with verified lifecycle emissions. Stakeholders must track evolving certification schemes for green hydrogen origin to secure offtake contracts and avoid stranded asset risk.
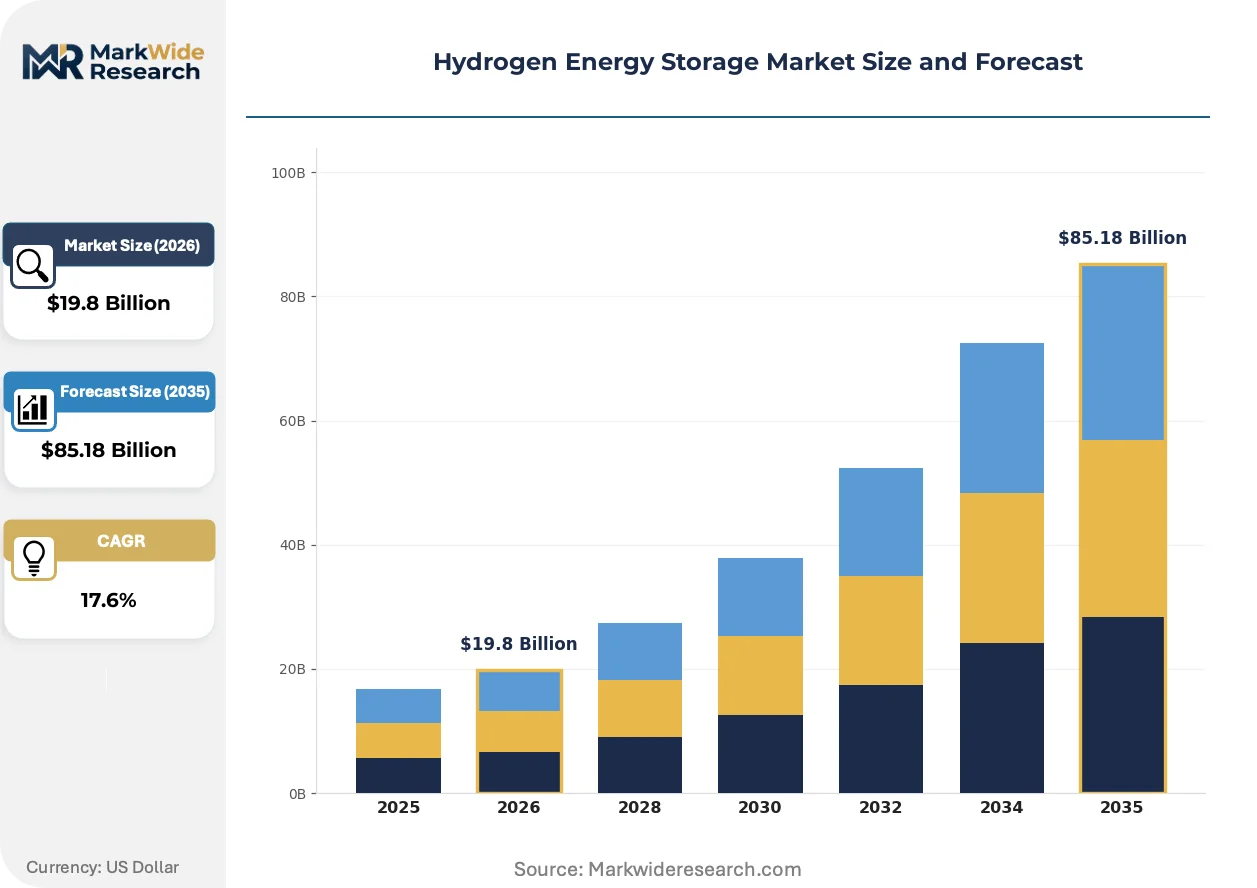
Market Dynamics
The hydrogen energy storage market is bifurcating around electrolyzer scale and storage form factor, as utility-scale renewable curtailment creates divergent investment paths between compressed gas infrastructure and liquid hydrogen terminals.
Growth Catalysts
- EU Green Deal carbon intensity thresholds:The framework mandates lifecycle emissions verification for imported hydrogen, forcing storage operators to deploy electrolyzer-integrated systems that can certify origin. Industrial offtake in Germany's Ruhr corridor is accelerating as a result.
- Japan's METI hydrogen roadmap:Port clusters in Yokohama and Kobe are receiving dedicated funding for liquid hydrogen import terminals. JIS certification requirements for vessel safety are standardizing equipment procurement across utilities.
- Power grid balancing applications:Renewable curtailment in California and Texas is driving seasonal storage investments. Long-duration discharge capabilities position hydrogen against lithium-ion for multi-day grid services.
Market Restraints
- Platinum and iridium input cost volatility:PEM electrolyzer membrane catalysts depend on concentrated South African and Russian supply. Price swings compress manufacturer margins and delay project financing.
- Liquid hydrogen boil-off losses:Cryogenic storage systems lose up to one percent daily to evaporation. This technical limitation restricts deployment to high-throughput industrial terminals with continuous offtake.
- F-Gas Regulation equipment standards:The EU framework imposes strict containment requirements on refrigeration systems used in liquefaction plants. Compliance adds capital cost and extends commissioning timelines.
Strategic Opportunities
- Solid-state metal hydride convergence:The technology combines compact stationary density with ambient temperature operation. Forklift fleets and backup power installations in Japan are piloting systems that eliminate compression infrastructure.
- US hydrogen hub funding criteria:The Department of Energy prioritizes projects with verified lifecycle emissions and regional supply networks. Developers securing certification early capture offtake preference from hard-to-abate industrial buyers.
- Ammonia as hydrogen carrier:Maritime shipping routes from the Middle East to Rotterdam and Singapore are adapting tankage for ammonia cracking. This distribution innovation unlocks intercontinental trade without cryogenic logistics.
Industry Challenges
- Electrolyzer technician skill gaps:Alkaline and PEM system maintenance requires specialized training in membrane handling and stack assembly. Germany's industrial corridor faces recruitment competition from battery manufacturing.
- Green hydrogen certification timeline complexity:Multiple overlapping schemes including CertifHy, TUV SUD, and proposed ISO 19870 create compliance fragmentation. Developers risk stranded certification investment if dominant standards consolidate differently.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Energy Storage Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $85.18 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Compressed Hydrogen, Liquid Hydrogen, Metal Hydrides, Chemical Hydrogen Storage Application: Energy Storage Systems, Transportation, Industrial Applications, Power Grids End User: Utilities, Manufacturing, Automotive, Aerospace Solution: Standalone Systems, Integrated Solutions, Retrofitting Services, Consulting Services |
| Companies Covered | Air Liquide, Linde plc, Air Products, ITM Power, Nel ASA, Cummins, Plug Power, Engie, Chart Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Energy Storage Market Emerging Trajectories
Electrolyzer efficiency gains and storage form factor innovations are compressing the cost gap between hydrogen and conventional long-duration alternatives, while regulatory pressure on carbon accounting reshapes procurement criteria.
Alkaline electrolyzer technology with improved membrane architecture is supplanting early-generation PEM systems in utility-scale installations. German utilities deploying 100MW+ arrays favor the lower catalyst load and extended operational lifespan. The shift is compressing PEM manufacturer margins and forcing specialization into dynamic response applications.
Japan's METI has tightened JIS certification protocols for high-pressure composite storage vessels, mandating burst testing protocols that exceed prior international norms. Domestic manufacturers are absorbing retooling costs while foreign suppliers face extended approval timelines. The regulation most affects Korean and Chinese tank exporters seeking utility contracts.
Industrial buyers are consolidating procurement around integrated electrolyzer-storage-fuel cell packages rather than component sourcing. German chemical operators and Japanese steel producers now specify single-vendor responsibility for round-trip efficiency guarantees. This bundling trend is most visible in Rotterdam and Hamburg port industrial zones where offtake scale justifies vertical contracting.
Hydrogen Energy Storage Market Segmentation
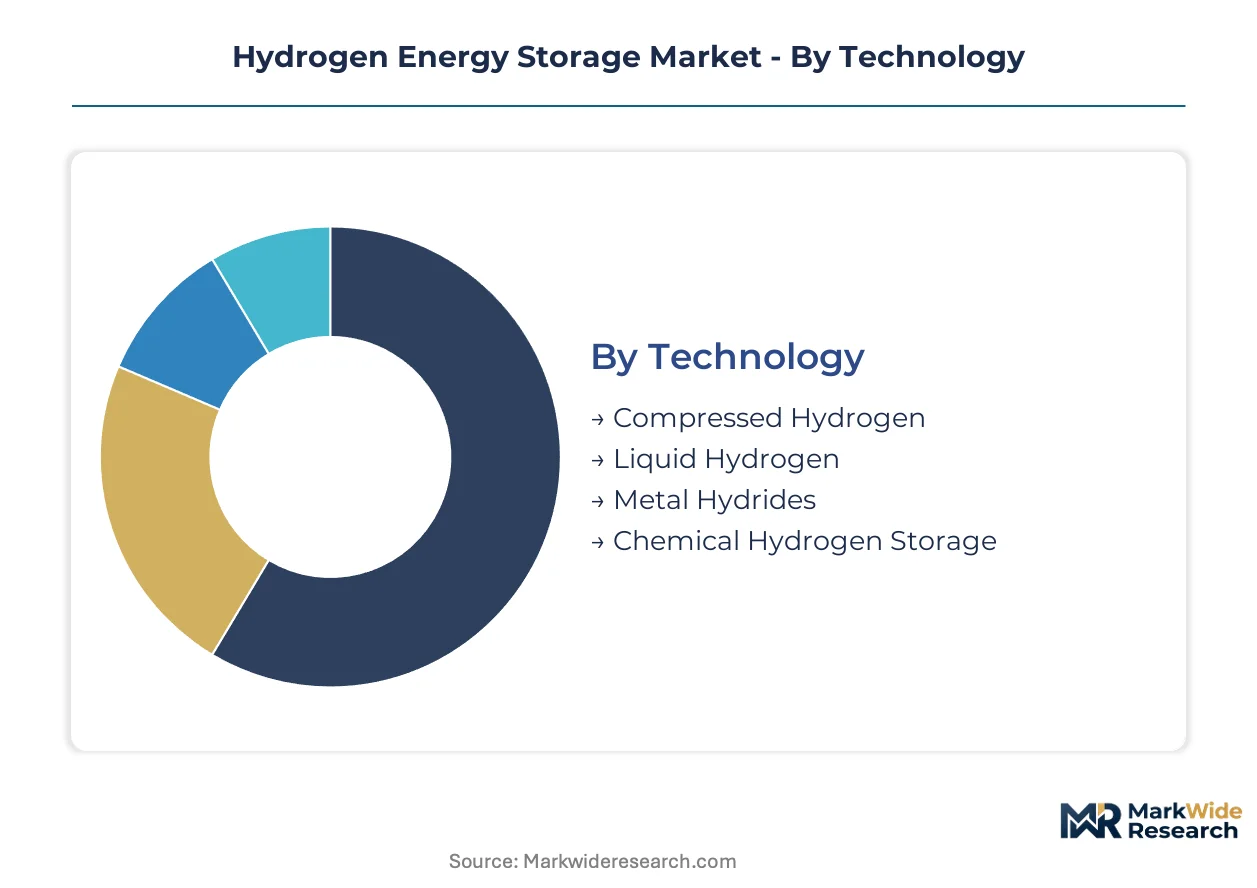
Technology choices in hydrogen storage determine capital deployment patterns and operational economics across the value chain. Form factor selection directly constrains which end-use applications become economically viable and which customer segments can be served profitably.
Technology:
Compressed hydrogen faces substitution pressure from metal hydrides in stationary applications requiring compact footprint, while liquid hydrogen competes with ammonia carriers for long-distance maritime distribution.
- Compressed Hydrogen:Gaseous storage at 350-700 bar pressure dominates utility-scale installations due to lower infrastructure barriers and established compressor supply chains. German utilities in the Ruhr corridor favor this technology for grid balancing services where space constraints are minimal.
- Liquid Hydrogen:Cryogenic storage below minus 253 degrees Celsius enables high-density energy transport but suffers from daily boil-off losses of approximately one percent. Japan's METI-funded port clusters in Yokohama and Kobe deploy liquid terminals to receive intercontinental hydrogen shipments from Middle Eastern producers.
- Metal Hydrides:Solid-state storage at ambient temperature eliminates compression infrastructure and offers compact stationary density. Forklift fleets in Japan and backup power installations are piloting systems where space premiums justify higher capital cost.
- Chemical Hydrogen Storage:Liquid organic hydrogen carriers and ammonia cracking enable maritime distribution without cryogenic logistics. Rotterdam and Singapore port authorities are adapting tankage infrastructure for ammonia-to-hydrogen conversion.
Compressed hydrogen anchors the volume base while metal hydrides gain share at the steepest rate in premium stationary applications.
Application:
Cost tier differentiation separates high-frequency grid services from seasonal storage investments, with transportation applications commanding premium pricing for rapid refueling capability.
- Energy Storage Systems:Diurnal and seasonal storage installations buffer renewable curtailment in California and Texas. Long-duration discharge capabilities position hydrogen against lithium-ion for multi-day grid services where battery degradation costs accumulate.
- Power Grids:Utility-scale balancing services require rapid response electrolyzer stacks and high-pressure buffer storage. German transmission operators deploy 100MW+ alkaline arrays to manage wind generation variability across the North Sea corridor.
- Transportation:Heavy-duty trucking and maritime shipping demand high-throughput refueling infrastructure. Port clusters in Hamburg and Rotterdam integrate hydrogen bunkering with existing fuel terminal operations.
- Industrial Applications:Steel production and chemical feedstock substitution drive demand for verified green hydrogen origin. German chemical operators in Ludwigshafen specify single-vendor responsibility for round-trip efficiency guarantees.
Power grids absorb the largest capital allocation while transportation applications expand most quickly as fuel cell costs decline.
End User:
Customer type determines procurement complexity, with utilities favoring integrated packages and automotive buyers demanding modular scaling for fleet deployment.
- Utilities:Grid operators procure electrolyzer-storage-fuel cell packages with performance guarantees spanning twenty-year asset lifecycles. German municipal utilities dominate procurement volumes for seasonal storage pilot projects.
- Manufacturing:Chemical and steel producers require certified green hydrogen to meet EU Green Deal carbon intensity thresholds. Industrial offtake in Germany's industrial corridor accelerates as lifecycle verification systems mature.
- Automotive:Heavy-duty truck manufacturers and fleet operators prioritize rapid refueling infrastructure over energy density optimization. California's hydrogen highway program channels public funding toward corridor development.
- Aerospace:Aviation fuel substitution trials focus on liquid hydrogen for long-haul routes where battery weight penalties are prohibitive. Airport authorities in Frankfurt and Tokyo are assessing cryogenic fueling infrastructure requirements.
Utilities command the dominant procurement volume while manufacturing end users show the steepest demand acceleration as carbon accounting tightens.
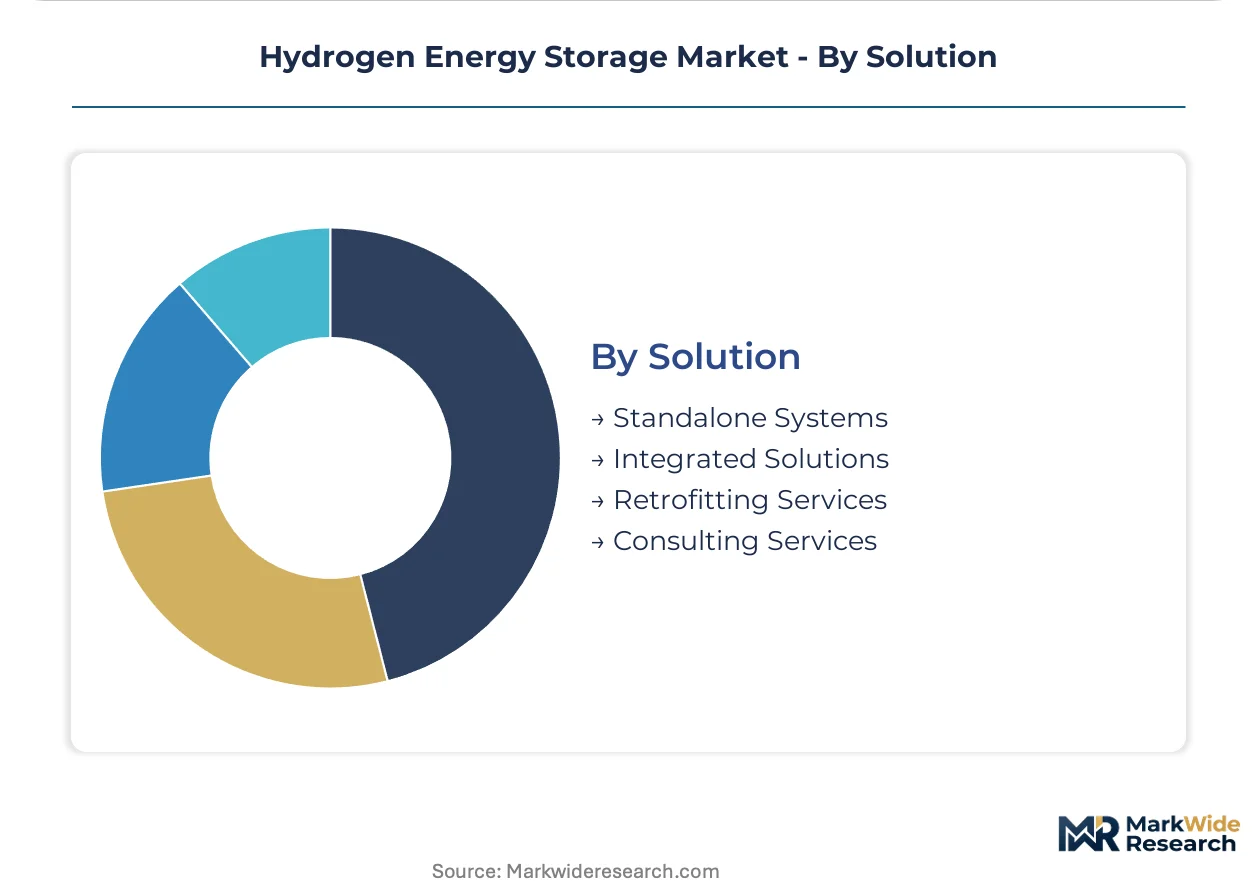
Solution:
Maturity gradients separate established equipment supply from emerging service categories, with retrofitting gaining traction as existing industrial assets face decarbonization deadlines.
- Standalone Systems:Discrete storage tanks and compression skids serve pilot projects and small-scale industrial offtake. German engineering procurement favors modular designs enabling future capacity expansion.
- Integrated Solutions:Combined electrolyzer-storage-fuel cell packages with single-vendor performance guarantees dominate utility-scale procurement. Japanese steel producers and German chemical operators now specify vertical contracting for round-trip efficiency accountability.
- Retrofitting Services:Conversion of existing natural gas infrastructure for hydrogen blending or pure hydrogen service extends asset lifecycles. Netherlands pipeline operators lead deployment of hydrogen-ready steel in transmission networks.
- Consulting Services:Certification navigation and lifecycle emissions verification support project financing. Developers engaging CertifHy and TUV SUD schemes early secure offtake preference from hard-to-abate industrial buyers.
Integrated solutions capture the majority of new capital deployment while consulting services climb the fastest as certification complexity fragments compliance pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in hydrogen energy storage concentrates with German electrolyzer-integrated developers while Japanese port infrastructure commands premium logistics margins. The EU Green Deal's carbon intensity thresholds create regulatory arbitrage favoring domestic European producers over import-dependent Asian markets. This geographic asymmetry shapes capital deployment patterns across four dominant national markets.
Germany
Ruhr corridor industrial demand and North Sea wind curtailment drive electrolyzer deployment at utility scale. The EU Green Deal mandates lifecycle emissions verification for imported hydrogen, forcing storage operators toward integrated electrolyzer systems. Municipal utilities in North Rhine-Westphalia dominate procurement volumes for seasonal storage pilot projects.
Japan
Port cluster import terminal development and steel industry feedstock substitution anchor demand growth. METI enforces JIS certification for high-pressure composite vessel safety, standardizing equipment procurement across utilities. Yokohama and Kobe liquid hydrogen terminals receive dedicated funding for Middle Eastern supply receipt.
United States
California and Texas renewable curtailment patterns create divergent investment paths for seasonal versus diurnal storage applications. The Department of Energy coordinates with EPA on hydrogen hub funding criteria privileging verified lifecycle emissions. Industrial buyers in the Gulf Coast petrochemical corridor specify single-vendor responsibility for round-trip efficiency guarantees.
China
Dual carbon goals and industrial decarbonization targets accelerate electrolyzer manufacturing scale-up. The Ministry of Ecology and Environment enforces carbon intensity benchmarks for hydrogen production certification. Yangtze River Delta chemical operators pilot integrated electrolyzer-storage packages for ammonia feedstock substitution.
Netherlands
Rotterdam port hydrogen bunkering infrastructure and pipeline retrofit programs extend natural gas asset lifecycles. EU F-Gas Regulation imposes strict containment requirements on liquefaction plant refrigeration systems. Pipeline operators lead deployment of hydrogen-ready steel in transmission networks serving German industrial offtake.
Hydrogen Energy Storage Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Industrial gas majors leverage integrated liquid hydrogen production and distribution networks to sustain margin capture across the value chain. Electrolyzer specialists anchor positions through membrane architecture specialization. Equipment fabricators compete on cryogenic storage infrastructure deployment near industrial offtake. Dominant competitive moves include strategic partnerships for electrolyzer-integrated project development and geographic expansion into port cluster logistics.
Within the industrial gas tier, Air Liquide and Linde plc exemplify integrated value chain operators spanning production through distribution. Among electrolyzer specialists, Nel ASA occupies a position representing alkaline and PEM system architecture focus. These three companies anchor the competitive landscape through distinct strategic positioning: industrial gas integration, large-scale cryogenic infrastructure, and electrolyzer technology specialization respectively.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products |
| ITM Power |
| Nel ASA |
| Cummins |
| Plug Power |
| Engie |
| Chart Industries |
| Others |
Supply Flow & Price Mechanics
Electrolyzer stack lead times stretching 18-24 months concentrate pricing power with German and Japanese manufacturers possessing captive membrane production, while compressed hydrogen tank fabricators in South Korea face margin compression from JIS certification delays and inventory carrying costs.
Pricing Analysis
Configured-to-order electrolyzer systems command 15-25% premiums over standard modular units, reflecting engineering customization for site-specific hydrogen output and integration complexity. Project-based contract structures dominate utility-scale procurement, with price differentiation driven by green certification tier and after-sales service bundling spanning 20-year asset lifecycles. Cost compression in alkaline electrolyzer segments intensifies as Chinese manufacturers scale membrane production, squeezing European PEM specialists. Chemical producers in Germany's Ruhr corridor exhibit lowest price sensitivity due to carbon accounting compliance deadlines, while municipal utilities in emerging markets prioritize capital expenditure minimization.
Supply Chain Analysis
China and Germany anchor electrolyzer manufacturing, with South Korea and Japan commanding composite pressure vessel fabrication. Platinum and iridium catalyst inputs draw from concentrated South African and Russian mining operations, creating single-source vulnerability for PEM membrane production. Distribution runs through port-centric logistics clusters in Rotterdam, Yokohama, and Houston, where cryogenic infrastructure and pipeline retrofit capabilities determine market access. Tariff exposure on Chinese alkaline electrolyzer exports to the EU threatens cost competitiveness for integrated storage developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen energy storage hardware margins are flattening while certification consulting and lifecycle verification services expand faster than equipment sales, creating attach-rate opportunities for recurring revenue streams.
For Market Incumbents: Fortify positions through backward integration into iridium catalyst recycling and captive membrane production, insulating margins from South African supply volatility. Deepen vertical control over electrolyzer-integrated project development in Germany's North Sea corridor to lock in 20-year offtake contracts before certification standards consolidate. Invest in JIS pre-certification for Japanese port cluster access, as Korean and Chinese competitors face extended approval timelines. For New Entrants and Emerging Players: Differentiate on solid-state metal hydride technology for forklift and backup power applications where compression infrastructure elimination justifies premium positioning. Target California's hydrogen highway corridor for rapid refueling infrastructure deployment, leveraging public funding availability and lower incumbent saturation than German or Japanese markets. Pursue ammonia cracking specialization for maritime shipping routes, capturing Rotterdam and Singapore port adaptation contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial gas majors seeking to divest non-core electrolyzer manufacturing assets amid alkaline-to-PEM technology transitions. Long-term viability hinges on certification scheme consolidation rather than hardware cost curves alone. Watch for ISO 19870 finalization as inflection indicator for stranded asset risk in competing verification investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Captive iridium sourcing from South African refiners insulates PEM margins from commodity volatility. |
| JIS Certification Pre-Investment | Early compliance with METI vessel safety protocols accelerates Japanese utility contract access. |
| Ammonia Cracking Infrastructure | Rotterdam port tankage adaptation unlocks Middle Eastern hydrogen import without cryogenic logistics. |
| Integrated Electrolyzer-Storage Packages | Single-vendor performance guarantees satisfy German chemical operators' round-trip efficiency requirements. |
| Green Certification Program Investment | CertifHy and TUV SUD early engagement secures offtake preference from hard-to-abate industrial buyers. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, electrolyzer project developers, EPC contractors, and industrial procurement leads; and secondary validation against EIA hydrogen hub disclosures, IEA technology roadmaps, FERC grid interconnection filings, and EU Green Deal implementation documents. Bottom-up electrolyzer deployment tallies triangulated with top-down carbon intensity target modeling.
Across the analysis window, forecasts employed technology-form-factor segmentation by storage state, application by discharge duration, end-user procurement complexity tier, and regional regulatory framework cluster. CAGRs derived from electrolyzer manufacturing capacity buildout curves, renewable curtailment patterns, and industrial feedstock substitution timelines.
The analysis sits within stated boundaries; outcomes outside EU Green Deal carbon intensity enforcement, METI funding continuity, or hydrogen hub appropriation levels would require recalibration. Forecasts reflect assumptions on certification scheme consolidation, catalyst supply diversification, and boil-off loss reduction technology maturation. Recalibration cycles align with material shifts in regulatory enforcement stringency and electrolyzer efficiency benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Merchant Hydrogen Market