
 Hydrogen-Cooled Turbine Generator Market | 2026-2036
Hydrogen-Cooled Turbine Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen-Cooled Turbine Generator Market Foresight
Turbine generator engineering talent is bifurcating between legacy air-cooled expertise and hydrogen-specific thermal management skills, constraining deployment timelines for next-generation units. Siemens Energy leverages its European manufacturing base to sustain hydrogen-cooled rotor supply chains for utility-scale projects. GE anchors North American demand through its long-standing utility relationships and heavy-duty gas turbine integration capabilities. Mitsubishi Electric differentiates via advanced hydrogen seal technology and precision winding expertise for high-capacity generators.
A hydrogen-cooled turbine generator employs pressurized hydrogen gas as the rotor and stator cooling medium, achieving thermal conductivity roughly seven times that of air and enabling higher power densities in units exceeding 300 MW. Combined cycle installations dominate current order books due to their superior heat rate performance and compatibility with hydrogen fuel blending roadmaps. Steam cycle retrofits represent a maturing revenue pool where margin compression limits new entrant participation. Open cycle configurations occupy niche peaking roles where rapid start capability outweighs efficiency penalties.
EPA emissions standards and MEE dual carbon goals are tightening allowable heat rates and NOx output, directly favoring hydrogen-cooled architectures that support higher firing temperatures and cleaner combustion profiles. IEC 60034 and IEEE C50.13 establish insulation thermal class and hydrogen purity benchmarks that determine generator warranty terms and interconnection eligibility. Stakeholders must monitor hydrogen infrastructure buildout pace and blending ratio mandates to calibrate capacity expansion decisions against fuel availability timelines.
Market Dynamics
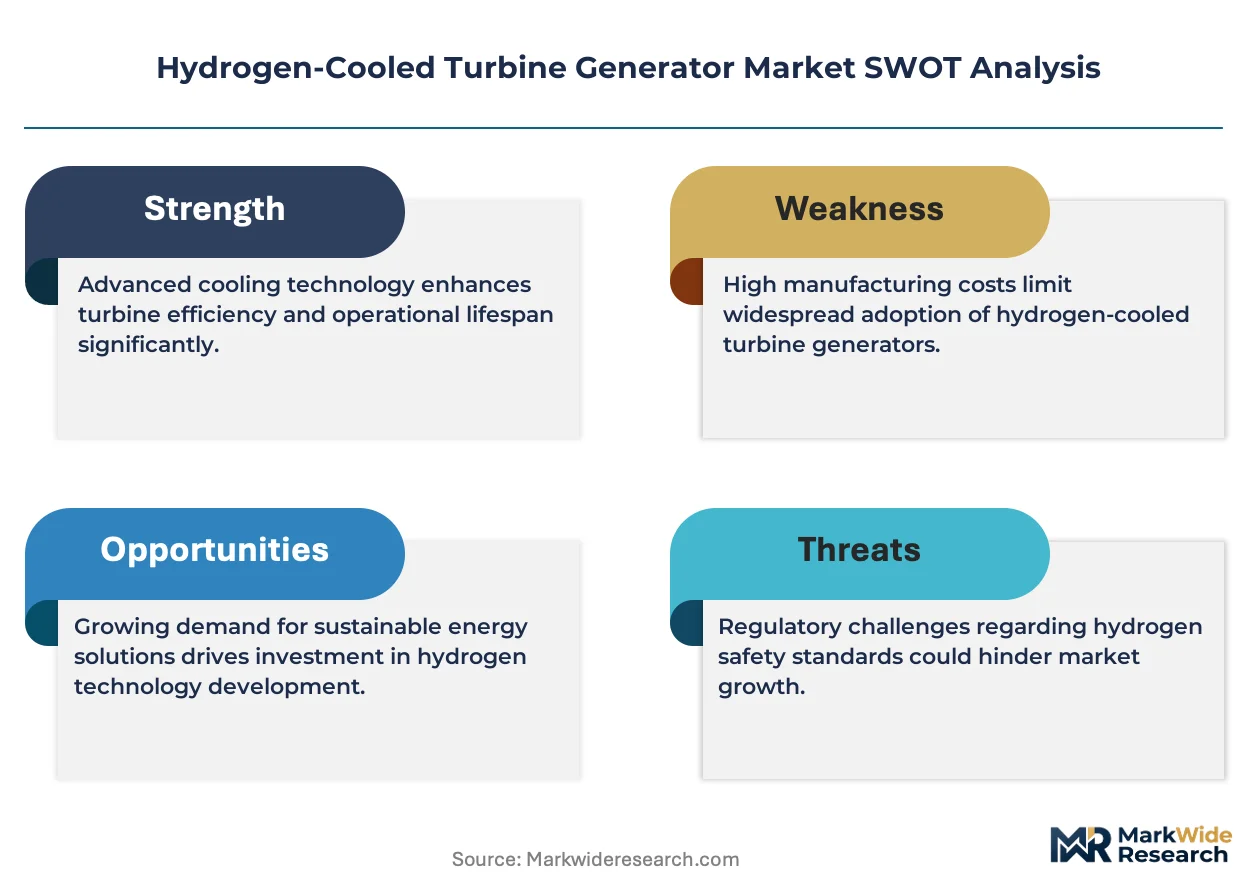
The hydrogen-cooled turbine generator market is experiencing a fundamental recalibration as utility procurement cycles compress and OEM engineering capacity concentrates among a shrinking pool of qualified suppliers. This supply-side tightening intersects with regulatory mandates for higher thermal efficiency, creating a structural bottleneck that favors incumbents with proven hydrogen seal and rotor winding expertise.
Growth Catalysts
- EPA emissions standards:The Environmental Protection Agency's tightening heat rate requirements are compelling US utilities to retire air-cooled units and specify hydrogen-cooled replacements for combined cycle baseload plants.
- China's dual carbon goals:The Ministry of Ecology and Environment framework is accelerating gas-fired capacity additions with hydrogen-ready turbine generators as bridging technology toward full decarbonization.
- Hydrogen fuel blending roadmaps:Utility-scale combined cycle operators are procuring next-generation generators capable of operating at 30% hydrogen fuel mix, locking in cooling architecture decisions early in project development.
Market Restraints
- Specialized alloy supply concentration:High-purity copper for precision rotor windings and nickel-based superalloys for hydrogen seals are sourced from a limited supplier base concentrated in Germany and Japan, exposing procurement to geopolitical friction.
- Technical limitation in retrofit economics:Steam cycle generator retrofits face margin compression due to site-specific civil works and foundation modifications that resist standardization.
- Substitution threat from direct air cooling:Advanced air-cooled designs with composite stator windings are capturing sub-300 MW orders where hydrogen infrastructure costs prove prohibitive.
Strategic Opportunities
- India's PLI scheme for power equipment:Production-linked incentives for domestic manufacturing of heavy electrical equipment are creating localized assembly opportunities for hydrogen-cooled generator components.
- Technology convergence with solid oxide electrolysis:Integrated hydrogen production and power generation facilities are specifying matched turbine generator sets with shared cooling systems and control architectures.
- Saudi Arabia's giga-project pipeline:NEOM and Red Sea tourism developments are procuring dedicated hydrogen-ready combined cycle plants with utility-scale generator specifications that exceed regional historical norms.
Industry Challenges
- Rotor winding specialist shortage:The bifurcation of engineering talent between air-cooled legacy expertise and hydrogen-specific thermal management skills is extending commissioning timelines for first-of-a-kind installations.
- IEC 60034 certification complexity:Insulation thermal class validation and hydrogen purity testing protocols are creating multi-month approval bottlenecks at third-party laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen-Cooled Turbine Generator Market |
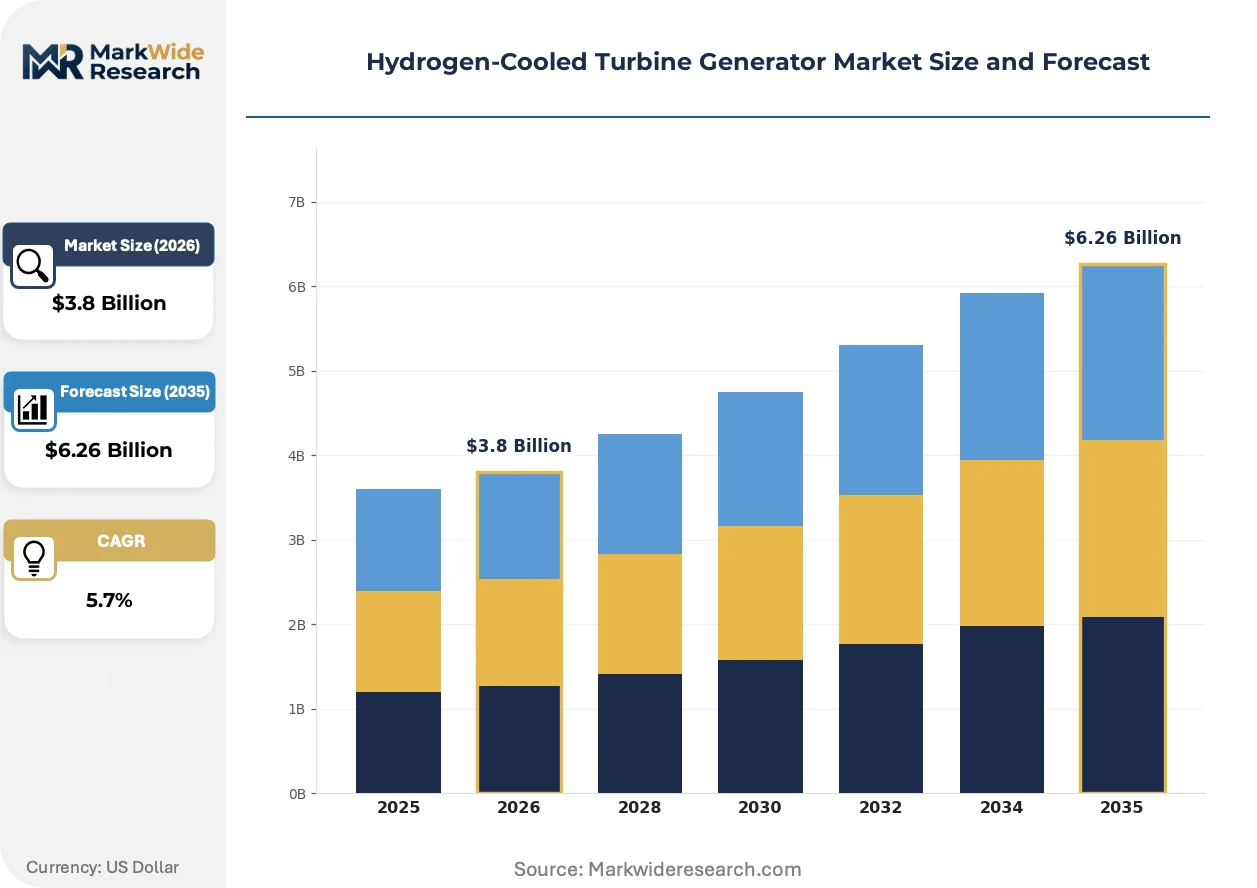
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Steam Cycle, Combined Cycle, Open Cycle, Advanced Cycle Fuel Type: Natural Gas, Hydrogen, Biogas, Diesel End User: Power Generation, Industrial Power, Marine, Aerospace Installation Type: Onshore, Offshore, Modular, Fixed |
| Companies Covered | GE, Siemens Energy, Mitsubishi Electric, Hitachi, Alstom, General Electric, Ansaldo Energia, Shanghai Electric, Doosan Enerbility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen-Cooled Turbine Generator Market Shifts & Advancements
Active innovation in hydrogen-cooled generator architecture is compressing physical footprints while expanding operational envelopes. These developments are reshaping procurement criteria and competitive differentiation among OEMs.
Direct hydrogen cooling of stator windings is miniaturizing generator frame sizes for equivalent megawatt ratings. Chinese utilities are specifying these compact units for urban combined cycle installations where site constraints limit building volumes. The technology is miniaturizing the civil works and foundation requirements that historically dominated project cost structures.
The EU F-Gas Regulation is phasing down sulfur hexafluoride use in electrical equipment, indirectly elevating hydrogen-cooled alternatives for generator switchgear integration. Industrial consequence includes accelerated R&D investment in hydrogen purity monitoring systems to prevent explosive mixture formation. European OEMs are responding with integrated generator-switchgear packages that eliminate SF6 entirely from the power train.
Long-term service agreements are unbundling from equipment purchase contracts as utilities seek operational flexibility. Independent service providers are capturing rotor rewinding and hydrogen seal replacement work that OEMs previously monopolized. This disintermediation is most visible in the US Southeast where merchant plant operators prioritize third-party maintenance to reduce fixed cost exposure.
Hydrogen-Cooled Turbine Generator Market Segmentation
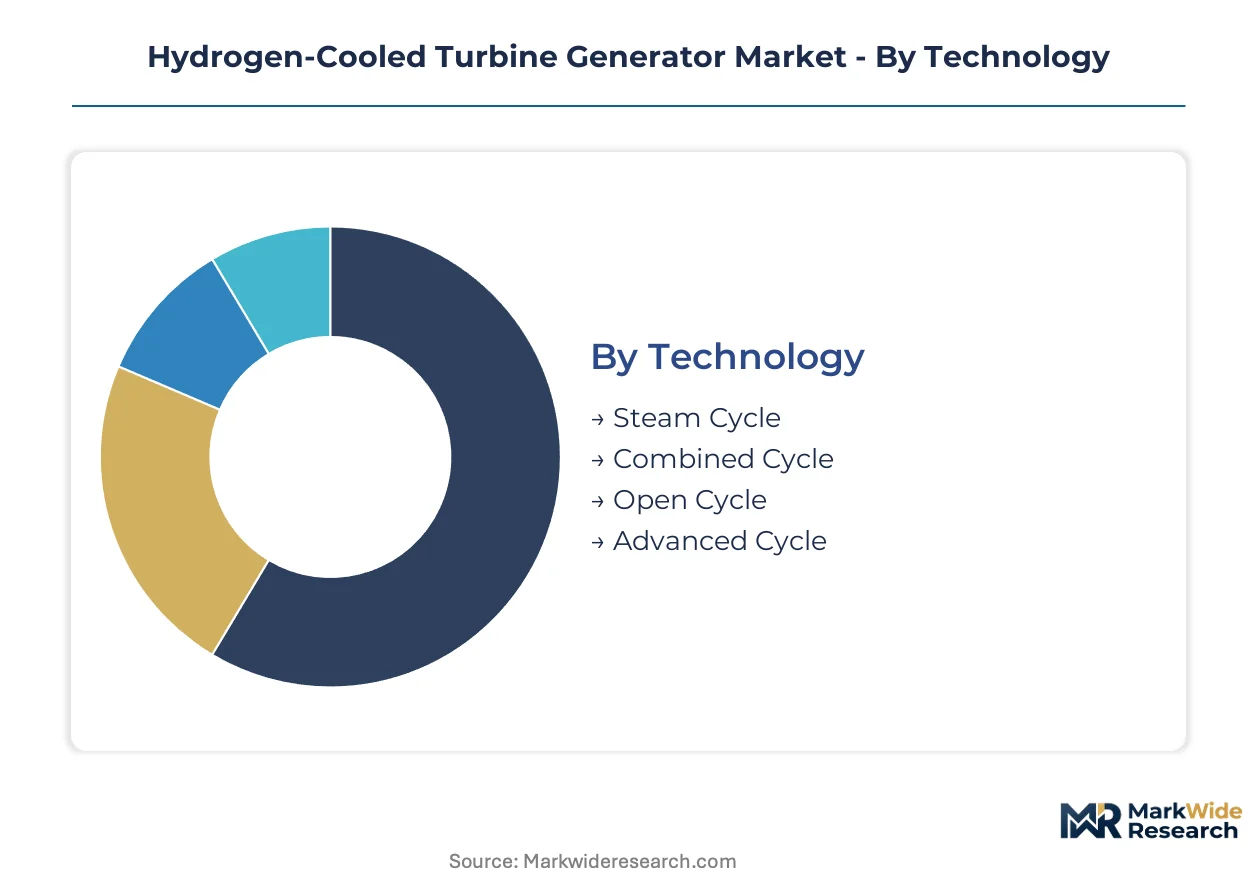
Segmentation in the hydrogen-cooled turbine generator market reveals how cooling architecture choices lock in across technology platforms, fuel roadmaps, and installation constraints. Each dimension carries distinct procurement economics and regulatory exposure that shape OEM competitive positioning.
Technology:
Substitution pressure from advanced air-cooled designs concentrates most intensely on smaller-capacity segments where hydrogen infrastructure costs outweigh thermal efficiency gains.
- Combined Cycle:These configurations integrate gas and steam turbines with shared hydrogen-cooled generators, achieving superior heat rates that satisfy EPA and MEE efficiency mandates. Demand clusters in China, the United States, and India where utilities scale gas-fired baseload capacity with hydrogen-ready specifications.
- Steam Cycle:Retrofit applications dominate this segment, leveraging existing civil works and foundation infrastructure to extend asset life. Margin compression from site-specific engineering requirements limits new entrant participation and concentrates revenue among incumbents with legacy installation databases.
- Open Cycle:Peaking plants specify these units where rapid start capability outweighs thermal efficiency penalties; hydrogen cooling enables higher power density in constrained footprints.
- Advanced Cycle:Experimental configurations integrating solid oxide fuel cells with turbine generators are piloting shared hydrogen cooling loops at integrated energy facilities.
Combined Cycle retains volume leadership; Advanced Cycle holds the steepest expansion curve.
Fuel Type:
Procurement patterns diverge sharply between established natural gas infrastructure and emerging hydrogen blending mandates that require generator warranty recertification.
- Natural Gas:Dominant fuel for current installations, with utilities specifying hydrogen-ready cooling architectures to future-proof against blending ratio mandates.
- Hydrogen:Pure hydrogen combustion demands specialized seal technology and purity monitoring systems; pilot projects in Saudi Arabia and European industrial clusters are validating generator performance at 100% hydrogen firing.
- Biogas:Agricultural and waste-to-energy facilities deploy hydrogen-cooled units for consistent baseload output where fuel variability requires robust thermal management.
- Diesel:Emergency backup and remote mining operations specify these generators; hydrogen cooling enables compact footprints in containerized installations where space constraints dominate.
Natural Gas commands current procurement volume; Hydrogen is climbing the fastest as blending roadmaps accelerate.
End User:
Customer type determines service agreement structures, with merchant operators prioritizing operational flexibility over integrated OEM maintenance packages.
- Power Generation:Utility-scale combined cycle operators represent the core revenue base, procuring units exceeding 300 MW with 30-year service life specifications.
- Industrial Power:Petrochemical and steel facilities deploy captive generation with hydrogen-cooled units sized for process steam integration and grid independence.
- Marine:LNG carriers and cruise vessels specify compact hydrogen-cooled generators where weight and volume constraints override first-cost considerations.
- Aerospace:Ground power and test facility applications occupy a niche segment with extreme reliability requirements and low unit volumes.
Power Generation anchors installed base value; Industrial Power is gaining share fastest through captive hydrogen production integration.
Installation Type:
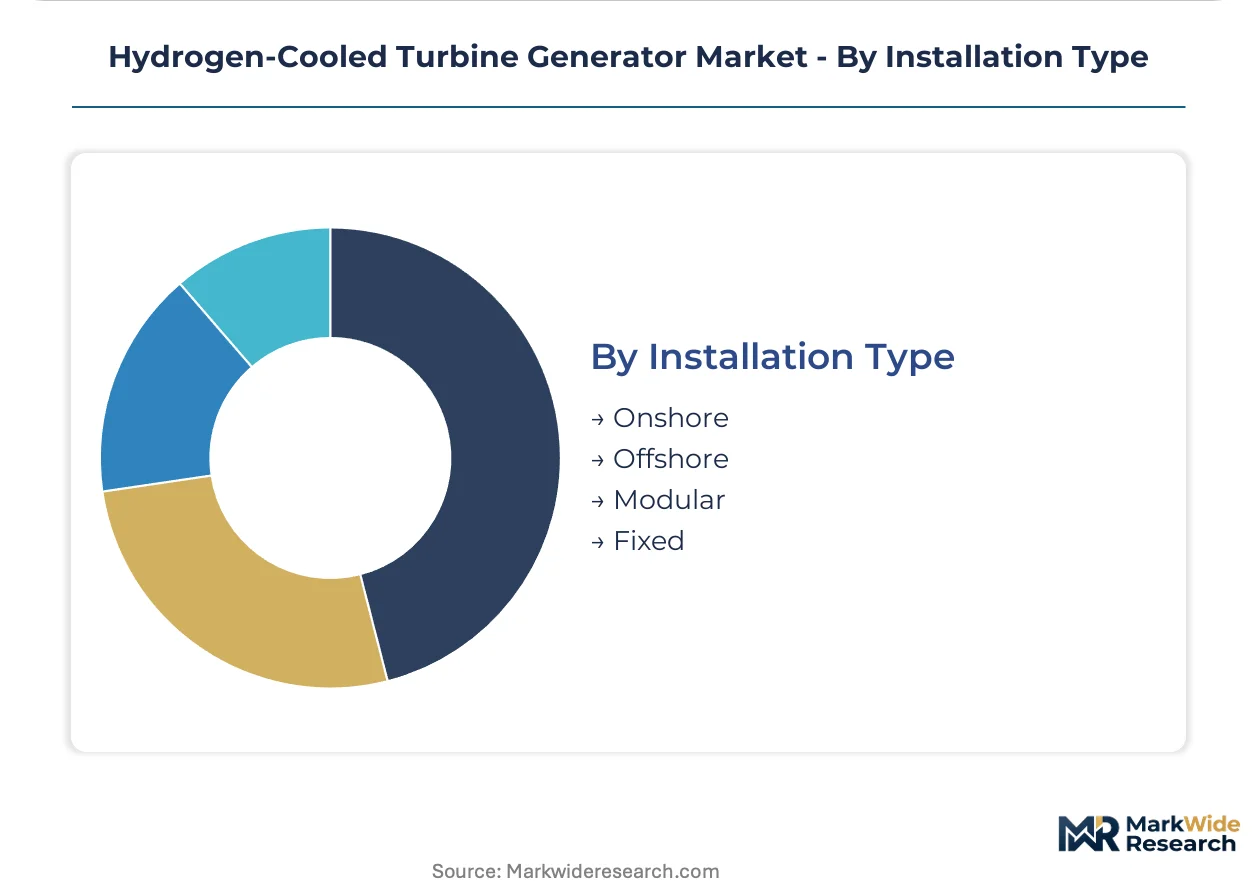
Margin structure varies with civil works intensity, as offshore and modular configurations command engineering premiums over standardized onshore deployments.
- Onshore:Conventional utility installations dominate order books, benefiting from standardized foundation designs and established supply chains for rotor transport and site assembly.
- Offshore:Platform-mounted generators for oil and gas or offshore wind integration require corrosion-resistant seals and compact frame sizes that elevate unit costs substantially.
- Modular:Factory-integrated generator-turbine packages compress commissioning timelines and reduce site labor exposure; Chinese utilities are specifying these for urban combined cycle projects with constrained construction windows.
- Fixed:Permanent installations at industrial facilities with dedicated hydrogen pipeline access minimize fuel logistics complexity and enable continuous operation profiles.
Onshore retains deployment volume leadership; Modular holds the steepest trajectory as procurement cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and MEE dual carbon frameworks are reshaping procurement patterns across utility markets worldwide. The analysis tracks five countries where hydrogen-cooled turbine generator deployment concentrates.
United States
FERC interconnection rules and EPA heat rate mandates are accelerating combined cycle retrofits across the Southeast and Texas. Merchant operators in the PJM and ERCOT markets specify hydrogen-ready generators to future-proof against blending requirements. The Permian Basin and Gulf Coast industrial corridors anchor demand for captive generation integrated with hydrogen production facilities.
China
MEE dual carbon targets and provincial renewable integration quotas are driving gas-fired capacity additions in coastal provinces. Yangtze River Delta utilities specify compact hydrogen-cooled units for urban combined cycle installations with constrained site footprints. Guangdong and Jiangsu provinces lead procurement volume through state-owned generation groups.
Germany
EU F-Gas Regulation phase-down and national hydrogen strategy roadmaps are elevating hydrogen-cooled architectures for industrial power applications. The Ruhr industrial cluster and Bavarian chemical corridor deploy captive generation with shared cooling loops for electrolysis integration. Grid stability requirements in northern wind-heavy regions favor fast-ramp hydrogen-ready units.
India
CEA technical standards and PLI scheme incentives for power equipment manufacturing are localizing assembly capacity for generator components. Gujarat and Maharashtra state utilities scale gas-fired baseload to complement renewable intermittency. The Hazira industrial belt and Mundra power hub concentrate demand for process-integrated generation.
Saudi Arabia
SFDA industrial safety frameworks and giga-project development timelines are procuring hydrogen-ready combined cycle plants at unprecedented scale. NEOM and Red Sea tourism developments specify utility-scale generators exceeding regional historical norms. The Eastern Province petrochemical complex anchors captive demand for hydrogen-cooled units with 30-year service specifications.
Hydrogen-Cooled Turbine Generator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. The market concentrates among integrated energy conglomerates with multi-decade utility relationships and specialized electrical equipment manufacturers with precision winding expertise. Three archetypes dominate: full-service OEMs with turbine-generator integration capabilities, generator specialists with hydrogen seal technology, and regional champions leveraging domestic content requirements. Competitive moves center on long-term service agreement unbundling and modular package standardization to compress commissioning timelines.
Among European-anchored conglomerates, Siemens Energy and Ansaldo Energia occupy positions defined by regional manufacturing footprints and utility-scale project execution. GE represents the North American integrated OEM archetype with heavy-duty gas turbine coupling capabilities. Mitsubishi Electric, Hitachi, and Doosan Enerbility exemplify Asia-Pacific specialists with advanced seal technology and precision manufacturing heritage. Shanghai Electric anchors Chinese domestic capacity expansion under localization mandates. Alstom sits within the European specialist tier with rotating machine expertise spanning multiple cooling architectures.
| Leading Market Players |
|---|
| GE |
| Siemens Energy |
| Mitsubishi Electric |
| Hitachi |
| Alstom |
| General Electric |
| Ansaldo Energia |
| Shanghai Electric |
| Doosan Enerbility |
| Others |
Supply & Pricing Matrix
Advanced air-cooled generator designs displacing hydrogen-cooled units in sub-300 MW applications simultaneously redraws supply geography toward East Asian manufacturing hubs and compresses pricing premiums for legacy hydrogen-seal technology. This substitution dynamic concentrates procurement leverage among Chinese and South Korean OEMs while forcing European and North American incumbents to recalibrate cost structures for remaining utility-scale segments.
Pricing Analysis
Chinese-manufactured units undercut European equivalents by substantial margins in standardized combined cycle configurations, while German and Japanese suppliers command premiums for hydrogen-seal precision in 300 MW-plus installations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with IEC 60034-validated units carrying substantial warranty premiums over unrated alternatives. Cost compression in the standard tier intensifies because modular package standardization reduces site-specific engineering margins. Merchant operators in deregulated US markets exhibit highest price sensitivity, while Saudi giga-project developers prioritize performance specifications over capital expenditure minimization.
Supply Chain Analysis
Strategic stockpiling of high-purity copper and nickel-based superalloys dominates procurement strategy among European OEMs confronting German and Japanese supplier concentration, while Chinese utilities rely on just-in-time delivery from domestic refined metal streams. Manufacturing gravity centers on Germany, Japan, and China for precision rotor windings and hydrogen seal components. Raw material feeds draw from Chilean copper mines, Indonesian nickel processing facilities, and Chinese rare earth refineries. Single-source vulnerability in hydrogen purity monitoring systems creates exposure to semiconductor component shortages. Distribution runs through EPC contractor channels for utility-scale projects, with direct OEM relationships governing aftermarket service parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen fuel blending roadmaps represent a structural inflection accelerating procurement cycles beyond OEM engineering capacity, compressing competitive windows for technology positioning. EPA and MEE regulatory tightening locks in hydrogen-cooled architectures for baseload applications through efficiency mandates that air-cooled alternatives cannot satisfy.
For Market Incumbents: Secure rotor winding specialist talent pools through apprenticeship pipelines and acquisition of precision manufacturing shops in Germany and Japan. Lock in long-term offtake agreements with Chilean copper and Indonesian nickel suppliers to insulate against commodity volatility. Defensive consolidation of hydrogen seal technology IP creates barriers against emerging Chinese competitors targeting modular package segments.
For New Entrants and Emerging Players: Differentiate on integrated generator-switchgear packages eliminating SF6 entirely, capturing EU F-Gas Regulation-driven retrofit demand. Target India's PLI scheme localization requirements for domestic assembly partnerships with Gujarat and Maharashtra state utilities. White-space concentration exists in aftermarket rotor rewinding services unbundled from OEM maintenance agreements, particularly in the US Southeast merchant plant segment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generator specialists possessing IEC 60034 certification infrastructure and legacy utility relationships. Long-term viability hinges on hydrogen infrastructure buildout pace and blending ratio mandate enforcement across the projection horizon. Acquisition priority targets precision winding shops with established hydrogen seal expertise and active utility service contracts. Watch for inflection when 30% hydrogen blending mandates cross threshold into binding procurement specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Certification Investment | IEC 60034 validation unlocks interconnection eligibility in EPA-regulated US utility markets. |
| Modular Package Standardization | Factory-integrated generator-turbine sets compress commissioning timelines for Chinese urban combined cycle projects. |
| Long-Term Service Agreement Unbundling | Independent providers capture rotor rewinding work previously monopolized by OEM incumbents. |
| Strategic Alloy Supply Partnership | Direct offtake from German and Japanese superalloy suppliers mitigates geopolitical procurement friction. |
| SF6-Free Switchgear Integration | Eliminates sulfur hexafluoride from power trains, aligning with EU F-Gas Regulation phase-down timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA capacity databases, IEA hydrogen roadmaps, FERC interconnection filings, and OEM technical documentation. Utility planning officers, IPP project developers, EPC contractors, and aftermarket service heads provided operational perspectives on procurement cycles and commissioning constraints. Bottom-up unit deployment tracking across combined cycle, steam cycle, and open cycle configurations triangulates against top-down market sizing from regulatory capacity announcements and OEM order backlogs.
Segmentation dimensions modeled span technology platform, fuel type roadmap, end-user archetype, and installation configuration across the projection horizon. Capacity tier stratification, hydrogen blending ratio specifications, and regional regulatory framework clusters anchor the analytical framework. CAGRs derive from installed base replacement schedules, greenfield project pipelines, and efficiency mandate compliance deadlines. Forecast inputs incorporate hydrogen infrastructure buildout pace, alloy supply availability, and rotor winding specialist labor pool expansion.
Material uncertainties — hydrogen blending mandate enforcement delays, alloy supply disruptions, and certification backlog extensions — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory trajectory and OEM engineering capacity scaling. Revision becomes warranted when hydrogen purity testing protocol changes or geopolitical trade restrictions cross thresholds affecting component sourcing feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen Production Electrolyser Market