
 Water Electrolysis Green Hydrogen Production Market | 2026-2036
Water Electrolysis Green Hydrogen Production Market Size, Share, and Industry Trends Forecast 2026-2036
Water Electrolysis Green Hydrogen Production Market Insights
Power purchase agreement-backed project finance is reconfiguring capital requirements for electrolyzer developers, enabling asset-light entrants to compete without balance-sheet intensity. Siemens Energy leverages its turbine-to-electrolyzer integration to anchor large-scale European deployments. Plug Power sustains North American market presence through captive fuel cell demand and on-site hydrogen generation contracts. Nel Hydrogen differentiates via automated manufacturing scale for PEM and alkaline stack production.
Water electrolysis green hydrogen production employs an electrochemical process splitting purified water into hydrogen and oxygen using direct current, with alkaline systems operating at 70-80°C and 1-30 bar while PEM units run at 50-80°C with proton-conducting polymer membranes to supply industrial feedstock and transport fuel. Alkaline electrolysis dominates installed capacity due to lower capital cost and mature supply chains, though PEM technology captures expanding share in renewable-coupled projects requiring rapid response. Solid oxide electrolysis occupies a nascent position with the highest theoretical efficiency but awaits durability validation for grid-scale deployment.
The EU Green Deal and delegated acts under the Renewable Energy Directive establish stringent criteria for green hydrogen certification, shaping product standards and cross-border trade eligibility. Japan METI and the US IRA production tax credits create divergent incentive architectures that reconfigure project economics by geography. Stakeholders must monitor evolving additionality requirements and certification reciprocity agreements that will determine which production assets qualify for premium offtake pricing.
Market Dynamics
Power purchase agreement structures are compressing project development timelines and redistributing capital risk between electrolyzer manufacturers, renewable developers, and offtakers across the US Gulf Coast and Rotterdam port clusters.
Growth Catalysts
- EU ETS Carbon Pricing:Tightened emissions trading scheme thresholds in Germany are forcing ammonia producers to contract green hydrogen supply, creating guaranteed offtake volumes for electrolyzer developers.
- Japan METI Roadmap:The ministry's hydrogen import targets are accelerating domestic electrolyzer deployment for export-oriented production facilities.
- Alkaline System Maturity:Established supply chains for nickel-coated steel electrodes and diaphragm materials are reducing commissioning delays for utility-scale installations.
Market Restraints
- Iridium Supply Concentration:South African and Russian mining operations control over 80% of global iridium output, creating price volatility for PEM catalyst coatings.
- Renewable Energy Directive Delegated Acts:Stringent additionality and temporal correlation requirements are disqualifying grid-connected electrolysis from green hydrogen certification.
- Grid Parity Gap:Levelized cost of hydrogen from electrolysis remains above grey hydrogen from steam methane reforming in regions without production tax credits.
Strategic Opportunities
- US IRA Production Tax Credits:The 45V credit structure rewards projects pairing electrolysis with new renewable buildout, creating first-mover advantages in Texas and California.
- Solid Oxide Electrolysis Convergence:High-temperature ceramic cells paired with industrial waste heat from steel and chemical plants are unlocking efficiency gains above 80%.
- Rotterdam Port Hydrogen Backbone:The converted natural gas pipeline network is creating a distribution channel independent of compressed tube trailer logistics.
Industry Challenges
- Electrolyzer Stack Assembly Talent:Shortages of technicians trained in proton exchange membrane sealing and catalyst layer deposition are extending commissioning schedules.
- Certification Timeline Compression:TÜV and DNV validation protocols for pressurized alkaline systems are creating 12-18 month approval bottlenecks for novel designs.
- Legacy Ammonia Plant Integration:Retrofitting Haber-Bosch synthesis loops for variable hydrogen feedstock requires custom compressor and buffer storage engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Electrolysis Green Hydrogen Production Market |
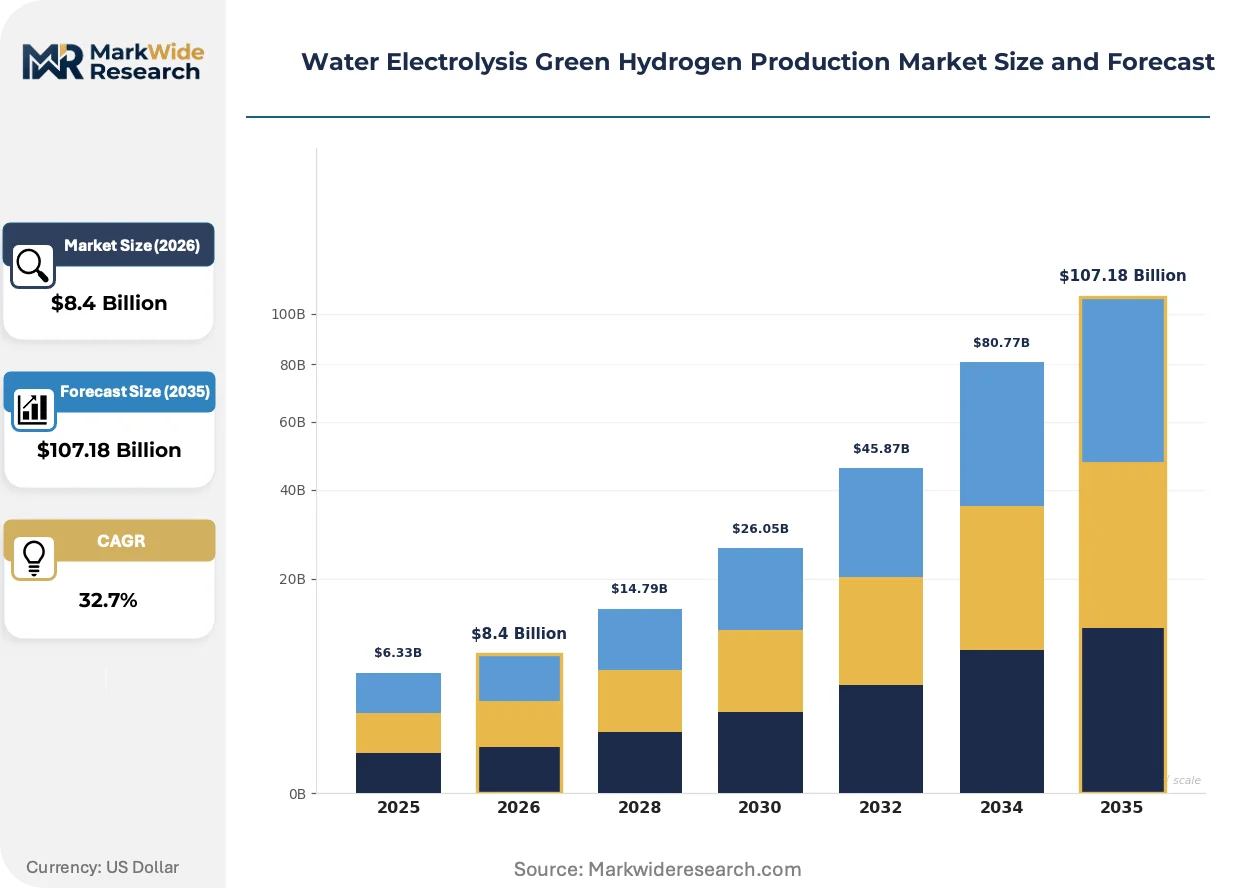
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $107.18 Billion |
| CAGR (2026 – 2036) | 32.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Alkaline Electrolysis, Proton Exchange Membrane, Solid Oxide Electrolysis, Anion Exchange Membrane End User: Industrial, Transportation, Power Generation, Chemical Production Deployment: On-site, Off-site, Centralized, Decentralized Application: Fuel Cells, Ammonia Production, Metal Processing, Energy Storage |
| Companies Covered | Siemens Energy, Plug Power, Linde, Nel Hydrogen, Thyssenkrupp Nucera, ITM Power, LONGi, Bloom Energy, Air Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Electrolysis Green Hydrogen Production Market Trends and Innovations
Electrolyzer technology trajectories are diverging between efficiency-optimized alkaline systems for baseload operation and response-optimized PEM units for renewable coupling, with solid oxide platforms emerging at the pilot stage.
PEM electrolyzer architecture is hybridizing with offshore wind control systems, enabling direct current coupling that bypasses grid interconnection costs. Danish and German developers are deploying these configurations at 100MW+ scale. The integration is compressing balance-of-plant costs while demanding new skill sets in power electronics and membrane humidity management.
EU Green Deal delegated acts under the Renewable Energy Directive are mandating hourly temporal correlation between renewable generation and hydrogen production. This regulatory architecture is disqualifying annual matching approaches and forcing electrolyzer developers to install dedicated solar or wind with minimal grid backup. German and Dutch projects are responding with oversizing ratios of 1.5-2x nameplate renewable capacity.
Offtake contracting is migrating from spot hydrogen markets to 10-15 year take-or-pay structures indexed to ammonia and methanol commodity prices. Chemical producers in Rotterdam and Houston are anchoring these agreements to secure feedstock cost predictability. The shift is visible most acutely in ammonia-to-fuel applications where bunker fuel specifications are tightening at the International Maritime Organization level.
Water Electrolysis Green Hydrogen Production Market Segmentation
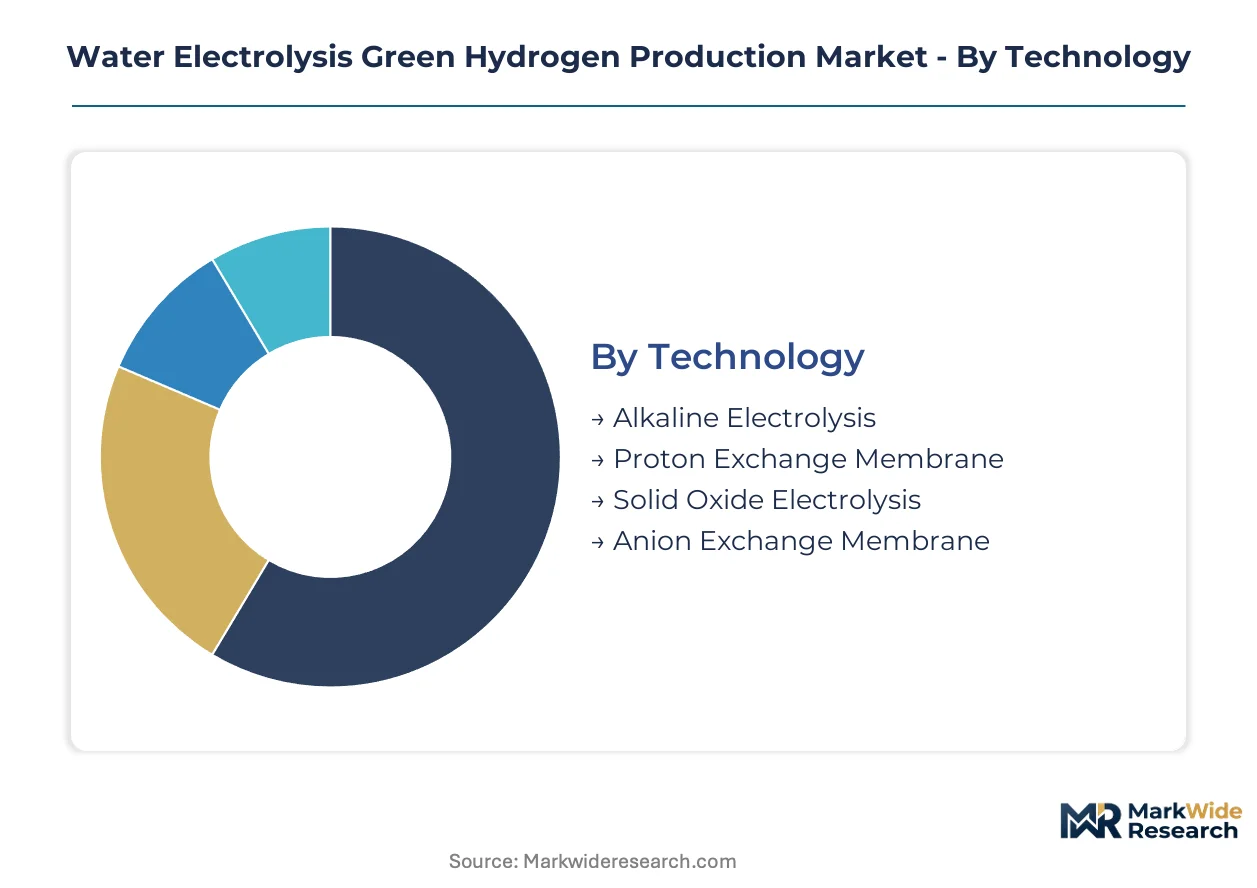
Technology choice dictates maintenance schedules, catalyst replacement cycles, and membrane refurbishment protocols that shape lifetime service revenue. End-use concentration in ammonia and transport applications is compressing commissioning timelines and forcing manufacturers to pre-qualify field service networks.
Technology:
After-sales intensity varies sharply across electrolyzer architectures, with membrane-based systems demanding specialized technician deployment and alkaline platforms relying on commodity electrode refurbishment.
- Alkaline Electrolysis:Nickel-coated steel electrodes and asbestos-free diaphragms operate at 70-80°C with 1-30 bar pressure ratings. German ammonia producers in the Rhine corridor are specifying 20-year service contracts with electrode replacement schedules to secure EU Green Deal compliance certification.
- Proton Exchange Membrane:Proton-conducting polymer membranes with platinum and iridium catalyst coatings run at 50-80°C with rapid response capability. Texas and California developers pairing PEM units with solar farms are contracting manufacturer-led membrane refurbishment to maintain 45V tax credit eligibility.
- Solid Oxide Electrolysis:High-temperature ceramic cells above 700°C paired with industrial waste heat streams.
- Anion Exchange Membrane:Emerging alkaline-compatible polymer architecture eliminating precious metal catalysts.
By volume, Alkaline Electrolysis leads. By growth pace, Proton Exchange Membrane is expanding most quickly.
End User:
Cost tier differentiation separates heavy industrial offtakers with 15-year contracting horizons from transport operators seeking hourly hydrogen delivery flexibility.
- Industrial:Steel mills and refineries requiring 99.999% purity hydrogen for direct reduction and hydrocracking processes. Rotterdam port cluster steelmakers are anchoring 10-year take-or-pay contracts to secure feedstock cost predictability against EU ETS carbon pricing.
- Transportation:Heavy-duty trucking and maritime bunkering applications demanding 350-700 bar compressed hydrogen or cryogenic liquid supply. Japanese METI-backed import terminals are concentrating procurement for ammonia-to-fuel cracking to meet International Maritime Organization bunker specifications.
- Power Generation:Grid-scale storage and peaking plants utilizing hydrogen turbines.
- Chemical Production:Methanol synthesis and specialty chemical hydrogenation requiring consistent feedstock quality.
Industrial offtakers dominate committed volumes. Transportation is climbing the fastest as fuel cell truck fleets scale.
Deployment:
Geography determines interconnection complexity, with port-adjacent centralized plants accessing converted pipeline networks while industrial on-site units bypass hydrogen logistics entirely.
- On-site:Electrolyzer installation at point of consumption eliminating tube trailer or pipeline delivery costs. German chemical parks in Ludwigshafen and Leverkusen are integrating 100MW+ units directly into Haber-Bosch synthesis loops with custom buffer storage engineering.
- Centralized:Large-scale production hubs feeding multiple offtakers through distribution infrastructure. Rotterdam's converted natural gas pipeline backbone is enabling 1GW+ clusters independent of compressed hydrogen logistics constraints.
- Off-site:Remote renewable-coupled production with hydrogen transport to demand centers.
- Decentralized:Distributed small-scale units serving isolated industrial facilities or fueling stations.
Centralized deployment leads by capital deployment. On-site configurations are gaining share fastest as industrial retrofit timelines compress.
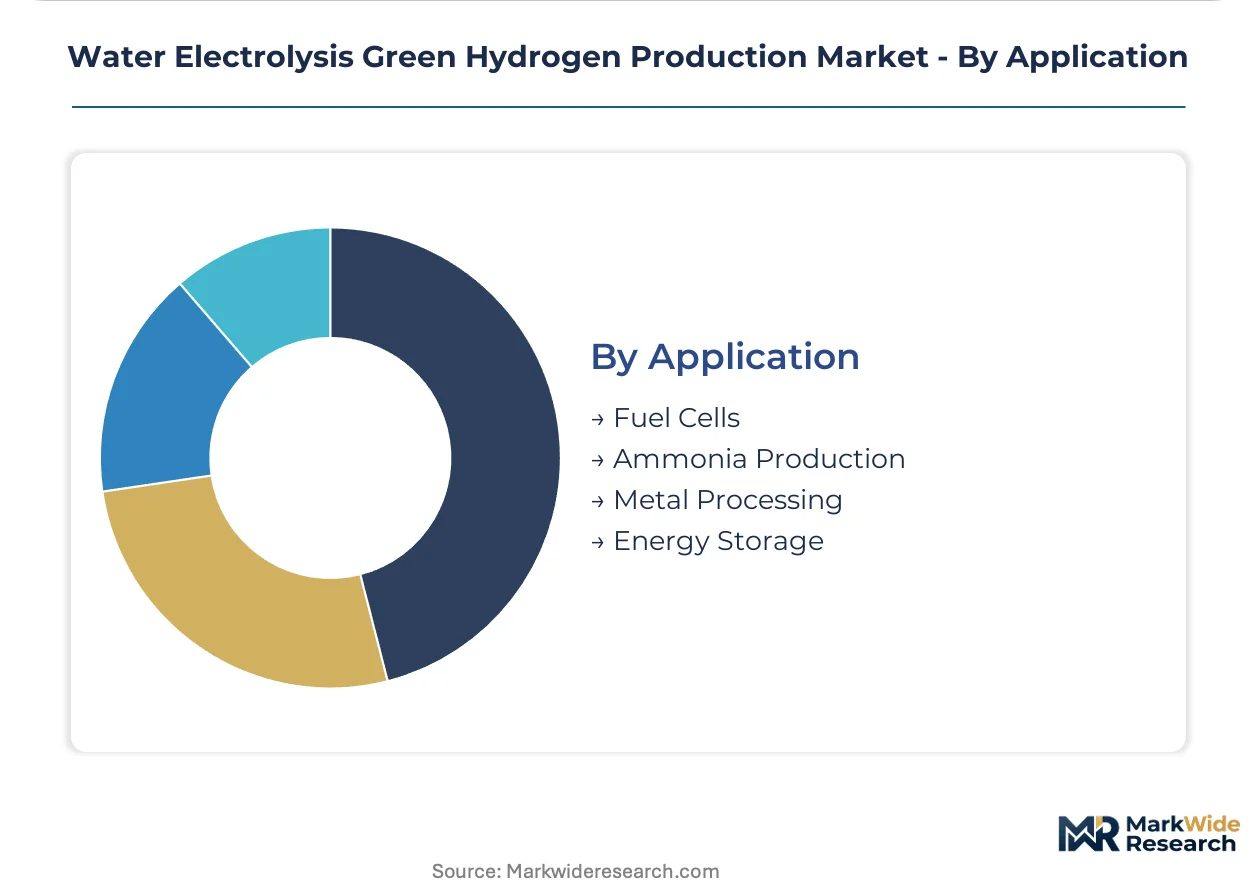
Application:
Margin structures diverge between commodity ammonia feedstock with thin spreads and premium fuel cell hydrogen with certification-linked pricing.
- Ammonia Production:Haber-Bosch synthesis feedstock for fertilizer and maritime fuel applications. Japanese and German producers are expanding offtake agreements under tightened EU ETS thresholds and METI hydrogen import roadmaps to secure guaranteed volumes.
- Fuel Cells:Mobility and stationary power applications requiring ultra-high purity hydrogen with trace contaminant specifications below 0.1 ppm total impurities. California's LCFS credit stacking with IRA 45V incentives is concentrating PEM deployment for heavy-duty trucking corridors.
- Metal Processing:Direct iron reduction and heat treatment applications in steel manufacturing.
- Energy Storage:Long-duration seasonal storage and grid balancing services.
Ammonia Production leads by electrolyzer capacity commitment. Fuel Cells show the steepest expansion trajectory as mobility subsidies activate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Green hydrogen production costs in Germany command premium pricing against US Gulf Coast projects backed by IRA incentives, creating divergent project finance structures across Atlantic markets. This pricing asymmetry is reshaping electrolyzer deployment timelines and offtake contracting patterns.
Germany
Rhine corridor ammonia producers are contracting 100MW+ alkaline electrolyzer installations under tightened EU ETS thresholds. The EU Green Deal delegated acts mandate hourly temporal correlation for green hydrogen certification. Ludwigshafen and Leverkusen chemical parks are integrating electrolyzers directly into Haber-Bosch synthesis loops with custom buffer storage engineering.
United States
Texas and California developers are pairing PEM units with solar farms to capture 45V production tax credit stacking. The IRA rewards projects pairing electrolysis with new renewable buildout. Houston and Corpus Christi port clusters are anchoring 10-15 year take-or-pay offtake contracts for ammonia-to-fuel applications.
Japan
METI hydrogen import targets are accelerating domestic electrolyzer deployment for export-oriented production facilities. The ministry's roadmap mandates ammonia cracking infrastructure for maritime bunkering. Yokohama and Osaka Bay industrial zones are concentrating procurement for International Maritime Organization-compliant fuel specifications.
Netherlands
Rotterdam's converted natural gas pipeline backbone is enabling 1GW+ electrolyzer clusters independent of compressed hydrogen logistics. The EU Renewable Energy Directive shapes certification requirements for cross-border trade eligibility. Port-adjacent steelmakers are anchoring long-term contracts to secure feedstock cost predictability against carbon pricing.
China
Dual carbon goals under MEE oversight are driving utility-scale alkaline system deployments in coastal industrial zones. GB standards and MIIT industrial policy favor domestic stack manufacturing. Yangtze River Delta chemical parks are specifying 20-year service contracts with electrode replacement schedules for compliance documentation.
Water Electrolysis Green Hydrogen Production Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in membrane, catalyst, and power electronics supply. The vendor base organizes around three archetypes: turbine-to-electrolyzer integrators leveraging rotating equipment heritage, automated stack manufacturers scaling PEM and alkaline production lines, and industrial gas incumbents with captive offtake relationships. Consolidation pressure is concentrating around strategic partnerships for offshore wind coupling and backward integration into precious metal catalyst supply.
Among European platform integrators, Siemens Energy and Thyssenkrupp Nucera occupy positions anchored to industrial process engineering heritage. ITM Power exemplifies the PEM specialist archetype with automated manufacturing scale. Plug Power represents North American presence through captive fuel cell demand integration. These three sit within distinct competitive vectors: system integration, manufacturing scale, and vertical demand capture.
| Leading Market Players |
|---|
| Siemens Energy |
| Plug Power |
| Linde |
| Nel Hydrogen |
| Thyssenkrupp Nucera |
| ITM Power |
| LONGi |
| Bloom Energy |
| Air Products |
| Others |
Pricing and Supply Chain Analysis
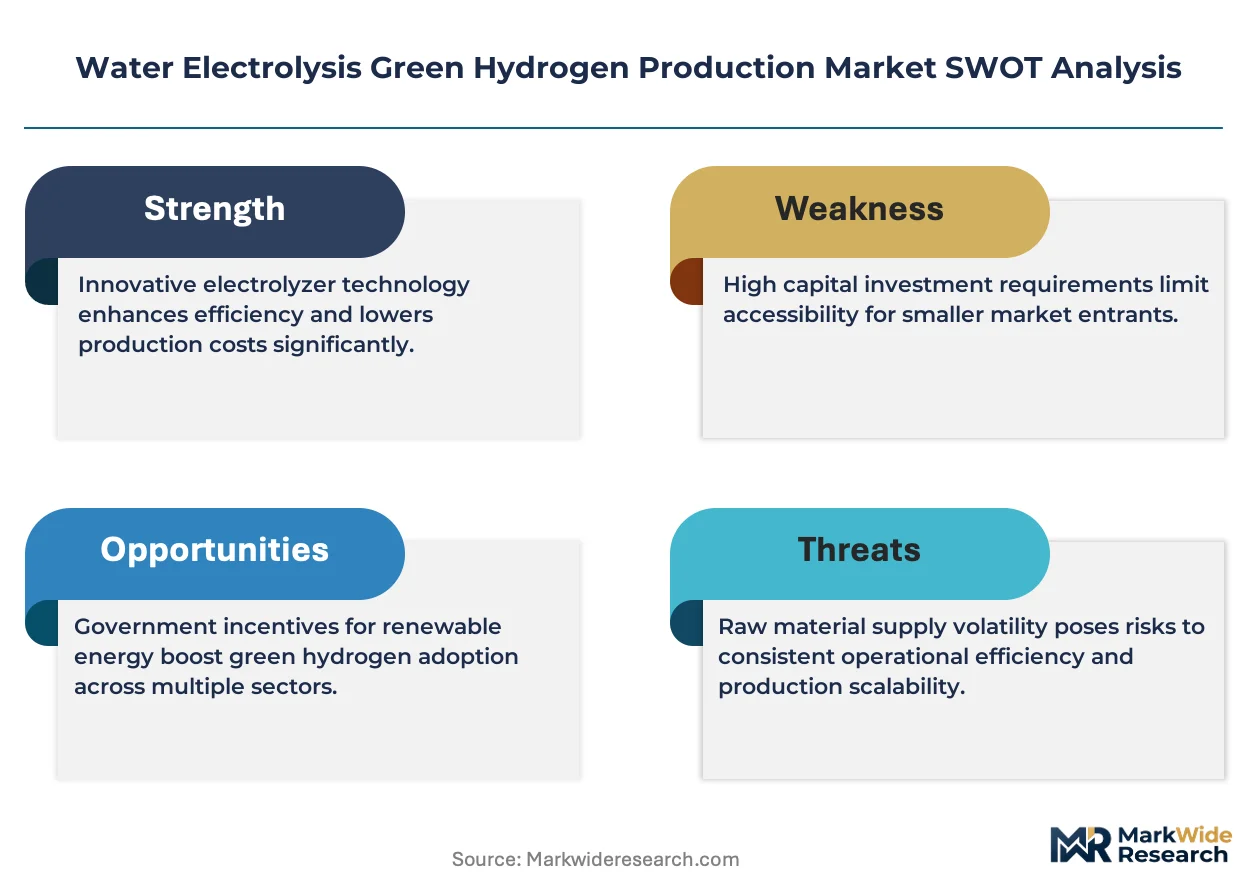
South African and Russian mining operations control over 80% of global iridium output, concentrating catalyst cost volatility in PEM electrolyzer stacks and compressing margin pools at system integrators rather than stack assemblers. This upstream concentration forces pricing power downstream toward membrane deposition specialists and away from balance-of-plant fabricators.
Pricing Analysis
Configured-to-order alkaline systems for German chemical parks command 15-25% premiums over standard PEM units for solar-coupled projects in Texas. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-certified installations from grid-connected units disqualified under Renewable Energy Directive delegated acts. Cost compression in standard PEM tiers is intensifying because iridium spot volatility feeds directly into catalyst layer deposition costs. Ammonia producers in Rotterdam show least price sensitivity due to EU ETS carbon pricing pass-through, while Texas solar developers exhibit highest sensitivity to stack capital cost.
Supply Chain Analysis
Extended payment terms from Japanese METI-backed project sponsors are reshaping working capital requirements for membrane manufacturers. Supply concentrates in Germany for precision-coated steel electrodes, China for alkaline diaphragm materials, and South Africa for iridium catalyst precursors. Raw material dependencies center on proton-conducting polymer membranes, nickel-coated electrode substrates, and high-purity titanium bipolar plates. Single-source vulnerability runs through South African platinum group metal refiners. Distribution runs through Rotterdam's converted pipeline backbone for port-adjacent clusters and compressed tube trailer networks for inland industrial sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyzer markets are approaching a platform-economics inflection where interoperability between offshore wind control systems and PEM stack power electronics determines competitive survival. The emergence of direct-current coupling architectures is fragmenting vendor lock-in advantages.
For Market Incumbents: Insulate service revenue streams by anchoring 20-year electrode replacement contracts with German ammonia producers. Deepen backward integration into precious metal catalyst supply to offset South African concentration risk. Siemens Energy and Thyssenkrupp Nucera must defend against automated stack manufacturers by pre-qualifying field service networks before certification bottlenecks ease.
For New Entrants and Emerging Players: Pursue solid oxide electrolysis pilot deployments at steel plants with accessible industrial waste heat streams. The nascent high-temperature segment offers lowest competitive density and fastest regulatory tailwind under EU efficiency mandates. Target anion exchange membrane technology licensing to alkaline incumbents seeking precious metal elimination.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed PEM specialists holding automated manufacturing scale but lacking turbine integration heritage. Long-term viability hinges on 5-10 year certification reciprocity agreements between EU Green Deal and Japan METI frameworks. Watch for TÜV validation protocol streamlining as the inflection signal indicating margin recovery in novel stack designs.
| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term renewable coupling secures 45V tax credit eligibility for Texas developers. |
| Backward Integration into Catalyst Supply | Captive iridium sourcing insulates PEM manufacturers from South African volatility. |
| Offshore Wind Direct Coupling | Danish and German 100MW+ deployments bypass grid interconnection cost premiums. |
| Certification Pre-Qualification Investment | TÜV and DNV validation compression accelerates novel alkaline system market entry. |
| Industrial Waste Heat Integration | Solid oxide pairing with steel plant exhaust unlocks efficiency gains above 80%. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA capacity data, IEA hydrogen technology reports, EU ETS compliance filings, and FERC interconnection queues. Electrolyzer manufacturers, offshore wind project developers, EPC contractors, and ammonia procurement leads provided structured input. Customs trade data for nickel-coated electrode imports and SEC filings from listed hydrogen technology suppliers furnished secondary validation. Bottom-up stack shipment aggregation and top-down renewable capacity modeling were cross-referenced.
Forecast inputs include electrolyzer technology trajectories, renewable PPA pricing dynamics, and regulatory certification evolution across the projection horizon. Segmentation dimensions cover technology architecture, end-use concentration, deployment configuration, and regional incentive framework. CAGRs were derived from capacity deployment curves mapped against offtake contracting velocity. IRA 45V credit phase-out schedules and EU Green Deal delegated act amendments were modeled as scenario variables.
Sensitivities concentrate around iridium supply disruption, temporal correlation requirement tightening, and offshore wind installation delays. Forecasts reflect assumptions regarding certification reciprocity and power purchase agreement tenor availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market