
 Hydrogen Storage Tank Market | 2026-2036
Hydrogen Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Storage Tank Market Intelligence
Fleet operators in heavy-duty trucking are unwinding reliance on diesel procurement as hydrogen fuel cell economics improve for long-haul routes. Worthington Industries leverages its steel cylinder expertise to anchor North American manufacturing scale for compressed gas tanks. Hexagon Composites dominates lightweight composite pressure vessel design for automotive applications. Luxfer Group specializes in aluminum-lined cylinders that balance cost and weight for industrial gas distribution.
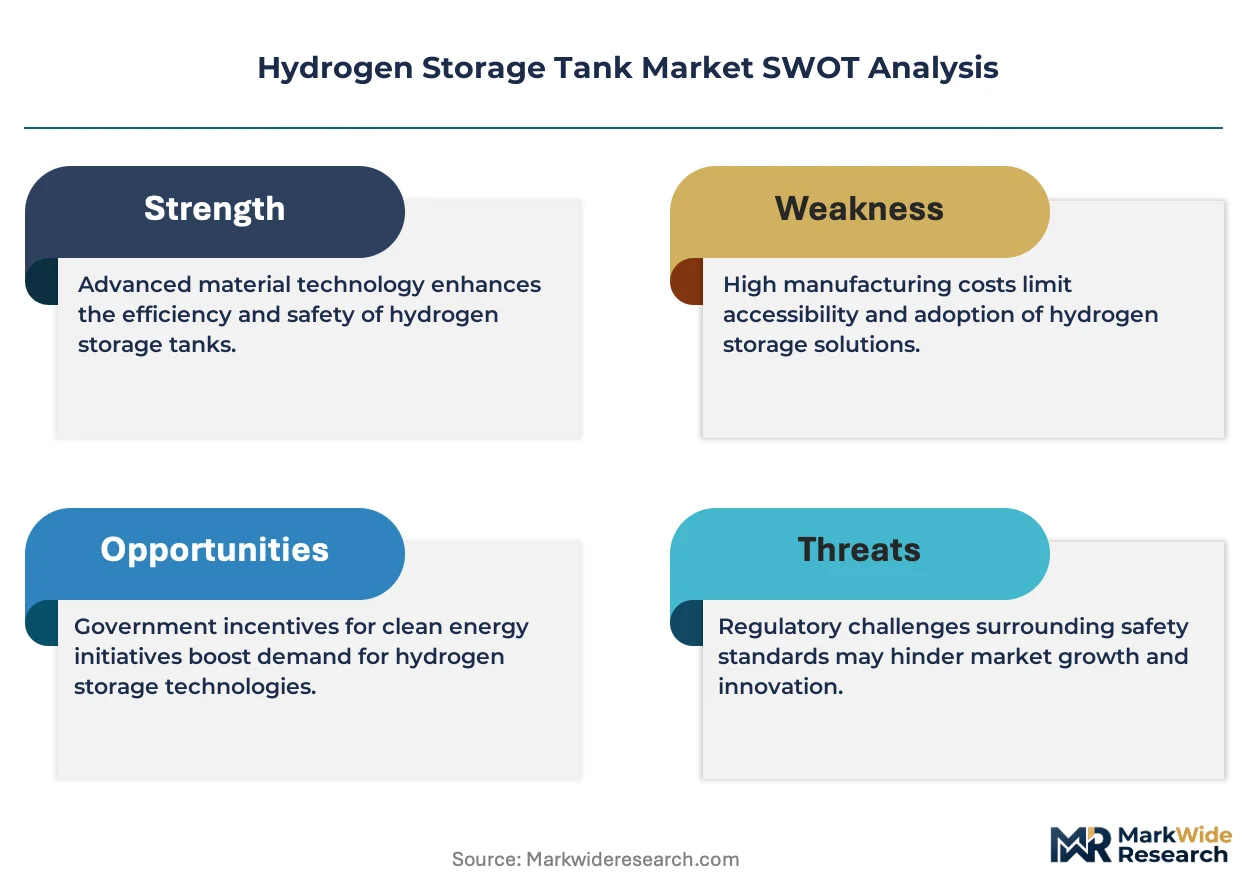
Hydrogen storage tanks are pressure vessels engineered to contain hydrogen in compressed gas, cryogenic liquid, or metal hydride forms, typically operating at pressures from 350 to 700 bar or temperatures near minus 253 degrees Celsius for liquid storage, serving the fundamental purpose of enabling safe hydrogen transport and dispensing across mobility and energy systems. Compressed gas technology leads installed base owing to infrastructure maturity and lower capital requirements, while cryogenic systems capture expanding margin pools as liquefaction costs decline and long-duration energy storage applications multiply. Metal hydride storage competes in niche stationary and portable power segments where volumetric density outweighs gravimetric efficiency.
The US Department of Transportation and the EU Pressure Equipment Directive enforce divergent certification protocols for tank safety and cycling durability, compelling manufacturers to maintain parallel testing regimes. Japan's METI hydrogen safety standards and South Korea's KGS codes add further compliance layers for market access across the three dominant demand clusters. Stakeholders must monitor regulatory convergence on tank recycling protocols and embodied carbon thresholds as these emerge as the next gatekeepers for product qualification.
Market Dynamics
Compressed gas tank certification requirements under the EU F-Gas Regulation are forcing parallel testing investments across manufacturing footprints, while heavy-duty fleet operators accelerate procurement timelines for zero-emission alternatives to diesel powertrains.
Growth Catalysts
- EU F-Gas Regulation:The framework mandates accelerated tank certification protocols that compress supplier qualification timelines and expand addressable market access for certified manufacturers.
- Heavy-duty transport fleets:Operators across Germany and South Korea are unwinding diesel procurement contracts as hydrogen fuel cell economics improve for long-haul route applications.
- Cryogenic liquid storage:Declining liquefaction costs and expanding long-duration energy storage applications are pulling investment toward minus 253 degrees Celsius systems.
Market Restraints
- High-purity aluminum input costs:Volatility in aluminum alloy pricing compresses margins for aluminum-lined cylinder manufacturers serving industrial gas distribution.
- Supply concentration in East Asian composites:Carbon fiber precursor and filament winding capacity clusters in Japan and South Korea, creating single-source exposure for lightweight vessel producers.
- Metal hydride gravimetric density:The technology's weight penalty limits adoption to stationary and portable power segments where volumetric density outweighs mass efficiency concerns.
Strategic Opportunities
- US IRA hydrogen production tax credits:The incentive structure is pulling infrastructure investment toward domestic tank manufacturing scale-up for compressed gas systems.
- Maritime propulsion applications:Ammonia and hydrogen dual-fuel vessel orders are creating new demand for high-capacity cryogenic storage in port clusters.
- Japan METI hydrogen safety standards:Early alignment with these codes positions suppliers for preferential access to Tokyo Bay and Osaka hydrogen hub procurement.
Industry Challenges
- Pressure cycling fatigue testing:The 15,000-cycle certification requirement under EU Pressure Equipment Directive extends product development timelines by 18-24 months.
- Cross-border regulatory divergence:Parallel compliance with US DOT, EU PED, and South Korea KGS protocols fragments engineering resources and testing budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Storage Tank Market |
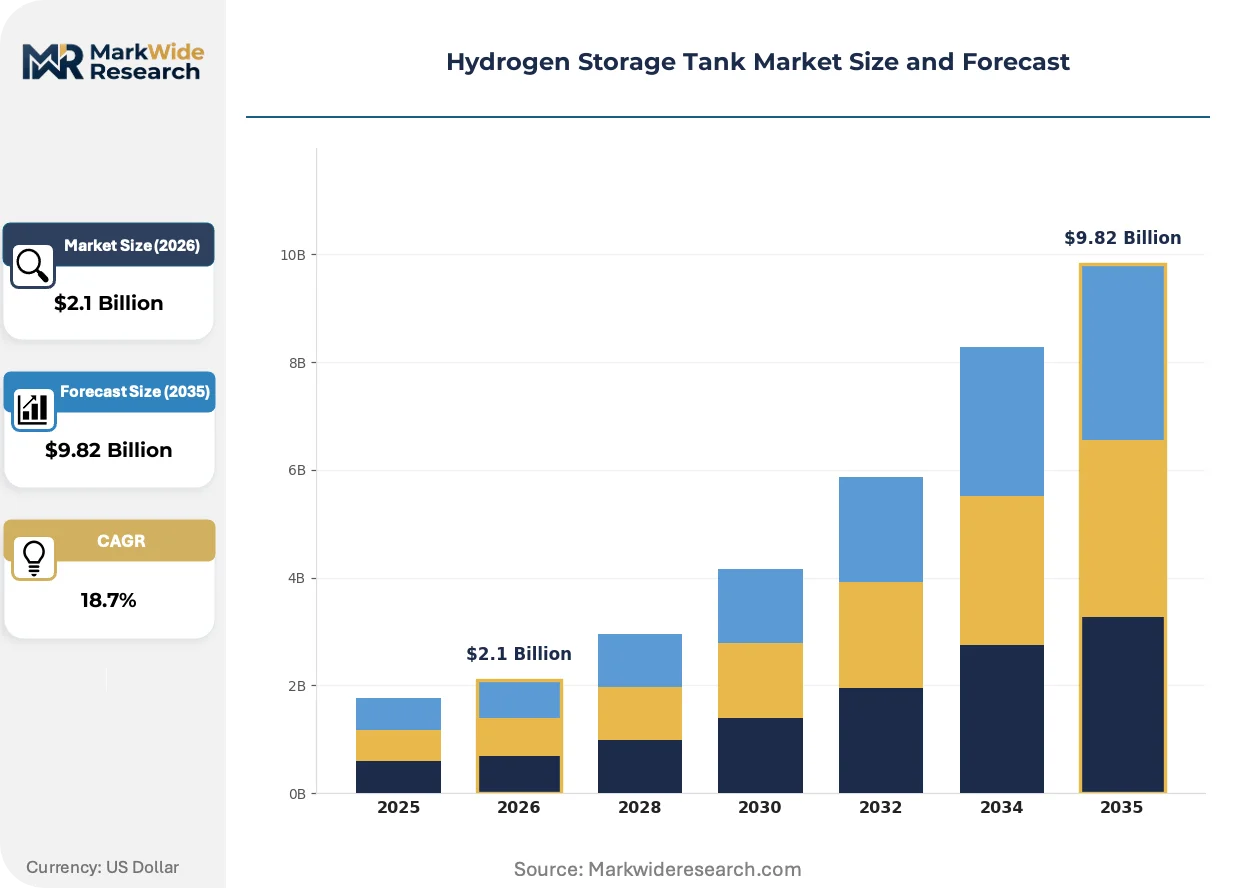
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cryogenic, Compressed Gas, Metal Hydride, Liquid Hydrogen Application: Transport, Energy Storage, Fuel Cells, Industrial Use End User: Automotive, Aerospace, Power Generation, Industrial Sectors Material: Steel, Aluminum, Composite, Polymer |
| Companies Covered | Worthington Industries, Luxfer Group, Hexagon Composites, Hexagon Purus, NPROXX, Quantum Fuel Systems LLC, Faber Industrie, Everest Kanto Cylinders Ltd., Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Storage Tank Market Strategic Shifts & Innovations
Type V all-composite pressure vessels are fragmenting the traditional aluminum-lined cylinder market as manufacturers pursue maximum gravimetric efficiency for automotive applications. The shift is compressing incumbent product lifecycles and redrawing supplier qualification hierarchies.
Composite filament winding automation is fragmenting production economics across tank categories. Automotive OEMs in Germany and Japan are qualifying suppliers with robotic winding capabilities for 700 bar automotive tanks. The technology is compressing labor cost differentials between established and emerging manufacturing bases.
The EU F-Gas Regulation is tightening embodied carbon reporting requirements for pressure equipment imports. Manufacturers must now document lifecycle emissions across aluminum smelting, carbon fiber production, and vessel fabrication. German and French certification bodies are processing the first wave of carbon-footprint-qualified tank designs.
Fleet operators are consolidating procurement under long-term service agreements that bundle tank leasing, maintenance, and hydrogen supply. The model is displacing discrete equipment purchases in California and Rotterdam port corridors. Energy majors are capturing tank asset ownership while operators focus on route economics.
Hydrogen Storage Tank Market Segmentation
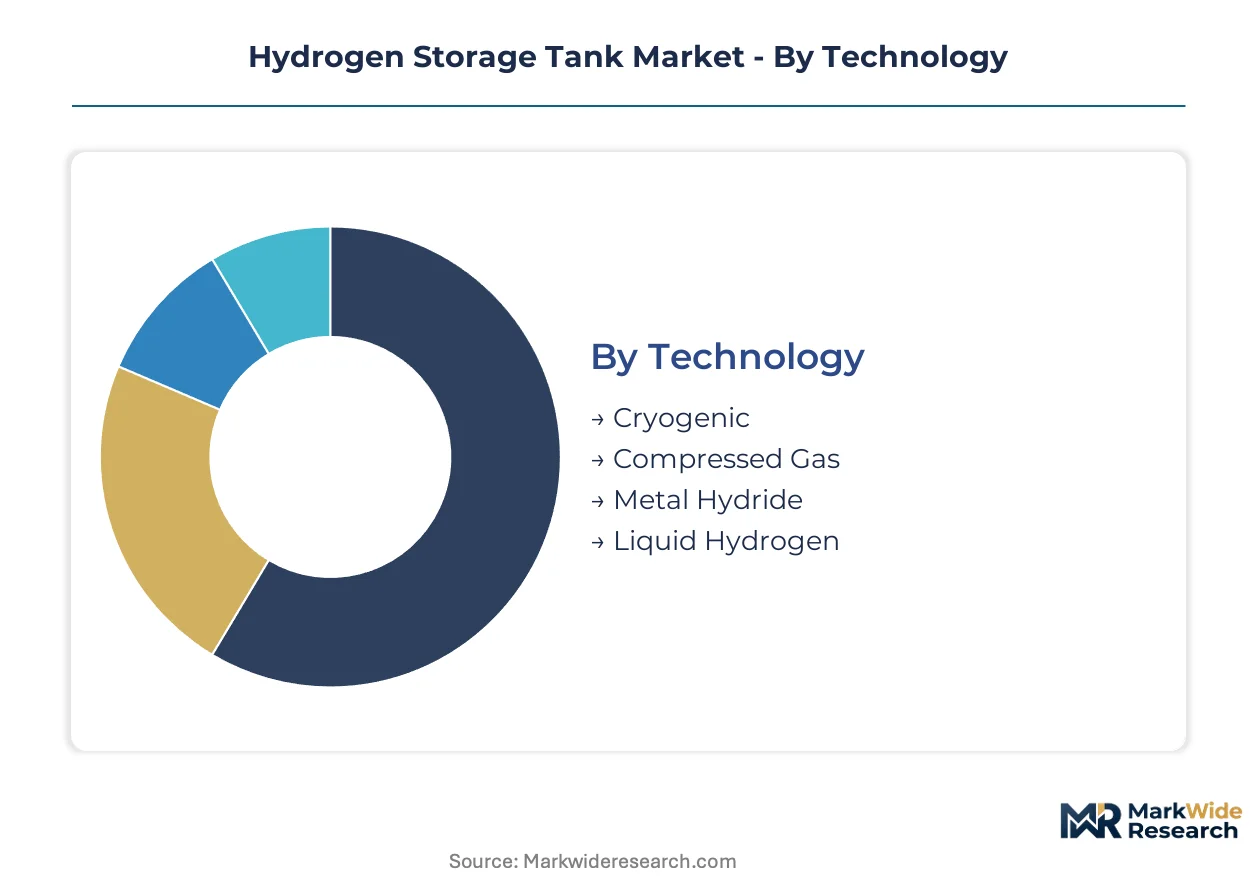
Technology and material choices in hydrogen storage tank manufacturing create divergent cost structures and certification pathways. Application requirements across mobility, stationary power, and industrial gas distribution pull tank specifications toward incompatible design optima.
Technology:
Compressed gas systems dominate domestic manufacturing footprints in Germany, Japan, and South Korea, while cryogenic and liquid hydrogen technologies concentrate export-led supply chains serving maritime and aerospace clients.
- Compressed Gas:Pressure vessels operating at 350-700 bar using aluminum-lined or all-composite construction. Demand concentrates in German heavy-duty trucking fleets and South Korean bus operators seeking zero-emission diesel alternatives under national hydrogen roadmaps.
- Cryogenic:Double-walled vacuum-insulated tanks maintaining minus 253 degrees Celsius for liquid hydrogen containment. Japanese port clusters and Rotterdam maritime corridors are pulling capacity expansion as ammonia-hydrogen dual-fuel vessel orders accelerate.
- Metal Hydride:Solid-state storage using intermetallic compounds to absorb hydrogen at moderate pressures. Stationary backup power installations in Japanese industrial zones favor the technology's volumetric density despite weight penalties.
- Liquid Hydrogen:High-capacity spherical or cylindrical vessels for long-duration energy storage and aerospace refueling. Export-led demand from European spaceports and California energy storage projects is driving specialized fabrication capacity.
Compressed gas holds the largest share; momentum sits with cryogenic systems as liquefaction costs decline and maritime applications multiply.
Application:
Transport applications command premium pricing tiers due to cycling durability requirements, while energy storage contracts favor volume-scale procurement with extended service agreements.
- Transport:Onboard vehicle tanks for fuel cell trucks, buses, and trains requiring 15,000-cycle certification under EU Pressure Equipment Directive. Fleet operators in California and Germany are consolidating procurement under long-term leasing models.
- Fuel Cells:Stationary and portable power systems using metal hydride or compressed gas tanks. Japanese residential cogeneration installations and South Korean backup power deployments anchor regional demand.
- Energy Storage:Grid-scale liquid hydrogen and cryogenic systems for seasonal electricity arbitrage. German renewable energy clusters and Japanese offshore wind projects are piloting long-duration configurations.
- Industrial Use:Refinery hydrogen supply and chemical process feedstock storage. German Ruhr industrial corridor and US Gulf Coast petrochemical complexes maintain established compressed gas infrastructure.
Transport commands the dominant revenue pool; energy storage is climbing fastest as grid-scale demonstration projects reach commercial scale.
End User:
Automotive qualification timelines stretch 24-36 months, compressing supplier margins, while power generation and industrial sectors accept faster certification cycles with lower performance thresholds.
- Automotive:OEM tank integration for passenger vehicles and commercial trucks requiring 700 bar Type IV or Type V composite vessels. German and Japanese automakers are qualifying robotic filament winding suppliers for lightweight 700 bar designs.
- Aerospace:Liquid hydrogen tanks for satellite launch vehicles and emerging hydrogen aircraft programs. Japanese space agency contracts and European aviation consortiums are funding specialized cryogenic fabrication.
- Power Generation:Stationary fuel cell and gas turbine blending applications. South Korean utility procurement and German industrial park microgrids are expanding metal hydride and compressed gas deployments.
- Industrial Sectors:Steelmaking, ammonia synthesis, and semiconductor manufacturing hydrogen supply. German chemical clusters and Japanese electronics fabrication maintain captive tank fleets with aluminum-lined cylinder preferences.
Automotive absorbs the highest unit margins; aerospace is gaining share fastest as hydrogen propulsion programs advance beyond demonstration.
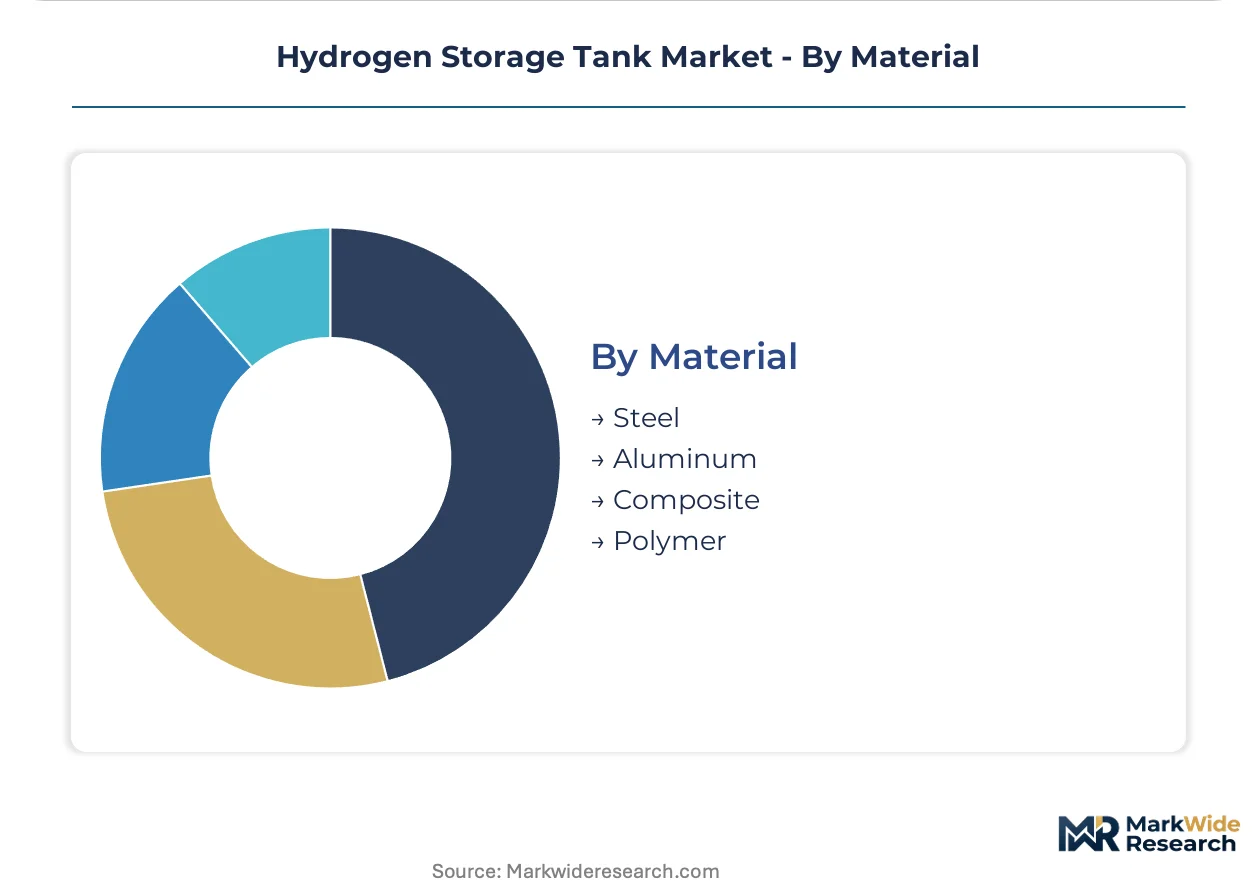
Material:
Composite materials concentrate in high-value automotive and aerospace segments where gravimetric efficiency determines competitive qualification, while steel and aluminum serve cost-sensitive industrial applications with established supply chains.
- Composite:Carbon fiber filament-wound pressure vessels achieving maximum weight reduction for 700 bar automotive tanks. Japanese and South Korean carbon fiber precursor supply concentration creates single-source exposure for lightweight vessel producers.
- Aluminum:Lined cylinders balancing cost and weight for industrial gas distribution. Volatility in high-purity aluminum alloy pricing compresses margins for manufacturers serving German and US merchant gas markets.
- Steel:Traditional seamless steel cylinders for stationary and lower-pressure applications. North American manufacturing scale anchored by established steel cylinder expertise serves compressed gas infrastructure buildout.
- Polymer:Liner materials and external protective layers in Type IV and Type V vessel construction. Specialized polymer formulations from German and Japanese chemical suppliers enable cycling durability improvements.
Composite captures the premium tier; aluminum maintains the broadest installed base across industrial gas applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tank fabricators export compressed gas systems to California fleet operators under long-term service agreements, while Japanese cryogenic specialists supply Rotterdam maritime corridors with liquid hydrogen infrastructure for dual-fuel vessel conversions.
Germany
Ruhr industrial corridor demand for refinery hydrogen storage and heavy-duty trucking fleet procurement anchor domestic tank consumption. The EU F-Gas Regulation and Pressure Equipment Directive compress supplier qualification timelines for 700 bar automotive certification. Bavarian automotive OEMs in Munich-Stuttgart corridor are qualifying robotic filament winding suppliers for lightweight vessel production.
Japan
Tokyo Bay and Osaka hydrogen hub procurement drives demand for METI-certified cryogenic and metal hydride systems. METI hydrogen safety standards create compliance layers that position early-aligned suppliers for preferential port cluster access. Chubu-Nagoya industrial zones favor metal hydride stationary backup installations despite weight penalties.
South Korea
Busan-Ulsan port complexes and national hydrogen roadmaps prioritize infrastructure buildout for fuel cell bus and heavy-duty truck operators. KGS codes add certification requirements parallel to EU and US protocols, fragmenting engineering resources for market entrants. Seoul Capital Area fleet operators are consolidating procurement under bundled tank leasing and hydrogen supply agreements.
United States
California heavy-duty fleet operators and IRA hydrogen production tax credits pull infrastructure investment toward domestic compressed gas manufacturing scale-up. DOT certification protocols diverge from EU PED requirements, compelling parallel testing regimes. Texas Gulf Coast petrochemical complexes maintain captive aluminum-lined cylinder fleets for refinery hydrogen distribution.
Netherlands
Rotterdam maritime corridors generate demand for high-capacity cryogenic storage as ammonia-hydrogen dual-fuel vessel orders accelerate. EU Green Deal frameworks and F-Gas Regulation embodied carbon reporting tighten import requirements for pressure equipment. Randstad port clusters are piloting long-duration liquid hydrogen configurations for seasonal energy arbitrage.
Hydrogen Storage Tank Market Key Industry Players
Player mix skews toward diversified industrial gas conglomerates with captive cylinder expertise and specialized composite vessel designers serving automotive qualification timelines. Market structure concentrates around three strategic archetypes: steel cylinder specialists leveraging legacy manufacturing scale, composite filament winding innovators pursuing gravimetric efficiency, and aluminum-lined cylinder producers balancing cost-weight tradeoffs for industrial distribution. Dominant competitive moves include backward integration into carbon fiber precursor supply and geographic expansion through port cluster joint ventures.
Among North American fabricators, Worthington Industries occupies a position exemplifying steel cylinder manufacturing scale, while Luxfer Group represents the aluminum-lined archetype for industrial gas applications. Hexagon Composites anchors the lightweight composite vessel tier alongside its subsidiary Hexagon Purus. These three entities collectively illustrate the technology-material segmentation that defines competitive positioning across mobility and stationary storage applications.
| Leading Market Players |
|---|
| Worthington Industries |
| Luxfer Group |
| Hexagon Composites |
| Hexagon Purus |
| NPROXX |
| Quantum Fuel Systems LLC |
| Faber Industrie |
| Everest Kanto Cylinders Ltd. |
| Air Liquide |
| Others |
Cost & Logistics Intelligence
Long-term service agreements bundling tank leasing, maintenance, and hydrogen supply lock in supply access for California and Rotterdam fleet operators while compressing price visibility for discrete equipment purchases. The contract structure displaces spot procurement in heavy-duty transport corridors and anchors pricing power with energy majors holding tank asset ownership.
Pricing Analysis
The technology-generation pricing gap between Type III aluminum-lined cylinders, Type IV composite vessels, and emerging Type V all-composite designs stratifies procurement tiers across automotive and industrial segments. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified cryogenic systems from EU PED-compliant compressed gas tanks and uncertified steel cylinders for stationary applications. Cost compression in aluminum-lined cylinder manufacturing is intensifying because high-purity alloy input volatility erodes margins for industrial gas distributors. Automotive OEMs demonstrate lowest price sensitivity due to 700 bar certification requirements, while merchant gas buyers in refinery supply chains exhibit highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Carbon fiber precursor supply concentration in Japan and South Korea creates single-source vulnerability for lightweight vessel producers serving German and North American automotive qualification programs. The hydrogen storage tank supply chain draws from Toray and Toho Tenax filament winding feedstock, high-purity aluminum smelting in Norway and Canada, and specialized polymer liner formulations from German chemical suppliers. Tariff exposure on carbon fiber imports fragments engineering resources for EU and US fabricators seeking alternative precursor sources. Distribution runs through port cluster joint ventures in Rotterdam, Tokyo Bay, and Busan-Ulsan corridors where cryogenic infrastructure bundling captures downstream value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application requirements across mobility, stationary power, and maritime propulsion fragment demand into incompatible design optima, creating specialist niches for targeted positioning. The divergence between 700 bar automotive cycling durability and cryogenic long-duration storage specifications prevents universal supplier dominance.
For Market Incumbents: Shield composite filament winding expertise through backward integration into carbon fiber precursor supply, securing captive access against Japanese and South Korean supply concentration. Accelerate robotic winding capacity additions in Germany and South Korea to compress labor cost differentials with emerging manufacturing bases. Invest in parallel EU PED and US DOT certification testing to maintain qualification timelines as regulatory divergence fragments engineering budgets.
For New Entrants and Emerging Players: Tank leasing and maintenance service layers represent under-served white space where energy majors capture asset ownership while fleet operators focus on route economics. Maritime cryogenic applications in Rotterdam and Japanese port clusters offer the most penetrable entry point given specialized fabrication requirements and limited incumbent capacity. Pursue joint venture structures with port authorities to secure offtake visibility before committing to high-capacity spherical vessel fabrication.
For Investors and Strategic Acquirers: Composite vessel designers with robotic winding capabilities and active automotive OEM qualification programs represent the most defensible acquisition archetype for long-term hydrogen infrastructure exposure. Monitor EU F-Gas Regulation embodied carbon reporting enforcement as the inflection indicator for supplier qualification hierarchy reshuffling, with early-aligned carbon-footprint-qualified tank designs gaining preferential procurement access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Captive supply from Toray or Toho Tenax secures filament winding feedstock against Japanese concentration risk. |
| Robotic Filament Winding Capacity Expansion | Automotive OEMs in Munich-Stuttgart corridor qualify suppliers with automated 700 bar vessel production. |
| Parallel Certification Testing Investment | Dual EU PED and US DOT qualification compresses product development timelines for cross-border market access. |
| Port Cluster Joint Venture Formation | Rotterdam and Tokyo Bay partnerships capture cryogenic infrastructure bundling in maritime propulsion corridors. |
| Embodied Carbon Reporting Compliance | German and French certification bodies process first wave of carbon-footprint-qualified tank designs under EU F-Gas Regulation. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with tank procurement managers at German heavy-duty fleet operators, composite vessel engineering directors, and EU certification body technical assessors; and secondary validation through US DOT certification databases, EU Pressure Equipment Directive filings, and Japanese METI hydrogen safety standard documentation. Bottom-up triangulation across technology-material segmentation and top-down cross-check against national hydrogen roadmap infrastructure targets anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by storage technology, application cycling requirements, end-user qualification timelines, and material cost structures. CAGRs were derived from infrastructure deployment schedules in Germany, Japan, and South Korea national hydrogen roadmaps, cross-referenced against fleet operator procurement consolidation patterns and maritime dual-fuel vessel order pipelines. Input assumptions incorporated liquefaction cost decline curves for cryogenic systems and carbon fiber precursor supply elasticity constraints.
Underlying assumptions cover regulatory certification timeline stability and aluminum alloy pricing mean reversion, with deviation risk concentrated in EU-US regulatory convergence pace and East Asian carbon fiber export restriction scenarios. Practitioners should keep alternative scenarios live as embodied carbon threshold enforcement and tank recycling protocol finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Powered Engine Market