
 Norway Oil and Gas Downstream Market | 2026-2036
Norway Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Oil and Gas Downstream Market Analytics
A shift from single-source crude procurement toward diversified multi-source supply chains is pivoting Norwegian downstream operations toward greater feedstock flexibility. Equinor ASA leverages its integrated North Sea production and refining assets to secure captive crude supplies. Shell PLC anchors its Norwegian position through advanced hydrocracking capacity at the Porsgrunn complex. Aker BP ASA specializes in upstream-to-midstream coordination rather than direct refining exposure.
Norway oil and gas downstream encompasses refining, petrochemical conversion, lubricant blending, and fuel distribution infrastructure processing North Sea crude into transport fuels, heating oils, and chemical feedstocks with typical refinery complexity indices ranging from 6.5 to 9.2. The sector's primary purpose centers on converting raw hydrocarbons into finished products for domestic consumption and export to Northwest European markets. Refined Products occupies the dominant revenue position given gasoline and diesel demand from the automotive sector, while Petrochemicals represents the fastest-expanding margin pool as ethylene and propylene derivatives feed Norwegian plastics manufacturing. Lubricants and Additives together constitute a mature, high-margin niche serving offshore drilling equipment and maritime engines operating under extreme North Sea conditions.
The Petroleum Safety Authority Norway and the Norwegian Environment Agency jointly enforce offshore and onshore facility standards, while EU REACH and the EU Green Deal impose product composition and carbon border requirements on exported fuels. Norwegian regulations now mandate progressive electrification of refinery process heat, directly altering capital allocation toward grid-connected upgrades. Stakeholders must monitor how carbon border adjustment mechanisms reshape the competitiveness of Norwegian refined products against Middle Eastern and Russian supply alternatives.
Market Dynamics
The Norwegian downstream sector faces structural pressure from the Petroleum Safety Authority Norway's progressive electrification mandates for refinery process heat, forcing capital reallocation toward grid-connected infrastructure upgrades at coastal processing facilities.
Growth Catalysts
- EU Green Deal carbon border adjustments:Norwegian refineries with lower carbon intensity than Middle Eastern and Russian competitors gain relative advantage in Northwest European export markets.
- North Sea shipping lane bunkering:Stricter International Maritime Organization sulfur caps concentrate compliant marine fuel demand around Mongstad and Porsgrunn supply points.
- Electrification of process heat:Grid-connected upgrades unlock operational cost efficiencies while positioning facilities for future hydrogen integration.
Market Restraints
- Crude supply concentration:Heavy dependence on North Sea Brent and Johan Sverdrup grades limits feedstock flexibility during regional production outages.
- Electrification capex burden:Grid connection upgrades at Mongstad and Slagen require substantial capital commitment without immediate margin recovery.
- EU REACH compliance friction:Petrochemical exporters face extended registration timelines and testing costs for novel chemical derivatives.
Strategic Opportunities
- Barents Sea frontier development:Goliat and Snøhvit field expansions could anchor new Arctic refining capacity serving polar shipping routes.
- Blue hydrogen production integration:Carbon capture-equipped reformers at existing sites can supply ammonia and synthetic fuel feedstocks.
- Advanced recycling feedstocks:Chemical recycling of plastic waste into naphtha crackers addresses EU circular economy mandates.
Industry Challenges
- Process control engineering scarcity:Specialized expertise in refinery electrification and carbon capture integration commands premium compensation in the Oslo-Stavanger corridor.
- Legacy distributed control system migration:Decades-old automation infrastructure at Slagen and Mongstad complicates digital twin implementation and predictive maintenance deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Oil and Gas Downstream Market |
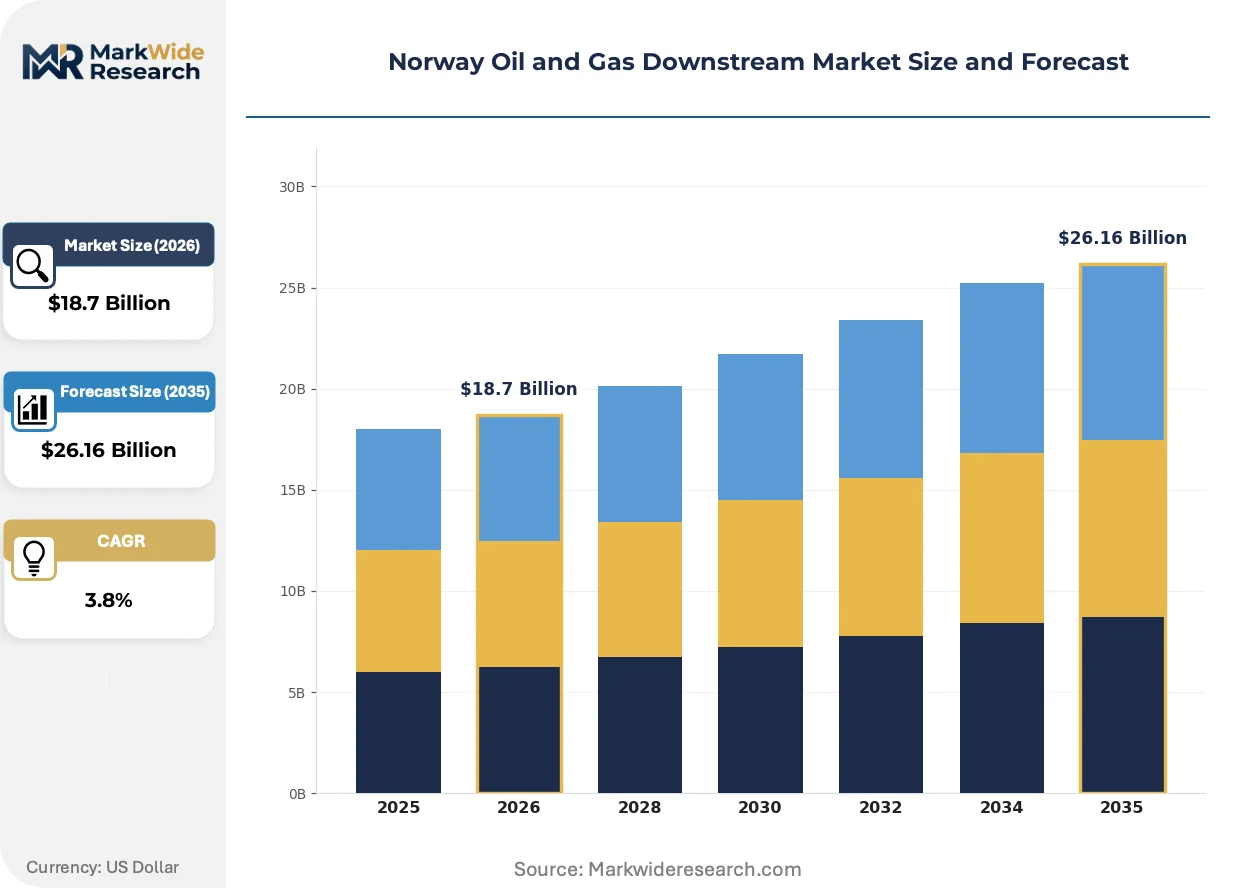
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Products, Petrochemicals, Lubricants, Additives Application: Transportation, Industrial Use, Residential Heating, Power Generation Delivery Mode: Pipelines, Tankers, Rail, Trucking End User: Refineries, Power Plants, Automotive Sector, Manufacturing |
| Companies Covered | Equinor ASA, Shell PLC, ExxonMobil, TotalEnergies, Aker BP ASA, Lundin Energy Norway, Wintershall Dea, ConocoPhillips, Vår Energi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Oil and Gas Downstream Market Evolving Landscape
Digitalization and decarbonization technologies are restructuring Norwegian downstream operations, with automation investments accelerating alongside carbon capture pilot programs at major processing complexes.
Advanced process control systems incorporating artificial intelligence is converging with traditional refinery unit operations to optimize yield structures across hydrocracking and catalytic reforming trains. Equinor and Shell operators at Mongstad and Porsgrunn are deploying these platforms for real-time energy management. This convergence is compressing the timeline between laboratory catalyst testing and commercial unit deployment.
The Petroleum Safety Authority Norway and Norwegian Environment Agency have jointly mandated progressive electrification of fired heaters and steam boilers, with compliance deadlines structured around facility turnaround cycles. This regulatory framework is accelerating partnerships between refiners and Statnett for grid reinforcement. Coastal processing units face the most severe retrofit requirements given their marine terminal integration.
Buyer consolidation among Northwest European marine fuel purchasers is compressing contracting cycles and unbundling traditional supply agreements into spot-indexed and formula-priced components. Trading houses in Rotterdam and Hamburg are displacing integrated oil company intermediaries in Norwegian bunker fuel offtake. This pattern is most pronounced in very low sulfur fuel oil procurement for container vessels transiting the English Channel.
Norway Oil and Gas Downstream Market Segmentation
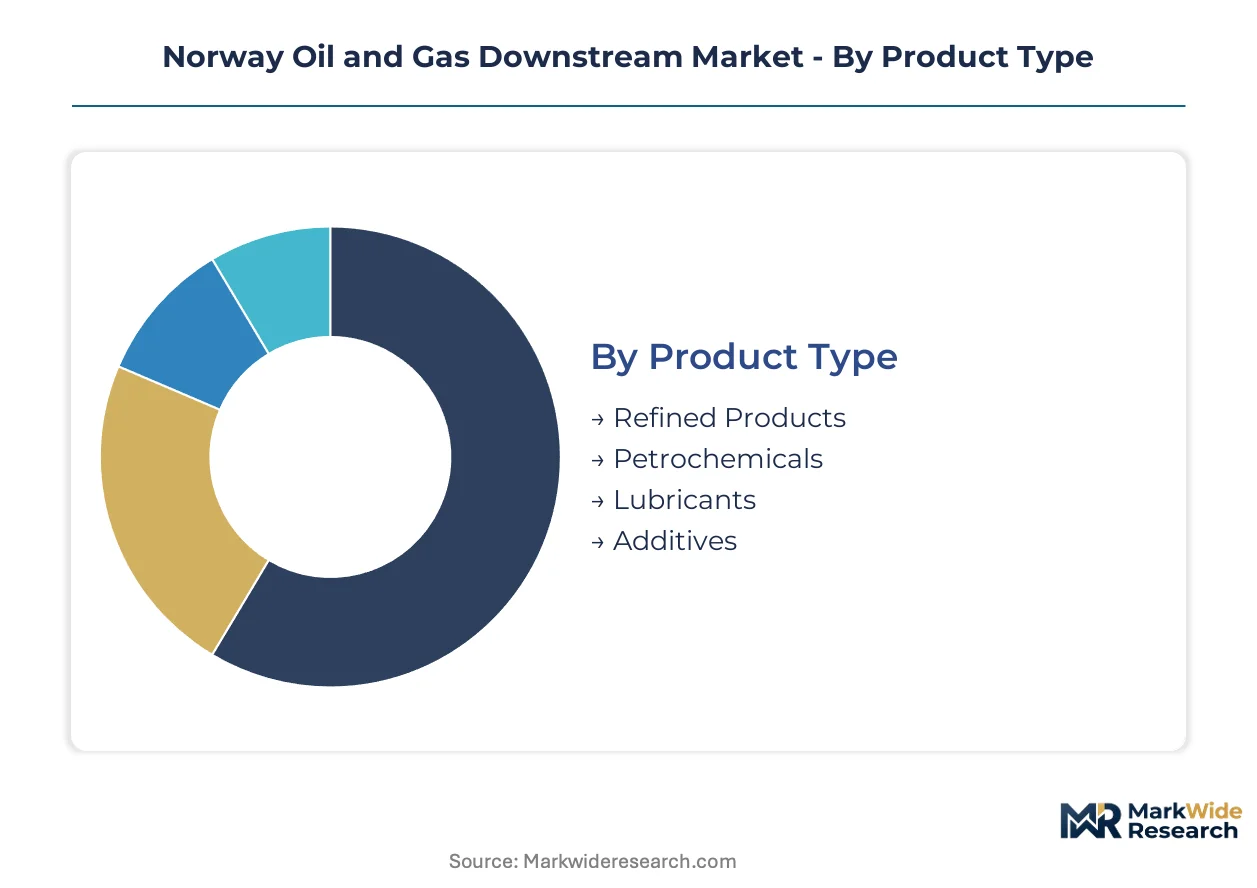
Segmentation in the Norwegian downstream sector reveals how regulatory pressure and infrastructure constraints reshape procurement patterns. Each dimension exposes different vulnerability points to electrification mandates and carbon border adjustments.
Product Type:
EU REACH registration requirements and carbon intensity benchmarks from the Norwegian Environment Agency create divergent compliance burdens across product categories.
- Refined Products:Gasoline, diesel, and marine fuels processed through hydrocracking and catalytic reforming units at Mongstad and Porsgrunn. Norwegian refineries supply bunker fuels to North Sea shipping lanes facing tightening International Maritime Organization sulfur caps.
- Petrochemicals:Ethylene, propylene, and aromatics derived from naphtha cracking feed conversion into plastics and synthetic materials. Demand concentrates around Mongstad's associated petrochemical processing units serving domestic manufacturing.
- Lubricants:High-viscosity base oils and formulated products for offshore drilling equipment and maritime engines.
- Additives:Detergents, dispersants, and viscosity modifiers blended to meet equipment-specific performance specifications.
Leading the category by volume: Refined Products. Growing fastest: Petrochemicals.
Application:
End-use concentration determines exposure to electrification displacement and import competition from lower-carbon European supply.
- Transportation:Road fuels, marine bunkers, and aviation kerosene distributed through coastal terminals and inland depots. Automotive sector demand from Oslo-Stavanger corridor drives gasoline and diesel offtake patterns.
- Industrial Use:Process heat, feedstocks, and motive power for chemical manufacturing and metal processing. Coastal industrial clusters near Mongstad concentrate petrochemical and lubricant consumption.
- Residential Heating:Distillate fuels and liquefied petroleum gas for building climate control in rural municipalities.
- Power Generation:Heavy fuel oil and diesel for peak-load and backup electricity production in islanded grid zones.
Transportation commands the largest volume share. Industrial Use faces the steepest regulatory pressure.
Delivery Mode:
Infrastructure ownership structures and Statnett grid access constraints shape cost differentials between transport methods.
- Pipelines:Fixed infrastructure connecting Mongstad and Slagen to marine terminals and inland storage facilities.
- Tankers:Coastal and short-sea vessels moving refined products to Northwest European export markets.
- Rail:Bulk liquid transport from coastal refineries to inland distribution terminals.
- Trucking:Final-mile delivery to retail stations and industrial offtake points across southern Norway.
Tankers dominate export volumes. Pipelines face the heaviest electrification retrofit requirements.
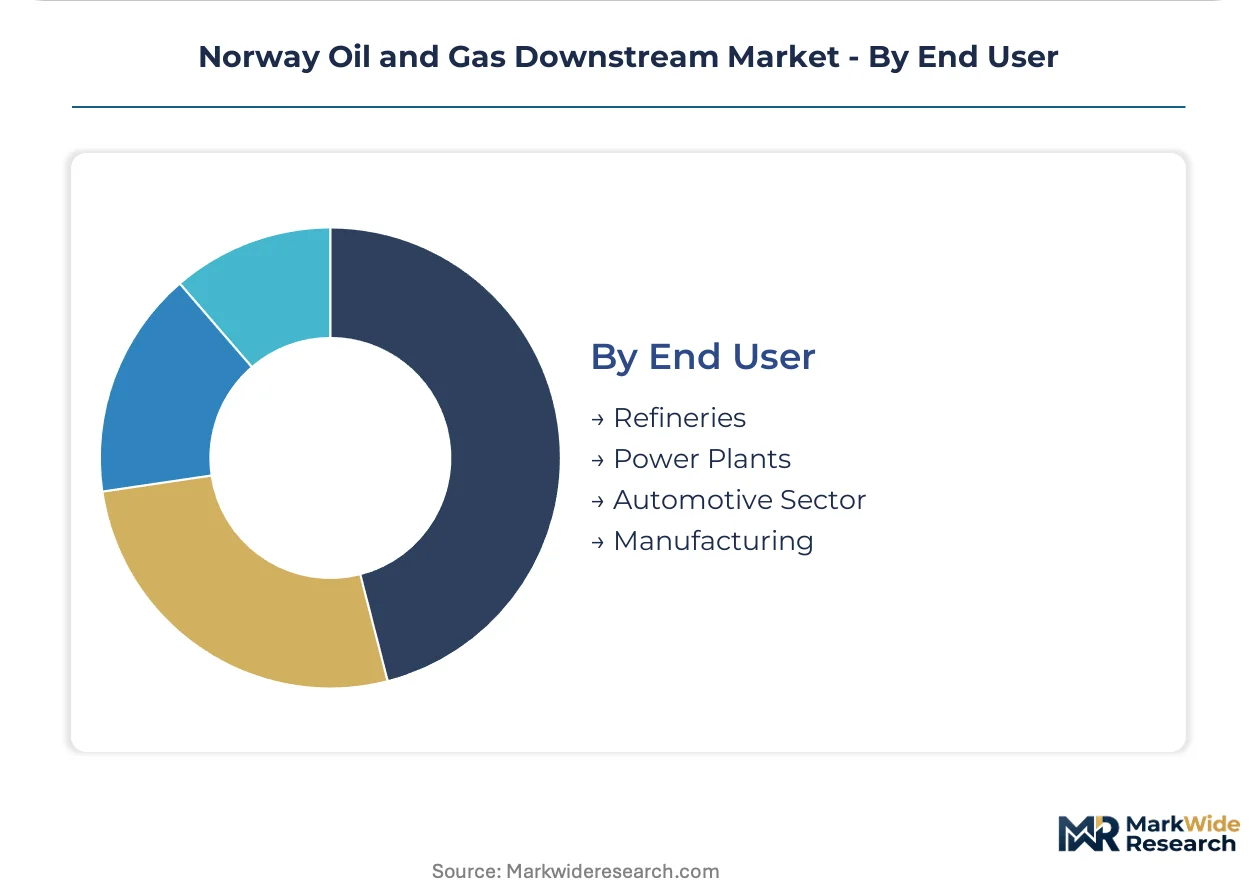
End User:
Customer scale and integration level determine contracting sophistication and price indexation terms.
- Refineries:Inter-facility transfers and tolling arrangements between Mongstad, Slagen, and Porsgrunn processing complexes.
- Power Plants:Distillate and residual fuel purchasers facing displacement by hydroelectric and wind generation expansion.
- Automotive Sector:Retail fuel networks and fleet operators sourcing through integrated oil company supply agreements.
- Manufacturing:Chemical processors and metal fabricators procuring naphtha, LPG, and specialty feedstocks.
Refineries transact the largest inter-facility volumes. Manufacturing shows the most rapid demand shift toward lower-carbon alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea crude production from the Johan Sverdrup and Ekofisk fields anchors Norwegian downstream operations, with coastal refineries at Mongstad and Porsgrunn processing these grades for Northwest European distribution.
Oslo-Stavanger Corridor
Automotive fuel demand and offshore equipment servicing drive refined product consumption along this southern axis. The Norwegian Environment Agency enforces coastal facility carbon intensity benchmarks that compress operating margins for older installations. Mongstad refinery complex and its petrochemical processing units concentrate Norway's highest downstream throughput capacity.
Vestlandet
Marine bunkering for North Sea shipping lanes and industrial process heat requirements sustain heavy fuel oil offtake from regional storage terminals. Petroleum Safety Authority Norway mandates progressive electrification of refinery fired heaters with compliance tied to facility turnaround schedules. Bergen and surrounding port infrastructure anchor coastal distribution networks for compliant very low sulfur fuel oil.
Trøndelag
Power generation backup demand and rural heating fuel requirements sustain distillate consumption in islanded grid zones. Statnett grid reinforcement partnerships with coastal processors unlock electrification pathways for steam boiler retrofits. Trondheim industrial cluster faces steepest displacement risk from hydroelectric and offshore wind expansion.
Northern Norway
Barents Sea frontier development at Goliat and Snøhvit fields could anchor new Arctic refining capacity serving polar shipping routes. The country's national petroleum regulator coordinates safety standards for expanded northern operations. Hammerfest and Finnmark sub-regions concentrate liquefied natural gas export infrastructure with potential for ammonia and synthetic fuel integration.
Sørlandet
Slagen refinery operations and associated product distribution sustain regional employment and supply chain activity. Grid connection upgrades at coastal processing facilities require substantial capital commitment without immediate margin recovery. Kristiansand port infrastructure handles intermediate feedstock imports and refined product exports to Northwest European markets.
Norway Oil and Gas Downstream Market Competitive Landscape
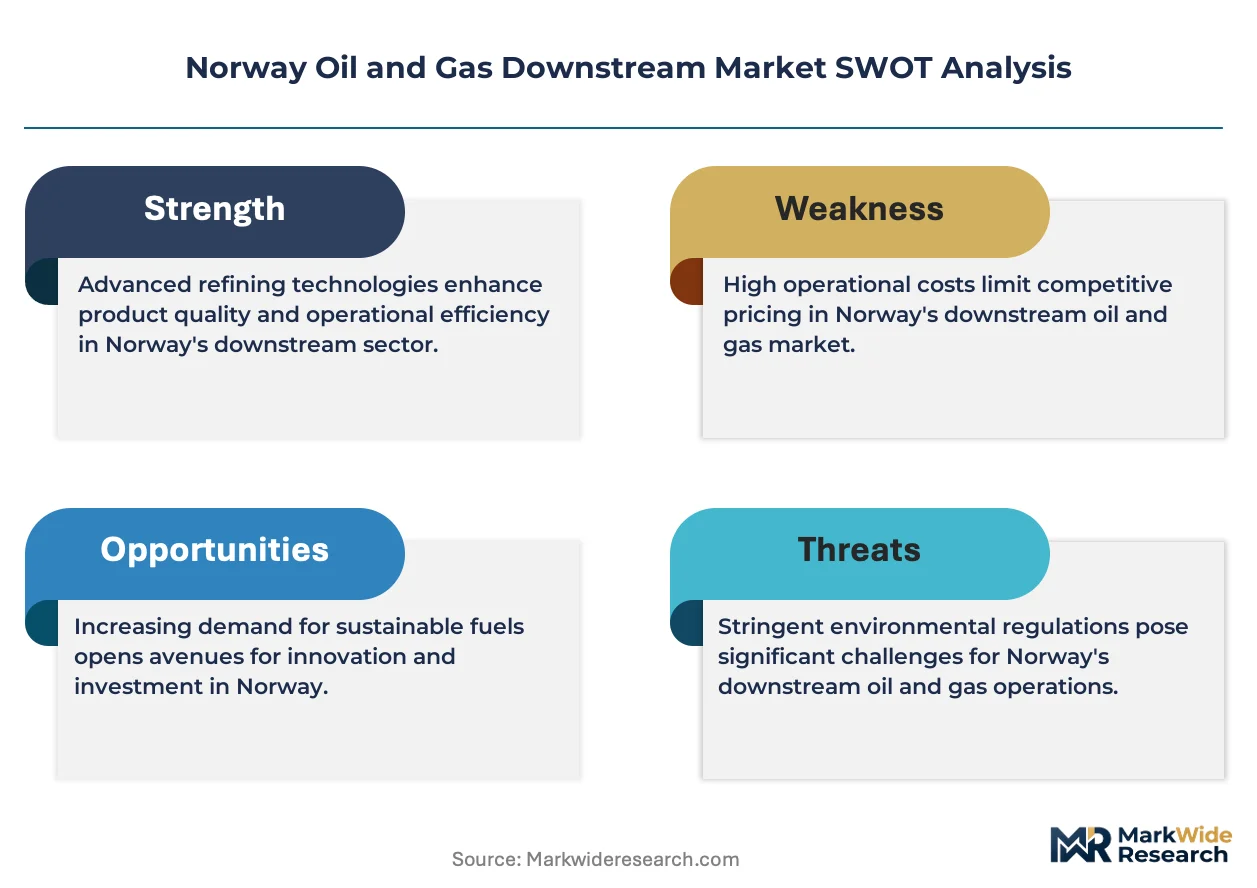
Global majors compete with regional champions across integrated production and refining assets, yielding a consolidated structure where international oil companies hold dominant capacity shares alongside specialized Norwegian upstream operators. The competitive terrain divides between fully integrated majors with captive crude supplies, regional specialists coordinating upstream-to-midstream logistics, and trading houses displacing traditional intermediaries in marine fuel offtake. Dominant competitive moves include strategic partnerships for grid-connected electrification upgrades and portfolio diversification toward hydrogen and carbon capture integration.
Within the integrated major tier, Equinor ASA and Shell PLC exemplify contrasting strategic positions. Equinor ASA represents the state-affiliated archetype leveraging North Sea production assets for captive refinery feedstock security. Shell PLC anchors international portfolio exposure through advanced hydrocracking capacity. Aker BP ASA occupies a distinct position as a regional specialist emphasizing upstream-to-midstream coordination rather than direct refining operations.
| Leading Market Players |
|---|
| Equinor ASA |
| Shell PLC |
| ExxonMobil |
| TotalEnergies |
| Aker BP ASA |
| Lundin Energy Norway |
| Wintershall Dea |
| ConocoPhillips |
| Vår Energi |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers like Equinor ASA anchor Norwegian downstream pricing discipline through captive North Sea crude supplies, compressing third-party feedstock arbitrage and reinforcing long-term offtake contract premiums at Mongstad and Porsgrunn.
Pricing Analysis
Long-term service and logistics bundling with marine fuel delivery separates spot-indexed bunker contracts from formula-priced supply agreements with integrated shipping operators. Three-tier pricing structure across premium low-carbon marine fuels, standard very low sulfur fuel oil, and economy high-sulfur residual grades tracks International Maritime Organization compliance tiers. Cost compression in standard-tier products is intensifying because Rotterdam trading houses displace traditional oil company intermediaries. Smaller coastal distributors show highest price sensitivity; integrated container lines with dedicated berth access show least.
Supply Chain Analysis
Empty tanker backhauls and product tank cleaning cycles create reverse-logistics value recovery through fuel-grade blending and slop reprocessing at coastal terminals. Supply concentrates in Norway, Netherlands, and Germany for Northwest European marine fuel distribution. Raw material dependencies include North Sea Brent and Johan Sverdrup crude grades, catalytic reformer catalysts, and hydrocracking hydrogen feedstocks. Single-source vulnerability runs through Statnett grid interconnections powering electrification retrofits. Distribution runs through coastal marine terminals with pipeline links to inland storage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid-connected electrification capex at Mongstad and Slagen functions as the binding capacity constraint, insulating incumbent margins from import competition while elevating break-even thresholds for marginal supply sources.
For Market Incumbents: To counter trading house disintermediation in marine fuel offtake, secure exclusive berth access agreements with container lines transiting the English Channel. Backward integration into Barents Sea production through Goliat and Snøhvit field equity stakes secures feedstock optionality for Arctic refining expansion. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Northwest Europe open a window for low-carbon hydrogen and ammonia supply to coastal industrial clusters. Target chemical recycling feedstock partnerships with Mongstad petrochemical processors as the most penetrable entry point. Lead with carbon intensity certification as the go-to-market differentiator against Middle Eastern and Russian supply alternatives. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale lubricant blenders with offshore equipment servicing contracts in the Oslo-Stavanger corridor. Five-to-ten year viability hinges on electrification cost pass-through to industrial offtakers. Monitor Petroleum Safety Authority Norway enforcement intensity for early signals of regulatory arbitrage closure.| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Retrofit Partnership | Statnett grid reinforcement agreements unlock process heat decarbonization at Mongstad and Porsgrunn. |
| Blue Hydrogen Integration | Carbon capture-equipped reformers supply ammonia feedstocks for maritime fuel blending at Hammerfest. |
| Chemical Recycling Feedstock Supply | Plastic waste pyrolysis naphtha addresses EU circular economy mandates for Mongstad crackers. |
| Arctic Refining Capacity Buildout | Goliat and Snøhvit expansions anchor polar shipping route marine fuel supply points. |
| Digital Twin Implementation | AI-enabled process control optimizes hydrocracking yields across Equinor and Shell operations. |
Research Methodology
Independent corroboration across refinery operations executives, marine fuel procurement managers, and Statnett grid planning officers underwrites the qualitative findings. Primary fieldwork with Petroleum Safety Authority Norway compliance officers, petrochemical process engineers, and coastal terminal operators combined with secondary validation from Norwegian Environment Agency emissions disclosures, EU ETS registry data, and customs trade statistics. Bottom-up facility capacity assessments and top-down Northwest European demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation dimensions include product type, application, delivery mode, and end user, with additional modeling of refinery complexity tier and carbon intensity band. CAGRs derive from facility-level throughput projections weighted by marginal cost position. Forecast inputs incorporate Johan Sverdrup production decline curves and International Maritime Organization sulfur cap phase-in schedules.
The model assumes a particular technology adoption path; alternative pathways for electrification versus hydrogen fuel switching would alter the outlook. Forecasts reflect assumptions around Statnett grid reinforcement timelines and EU carbon border adjustment implementation scope. Practitioners should monitor Barents Sea exploration licensing rounds and Northwest European marine fuel buyer consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Global Offshore Oil and Gas Seismic Equipment and Acquisitions Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Netherlands Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Offshore Drilling Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Canada Oil and Gas Downstream Market
Offshore Oil and Gas
Kazakhstan Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market