
 Hydrogen Powered Engine Market | 2026-2036
Hydrogen Powered Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Powered Engine Market Analysis
The gap between premium fuel-cell systems and commodity hydrogen combustion engines is recalibrating competitive investment across the sector. Toyota Motor Corporation leverages its decades of fuel-cell stack development to sustain technology leadership in passenger and commercial vehicle integration. Cummins Inc. anchors the North American heavy-duty segment through dedicated hydrogen internal-combustion engine platforms. MAN competes aggressively in European long-haul trucking by integrating hydrogen combustion into existing diesel architecture, reducing OEM switching costs.
A hydrogen powered engine converts hydrogen fuel into mechanical work through either electrochemical reaction in fuel cells or controlled combustion in modified thermal engines, with fuel-cell variants achieving thermal efficiencies above 60% and combustion variants retaining conventional drivetrain compatibility. Its primary industrial purpose centers on decarbonizing transportation and stationary power where battery-electric solutions face weight, range, or refueling-time constraints. Fuel cells dominate premium automotive applications where zero-emission certification unlocks regulatory access, while combustion engines capture cost-sensitive segments through manufacturing continuity with existing engine plants. Hybrid Systems represent the fastest-growing configuration as marine and aerospace operators seek redundancy across dual-fuel architectures.
The EU's Alternative Fuels Infrastructure Regulation and Japan's METI hydrogen supply chain targets are tightening emission thresholds while funding refueling corridors that determine market-access geography for engine OEMs. The EPA and California Air Resources Board in the United States are aligning heavy-duty engine standards with hydrogen eligibility in zero-emission vehicle credit frameworks. Stakeholders must monitor which regulatory jurisdiction first mandates hydrogen-ready infrastructure at scale, as this will dictate regional production commitments and technology standardization timelines.
Market Dynamics
The EU's Alternative Fuels Infrastructure Regulation is forcing infrastructure buildout decisions faster than OEM product cycles, compressing the timeline between hydrogen corridor announcement and fleet procurement commitments.
Growth Catalysts
- Japan's METI hydrogen roadmap:National supply chain targets are accelerating refueling station deployment along the Tokaido corridor, enabling commercial vehicle trials between Tokyo and Osaka industrial zones.
- Heavy-duty trucking electrification limits:Battery weight constraints on long-haul routes are redirecting fleet procurement toward hydrogen combustion platforms that retain diesel-equivalent range and payload capacity.
- Rhine-Ruhr industrial clustering:Captive logistics networks in Germany's chemical corridor are integrating hydrogen engines into short-haul distribution, creating demand density for localized fuel production.
Market Restraints
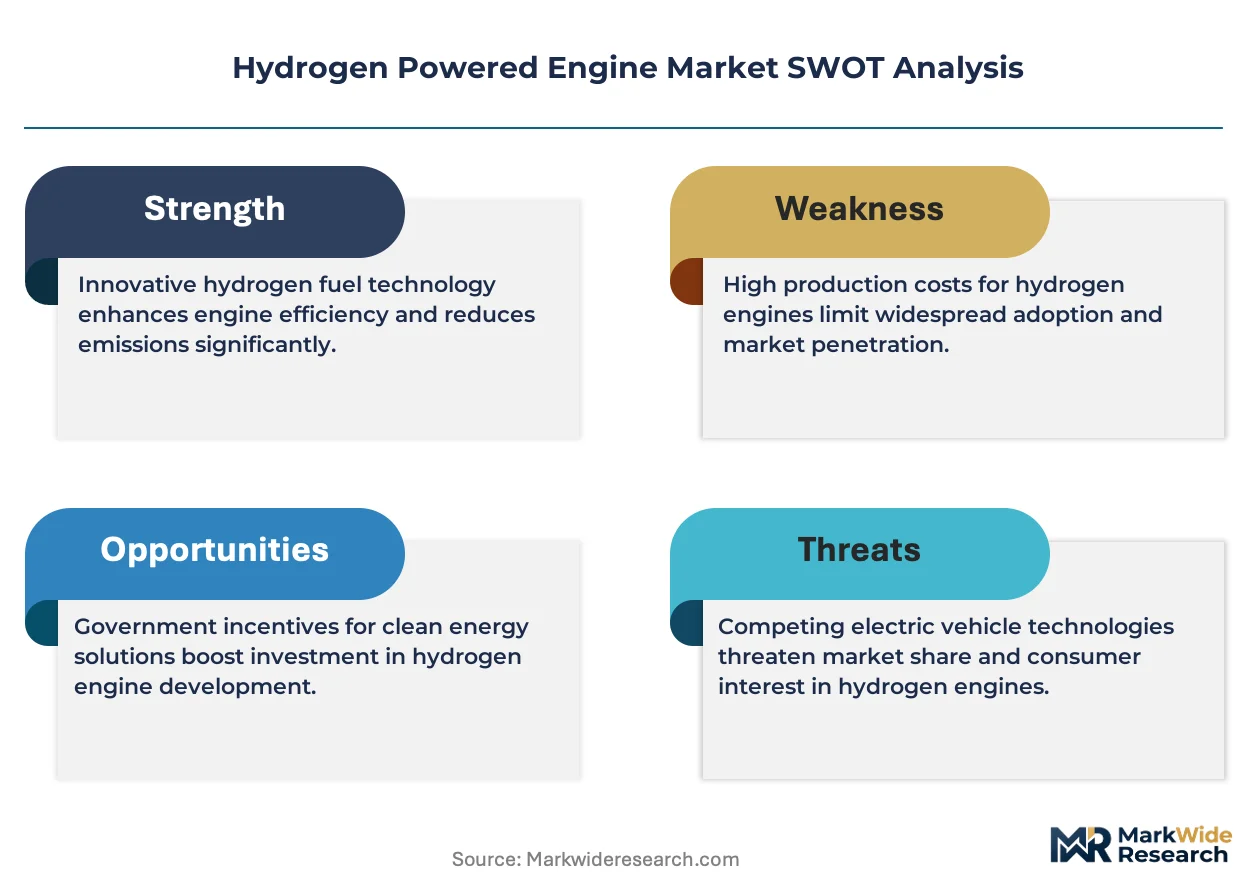
- Electrolyzer capacity concentration:Green hydrogen supply remains bottlenecked by limited European electrolyzer manufacturing, constraining fuel availability for engine deployment at scale.
- Fuel-cell stack cost structure:Platinum group metal loading in proton-exchange membrane stacks sustains premium pricing that combustion alternatives undercut by 40-60% on powertrain cost.
- California ZEV credit complexity:CARB's evolving hydrogen eligibility rules create regulatory uncertainty for fleet operators calculating total cost of ownership against battery-electric alternatives.
Strategic Opportunities
- Marine dual-fuel architectures:Hybrid hydrogen-diesel systems for coastal shipping routes offer compliance pathways under IMO 2030 emission intensity targets without full fleet replacement.
- German hydrogen core network:The government's pipeline conversion program creates geographic anchor points for stationary power applications at industrial facilities.
- Aerospace auxiliary power units:Hydrogen combustion for aircraft ground power and taxiing operations represents a certification-friendly entry point before propulsion system integration.
Industry Challenges
- Hydrogen storage system integration:Cryogenic tank packaging within existing vehicle architectures requires structural redesigns that extend engineering timelines and certification cycles.
- NOx aftert calibration:Combustion variants demand novel catalytic reduction strategies to meet Euro VII and EPA 2027 standards without urea-based systems.
- Technician retraining requirements:High-pressure fuel system maintenance protocols differ substantially from diesel or CNG, creating workforce transition friction at dealership networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Powered Engine Market |
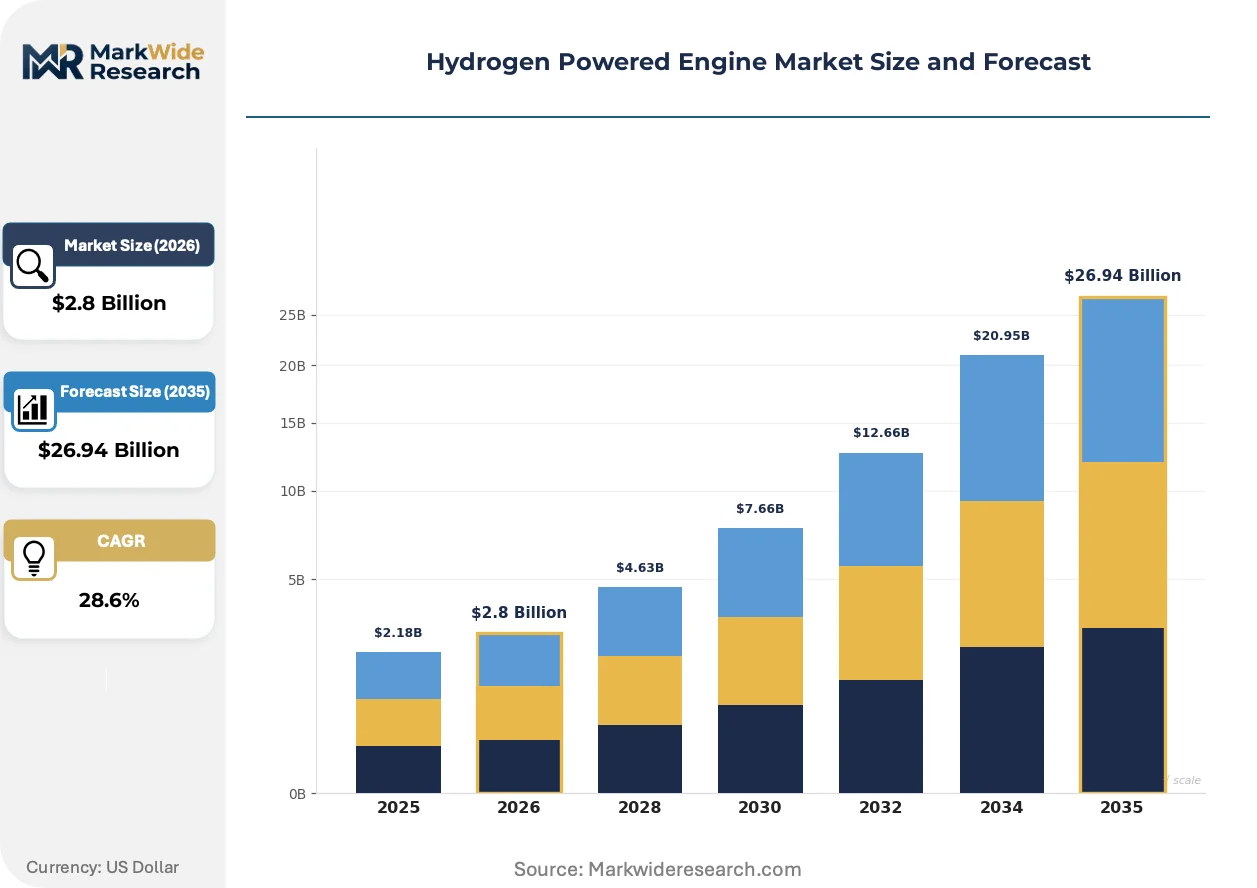
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Cells, Combustion Engines, Hybrid Systems, Turbines Application: Automotive, Aerospace, Marine, Power Generation End User: OEMs, Energy Suppliers, Transportation Companies, Industrial Users Technology: Electrolysis, Reforming, Storage Solutions, Distribution Systems |
| Companies Covered | Toyota Motor Corporation, Cummins Inc., MAN, Hyundai Motor Company, Honda Motor Corporation, BMW, J C Bamford Excavators, Ashok Leyland, HD Hyundai Infracore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Powered Engine Market Emerging Trajectories
Technology convergence between fuel-cell and combustion architectures is blurring traditional segment boundaries, with hybrid systems emerging as the dominant configuration for applications requiring operational redundancy.
Dual-fuel hydrogen-diesel injection is absorbing development resources from pure hydrogen combustion programs as marine and mining operators prioritize fuel flexibility over zero-emission certification. Wärtsilä and MAN Energy Solutions are retrofitting existing engine blocks with hydrogen admixture capabilities, compressing the payback period for vessel owners hesitant to commit to single-fuel infrastructure. This technology is absorbing capital that would otherwise flow toward battery-electric alternatives in heavy transport segments.
The EU's F-Gas Regulation is tightening restrictions on fluorinated greenhouse gases used in fuel-cell membrane manufacturing, forcing stack producers toward alternative ionomer chemistries. Industrial consequence includes extended qualification timelines for new membrane formulations. Heavy-duty trucking OEMs sourcing from European fuel-cell suppliers face compressed product launch windows as certification cycles extend.
Fleet procurement committees are consolidating vendor relationships around integrated hydrogen supply contracts rather than discrete engine purchases. Energy majors including Shell and TotalEnergies are displacing traditional equipment financiers by bundling fuel provision with powertrain leases. This behavior is most visible in German long-haul trucking, where Rhine-based chemical producers negotiate directly with infrastructure operators for captive fleet supply.
Hydrogen Powered Engine Market Segmentation
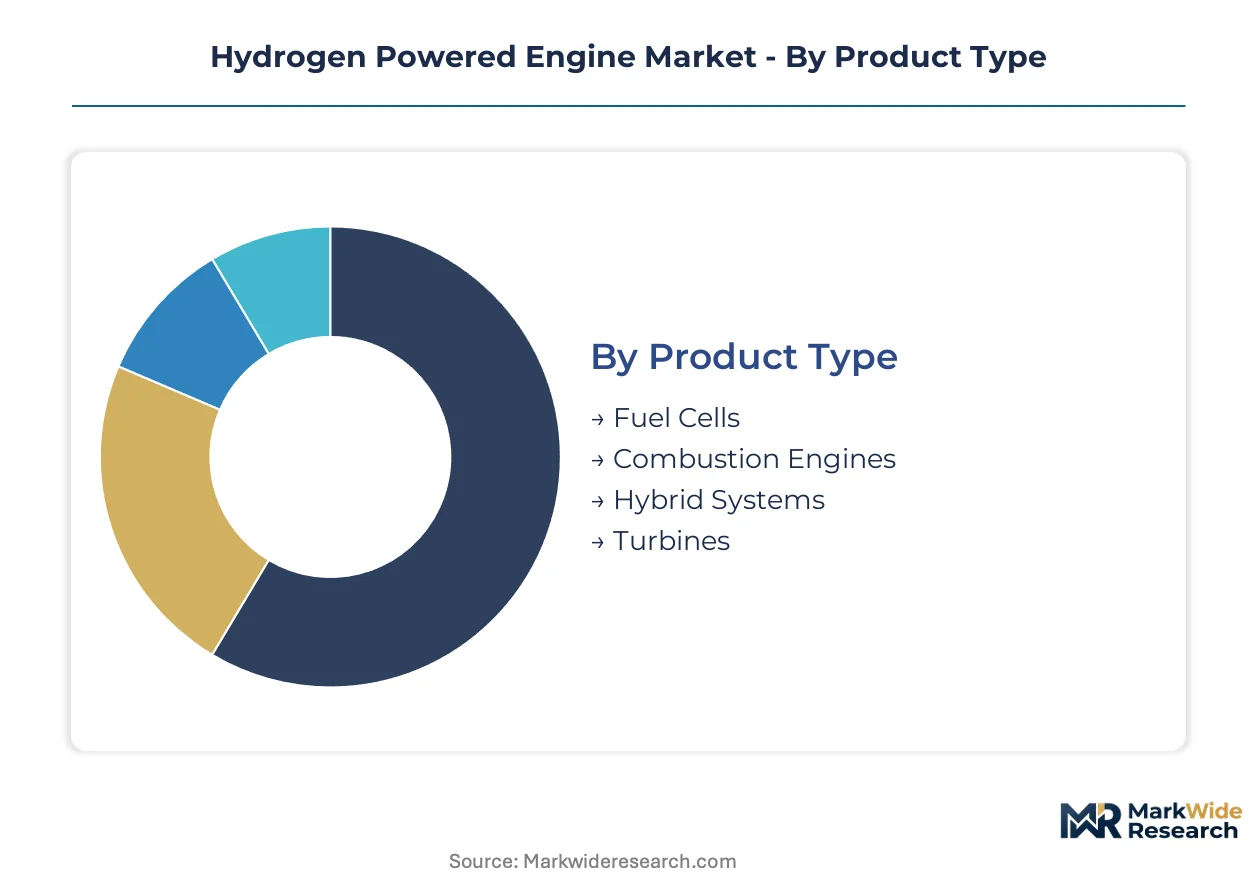
Technology divergence between electrochemical and thermal conversion pathways determines capital allocation, supply chain requirements, and regulatory compliance strategies across the hydrogen engine sector. Each segmentation axis reveals distinct competitive dynamics governing OEM procurement decisions and infrastructure investment priorities.
Product Type:
Fuel cells, combustion engines, hybrid systems, and turbines occupy differentiated positions on the cost-efficiency spectrum, with thermal efficiency targets and manufacturing continuity driving platform selection.
- Fuel Cells:Proton-exchange membrane stacks convert hydrogen electrochemically with thermal efficiencies exceeding 60%, commanding premium positioning in passenger automotive applications where zero-emission certification unlocks regulatory access. Platinum group metal loading sustains elevated powertrain costs that limit penetration in cost-sensitive commercial vehicle segments.
- Combustion Engines:Modified internal-combustion architectures retain conventional drivetrain compatibility and manufacturing continuity with existing engine plants, capturing heavy-duty trucking procurement in Germany where fleet operators prioritize diesel-equivalent range and payload capacity. MAN and Cummins anchor this segment through dedicated hydrogen combustion platforms.
- Hybrid Systems:Dual-fuel architectures combining hydrogen with diesel or ammonia deliver operational redundancy for marine and aerospace applications. Wärtsilä and MAN Energy Solutions retrofit existing engine blocks with hydrogen admixture capabilities.
- Turbines:Gas turbine derivatives adapted for pure hydrogen combustion serve stationary power generation and aviation propulsion research programs. Siemens Energy and GE Vernova lead development for utility-scale applications.
Mature deployment sits with Combustion Engines. Newer deployment is concentrated in Hybrid Systems.
Application:
End-use requirements for range, refueling infrastructure, and emission certification intensity segment demand across mobility and stationary power markets.
- Automotive:Passenger and commercial vehicle integration dominates unit volume, with Toyota sustaining technology leadership through decades of fuel-cell stack development. Heavy-duty electrification limits redirect long-haul fleet procurement toward hydrogen platforms.
- Aerospace:Auxiliary power units and ground operations represent certification-friendly entry points before propulsion system integration. Hydrogen combustion for aircraft taxiing operations climbs the fastest as airlines seek incremental decarbonization pathways.
- Marine:Coastal shipping routes under IMO 2030 emission intensity targets drive dual-fuel retrofit demand. Vessel owners prioritize fuel flexibility over single-fuel infrastructure commitment.
- Power Generation:Captive industrial power applications concentrate in Germany's Rhine-Ruhr chemical corridor, where localized hydrogen production supports short-haul distribution networks.
Revenue concentration remains with Automotive. Steepest expansion trajectory appears in Aerospace.
End User:
Procurement authority and fuel supply integration capabilities determine vendor relationship structures and contract bundling patterns.
- OEMs:Toyota, Cummins, and MAN compete through integrated powertrain platforms, with technology convergence blurring traditional fuel-cell and combustion boundaries.
- Energy Suppliers:Shell and TotalEnergies displace traditional equipment financiers by bundling fuel provision with powertrain leases in German long-haul trucking.
- Transportation Companies:Fleet procurement committees consolidate vendor relationships around integrated hydrogen supply contracts rather than discrete engine purchases.
- Industrial Users:Rhine-based chemical producers negotiate directly with infrastructure operators for captive fleet supply, creating demand density for localized fuel production.
Contract sophistication is highest with Energy Suppliers. Procurement fragmentation persists with Industrial Users.
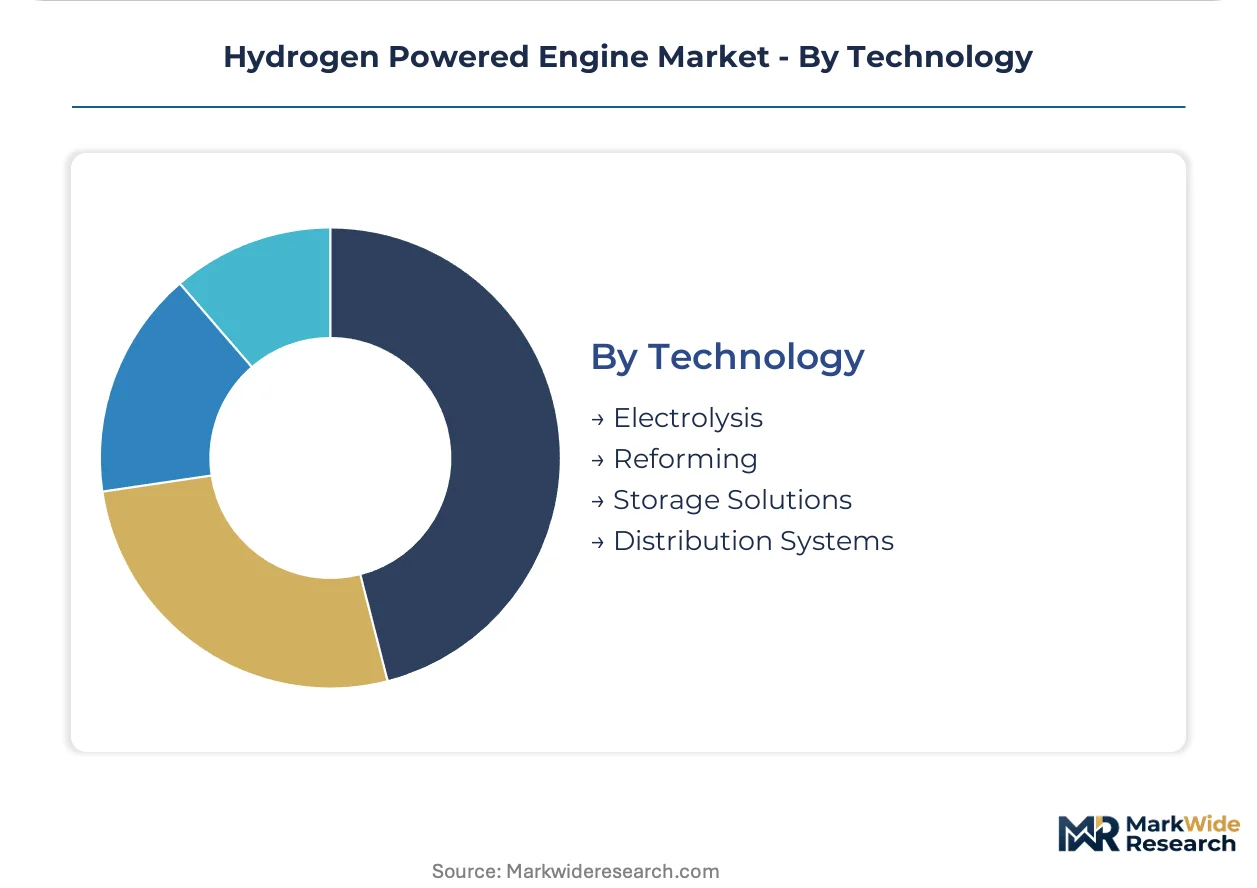
Technology:
Upstream hydrogen production, conditioning, and delivery infrastructure determines fuel availability and cost structure for downstream engine deployment.
- Electrolysis:Green hydrogen production via proton-exchange membrane and alkaline electrolyzers faces European manufacturing capacity constraints that bottleneck fuel availability for engine deployment at scale.
- Reforming:Steam methane reforming with carbon capture delivers near-term hydrogen supply for combustion engine trials, though lifecycle emission profiles limit regulatory acceptance under tightening EU thresholds.
- Storage Solutions:Cryogenic tank packaging within existing vehicle architectures requires structural redesigns that extend engineering timelines and certification cycles for OEM product launches.
- Distribution Systems:Germany's hydrogen core network pipeline conversion program creates geographic anchor points for stationary power applications at industrial facilities.
Capital deployment concentrates in Storage Solutions. Infrastructure buildout accelerates fastest in Distribution Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors European hydrogen engine deployment, with industrial clusters integrating captive power and logistics applications into localized fuel production networks.
Germany
Heavy-duty trucking fleets around Duisburg and Leverkusen are expanding hydrogen combustion trials as fleet operators prioritize diesel-equivalent range. The EU's Alternative Fuels Infrastructure Regulation mandates hydrogen-ready corridor buildout along major freight routes. The government's hydrogen core network pipeline conversion program creates geographic anchor points for stationary power at BASF and ThyssenKrupp facilities.
Japan
Commercial vehicle trials concentrate along the Tokaido corridor between Tokyo and Osaka industrial zones, with METI hydrogen supply chain targets accelerating refueling station deployment. METI's hydrogen roadmap tightens emission thresholds while funding infrastructure that determines market-access geography for engine OEMs. Toyota's fuel-cell stack development in Aichi Prefecture sustains technology leadership in passenger and commercial vehicle integration.
United States
California fleet operators face regulatory uncertainty as CARB evolves hydrogen eligibility rules within zero-emission vehicle credit frameworks. The EPA aligns heavy-duty engine standards with hydrogen eligibility, creating compliance pathways for combustion variants. Long-haul trucking procurement in the Central Valley redirects toward hydrogen platforms as battery weight constraints limit electrification feasibility.
China
Industrial hydrogen demand concentrates in Yangtze River Delta chemical clusters, where state-owned enterprises pilot captive power applications. MIIT dual carbon goals accelerate electrolyzer manufacturing capacity expansion to reduce green hydrogen supply bottlenecks. Port operators in Ningbo-Zhoushan test marine dual-fuel architectures for coastal shipping compliance with IMO 2030 targets.
South Korea
Hyundai Motor Company anchors domestic fuel-cell commercial vehicle deployment from Ulsan manufacturing complexes, with government targets supporting hydrogen bus fleet conversion. The national hydrogen economy roadmap funds refueling infrastructure along the Seoul-Busan expressway corridor. Daegu-Gyeongbuk industrial zones integrate stationary hydrogen turbines into combined heat and power systems for manufacturing facilities.
Hydrogen Powered Engine Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology certification tiers, with fuel-cell stack manufacturers commanding pricing power through platinum group metal loading while combustion engine converters capture volume through manufacturing continuity. The vendor base stratifies into three strategic archetypes: integrated automotive OEMs with decades of electrochemical development, dedicated engine fabricators with heavy-duty platform specialization, and energy majors bundling fuel provision with equipment leases. Dominant competitive moves include backward integration into electrolyzer partnerships and geographic expansion through hydrogen corridor anchor contracts.
Within the integrated OEM tier, Toyota Motor Corporation and Hyundai Motor Company represent archetypes of sustained fuel-cell stack development spanning passenger and commercial applications. Among dedicated engine specialists, Cummins Inc. and MAN occupy positions that exemplify platform strategies differentiated by regional heavy-duty procurement patterns. Honda Motor Corporation sits within a hybrid positioning that bridges automotive integration with stationary power system deployment.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Cummins Inc. |
| MAN |
| Hyundai Motor Company |
| Honda Motor Corporation |
| BMW |
| J C Bamford Excavators |
| Ashok Leyland |
| HD Hyundai Infracore |
| Others |
Supply Flow & Price Mechanics
Platinum group metal spot indices cascade through proton-exchange membrane stack production, compressing margins at the fuel-cell tier while combustion engine manufacturers exploit manufacturing continuity with existing diesel plants to hold price positions.
Pricing Analysis
Uptime guarantees and total-cost-of-ownership performance anchor value-based pricing for fleet operators calculating diesel-equivalent range retention. Three-tier pricing structure across premium fuel-cell, standard combustion, and economy retrofit tiers separates zero-emission certification value from manufacturing continuity plays. Cost compression in the combustion tier intensifies because MAN and Cummins scale dedicated hydrogen platforms. Heavy-duty trucking procurement committees show highest price sensitivity, while marine operators accepting dual-fuel architectures demonstrate lowest sensitivity due to IMO 2030 compliance premiums.
Supply Chain Analysis
CE marking and EPA 2027 qualification gates stretch certification cycles for cryogenic tank packaging redesigns, delaying OEM product launches. Electrolyzer manufacturing concentrates in Germany, Japan, and China, drawing from platinum group metals, carbon-fiber composite tanks, and high-pressure valve assemblies. Single-source vulnerability sits with European electrolyzer capacity concentration constraining green hydrogen availability. Distribution runs through integrated hydrogen supply contracts bundling fuel provision with powertrain leases rather than discrete equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogen powered engine market operates as a vertical-integration race where electrolyzer partnerships and refueling corridor anchor contracts determine regional production commitments.
For Market Incumbents: Anchor technology leadership through backward integration into electrolyzer manufacturing partnerships, securing captive green hydrogen supply for fleet customers. Expand certification investment in Euro VII and EPA 2027 compliance pathways before regulatory windows tighten. Battery-electric long-haul limitations present the primary substitution threat requiring defensive positioning through hydrogen combustion platform scale.
For New Entrants and Emerging Players: Begin with marine dual-fuel retrofit opportunities where Wärtsilä and MAN Energy Solutions have not fully captured coastal shipping routes under IMO 2030 targets. German hydrogen core network pipeline conversion programs offer the most penetrable geographic anchor for stationary power applications. Pursue direct negotiation with Rhine-Ruhr chemical producers for captive fleet supply contracts bypassing incumbent equipment financiers.
For Investors and Strategic Acquirers: The window for entry favors mid-cap electrolyzer specialists with European manufacturing footprint before capacity bottlenecks resolve. Long-term viability hinges on green hydrogen cost parity achievement within the decade-long infrastructure buildout horizon. Watch for CARB hydrogen eligibility rule finalization as the inflection signal triggering fleet procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Partnership Formation | Secures captive green hydrogen supply for OEM fleet customers in Germany's chemical corridor. |
| Dual-Fuel Retrofit Program Launch | Captures marine compliance demand under IMO 2030 without full vessel replacement commitment. |
| Hydrogen Corridor Anchor Contract | Locks geographic production priority under EU Alternative Fuels Infrastructure Regulation mandates. |
| NOx Aftert System Certification | Enables Euro VII compliance for combustion variants without urea-based catalytic reduction. |
| Technician Training Network Buildout | Reduces workforce transition friction at dealership networks for high-pressure fuel system maintenance. |
Methodological Framework
Trade publications, electrolyzer manufacturing databases, and EU regulatory filings formed the secondary backbone, supplemented by primary interviews with fleet procurement directors, hydrogen infrastructure planners, OEM platform engineers, and aftermarket service heads. Bottom-up and top-down triangulation validated hydrogen engine deployment assumptions across technology conversion pathways.
Bottom-up modeling anchored volume projections to individual OEM platform rollout schedules and refueling station deployment timelines across the analysis window. Segmentation dimensions included propulsion architecture, vehicle class, application mobility versus stationary, and regional regulatory cluster. CAGRs derived from hydrogen supply cost curve trajectories and fleet operator total-cost-of-ownership sensitivity analyses, with electrolyzer capacity expansion rates and platinum group metal price volatility as key forecast inputs.
Underlying measurement precision varies by segment; fuel-cell stack cost structures carry tighter precision than nascent hybrid system deployments. Forecasts reflect assumptions about infrastructure buildout pacing and regulatory eligibility evolution. A model refresh is warranted upon material change in EU Alternative Fuels Infrastructure Regulation enforcement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market