
 Clean Hydrogen Market | 2026-2036
Clean Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Hydrogen Market Intelligence
Industrial offtakers in steel and ammonia production are redrawing procurement priorities away from transport-focused developers. Air Products sustains its position through captive supply of hydrogen for refinery and chemical complexes across the Gulf Coast. Linde plc leverages its global engineering network to anchor large-scale electrolyzer deployments in European industrial corridors. Nel ASA specializes in PEM and alkaline electrolyzer manufacturing, competing on modular system design for distributed hydrogen hubs.
Clean hydrogen refers to hydrogen produced with minimal greenhouse gas emissions, typically via electrolysis using renewable electricity or through steam methane reforming with carbon capture, yielding purity grades from 99.9% to 99.999% for industrial and energy applications. Its primary purpose is to decarbonize hard-to-abate sectors where direct electrification proves technically or economically impractical. Electrolysis technology leads capital deployment as alkaline and PEM systems achieve scale, while steam methane reforming with carbon capture occupies the transitional supply position where natural gas infrastructure already exists. Application demand concentrates in industrial processes and chemical manufacturing, where ammonia synthesis and refinery hydrotreating constitute established offtake channels with defined purity specifications and long-term supply contracts.
The EU Green Deal and delegated acts on renewable fuels of non-biological origin establish carbon intensity thresholds that shape project eligibility for subsidies and offtake guarantees. The EPA and IRA tax credit provisions in the United States create parallel demand incentives tied to lifecycle emissions verification and domestic content requirements. Stakeholders must monitor regulatory divergence between jurisdictions on certification methodologies, as these definitions will determine which production assets qualify for preferential treatment and long-term contract security.
Market Dynamics
Industrial offtakers in steel and ammonia production are redrawing procurement priorities away from transport-focused developers, concentrating demand around electrolyzer manufacturing clusters with direct pipeline connections to chemical complexes.
Growth Catalysts
- EU Green Deal delegated acts:Carbon intensity thresholds for renewable fuels of non-biological origin tighten eligibility criteria, directing subsidy flows toward electrolysis projects with verified lifecycle emissions.
- Alkaline electrolyzer scale-up:Modular system designs achieve capital cost reductions through standardized manufacturing, accelerating deployment in distributed hydrogen hubs serving industrial corridors.
- Germany's H2Global mechanism:Auction-based offtake guarantees de-risk production investments by anchoring long-term supply contracts with price discovery transparency.
Market Restraints
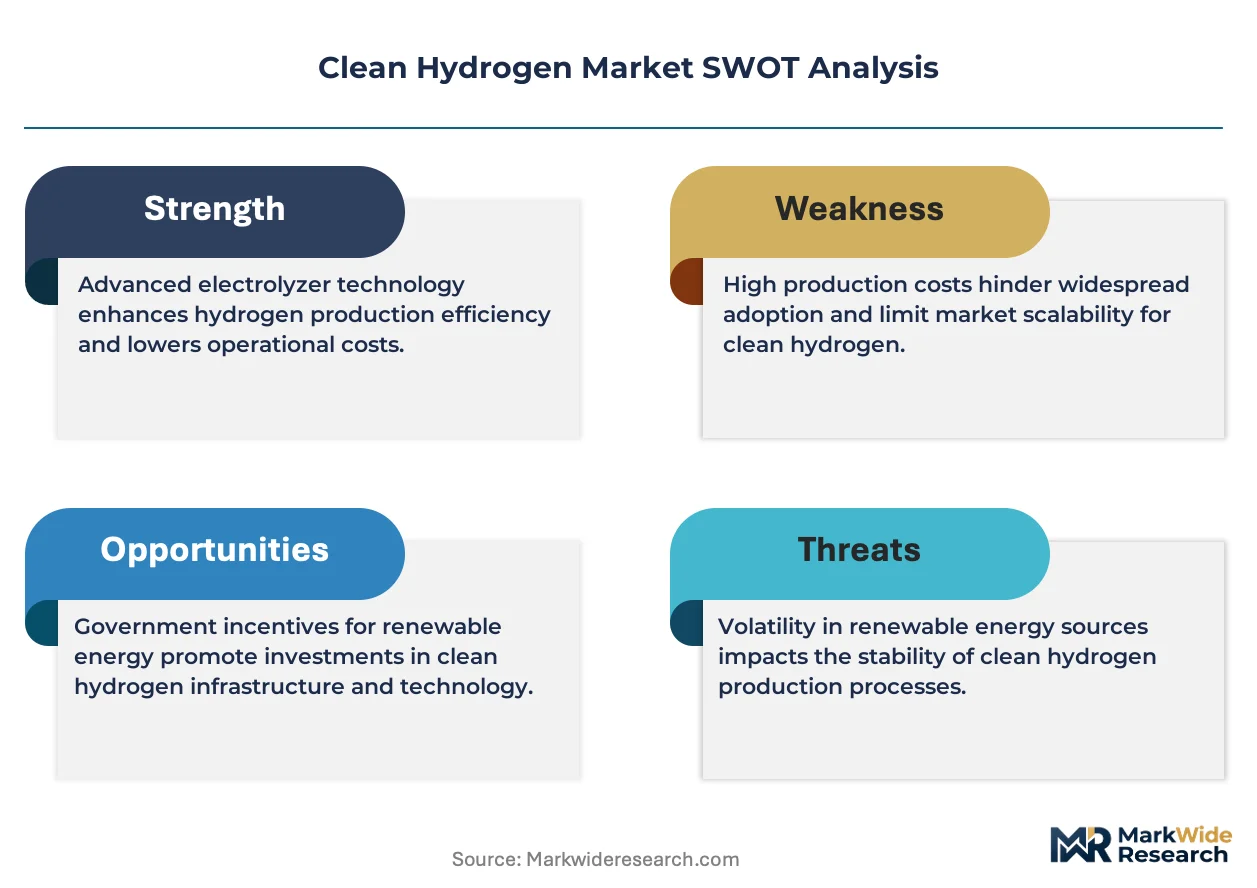
- Renewable electricity cost volatility:Intermittent solar and wind output in Spain and Denmark compress electrolyzer capacity factors, inflating levelized hydrogen costs during low-generation periods.
- Electrolyzer supply concentration:PEM stack manufacturing concentrates among specialized membrane suppliers, creating chokepoints for project developers seeking GW-scale deployments.
- Steam methane reforming lock-in:Existing natural gas infrastructure in the US Gulf Coast delays green hydrogen substitution where carbon capture retrofit costs undercut electrolysis premiums.
Strategic Opportunities
- India's PLI scheme for electrolyzer manufacturing:Production-linked incentives attract domestic assembly capacity, reducing import dependence for alkaline and PEM systems in emerging industrial zones.
- Refinery hydrotreating conversion:Petroleum complexes in Rotterdam and Singapore pilot hydrogen-for-fuel substitution, opening captive demand channels bypassing merchant market development.
- Power-to-ammonia integration:Converging electrolysis and Haber-Bosch synthesis technologies enable colocated production, trimming transport costs for fertilizer and shipping fuel applications.
Industry Challenges
- Electrolyzer commissioning delays:Grid connection timelines and utility interconnection queues in Germany and the Netherlands stretch project completion schedules beyond contracted offtake start dates.
- Certification methodology fragmentation:Divergent lifecycle accounting rules between EU delegated acts and IRA tax credit provisions in the United States force producers to maintain parallel verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Hydrogen Market |
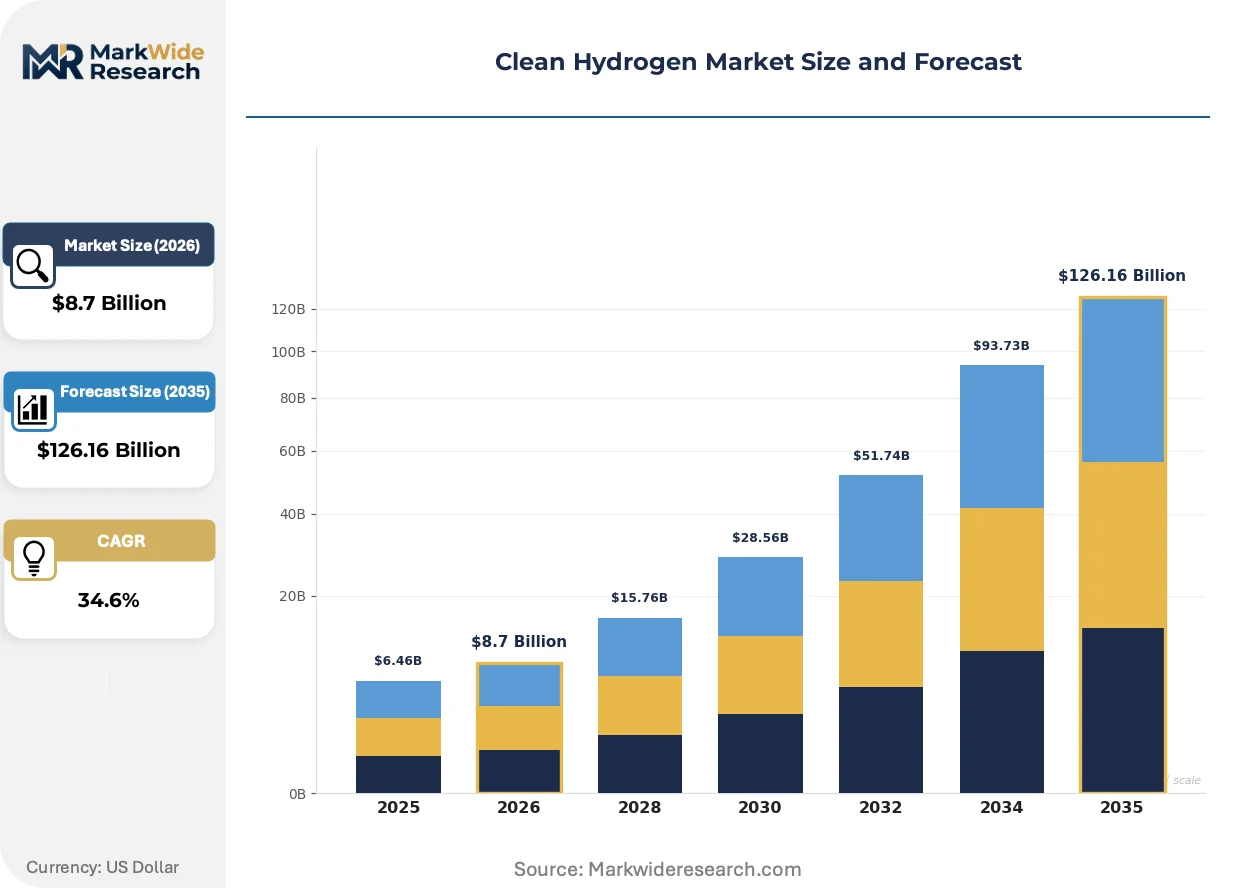
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $126.16 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Gasification, Photoelectrochemical Application: Transport, Industrial Processes, Power Generation, Chemical Manufacturing End User: Utilities, Energy Companies, Automotive OEMs, Manufacturing Distribution Channel: Direct Sales, Online Sales, Distributors, Partners |
| Companies Covered | Air Liquide, Linde plc, Air Products, Engie, Cummins Inc, Nel ASA, Plug Power, Siemens Energy, Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Hydrogen Market Strategic Shifts & Innovations
Electrolyzer technology pathways are diverging as alkaline systems compete with PEM on capital efficiency and modular deployment flexibility, reshaping how developers structure project finance and offtake agreements.
PEM electrolyzer stack architecture is fragmenting as platinum group metal loading reductions and alternative membrane chemistries proliferate. Steel producers in Sweden and ammonia synthesizers in Norway adopt these systems for rapid response to renewable curtailment. The technology is fragmenting procurement strategies between large centralized plants and distributed hub configurations.
Delegated acts on renewable fuels of non-biological origin under the EU Green Deal establish granular carbon intensity accounting methodologies. Project developers must now source hourly-matched renewable electricity to qualify for premium hydrogen certification. Industrial buyers in German chemical corridors restructure power purchase agreements to meet temporal correlation requirements.
Long-term contracting is displacing spot market exposure as steel mills and refineries seek supply security for capital-intensive hydrogen-ready equipment investments. Developers in Spain and Portugal abandon merchant market assumptions in favor of 10-15 year offtake commitments with industrial anchor tenants. This behavioral shift concentrates project development around existing industrial demand clusters rather than speculative export infrastructure.
Clean Hydrogen Market Segmentation
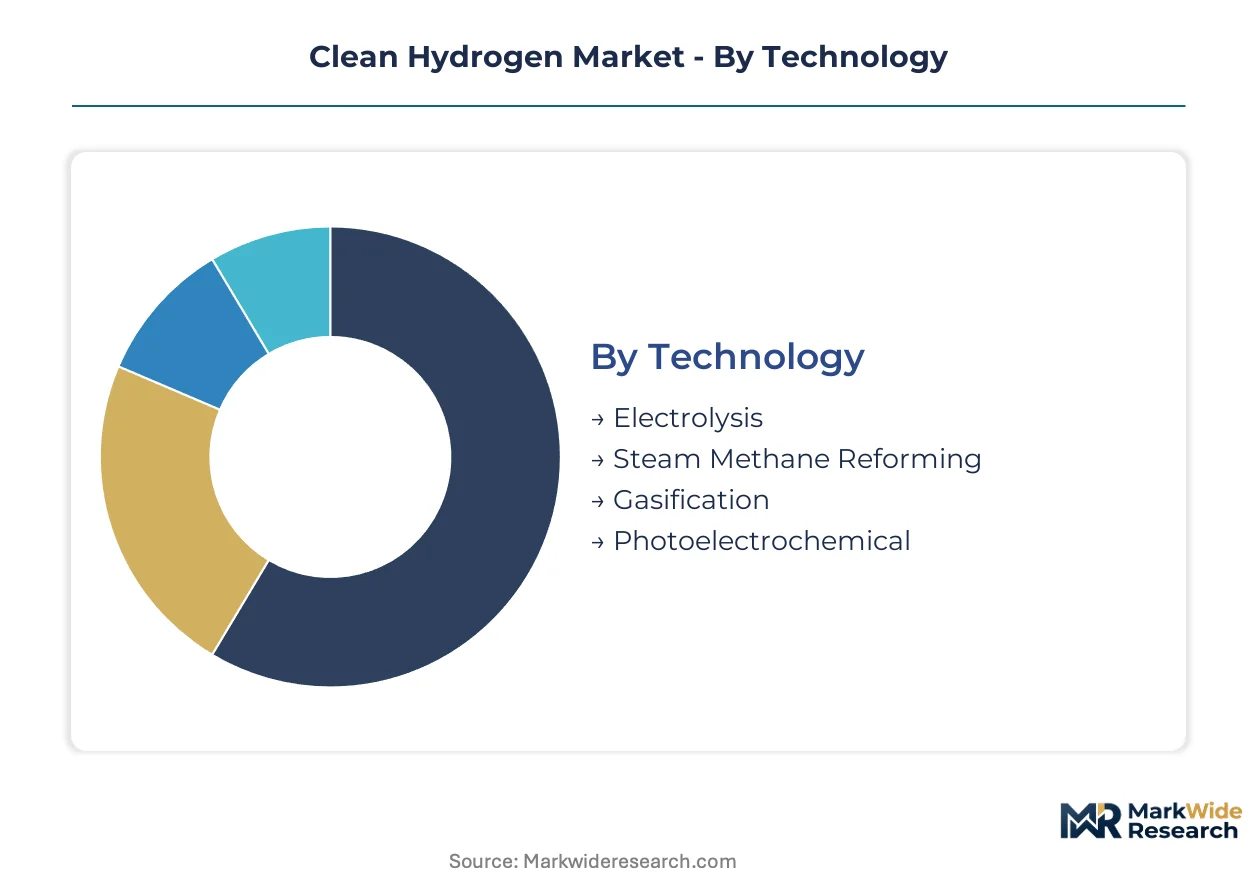
Clean hydrogen market segmentation reveals how production technology, application focus, and end-user priorities diverge across regulatory jurisdictions. Understanding these divisions exposes which segments face immediate substitution pressure from incumbent fossil fuels and which command premium positioning through carbon intensity certification.
Technology:
Electrolysis confronts the most acute substitution pressure from unabated steam methane reforming where natural gas infrastructure already exists, while emerging pathways compete on capital efficiency and carbon accounting granularity.
- Electrolysis:Alkaline and PEM systems split water using renewable electricity, yielding purity grades from 99.9% to 99.999%. Demand concentrates in German industrial corridors where the H2Global mechanism anchors long-term offtake contracts tied to EU Green Deal delegated acts.
- Steam Methane Reforming:Natural gas reforming with carbon capture occupies transitional supply positions across the US Gulf Coast, where EPA and IRA tax credit provisions reward lifecycle emissions verification. Existing pipeline infrastructure delays green hydrogen substitution where retrofit costs undercut electrolysis premiums.
- Gasification:Coal or biomass gasification with carbon capture serves regions with stranded feedstock assets and established syngas infrastructure.
- Photoelectrochemical:Direct solar-to-hydrogen conversion remains pre-commercial, with pilot deployments concentrated in Australian and Spanish research clusters.
Steam methane reforming anchors the volume base while electrolysis gains share at the steepest rate.
Application:
Cost tier stratification separates established industrial feedstock demand from emerging mobility applications where infrastructure gaps inflate delivered hydrogen costs.
- Industrial Processes:Steelmaking and refinery hydrotreating constitute established offtake channels with defined purity specifications. Rotterdam and Singapore petroleum complexes pilot hydrogen-for-fuel substitution, opening captive demand that bypasses merchant market development.
- Chemical Manufacturing:Ammonia synthesis and methanol production require continuous hydrogen supply at scale. Converging electrolysis and Haber-Bosch synthesis technologies enable colocated production in Norwegian and Saudi industrial zones.
- Transport:Fuel cell vehicle adoption concentrates in Korean and Japanese mobility corridors where METI and domestic OEM partnerships anchor hydrogen station networks.
- Power Generation:Grid-scale storage and peaking applications compete with battery economics in markets with seasonal renewable curtailment patterns.
Industrial processes anchor the volume base while chemical manufacturing expands most quickly through power-to-ammonia integration.
End User:
Customer type segmentation tracks procurement maturity, with integrated energy companies leveraging captive supply against merchant market exposure that manufacturing sectors seek to minimize.
- Energy Companies:Integrated oil and gas majors deploy hydrogen for refinery decarbonization and synthetic fuel production. Air Products sustains position through captive Gulf Coast supply serving chemical complexes with pipeline-connected distribution.
- Utilities:Power sector buyers evaluate hydrogen for seasonal storage and grid balancing, with FERC interconnection rules shaping project economics in US wholesale markets.
- Automotive OEMs:Vehicle manufacturers procure hydrogen for fuel cell powertrain validation and limited series production.
- Manufacturing:Steel and cement producers face EU carbon border adjustment pressure, restructuring procurement around certified low-carbon hydrogen supply.
Energy companies anchor the volume base while manufacturing climbs the fastest as carbon border adjustments tighten.
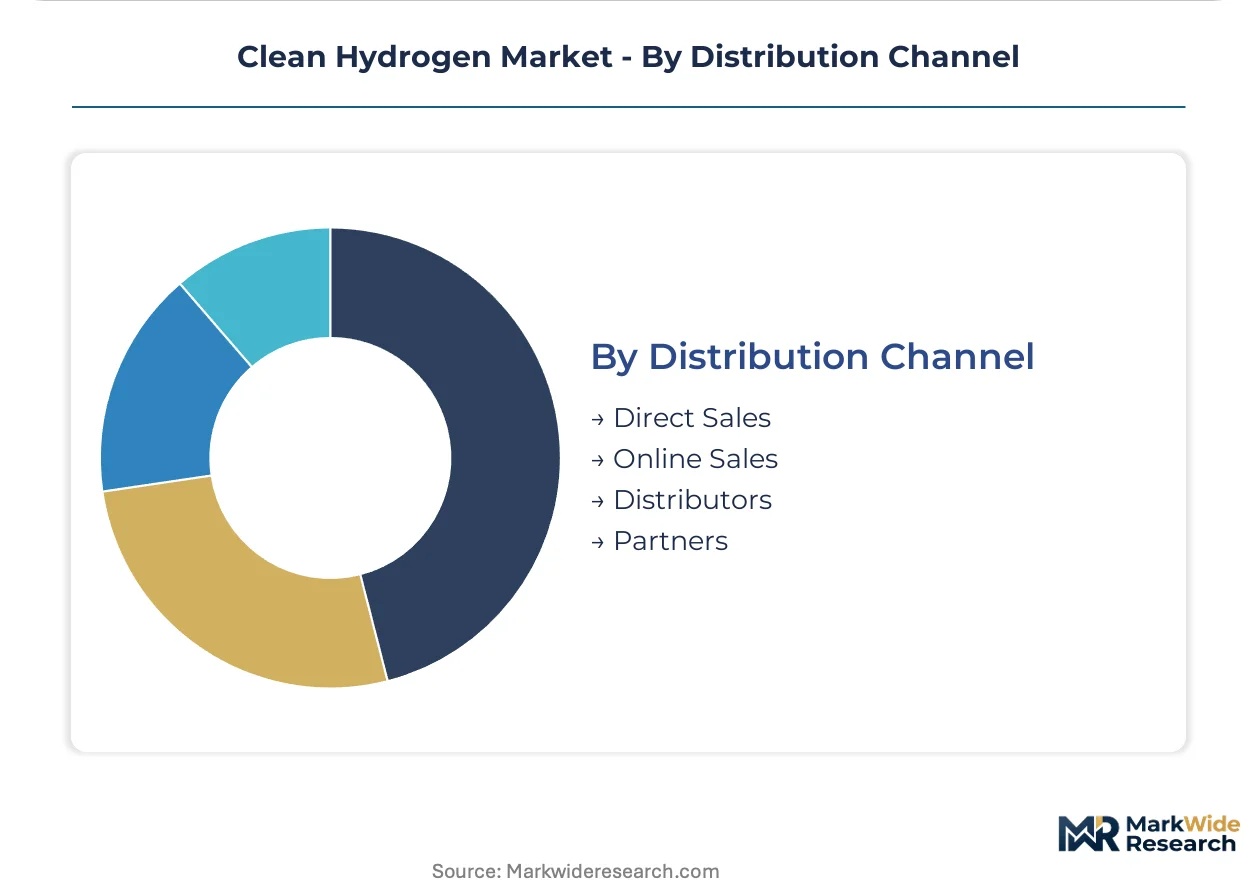
Distribution Channel:
Supply concentration in pipeline-connected industrial zones favors direct procurement relationships over intermediated channels where transport costs erode competitiveness.
- Direct Sales:Long-term supply contracts dominate industrial offtake, with 10-15 year tenors matching hydrogen-ready equipment investment horizons. Developers in Spain and Portugal abandon merchant assumptions for industrial anchor tenants.
- Distributors:Regional gas merchants handle compressed and liquid hydrogen logistics for smaller industrial consumers lacking pipeline access.
- Partners:Consortium structures bundle electrolyzer supply, renewable power offtake, and hydrogen delivery for integrated project development.
- Online Sales:Digital procurement platforms serve laboratory and specialty gas segments with small-volume, high-purity requirements.
Direct sales anchor the volume base while partner structures gain share fastest through integrated project bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SoutH2 Corridor pipeline network underwrites Germany's central role in European hydrogen infrastructure, connecting North Sea electrolyzer clusters to industrial demand centers in the Ruhr and Bavaria.
Germany
Steel producers in Duisburg and chemical complexes in Ludwigshafen drive electrolyzer procurement at scale. The H2Global auction mechanism anchors long-term offtake guarantees through the Federal Ministry for Economic Affairs and Climate Action. Domestic manufacturing clusters in North Rhine-Westphalia assemble alkaline and PEM systems for export across the EU.
United States
Refinery hydrotreating demand concentrates along the Gulf Coast petrochemical corridor, where existing hydrogen pipeline networks serve Texas and Louisiana complexes. EPA lifecycle emissions verification rules and IRA tax credit provisions reward projects with domestic content compliance. Electrolyzer deployments in Texas cluster around wind-rich West Texas renewable zones with direct pipeline connections to Houston Ship Channel refineries.
China
State-owned energy majors deploy electrolysis capacity in Inner Mongolia and Xinjiang wind-solar bases, feeding ammonia synthesis plants in Ningxia and Shandong. MIIT industrial policy directs subsidies toward alkaline electrolyzer manufacturing scale-up. Demonstration projects in the Yangtze River Delta test PEM integration with chemical manufacturing complexes.
India
Fertilizer producers in Gujarat and steel mills in Odisha pilot green hydrogen substitution under National Hydrogen Mission targets. The PLI scheme for electrolyzer manufacturing attracts assembly investment in Tamil Nadu and Maharashtra renewable industrial zones. Reliance Industries and NTPC anchor early offtake commitments for refinery and power sector applications.
Saudi Arabia
NEOM's integrated hydrogen-ammonia complex leverages Red Sea wind and solar resources for export-oriented production. The Saudi Industrial Development Fund channels capital toward electrolyzer deployments in the Eastern Province petrochemical corridor. ACWA Power and SABIC structure captive supply arrangements that bypass merchant market development.
Clean Hydrogen Market Key Industry Players
Concentration sits with integrated industrial gas suppliers and specialized electrolyzer manufacturers. The vendor base spans three tiers: global gas majors with captive hydrogen infrastructure, pure-play electrolyzer technology firms, and energy majors diversifying through project development. Strategic moves center on backward integration into renewable power sourcing and forward integration into ammonia synthesis to capture value chain margins.
Among the integrated gas majors, Air Products, Linde plc, and Air Liquide exemplify archetypes of infrastructure-anchored competitive positioning. Air Products represents the captive supply model through Gulf Coast pipeline networks. Linde plc occupies the engineering-led deployment position in European industrial corridors. Air Liquide exemplifies the diversified industrial gas platform extending into electrolyzer project development.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products |
| Engie |
| Cummins Inc |
| Nel ASA |
| Plug Power |
| Siemens Energy |
| Shell |
| Others |
Cost & Logistics Intelligence
Alkaline electrolyzer substitution for PEM systems in German industrial corridors simultaneously redraws supply geography toward North Rhine-Westphalia manufacturing clusters and compresses pricing premiums for modular system deployments. This technology shift rewards developers with captive renewable power sourcing while penalizing merchant market exposure.
Pricing Analysis
Volume-discount tiering structures separate long-term offtake contracts above 100 MW from spot market transactions and small-scale distributed hub deployments. Price differentiation rests on EU Green Deal delegated act certification tiers, with hourly-matched renewable electricity commanding substantial premiums over annual-matching alternatives. Cost compression in standard-grade hydrogen intensifies as Chinese alkaline electrolyzer exports penetrate European markets. Steel producers in Duisburg exhibit the highest price sensitivity due to carbon border adjustment exposure, while Saudi ammonia exporters demonstrate the lowest sensitivity through integrated captive supply.
Supply Chain Analysis
PEM membrane manufacturing concentrates in Germany, Japan, and the United States, creating chokepoints for project developers seeking GW-scale deployments. Electrolyzer stack production draws from iridium catalyst supplies anchored in South African mining operations and perfluorinated membrane feedstocks from Belgian chemical complexes. Single-source vulnerability in platinum group metal refining exposes supply chains to export restriction shocks. Distribution runs through pipeline-connected industrial zones rather than compressed gas logistics, favoring direct procurement relationships over intermediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among steel and ammonia producers restructuring procurement around certified low-carbon supply, fragmenting developer margins and rewarding scale-backed contract security.
For Market Incumbents: Compound engineering capabilities in alkaline electrolyzer manufacturing through North Rhine-Westphalia cluster expansion, defending against Chinese cost competition. Deepen backward integration into renewable power sourcing via hourly-matched PPA restructuring to preserve delegated act eligibility. Certification investment in lifecycle emissions verification systems represents the critical lever for contract retention as EU carbon intensity thresholds tighten. For New Entrants and Emerging Players: Anchor in India's PLI scheme for electrolyzer assembly capacity, targeting Tamil Nadu and Maharashtra renewable industrial zones with minimal incumbent presence. Refinery hydrotreating conversion in Rotterdam offers the most penetrable application segment, bypassing merchant market development through captive supply structures. Joint venture positioning with state-owned energy majors accelerates offtake anchoring in emerging demand corridors. For Investors and Strategic Acquirers: The market sits at a manufacturing scale-up phase that favors integrated project developers with pipeline-connected industrial assets. Long-term viability across the analysis window hinges on securing 10-15 year offtake commitments before carbon border adjustments harden procurement requirements. Acquisition targets should demonstrate hourly-matched renewable power sourcing and delegated act certification readiness. The signal to watch is H2Global auction clearing prices as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Power | Hourly-matched PPAs secure EU Green Deal delegated act certification premiums for electrolyzer operators. |
| Electrolyzer Manufacturing Scale-Up | Alkaline system deployment in North Rhine-Westphalia clusters captures German industrial corridor demand. |
| Long-Term Supply Agreement | 10-15 year offtake contracts with Duisburg steel producers de-risk hydrogen-ready equipment investments. |
| Joint Venture Formation | Consortium structures bundle electrolyzer supply, renewable offtake, and pipeline delivery for integrated projects. |
| Green Certification Program | Lifecycle emissions verification systems qualify production for IRA tax credits and H2Global auction eligibility. |
Research Approach
The analysis maps electrolysis technology pathways, industrial application segments, and end-user procurement archetypes, each validated through electrolyzer manufacturing executives, utility planning officers, and steel procurement leads. Primary interviews with EPC contractors and renewable project developers combined with secondary validation from EIA data, IEA hydrogen reports, FERC interconnection filings, and EU delegated act regulatory texts. Bottom-up electrolyzer deployment tracking triangulates against top-down industrial demand modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include production technology tier, application intensity, end-user procurement maturity, and regional regulatory framework cluster. CAGRs were derived from electrolyzer manufacturing capacity announcements, offtake contract tenors, and industrial substitution economics. Forecast inputs incorporated renewable electricity cost trajectories and carbon border adjustment implementation schedules.
Material uncertainties — regulatory divergence on certification methodologies, electrolyzer supply chain chokepoints, and renewable curtailment patterns — sit outside the modeled envelope. Forecasts reflect assumptions about delegated act temporal correlation requirements and IRA domestic content compliance thresholds. Practitioners should keep alternative scenarios live as EU carbon intensity thresholds and Chinese export pricing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
Hydrogen Purifiers Market